
 Americas Coating Additives Market | 2026-2036
Americas Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Americas Coating Additives Market Analytics
Performance-grade additive specifications is bifurcating the competitive landscape between commodity suppliers and specialty formulators. BASF leverages integrated polymer science capabilities to anchor high-performance rheology modifier supply across North American industrial coatings. Evonik Industries differentiates through silicone-based surface control additives that dominate automotive clearcoat applications. Dow competes on scale in waterborne dispersant chemistries, sustaining cost positions across architectural coating channels.
Americas coating additives encompass functional chemicals—typically dosed at 0.1–5.0% by weight—that modify viscosity, dispersion stability, substrate wetting, or film formation in liquid and powder coatings. These materials include polymer modifiers, surfactants, and rheology agents synthesized through controlled radical polymerization or organosilane chemistry, serving primarily to meet durability, appearance, and application-efficiency requirements in protective and decorative films. Rheology modifiers command the deepest margin pools due to formulation specificity and patent-protected molecular architectures, while waterborne dispersants represent the fastest-growing technology segment as VOC compliance tightens across US and Canadian regulatory jurisdictions. Architectural coatings still generates the largest volume pull, though automotive finishes concentrates premium additive value per gallon.
EPA VOC rules under the National Emission Standards for Hazardous Air Pollutants constrain solventborne additive use, while OSHA workplace exposure limits push manufacturers toward closed-system handling of powder and UV-curable technologies. Health Canada's PMRA and Brazil's ANVISA impose parallel substance registration requirements that filter which chemistries enter regional supply chains. Formulators and additive suppliers must monitor pending state-level amendments to California's SCAQMD Rule 1113 and evolving Mexican PROFEPA environmental enforcement protocols to anticipate specification shifts before they cascade through procurement timelines.
Market Dynamics
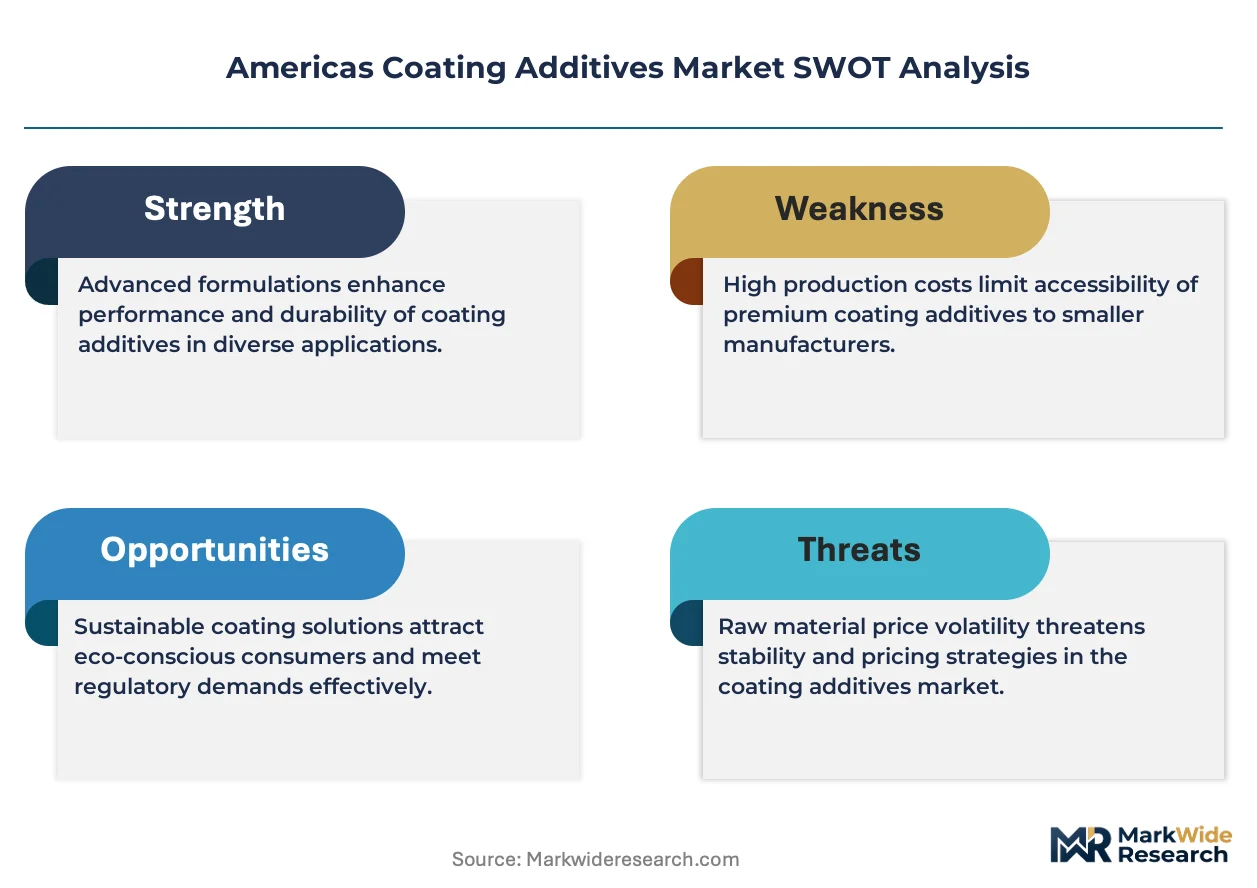
Waterborne formulation mandates from EPA VOC regulations are compressing solventborne additive demand while concentrating procurement power among Gulf Coast petrochemical clusters capable of integrated specialty chemical production.
Growth Catalysts
- Automotive refinishing expansion:Brazil and Mexico OEM finish specifications are elevating additive performance requirements for durability and appearance standards.
- EPA NESHAP enforcement:Hazardous air pollutant standards are accelerating facility upgrades toward compliant waterborne systems across US industrial coating operations.
- Rheology modifier patent architecture:Formulation-specific molecular designs are locking in premium supply relationships with industrial coatings manufacturers.
Market Restraints
- Petrochemical feedstock volatility:Acrylic monomer and organosilane precursor costs swing with Gulf Coast cracker utilization rates.
- Specialty production concentration:Controlled radical polymerization capacity clusters along the Texas-Louisiana corridor, creating single-source vulnerability.
- Substrate compatibility limitations:Waterborne dispersants fail on certain engineered plastics used in automotive interior applications.
Strategic Opportunities
- Mexico manufacturing corridor:Querétaro and Guanajuato automotive assembly hubs lack localized additive blending capacity.
- UV-curable convergence:Energy-curable oligomers combined with silicone surface control additives open industrial wood coating segments.
- Canadian PMRA registration streamlining:Revised substance approval timelines reduce market entry barriers for novel biocide additives.
Industry Challenges
- Formulation chemist scarcity:Expertise in controlled radical polymerization and organosilane synthesis concentrates among retiring specialists.
- Multi-jurisdiction registration costs:Parallel EPA, PMRA, and ANVISA substance dossiers drain R&D budgets for mid-scale suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Americas Coating Additives Market |
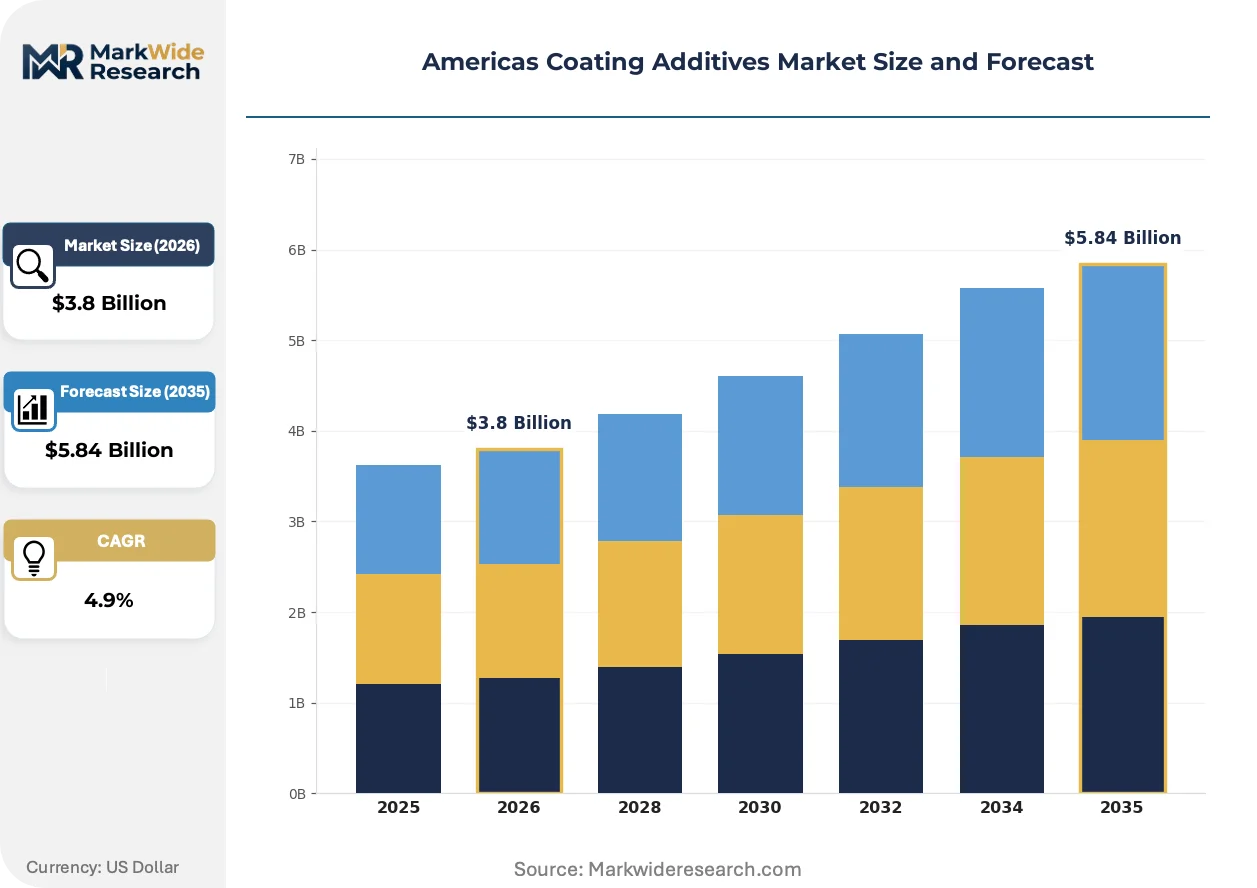
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.84 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer Additives, Pigment Dispersants, Surfactants, Rheology Modifiers Application: Architectural Coatings, Industrial Coatings, Automotive Finishes, Wood Coatings End User: Construction, Automotive, Consumer Goods, Electronics Technology: Waterborne, Solventborne, Powder Coatings, UV Curable |
| Companies Covered | BASF, Dow, Evonik Industries, AkzoNobel, Elementis, The Lubrizol Corporation, Ashland, The Eastman Chemical Company, BYK-Chemie GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Americas Coating Additives Market Evolving Landscape
Hybrid additive architectures that merge multiple functional chemistries into single-molecule designs are compressing formulation complexity while raising performance thresholds across automotive and industrial coating segments.
Silicone-polyether hybrid surface control additives are displacing traditional fluorosurfactants in automotive clearcoat applications. Tier-1 automotive finish suppliers in Michigan and Ohio are qualifying these materials for next-generation scratch-resistant topcoats. The shift is displacing legacy fluorocarbon chemistry from high-value specification sheets.
California SCAQMD Rule 1113 amendments are tightening VOC limits for architectural coatings beyond federal EPA benchmarks. Formulators serving the Los Angeles-San Diego corridor must reformulate with exempt solvents or waterborne alternatives. The regulation is compressing solventborne additive demand in the largest US regional market.
Direct procurement from additive manufacturers is fragmenting traditional distributor channels. Large architectural coatings producers in the US Southeast are establishing captive supply agreements with Gulf Coast specialty chemical plants. The pattern is most visible in dispersant and rheology modifier categories where volume concentration justifies bypassing regional distributors.
Americas Coating Additives Market Segmentation
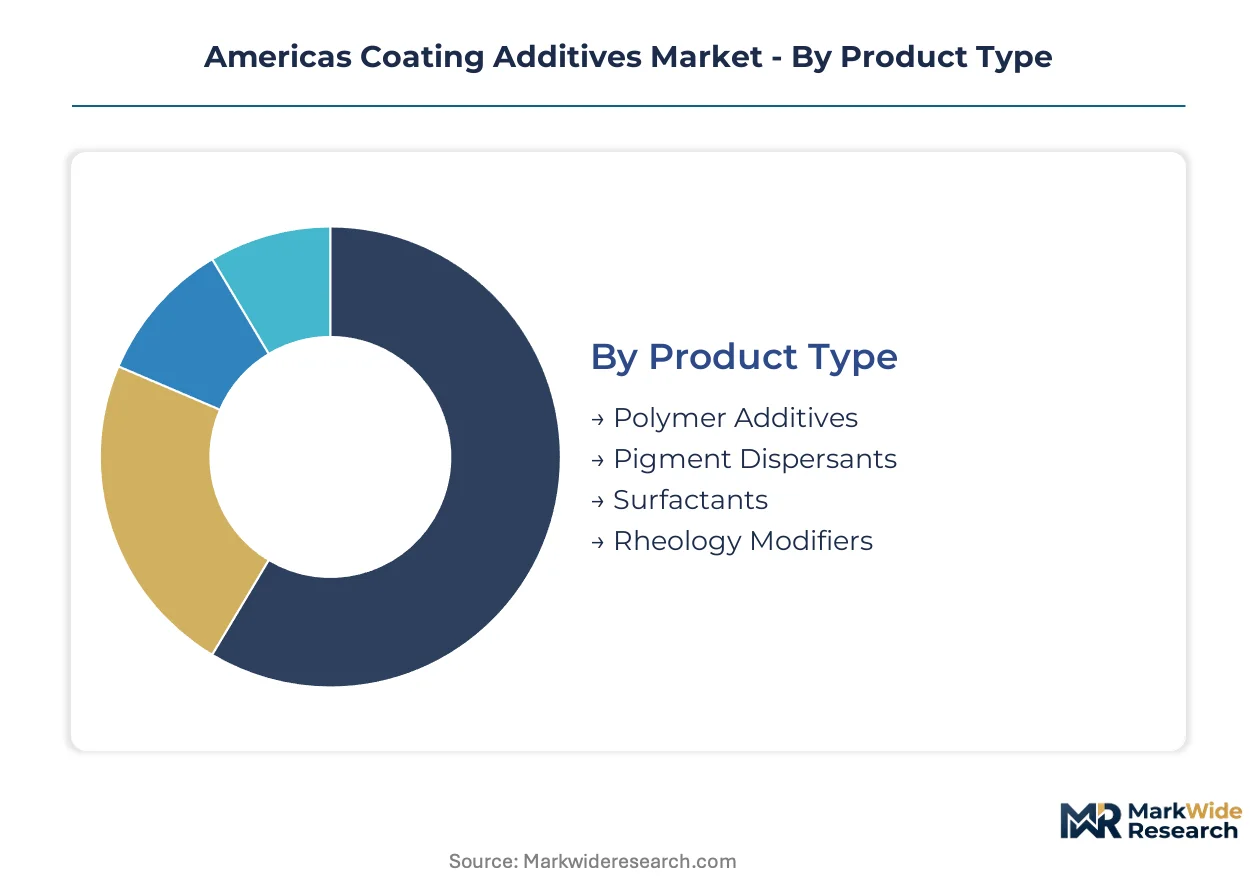
Segmentation in the Americas coating additives market reveals how formulation chemistry, application requirements, and regulatory compliance intersect to determine value capture. Understanding these divides exposes where specialty suppliers command premium positioning versus where commodity scale dominates procurement decisions.
Product Type:
Rheology modifiers concentrate the deepest margin pools due to patent-protected molecular architectures and formulation-specific integration requirements.
- Rheology Modifiers:These materials control viscosity and flow behavior through associative thickening or clay-based mechanisms. Automotive OEM clearcoat specifications in Michigan and Ohio drive demand for high-shear stable grades that maintain appearance during robotic application. Patent-protected controlled radical polymerization processes lock in supply relationships with industrial coatings manufacturers.
- Pigment Dispersants:Polymeric dispersants stabilize particle distribution through steric hindrance and electrostatic repulsion mechanisms. Waterborne architectural coatings producers along the US Gulf Coast represent the primary volume pull as EPA VOC regulations compress solventborne alternatives. Formulators prize dispersants that maintain color development across tinting systems.
- Polymer Additives:Film-forming aids and coalescing agents modify glass transition temperatures to enable low-temperature cure.
- Surfactants:Wetting agents and defoamers manage substrate interaction and foam control during high-speed application.
The dominant share belongs to Rheology Modifiers, while Pigment Dispersants are closing the gap fastest as waterborne conversion accelerates.
Application:
Volume concentration varies sharply across these segments, with architectural coatings generating the largest gallonage while automotive finishes captures the highest additive value per unit.
- Architectural Coatings:Interior and exterior house paints, stains, and sealers consume dispersants and cellulosic thickeners in massive volume. US Southeast production clusters near Gulf Coast petrochemical corridors enable direct procurement relationships that bypass traditional distribution channels. California SCAQMD Rule 1113 amendments are forcing reformulation toward exempt solvents and waterborne systems in the Los Angeles-San Diego corridor.
- Automotive Finishes:OEM basecoats, clearcoats, and primers demand silicone-polyether hybrid surface control additives for scratch resistance and distinctness of image. Tier-1 finish suppliers in Michigan and Ohio are qualifying these materials for next-generation specifications, displacing legacy fluorocarbon chemistry from high-value specification sheets. Brazil and Mexico OEM assembly expansion is elevating performance requirements for durability and appearance standards.
- Industrial Coatings:Protective and marine coatings utilize corrosion inhibitors and rheology modifiers for heavy-duty film performance.
- Wood Coatings:Furniture and flooring finishes employ UV-curable oligomers combined with silicone surface control additives for industrial segments.
Architectural Coatings holds the volume lead, though Automotive Finishes commands the steepest expansion trajectory in value terms.
End User:
Customer procurement sophistication determines specification control, with automotive and electronics segments driving the tightest performance requirements.
- Construction:Residential and commercial building activity generates steady demand for cost-optimized additive packages in architectural coatings. Multi-jurisdiction registration costs for novel chemistries concentrate procurement power among established suppliers with existing EPA and PMRA dossiers.
- Automotive:OEM finish specifications and refinish operations in Brazil and Mexico are elevating additive performance requirements. Querétaro and Guanajuato assembly hubs currently lack localized additive blending capacity, creating supply chain vulnerability.
- Consumer Goods:Appliance and furniture coatings utilize standard-grade rheology modifiers and dispersants for appearance and durability.
- Electronics:Conformal coatings and specialty finishes demand ultra-pure additive grades with tight ionic contamination controls.
Construction maintains the broadest installed base, while Automotive is gaining share fastest through OEM specification upgrades.
Technology:
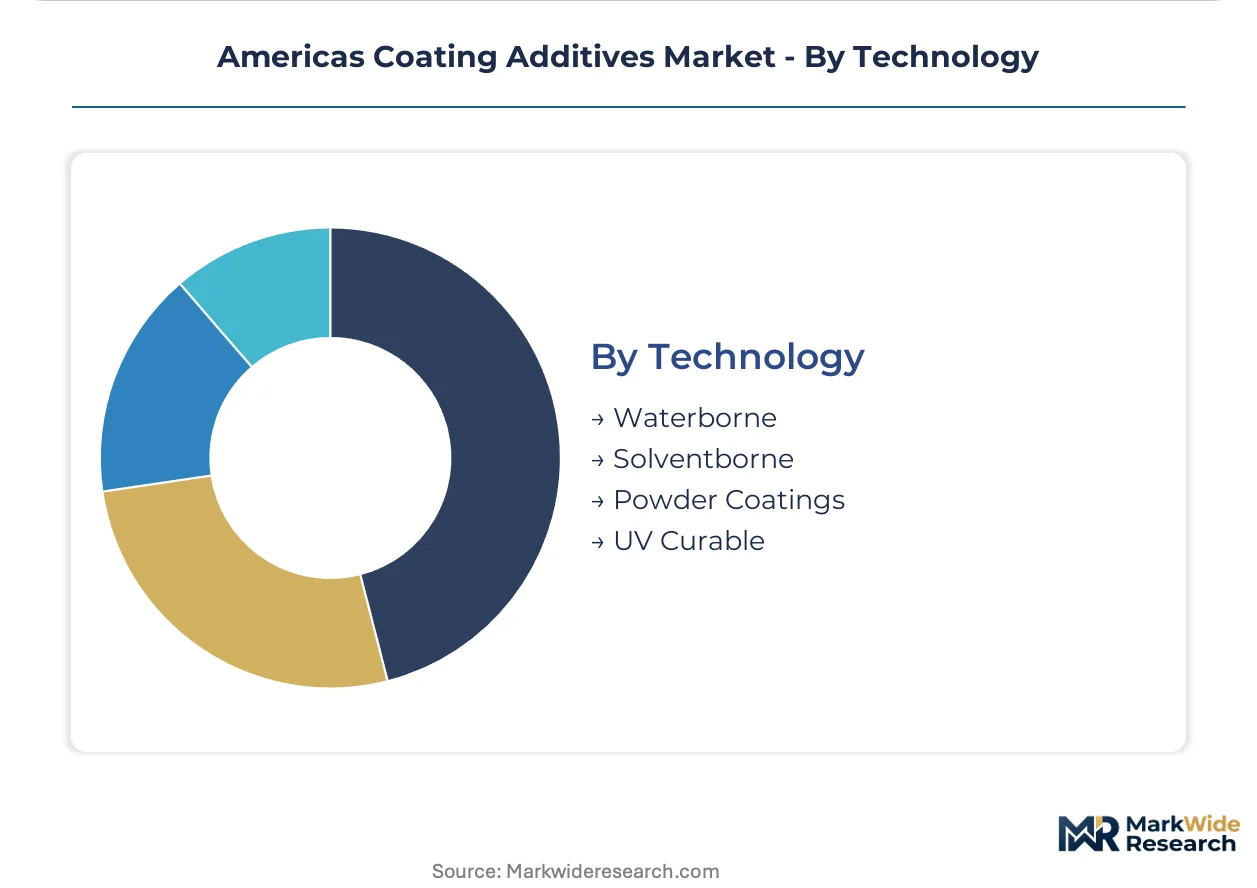
Regulatory enforcement patterns are compressing solventborne demand while concentrating investment in compliant waterborne and energy-curable platforms.
- Waterborne:Acrylic and polyurethane dispersions utilize specialized dispersants and coalescing aids to achieve film formation without volatile organic content. EPA NESHAP enforcement is accelerating facility upgrades across US industrial coating operations. The technology represents the fastest-growing platform as VOC compliance tightens across US and Canadian jurisdictions.
- UV Curable:Energy-curable oligomers combined with silicone surface control additives open industrial wood coating segments with instant cure and low energy consumption. OSHA workplace exposure limits push manufacturers toward closed-system handling of these technologies.
- Solventborne:Traditional alkyd and urethane systems face compression from EPA VOC regulations and California SCAQMD Rule 1113 amendments.
- Powder Coatings:Thermoset powders utilize flow control and degassing additives for thin-film application without liquid carriers.
Waterborne technology holds the regulatory tailwind, while UV Curable is climbing the fastest in niche industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Americas coating additives trade flows reflect a net-export position from US Gulf Coast petrochemical corridors toward Mexican and Brazilian manufacturing hubs. Canada supplies specialty-grade raw materials southward while importing formulated additive packages for its architectural coatings sector.
United States
EPA NESHAP enforcement drives facility upgrades toward waterborne systems across industrial coating operations in Texas and Louisiana. The SCAQMD Rule 1113 amendments in California force reformulation toward exempt solvents in the Los Angeles-San Diego corridor. Houston and Lake Charles host controlled radical polymerization capacity clusters serving direct procurement relationships with Southeast architectural coatings producers.
Mexico
Automotive assembly expansion in Querétaro and Guanajuato elevates additive performance requirements for OEM finish specifications. PROFEPA environmental enforcement protocols are tightening substance registration timelines for imported specialty chemicals. The Bajío Region currently lacks localized additive blending capacity, creating supply chain vulnerability for tier-1 finish suppliers.
Brazil
OEM finish specifications from expanding automotive production in São Paulo and Minas Gerais drive demand for durability-grade rheology modifiers. ANVISA substance registration requirements filter which chemistries enter regional supply chains for refinish operations. The ABC Paulista industrial corridor concentrates downstream coating manufacturing without matching upstream specialty additive synthesis capacity.
Canada
PMRA registration streamlining reduces market entry barriers for novel biocide additives targeting wood coatings and architectural applications. Health Canada workplace exposure limits push manufacturers toward closed-system handling of powder and UV-curable technologies. Southern Ontario production clusters near Detroit automotive finish specifications, importing premium silicone-polyether hybrid additives for clearcoat applications.
Argentina
Industrial protective coatings demand in Buenos Aires and Córdoba generates pull for corrosion-inhibiting additive packages. The national chemical regulator imposes parallel substance dossier requirements that concentrate procurement among established suppliers with existing regional registrations. The Rosario-Santa Fe corridor hosts formulation facilities relying on imported dispersant and rheology modifier supply.
Americas Coating Additives Market Competitive Landscape
Listed leaders compete with private specialists across patent-protected molecular architectures and regional registration capabilities. The vendor base spans three tiers: integrated petrochemical majors with Gulf Coast production assets, mid-scale specialty chemical houses with formulation-specific expertise, and regional distributors facing compression from direct procurement trends. Strategic moves concentrate on captive supply agreements with large architectural coatings producers and qualification programs for tier-1 automotive finish specifications.
Within the integrated petrochemical tier, BASF and Dow exemplify scale-driven positions anchored in polymer science capabilities and waterborne dispersant chemistries respectively. Evonik Industries occupies a specialization position representing silicone-based surface control additive expertise. These three entities illustrate how patent architecture and regional production clustering determine competitive positioning across the Americas coating additives value chain.
| Leading Market Players |
|---|
| BASF |
| Dow |
| Evonik Industries |
| AkzoNobel |
| Elementis |
| The Lubrizol Corporation |
| Ashland |
| The Eastman Chemical Company |
| BYK-Chemie GmbH |
| Others |
Value Network & Pricing Analysis
Controlled radical polymerization capacity utilization along the Texas-Louisiana corridor shapes both supply concentration and price floors for rheology modifiers. Gulf Coast petrochemical scale economies lock in cost positions that commodity dispersant suppliers cannot replicate without captive monomer supply.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automotive clearcoat specifications. Three-tier pricing structure across premium, standard, and economy levels separates patent-protected silicone-polyether hybrids from commodity cellulosic thickeners and generic dispersants. Cost compression in standard-grade waterborne additives is intensifying because direct procurement from Gulf Coast producers eliminates distributor markups. Construction sector procurement teams exhibit highest price sensitivity, while tier-1 automotive finish suppliers in Michigan and Ohio prioritize performance consistency over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among automotive OEMs facing ANVISA and PMRA registration delays for novel chemistries. Supply concentrates in the United States, Mexico, and Brazil, with the US Gulf Coast feeding downstream formulation clusters. Acrylic monomer and organosilane precursor flows draw from Texas-Louisiana crackers and international silicone feedstock channels. Single-source vulnerability runs through controlled radical polymerization assets concentrated in Houston and Lake Charles. Distribution runs through direct captive agreements between large architectural producers and Gulf Coast specialty plants, bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is consolidating among large architectural coatings producers establishing direct procurement relationships with Gulf Coast additive manufacturers. This consolidation fragments traditional distributor channels and compresses margin capture for mid-scale suppliers lacking captive supply scale.
For Market Incumbents: Compound patent-protected molecular architectures in rheology modifiers to lock in automotive OEM qualification cycles. Expand controlled radical polymerization capacity in Texas-Louisiana corridor to defend against specialty chemical entrants from Asia. Backward integration into acrylic monomer supply secures cost positions as Gulf Coast cracker utilization swings feedstock pricing. For New Entrants and Emerging Players: Canadian PMRA registration fast-tracks offer lower barrier entry for novel biocide additives targeting wood coatings and architectural segments. Querétaro and Guanajuato automotive assembly hubs lack localized additive blending capacity, creating white-space for regional formulation facilities. Target direct supply agreements with tier-1 finish suppliers seeking to reduce import dependency from US Gulf Coast. For Investors and Strategic Acquirers: Mid-scale specialty chemical houses with existing EPA and ANVISA dossiers represent prime acquisition targets as multi-jurisdiction registration costs filter out smaller competitors. Long-term viability hinges on waterborne formulation conversion trajectories across US and Canadian regulatory jurisdictions. Watch California SCAQMD Rule 1113 amendment enforcement intensity as inflection indicator for solventborne additive demand compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive acrylic monomer supply insulates BASF and Dow from Gulf Coast cracker volatility. |
| Capacity Expansion | Controlled radical polymerization additions in Lake Charles serve direct procurement relationships with Southeast architectural producers. |
| Long-term Supply Agreement | Captive contracts between tier-1 automotive finish suppliers and silicone-polyether hybrid producers displace legacy fluorocarbon channels. |
| Joint Venture | Querétaro additive blending partnerships address supply chain vulnerability for Mexican automotive assembly hubs. |
| Green Manufacturing Transition | Waterborne dispersant capacity investments align with EPA NESHAP enforcement timelines across industrial coating operations. |
Research Methodology
The analysis maps rheology modifiers, pigment dispersants, polymer additives, and surfactant sub-sectors, each validated through formulation chemists, procurement leads at downstream coatings OEMs, distribution channel partners, and technical R&D directors. Primary interviews with plant managers at Gulf Coast petrochemical facilities combined with secondary validation from ACC reports, customs/trade data, EPA regulatory filings, and SEC 10-K disclosures. Bottom-up segment sizing and top-down market reconciliation triangulate volume and value estimates.
Consistency checks against external benchmarks validated projections across the analysis window. Segmentation dimensions modeled include product type, application category, end-user industry, and technology platform. CAGRs derive from trend extrapolation of waterborne conversion rates, automotive assembly expansion patterns, and regulatory enforcement intensity. Industry-specific inputs encompass EPA NESHAP compliance timelines, PMRA registration streamlining progress, and PROFEPA environmental protocol evolution.
Underlying assumptions cover sustained EPA VOC regulatory tightening, stable Gulf Coast petrochemical operating rates, and continued automotive assembly expansion in Mexico and Brazil, with deviation risk concentrated in feedstock price volatility and formulation chemist labor scarcity. Revision becomes warranted when waterborne technology penetration crosses thresholds that eliminate solventborne additive demand faster than modeled.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Pearlizers Market
Additives
Grinding Aids Market
Additives
Citrate Ester Market
Additives
Global UV Stabilizers Market
Additives
Antimicrobial Ingredients Market
Additives
Europe Feed Additives Market
Additives
Feedstuff Additives Market
Additives
Thallium Acetate Market
Additives
Global Sodium Acetate Trihydrate Market
Additives
Organic Friction Modifier Additives Market
Additives
Calcium Acetate Market
Additives
Triazine UV Absorber Market
Additives
Phenolic Antioxidant Market
Additives
Material Shrinkage-reducing Agents Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Biofuel Additives Market