
 North America Phosphate Esters Market | 2026-2036
North America Phosphate Esters Market Size, Share, and Industry Trends Forecast 2026-2036
North America Phosphate Esters Market Insights
Fire-resistant specification upgrades in hydraulic fluid formulations is reorganizing procurement priorities across industrial end users. Exxon Mobil Corporation leverages its integrated lubricant supply chain to anchor premium phosphate ester distribution in the region. Stepan Company specializes in surfactant-grade phosphate esters for institutional cleaning applications. Eastman Chemical Company controls a significant share of aryl phosphate ester capacity through its Kingsport manufacturing complex.
Phosphate esters are organophosphorus compounds synthesized through phosphorylation of alcohols or phenols, yielding products with phosphorus content typically between four and twelve percent by weight; these compounds function primarily as flame retardants, lubricant additives, and surfactants in industrial and consumer formulations. Aryl phosphate esters dominate volume in plasticizer applications due to established supply chains and cost structures, while alkyl phosphate esters represent the fastest-growing product category driven by demand for low-toxicity hydraulic fluids. The lubricants application segment holds concentrated margin pools because fire-resistant specifications command technical premiums from aerospace and steel mill buyers.
EPA regulates phosphate ester discharge under the Clean Water Act, while OSHA sets exposure limits for workplace organophosphate handling, and the TSCA framework governs new chemical introductions in US commerce. These standards elevate compliance costs for importers and favor domestic producers with established environmental permits. Stakeholders must monitor evolving state-level restrictions on phosphorus content in consumer products, as California and New York regulatory precedents typically diffuse across North American jurisdictions.
Market Dynamics
Fire-resistant hydraulic fluid specifications are compressing procurement cycles across North American industrial buyers as OEMs mandate higher-performance lubricant formulations for critical machinery applications.
Growth Catalysts
- Clean Water Act phosphorus discharge limits:EPA enforcement is accelerating facility upgrades at Gulf Coast processing plants, driving replacement demand for compliant phosphate ester formulations in wastewater treatment chemicals.
- Aerospace hydraulic systems:Commercial aircraft OEMs are specifying aryl phosphate esters for next-generation landing gear and flight control systems, creating technical premium pools for qualified suppliers.
- Texas-Louisiana chemical corridor clustering:Integrated phosphate processing infrastructure is shortening raw material transit distances and enabling just-in-time surfactant production for institutional cleaning compounders.
Market Restraints
- Phosphate rock import dependency:North American manufacturers rely on Moroccan and Jordanian phosphate rock concentrate, exposing margin structures to ocean freight volatility and geopolitical supply interruptions.
- TSCA new chemical review timelines:EPA's 90-day review window for novel phosphate ester introductions extends product development cycles and elevates pre-commercialization compliance expenditure.
- Polyol ester substitution in aviation:Synthesized polyol-based hydraulic fluids are capturing share in commercial aircraft applications where extreme temperature performance outweighs fire-resistance requirements.
Strategic Opportunities
- Mexican automotive manufacturing expansion:Queretaro and Guanajuato assembly plants are localizing phosphate ester procurement for transmission fluid and metalworking applications, bypassing US-Mexico-Canada Agreement tariff complexity.
- California phosphorus content restrictions:State-level consumer product mandates are creating first-mover advantage for low-phosphorus surfactant-grade ester producers serving institutional cleaning channels.
- Bio-based alcohol feedstock integration:Renewable isobutanol and 2-ethylhexanol pathways are converging with conventional phosphorylation processes, enabling carbon intensity reductions for sustainability-positioned formulations.
Industry Challenges
- Organophosphate toxicology expertise scarcity:Industrial hygienists and environmental compliance officers with specialized organophosphate handling credentials command compensation premiums that elevate operational overhead.
- Fire-resistance certification timelines:Factory Mutual and UL hydraulic fluid approval processes extend 18-24 months, compressing product launch windows and tying up technical resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Phosphate Esters Market |
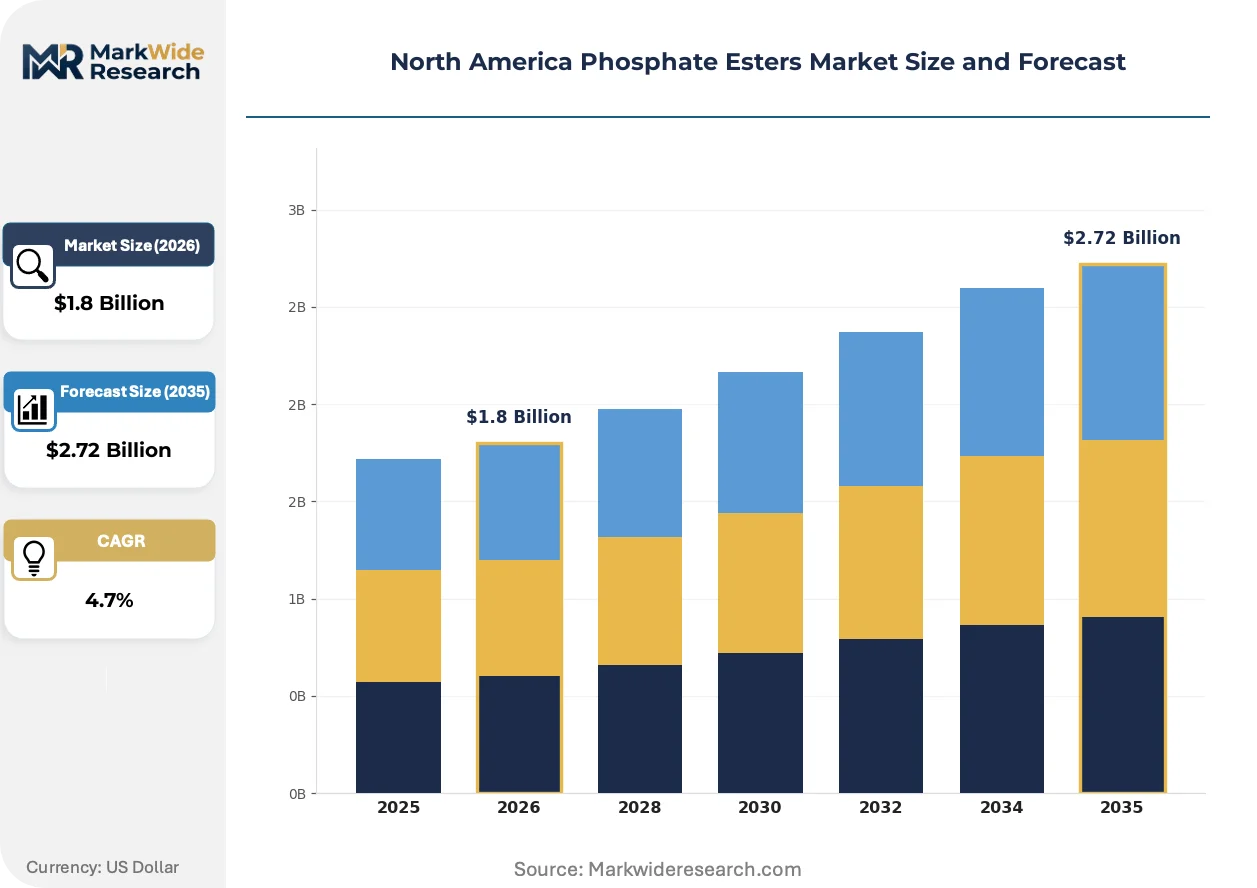
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkyl Phosphate Esters, Aryl Phosphate Esters, Phosphate Ester Amides, Glycerol Phosphate Esters Application: Food Additives, Lubricants, Surface Coatings, Plasticizers Form: Liquid, Powder, Granule, Gel End User: Chemical Industry, Pharmaceutical Sector, Food & Beverage, Automotive |
| Companies Covered | Exxon Mobil Corporation, Stepan Company, Ashland Inc., Eastman Chemical Company, Dow, Solvay, LANXESS, ICL Group, Dover Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Phosphate Esters Market Trends and Innovations
Synthetic route diversification and regulatory chemistry evolution are fragmenting established supply relationships while creating entry points for specialized compounders with differentiated environmental profiles.
Alkyl phosphate ester synthesis is fragmenting traditional aryl-dominated supply structures. Hydraulic fluid formulators in steel mills and aluminum smelters are specifying these lower-toxicity alternatives for worker safety compliance. The technology is fragmenting volume concentration among legacy aryl producers and enabling specialty alkyl manufacturers to capture specification-driven procurement decisions.
EPA's pending revisions to phosphorus discharge limits under the Clean Water Act are tightening effluent standards for chemical manufacturing facilities. Industrial laundries and metal finishing operations face accelerated compliance deadlines. Aryl phosphate ester users in Great Lakes basin states are pre-emptively reformulating to reduce environmental liability exposure before state-level enforcement intensifies.
Direct procurement relationships between phosphate ester manufacturers and end-use formulators are displacing traditional distributor intermediaries in lubricant additive channels. Large automotive fluid compounders are consolidating supplier panels and negotiating multi-year toll manufacturing agreements. This concentration is most visible in the US Southeast where transmission fluid blenders have reduced qualified supplier bases from twelve to four primary relationships.
North America Phosphate Esters Market Segmentation
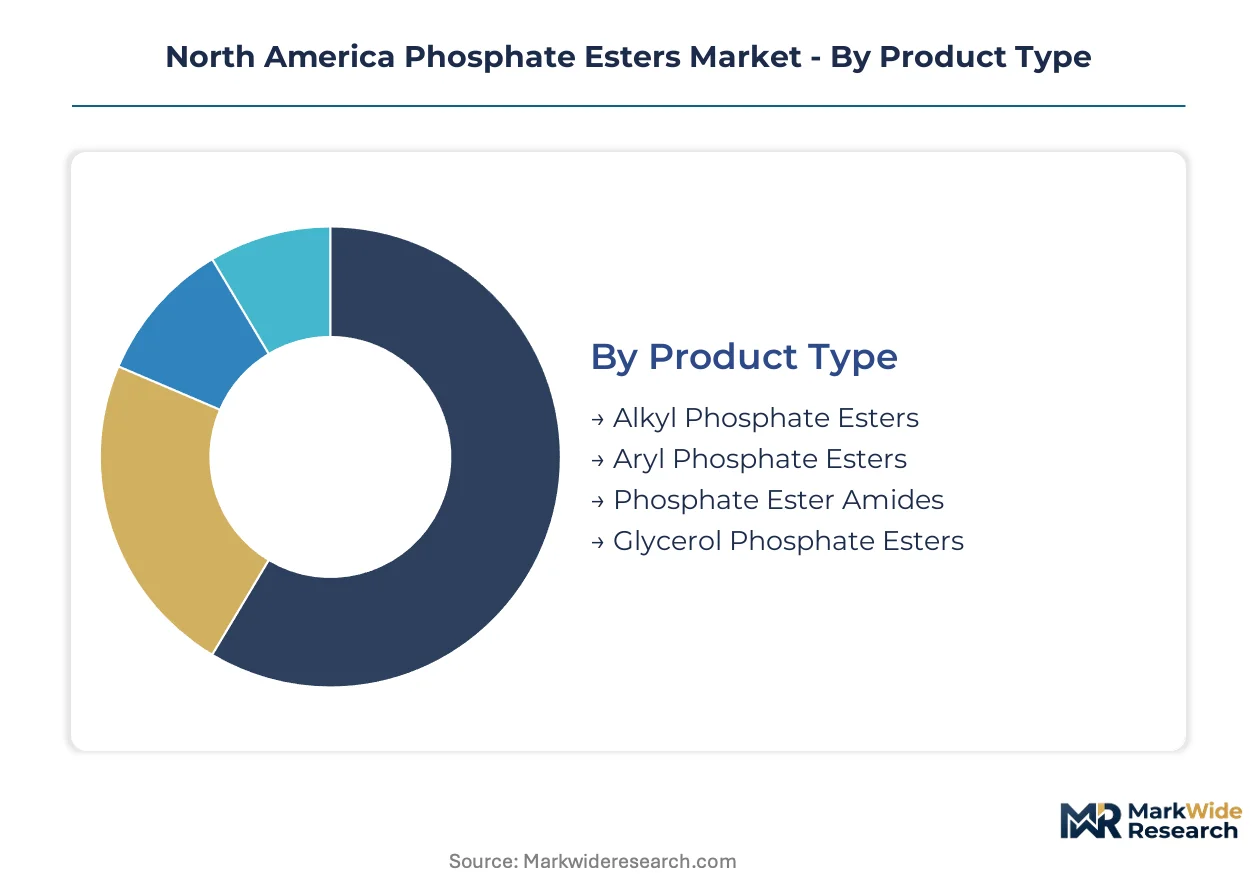
Phosphate ester procurement channels diverge sharply across product chemistries and end-use specifications. Channel selection determines margin capture, technical service intensity, and regulatory compliance burden for suppliers and buyers alike.
Product Type:
Channel mix varies by phosphorus content and toxicity profile—alkyl esters flow through industrial distributors to hydraulic fluid compounders, while aryl esters move through direct OEM supply agreements for fire-resistant applications.
- Alkyl Phosphate Esters:These compounds carry aliphatic substituents that reduce aquatic toxicity versus aryl counterparts. Demand is concentrating in Texas-Louisiana chemical corridor steel mills where OSHA workplace exposure limits are tightening. The lower toxicity profile commands specification premiums from aluminum smelter hydraulic system operators.
- Aryl Phosphate Esters:Phenol-derived structures deliver superior thermal stability and fire resistance for aerospace landing gear systems. Procurement concentrates through Factory Mutual-certified supply chains to Gulf Coast aircraft maintenance facilities. EPA phosphorus discharge scrutiny is accelerating reformulation timelines for Great Lakes basin users.
- Phosphate Ester Amides:Amide-functionalized variants serve institutional cleaning compounders seeking surfactant-grade performance with reduced environmental persistence.
- Glycerol Phosphate Esters:Bio-derived glycerol backbones attract food additive channel buyers navigating California phosphorus content restrictions.
Aryl phosphate esters dominate installed base. Alkyl phosphate esters are where expansion concentrates.
Application:
Cost tier stratification separates commodity-grade food additives from premium lubricant formulations with fire-resistance certification.
- Lubricants:Fire-resistant hydraulic specifications command the steepest technical premiums in this category. Aerospace and steel mill buyers in the US Southeast negotiate multi-year toll manufacturing agreements directly with phosphorylation specialists. Factory Mutual approval timelines extend 18-24 months, compressing supplier qualification windows.
- Plasticizers:Aryl phosphate esters anchor volume in PVC and engineered polymer compounding through established Gulf Coast supply chains. Cost structures favor incumbent producers with integrated phosphate rock processing.
- Surface Coatings:Flame-retardant coating formulators in automotive OEM paint shops specify phosphate esters for intumescent systems.
- Food Additives:Glycerol phosphate esters serve leavening acid and pH buffering applications under FDA food contact substance regulations.
Lubricants anchor margin pools. Food additives are climbing the fastest as clean-label positioning drives phosphate salt substitution.
Form:
Volume concentration favors liquid formulations for continuous process integration, while powder and granule forms serve batch compounders with precise dosing requirements.
- Liquid:Pumpable formulations dominate hydraulic fluid and metalworking coolant channels. Tanker truck delivery to Texas-Louisiana integrated processors minimizes handling costs.
- Powder:Spray-dried grades serve institutional cleaning powder blenders and food additive premix operations.
- Granule:Dust-suppressed granules attract agricultural chemical compounders with OSHA respiratory protection obligations.
- Gel:Thickened formulations target specialty coating applicators requiring sag resistance on vertical substrates.
Liquid forms dominate installed base. Gel formulations are where expansion concentrates.
End User:
Customer type determines service intensity—automotive OEMs demand collaborative formulation development while chemical industry buyers prioritize supply security.
- Automotive:Transmission fluid and metalworking coolant formulators in Queretaro and Guanajuato assembly plants are localizing procurement. USMCA tariff complexity is bypassed through Mexican toll manufacturing relationships.
- Chemical Industry:Surfactant and plasticizer compounders along the US Gulf Coast chemical corridor source through just-in-time supply agreements with integrated phosphate processors.
- Pharmaceutical Sector:Excipient-grade phosphate esters serve parenteral formulation manufacturers under FDA active pharmaceutical ingredient guidance.
- Food & Beverage:Leavening agent and emulsifier buyers navigate California and New York state-level phosphorus restrictions with reformulated low-phosphate alternatives.
Chemical industry buyers dominate installed base. Automotive sector procurement is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan phosphate rock exports supply integrated processors across the North American chemical corridor. United States Gulf Coast facilities convert this feedstock into aryl and alkyl ester formulations for lubricant and surfactant channels. Canadian and Mexican industrial buyers increasingly source through regional toll manufacturing arrangements.
United States
Texas-Louisiana chemical corridor steel mills and aerospace maintenance facilities drive aryl phosphate ester demand for fire-resistant hydraulic specifications. EPA Clean Water Act enforcement tightens phosphorus discharge limits at Gulf Coast processing plants. Houston-area integrated phosphate clusters enable just-in-time surfactant production for institutional cleaning compounders.
Canada
Ontario automotive transmission fluid blenders and Quebec aerospace suppliers anchor phosphate ester procurement for metalworking and hydraulic applications. Health Canada regulates phosphate ester residues in food contact substances under Food and Drugs Act guidelines. Toronto-Windsor manufacturing corridor buyers negotiate direct supply agreements bypassing traditional distributor channels.
Mexico
Queretaro and Guanajuato automotive assembly plants localize phosphate ester sourcing for transmission fluid formulations. USMCA tariff provisions incentivize toll manufacturing relationships with US Gulf Coast suppliers. Mexico City industrial chemical distributors consolidate procurement for northern border state metalworking operations.
North America Phosphate Esters Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and specification certification dimensions. The North America Phosphate Esters Market structures around three tiers: integrated petrochemical majors with captive phosphorus supply, mid-cap specialty chemical houses with Factory Mutual approvals, and regional toll manufacturers serving automotive clusters. Strategic archetypes include backward-integrated phosphate rock processors, formulation specialists with aerospace certification, and distributor-forward surfactant compounders. Dominant competitive moves involve multi-year toll manufacturing agreements and capacity consolidation around Gulf Coast chemical corridor infrastructure.
Among integrated petrochemical majors, Exxon Mobil Corporation exemplifies scale-driven supply chain control through lubricant distribution networks. Eastman Chemical Company and Stepan Company occupy positions within the specialty formulation tier, with Kingsport-based aryl capacity and surfactant-grade expertise respectively. These three anchors represent distinct competitive vectors: captive raw material access, fire-resistance certification depth, and institutional cleaning channel penetration.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Stepan Company |
| Ashland Inc. |
| Eastman Chemical Company |
| Dow |
| Solvay |
| LANXESS |
| ICL Group |
| Dover Chemical |
| Others |
Pricing and Supply Chain Analysis
Multi-year toll manufacturing agreements between phosphate ester producers and automotive fluid compounders lock in both supply access and price visibility across the North American market. These contracts insulate integrated Gulf Coast processors from Moroccan phosphate rock freight volatility while securing volume commitments from transmission fluid blenders in Queretaro and Guanajuato.
Pricing Analysis
Current-generation alkyl phosphate esters command specification premiums over prior-generation aryl formulations due to tightening OSHA workplace exposure limits. Three-tier pricing structure across Factory Mutual-certified, UL-listed, and uncertified grades separates aerospace procurement from steel mill bulk purchasing. Pricing pressure stems from polyol ester substitution in commercial aviation hydraulic systems. Food additive buyers exhibit highest price sensitivity as glycerol phosphate esters compete with phosphate salt alternatives.
Supply Chain Analysis
Ocean freight congestion on Morocco-Texas trade lanes elevates inbound logistics costs for phosphate rock concentrate shipments. Supply concentrates in Morocco, Jordan, and the Texas-Louisiana chemical corridor. Phosphorus pentachloride, phenol derivatives, and aliphatic alcohols constitute critical raw material dependencies. Single-source vulnerability runs through Moroccan OCP Group export channels. Distribution runs through direct OEM supply agreements for lubricant additives and industrial distributor networks for surfactant-grade formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Phosphate ester demand sits in early-cycle expansion as fire-resistant hydraulic fluid specifications penetrate beyond aerospace into steel mill and aluminum smelter applications. This specification upgrade tailwind creates durable procurement relationships for qualified suppliers.
For Market Incumbents: Shield installed base relationships by securing Factory Mutual certification renewals before 18-24 month approval windows compress further. Deepen backward integration into phosphate rock processing through Gulf Coast capacity consolidation. Polyol ester substitution in aviation represents the primary substitution threat requiring technical service investment to defend specification position. For New Entrants and Emerging Players: Lead with bio-based alcohol feedstock pathways serving California institutional cleaning compounders navigating state phosphorus restrictions. Mexican automotive manufacturing expansion offers the most penetrable geography for toll manufacturing relationships. Position around sustainability credentials and low-toxicity alkyl ester formulations to bypass incumbent aryl supply chain lock-in. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap specialty houses with Factory Mutual approvals and captive Gulf Coast infrastructure. The five-to-ten year viability window favors processors with integrated phosphorus supply and aerospace certification depth. Monitor EPA Clean Water Act enforcement intensity in Great Lakes basin states as inflection indicator for reformulation-driven demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Processing | Captive Moroccan concentrate supply insulates margin structures from ocean freight volatility. |
| Factory Mutual Certification Investment | 18-24 month approval timelines create defensive moats against uncertified competitors. |
| Bio-Based Alcohol Feedstock Transition | Renewable isobutanol pathways attract California institutional cleaning procurement. |
| Mexican Toll Manufacturing Expansion | Queretaro proximity bypasses USMCA tariff complexity for automotive fluid compounders. |
| Long-Term Supply Agreement with Aerospace OEMs | Multi-year contracts anchor aryl ester volume through landing gear specification cycles. |
Research Methodology
Desk research of customs trade data, SEC chemical company filings, and EPA enforcement records preceded structured interviews with phosphate ester plant managers, automotive fluid procurement leads, and institutional cleaning compounder technical directors. Primary fieldwork across Texas-Louisiana chemical corridor facilities combined with secondary validation from American Chemistry Council reports and Factory Mutual approval databases. Bottom-up volume modeling triangulated against top-down industry association estimates.
Variance decomposition across product chemistry, application specification, and end-use industry dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from segment-level demand elasticity modeling and input cost trajectory assumptions. Phosphate rock import dependency ratios and fire-resistant specification adoption curves served as industry-specific forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement intensity or stable Moroccan export flows would require recalibration. Forecasts reflect assumptions regarding specification upgrade timelines and bio-based feedstock cost parity. Geopolitical interruption of phosphate rock supply or accelerated polyol ester substitution in aviation would revise volume projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Supplemental Coolant Additives Market
Additives
FD and C Lakes Market
Additives
Global Flame Retardant Masterbatches Market
Additives
Global Lubricating Oil Additives Market
Additives
Performance Minerals Additives Market
Additives
Polyols and Sorbitols Products Market
Additives
Sodium Stearyl Fumarate Market
Additives
Global PVC Stabilizer Market
Additives
Asia Pacific Plastic Additives Market
Additives
Anti-Slip Additives Market
Additives
Polysorbate-80 Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Phthalic Anhydride Derivatives Market
Additives
Ethoxyquin Market
Additives
United States Citric Acid Market
Additives
Glyceryl Caprylate Market