
 Global Pour Point Depressant Market | 2026-2036
Global Pour Point Depressant Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pour Point Depressant Market Foresight
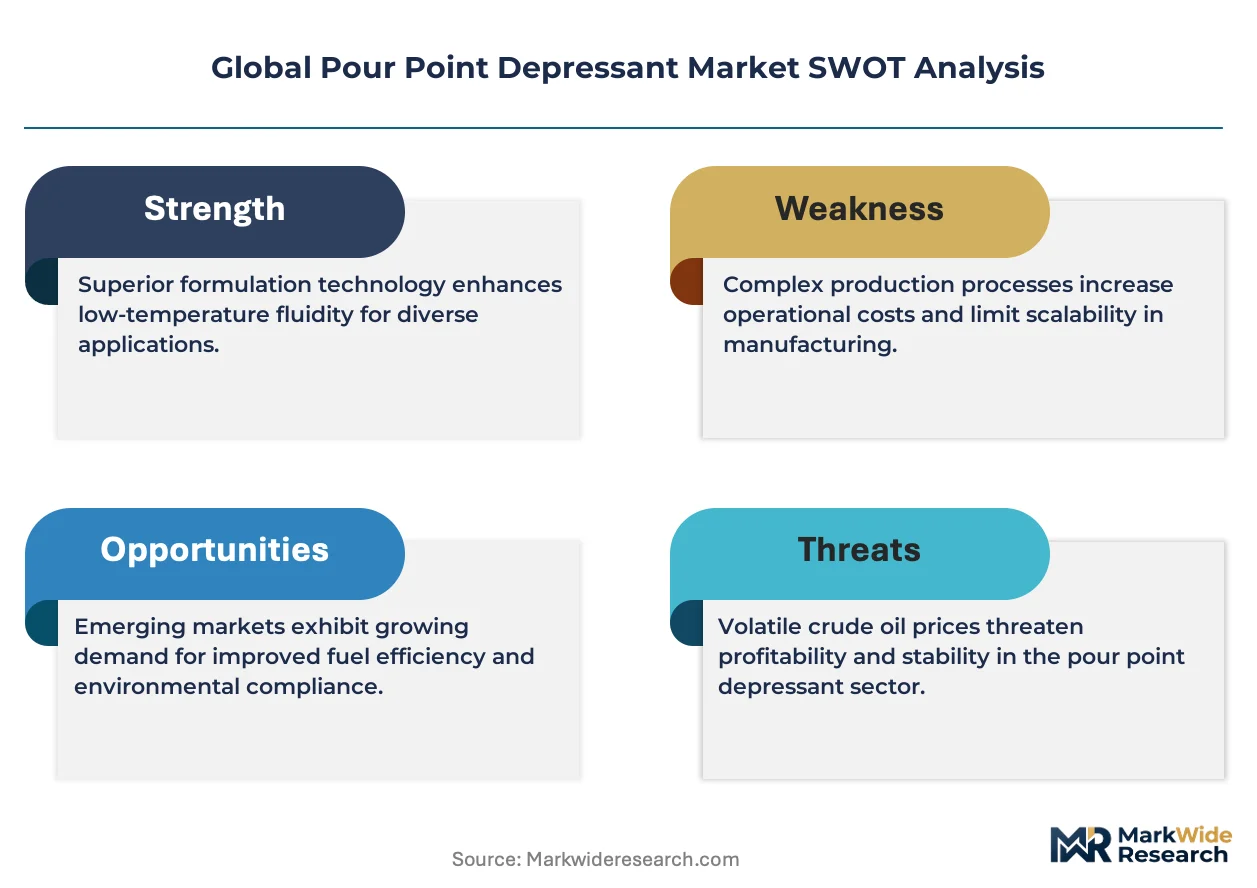
Multi-additive bundled packages is consolidating as the dominant procurement format across industrial lubricant buyers, reducing standalone pour point depressant purchases in favor of integrated cold-flow solutions. Clariant leverages its polymer synthesis expertise to anchor supply relationships with European blending houses. The Lubrizol Corporation sustains technology leadership through proprietary methacrylate backbone architectures. Evonik Industries differentiates via ester-based formulations targeting arctic-grade hydraulic systems.
Pour point depressants are polymeric or ester-based additives that disrupt paraffin crystal lattice formation in hydrocarbon fluids, typically effective at treat rates between 0.1% and 1.0% by weight, enabling petroleum products to maintain pumpability at temperatures below their natural gel point. Polymer formulations dominate volume demand due to established supply chains and predictable performance across mid-range temperature applications, while ester chemistry captures premium positioning in aerospace and subsea drilling fluids where biodegradability requirements apply. Ethylene-vinyl acetate copolymers occupy a mature niche in transformer oil specifications, with limited growth but stable replacement demand from utility infrastructure operators.
REACH registration requirements in Europe mandate full toxicological dossiers for polymer and ester chemistries, elevating compliance costs for new market entrants while reinforcing incumbent positions. EPA fuel and additive regulations under the Clean Air Act framework influence formulation choices in United States lubricant blending operations, particularly regarding volatile organic compound thresholds. Stakeholders must monitor evolving F-Gas Regulation interactions with cold-chain logistics, as refrigerant-lubricant compatibility testing creates secondary demand channels for specialized pour point chemistries.
Market Dynamics
Multi-additive bundled procurement is compressing standalone pour point depressant volumes as lubricant blenders consolidate cold-flow chemistry into integrated packages, forcing specialty additive suppliers to anchor within broader formulation partnerships.
Growth Catalysts
- Arctic pipeline expansion:Russia's Siberian oilfields require continuous pour point management to maintain winter throughput, driving sustained procurement of polymer-based formulations.
- REACH compliance deadlines:ECHA registration requirements for new chemistries are locking in incumbent suppliers with existing toxicological dossiers.
- Biodegradable hydraulic fluids:Esters with pour point functionality capture specification wins in subsea drilling and aerospace applications where environmental discharge limits apply.
Market Restraints
- Ethylene-vinyl acetate supply concentration:Transformer oil specifications depend on mature EVA copolymers with limited supplier diversity and stagnant replacement demand.
- Base oil volatility:Paraffinic crude sourcing disruptions in key production zones inflate formulation costs unpredictably.
- Regulatory friction from F-Gas interactions:Refrigerant-lubricant compatibility testing creates secondary certification burdens that delay product launches.
Strategic Opportunities
- India's cold-chain infrastructure:PLI scheme incentives for refrigerated transport equipment generate downstream demand for specialized low-temperature lubricant additives.
- Wind turbine gearbox fluids:Offshore installations in the North Sea specify arctic-grade formulations with combined pour point and oxidation stability performance.
- Digital blending optimization:AI-driven treat rate prediction enables just-in-time additive dosing that reduces inventory carrying costs for mid-size blenders.
Industry Challenges
- Polymer synthesis talent scarcity:Specialized methacrylate backbone chemists command premium compensation, constraining R&D expansion at regional suppliers.
- REACH dossier maintenance:ECHA requires continuous toxicological data updates that consume technical resources without generating revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pour Point Depressant Market |
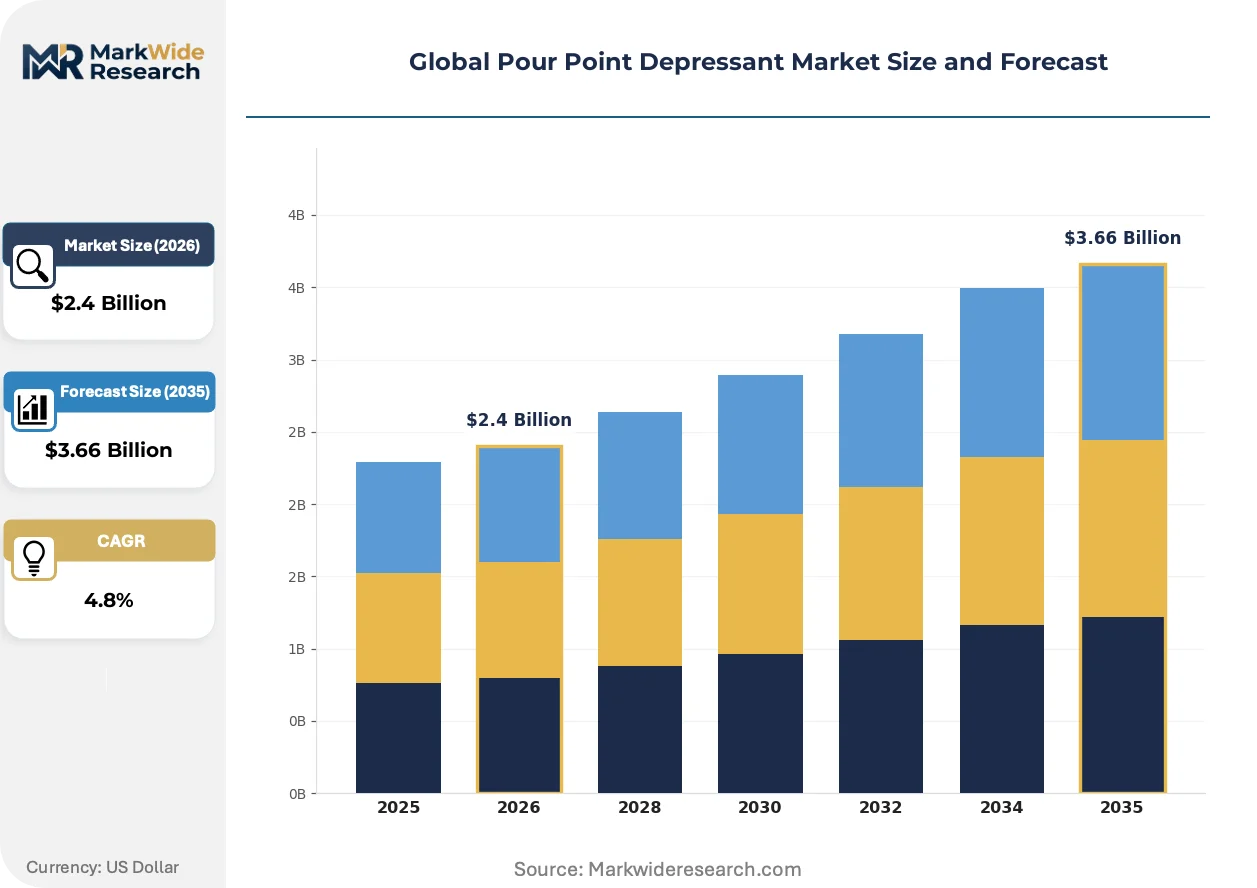
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.66 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymer, Ester, Ethylene-Vinyl Acetate, Phenol-Formaldehyde, Others Application: Industrial Lubricants, Drilling Fluids, Hydraulic Fluids, Metalworking Fluids, Transformer Oil End User: Oil & Gas Companies, Manufacturing Plants, Chemical Processing Units, Power Generation Firms, Automotive Suppliers Form: Liquid, Powder, Emulsion, Granular, Paste |
| Companies Covered | Clariant, The Lubrizol Corporation, Evonik Industries, Afton Chemical, Infineum International, Ecolab, BASF SE, Croda International Plc, Innospec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pour Point Depressant Market Shifts & Advancements
Formulation chemistry is pivoting toward integrated performance bundles that combine pour point depression with viscosity index improvement and oxidative stability, collapsing the historical silo of standalone cold-flow additives.
Ester-based biodegradable chemistries are overtaking conventional polymer formulations in premium hydraulic applications. These molecules deliver comparable low-temperature fluidity while meeting OECD 301B biodegradability thresholds. Offshore drilling contractors in the Norwegian continental shelf specify ester pour point depressants exclusively, compressing polymer share in this high-value segment.
EPA fuel and additive regulations under the Clean Air Act framework are tightening volatile organic compound thresholds in lubricant blending operations. This pressure is forcing reformulation of solvent carriers used in additive packages. United States mid-continent blenders are responding by shifting toward low-VOC delivery systems that maintain pour point performance without compliance penalties.
Long-term supply agreements are displacing spot purchasing across European industrial lubricant buyers. These contracts bundle pour point depressants with corrosion inhibitors and anti-wear agents, locking in volume commitments. Germany's automotive supplier cluster exhibits this pattern most visibly, with tier-one component manufacturers negotiating three-year additive packages directly with blending houses.
Global Pour Point Depressant Market Segmentation
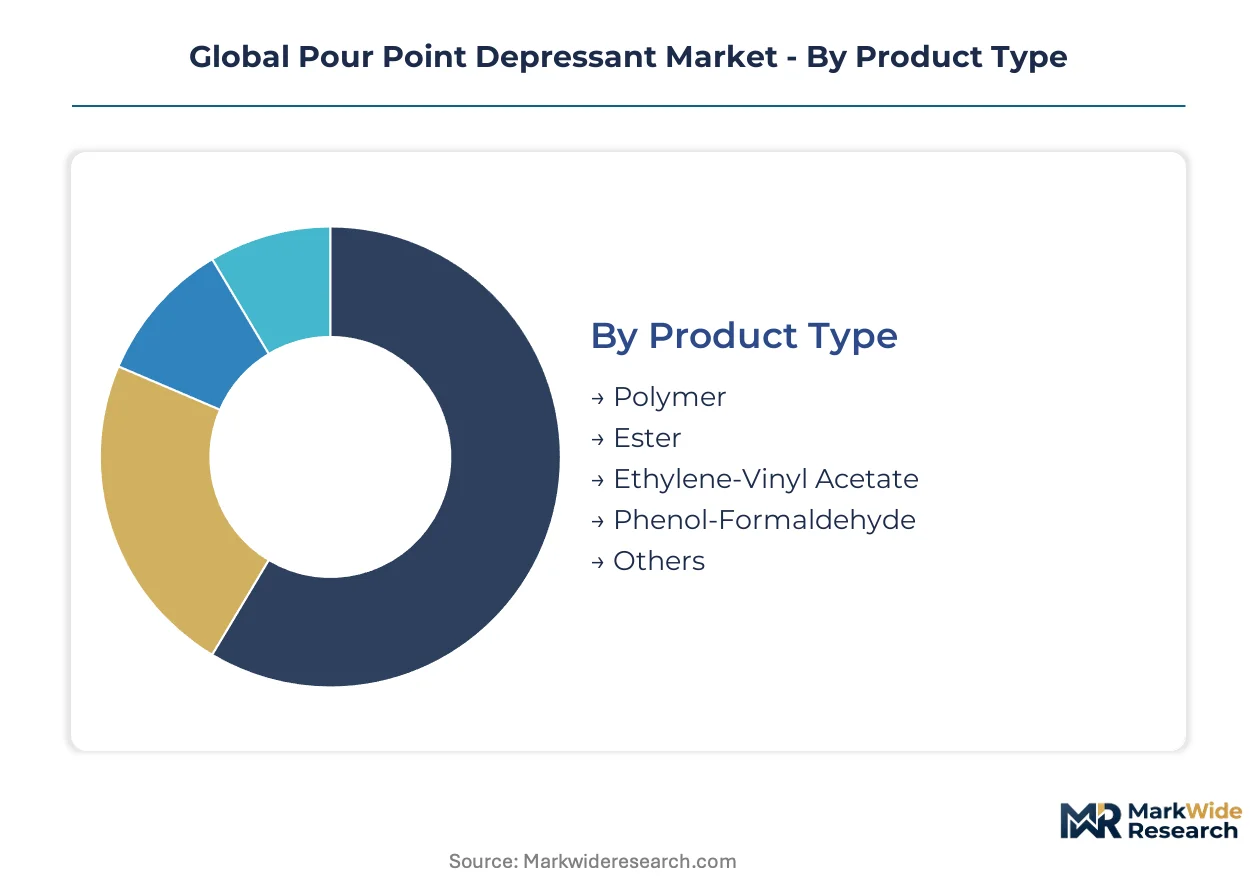
Pour point depressant procurement varies sharply across chemistry types, application environments, and buyer operational profiles. Segment boundaries determine formulation specifications, treat rate economics, and regulatory compliance pathways.
Product Type:
Buyers select chemistry based on temperature performance requirements and environmental discharge constraints.
- Polymer:Methacrylate and alkyl methacrylate copolymers dominate volume procurement through established synthesis infrastructure and predictable performance across mid-range arctic conditions. Oil & gas operators in Russia's Siberian fields specify polymer formulations for pipeline throughput assurance where temperatures plunge below minus 40 degrees Celsius.
- Ester:Synthetic ester chemistry delivers biodegradability compliance alongside pour point depression, capturing specification wins in subsea drilling and aerospace hydraulic systems where OECD 301B standards apply. Norwegian continental shelf contractors mandate ester formulations exclusively.
- Ethylene-Vinyl Acetate:Mature copolymer chemistry serves transformer oil specifications with stable replacement demand from utility infrastructure operators.
- Phenol-Formaldehyde:Condensation polymer chemistry occupies niche applications in specialized industrial lubricant formulations.
- Others:Proprietary and experimental chemistries including polyalkylmethacrylate variants and hybrid molecular architectures.
Polymer leads on scale; ester leads on momentum.
Application:
Operating temperature regimes and fluid contamination risks dictate additive selection across use cases.
- Industrial Lubricants:Multi-additive bundled procurement compresses standalone pour point depressant volumes as blenders integrate cold-flow chemistry with viscosity index improvers and anti-wear agents.
- Drilling Fluids:Arctic and subsea drilling contractors specify ester-based formulations where environmental discharge limits apply, particularly in North Sea regulatory jurisdictions.
- Hydraulic Fluids:Offshore wind turbine installations in the North Sea demand arctic-grade formulations combining pour point depression with oxidation stability.
- Metalworking Fluids:Machining operations require low-temperature pumpability for centralized coolant systems in unheated manufacturing facilities.
- Transformer Oil:Utility infrastructure replacement cycles sustain steady demand for EVA-based pour point management in electrical insulation fluids.
Industrial lubricants anchor volume commitments; drilling fluids command premium pricing.
End User:
Procurement sophistication and technical specification authority vary dramatically across buyer categories.
- Oil & Gas Companies:Integrated majors and national oil companies negotiate long-term supply agreements directly with additive houses, bundling pour point depressants with corrosion inhibitors and demulsifiers.
- Manufacturing Plants:Automotive supplier clusters in Germany negotiate three-year additive packages through blending house intermediaries, consolidating multi-additive procurement.
- Chemical Processing Units:Petrochemical facilities require cold-flow assurance for intermediate product storage and transfer in temperate climates.
- Power Generation Firms:Utility operators specify transformer oil additives through equipment OEM recommendations and industry standard compliance.
- Automotive Suppliers:Tier-one component manufacturers integrate pour point functionality into transmission and axle fluid specifications.
Oil & gas companies concentrate procurement volume; automotive suppliers drive specification innovation.
Form:
Physical delivery format determines blending equipment compatibility and treat rate precision.
- Liquid:Pumpable concentrates enable automated dosing systems at high-throughput blending facilities, dominating industrial lubricant and hydraulic fluid applications.
- Powder:Solid-state delivery suits remote drilling operations where liquid storage poses logistical constraints.
- Emulsion:Water-based dispersions serve specialized metalworking fluid formulations requiring compatibility with aqueous coolant systems.
- Granular:Free-flowing solid form factors facilitate manual dosing in small-batch blending operations.
- Paste:High-viscosity delivery systems target applications requiring precise localized application or compatibility with thickener-stabilized base stocks.
Liquid dominates operational throughput; emulsion gains share in water-based formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pour point depressant chemistry originated in German industrial laboratories during the mid-20th century, where methacrylate polymer synthesis first enabled systematic wax crystal modification. The technology subsequently migrated to North American petroleum corridors and Russian arctic extraction zones as cold-climate operational requirements intensified.
Russia
Siberian oilfield operators consume polymer formulations at scale to maintain pipeline throughput through winter temperatures below minus 40 degrees Celsius. The country's technical regulations mandate continuous pour point management for trunk pipeline certification. Tyumen and Novy Urengoy anchor procurement clusters where national oil companies negotiate direct supply agreements with additive houses.
United States
Gulf Coast lubricant blenders integrate cold-flow chemistry into multi-additive packages serving the Permian Basin's winterized drilling operations. EPA fuel and additive regulations under the Clean Air Act framework tighten volatile organic compound thresholds in blending operations. Houston's petrochemical corridor concentrates formulation R&D and toll manufacturing capacity for domestic distribution.
Germany
Automotive supplier clusters in Baden-Württemberg negotiate three-year bundled additive packages through blending house intermediaries. REACH registration requirements mandate full toxicological dossiers for polymer and ester chemistries, elevating compliance costs for new entrants. Ludwigshafen's chemical manufacturing hub sustains incumbent supplier positions through established ECHA dossier maintenance.
Norway
North Sea offshore drilling contractors specify ester-based formulations exclusively where OECD 301B biodegradability standards apply to subsea discharge. The country's petroleum regulator enforces strict environmental compliance for arctic-grade hydraulic fluids. Stavanger's oilfield services cluster drives specification innovation through integrated contractor procurement.
India
Cold-chain infrastructure expansion under the PLI scheme generates downstream demand for specialized low-temperature lubricant additives in refrigerated transport equipment. The Bureau of Indian Standards issues evolving specifications for transformer oil and industrial lubricant formulations. Gujarat's chemical manufacturing belt attracts additive blending investments serving domestic agriculture and logistics sectors.
Global Pour Point Depressant Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and regulatory dossier depth. The vendor base organizes into three tiers: integrated chemical majors with captive polymer synthesis, specialized additive houses with proprietary backbone architectures, and regional blenders sourcing white-label chemistries. Strategic moves concentrate on long-term supply agreement negotiation and integrated performance bundle development combining pour point depression with viscosity index improvement.
Within the integrated chemical major tier, BASF SE and Evonik Industries exemplify European-based incumbents leveraging established REACH dossiers to defend market position. Clariant and Croda International Plc occupy specialist positions anchored in polymer synthesis expertise and ester chemistry capabilities respectively. The Lubrizol Corporation represents the dedicated additive house archetype with focused methacrylate technology development. These named entities illustrate how geographic origin and company structure correlate with competitive positioning across regulatory jurisdictions and application segments.
| Leading Market Players |
|---|
| Clariant |
| The Lubrizol Corporation |
| Evonik Industries |
| Afton Chemical |
| Infineum International |
| Ecolab |
| BASF SE |
| Croda International Plc |
| Innospec |
| Others |
Supply & Pricing Matrix
Oil & gas procurement officers in Russia's Siberian fields anchor volume demand through multi-year supply agreements, locking in polymer-based pour point depressant pricing through integrated cold-flow packages rather than standalone additive purchases.
Pricing Analysis
Contract-based long-term offtake dominates procurement, with pricing stratifying across premium ester formulations, standard methacrylate polymers, and economy-grade EVA copolymers. REACH dossier depth and biodegradability certification tier drive price differentiation between European and Asian supply origins. Cost compression in the EVA segment intensifies as transformer oil replacement cycles stagnate. Mid-size lubricant blenders exhibit highest price sensitivity, while national oil companies prioritize performance assurance over unit economics.
Supply Chain Analysis
REACH and EPA certification requirements gate supply participation, concentrating qualified production in Germany, the United States, and Russia. Methacrylate monomer and specialized ester feedstock supply draws from petrochemical corridors in Ludwigshafen and Houston. Single-source vulnerability persists for arctic-grade ester formulations where Norwegian continental shelf specifications limit approved suppliers. Distribution runs through blending house intermediaries that bundle pour point depressants with complementary additives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where biodegradable ester specifications and integrated performance bundles displace commodity polymer volumes.
For Market Incumbents: Deepen backward integration into methacrylate monomer supply to defend margin position against feedstock volatility. Anchor long-term supply agreements with Russia's national oil companies before REACH dossier maintenance costs escalate. Prioritize ester synthesis R&D to capture Norwegian continental shelf specifications. For New Entrants and Emerging Players: Blending house intermediaries in India's Gujarat chemical belt represent the most penetrable channel for white-label ester formulations. Target cold-chain infrastructure procurement under the PLI scheme where specification standards remain fluid. Lead with biodegradable hydraulic fluid certifications to bypass entrenched polymer relationships. For Investors and Strategic Acquirers: Integrated chemical majors with captive polymer synthesis are the most active acquirer in this space, consolidating specialist additive houses to complete bundled offering portfolios. The five-to-ten year viability window favors targets with established ECHA dossiers and arctic-grade formulation libraries. Watch for F-Gas Regulation expansion into refrigerant-lubricant compatibility testing as an inflection signal for specialized pour point chemistry demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Monomer | Captive feedstock supply insulates margin from ethylene price volatility in Gulf Coast corridors. |
| Long-term Supply Agreement with National Oil Companies | Russia's Siberian operators lock in three-year polymer volumes through direct additive house contracts. |
| Green Manufacturing Transition to Biodegradable Esters | OECD 301B compliance opens Norwegian continental shelf and aerospace hydraulic specifications. |
| Joint Venture with Blending House Intermediaries | Germany's automotive supplier clusters bundle pour point depressants through tier-one negotiated packages. |
| Capacity Expansion in Cold-Chain Logistics Corridors | India's PLI scheme incentives for refrigerated transport generate downstream additive demand in Gujarat. |
Research Methodology
Multiple input streams — additive procurement managers at oil & gas majors, lubricant blending house technical directors, ECHA regulatory affairs specialists, and polymer synthesis R&D leads — were reconciled against customs trade data, SEC chemical sector filings, REACH registration databases, and IEA arctic extraction reports. Bottom-up treat rate modeling across application segments was cross-validated with top-down market sizing from regional production capacity disclosures.
Data-stream reconciliation anchored volume projections across chemistry type, end-use industry, and regional regulatory cluster throughout the forecast period. Segmentation dimensions modeled included product chemistry, application environment, buyer procurement sophistication, and physical delivery format. CAGRs were derived from slope analysis of historical procurement volumes against projected arctic pipeline expansion and cold-chain infrastructure buildout schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to REACH dossier renewal timelines and F-Gas Regulation expansion scope. Model outputs reflect assumptions about polymer synthesis capacity additions and biodegradability standard adoption rates across offshore drilling jurisdictions. A model refresh is warranted upon material change in ECHA registration fee structures or Siberian pipeline throughput certification requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Matting Agents Market
Additives
Middle East Lubricant Additives Market
Additives
Encapsulated Citric Acid Market
Additives
Potassium Nitrate Market
Additives
Canada Water Enhancer Market
Additives
Ethoxyquin Market
Additives
Feed Additives Market
Additives
Global UV Stabilizers Market
Additives
Plastics Modifiers Market
Additives
Liquid Thickeners Market
Additives
1,4 Butanediol Derivatives Market
Additives
Metal Modifiers Market
Additives
Europe UV Stabilizers Market
Additives
Dispersing Agents Market
Additives
Cold Flow Improvers Market
Additives
Global Carboxylic Acids Based Esters Market