
 Cosmetic Grade Color Additives Market | 2026-2036
Cosmetic Grade Color Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Cosmetic Grade Color Additives Market Analytics
Iron oxide pigments are repositioning titanium dioxide in sunscreen and foundation formulations due to consumer preference for reef-safe mineral alternatives. BASF SE leverages its integrated pigment production network across Europe to sustain supply security for cosmetic manufacturers. Clariant AG anchors its position through specialized surface-treated pigments that enhance dispersion in water-based foundations. Sensient Technologies Corporation differentiates via botanical-derived colorant technologies that navigate clean-label certification requirements.
Cosmetic grade color additives are purified colorants formulated to meet stringent limits on heavy metals, microbial contamination, and residual solvents, typically achieving particle sizes below 10 microns for optimal skin adhesion and optical performance. These materials serve primarily to impart hue, opacity, or visual effects in personal care products while maintaining dermal safety profiles. Pigments dominate the product type landscape due to their light stability and broad regulatory acceptance across jurisdictions, whereas lake colors represent the fastest-expanding category as brands seek water-insoluble options for long-wear lip and eye formulations. Within applications, makeup commands the largest volume allocation, while skin care colorants capture expanding margin pools as tinted moisturizers and color-correcting serums proliferate.
FDA Title 21 CFR regulations govern permitted color additives in the United States, while REACH and the EU Cosmetics Regulation impose purity and labeling standards across Europe, collectively shaping reformulation cycles and raw material qualification timelines. China's NMPA and GB standards for cosmetic ingredients are tightening documentation requirements for imported colorants, affecting market access protocols for foreign suppliers. Stakeholders must monitor evolving regulatory divergence between major jurisdictions to anticipate reformulation investments and qualification delays.
Market Dynamics
Clean-label certification requirements are forcing cosmetic manufacturers to requalify entire colorant portfolios, compressing supplier qualification timelines and elevating botanical-derived alternatives above petroleum-based lakes.
Growth Catalysts
- Mineral sunscreen reformulation:Hawaii and Palau reef-safe mandates are accelerating iron oxide substitution for titanium dioxide in SPF formulations, creating dedicated supply channels for cosmetic-grade mineral pigments.
- China domestic premiumization:NMPA streamlined approval pathways for imported colorants serving local manufacturers scaling color-correcting skincare lines.
- Surface treatment advances:Silane and polymer encapsulation technologies enable water-dispersible pigments in anhydrous lipsticks, expanding formulation flexibility for long-wear color cosmetics.
Market Restraints
- Heavy metal testing costs:REACH and FDA tightening of arsenic, lead, and mercury thresholds requires batch-level ICP-MS analysis, adding fixed cost per production run regardless of volume.
- Mica supply concentration:Jharkhand and Bihar districts in India supply 25% of global cosmetic mica, creating geographic single-point vulnerability for pearlescent effect pigments.
- Synthetic dye substitution ceiling:FD&C Red No. 40 and Yellow No. 5 remain irreplaceable for vivid water-soluble applications where botanical alternatives achieve insufficient chroma saturation.
Strategic Opportunities
- Biotechnology-derived colorants:Precision fermentation of violacein and prodigiosin pigments offers batch-to-batch consistency unavailable in agricultural botanical extracts, attracting investment from clean-beauty brands.
- Halal certification expansion:Indonesia's BPJPH and Malaysia's JAKIM halal mandates for colorants create first-mover advantage for suppliers achieving alcohol-free and animal-derivative-free production.
- Color cosmetic skincare hybridization:Tinted serums with niacinamide or vitamin C delivery require pH-stable pigments, opening formulation partnerships between colorant suppliers and active ingredient houses.
Industry Challenges
- Toxicological assessor scarcity:Qualified cosmetic safety assessors familiar with SCCS guidelines and local equivalent frameworks command premium compensation, extending product launch timelines.
- Legacy ERP integration:Batch genealogy tracking for REACH Article 33 compliance requires retrofitting manufacturing execution systems at mid-tier pigment houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cosmetic Grade Color Additives Market |
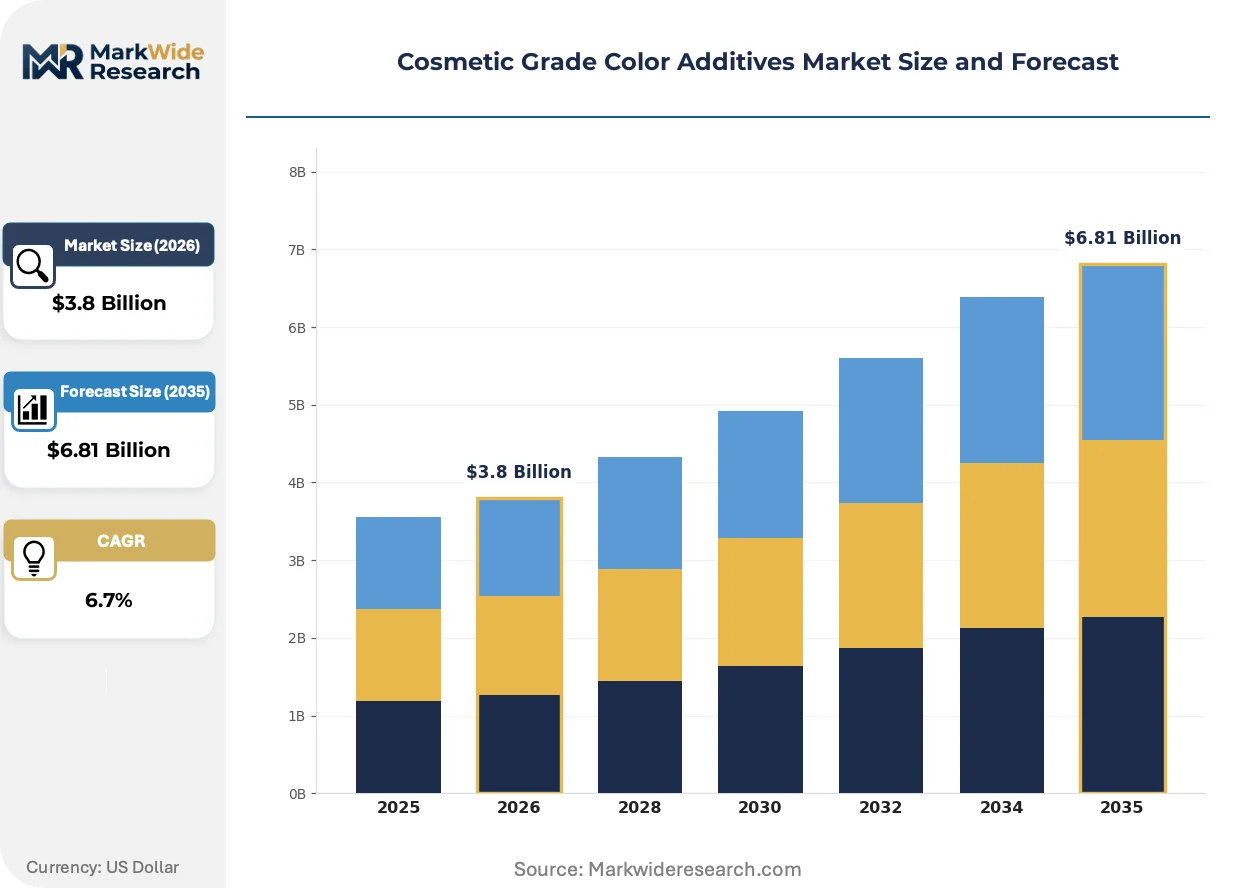
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Pigments, Lake Colors, Mica Application: Skin Care, Hair Care, Makeup, Nail Products Form: Liquid, Powder, Gel, Solid End User: Manufacturers, Retailers, Wholesalers, Distributors |
| Companies Covered | DIC Corporation, DyStar Singapore Pte Ltd, BASF SE, Lanxess AG, Huntsman Corporation, Clariant AG, Merck KGaA, Ferro Corporation, Sensient Technologies Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cosmetic Grade Color Additives Market Evolving Landscape
Multi-functional colorants that deliver optical performance alongside active ingredient protection are compressing the traditional separation between color cosmetic and skincare supply chains.
Encapsulated pigment technologies with triggered-release shells are unifying color deposition with moisture or pH-responsive activation. Premium foundation brands in South Korea and France are adopting these systems for 12-hour wear claims without oxidation-induced shade shifting. This convergence is compressing the supplier base toward houses with in-house encapsulation capabilities.
REACH restriction proposals for microplastic-containing glitter are forcing reformulation of eye and body products toward cellulose-based biodegradable alternatives. The European Chemicals Agency consultation timeline is compressing product development cycles for holiday 2026 collections. Specialty chemical distributors are stockpiling compliant effect materials ahead of anticipated enforcement.
Direct-to-consumer sampling programs are fragmenting bulk colorant procurement into smaller, SKU-diverse orders. Indie beauty brands in Los Angeles and Seoul now specify 5-kilogram minimums across 20 shade variants rather than 500-kilogram single-SKU commitments. Pigment houses are responding with modular production cells and digital color-matching platforms that compress custom shade development from weeks to days.
Cosmetic Grade Color Additives Market Segmentation
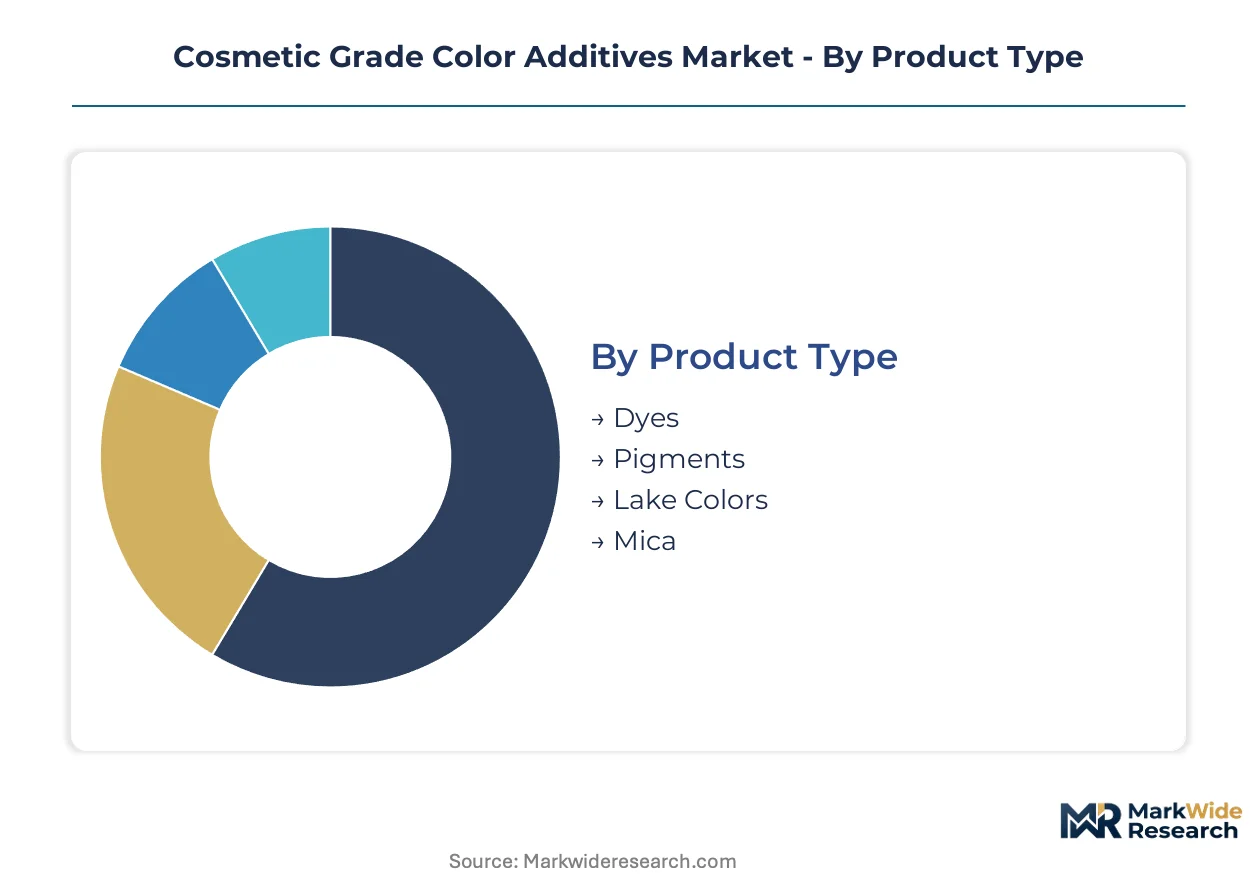
Color additive procurement patterns diverge sharply between high-volume commodity pigments and specialized surface-treated grades commanding formulation premiums. Segmentation clarity enables suppliers to align production assets with the divergent technical and regulatory requirements of each category.
Product Type:
Pigments anchor volume flows through their broad regulatory acceptance and light stability, while lake colors capture expanding premium allocation as water-insoluble alternatives gain traction.
- Pigments:Inorganic and organic particulate colorants achieving particle sizes below 10 microns for optimal skin adhesion. Iron oxide and titanium dioxide variants dominate sunscreen and foundation formulations in the United States, where FDA Title 21 CFR compliance remains mandatory for mineral SPF claims.
- Lake Colors:Water-insoluble complexes formed by precipitating soluble dyes onto aluminum or calcium substrates. Demand concentrates in long-wear lip and eye formulations across France and South Korea, where 12-hour wear claims require oxidation-resistant color deposition.
- Dyes:Water-soluble colorants delivering vivid chroma in aqueous systems. FD&C Red No. 40 and Yellow No. 5 remain irreplaceable for water-based applications where botanical alternatives achieve insufficient saturation.
- Mica:Naturally occurring silicate minerals providing pearlescent optical effects. Jharkhand and Bihar districts in India supply concentrated feedstock, creating geographic vulnerability for shimmer and glow formulations.
Today's leader: Pigments. Tomorrow's challenger: Lake Colors.
Application:
Makeup commands the largest absolute volume allocation, though skin care colorants are capturing expanding margin pools as hybrid tinted treatments proliferate.
- Makeup:Colorants for foundation, lipstick, eyeshadow, and concealer formulations requiring batch-to-batch shade consistency. Foundation brands in South Korea and France drive adoption of encapsulated pigments with triggered-release shells for oxidation-resistant wear claims.
- Skin Care:Tinted moisturizers, color-correcting serums, and SPF hybrids integrating niacinamide or vitamin C delivery. NMPA streamlined approval pathways in China are accelerating domestic premiumization for color-correcting skincare lines.
- Hair Care:Permanent, semi-permanent, and temporary colorants for consumer and professional use. REACH and FDA tightening of heavy metal thresholds requires batch-level ICP-MS analysis for lead and arsenic compliance.
- Nail Products:Pigments and dyes for lacquers, gels, and dip powder systems. Solvent-resistant grades face reformulation pressure as clean-label certification requirements expand.
Makeup retains volume dominance. Skin Care posts the steepest expansion trajectory.
Form:
Liquid and powder formats split procurement based on formulation water content and manufacturing equipment compatibility.
- Powder:Dry particulate colorants for anhydrous systems and powder-to-cream formulations. Silane and polymer encapsulation technologies enable water-dispersible variants in lipsticks, expanding long-wear flexibility.
- Liquid:Pre-dispersed colorants reducing manufacturing dust exposure and batch variability. Water-based foundations and tinted serums favor liquid concentrates for homogeneous distribution.
- Gel:Thixotropic dispersions for precise dosing in automated filling lines. Nail gel and hair colorant manufacturers specify gel forms for viscosity control.
- Solid:Compressed pigment cakes and pressed powders for direct compression or milling. Compact makeup manufacturing favors solid forms for equipment compatibility.
Powder maintains manufacturing share. Liquid gains on skincare hybridization.
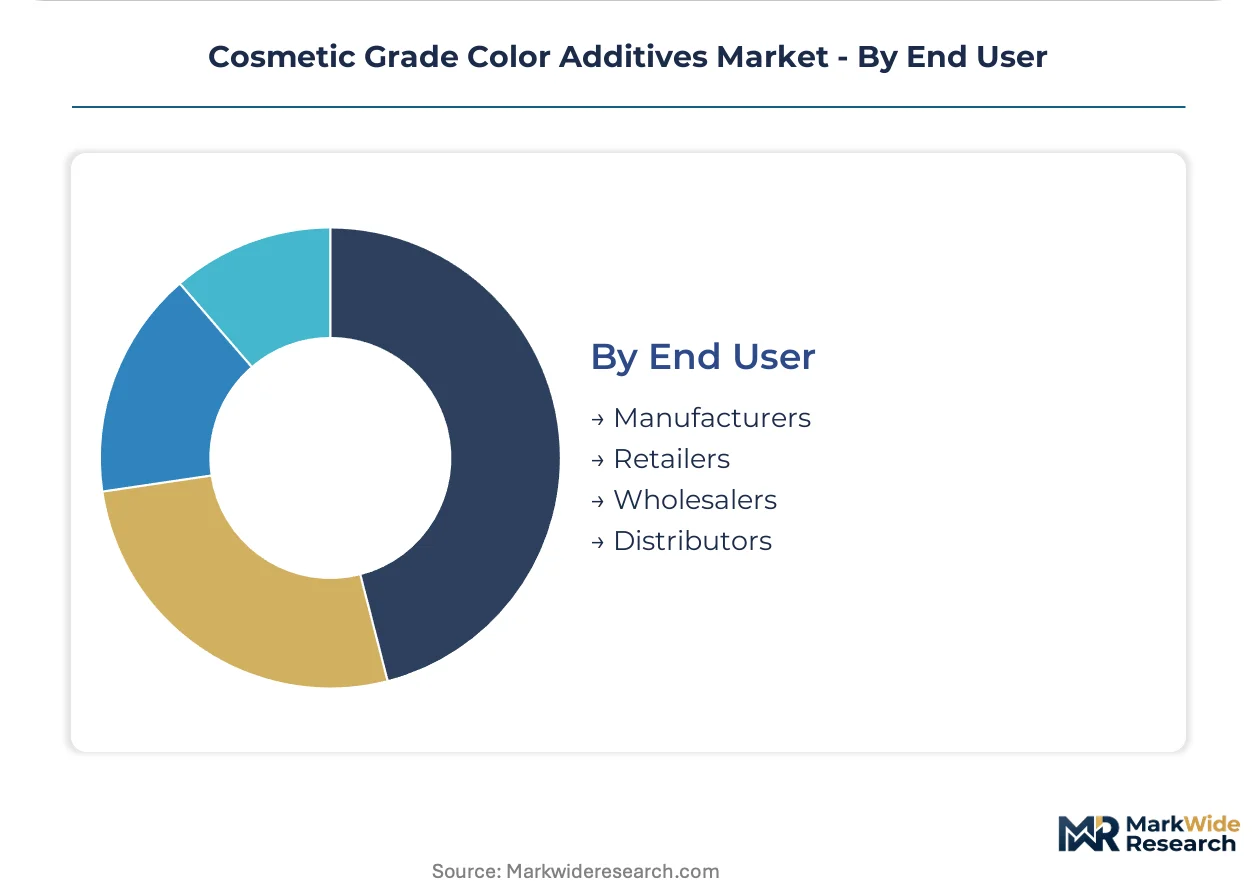
End User:
Manufacturer procurement patterns fragment as direct-to-consumer sampling programs compress minimum order quantities.
- Manufacturers:Cosmetic and personal care product formulators specifying colorants for in-house production. Indie beauty brands in Los Angeles and Seoul now request 5-kilogram minimums across 20 shade variants rather than 500-kilogram single-SKU commitments.
- Distributors:Specialty chemical distributors stockpiling REACH-compliant effect materials ahead of anticipated microplastic glitter enforcement. European Chemicals Agency consultation timelines are compressing holiday collection development cycles.
- Retailers:Private-label beauty brands and house-brand cosmetics divisions. Clean-label certification requirements are forcing entire colorant portfolio requalification.
- Wholesalers:Bulk procurement intermediaries serving smaller formulators and contract manufacturers. Modular production cells and digital color-matching platforms are compressing custom shade development timelines.
Manufacturers drive specification. Distributors absorb regulatory compliance burden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jharkhand and Bihar districts anchor global mica supply chains, while regulatory divergence between FDA, REACH, and NMPA frameworks reshapes qualification timelines for cosmetic colorant manufacturers. Demand concentrates in three distinct clusters: North American mineral sunscreen reformulation, European clean-label enforcement, and Chinese domestic premiumization.
United States
Hawaii and Florida reef-safe mandates accelerate iron oxide substitution in SPF formulations, with Miami and Los Angeles emerging as formulation hubs for mineral sunscreen brands. FDA Title 21 CFR compliance remains mandatory for mineral SPF claims, extending raw material qualification timelines. Indie beauty brands in Los Angeles now specify 5-kilogram minimum orders across 20 shade variants.
China
NMPA streamlined approval pathways for imported colorants serving domestic manufacturers scaling color-correcting skincare lines. Shanghai and Guangzhou house the principal formulation clusters for tinted serums with niacinamide delivery. GB standards for cosmetic ingredients are tightening documentation requirements for foreign suppliers.
Germany
BASF SE leverages its integrated pigment production network across Ludwigshafen to sustain supply security for cosmetic manufacturers. REACH restriction proposals for microplastic-containing glitter compress product development cycles for holiday collections. Specialty chemical distributors in Frankfurt stockpile compliant effect materials ahead of anticipated ECHA enforcement.
France
Premium foundation brands in Paris drive adoption of encapsulated pigments with triggered-release shells for oxidation-resistant wear claims. ANSM guidelines on heavy metal thresholds align with REACH tightening, requiring batch-level ICP-MS analysis. The Île-de-France region concentrates formulation partnerships between colorant suppliers and active ingredient houses.
South Korea
Seoul-based brands pioneer 12-hour wear claims through surface-treated pigments that enhance dispersion in water-based foundations. MFDS cosmetic safety assessor scarcity extends product launch timelines for new colorant qualifications. The capital region anchors K-beauty export manufacturing for hybrid tinted skincare products.
Cosmetic Grade Color Additives Market Competitive Landscape
Portfolio diversification dominates the current landscape as pigment houses reconfigure production assets for modular, low-volume shade development. The vendor base splits between integrated chemical conglomerates with captive raw material positions and specialized surface-treatment specialists. Three archetypes define competitive positioning: scale-driven mineral pigment producers, biotechnology-derived colorant innovators, and regional distribution intermediaries absorbing regulatory compliance burdens. M&A activity concentrates on encapsulation technology capabilities, while geographic expansion targets NMPA-qualification pathways in China.
Among integrated chemical producers, BASF SE and Lanxess AG exemplify the scale-driven archetype with European-based production networks. Sensient Technologies Corporation occupies a position within the specialized tier, representing botanical-derived colorant capabilities. Clariant AG anchors the surface-treatment specialist segment. These three entities collectively illustrate the competitive tension between commodity mineral supply security and premium formulation functionality.
| Leading Market Players |
|---|
| DIC Corporation |
| DyStar Singapore Pte Ltd |
| BASF SE |
| Lanxess AG |
| Huntsman Corporation |
| Clariant AG |
| Merck KGaA |
| Ferro Corporation |
| Sensient Technologies Corporation |
| Others |
Value Network & Pricing Analysis
Captive mica sourcing from Jharkhand and Bihar districts anchors supply security for pearlescent pigments while simultaneously constraining pricing flexibility for cosmetic manufacturers dependent on Indian feedstock. This geographic concentration of critical raw material inputs compresses margin pools for formulators unable to backward-integrate into mineral extraction networks.
Pricing Analysis
Batch-level ICP-MS testing costs for heavy metal compliance pass directly through to cosmetic manufacturers, elevating surface-treated pigment premiums above commodity mineral grades. Three-tier pricing structure across cosmetic-grade certified, technical-grade, and uncertified pigment levels separates formulation-ready materials from industrial alternatives. Pricing pressure stems from REACH and FDA threshold tightening, which mandates repeated analytical expenditure regardless of production volume. Indie beauty brands in Los Angeles and Seoul exhibit highest price sensitivity, while multinational personal care houses absorb certification premiums to secure supply continuity.
Supply Chain Analysis
Qualified toxicological assessors familiar with SCCS guidelines remain scarce in Ludwigshafen and Paris manufacturing clusters, extending raw material qualification timelines for pigment houses. Supply concentrates in Germany, China, and India, with BASF SE's integrated European network and Jharkhand's mica deposits anchoring global flows. Silane encapsulation technologies and aluminum substrate precipitates constitute critical input dependencies. Single-source vulnerability in Indian mica districts threatens pearlescent pigment availability. Distribution runs through specialty chemical intermediaries in Frankfurt and Shanghai who stockpile REACH-compliant materials ahead of regulatory enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where NMPA-qualification investments in China unlock premium pricing unavailable in saturated European mineral pigment channels.
For Market Incumbents: Extend surface-treatment capabilities into pH-stable pigments for niacinamide-tinted serums, defending against biotechnology-derived colorant substitution. Backward integration into Jharkhand mica sourcing secures supply continuity against export restriction risks. Encapsulation technology R&D partnerships with Seoul-based K-beauty formulators preserve formulation exclusivity. For New Entrants and Emerging Players: Direct-to-consumer digital sampling platforms enable 5-kilogram minimum order fulfillment for Los Angeles indie brands, bypassing traditional 500-kilogram bulk procurement barriers. Halal-certified botanical colorants for Indonesia's BPJPH mandates represent the most penetrable white-space segment. Precision fermentation partnerships with clean-beauty brands offer batch-to-consistency advantages over agricultural extract variability. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier surface-treatment specialists because regulatory compliance burdens favor scaled qualification infrastructure over fragmented pigment houses. Long-term viability hinges on encapsulation capability ownership as skincare-colorant hybridization accelerates. Watch MFDS cosmetic safety assessor availability in Seoul as inflection indicator for K-beauty launch timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mica Sourcing | Jharkhand district mining concessions secure pearlescent pigment supply against geographic concentration risk. |
| Encapsulation Technology Acquisition | Triggered-release shell capabilities unlock 12-hour wear claims for Paris and Seoul foundation brands. |
| NMPA Qualification Investment | Streamlined approval pathways in Shanghai accelerate access to China's domestic premiumization wave. |
| Halal Certification Program | Alcohol-free production lines satisfy Indonesia BPJPH and Malaysia JAKIM mandates for Muslim-market access. |
| Biotechnology Colorant Partnership | Precision fermentation of violacein pigments offers batch consistency unattainable in botanical extracts. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region balanced against secondary validation. Formulation chemists at personal care manufacturers, regulatory affairs specialists navigating FDA Title 21 CFR and REACH frameworks, procurement directors at pigment houses, and cosmetic safety assessors familiar with SCCS guidelines provided stakeholder perspectives. Secondary sources included FDA color additive listings, ECHA restriction proposal consultations, NMPA import documentation requirements, SEC filings from integrated chemical producers, and trade flow data through Frankfurt and Shanghai specialty chemical distributors. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Granularity-level modeling deployed product type, application, form, and end-user dimensions across the projection horizon, with additional disaggregation by surface-treatment technology tier and certification status. CAGRs derived from regression analysis of historical volume flows and elasticity-adjusted demand projections. Forecast inputs incorporated reef-safe mandate adoption curves in Hawaii and Florida, NMPA approval pathway efficiency metrics, and REACH microplastic restriction implementation timelines.
The model assumes a particular technology adoption path; alternative pathways for biotechnology-derived colorants would alter the outlook if precision fermentation achieves cost parity with mineral pigments faster than projected. Forecasts reflect documented assumptions regarding regulatory harmonization trajectories and raw material supply continuity. Material deviation in Indian mica export policies or MFDS assessor availability warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Synthetic Tackifier Market
Additives
Global PVC Additives Market
Additives
Oxygen Scavengers Market
Additives
Liquid Silage Additive Market
Additives
Anti-Foaming Agent Market
Additives
Americas Coating Additives Market
Additives
Alkyl Ketene Dimers (AKD) Wax Market
Additives
Competitive Inhibitors Market
Additives
Global Isononanoic Acid Market
Additives
Europe Choline Chloride Market
Additives
Polymeric Plasticizer Market
Additives
Binder Excipients Market
Additives
Global Carboxylic Acids Based Esters Market
Additives
Carboxymethylcellulose (CMC) Market
Additives
China Sodium Reduction Ingredient Market
Additives
Humectants Market