
 Feed Additives Market | 2026-2036
Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Feed Additives Market Analysis
China is reshaping feed additive supply chains through massive amino acid capacity expansion in the Shandong and Hebei corridors. Cargill, Incorporated leverages its integrated oilseed-crushing-to-premix network across the US Midwest to sustain cost leadership in lysine distribution. Evonik Industries AG anchors European methionine output with dedicated fermentation complexes in Belgium and Germany. BASF SE competes on vitamin A and E stability technology, differentiating through encapsulated delivery systems that reduce nutrient degradation during pelleting.
Feed additives are biologically active substances or compound formulations incorporated into animal diets at inclusion rates typically below one percent by weight to enhance nutrient utilization, preserve feed quality, or support physiological function. Enzyme additives such as phytase and xylanase break down anti-nutritional factors in cereal-based rations, improving phosphorus release and energy digestibility in poultry and swine operations. Antioxidant product types command stable margin pools as compound feed manufacturers face extended storage requirements in tropical climates and volatile grain markets. Aquaculture application segments show the fastest structural expansion as shrimp and salmon producers substitute fishmeal with plant-based proteins that require precise amino acid balancing and gut health modifiers.
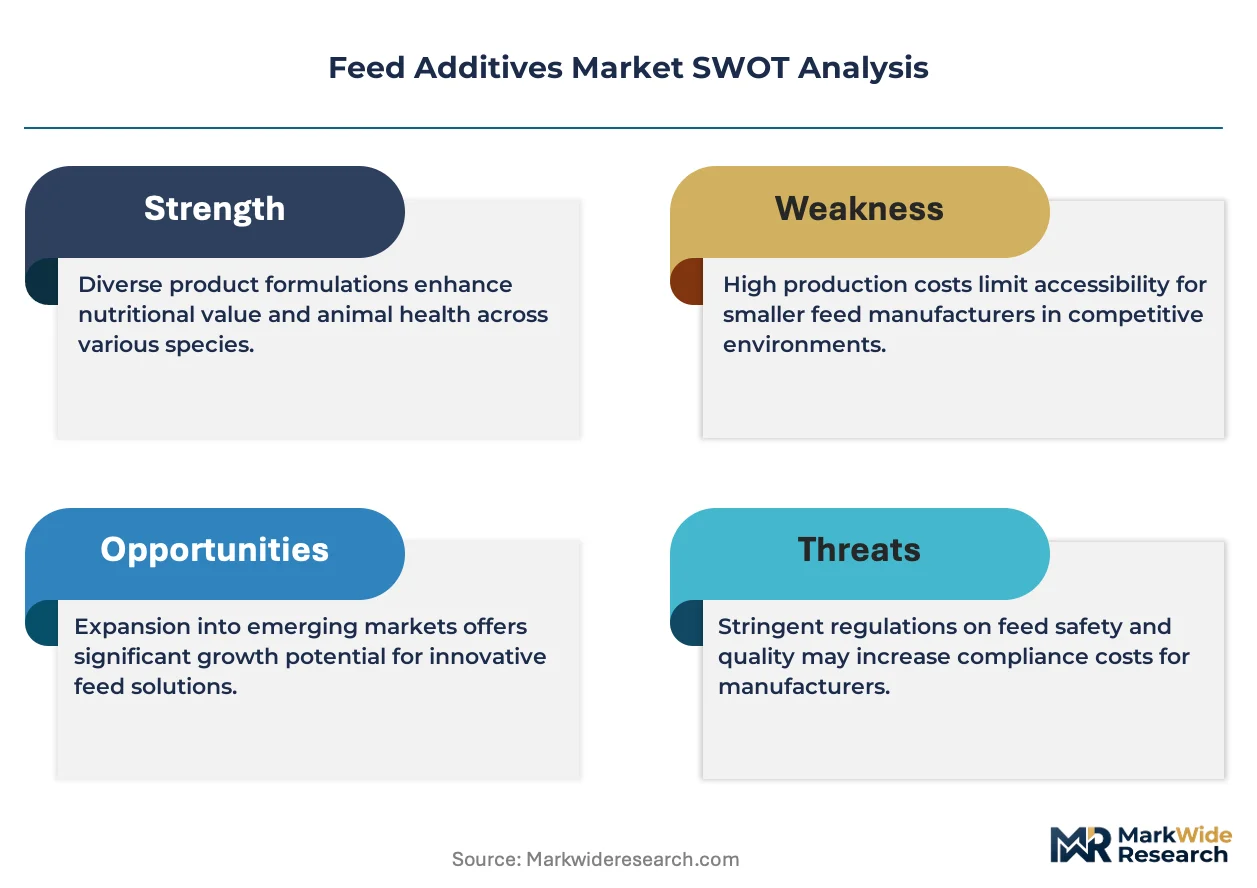
Regulators including the FDA, EFSA, and China's SAMR enforce divergent approval pathways for novel feed enzymes and microbial additives, fragmenting product registration timelines and raising compliance costs for multinational suppliers. The EU Green Deal and F-Gas Regulation are accelerating pressure on producers to document carbon intensity across additive manufacturing and raw material sourcing. Stakeholders must monitor how divergent maximum residue limits and biotechnology approval frameworks between jurisdictions reshape product portfolios and localization requirements.
Market Dynamics
Precision fermentation and enzymatic synthesis are collapsing traditional chemical manufacturing cost curves for amino acids, while the EU Green Deal's carbon border adjustments force feed compounders to document Scope 3 emissions across additive supply chains.
Growth Catalysts
- EU Green Deal carbon accounting mandates:Compound feed manufacturers in Belgium and Germany now require suppliers to certify manufacturing emissions, creating pull-through demand for low-carbon lysine and methionine variants.
- Industrial aquaculture expansion:Salmon producers in Norway and shrimp operations in Vietnam are substituting fishmeal with plant-based proteins that require precise amino acid fortification and gut health modifiers.
- Phytase enzyme adoption:Poultry integrators across the US Midwest and Brazil's Mato Grosso region are deploying next-generation phytase variants that unlock phosphorus from corn-soy rations, reducing inorganic phosphate purchases.
Market Restraints
- Feed-grade vitamin A input volatility:Beta-ionone synthesis depends on petrochemical-derived acetone and citral, exposing formulators to naphtha price swings and force majeure disruptions at BASF's Ludwigshafen complex.
- China amino acid supply concentration:Shandong and Hebei provinces host over 60 percent of global lysine fermentation capacity, creating geographic single-point-of-failure risk for international premix blenders.
- EFSA novel enzyme approval timelines:Microbial feed additives face 18-24 month safety evaluation windows that lag FDA-CVM pathways by 8-12 months, fragmenting product launch synchronization.
Strategic Opportunities
- Underpenetrated African poultry sectors:Nigeria and Egypt's broiler industries operate with minimal enzyme supplementation, presenting first-mover openings for phytase and xylanase distributors establishing local technical service networks.
- EU F-Gas Regulation refrigerant transition:Fermentation cooling systems must shift from hydrofluorocarbons to ammonia or CO2 cascades, rewarding engineering firms that retrofit existing lysine plants with compliant infrastructure.
- Precision livestock farming convergence:Integration of real-time feed intake monitoring with automated micro-ingredient dosing creates demand for water-soluble vitamin premixes calibrated to individual pen performance data.
Industry Challenges
- Fermentation strain development talent scarcity:Industrial microbiology PhDs capable of CRISPR-based methionine producer strain optimization command premium compensation that mid-tier additive houses struggle to match.
- SAMR-EFSA-FDA triplicate registration burden:Novel microbial additives require parallel dossier preparation for China's National Feed Review Committee, EFSA's FEEDAP panel, and FDA-CVM, stretching regulatory affairs teams across incompatible data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Feed Additives Market |
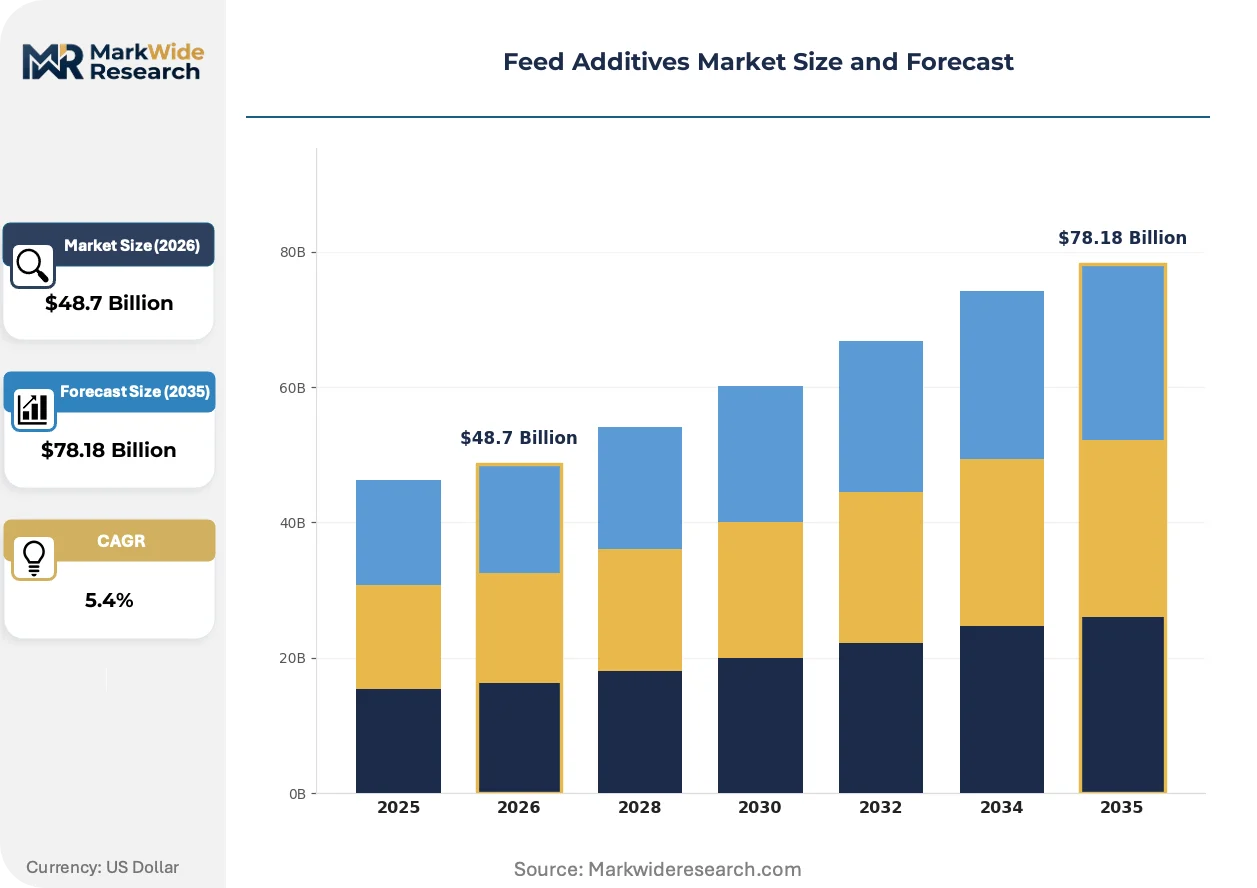
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $78.18 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antimicrobials, Antioxidants, Enzymes, Vitamins Form: Granules, Liquids, Powders, Pellets Application: Poultry, Ruminants, Swine, Aquaculture End User: Farmers, Feed Manufacturers, Veterinary Clinics, Research Institutions |
| Companies Covered | Evonik Industries AG, Nutreco N.V., Cargill, Incorporated, Alltech International Holdings, Inc., Ajinomoto Co. Inc, Archer Daniels Midland Company, DSM-Firmenich AG, Kemin Industries, Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Feed Additives Market Emerging Trajectories
Biological manufacturing methods and digital traceability systems are restructuring how feed additives move from fermentation tanks to farm silos, with sustainability verification becoming as critical as nutritional efficacy.
Cell-free enzymatic synthesis is collapsing the capital intensity barrier for specialty amino acid production. Startups in California and the Netherlands are deploying immobilized enzyme cascades that convert sugar feedstocks to tryptophan and valine without fermentation infrastructure. Venture-backed operations in Rotterdam and Berkeley are licensing these biocatalytic platforms to regional premix blenders seeking supply chain independence from Chinese fermentation majors.
REACH's 2023 restriction of per- and polyfluoroalkyl substances is forcing antioxidant formulators to abandon PFAS-containing encapsulation coatings used for vitamin stability during pelleting. German compound feed manufacturers now specify silicone-based or lipid-matrix alternatives in procurement tenders, while ECHA's restriction roadmap pressures suppliers to validate non-fluorinated delivery systems by 2026 for continued EU market access.
Integrated oilseed processors are capturing additive margins through backward integration into vitamin E and lecithin production. Crush facilities in Argentina's Rosario corridor and Iowa's Cedar Rapids cluster are installing molecular distillation units to convert deodorizer distillate into feed-grade tocopherol, displacing standalone vitamin merchants. This captive supply model concentrates with multinational agribusinesses that already control soybean procurement and oil refining infrastructure.
Feed Additives Market Segmentation
Feed additive suppliers structure service networks around formulation complexity and dosing precision requirements. Technical support intensity varies sharply across product categories, with enzymatic premixes demanding on-site calibration while commodity vitamins operate through distributor self-service models.
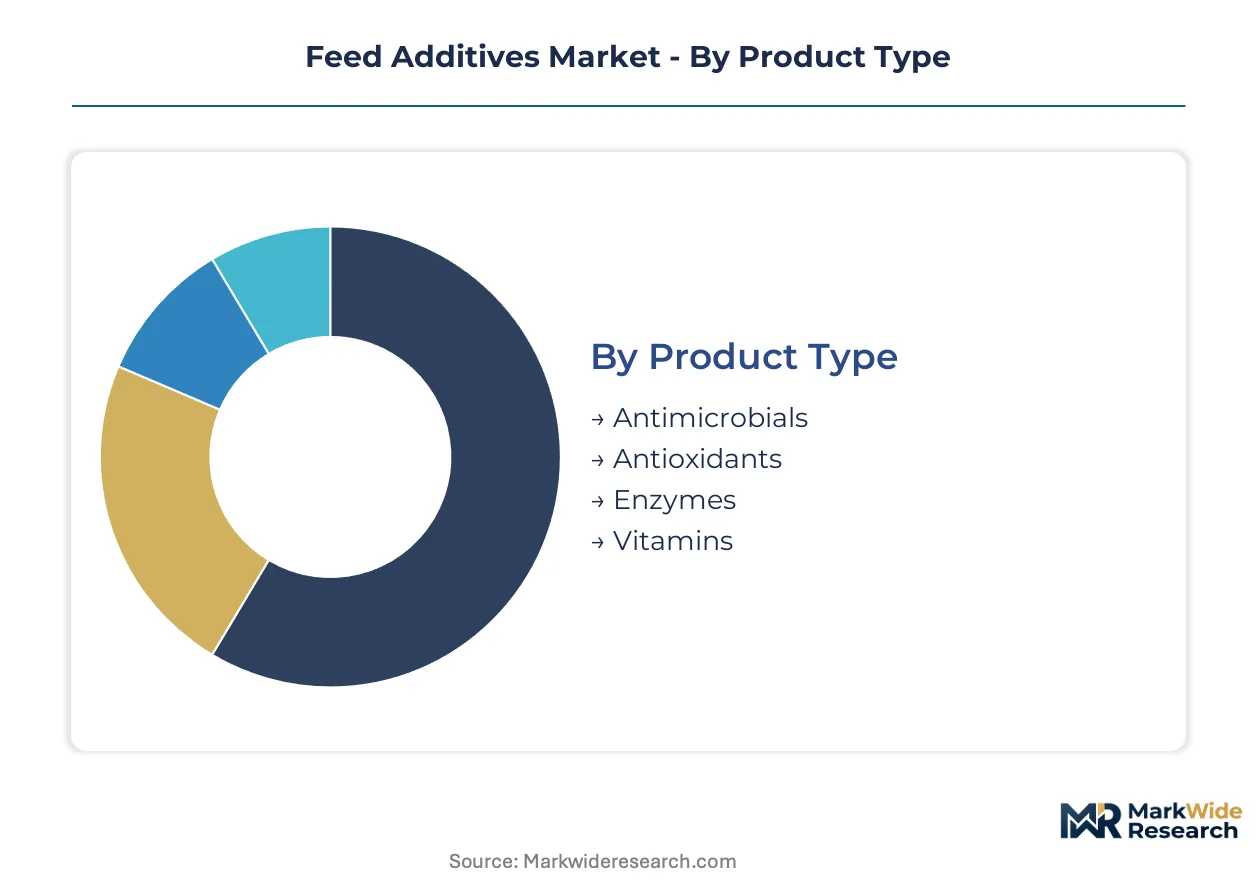
Product Type:
After-sales engagement intensity escalates with biological activity and stability sensitivity. Enzyme and antimicrobial categories require continuous technical liaison, whereas antioxidant and vitamin segments function through standardized specification sheets.
- Enzymes:Phytase and xylanase variants degrade anti-nutritional factors in cereal-based rations, improving phosphorus release and metabolizable energy coefficients. Poultry integrators in Brazil's Mato Grosso and US Midwest corn-soy belts deploy next-generation variants with thermostability engineered for pelleting temperatures above 85°C, reducing inorganic phosphate purchases by 30-40%.
- Antimicrobials:Growth-promoting and therapeutic formulations face tightening residue monitoring under FDA-CVM and EFSA FEEDAP frameworks. Chinese industrial pork producers rebuilding sow herds post-ASF rely on precision-dosed acidifiers and medium-chain fatty acids as ionophore alternatives in antibiotic-reduction protocols.
- Antioxidants:Ethoxyquin, BHT, and BHA formulations preserve lipid stability in extended tropical storage. Compound feed manufacturers in Vietnam and Thailand specify these additives for palm oil-rich rations vulnerable to rancidity.
- Vitamins:Fat-soluble A, D, E, K and water-soluble B-complex formulations fortify basal rations. REACH 2023 PFAS restrictions are forcing reformulation of encapsulation coatings used for vitamin stability during pelleting.
Enzymes holds the largest share; momentum sits with antimicrobials as regulatory pressure accelerates alternative gut health solutions.
Form:
Physical presentation determines handling infrastructure, shelf-life, and dosing equipment compatibility. Liquid systems demand tankage and pumping capital, while dry forms suit decentralized farm-level blending.
- Powders:Fine-milled premix bases with 0.5-2% inclusion rates dominate small-to-medium feed mill operations. Nigerian and Egyptian poultry sectors rely on bagged powder enzymes for on-farm top-dressing where automated dosing is unavailable.
- Liquids:Pumpable concentrates enable post-pelleting application and drinking water medication. Salmon producers in Norway deploy liquid phytase and organic acid blends through automated barn dosing systems.
- Granules:Agglomerated particles with controlled dissolution profiles protect heat-sensitive actives during extrusion. Shrimp feed manufacturers in Vietnam specify granule forms for slow-release amino acid delivery.
- Pellets:Compressed carriers with precise density for pneumatic conveying systems. Large compounders in Germany's Lower Saxony cluster favor pelletized vitamin premixes for automated batching accuracy.
Powders dominate volume; liquids are climbing the fastest as precision livestock farming expands automated dosing infrastructure.
Application:
Species-specific digestive physiology and production intensity dictate additive selection and service requirements. Monogastric operations drive amino acid and enzyme demand, while ruminant systems emphasize fiber-degrading and methane-mitigation formulations.
- Poultry:Broiler and layer operations consume phytase, xylanase, and synthetic methionine at highest per-ton inclusion rates. US integrators in Georgia and Arkansas deploy enzyme cocktails calibrated to local corn mycotoxin profiles.
- Swine:Post-weaning diets require acidifiers, zinc oxide alternatives, and gut health modifiers. China's Shandong corridor producers rebuilding herds emphasize low-protein amino acid-balanced formulations.
- Ruminants:Dairy and beef operations utilize ionophores, yeast cultures, and methane inhibitors. Dutch and Danish producers face EU Green Deal pressure to document enteric fermentation reductions.
- Aquaculture:Salmon and shrimp producers substitute fishmeal with plant proteins requiring precise amino acid fortification. Norwegian Atlantic salmon farms drive demand for water-soluble vitamin premixes.
Poultry commands the greatest volume; aquaculture shows the steepest expansion trajectory as marine protein substitution accelerates.
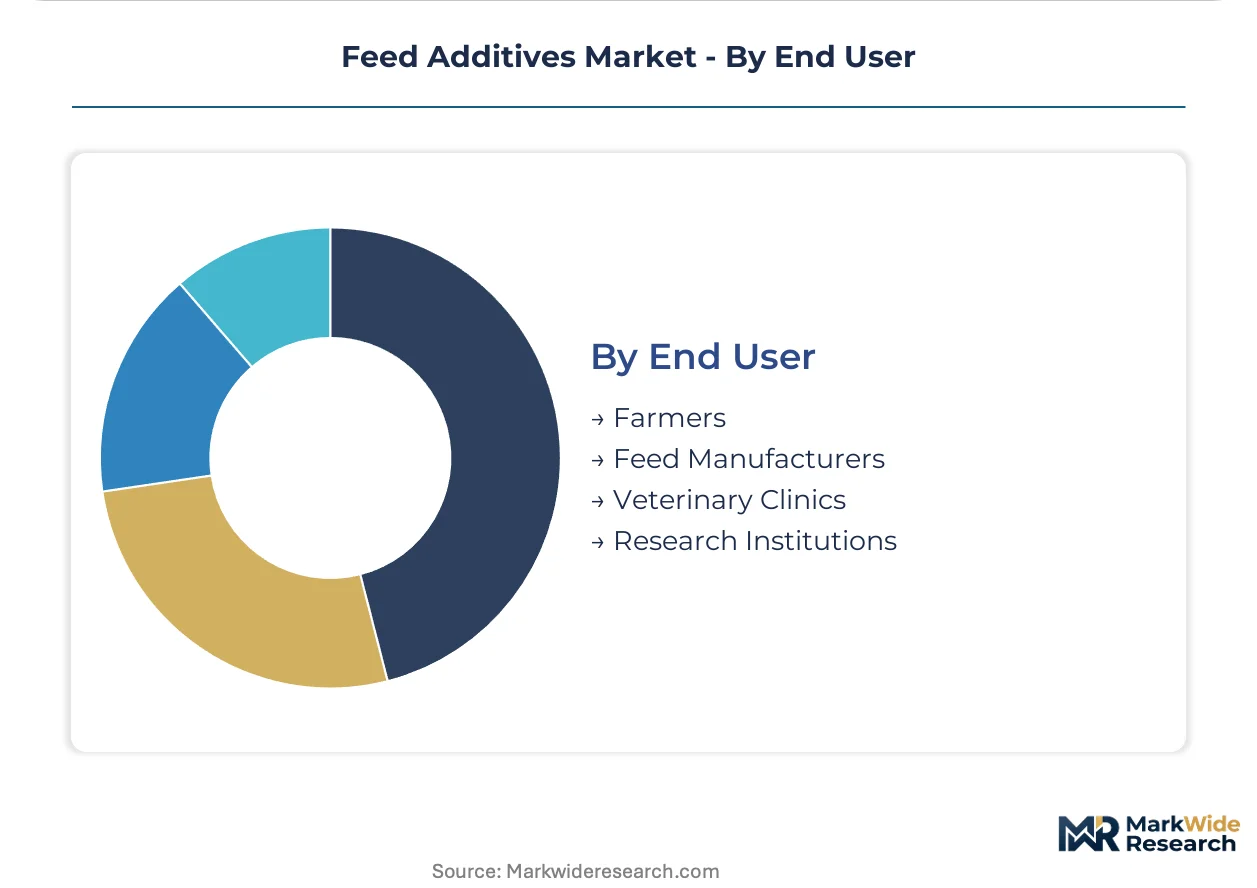
End User:
Procurement sophistication and technical capability vary dramatically across customer archetypes, fragmenting sales channel design and support economics.
- Feed Manufacturers:Industrial compounders with in-house laboratories and formulation teams purchase bulk amino acids and vitamin premixes. Cargill's US Midwest network and Chinese state-owned conglomerates in Shandong operate at this tier.
- Farmers:Direct-to-producer sales concentrate on smaller-scale operations and specialty segments. Brazilian Mato Grosso poultry growers source phytase through cooperative purchasing arrangements.
- Veterinary Clinics:Therapeutic and prophylactic additive distribution channels for prescription-grade formulations. EU member state veterinary pharmacies handle regulated growth promoter alternatives.
- Research Institutions:Universities and trial stations source reference-grade materials for efficacy studies. Wageningen University and Iowa State trial stations validate novel enzyme variants.
Feed manufacturers absorb the largest share; farmers are gaining share fastest as precision livestock farming enables direct-to-farm digital ordering platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SAMR's feed additive registration protocols in China anchor the dominant geography, where industrial pork producers in Shandong and Hebei corridors drive amino acid demand. Brazil's Mato Grosso poultry belt and Germany's Lower Saxony dairy cluster complete the critical supply-demand triangle for this market.
China
Shandong and Hebei provinces host over 60 percent of global lysine fermentation capacity as industrial pork producers rebuild sow herds with precision nutrition protocols. SAMR enforces parallel dossier requirements for novel microbial additives that lag FDA-CVM pathways by 8-12 months. The Yangtze River Delta concentration of state-owned premix blenders is capturing backward integration margins through captive amino acid sourcing.
United States
Georgia and Arkansas poultry integrators deploy enzyme cocktails calibrated to local corn mycotoxin profiles at highest per-ton inclusion rates. FDA-CVM's streamlined approval windows for feed enzymes attract multinational suppliers seeking faster market access than EFSA pathways. The US Midwest oilseed-crushing-to-premix network sustains cost leadership in lysine distribution through integrated logistics.
Brazil
Mato Grosso broiler operations scale up amino acid supplementation programs as commercial livestock intensifies. ANVISA monitors residue limits for growth-promoting additives under Mercosur harmonization pressures. The São Paulo-Rio corridor hosts Latin America's largest compound feed manufacturing base, drawing premix distributors into technical service partnerships.
Germany
Lower Saxony dairy and beef operations face EU Green Deal pressure to document enteric fermentation reductions through methane inhibitors. EFSA's FEEDAP panel enforces 18-24 month safety evaluation windows for novel enzymes that fragment product launch synchronization. Evonik's Ludwigshafen complex anchors European methionine output with dedicated fermentation infrastructure.
Vietnam
Mekong Delta shrimp producers substitute fishmeal with plant-based proteins requiring precise amino acid fortification and gut health modifiers. Compound feed manufacturers specify antioxidant formulations for palm oil-rich rations vulnerable to tropical storage degradation. The Ho Chi Minh City industrial zone concentrates aquaculture premix blending capacity serving Southeast Asian export markets.
Feed Additives Market Vendor Landscape
Capability concentration sits with fermentation strain optimization specialists; scale advantage sits with integrated oilseed processors with captive additive streams. The vendor base organizes into three tiers: multinational chemical conglomerates with vitamin stability technology, regional premix blenders with technical service networks, and venture-backed biocatalytic startups licensing cell-free synthesis platforms. Dominant competitive moves include backward integration into vitamin E and lecithin production from deodorizer distillate, and retrofit partnerships for F-Gas Regulation-compliant cooling infrastructure.
Among European chemical conglomerates, Evonik Industries AG and BASF SE exemplify the integrated fermentation-to-distribution archetype with dedicated manufacturing complexes in Belgium and Germany. Cargill, Incorporated occupies a position among North American agribusinesses leveraging oilseed procurement control to capture additive margins through molecular distillation units in Iowa and Argentina. These three entities represent contrasting pathways to supply chain positioning: chemical synthesis expertise, integrated crop processing infrastructure, and regional technical service density.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Nutreco N.V. |
| Cargill, Incorporated |
| Alltech International Holdings, Inc. |
| Ajinomoto Co. Inc |
| Archer Daniels Midland Company |
| DSM-Firmenich AG |
| Kemin Industries, Inc. |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Shandong and Hebei province concentration of lysine fermentation capacity anchors margin capture for Chinese state-owned premix blenders while forcing international compounders into long-term offtake negotiations. This geographic supply lockup transfers pricing power upstream to fermentation majors and squeezes formulation margins for distributors lacking captive amino acid sourcing.
Pricing Analysis
European methionine quotations trade at persistent premiums to Chinese spot markets due to EU Green Deal carbon accounting compliance costs embedded in Belgian and German production. Three-tier pricing structure across premium, standard, and economy levels separates encapsulated vitamin variants with silicone-based coatings from commodity grades still using legacy matrix technologies. Pricing pressure stems from Shandong corridor capacity additions flooding export markets with lysine. Small-to-medium feed mill operators in Nigeria and Egypt show highest price sensitivity, while Norwegian salmon integrators prioritize stability performance over unit cost.
Supply Chain Analysis
Tariff exposure between China and key importing regions dominates supply chain risk calculus for multinational premix blenders. Fermentation capacity concentrates in China, Belgium, and Germany; vitamin A synthesis feeds from BASF's Ludwigshafen complex and select Chinese petrochemical corridors. Raw material flows draw from acetone and citral derivatives, naphtha-cracked intermediates, and oilseed deodorizer distillate. Single-source vulnerability concentrates in beta-ionone supply chains. Distribution runs through integrated oilseed processors with captive crushing-to-premix networks and regional technical service distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The feed additives sector is recovering from cyclical lows as China's industrial pork herd rebuilding drives amino acid demand normalization. Sow inventory expansion in Shandong and Hebei corridors provides the demand-side anchor for this recovery phase.
For Market Incumbents: Insulate margin structures by deepening backward integration into oilseed processing infrastructure across Argentina's Rosario corridor and Iowa's Cedar Rapids cluster. Acquire or license cell-free enzymatic synthesis platforms from Rotterdam and Berkeley venture-backed operations before biocatalytic production achieves cost parity. Carbon border documentation capabilities represent the critical defensive lever as EU Green Deal compliance becomes a procurement gate. For New Entrants and Emerging Players: Build out technical service networks in underpenetrated African poultry sectors, specifically Nigeria and Egypt where enzyme supplementation rates lag Brazilian and US benchmarks. Establish local phytase and xylanase distribution partnerships with Mato Grosso cooperative purchasing arrangements as a proof-of-concept beachhead. Precision livestock farming integration expertise offers the most penetrable go-to-market angle against incumbent commodity distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional premix blenders in Southeast Asia lacking fermentation strain optimization capabilities but holding established veterinary clinic distribution channels. Long-term viability over a multi-year horizon favors targets with SAMR registration dossiers already filed or EFSA FEEDAP panel approvals in process. Watch Shandong province environmental enforcement intensity as the inflection signal—capacity curtailments there would reprice global lysine markets and validate Western fermentation infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Processing | Cargill's US Midwest network captures vitamin E margins through molecular distillation of deodorizer distillate. |
| F-Gas Regulation Cooling Retrofit | Belgian and German lysine plants must shift from hydrofluorocarbons to ammonia cascades by regulatory deadlines. |
| Cell-Free Enzymatic Synthesis Licensing | Rotterdam startups license biocatalytic platforms that convert sugar feedstocks to tryptophan without fermentation tanks. |
| Precision Livestock Farming Convergence | Real-time feed intake monitoring creates demand for water-soluble vitamin premixes calibrated to pen performance data. |
| PFAS-Free Encapsulation Development | German compound feed manufacturers now specify silicone-based vitamin coatings after REACH 2023 restrictions. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fermentation plant managers, compound feed procurement leads at Cargill and ADM networks, veterinary clinic distribution partners, and regulatory affairs directors navigating SAMR-EFSA-FDA triplicate requirements. Secondary validation drew from customs and trade data tracking lysine and methionine flows, SEC 10-K filings of listed agribusinesses, EFSA FEEDAP panel opinions, and Chinese Ministry of Agriculture feed industry statistics. Bottom-up capacity modeling across Shandong and Hebei fermentation corridors was triangulated against top-down demand estimates from pork and poultry production forecasts.
Calibration against historical price spreads between Chinese export markets and European delivered quotations anchored the projection framework across the analysis window. Segmentation dimensions modeled include product type, physical form, species application, and end-user procurement sophistication tier. CAGRs were derived from elasticity-adjusted demand curves incorporating amino acid inclusion rate trends and enzyme substitution coefficients. Industry-specific inputs comprised sow herd rebuilding trajectories in China's industrial pork sector and phytase adoption curves in Brazil's Mato Grosso poultry belt.
Stress conditions across naphtha price volatility, Shandong environmental enforcement intensity, and EFSA novel enzyme approval timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions around carbon border adjustment implementation schedules and fermentation strain development productivity gains. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Carboxymethylcellulose (CMC) Market
Additives
Foundry Additives Market
Additives
Emulsifiers In Personal Care Market
Additives
Pearlizers Market
Additives
Inorganic Rheology Modifiers Market
Additives
Battery Additives Market
Additives
Middle East Lubricant Additives Market
Additives
Lactic Acid Ester Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Nucleating Agents Market
Additives
Propyl Gallate Market
Additives
Europe UV Stabilizers Market
Additives
Canada Water Enhancer Market
Additives
Phthalate Plasticizer Market
Additives
United States Betaine Market
Additives
North America Citric Acid Market