
 Caprylyl Glycol Market | 2026-2036
Caprylyl Glycol Market Size, Share, and Industry Trends Forecast 2026-2036
Caprylyl Glycol Market Outlook
Personal care is consolidating its share of caprylyl glycol consumption as clean-label moisturizers and hair care products displace conventional preservative systems. Evonik Industries AG leverages its specialty additives portfolio to supply cosmetic compounders with high-purity grades. Ashland anchors North American supply through its personal care ingredients division. Clariant AG competes on microbial control efficacy in leave-on applications.
Caprylyl glycol is a C8 diol produced via catalytic hydrogenation of caprylic acid, functioning as a humectant, emollient, and preservative booster with broad microbial efficacy across pH ranges. Cosmetics applications lead volume absorption due to multifunctional demand from clean-label beauty brands, while hair care products represent the fastest-growing application as silicone-free formulations proliferate. Pharmaceutical-grade specifications command premium positioning due to compendial compliance burdens and lower batch volumes.
REACH registration requirements and EU Green Deal chemical sustainability targets constrain conventional preservative availability, redirecting formulation investment toward caprylyl glycol across European cosmetic manufacturing. FDA cosmetic labeling regulations and state-level clean beauty legislation in California shape product positioning for US market access. Stakeholders must monitor evolving preservative bans and microbiological testing standards to align R&D pipelines with regulatory trajectory.
Market Dynamics
REACH registration requirements and EU Green Deal chemical sustainability targets are systematically constraining conventional preservative availability, redirecting formulation investment toward caprylyl glycol across European cosmetic manufacturing and establishing multifunctional diols as the default preservative booster in clean-label personal care.
Growth Catalysts
- REACH and EU Green Deal restrictions:Regulatory pressure on conventional preservatives redirects formulators toward caprylyl glycol as a compliant multifunctional alternative in leave-on cosmetic applications.
- Clean-label beauty procurement:Personal care brands are expanding procurement of this humectant for silicone-free hair care and moisturizer formulations that displace traditional preservative systems.
- German specialty chemical concentration:High-purity grade production clusters in Germany serve cosmetic compounders with compendial-compliant specifications for pharmaceutical and premium cosmetic applications.
Market Restraints
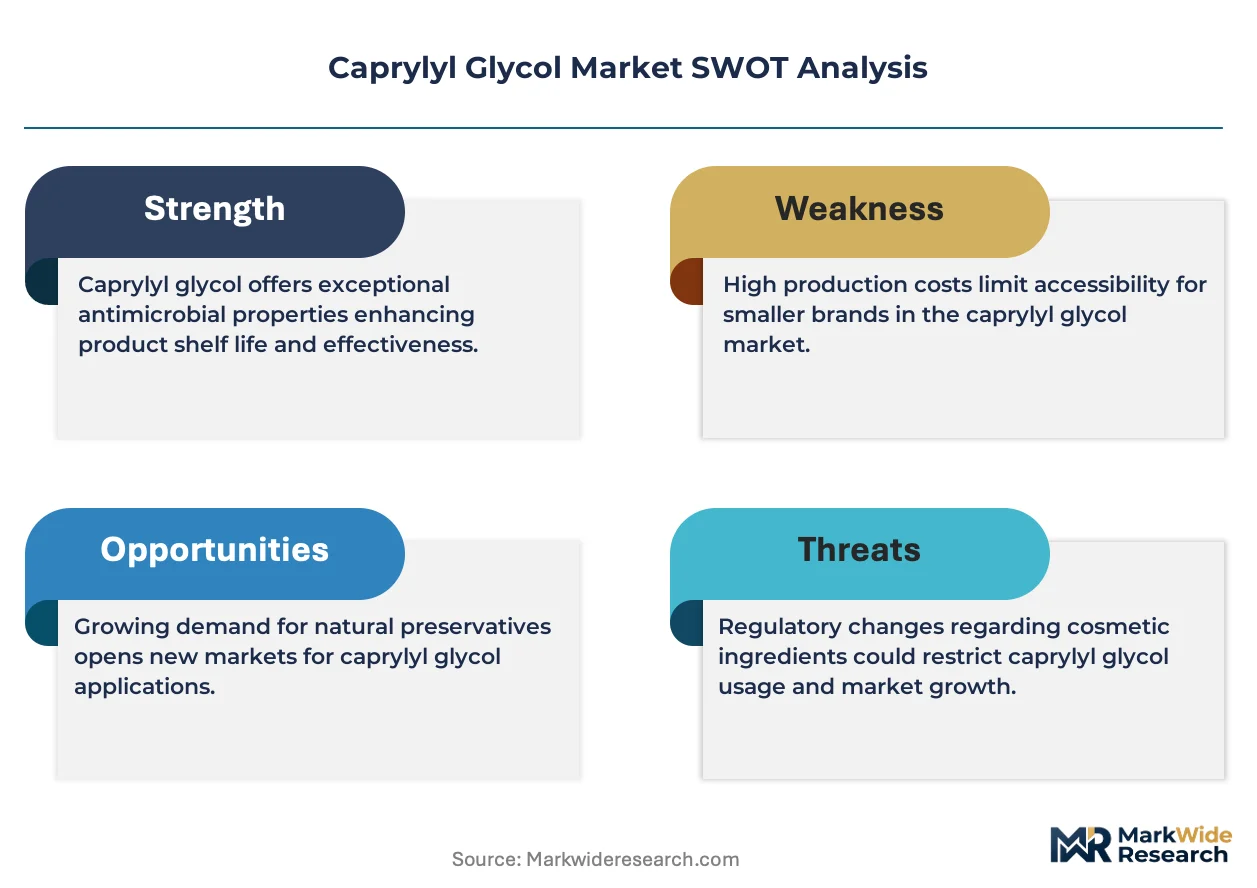
- Caprylic acid feedstock volatility:Catalytic hydrogenation input costs fluctuate with palm kernel and coconut oil commodity markets, compressing margin stability for C8 diol producers.
- Compendial compliance burdens:Pharmaceutical-grade specifications require extensive documentation and lower batch volumes, limiting scale economies for premium positioning tiers.
- Propylene glycol substitution threat:Lower-cost diols compete in industrial and mass-market cosmetic applications where microbial efficacy requirements are less stringent.
Strategic Opportunities
- California clean beauty legislation:State-level preservative disclosure mandates and ingredient transparency requirements create regulatory tailwinds for caprylyl glycol adoption in US personal care manufacturing.
- Hair care application expansion:Silicone-free formulation proliferation represents an emerging volume absorption channel as brands reformulate conditioners and styling products.
- ISO 16128 natural origin certification:Convergence with biobased feedstock verification standards enables positioning in certified natural and organic cosmetic segments.
Industry Challenges
- Microbiological testing standard evolution:Shifting preservative efficacy protocols require continuous R&D pipeline adjustment to demonstrate broad-spectrum performance across pH ranges.
- Clean-label formulator skill gaps:Cosmetic chemists trained on conventional preservative systems face retraining requirements to optimize multifunctional diol performance in complex emulsion matrices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caprylyl Glycol Market |
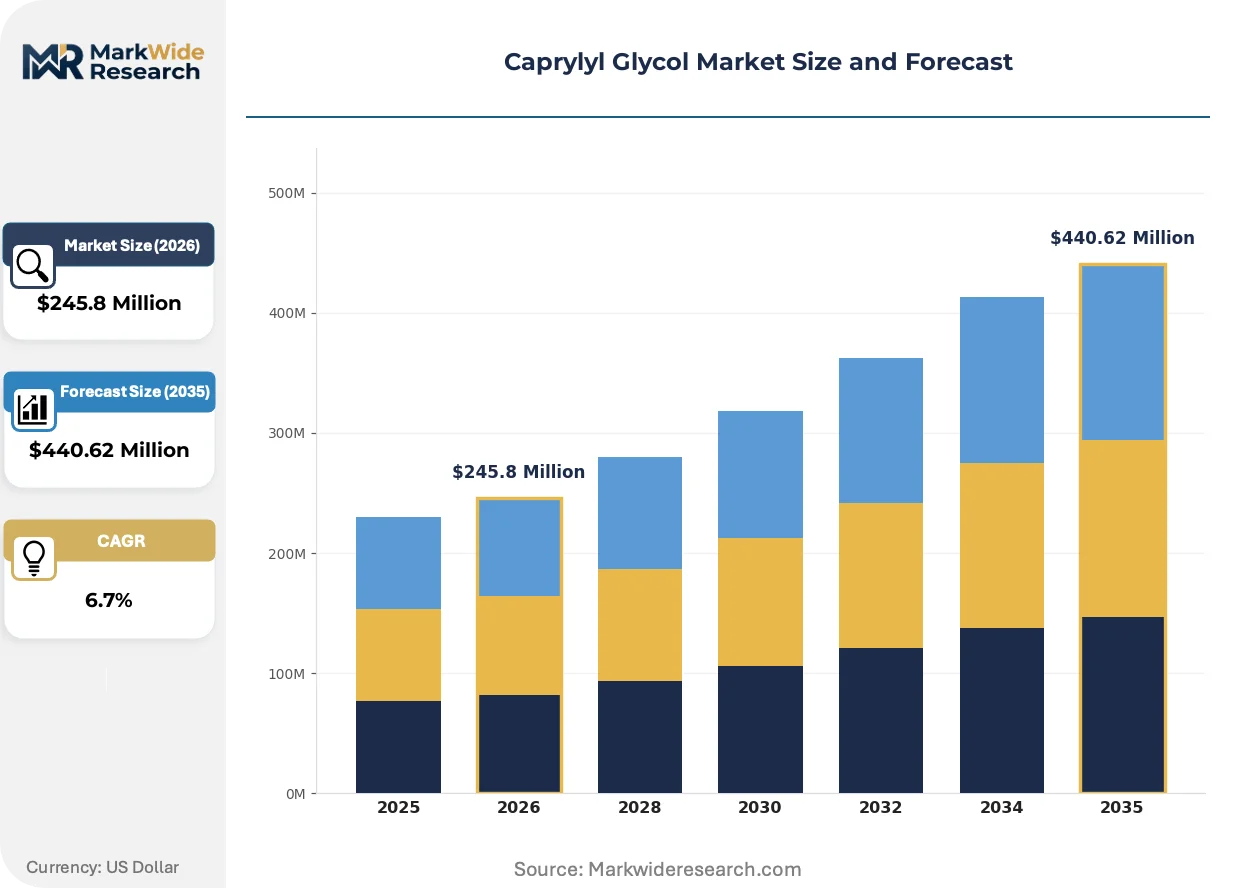
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $440.62 Million |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Personal Care, Household Products Application: Moisturizers, Anti-Aging Creams, Hair Care Products, Sunscreens End User: Beauty Brands, Pharmaceutical Companies, Contract Manufacturers, Retailers Distribution Channel: Online Platforms, Specialty Stores, Supermarkets, Distributors |
| Companies Covered | Inolex, Inc., Evonik Industries AG, Ashland, Clariant AG, Dow, BASF SE, Lonza Group Ltd., Thor Personal Care, Symrise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caprylyl Glycol Market Strategic Shifts
Continuous processing technology is automating catalytic hydrogenation operations, while regulatory frameworks and procurement models are simultaneously compressing batch cycle times and reshaping supplier qualification protocols across cosmetic ingredient supply chains.
Flow chemistry reactor systems are automating caprylyl glycol synthesis through integrated hydrogenation and purification sequences. Specialty chemical producers in Germany and Switzerland are adopting these continuous platforms to reduce solvent waste and improve lot-to-lot consistency. This automation is compressing capital recovery timelines while enabling real-time quality release for pharmaceutical-grade specifications.
REACH authorization timelines and EU Green Deal chemical sustainability targets are systematically constraining conventional preservative availability. Formulators face mandatory substitution deadlines for specific biocidal actives, redirecting R&D investment toward multifunctional alternatives. Personal care manufacturers in France and Germany are responding by qualifying caprylyl glycol across their entire leave-on product portfolios ahead of regulatory enforcement phases.
Direct procurement relationships between personal care brands and specialty chemical producers are displacing traditional distributor intermediaries. Large cosmetic compounders in California and New York are establishing preferred supplier agreements with high-purity grade manufacturers to secure volume commitments and technical support. This channel consolidation is most visible in premium hair care and skincare verticals where formulation complexity demands collaborative development partnerships.
Caprylyl Glycol Market Segmentation
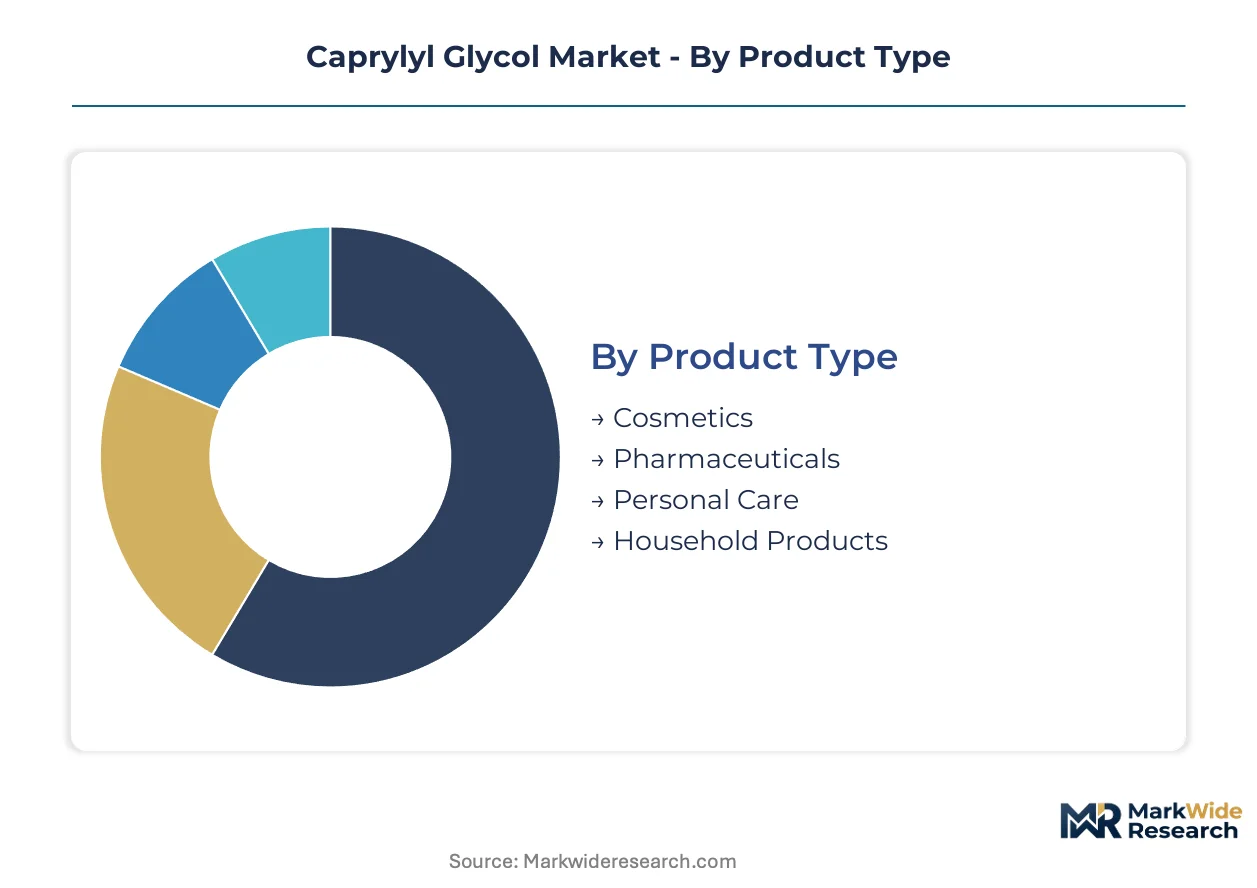
Caprylyl glycol procurement patterns diverge sharply across purity grades and regulatory compliance tiers. Segmentation reveals how multifunctional diol positioning shifts between mass-market cosmetic compounders and pharmaceutical-grade specifiers.
Product Type:
Customization intensity escalates from industrial household applications through compendial pharmaceutical grades, with specification depth determining margin architecture across the value chain.
- Cosmetics:Multifunctional humectant and preservative booster deployed across leave-on emulsions and rinse-off formulations. Demand concentrates in German and French cosmetic manufacturing clusters serving clean-label beauty brands reformulating ahead of REACH authorization deadlines.
- Pharmaceuticals:Compendial-grade material requiring extensive documentation, stability testing, and lower batch volumes for topical drug delivery systems. FDA and EMA compliance burdens limit supplier qualification to specialty chemical producers with dedicated pharmaceutical manufacturing suites.
- Personal Care:Intermediate specification tier bridging cosmetic aesthetics with enhanced microbial efficacy for deodorants and oral care applications.
- Household Products:Standardized industrial grade competing on cost efficiency in surface cleaners and laundry formulations with less stringent purity requirements.
Leading the category by volume: Cosmetics. Expanding most quickly: Pharmaceuticals.
Application:
Volume absorption correlates directly with formulation complexity and silicone replacement intensity across personal care verticals.
- Moisturizers:Primary absorption channel where caprylyl glycol serves dual humectant and preservative booster functions in clean-label facial creams. California clean beauty legislation accelerates procurement from brands eliminating parabens and formaldehyde releasers.
- Hair Care Products:Silicone-free conditioner and styling product reformulations drive steepest expansion trajectory as brands respond to consumer demand for lightweight, non-occlusive hair treatments.
- Anti-Aging Creams:Premium positioning tier leveraging caprylyl glycol's emollient properties in high-actives formulations targeting mature skin demographics.
- Sunscreens:Niche application requiring photostability validation and compatibility with organic UV filters in reef-safe formulations.
Moisturizers dominate current procurement volumes. Hair care applications gain share fastest.
End User:
Customer sophistication spans from formulation-naive retailers to technically demanding contract manufacturers managing multi-brand portfolios.
- Beauty Brands:Direct procurement relationships with specialty chemical producers displace traditional distributor channels for premium skincare and hair care verticals. Technical collaboration demands intensify for complex emulsion development.
- Contract Manufacturers:Volume aggregation points serving multiple brand clients with standardized specification tiers and batch flexibility requirements.
- Pharmaceutical Companies:Rigorous supplier qualification protocols and long validation timelines constrain sourcing to established compendial-grade producers.
- Retailers:Private-label formulators prioritizing cost efficiency and supply security over technical partnership depth.
Beauty brands command specification-setting authority. Contract manufacturers absorb volume scale.
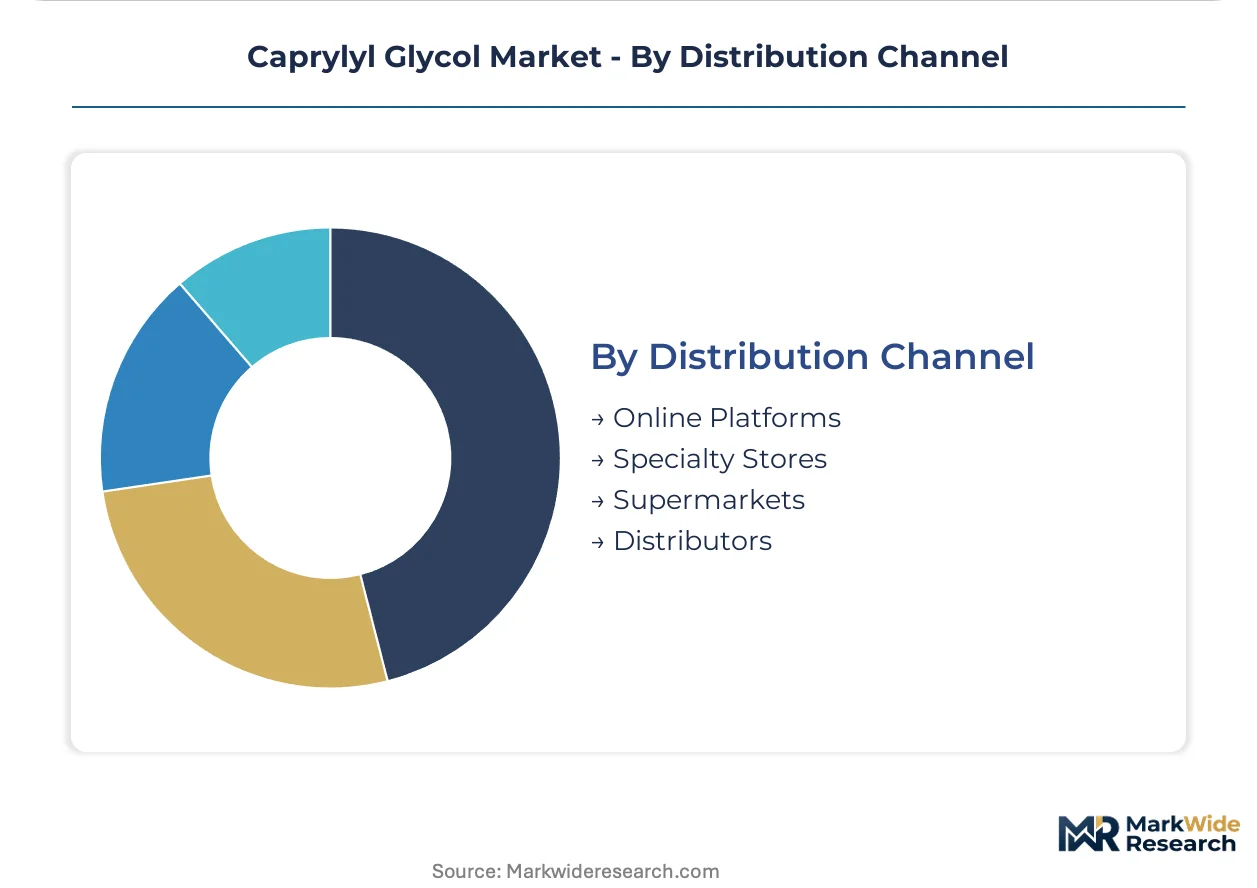
Distribution Channel:
Channel selection reflects order size, technical support requirements, and geographic proximity to manufacturing clusters.
- Direct Supply Agreements:Large cosmetic compounders in New York and California establish preferred supplier relationships with high-purity grade manufacturers for volume commitments and collaborative R&D access.
- Specialty Distributors:Technical ingredient distributors serve mid-tier formulators requiring smaller minimum order quantities and regulatory documentation support.
- Online Platforms:Emerging procurement channel for independent formulators and startup beauty brands seeking sample quantities and rapid turnaround.
- Supermarkets:Mass-market personal care manufacturers leveraging established chemical supply relationships through consolidated procurement functions.
Direct agreements capture premium-tier volume. Specialty distributors serve the broadest customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates high-purity caprylyl glycol manufacturing capacity, while consumption spreads across cosmetic formulation clusters in Western Europe, North America, and select Asian markets. Production scale advantages in German specialty chemical hubs contrast with demand fragmentation across brand headquarters and contract manufacturing sites.
Germany
Specialty chemical producers in the Rhine-Ruhr and Bavarian regions supply compendial-grade material to cosmetic compounders reformulating ahead of REACH authorization deadlines. ECHA's systematic restriction of isothiazolinone preservatives redirects formulation investment toward multifunctional diols. Frankfurt and Hamburg serve as logistics nodes for pharmaceutical-grade distribution across the EU.
United States
California clean beauty legislation and New York-based brand headquarters drive procurement of preservative-boosting alternatives in premium skincare and hair care verticals. FDA cosmetic labeling regulations and state-level disclosure mandates shape supplier qualification protocols. Specialty distributors in New Jersey and Illinois intermediate between German manufacturers and mid-tier formulators.
France
Paris-based beauty conglomerates and contract manufacturers in the Île-de-France region accelerate caprylyl glycol adoption across leave-on product portfolios. ANSM guidance on preservative safety assessments reinforces the shift from conventional biocidal systems. Lyon and Strasbourg house technical centers supporting silicone-free hair care reformulation.
Switzerland
Swissmedic pharmaceutical compliance requirements and proximity to German raw material suppliers position Basel and Zurich as high-specification formulation hubs. Precision chemical producers adopt continuous flow hydrogenation technology to serve niche pharmaceutical and premium cosmetic segments. Geneva-based brand owners specify compendial grades for anti-aging and sun care applications.
China
Domestic cosmetic manufacturers in Shanghai and Guangzhou incorporate caprylyl glycol into clean-label products targeting middle-class consumers. NMPA cosmetic ingredient filing requirements and evolving national safety standards influence import sourcing decisions. Yangtze River Delta chemical parks develop catalytic hydrogenation capacity for industrial-grade supply to household product manufacturers.
Caprylyl Glycol Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade and premium cosmetic supply, while mid-scale specialty chemical producers compete on batch flexibility and regional regulatory support. The vendor base stratifies across compendial certification depth, with three to four German and Swiss producers commanding qualification-intensive segments and North American distributors capturing formulation service revenue. Strategic archetypes include integrated hydrogenation specialists, multi-ingredient personal care portfolios, and regional compliance-focused distributors. Competitive moves center on preferred supplier agreements with large cosmetic compounders and continuous processing technology licensing.
Among German-headquartered specialty chemical producers, Evonik Industries AG and BASF SE exemplify the integrated hydrogenation archetype with downstream personal care ingredient portfolios. Ashland occupies a position bridging North American distribution scale with technical formulation support capabilities. Clariant AG represents the Swiss precision chemical model emphasizing compendial documentation and pharmaceutical manufacturing suite investments.
| Leading Market Players |
|---|
| Inolex, Inc. |
| Evonik Industries AG |
| Ashland |
| Clariant AG |
| Dow |
| BASF SE |
| Lonza Group Ltd. |
| Thor Personal Care |
| Symrise |
| Others |
Value Chain & Pricing Dynamics
Compendial-grade certification ladders create sharp price divergence between pharmaceutical and industrial tiers, with REACH-registered high-purity material commanding sustained premiums while mass-market cosmetic grades face margin compression from propylene glycol substitution. German specialty chemical producers leverage this bifurcation to defend margin architecture through dedicated pharmaceutical manufacturing suites, whereas Asian compounders compete on batch flexibility for cost-sensitive household applications.
Pricing Analysis
Short-lead-time premiums for compendial-grade caprylyl glycol reach substantial markups over spot industrial inventory, with pharmaceutical manufacturers paying elevated rates for validated supply security. Three-tier pricing structure across pharmaceutical, cosmetic, and industrial levels reflects certification depth and documentation burden. Cost compression in cosmetic tiers is intensifying because palm kernel oil feedstock volatility compresses hydrogenation margins. Contract manufacturers exhibit highest price sensitivity, while Swiss and German pharmaceutical formulators prioritize supply assurance over unit economics.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade returns and expired batches require specialized handling through Basel and Frankfurt chemical waste networks, adding compliance overhead to distribution economics. Manufacturing concentrates in Germany, Switzerland, and China, with Rhine-Ruhr hydrogenation clusters feeding European cosmetic compounders. Catalytic hydrogenation draws from caprylic acid derived via palm kernel and coconut oil processing, creating tethered exposure to tropical commodity markets. Single-source vulnerability runs through German high-purity producers for EMA-compliant material. Distribution runs through direct supply agreements for premium tiers and specialty distributors for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH authorization timelines and EU Green Deal chemical sustainability targets erect formidable cost-of-compliance barriers, with ECHA's systematic restriction of conventional preservatives creating qualification moats that favor incumbent specialty chemical producers with dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter propylene glycol substitution threats in mass-market cosmetics, BASF SE and Evonik Industries AG should deepen backward integration into sustainable caprylic acid feedstocks while expanding continuous flow hydrogenation capacity in Bavarian manufacturing clusters. Certification investment in ISO 16128 natural origin standards creates defensive positioning against emerging biobased competitors.
For New Entrants and Emerging Players: Capture white-space opportunity in California clean beauty supply chains by targeting silicone-free hair care formulators seeking preservative-boosting alternatives to parabens. The most penetrable segment sits with mid-tier contract manufacturers in New York and New Jersey lacking direct relationships with German high-purity producers. Go-to-market leverage flows through technical partnership positioning emphasizing formulation support capabilities.
For Investors and Strategic Acquirers: Re-rating potential sits with Swiss precision chemical specialists given Swissmedic pharmaceutical compliance requirements and continuous processing technology adoption. Long-term viability across the analysis window favors producers with compendial-grade manufacturing suites and established EMA qualification histories. The signal to watch is acceleration in direct procurement relationships displacing distributor intermediaries in premium personal care verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sustainable Feedstocks | Palm kernel oil supply security anchors margin stability for German hydrogenation specialists. |
| Continuous Flow Hydrogenation Technology Licensing | Swiss and German producers reduce solvent waste while compressing pharmaceutical-grade batch cycle times. |
| ISO 16128 Natural Origin Certification | Biobased verification standards unlock premium positioning in certified organic cosmetic segments. |
| Direct Supply Agreement Expansion | California and New York cosmetic compounders secure volume commitments and collaborative R&D access. |
| Pharmaceutical Manufacturing Suite Investment | Dedicated compendial-grade capacity limits supplier qualification to EMA-compliant specialty chemical producers. |
Study Parameters
Independent corroboration across specialty chemical procurement leads, cosmetic formulation directors, and pharmaceutical regulatory affairs managers underwrites the qualitative findings presented in this analysis. Primary interviews with plant managers at German hydrogenation facilities, technical R&D directors at Swiss precision chemical producers, and distribution channel partners in North American personal care markets combined with secondary validation from ECHA restriction dossiers, FDA cosmetic labeling guidance, and SEC filings from disclosed specialty chemical segments. Bottom-up volume modeling and top-down value triangulation across grade tiers and application verticals ensure analytical robustness.
Rate-of-change decomposition separates volume expansion in hair care applications from value capture in pharmaceutical-grade specifications across the projection horizon. The analytical framework models segmentation across purity tiers, end-use industries, geographic production clusters, and regulatory compliance levels. CAGRs derive from weighted average growth assumptions calibrated to REACH authorization timelines and clean-label procurement intensity. Industry-specific forecast inputs include silicone-free formulation adoption curves and continuous processing technology penetration rates in European manufacturing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to palm kernel oil commodity volatility and evolving microbiological testing standards. Practitioners should monitor ECHA authorization enforcement phases and California clean beauty legislative amendments for early signals of demand inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Pectin Market
Additives
Gelatin Peptones Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Antimicrobial Ingredients Market
Additives
Conditioning Agent Market
Additives
Antioxidant and Stabilizer Agents Market
Additives
Adjustive Agents Market
Additives
Performance Minerals Additives Market
Additives
Additives for Floor Coatings Market
Additives
Piperonyl Butoxide (PBO) Market
Additives
Cement Grinding Aid and Performance Enhancers Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Sorbitan Tristearate Market
Additives
Nucleating Agents Market
Additives
Encapsulated Citric Acid Market
Additives
Glycyrrhizic Acid Glycosides Market