
 Sorbitan Tristearate Market | 2026-2036
Sorbitan Tristearate Market Size, Share, and Industry Trends Forecast 2026-2036
Sorbitan Tristearate Market Analytics
Technical service contracts for emulsifier formulation support is restructuring how Sorbitan Tristearate suppliers capture recurring revenue beyond bulk chemical sales. Croda International Plc leverages its lipid technology platform to anchor premium positions in pharmaceutical-grade segments. Kao Corporation sustains manufacturing scale across Asian surfactant markets through integrated oleochemical supply chains. Evonik Industries AG differentiates via R&D intensity in specialty ester chemistry for high-purity applications.
Sorbitan Tristearate is a nonionic surfactant synthesized through the esterification of sorbitan with stearic acid, typically yielding a product with a hydroxyl value between 235-260 mg KOH/g and an acid value below 15 mg KOH/g, functioning primarily as a water-in-oil emulsifier and stabilizer across food, cosmetic, and pharmaceutical matrices. The emulsifiers category within product type segmentation commands the dominant margin pool due to stringent performance specifications in food and pharma applications, while personal care represents the fastest-growing application segment as clean-label formulations drive reformulation cycles among beauty manufacturers. Nonionic surfactants occupy the mature volume base, though stabilizer demand accelerates in extended-shelf-life food systems.
REACH registration requirements under ECHA govern chemical identity and safety data obligations for Sorbitan Tristearate distributed across European Union member states, while FDA food additive regulations under CFR 21 establish purity and usage limits for direct food contact applications in the United States. BIS certification requirements in India and evolving GB standards under SAMR in China further fragment compliance architectures for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether regional formulation customization or harmonized global specifications offer superior cost efficiency.
Market Dynamics
Technical service contracts for emulsifier formulation support are restructuring supplier revenue models beyond bulk chemical sales, as food and pharmaceutical manufacturers demand integrated application expertise rather than commodity procurement.
Growth Catalysts
- REACH compliance tightening:ECHA purity benchmarks are forcing reformulation across European food processing, creating demand for high-grade Sorbitan Tristearate in extended-shelf-life bakery systems.
- Clean-label cosmetics:Beauty manufacturers in South Korea and Japan are replacing synthetic emulsifiers with plant-derived alternatives, accelerating specification upgrades in personal care formulations.
- Oleochemical supply chain integration:Integrated palm and coconut oil processing in Malaysia and Indonesia is compressing input costs for regional esterification facilities.
Market Restraints
- Stearic acid price volatility:Feedstock fluctuations tied to tallow and palm oil commodity markets squeeze margin predictability for non-integrated producers.
- Supply concentration in China:Domestic surfactant production scaling in Shandong and Jiangsu provinces creates dependency risk for buyers seeking dual-source security.
- Technical substitution:Polyglycerol esters and sucrose esters are displacing Sorbitan Tristearate in certain water-in-oil emulsion applications where lower hydroxyl values suffice.
Strategic Opportunities
- Pharmaceutical-grade expansion:Injectable lipid formulations and vaccine adjuvant applications are opening premium specification tiers with validation requirements that filter out commodity suppliers.
- India BIS certification gap:Domestic manufacturers lag in food-grade certification compliance, creating import substitution potential for validated foreign suppliers.
- Enzymatic esterification:Lipase-catalyzed processes are converging with continuous flow reactor technology to enable lower-temperature production with superior color and odor profiles.
Industry Challenges
- Analytical chemistry talent scarcity:Hydroxyl value and acid value testing expertise is concentrated among aging technician cohorts in contract laboratories.
- Multi-jurisdiction registration timelines:Parallel FDA food additive petitions, ECHA dossier updates, and SAMR GB standard compliance are extending product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sorbitan Tristearate Market |
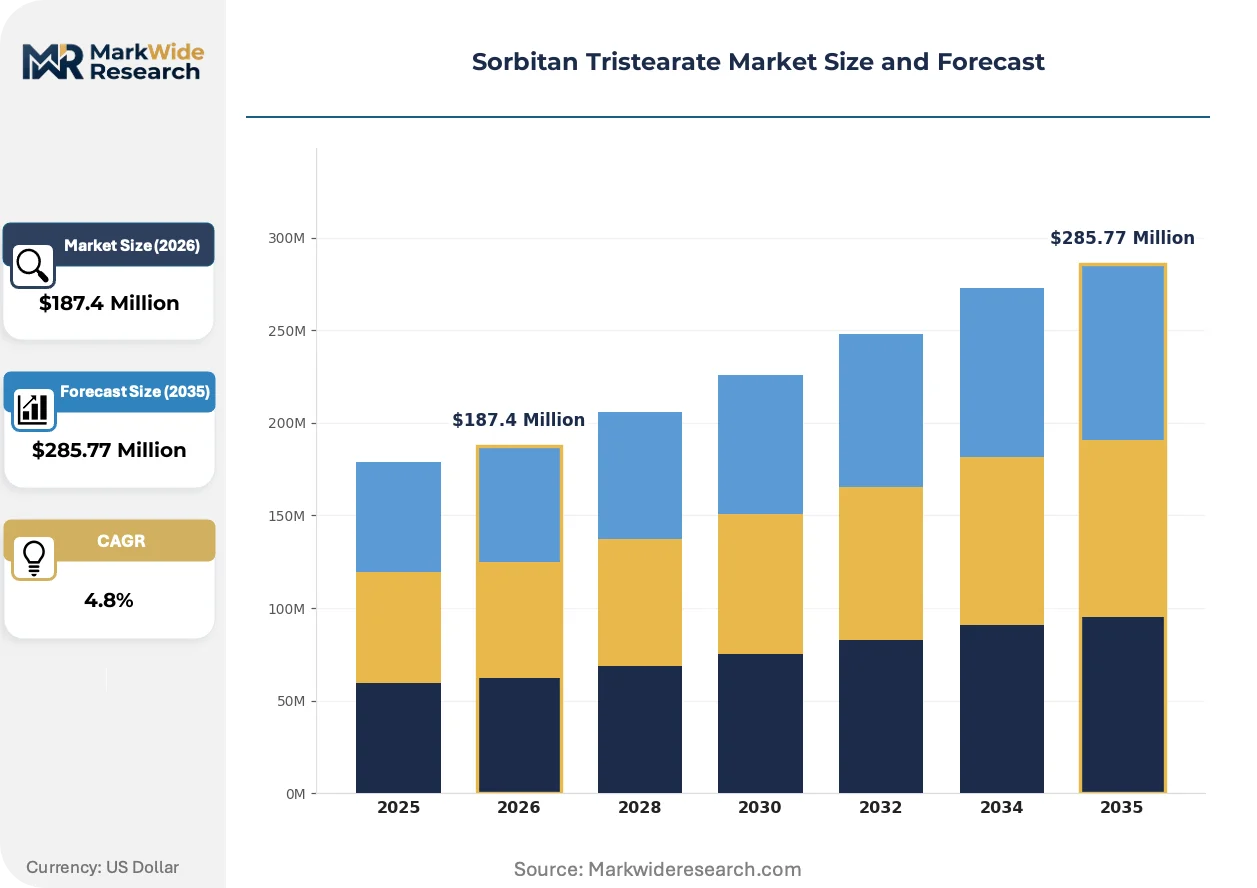
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nonionic Surfactants, Emulsifiers, Stabilizers, Dispersants Application: Food Industry, Cosmetics, Pharmaceuticals, Personal Care End User: Manufacturers, Retailers, Wholesalers, Distributors Packaging Type: Bulk Containers, Drums, Bags, Bottles |
| Companies Covered | Croda International Plc, Kao Corporation, Evonik Industries AG, Clariant AG, Palsgaard A/S, Estelle Chemicals Pvt. Ltd., Fine Organics Industries Ltd., Mohini Organics Pvt. Ltd., Stepan Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sorbitan Tristearate Market Evolving Landscape
Process intensification and regulatory harmonization pressures are simultaneously compressing production economics and expanding addressable application spaces for specialty-grade emulsifiers.
Continuous flow reactor technology for sorbitan esterification is modularizing manufacturing scale decisions, allowing mid-cap producers to deploy skid-mounted systems without full greenfield investment. Pharmaceutical contract manufacturers in Switzerland and Singapore are piloting these units for GMP-compliant output. The technology is modularizing capacity expansion timelines from years to quarters, eroding the scale advantage of legacy batch-reactor facilities.
EFSA re-evaluation of sorbitan ester exposure thresholds is tightening acceptable daily intake calculations, forcing reformulation in European infant nutrition and dietary supplement applications. Manufacturers are responding with enhanced purification protocols and documentary evidence packages. The regulatory revision most acutely impacts legacy suppliers lacking toxicology study archives.
Direct technical service contracting is displacing traditional distributor relationships in Asian food processing hubs, as bakery and confectionery manufacturers seek embedded formulation support rather than arm's-length chemical procurement. This channel shift is most visible in Vietnam and Thailand, where multinational emulsifier suppliers are establishing application laboratories co-located with customer R&D centers.
Sorbitan Tristearate Market Segmentation
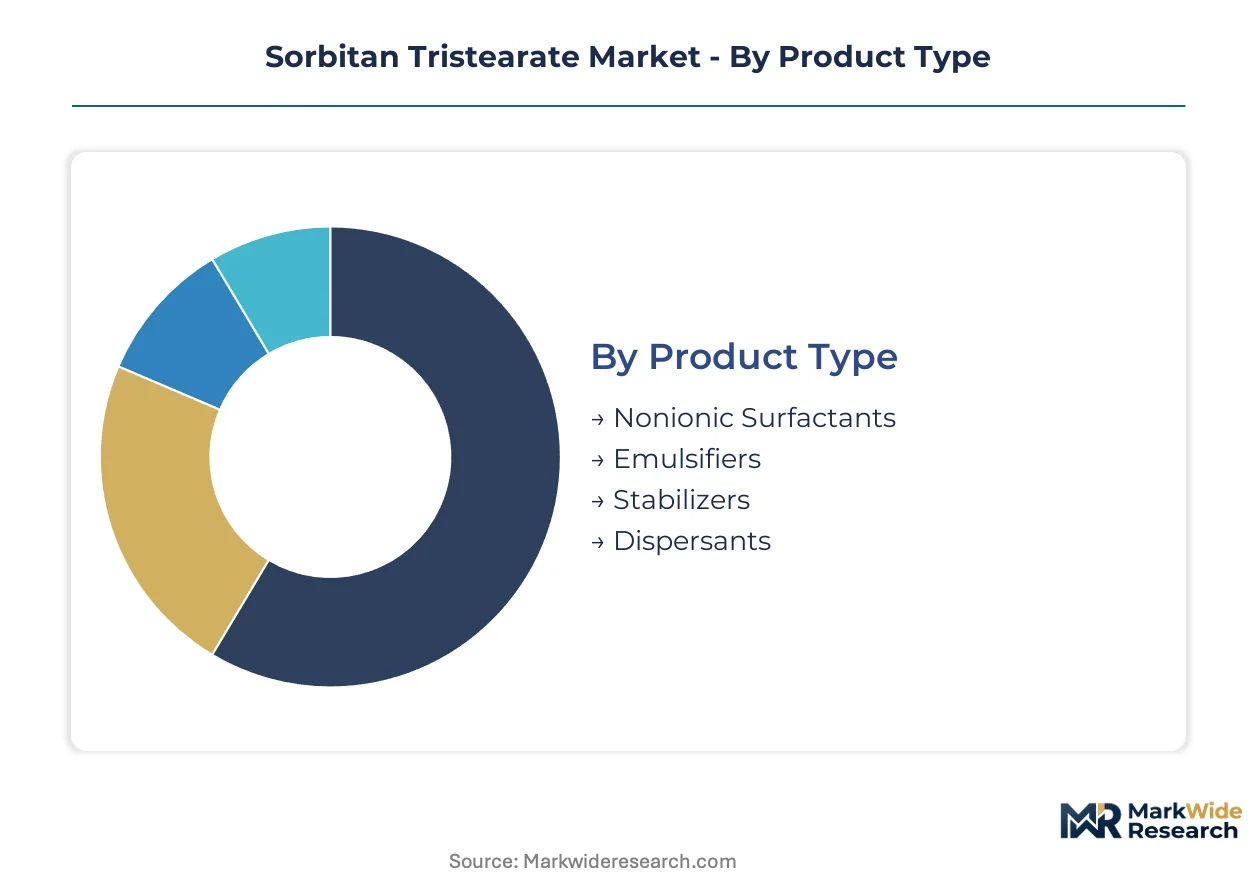
Sorbitan Tristearate applications span standalone additive formulations and complex multi-ingredient systems where emulsifier performance must integrate with broader processing parameters. Segmentation reveals where specification premiums concentrate versus commodity procurement patterns.
Product Type:
Integration depth varies sharply: emulsifiers typically embed within finished formulations requiring technical service support, while surfactants often ship as standalone intermediates for downstream blending.
- Emulsifiers:Water-in-oil emulsification systems for bakery shortenings and confectionery coatings demand hydroxyl values between 235-260 mg KOH/g with tight acid value control below 15 mg KOH/g. European infant nutrition manufacturers under EFSA exposure threshold revisions are upgrading to enhanced-purity grades, creating specification tiers that filter commodity suppliers.
- Nonionic Surfactants:The mature volume base in industrial cleaning and agrochemical formulations operates on standardized HLB values. Chinese domestic production in Shandong and Jiangsu provinces concentrates supply for Asian processing hubs, compressing margin structures for non-integrated producers.
- Stabilizers:Extended-shelf-life food systems in Southeast Asian export-oriented processing drive demand for oxidative stability enhancement.
- Dispersants:Pigment and active ingredient suspension applications in pharmaceutical manufacturing require validated particle size distribution controls.
Emulsifiers lead volumes today; stabilizers are gaining share fastest.
Application:
Cost tier stratification separates pharmaceutical-grade validation requirements from food-grade commodity procurement, with cosmetics occupying a mid-tier reformulation-driven segment.
- Food Industry:Bakery and confectionery manufacturers across Vietnam and Thailand are displacing traditional distributor relationships with direct technical service contracts. Clean-label pressures in South Korean and Japanese markets are accelerating specification upgrades beyond standard food-grade benchmarks.
- Pharmaceuticals:Injectable lipid formulations and vaccine adjuvant applications demand GMP-compliant production with full toxicology documentation packages. Swiss and Singaporean contract manufacturers are piloting continuous flow reactor technology to meet these validation requirements.
- Cosmetics:Beauty manufacturers reformulating around plant-derived emulsifier alternatives are driving ingredient substitution cycles in premium skincare.
- Personal Care:Hair care and oral care formulations represent steady demand for standardized sorbitan ester grades with consistent odor profiles.
Food Industry leads volumes today; Pharmaceuticals climbs the fastest.
End User:
Customer type determines whether procurement emphasizes embedded formulation expertise or arm's-length chemical supply.
- Manufacturers:Integrated food and pharmaceutical processors with captive R&D capabilities are consolidating supplier relationships toward fewer validated partners with application laboratory support.
- Distributors:Traditional channel intermediaries face margin compression as direct technical service contracting displaces their role in Asian processing hubs.
- Wholesalers:Bulk volume aggregation for smaller compounders remains relevant in fragmented regional markets lacking scale for direct supplier relationships.
- Retailers:Minimal direct engagement; specialty chemical retail is negligible for this ingredient category.
Manufacturers lead volumes today; Distributors are losing share fastest.
Packaging Type:
Supply chain configuration separates bulk integrated delivery systems from discrete packaging for smaller-scale or specialized applications.
- Bulk Containers:Tanker and tote deliveries dominate pharmaceutical and large-scale food manufacturing where just-in-time inventory management reduces working capital requirements.
- Drums:Standard 200-liter steel and plastic drums serve mid-scale cosmetics and personal care compounders with moderate volume needs and batch traceability requirements.
- Bags:Multi-layer laminated sacks for powder-grade stabilizer and dispersant shipments to dry blend operations.
- Bottles:Laboratory and pilot-scale quantities for formulation development and regulatory submission samples.
Bulk Containers lead volumes today; Drums hold steady as mid-tier standard.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China and India demonstrate divergent surfactant procurement patterns, with Chinese domestic production scaling rapidly while Indian buyers remain dependent on validated imports for food-grade certification compliance.
China
Shandong and Jiangsu provinces concentrate domestic surfactant manufacturing capacity for bakery and confectionery emulsifiers. SAMR's evolving GB standards under tightened food additive protocols are forcing purification upgrades among legacy producers. Qingdao processing clusters are deploying continuous flow reactor modules to compress batch cycle times.
India
Bakery shortening manufacturers in Maharashtra and Gujarat drive food-grade emulsifier procurement despite lagging domestic BIS certification capacity. FSSAI alignment with Codex Alimentarius specifications is accelerating third-party validation requirements for imported Sorbitan Tristearate. Mumbai-Pune industrial corridors host formulation laboratories serving regional confectionery exporters.
Germany
Pharmaceutical contract manufacturers in North Rhine-Westphalia demand GMP-compliant Sorbitan Tristearate for injectable lipid formulations. ECHA REACH registration maintenance and EFSA exposure threshold revisions are tightening documentary evidence packages for infant nutrition applications. Frankfurt-Rhine-Main chemical clusters specialize in high-purity ester validation.
United States
FDA CFR 21 food additive petitions govern direct food contact applications across Midwest bakery processing hubs. Illinois and Ohio shortening manufacturers consolidate supplier relationships toward validated partners with embedded formulation support. Chicago-area distribution networks serve regional compounders seeking dual-source security.
Vietnam
Export-oriented confectionery processors in Ho Chi Minh City industrial zones are displacing traditional distributor relationships with direct technical service contracts. ASEAN harmonization initiatives are converging food additive standards with Codex benchmarks, simplifying import validation. Mekong Delta agro-processing clusters drive stabilizer demand for extended-shelf-life bakery systems.
Sorbitan Tristearate Market Competitive Landscape
Top-tier vendors anchor premium pharmaceutical-grade segments, while mid-cap regional producers compete on volume in standardized food-grade applications. The vendor base stratifies across three tiers: multinational specialists with lipid technology platforms, integrated Asian oleochemical processors, and commodity-focused regional esterification facilities. Strategic archetypes include R&D-intensive purity leaders, backward-integrated palm oil processors, and technical service contractors. Competitive moves center on enzymatic process licensing and application laboratory co-location with customer R&D centers.
Within the multinational specialist tier, Croda International Plc and Evonik Industries AG exemplify R&D-intensive positioning anchored in pharmaceutical-grade validation requirements. Kao Corporation occupies a scale-driven position leveraging integrated Asian oleochemical supply chains. Among India-based fabricators, Estelle Chemicals Pvt. Ltd. and Fine Organics Industries Ltd. represent mid-cap specialists navigating BIS certification gaps for food-grade market entry.
| Leading Market Players |
|---|
| Croda International Plc |
| Kao Corporation |
| Evonik Industries AG |
| Clariant AG |
| Palsgaard A/S |
| Estelle Chemicals Pvt. Ltd. |
| Fine Organics Industries Ltd. |
| Mohini Organics Pvt. Ltd. |
| Stepan Company |
| Others |
Value Network & Pricing Analysis
Palm oil futures volatility on Bursa Malaysia Derivatives cascades through oleochemical conversion costs into differentiated pricing tiers for sorbitan ester grades. Stearic acid spot movements compress margin predictability for non-integrated esterification facilities while rewarding backward-linked processors with captive tallow and palm kernel feedstock.
Pricing Analysis
Capacity additions in Shandong and Jiangsu provinces are reshaping price floors for standard-grade nonionic surfactants. Three-tier pricing structure across pharmaceutical, food-grade, and industrial specifications reflects validation burden differentials rather than input cost alone. Cost compression in the industrial tier is intensifying because Chinese domestic production scales rapidly. Bakery manufacturers in Vietnam and Thailand demonstrate highest price sensitivity, while Swiss pharmaceutical contract manufacturers absorb premiums for GMP-compliant documentation packages.
Supply Chain Analysis
Dual-sourcing mandates from European infant nutrition manufacturers are fragmenting procurement patterns away from single-country dependency. Supply concentrates in China, Malaysia, and Germany for distinct grade tiers. Raw material flows draw from Indonesian palm oil plantations, Indian tallow rendering facilities, and German oleochemical refineries. Single-source vulnerability persists in enzymatic lipase supply for emerging biocatalytic processes. Distribution runs through integrated technical service contracts in Asian food processing hubs alongside traditional bulk tanker deliveries to pharmaceutical compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. EFSA exposure threshold revisions and FDA purity benchmarks are concentrating procurement toward validated suppliers with toxicology archives and GMP infrastructure.
For Market Incumbents: Anticipate displacement from polyglycerol esters in water-in-oil applications by embedding application laboratories with customer R&D centers in Ho Chi Minh City and Bangkok. Deepen backward integration into Malaysian palm oil processing to compress input cost volatility. Certification investment in BIS compliance for Indian market entry offers defensive positioning against domestic lag in food-grade validation capacity. For New Entrants and Emerging Players: Begin with enzymatic esterification technology licensing to bypass capital-intensive batch reactor infrastructure and capture premium positioning in color-sensitive cosmetic applications. India BIS certification gap represents the most penetrable entry point, particularly for Maharashtra and Gujarat bakery shortening manufacturers seeking validated import alternatives. Direct technical service contracting displaces traditional distributor relationships in Vietnamese export-oriented confectionery processing. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap specialists possessing continuous flow reactor pilots and pending pharmaceutical-grade validation dossiers. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Acquisition target archetype: regional esterification facilities with SAMR GB standard alignment and underutilized capacity in Qingdao or Jiangsu clusters. The signal to watch is EFSA final opinion publication on sorbitan ester acceptable daily intake revisions.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Reactor Deployment | Modular capacity expansion in Swiss and Singaporean GMP facilities compresses validation timelines from years to quarters. |
| Backward Integration into Oleochemical Feedstock | Captive palm and tallow processing in Malaysia insulates margin structures from Bursa Malaysia derivatives volatility. |
| Pharmaceutical-Grade Certification Investment | Full toxicology documentation packages filter out commodity competitors in injectable lipid formulation segments. |
| Application Laboratory Co-location | Embedded formulation support in Vietnam and Thailand displaces traditional distributor channels with recurring technical service revenue. |
| Enzymatic Esterification Licensing | Lipase-catalyzed processes enable lower-temperature production with superior color profiles for premium cosmetic specifications. |
Research Methodology
Direct dialogue with plant managers at Shandong and Jiangsu surfactant facilities, procurement leads at European infant nutrition manufacturers, technical R&D directors at Asian oleochemical processors, and regulatory affairs specialists navigating ECHA dossier requirements grounded qualitative findings. Secondary validation drew from customs and trade data, SEC 10-K disclosures from listed specialty chemical firms, BIS certification registries, and SAMR GB standard publications. Bottom-up capacity modeling and top-down demand segmentation triangulated volume estimates across grade tiers and application matrices.
Segment-level outputs across emulsifier, surfactant, stabilizer, and dispersant categories combined with food, pharmaceutical, cosmetic, and personal care end-use splits to generate the projection horizon. CAGRs derived from regression against historical oleochemical price cycles, regulatory implementation timelines, and substitution elasticity estimates for competing emulsifier chemistries. Forecast inputs included EFSA re-evaluation schedules, continuous flow reactor adoption curves, and BIS certification capacity buildout in Indian domestic manufacturing.
Several conditions sit outside the modeled scope, including abrupt palm oil supply disruptions from El Niño weather patterns, unilateral tariff impositions on Chinese surfactant imports, and breakthrough displacement by novel biosurfactant platforms. Deviation in EFSA final opinion timing or severity of exposure threshold reduction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Metal Modifiers Market
Additives
Global Isosorbide Market
Additives
Sodium Stearyl Fumarate Market
Additives
Global Coalescing Agent Market
Additives
Global Peptone Market
Additives
Global Butyric Acid Derivatives Market
Additives
Phthalate and Non-Phthalate Plasticizers Market
Additives
Anti Crystallizing Agents Market
Additives
Global Propyl Acetate Market
Additives
Hydroxypropyl Distarch Phosphate Market
Additives
Spain Anti Caking Market
Additives
Global Lubricating Oil Additives Market
Additives
Tocopheryl Acetate Market
Additives
Europe Feed Additives Market
Additives
Global Silica-Based Matting Agents Market
Additives
Anti-Wear Additives Market