
 Coating Additives Market | 2026-2036
Coating Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Additives Market Intelligence
Specialty chemical production in Germany is decoupling from traditional petrochemical feedstocks, favoring bio-based alternatives for sustainable formulations. This transition allows major suppliers like BASF SE to leverage its significant R&D investment in green chemistry. Evonik Industries AG specializes in high-performance rheology modifiers and dispersants for complex water-borne systems. Meanwhile, Dow Inc. sustains its market position through its extensive global manufacturing footprint and supply chain scale.
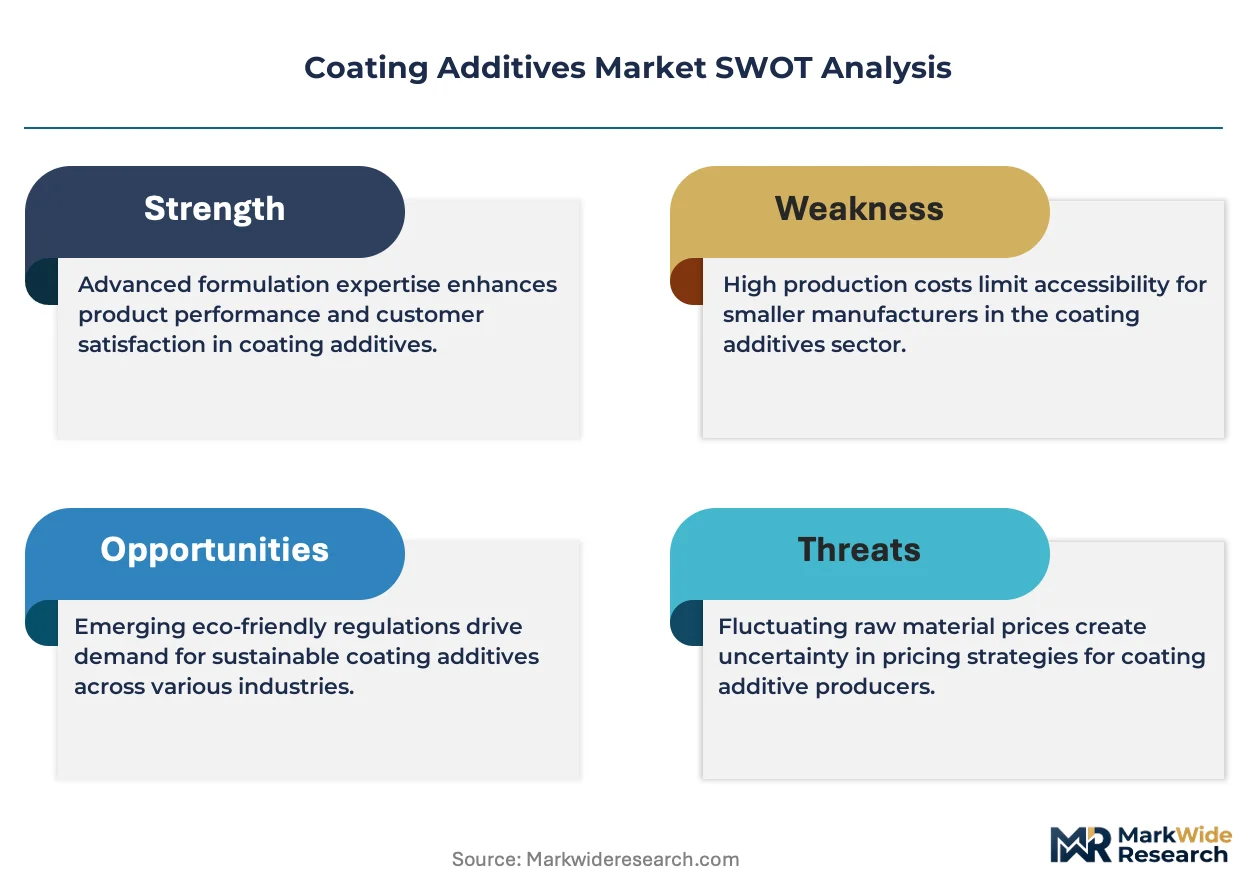
Coating additives are chemical formulations incorporated into paints and coatings to enhance specific properties and optimize cure performance. These materials, often used at concentrations below 5% by weight, modify critical characteristics like viscosity, surface tension, and pigment stability. Rheology modifiers and surfactants represent high-value product types due to their essential role in advanced water-borne systems. While architectural coatings form the largest application segment by volume, automotive coatings offer higher margins for specialized anti-corrosion and UV-resistant additives.
Regulations such as the US EPA's stringent rules on Volatile Organic Compounds (VOCs) and Europe's REACH framework directly influence product formulation. In parallel, China's national GB standards for coatings are pushing manufacturers towards lower-emission and safer chemical ingredients. Formulators must now prioritize the development of multi-functional, bio-based additives to secure a durable competitive advantage in a compliance-driven market.
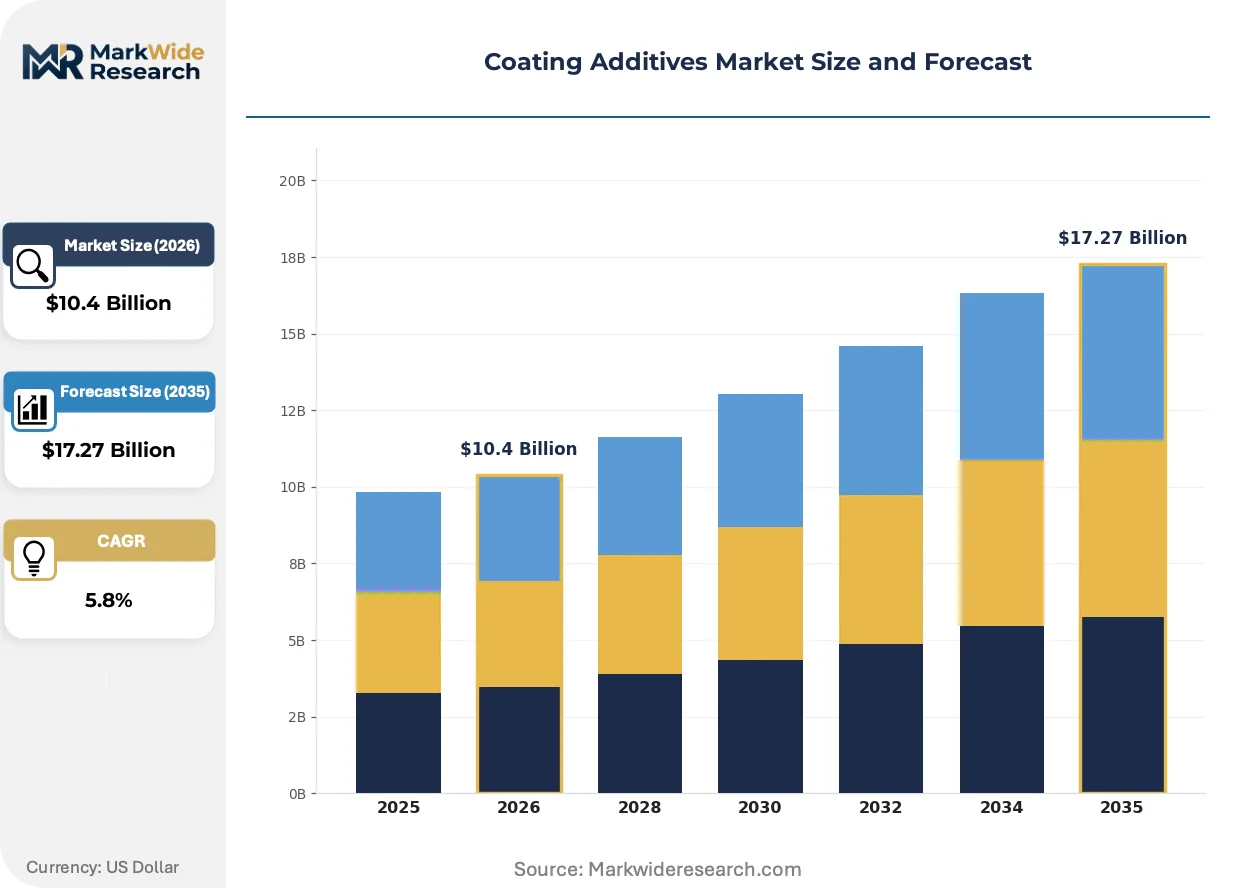
Market Dynamics
The fundamental shift from solvent-borne to water-borne and powder coating systems, driven by stringent regulations on Volatile Organic Compounds (VOCs), defines the market's trajectory. This transition, mandated by frameworks like Europe's REACH, is forcing reformulation across all application segments.
Growth Catalysts
- Sustainable Formulation Mandates:The EU Green Deal promotes bio-based additives in architectural coatings, as formulators seek sustainable ingredients to meet environmental goals.
- Electric Vehicle Production:The automotive shift to EVs demands specialized additives for thermal management and corrosion resistance in battery coatings.
- Asian Construction Boom:China's infrastructure development drives high-volume consumption of functional additives for improving durability in architectural paints.
Market Restraints
- Feedstock Price Volatility:Dependence on petrochemicals exposes manufacturers to fluctuating raw material costs, compressing margins for additives derived from acrylics.
- Water-Borne Performance Gaps:Water-borne systems often struggle to match the durability and application ease of solvent-borne coatings, a key technical hurdle.
- Supply Chain Concentration:Heavy reliance on China for key chemical intermediates creates supply vulnerabilities and exposes manufacturers to geopolitical trade risks.
Strategic Opportunities
- Smart Coating Functionality:Developing additives for self-healing or thermochromic coatings opens high-margin opportunities in aerospace and consumer electronics.
- Southeast Asian Industrial Growth:Expanding manufacturing in Vietnam and Indonesia creates new demand for performance additives in industrial and protective coatings.
- Health-Focused Additives:Integrating antimicrobial properties into additives for architectural paints meets demand for healthier indoor spaces in hospitals and schools.
Industry Challenges
- Regulatory Compliance Complexity:Manufacturers face significant operational burdens navigating the fragmented and evolving regulatory landscape, including Europe's REACH, US EPA rules, and China's GB standards.
- Formulation Expertise Scarcity:A shortage of polymer chemists skilled in developing advanced water-borne and bio-based systems hinders rapid innovation and product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Additives Market |
| Market Size in 2026 | $10.4 Billion |
| Market Size in 2035 | $17.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Resins, Pigments, Rheology Modifiers, Anti-Corrosion Agents, Surfactants Form: Liquid, Powder, Paste, Emulsion, Granule Application: Architectural Coatings, Protective Coatings, Industrial Coatings, Automotive Coatings, Wood Coatings End User Industry: Construction, Manufacturing Plants, Vehicle Assemblers, Furniture Makers, Electronics Producers |
| Companies Covered | BASF SE, Dow Inc., Evonik Industries AG, ALTANA AG, Arkema, Nouryon, Eastman Chemical Company, Clariant AG, Akzo Nobel N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Additives Market Strategic Shifts & Innovations
A pivot towards multi-functional additives that deliver performance and sustainability benefits is redefining product development. Formulators are creating single-additive solutions that address multiple challenges like flow control and pigment dispersion simultaneously.
Multi-functional additives combine properties like dispersion and rheology modification into a single formulation. Automotive and architectural manufacturers adopt these products to simplify production and reduce material complexity. This integrated approach is overtaking the traditional use of multiple, single-function additives, especially in advanced water-borne systems where component interaction is critical.
China's national GB standards for coatings impose stricter limits on Volatile Organic Compounds and hazardous substances. These regulations compel manufacturers to reformulate products, accelerating the phase-out of specific solvents and heavy-metal additives. The architectural coatings segment feels the most impact, with formulators shifting to water-based systems to meet new mandates for interior paints.
End-user procurement in high-value segments is evolving from component-based purchasing to performance-based specification. Industrial clients now demand additives that guarantee outcomes like a specific corrosion-resistance rating or UV-stability duration. This trend is most pronounced in the European marine and infrastructure sectors, where asset longevity is a critical factor in project bidding.
Coating Additives Market Segmentation
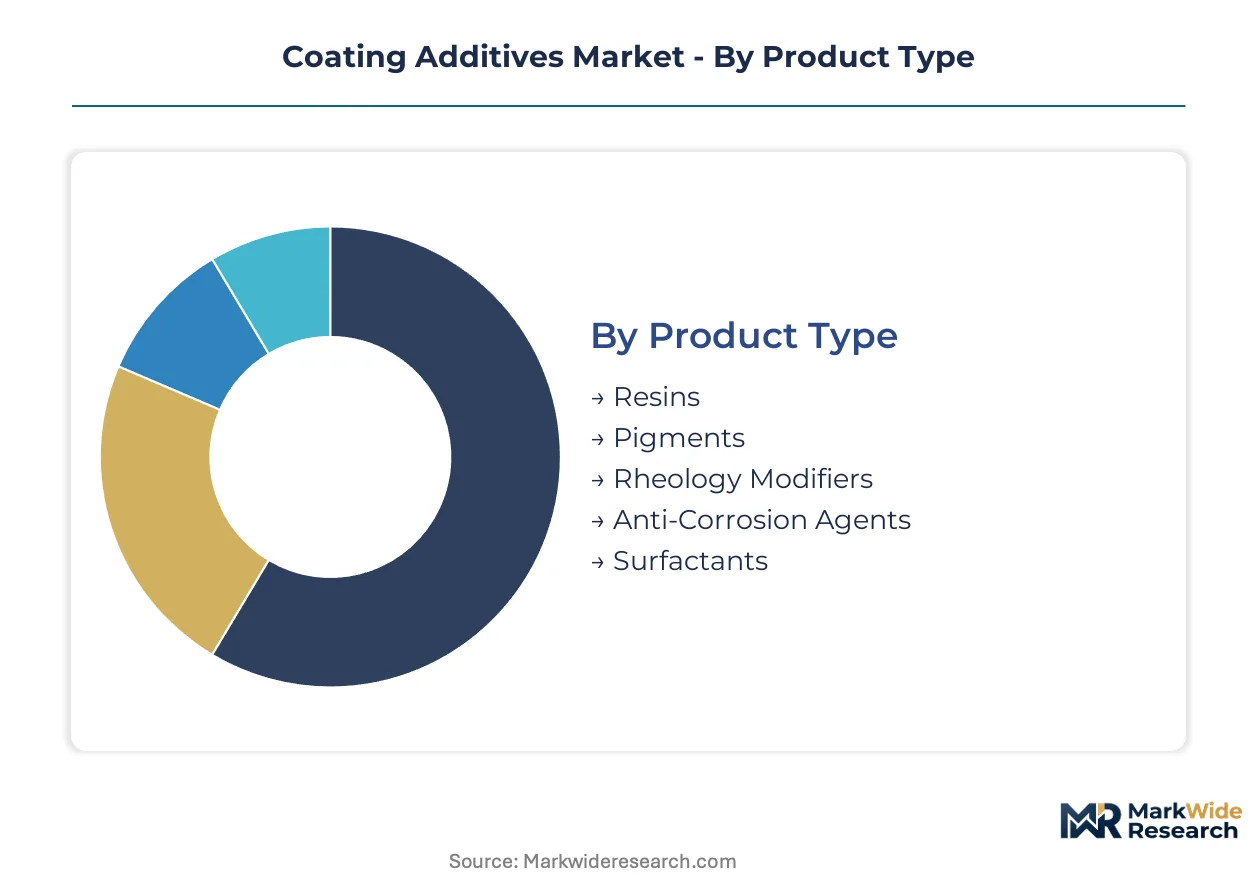
The Coating Additives market segments based on the distinct functional requirements and application environments of various coatings. Understanding these classifications helps manufacturers tailor chemical formulations for optimal performance and regulatory compliance across diverse end-use sectors. These granular distinctions drive product development and strategic market positioning for additive suppliers.
Product Type:
Buyers prioritize specific functional enhancements when selecting coating additives, directly influencing product type demand.
- Rheology Modifiers:These additives control the flow, leveling, and sag resistance of liquid coatings during application, crucial for achieving uniform film thickness. Demand concentrates in advanced water-borne systems for architectural paints and industrial finishes, where precise viscosity control is essential.
- Surfactants:Surface-active agents reduce surface tension, improve wetting, and stabilize pigment dispersion within a coating formulation. High-performance surfactants are critical for water-borne systems and automotive coatings, ensuring defect-free film formation and long-term stability.
- Resins:These form the primary binder of the coating, providing adhesion, film formation, and overall mechanical properties.
- Pigments:Insoluble particles impart color, opacity, and sometimes corrosion resistance to the coating film.
- Anti-Corrosion Agents:These chemicals protect substrates from degradation by inhibiting electrochemical reactions, highly valued in marine and protective coatings.
Volume sits with Resins; growth tilts toward Rheology Modifiers.
Form:
The physical state of coating additives dictates their ease of incorporation and compatibility with different coating systems.
- Liquid:These additives are typically supplied as solutions or dispersions, offering easy miscibility and uniform distribution within liquid coating formulations. Liquid forms are prevalent in water-borne and solvent-borne systems, simplifying manufacturing processes and ensuring consistent performance.
- Powder:Powder additives are solid particles used in powder coatings or as dry blends for specific applications, reducing VOC emissions. The shift towards powder coatings in industrial and automotive sectors drives demand for high-performance powder rheology modifiers and matting agents.
- Paste:Concentrated dispersions of pigments or functional additives in a binder, used for tinting or enhancing specific properties.
- Emulsion:Fine dispersions of polymeric or active ingredients in a liquid medium, commonly water, for stable and uniform incorporation.
- Granule:Solid, free-flowing particles offering good handling characteristics and dust reduction, often used for bulk applications.
Demand for Liquid forms remains foundational, while Powder shows accelerated adoption.
Application:
Margin potential significantly influences additive development, with specialized applications commanding higher value.
- Architectural Coatings:These coatings are applied to buildings and structures for aesthetic appeal and protection, representing the largest volume segment. Formulators prioritize cost-effectiveness and low VOC content for interior and exterior paints.
- Automotive Coatings:Applied to vehicles for aesthetics, corrosion protection, and durability, this segment demands high-performance additives. Specialized anti-corrosion and UV-resistant additives for electric vehicle batteries offer premium margins.
- Protective Coatings:Designed to shield substrates from harsh environments, requiring additives for extreme durability and chemical resistance.
- Industrial Coatings:Used on machinery, equipment, and manufacturing facilities for wear resistance and functional properties.
- Wood Coatings:Applied to wood surfaces for protection against moisture, UV radiation, and abrasion, enhancing appearance.
The largest segment by volume is Architectural Coatings, with Automotive Coatings offering premium opportunities.
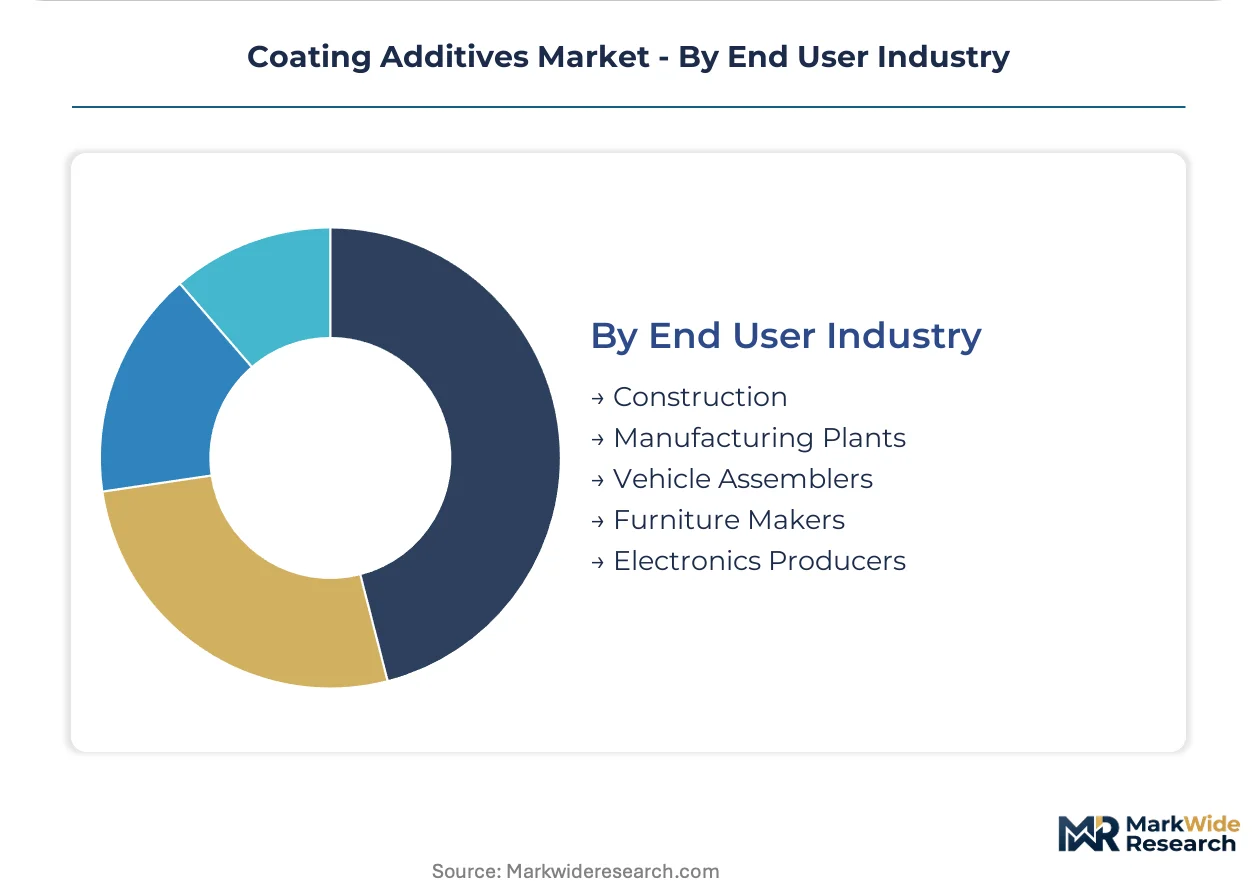
End User Industry:
Customer type and their specific operational needs determine the additive properties required for optimal performance.
- Construction:This industry uses coating additives in architectural paints, concrete sealers, and roofing materials for durability and aesthetic finishes. China's infrastructure development drives high-volume consumption of functional additives in this sector.
- Vehicle Assemblers:Automotive manufacturers require specialized additives for primers, basecoats, and clearcoats to ensure vehicle aesthetics and corrosion protection. The shift to electric vehicles creates demand for thermal management and battery coating additives.
- Manufacturing Plants:Industrial facilities utilize coatings for equipment protection, floor longevity, and safety markings.
- Furniture Makers:Manufacturers employ coatings for wood protection, scratch resistance, and aesthetic enhancement of furniture products.
- Electronics Producers:This sector uses specialized coatings for insulation, heat dissipation, and protection of delicate electronic components.
Core demand originates from Construction, with specialized requirements from Vehicle Assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive chemical intermediate production and manufacturing capacity anchors global supply chains for coating additives. This concentration influences raw material availability and cost structures worldwide. The country's large-scale industrial output drives significant demand.
China
China's vast construction and automotive sectors generate substantial demand for coating additives, especially low-VOC formulations. The country's national GB standards impose stricter limits on hazardous substances, driving reformulation efforts. Manufacturing hubs in the Yangtze River Delta actively develop advanced water-borne systems for environmental mandates.
Germany
German specialty chemical producers drive innovation in bio-based and water-borne coating additives for automotive and architectural applications. The EU Green Deal and REACH mandate sustainable formulations, influencing product development. Companies in the Rhine-Main region invest heavily in green chemistry research and development.
United States
The United States market sees strong demand for low-VOC architectural and industrial coatings, driven by environmental compliance. US EPA regulations on Volatile Organic Compounds directly influence product formulation and material selection. Chemical manufacturers along the Gulf Coast are expanding capacity for bio-based intermediates.
India
India's rapid urbanization and infrastructure projects fuel significant demand for durable architectural and protective coating additives. The Bureau of Indian Standards (BIS) promotes quality and safety, impacting additive specifications. Manufacturing clusters in Maharashtra are scaling up functional additives for domestic and export markets.
Japan
Japanese manufacturers prioritize high-performance and multi-functional additives for advanced automotive and electronics applications. METI supports research into cutting-edge materials, fostering innovation in specialized coating properties. Companies in the Kanto region focus on developing highly durable and UV-resistant additives for high-tech industries.
Coating Additives Market Key Industry Players
Global majors compete with regional champions across technology and scale in the coating additives market, creating a diverse competitive landscape. The industry exhibits a tiered structure, with large, integrated chemical conglomerates offering broad portfolios alongside specialized niche players focusing on high-performance solutions. These archetypes engage in strategic partnerships for research and development, and also pursue targeted acquisitions to expand their product lines and geographic reach.
Within the integrated chemical giants tier, BASF SE and Dow Inc. exemplify broad portfolio providers with extensive global manufacturing footprints and diverse product lines. BASF SE, a German-based Aktiengesellschaft, represents a leader in green chemistry innovation, leveraging significant R&D investments in sustainable formulations. Dow Inc., an American-based corporation, maintains its market position through its extensive supply chain scale and wide-ranging chemical offerings. Evonik Industries AG, another German-based Aktiengesellschaft, occupies a specialized position, anchoring expertise in high-performance rheology modifiers and dispersants for complex water-borne systems.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| Evonik Industries AG |
| ALTANA AG |
| Arkema |
| Nouryon |
| Eastman Chemical Company |
| Clariant AG |
| Akzo Nobel N.V. |
| Others |
Cost & Logistics Intelligence
China's national GB standards, mandating lower VOCs, significantly pressure coating additive manufacturers to reformulate products. This regulatory push forces investment in new technologies, impacting the cost structure of compliant bio-based and water-borne materials.
Pricing Analysis
After-sales technical support and formulation expertise are increasingly bundled with high-performance coating additive sales, shifting from unbundled transactional models. The market operates on a hybrid pricing model, combining contract-based long-term offtake for commodity volumes with value-based pricing for specialized additives. Price differentiation stems from performance characteristics, such as UV-resistance or corrosion protection, and compliance with stringent regulations like Europe's REACH framework. Feedstock price volatility compresses margins for standard products, making architectural coatings buyers highly price-sensitive, while automotive and protective coating manufacturers prioritize performance outcomes.
Supply Chain Analysis
Reverse logistics for coating additives remains minimal, given their complete consumption within final coating formulations. Geographic supply concentrates heavily in China for chemical intermediates and in Germany for specialized, high-performance additives. The industry relies on petrochemicals and increasingly on bio-based intermediates, facing geopolitical trade risks from China's dominant position. Distribution runs primarily through direct sales channels to large coating manufacturers, complemented by specialized chemical distributors serving smaller formulators globally.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coating additives market operates under supply constraints, particularly for high-performance bio-based intermediates. Limited specialized green chemistry production capacity props up premium pricing for sustainable formulations, creating a competitive bottleneck.
For Market Incumbents:Extend R&D investment in green chemistry to maintain leadership in sustainable formulations and bio-based alternatives. Deepen vertical integration into bio-based feedstock production to mitigate supply chain risks and ensure raw material access. Acquire niche specialists focused on advanced water-borne systems to counter emerging competitive threats from agile formulators. Prioritize certification investment for new sustainable product lines to meet evolving regulatory demands like the EU Green Deal.
For New Entrants and Emerging Players:The price-point gap between premium multi-functional additives and basic commodity products offers a clear entry opportunity. Target the mid-tier industrial coatings segment with cost-effective, bio-based rheology modifiers that meet local environmental standards. Focus on localized production in Southeast Asia, particularly Vietnam and Indonesia, where industrial growth drives new demand. A direct-to-customer digital sales platform, coupled with robust technical service, can penetrate smaller formulator accounts effectively.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers with deep pockets and a long-term vision for sustainable chemistry. This market offers strong long-term viability, driven by the global transition to bio-based and water-borne systems over the next decade. Target mid-sized specialty chemical firms possessing proprietary bio-based technologies or established distribution networks in rapidly industrializing Asian markets. Acceleration of regulatory mandates for VOC reduction in emerging economies serves as a critical inflection indicator for investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Bio-based Intermediates | Secures raw material supply for sustainable formulations, reducing dependence on petrochemical feedstocks. |
| Acquisition of Water-Borne Technology Specialists | Accelerates portfolio shift to meet stringent VOC regulations from US EPA and EU REACH. |
| Joint Venture for Asian Distribution Network | Expands market reach into high-growth construction and automotive sectors in India and Southeast Asia. |
| R&D Investment in Multi-functional Additives | Delivers single-additive solutions for complex water-borne systems, simplifying customer formulations. |
| Green Chemistry Certification Program | Validates product sustainability claims, enhancing competitive positioning with environmentally conscious buyers. |
Research Approach
Document review covered academic journals, industry reports, and regulatory filings from EU REACH, China GB standards, and US EPA, complemented by interviews. This study combined primary interviews with R&D directors, procurement leads at automotive OEMs, and specialty chemical plant managers for qualitative insights. Secondary validation utilized company annual reports and trade association publications. A rigorous bottom-up market sizing approach was triangulated with top-down validation to ensure data accuracy.
The quantitative model produced volume and value projections across the analysis window, integrating supply-side capacity and demand-side consumption trends. Segmentation dimensions modeled included product type, form, application, end-user industry, and regional regulatory impact. Compound Annual Growth Rates were derived from historical growth rates and projected adoption of water-borne systems. Key industry-specific forecast inputs included electric vehicle production forecasts and infrastructure development in China.
Inputs from major chemical suppliers and regulatory bodies were available through the study window; gaps in real-time feedstock pricing introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory enforcement and technological adoption. Geopolitical trade tensions or rapid shifts in environmental policy represent key risk factors, and material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Caustic Sulphite Caramel Market
Additives
Asia-Pacific Concrete Admixtures Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Lecithin and Phospholipids Market
Additives
Biosaccharide Gum Market
Additives
Global Calcium Formate Market
Additives
Tamarind Gum Derivatives Market
Additives
Butyrate Additives Market
Additives
Liquid Silage Additive Market
Additives
Potassium Nitrate Market
Additives
Drilling Fluid Additives Market
Additives
Monocalcium Phosphate Market
Additives
Russia Sodium Reduction Ingredient Market
Additives
Phthalate Plasticizer Market
Additives
Enzyme Stabilizer Market
Additives
Emulsifiers In Personal Care Market