
 Deepwater and Ultra-Deepwater Drilling Market | 2026-2036
Deepwater and Ultra-Deepwater Drilling Market Size, Share, and Industry Trends Forecast 2026-2036
Deepwater and Ultra-Deepwater Drilling Market Analysis
API Specification 16D for subsea blowout preventer control systems is rotating the competitive landscape by disqualifying operators without certified equipment stacks. Transocean sustains one of the largest fleets of sixth-generation drillships purpose-built for ultra-deepwater horizons. Noble Corporation specializes in harsh-environment rigs rated for North Atlantic and Barents Sea conditions. China Oilfield Services Ltd. extends its position through state-backed financing for frontier basin campaigns in Asia-Pacific and African waters.
Deepwater and ultra-deepwater drilling encompasses the deployment of floating or fixed platforms to access hydrocarbon reservoirs lying beneath ocean depths exceeding 400 meters, with ultra-deepwater classifications pushing past 1,500 meters where pressures surpass 15,000 psi and temperatures top 350°F. Drillships dominate the technology segment due to dynamic positioning capabilities that eliminate mooring constraints in ultra-deepwater frontiers, while semi-submersibles retain share in mature basins where station-keeping stability matters more than mobility. Among applications, field development commands the largest capital allocation as producers shift from exploratory drilling toward full-field subsea tiebacks that de-risk reservoir uncertainty.
Brazil's ANP mandates local content requirements that shape rig procurement decisions for operators working the pre-salt polygon, while the US Bureau of Safety and Environmental Enforcement enforces BSEE regulations governing well containment and spill response in the Gulf of Mexico. The International Maritime Organization's greenhouse gas strategy is forcing fleet operators to evaluate dual-fuel engines and emissions abatement retrofits as a condition of charter competitiveness. Stakeholders must weigh the capital intensity of next-generation rig specifications against the duration of operator commitment windows in a capital cycle defined by energy transition uncertainty.
Market Dynamics
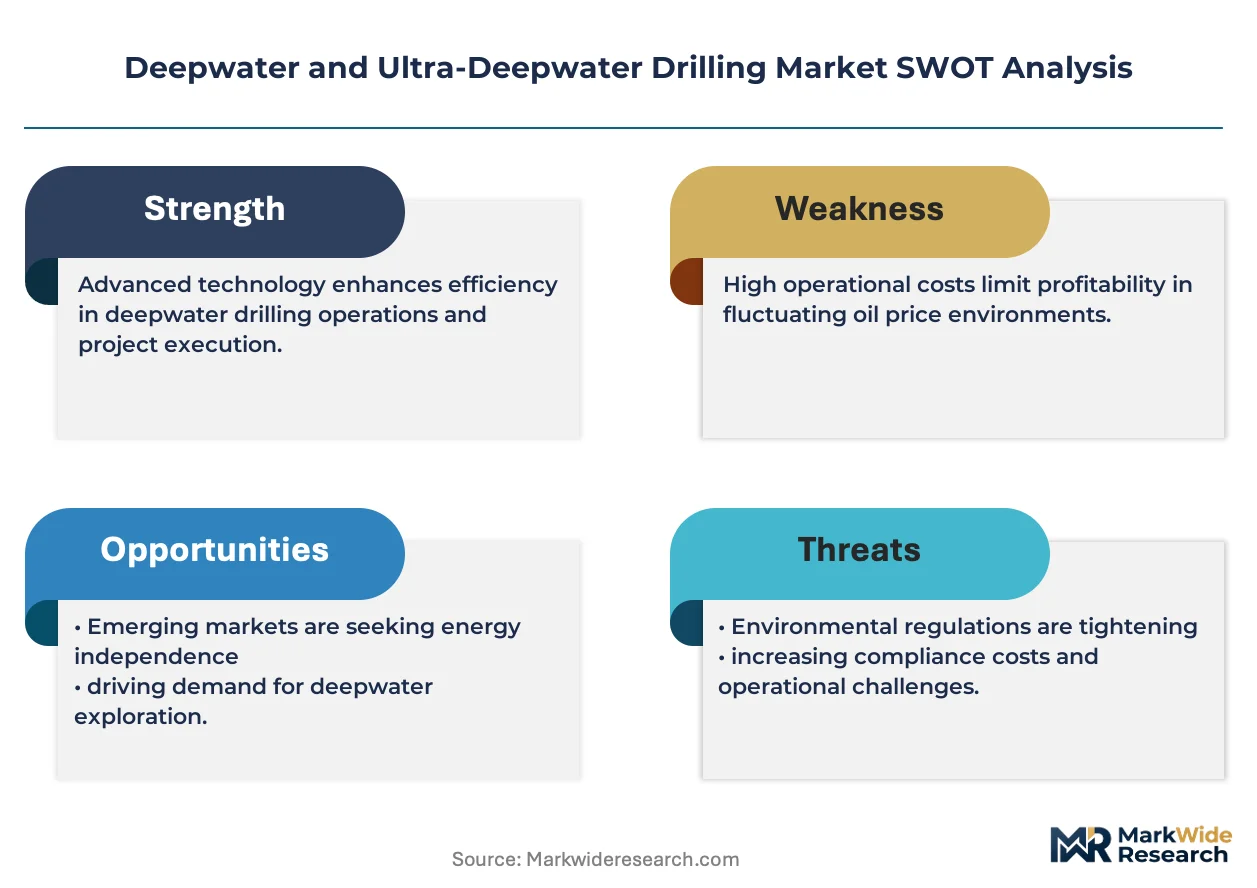
API Specification 16D certification requirements for subsea blowout preventer control systems are compressing the addressable contractor pool and concentrating day-rate negotiating power among certified fleet operators.
Growth Catalysts
- Pre-salt polygon expansion:Brazil's ANP local content mandates are sustaining rig demand as Petrobras and international partners advance development campaigns in water depths exceeding 2,000 meters.
- Dual-fuel engine retrofits:The International Maritime Organization's greenhouse gas strategy is compelling charterers to specify low-emission propulsion as a condition of contract award.
- West Africa licensing rounds:National oil companies in Angola and Nigeria are accelerating exploration commitments in ultra-deepwater blocks where reservoir quality supports full-field subsea tiebacks.
Market Restraints
- Specialized steel alloy costs:High-strength riser materials face price volatility tied to nickel and chromium supply concentration in Indonesian and Russian mining operations.
- Drillship construction backlog:South Korean and Singaporean shipyards operate at capacity, extending newbuild delivery timelines beyond operator planning horizons.
- Well containment complexity:BSEE regulations governing subsea capping stack availability impose standby vessel requirements that inflate operating expenditure baselines.
Strategic Opportunities
- Guyana-Suriname basin frontier:ExxonMobil and consortium partners are proving commercial viability in untested ultra-deepwater plays with recoverable resource estimates attracting second-tier operator entry.
- Electrification of offshore platforms:Shore power and floating offshore wind integration present pathways to eliminate offshore combustion emissions and satisfy ESG-linked financing conditions.
- Remote operations centers:Onshore rig control facilities reduce offshore headcount requirements and expand the addressable talent pool beyond traditional maritime labor markets.
Industry Challenges
- Subsea systems integration:Coordinating BOP control systems with managed pressure drilling equipment demands cross-functional engineering teams that remain scarce across contractor organizations.
- API 16D recertification timelines:Existing fleet units require hardware modifications and software validation that compress availability windows during peak demand periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deepwater and Ultra-Deepwater Drilling Market |
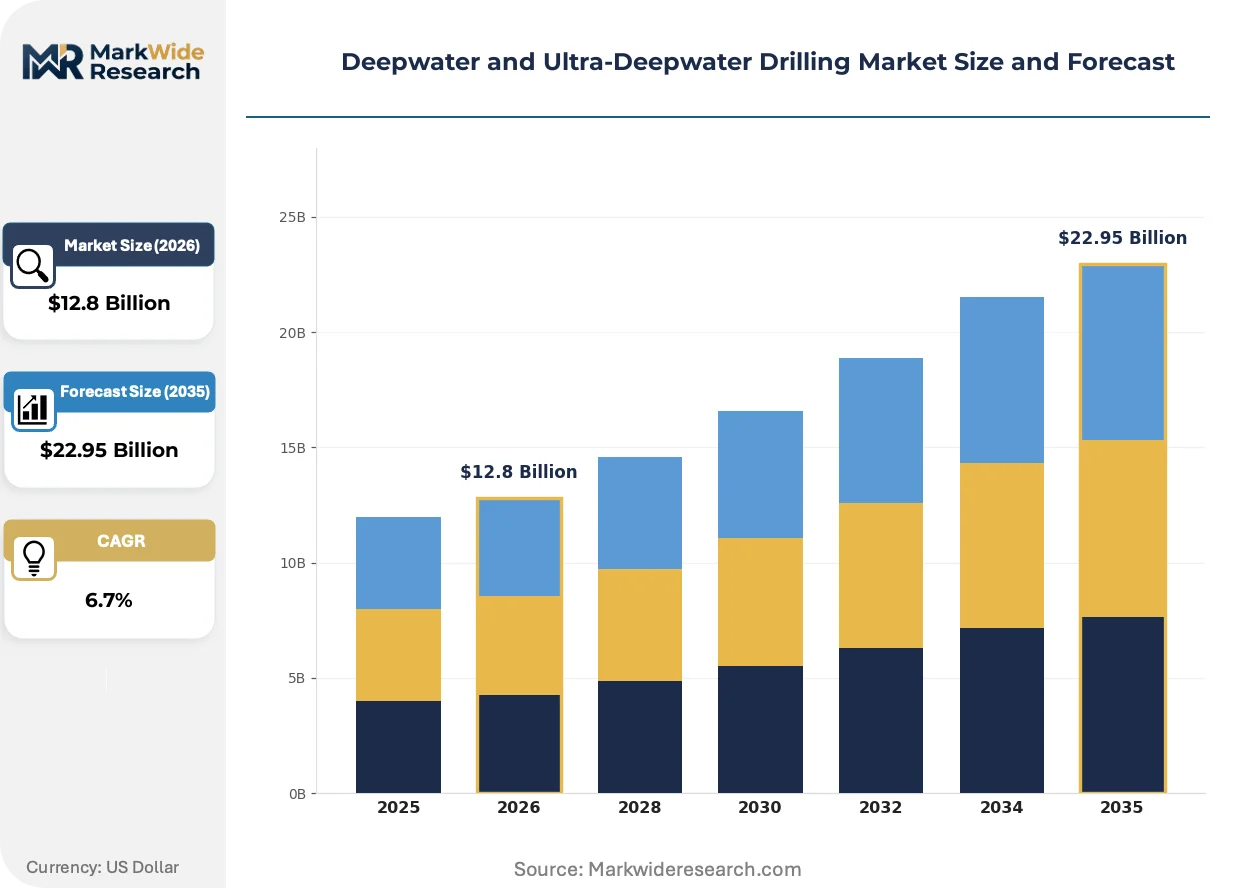
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Drillships, Semi-Submersibles, Jack-Up Rigs, Subsea Production Systems Application: Oil Exploration, Natural Gas Extraction, Field Development, Well Testing End User: Independent Operators, National Oil Companies, Multi-National Corporations, Service Providers Operation Type: Deepwater, Ultra-Deepwater, High-Pressure, Harsh Environment |
| Companies Covered | Borr Drilling, Chevron Corporation, Transocean, Shell, Exxon Mobil Corporation, Noble Corporation, BP, TotalEnergies, China Oilfield Services Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deepwater and Ultra-Deepwater Drilling Market Emerging Trajectories
Digital twin technology and autonomous subsea intervention systems are compressing the operational envelope for human-occupied vessels while extending reach into geologically complex reservoirs.
Managed pressure drilling systems with real-time annular pressure control are supplanting conventional riser-margin approaches in high-pressure, high-temperature formations. Operators in the Gulf of Mexico and Brazil's pre-salt are specifying these capabilities as baseline tender requirements. The technology is compressing non-productive time associated with wellbore instability and narrow drilling windows.
The EU Green Deal's Fit for 55 package is extending emissions monitoring obligations to offshore supply chains. Charter contracts now incorporate carbon intensity clauses that penalize excess fuel consumption. Drillship operators are responding with battery-hybrid power systems and optimized station-keeping algorithms.
Integrated service contracts that bundle drilling, completions, and subsea installation under single-source accountability are displacing fragmented procurement models. National oil companies in Brazil and Angola favor this structure to reduce interface risk. The shift is most pronounced in pre-salt developments where reservoir complexity rewards tight coordination between drilling and production engineering functions.
Deepwater and Ultra-Deepwater Drilling Market Segmentation
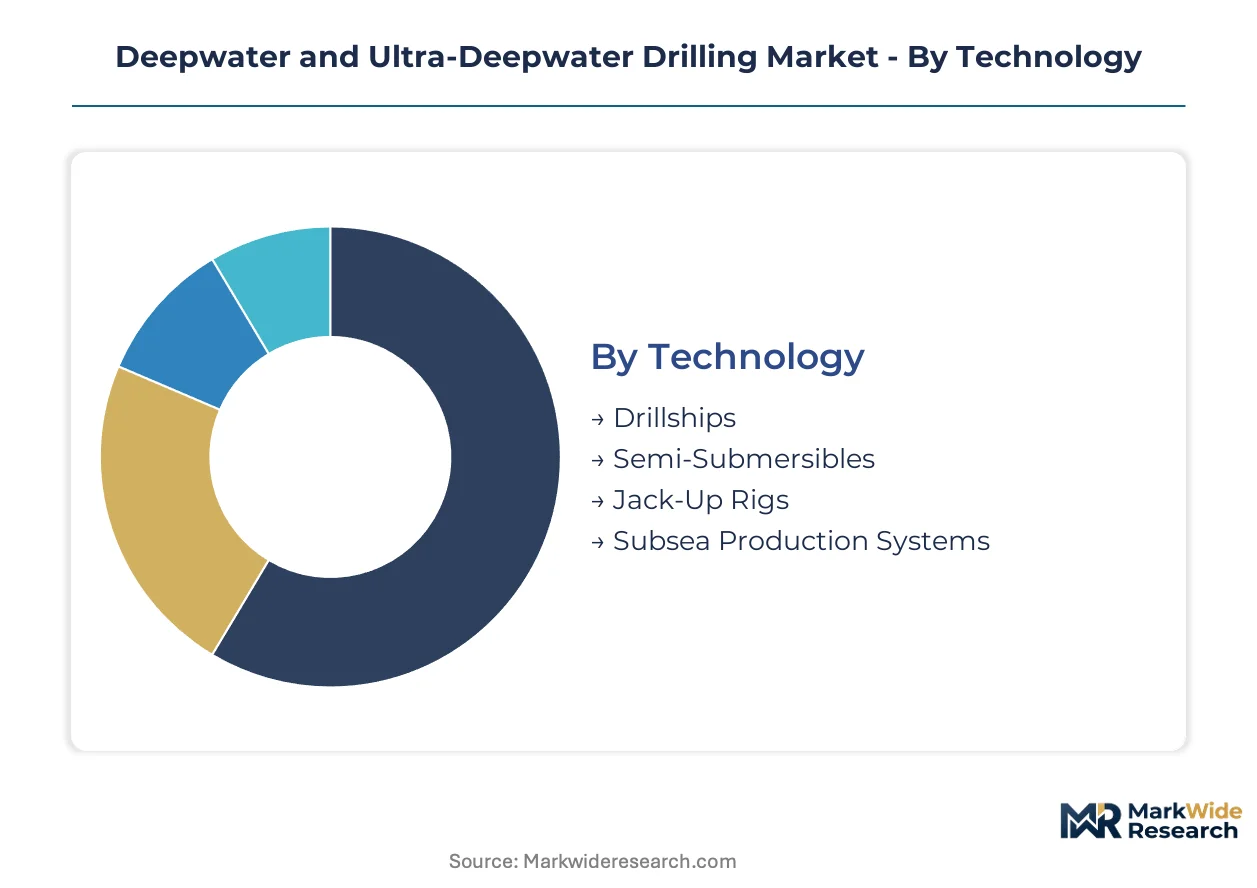
Segmentation in deepwater and ultra-deepwater drilling reveals how capital allocation, regulatory compliance, and reservoir complexity concentrate value across distinct operational profiles. Understanding these divisions clarifies where day-rate premiums materialize and which specifications command priority in contractor procurement.
Technology:
Highest margins concentrate in sixth-generation assets purpose-built for pressure regimes exceeding standard ratings.
- Drillships:Dynamic positioning systems eliminate mooring constraints in water depths surpassing 1,500 meters. Demand clusters in Brazil's pre-salt polygon and the Gulf of Mexico where Petrobras and ExxonMobil specify dual-fuel propulsion as charter prerequisites.
- Semi-Submersibles:Pontoon-stabilized hull configurations deliver station-keeping stability in mature basins. North Sea and Barents Sea operators favor these units for harsh-environment campaigns where wave height tolerances exceed drillship thresholds.
- Jack-Up Rigs:Leg-supported platforms access shelf-edge reservoirs in 400-meter depth bands. Southeast Asian national oil companies deploy these for marginal field redevelopment where full floating solutions prove economically prohibitive.
- Subsea Production Systems:Seabed processing hardware enables tiebacks to host facilities. Angola's block operators specify these for full-field developments requiring artificial lift and separation at the mudline.
Drillships hold installed capacity in ultra-deepwater basins. Semi-submersibles are rotating up the share rankings in harsh-environment Atlantic frontiers.
Application:
Capital intensity varies sharply between exploratory phases and production-scale commitments.
- Field Development:Subsea infrastructure installation and production well drilling absorb the largest capital allocations. Brazil's ANP local content mandates shape procurement for pre-salt full-field programs where reservoir uncertainty has been de-risked.
- Oil Exploration:Wildcat drilling in frontier basins demands highest-specification rigs with managed pressure drilling capabilities. Guyana-Suriname basin campaigns require real-time annular pressure control to navigate narrow drilling windows.
- Natural Gas Extraction:Deepwater gas developments concentrate in East Mediterranean and Australian waters. High-pressure, high-temperature formations necessitate specialized BOP stacks rated above standard oil-focused configurations.
- Well Testing:Formation evaluation and flow assurance activities support reservoir characterization. West African operators integrate these services into integrated drilling contracts to reduce interface risk between exploration and production engineering.
Field Development commands the dominant share of contracted rig years. Oil Exploration is expanding most quickly as licensing rounds accelerate in Atlantic margin basins.
End User:
Procurement authority and contract duration diverge across ownership structures.
- National Oil Companies:State-backed balance sheets support long-term rig charters and local content compliance. Petrobras and Sonangol dictate specifications that reshape fleet composition through ANP and ministry-level mandates.
- Multi-National Corporations:Integrated majors optimize global rig portfolios across multiple basins. ExxonMobil and consortium partners in Guyana specify standardized equipment stacks to reduce mobilization costs between campaigns.
- Independent Operators:Mid-cap producers access rigs through spot market and short-term fixtures. These players concentrate in Gulf of Mexico shelf-edge plays where jack-up availability supports marginal economics.
- Service Providers:Integrated drilling contractors bundle equipment and personnel under single-source accountability. This structure gains traction in Brazil and Angola where national oil companies seek reduced interface complexity.
National Oil Companies hold the largest contracted rig inventory. Multi-National Corporations are climbing the fastest in ultra-deepwater day-rate commitments.
Operation Type:
Technical specifications escalate with depth and environmental severity.
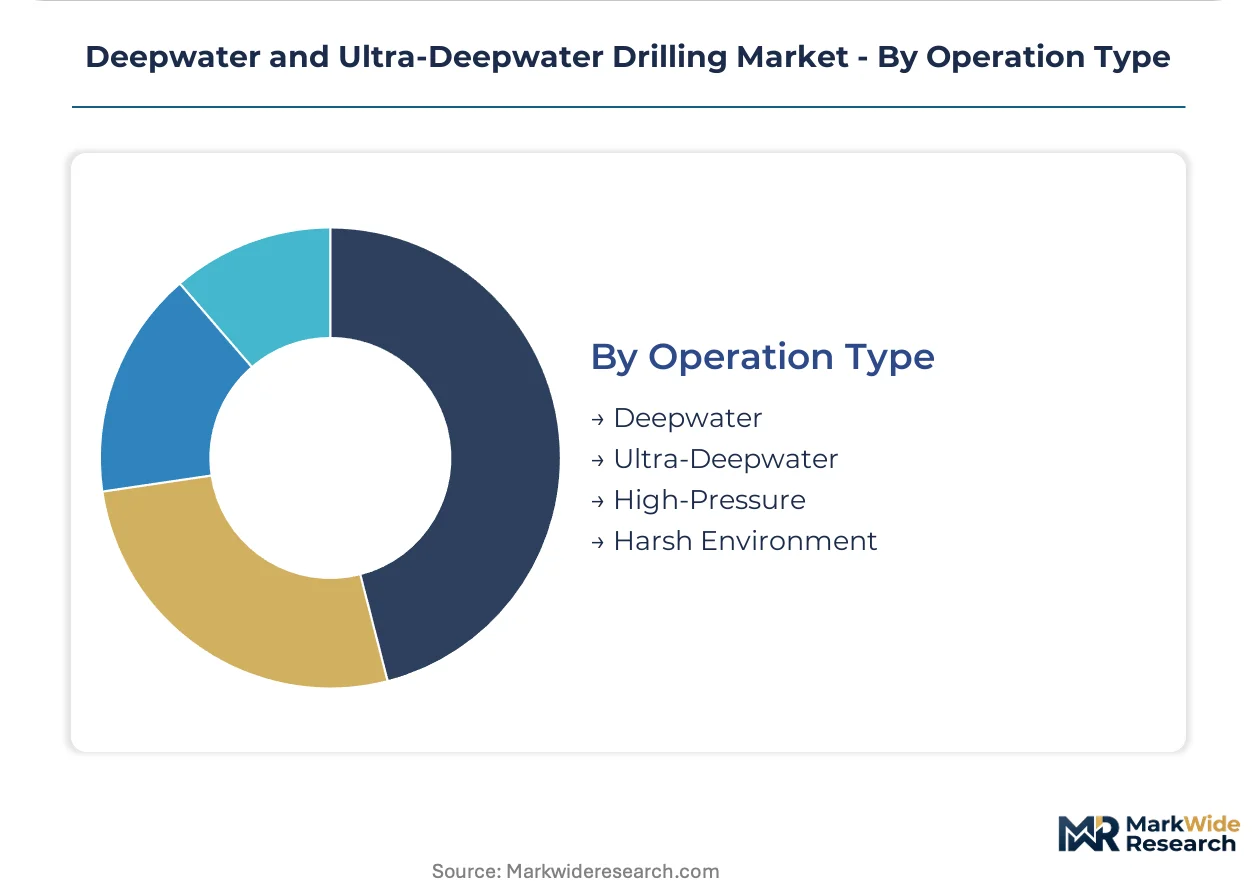
- Ultra-Deepwater:Operations below 1,500 meters require dynamic positioning and dual BOP configurations. Brazil's pre-salt and Angola's deepwater blocks represent the primary demand centers for these highest-specification assets.
- Deepwater:400-1,500 meter operations support mature basin development and frontier exploration. Gulf of Mexico operators balance rig capability against BSEE regulatory compliance costs in this depth band.
- High-Pressure:Reservoir pressures exceeding 15,000 psi demand managed pressure drilling and specialized riser materials. These conditions characterize pre-salt carbonates and select Gulf of Mexico Lower Tertiary plays.
- Harsh Environment:North Atlantic and Barents Sea operations require winterization and ice-class certifications. Norwegian and Russian Arctic campaigns specify these capabilities as non-negotiable tender requirements.
Ultra-Deepwater holds the premium day-rate tier. High-Pressure is gaining share fastest as pre-salt development scales beyond exploratory phases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-backed operators in Brazil, Angola, and the Gulf of Mexico dominate ultra-deepwater rig demand through long-term charter commitments and local content mandates. National oil companies anchor procurement decisions with decade-long planning horizons that reshape fleet deployment patterns.
United States
ExxonMobil and Chevron drive demand in the Gulf of Mexico Lower Tertiary plays where managed pressure drilling capabilities command day-rate premiums. BSEE regulations mandate subsea capping stack availability within 24 hours, inflating standby vessel requirements. Houston anchors the contractor ecosystem where Transocean and Noble Corporation maintain operational headquarters.
Brazil
Petrobras sustains the world's largest contracted drillship inventory for pre-salt carbonate development below 2,000 meters. ANP local content requirements disqualify operators without certified Brazilian-flagged support vessels. Macaé and Rio de Janeiro host the primary supply chain clusters where subsea equipment integration occurs.
Angola
Sonangol accelerates licensing rounds in ultra-deepwater blocks with reservoir quality supporting full-field subsea tiebacks. Ministry-level procurement mandates favor integrated service contracts reducing interface risk. Luanda concentrates the operational planning functions for West African frontier campaigns.
Norway
Equinor and Aker BP specify harsh-environment rigs for Barents Sea winterization requirements where ice-class certifications prove non-negotiable. The Norwegian Petroleum Directorate enforces stringent well integrity standards exceeding North Sea baselines. Stavanger hosts the engineering clusters coordinating Arctic drilling logistics.
China
China Oilfield Services Ltd. leverages state-backed financing to expand frontier basin campaigns across Asia-Pacific and African waters. The Ministry of Natural Resources prioritizes domestic ultra-deepwater capability development through technology transfer mandates. Shenzhen and Tianjin concentrate the shipyard capacity constructing dual-fuel drillship newbuilds.
Deepwater and Ultra-Deepwater Drilling Market Vendor Landscape
Player mix skews toward integrated drilling contractors with sixth-generation fleets capable of API 16D certification compliance. Market structure concentrates negotiating power among operators holding certified BOP stacks as regulatory requirements compress the addressable contractor pool. Three archetypes dominate: state-backed national champions, integrated majors with captive rig portfolios, and independent contractors serving spot market demand. Competitive moves center on dual-fuel engine retrofits for IMO compliance and strategic partnerships with shipyards to secure newbuild slots.
Within the state-backed tier, China Oilfield Services Ltd. exemplifies the national champion archetype leveraging sovereign financing for frontier expansion. Among integrated majors, ExxonMobil and Chevron occupy positions where standardized equipment stacks reduce mobilization costs across basin portfolios. Transocean anchors the independent contractor segment with sixth-generation drillship concentration purpose-built for ultra-deepwater pressure regimes.
| Leading Market Players |
|---|
| Borr Drilling |
| Chevron Corporation |
| Transocean |
| Shell |
| Exxon Mobil Corporation |
| Noble Corporation |
| BP |
| TotalEnergies |
| China Oilfield Services Ltd. |
| Others |
Supply Flow & Price Mechanics
Dual-fuel engine retrofits replacing conventional diesel propulsion simultaneously relocate shipyard demand toward South Korean and Singaporean facilities while compressing day-rate spreads between certified and non-certified fleet tiers. This substitution dynamic concentrates pricing power among contractors holding IMO-compliant assets as charterers bake emissions clauses into term contracts.
Pricing Analysis
Cost-plus contracts with steel alloy indexation dominate ultra-deepwater fixtures, linking day rates to nickel and chromium spot movements. Three-tier pricing structure across sixth-generation premium, fifth-generation standard, and legacy economy tiers reflects API 16D certification status and dynamic positioning capability. Pricing pressure stems from extended newbuild delivery timelines at Asian shipyards, stretching operator planning horizons. National oil companies exhibit lowest price sensitivity due to state-backed balance sheets, while independent operators in Gulf of Mexico shelf-edge plays face acute margin compression.
Supply Chain Analysis
Inbound logistics costs through the Singapore-Johore Strait corridor and Port of Busan concentrate riser material flows, with container availability fluctuations rippling through subsea equipment lead times. High-strength steel alloys draw from Indonesian nickel and Russian chromium mining operations, while BOP control systems rest on Norwegian and US engineering clusters. Single-source vulnerability in specialized forging capacity for wellhead connectors presents structural risk. Distribution runs through integrated service contractors bundling drilling, completions, and subsea installation under single-source accountability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of cross-functional engineering teams capable of integrating BOP control systems with managed pressure drilling equipment constrains fleet expansion regardless of capital availability. This capability gap shapes competitive durability across contractor tiers.
For Market Incumbents: Shield certified fleet positions by accelerating API 16D recertification programs before peak demand windows compress availability. Secure captive shipyard slots through strategic partnerships with South Korean builders to defend against newbuild delivery backlogs. Prioritize backward integration into high-strength riser material sourcing to offset nickel and chromium price volatility.
For New Entrants and Emerging Players: Differentiate on remote operations center capabilities that reduce offshore headcount and expand talent pools beyond traditional maritime labor markets. Target West African integrated service contracts where Sonangol procurement mandates favor bundled accountability structures. Pursue shore power and floating offshore wind integration as ESG-linked financing differentiators.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed drilling contractors holding fifth-generation fleets requiring costly IMO compliance retrofits. Long-term viability hinges on charter duration visibility through energy transition uncertainty. Monitor ANP local content enforcement intensity as inflection indicator for Brazilian pre-salt contractor profitability.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Engine Retrofit Program | IMO greenhouse gas compliance secures charter competitiveness against diesel-only fleet. |
| API 16D Certification Investment | Regulatory compliance concentrates negotiating power among certified BOP stack holders. |
| Integrated Service Contract Expansion | Single-source accountability reduces interface risk for Petrobras and Sonangol procurement. |
| Remote Operations Center Deployment | Onshore rig control expands addressable engineering talent beyond maritime labor pools. |
| Subsea Production Systems Integration | Seabed processing hardware enables Angola full-field tiebacks to host facilities. |
Methodological Framework
Operator-level perspectives from drilling contractors, national oil company procurement officers, subsea equipment integrators, and shipyard project managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through API certification databases, BSEE regulatory filings, ANP local content registries, and IMO emissions compliance records. Bottom-up rig-by-rig capacity modeling triangulated against top-down basin demand projections from licensing round schedules and field development timelines.
Sensitivity analysis tested day-rate assumptions across varying steel alloy cost scenarios and charter duration distributions. Segmentation dimensions modeled include technology tier, operation type, application phase, and end-user ownership structure. CAGRs derived from rig supply-demand balance projections incorporating newbuild delivery schedules and retirement assumptions. Forecast inputs incorporated Petrobras pre-salt development cadence and ExxonMobil Guyana-Suriname campaign pacing.
The analysis sits within stated boundaries; outcomes outside sustained oil price bands supportive of ultra-deepwater economics would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement continuity for API 16D and IMO greenhouse gas standards. Geopolitical disruption to Indonesian nickel or Russian chromium supply chains, or abrupt energy transition policy shifts, would necessitate model revision. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
East Africa Oil and Gas Downstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Oman Oil and Gas Downstream Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
Norway Oil and Gas Downstream Market