
 Oman Oil and Gas Market | 2026-2036
Oman Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Oil and Gas Market Analytics
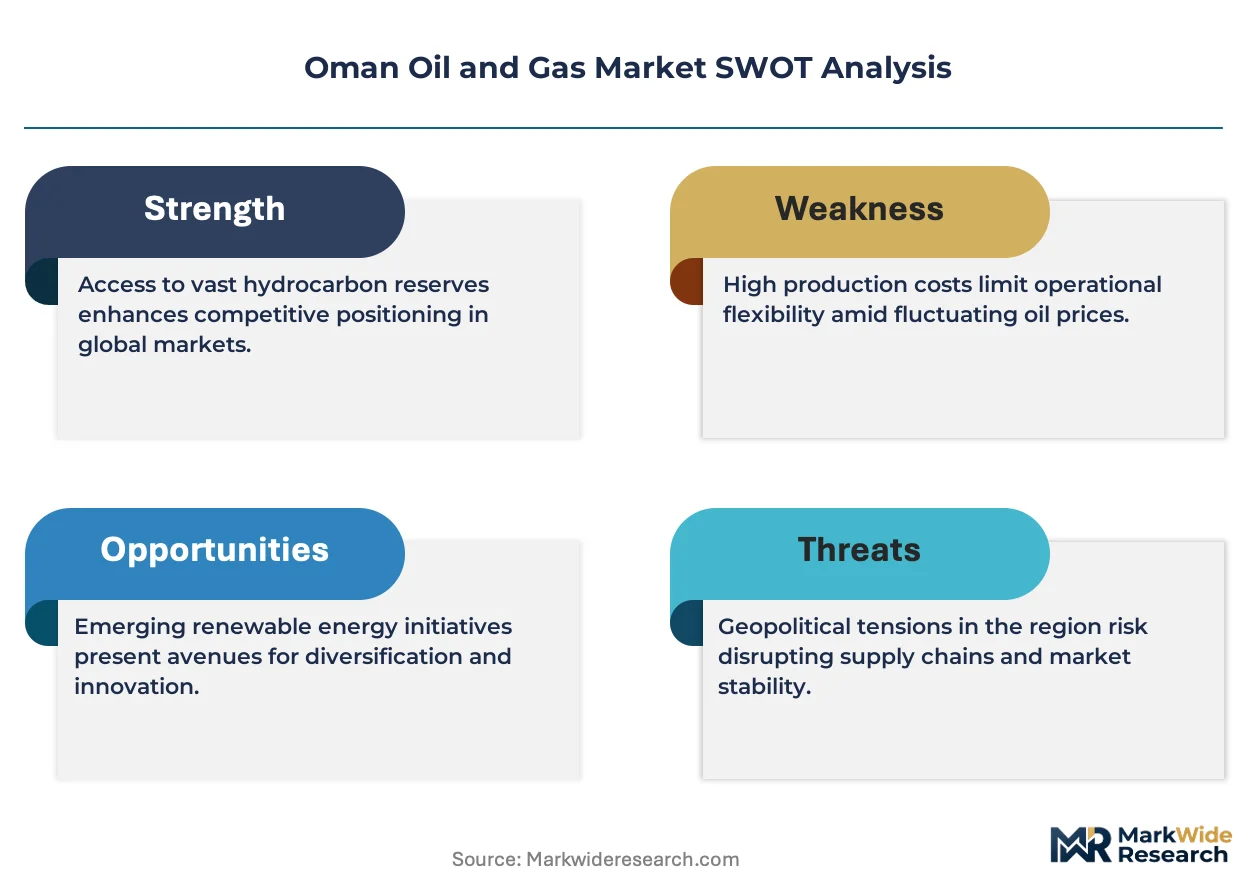
Long-term offtake contracting for Oman LNG cargoes is narrowing as Asian utility buyers seek shorter tenors and destination flexibility. Shell PLC leverages its integrated gas position to sustain feedstock security for the Qalhat liquefaction trains. TotalEnergies competes through deepwater exploration partnerships in Block 11, while Petroleum Development Oman anchors conventional output from the Marmul and Amal heavy oil fields.
Oman oil and gas encompasses hydrocarbon extraction, processing, and transport infrastructure spanning onshore conventional fields, tight gas formations, and offshore deepwater blocks with API gravities ranging from heavy 16-20 degrees to light 35-40 degrees crude, serving power generation, industrial feedstock, and export markets. Crude oil and natural gas segments dominate current production volumes, while LNG commands premium margins through long-haul Asian contracts. Refined products and petrochemical applications concentrate value-add downstream, with OQ Group's Sohar and Duqm complexes processing domestic and imported feedstocks for regional supply.
Ministry of Energy and Minerals licensing rounds and fiscal terms shape upstream access, while Environmental Authority Oman mandates flaring reduction and water management standards that elevate capital intensity for greenfield developments. International Maritime Organization sulfur caps and EU carbon border adjustments on embedded emissions redirect refining investment toward lower-carbon intensity crude slates and carbon capture integration. Stakeholders must weigh block economics against tightening domestic gas obligations and emerging hydrogen offtake frameworks before committing long-cycle capital.
Market Dynamics
Enhanced oil recovery mandates from the Ministry of Energy and Minerals are compressing capital deployment timelines while tightening domestic gas allocation obligations redirect field development priorities toward tight gas and deepwater blocks.
Growth Catalysts
- Block Licensing Rounds:Ministry of Energy and Minerals tendering of frontier acreage accelerates international participation in deepwater exploration.
- LNG offtake to Asian power utilities:Long-haul contracting to Japanese and South Korean electricity generators sustains liquefaction train utilization.
- Carbon capture integration:Environmental Authority Oman flaring reduction mandates drive investment into subsurface CO2 storage for enhanced recovery.
Market Restraints
- Mature field decline rates:Marmul and Amal heavy oil reservoirs require escalating steam and chemical injection intensity to maintain plateau.
- Domestic gas obligation tightening:State-mandated supply quotas to Sohar and Duqm industrial complexes constrain exportable LNG volumes.
- Deepwater technical limitations:Block 11 ultra-deep targets face pressure regime complexity and subsea infrastructure cost escalation.
Strategic Opportunities
- Duqm Special Economic Zone:Greenfield refining and petrochemical complex expansion offers integrated downstream entry with captive feedstock access.
- Hydrogen offtake frameworks:Emerging blue hydrogen export protocols to European industrial buyers create new monetization pathways for gas reserves.
- Al Wusta tight gas:Khazzan-Makarem field extensions and adjacent formations hold undeveloped volumes for unconventional extraction.
Industry Challenges
- Specialized subsurface engineering talent:Tight gas fracturing and deepwater drilling expertise concentrates with international service contractors, elevating project execution risk.
- Legacy infrastructure integration:New carbon capture and hydrogen production facilities must interface with decades-old pipeline networks and separation plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Oil and Gas Market |
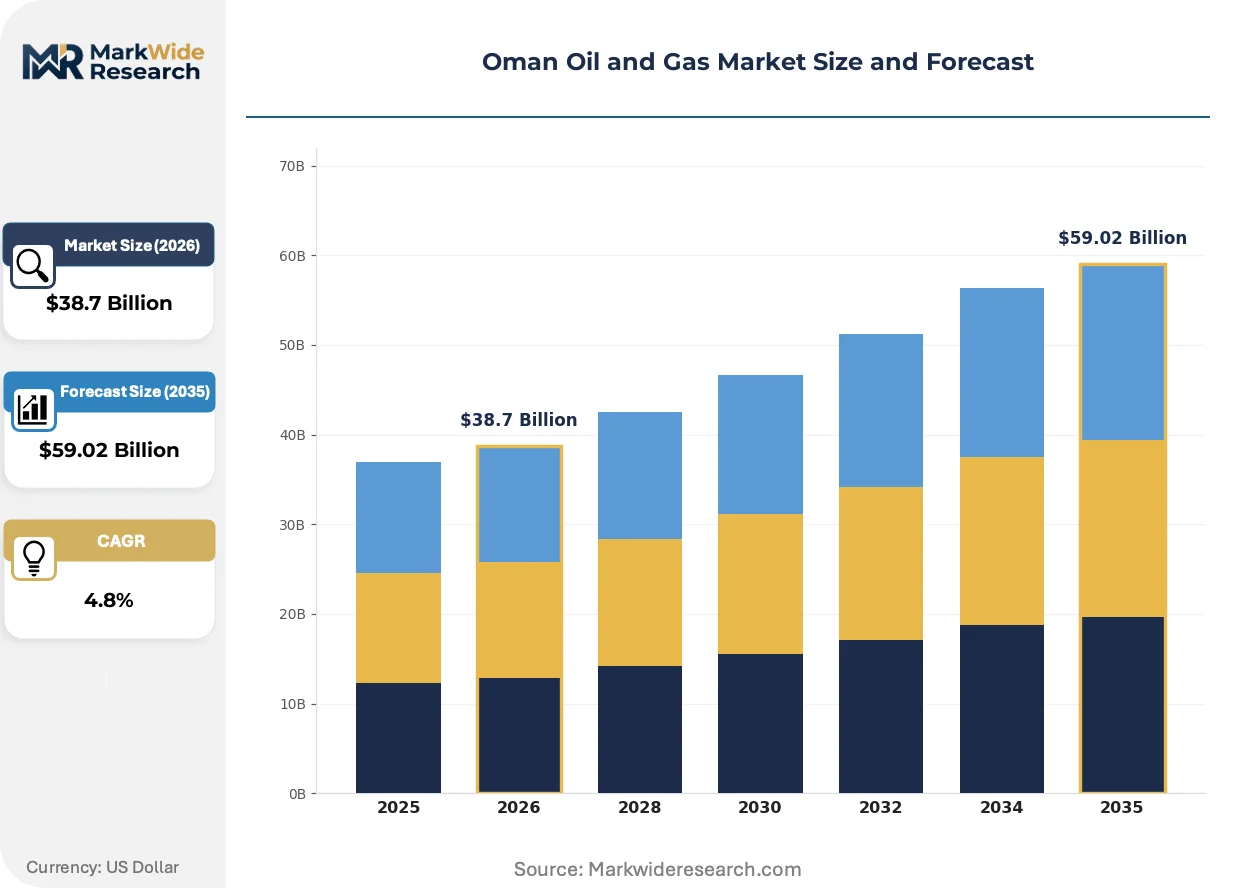
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $59.02 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crude Oil, Natural Gas, LNG, Refined Products End User: Power Plants, Industrial Sector, Residential, Refineries Application: Energy Generation, Petrochemical Production, Transportation, Heating Technology: Drilling, Exploration, Production, Refining |
| Companies Covered | TotalEnergies, China National Petroleum Corporation, Petroleum Development Oman, OQ Group, Occidental Petroleum, BP Plc, Eni SpA, Oman LNG, Shell PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Oil and Gas Market Evolving Landscape
Upstream technology deployment is pivoting toward reservoir characterization precision and emissions intensity reduction, while contractual structures and buyer preferences reconfigure around shorter commitment horizons and destination flexibility.
Digital twin reservoir modeling is hybridizing subsurface interpretation workflows by integrating real-time production data with geomechanical simulation. Petroleum Development Oman deploys these systems across mature heavy oil fields to optimize steam flood patterns. The technology is compressing field development plan revision cycles from annual to quarterly intervals.
Environmental Authority Oman flaring reduction mandates are forcing facility retrofit programs across onshore production clusters. Operators must install gas compression and reinjection infrastructure or face escalating penalty structures. The Al Wusta Governorate tight gas developments are most affected, with projects now engineering zero-routine-flaring designs from inception.
Asian utility procurement patterns are shortening LNG contract tenors and inserting destination flexibility clauses. Japanese and South Korean power generators now favor five-year agreements with reload rights over traditional twenty-year fixed-destination structures. This compression is most visible in Qalhat liquefaction train offtake negotiations, where Shell PLC adapts portfolio contracting to retain feedstock security.
Oman Oil and Gas Market Segmentation
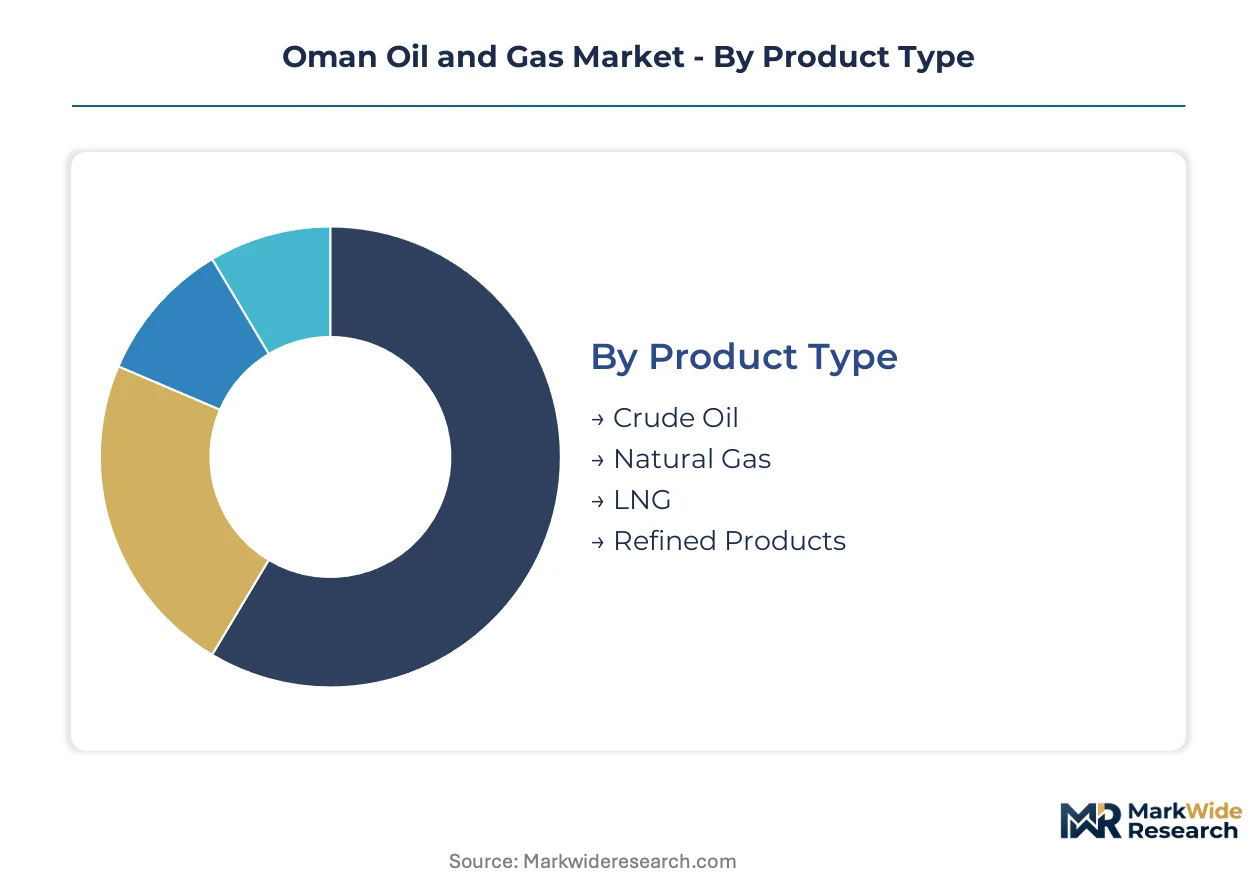
Segmentation in Oman's hydrocarbon sector reveals how resource characteristics, end-use obligations, and technology deployment shape capital allocation across upstream, midstream, and downstream nodes. Understanding these divisions clarifies where Ministry of Energy and Minerals policy intersects with commercial viability.
Product Type:
Product categories span the full value chain from extraction through processing, with each stream carrying distinct margin profiles and offtake constraints.
- Crude Oil:API gravities range from heavy 16-20 degrees at Marmul and Amal fields to light 35-40 degrees at newer blocks. Power plants in Sohar and Duqm industrial zones absorb heavier sour grades for captive energy generation, while lighter crudes command export premia to Asian refiners.
- Natural Gas:Tight gas formations in Al Wusta Governorate and conventional associated gas from mature oil fields supply dual markets—domestic industrial complexes and liquefaction trains at Qalhat. Ministry-mandated domestic allocation quotas increasingly constrain exportable volumes.
- LNG:Qalhat facility liquefaction capacity serves long-haul contracts to Japanese and South Korean utilities. Asian buyers now demand shorter tenors and destination flexibility clauses, compressing contracting structures from traditional twenty-year terms.
- Refined Products:OQ Group's Sohar and Duqm complexes process domestic and imported feedstocks into gasoline, diesel, and petrochemical precursors for regional supply.
The dominant share belongs to crude oil, while LNG is closing the gap fastest through premium Asian offtake pricing.
End User:
Customer concentration varies sharply across the sultanate's industrial geography, with state-mandated supply obligations redirecting field development priorities.
- Power Plants:Electricity generation utilities in Muscat and northern governorates consume natural gas for combined-cycle turbines. Domestic gas obligation tightening under Ministry of Energy and Minerals oversight elevates supply security concerns for grid operators.
- Industrial Sector:OQ Group's Sohar and Duqm refining and petrochemical complexes represent the largest single demand block. These facilities require consistent feedstock quality for continuous process operations.
- Residential:Distributed LPG and natural gas connections serve household heating and cooking demand, concentrated in Muscat metropolitan area and coastal urban centers.
- Refineries:OQ Group operates the primary downstream complex at Sohar with expansion underway at Duqm Special Economic Zone, processing domestic and imported crudes for product export.
Industrial offtake commands the largest volume commitment, though power sector demand is expanding most quickly through grid capacity additions.
Application:
Downstream conversion pathways determine value capture, with petrochemical integration offering highest margins per barrel equivalent.
- Energy Generation:Natural gas-fired power plants and crude oil combustion for industrial heat dominate current consumption patterns across Muscat and northern governorates.
- Petrochemical Production:OQ Group's aromatics and polyolefin units at Sohar convert naphtha and natural gas liquids into higher-value chemical intermediates for Asian manufacturing supply chains.
- Transportation:Refined gasoline, diesel, and emerging hydrogen carriers serve vehicle fleets and marine bunkering at Port of Duqm and Port of Sohar.
- Heating:Residential and commercial LPG and natural gas consumption concentrates in winter months across mountainous interior regions.
Energy generation retains the largest share, while petrochemical production is gaining share fastest through downstream margin capture.
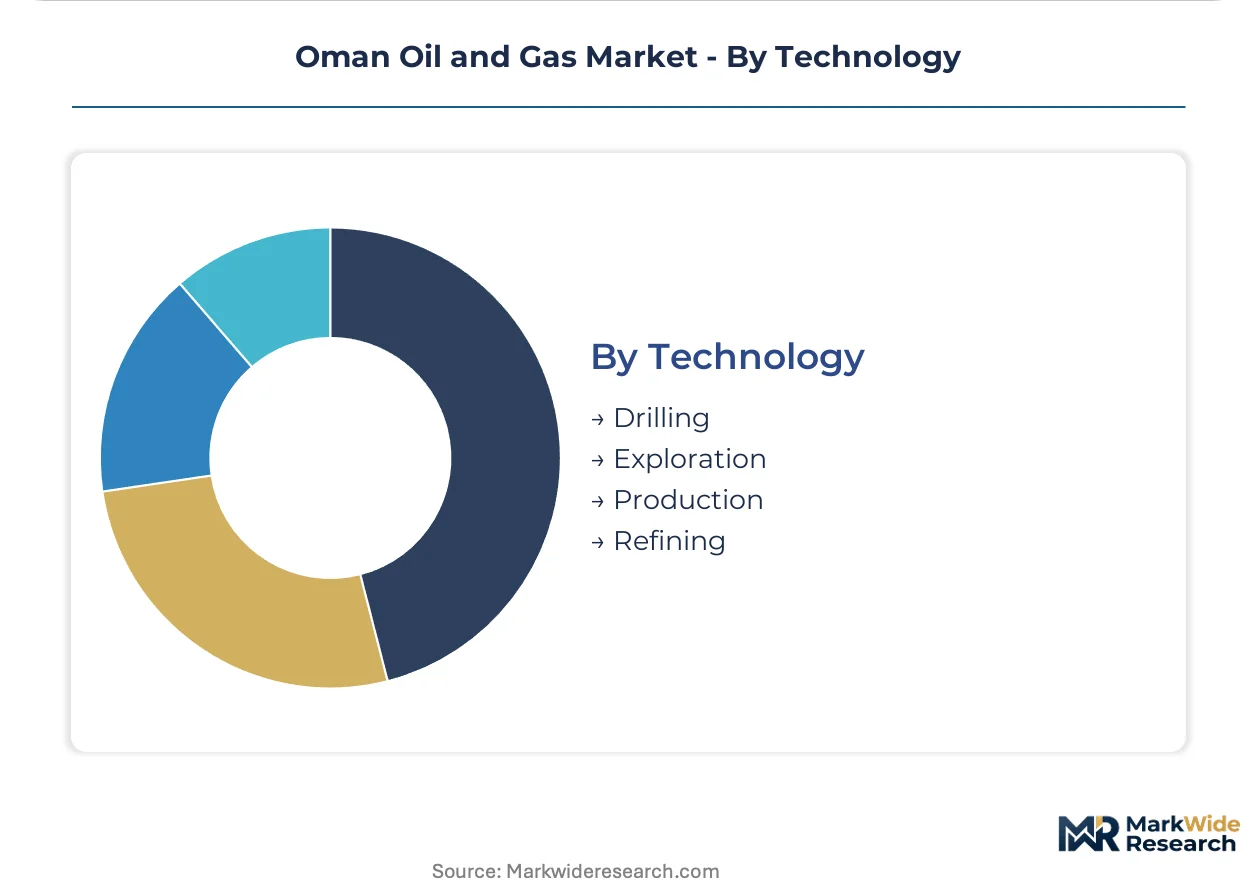
Technology:
Capital intensity and technical risk profiles vary substantially across the operational sequence, with frontier developments demanding specialized service contractor capabilities.
- Drilling:Tight gas fracturing in Al Wusta and deepwater exploration in Block 11 require horizontal well architectures and managed pressure drilling systems. Service contractors from international oilfield service providers dominate this segment.
- Exploration:Seismic acquisition and subsurface interpretation across frontier acreage, including Block 11 ultra-deep targets, faces pressure regime complexity and subsea infrastructure cost escalation.
- Production:Enhanced oil recovery mandates from Petroleum Development Oman compress capital deployment timelines for steam flood and chemical injection at Marmul and Amal heavy oil fields.
- Refining:Hydrocracking and aromatics extraction units at Sohar and Duqm complexes process varied crude slates into specification products for regional and export markets.
Production technology commands the dominant investment share, though drilling is climbing the fastest through tight gas and deepwater frontier development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ministry of Energy and Minerals licensing rounds and fiscal incentives are redirecting exploration capital toward frontier blocks while tightening domestic gas obligations reshape field development priorities across Oman's governorates.
Muscat Governorate
Power generation utilities and OQ Group's refining complex anchor natural gas demand in the capital region. Environmental Authority Oman flaring reduction mandates are accelerating carbon capture retrofit programs at onshore production clusters. The Sohar industrial corridor processes heavy sour crudes for regional product supply.
Al Wusta Governorate
Khazzan-Makarem tight gas fields and adjacent unconventional formations concentrate upstream investment and drilling activity. Ministry-mandated zero-routine-flaring designs elevate capital intensity for greenfield developments. The Qalhat liquefaction facility serves Asian utility offtake contracts with destination flexibility clauses.
Dhofar Governorate
Marmul and Amal heavy oil reservoirs require escalating steam flood intensity to combat mature field decline rates. Petroleum Development Oman deploys enhanced oil recovery mandates across these southern blocks. The Duqm Special Economic Zone offers greenfield refining and petrochemical expansion with captive feedstock access.
Block 11 ultra-deepwater exploration targets face pressure regime complexity and subsea infrastructure cost escalation. TotalEnergies partnerships compete for frontier acreage against international majors. Deepwater technical limitations compress capital deployment timelines for frontier developments.
Al Batinah Governorate
Pipeline networks and separation plants from decades-old infrastructure require integration with new hydrogen production facilities. Domestic gas allocation quotas to northern industrial zones constrain exportable LNG volumes. Legacy infrastructure retrofit programs concentrate on gas compression and reinjection systems.
Oman Oil and Gas Market Competitive Landscape
On the supply side, the industry is tiered between state-owned incumbents controlling mature acreage and international majors competing for frontier blocks through production-sharing contracts. State-owned Petroleum Development Oman anchors conventional output while Shell PLC leverages integrated gas positions and TotalEnergies pursues deepwater exploration partnerships. Competitive moves center on block licensing round participation and carbon capture integration for flaring compliance.
Within the state-controlled tier, Petroleum Development Oman exemplifies incumbent field operatorship, while Shell PLC and TotalEnergies occupy positions as international majors competing for frontier access. China National Petroleum Corporation represents Asian national oil company participation in Oman's upstream, and OQ Group anchors downstream integration across refining and petrochemical complexes. These players illustrate the competitive archetypes shaping capital allocation between mature field stewardship and frontier exploration.
| Leading Market Players |
|---|
| TotalEnergies |
| China National Petroleum Corporation |
| Petroleum Development Oman |
| OQ Group |
| Occidental Petroleum |
| BP Plc |
| Eni SpA |
| Oman LNG |
| Shell PLC |
| Others |
Value Network & Pricing Analysis
Shell PLC's integrated gas position at Qalhat and Petroleum Development Oman's mature field dominance concentrate upstream supply leverage, translating into margin capture at downstream liquefaction and refining nodes where Asian utility buyers and OQ Group complexes compete for offtake security.
Pricing Analysis
Long-term offtake contracting for Oman LNG cargoes stratifies across premium Asian utility contracts, standard industrial feedstock agreements, and spot-indexed short-tenor sales to destination-flexible buyers. Price differentiation hinges on contract duration and sulfur content specifications, with heavy sour grades from Marmul and Amal fields trading at widening discounts to lighter export crudes. Pricing pressure stems from Asian buyers demanding shorter tenors and reload rights, compressing forward revenue visibility for liquefaction train operators. Industrial offtakers at Sohar and Duqm exhibit lowest price sensitivity due to captive feedstock requirements, while speculative traders in spot LNG cargoes drive volatility at the margin.
Supply Chain Analysis
Extended payment terms from international oilfield service contractors now finance subsea infrastructure and tight gas fracturing fleets across Al Wusta and Block 11 developments. Equipment and specialized engineering talent draws from the United States, the United Kingdom, and Singapore, while steel and subsea umbilicals rest on Japanese and South Korean manufacturing. Single-source vulnerability concentrates around deepwater drilling riser systems and managed pressure control units. Distribution runs through Port of Sohar and Port of Duqm for equipment import, with pipeline networks feeding OQ Group complexes and Qalhat liquefaction trains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized subsurface engineering capabilities for tight gas fracturing and deepwater drilling remain concentrated with international service contractors, creating execution bottlenecks that elevate project risk premiums across frontier developments.
For Market Incumbents: Insulate core positions at Khazzan-Makarem and Qalhat through long-term service contractor lock-ups that preempt competitor access to fracturing fleets and subsea installation capacity. Deepen backward integration into carbon capture infrastructure to satisfy Environmental Authority Oman flaring mandates before penalty structures escalate. Prioritize vertical control over zero-routine-flaring engineering standards to deflect emerging entrant cost advantages in greenfield Al Wusta developments. For New Entrants and Emerging Players: Establish a beachhead in Block 11 deepwater exploration partnerships where TotalEnergies and Shell PLC have yet to consolidate drilling commitments, exploiting technical capability gaps for ultra-high-pressure reservoir characterization. Target the Duqm Special Economic Zone hydrogen offtake corridor where European industrial buyer protocols remain unsettled and first-mover certification advantages are available. Lead with modular carbon capture retrofit offerings for decades-old pipeline networks in Al Batinah Governorate. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private-equity-backed oilfield service specialists holding tight gas fracturing intellectual property and deepwater project management capabilities. Long-term viability centers on five-to-ten-year feedstock security for Qalhat liquefaction trains as Asian utility contracting structures compress. Watch Ministry of Energy and Minerals licensing round participation rates as the inflection signal for frontier block economics.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Integration | Environmental Authority Oman flaring mandates force retrofit investment across Al Wusta production clusters. |
| Deepwater Exploration Partnership | Block 11 ultra-deep targets require TotalEnergies alliances to manage pressure regime complexity. |
| LNG Contract Restructuring | Shell PLC adapts Qalhat offtake terms to retain Japanese and South Korean utility feedstock security. |
| Zero-Routine-Flaring Design | Khazzan-Makarem greenfield developments engineer compliance from inception to preempt penalty exposure. |
| Hydrogen Offtake Framework | Duqm Special Economic Zone positions blue hydrogen exports to European industrial buyers. |
Research Methodology
A standing panel of reservoir engineers at Petroleum Development Oman, procurement leads at OQ Group refining complexes, and LNG offtake negotiators at Asian utility buyers provided ongoing calibration across primary interview cycles. Secondary validation drew from Ministry of Energy and Minerals licensing round disclosures, Environmental Authority Oman regulatory filings, and IEA natural gas market reports. Bottom-up field development cost builds and top-down macro demand projections were triangulated to anchor volume and value estimates.
Scenario-bracketing around Asian utility contracting tenor compression and domestic gas obligation tightening framed the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, end user category, application pathway, and technology deployment intensity. CAGRs were derived from production volume trajectories and price realization assumptions, with specific inputs for enhanced oil recovery mandate compliance costs and deepwater subsea infrastructure escalation indices.
Sensitivities concentrate around Ministry of Energy and Minerals fiscal term adjustments and Asian utility buyer demand destruction from renewable power substitution. Forecasts reflect documented assumptions on block licensing round participation and frontier exploration success rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Iran Oil and Gas Downstream Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Jack-Up Rigs Market
Offshore Oil and Gas
Offshore Mooring Line Fatigue Monitoring and Test Equipment Market
Offshore Oil and Gas
East Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Azerbaijan Oil and Gas Upstream Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Offshore Remote Monitoring Solutions Market