
 Uzbekistan Oil and Gas Upstream Market | 2026-2036
Uzbekistan Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Uzbekistan Oil and Gas Upstream Market Analytics
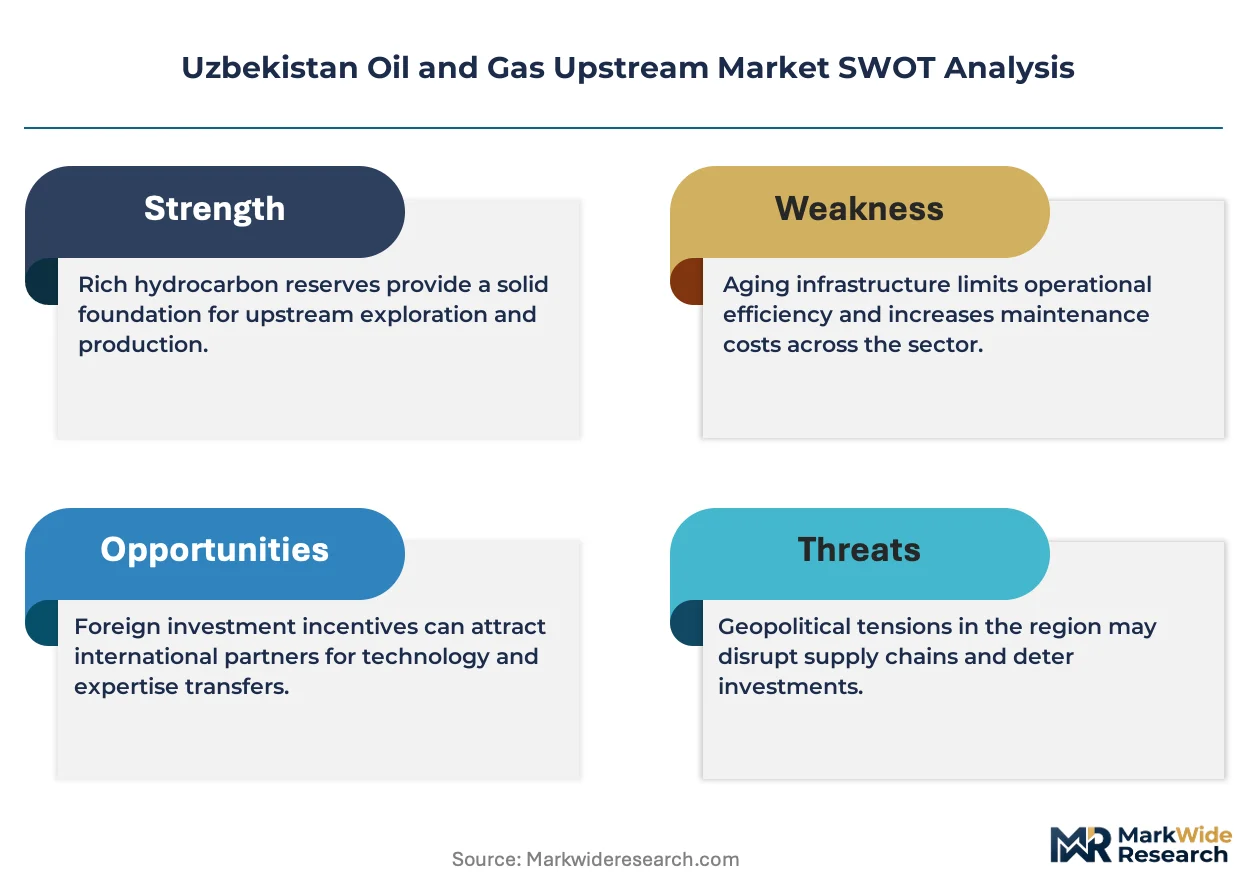
Uzbekistan's Surkhandarya gas field development is reshaping upstream capacity timelines and contractor procurement priorities. JSC Uzbekneftegaz anchors domestic production through its control of the majority of licensed acreage in the Amu Darya basin. China National Petroleum Corporation leverages its integrated drilling and pipeline construction capabilities across multiple PSA blocks. LLC LUKOIL Uzbekistan Operating Company sustains output from the Kandym gas processing complex through continuous well workover programs.
Uzbekistan Oil and Gas Upstream encompasses exploration, drilling, and hydrocarbon extraction activities targeting crude oil and natural gas reserves, with well depths typically ranging from 2,500 to 5,500 meters in the country's primary sedimentary basins. These operations supply feedstock to domestic refineries, power generation facilities, and export pipelines traversing Central Asia. Conventional production dominates current output given the mature sandstone reservoirs of the Amu Darya and Fergana valleys, while enhanced recovery methods represent the fastest-growing technology category as operators target declining legacy fields. National oil companies capture the largest share of operational control, though independent operators and international consortiums increasingly access marginal fields through tender processes.
Uzbekistan's Ministry of Energy and the State Committee for Geology regulate licensing, environmental compliance, and PSA terms for upstream operators. The country's national standards body aligns technical specifications with GB and GOST reference frameworks for drilling equipment and wellhead integrity. PJSC Gazprom and KOGAS navigate these requirements through established joint venture structures with Uzbekneftegaz. Stakeholders must monitor PSA renegotiation cycles and domestic gas pricing reform timelines to calibrate capital commitment intensity.
Market Dynamics
Enhanced recovery methods are compressing breakeven thresholds across Uzbekistan's mature sandstone reservoirs, forcing capital reallocation toward well workover intensity and artificial lift optimization in legacy Amu Darya fields.
Growth Catalysts
- PSA Framework Liberalization:Uzbekistan's Ministry of Energy Production Sharing Agreement terms now permit longer cost-recovery periods for enhanced oil recovery investments, drawing technical service contractors into marginal field tenders.
- Domestic Gas-to-Liquids Feedstock Demand:Uzbekneftegaz processing complexes require sustained upstream gas volumes, anchoring drilling commitments in the Bukhara-Khiva region regardless of export price volatility.
- Hydraulic Fracturing Technology Transfer:CNPC and KOGAS joint ventures are deploying multi-stage fracturing in tight gas sandstone, unlocking previously non-commercial reserves in Surkhandarya.
Market Restraints
- Steel Tubular Cost Volatility:Well casing and production tubing inputs track global alloy prices, exposing Uzbek drilling budgets to supply shocks from East Asian mills.
- Water Handling Infrastructure Deficits:Produced water reinjection capacity lags output growth in the Kandym complex, constraining sustainable production rates.
- Limited Domestic Drilling Rig Availability:Heavy-duty land rigs capable of 5,500-meter depths concentrate with Chinese and Russian service providers, creating procurement bottlenecks during campaign peaks.
Strategic Opportunities
- Shallow Gas Recompletions:Thousands of suspended wells in the Fergana Valley await recompletion with modern plunger lift systems, offering low-capex production restart potential.
- Carbon Capture Utilization Integration:Uzbekistan's draft climate strategy incentivizes CO2 injection for enhanced recovery, aligning with Gazprom's existing compressor station infrastructure.
- Digital Well Monitoring Adoption:SCADA and remote telemetry deployment remains below 30 percent of active well stock, creating aftermarket sensor and analytics demand.
Industry Challenges
- Reservoir Engineer Talent Scarcity:Enhanced recovery design and simulation expertise concentrates with aging Soviet-trained specialists, constraining project execution timelines.
- Legacy Wellhead Standardization:GOST-era wellhead configurations complicate international equipment integration, forcing custom fabrication or full replacement.
- Domestic Gas Price Reform Uncertainty:Wholesale pricing mechanisms remain under Ministry of Energy review, freezing long-term field development economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uzbekistan Oil and Gas Upstream Market |
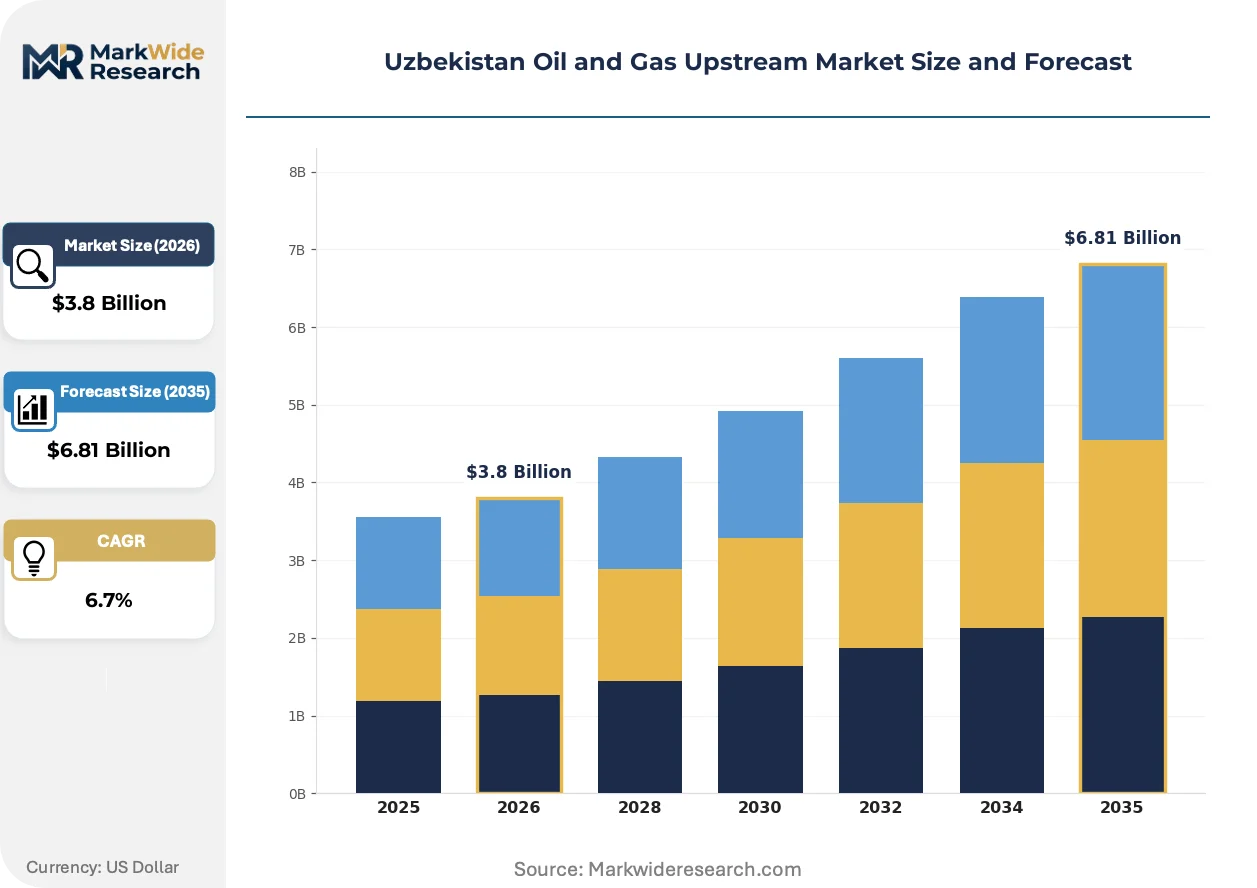
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Type: Conventional, Unconventional, Enhanced Recovery, Gas Fields Service Type: Drilling, Geological Services, Seismic Analysis, Maintenance Technology: Hydraulic Fracturing, Vertical Drilling, Horizontal Drilling, Refractory End User: National Oil Companies, Independent Operators, Contractors, Consortiums |
| Companies Covered | China National Petroleum Corporation, Petronas, JSC Uzbekneftegaz, KOGAS, KNOC, PJSC Gazprom, TotalEnergies, Centrex Europe Energy & Gas, LLC LUKOIL Uzbekistan Operating Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uzbekistan Oil and Gas Upstream Market Evolving Landscape
Automation and data-intensive reservoir characterization are compressing decision cycles between seismic acquisition and drilling commitment, collapsing traditional upstream timelines in Uzbekistan's tender-driven project environment.
Multilateral drilling and intelligent completion systems are rendering obsolete single-bore vertical well designs in tight gas sandstone. Uzbekneftegaz joint ventures with Chinese operators are deploying these configurations in Surkhandarya at accelerating frequency. The technology is rendering obsolete conventional wellhead density requirements, allowing fewer surface locations to drain larger subsurface volumes.
Uzbekistan's State Committee for Geology has tightened environmental impact assessment timelines for new exploration licenses, compressing pre-drilling approval windows from 18 months to 9 months. Operators must now submit simultaneous seismic and drilling programs to maintain schedule integrity. PSA holders in the Amu Darya basin are responding by front-loading geological staffing and contracting environmental consultancies earlier in project cycles.
Integrated service contracting is displacing discrete equipment procurement across Uzbek drilling campaigns. National oil companies now bundle directional drilling, mud logging, and completion services under single-vendor frameworks rather than managing multiple subcontractors. This consolidation is most visible in Bukhara-Khiva region tenders, where Uzbekneftegaz has mandated turnkey well construction for 2024-2025 work programs.
Uzbekistan Oil and Gas Upstream Market Segmentation
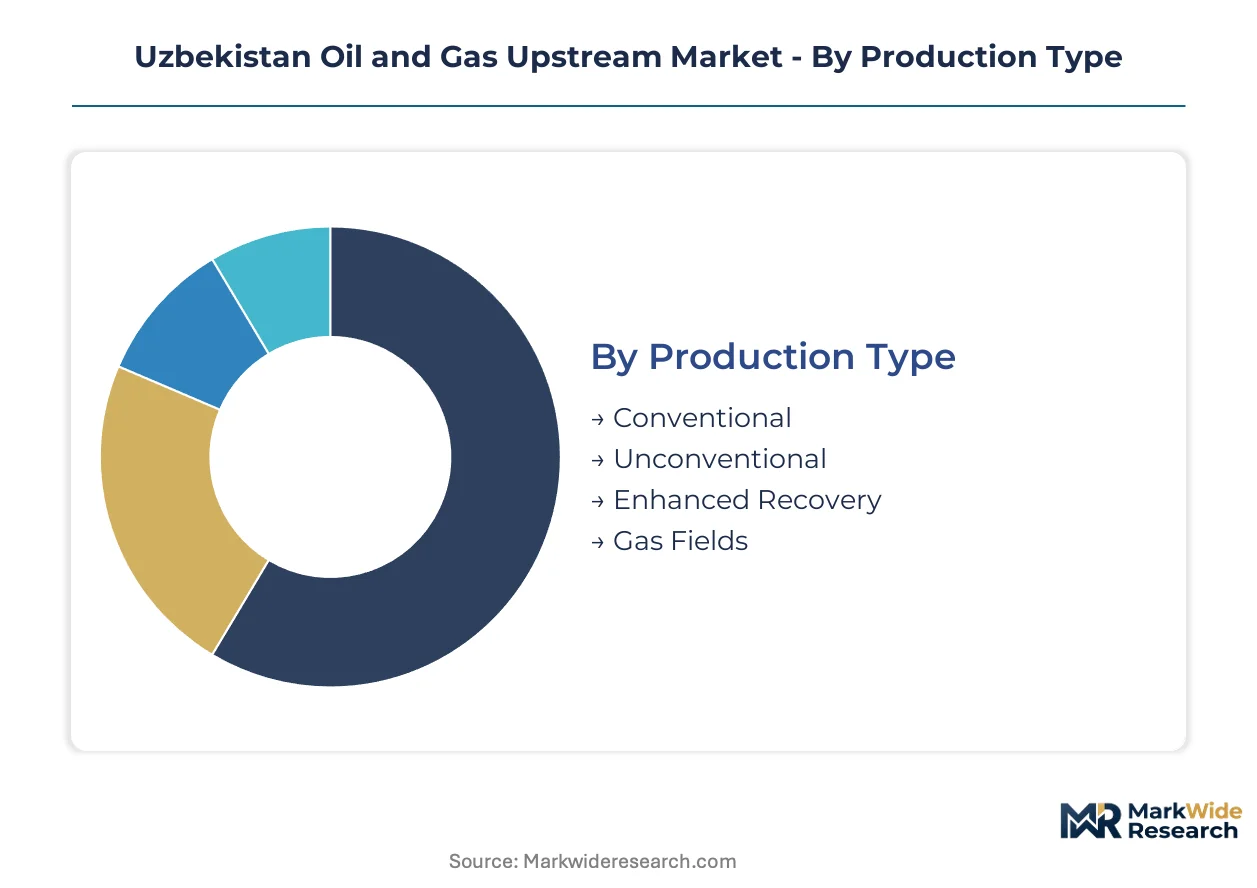
Segmentation of Uzbekistan's upstream market reveals how capital flows diverge across production methodologies, service procurement models, and technology deployment strategies. These divisions expose where state-directed investment concentrates versus where international operators extract marginal returns.
Production Type:
Cost tier differentiation separates mature field economics from frontier development in Uzbekistan's sedimentary basins.
- Conventional:Sandstone reservoirs in the Amu Darya and Fergana valleys deliver the bulk of current output through vertical well completions. Uzbekneftegaz prioritizes workover spending here to sustain baseline production volumes feeding domestic gas-to-liquids plants.
- Enhanced Recovery:Waterflooding and gas injection programs target declining legacy fields in the Bukhara-Khiva region. PSA terms now extend cost-recovery periods specifically for these investments, drawing Schlumberger and Halliburton into technical service tenders.
- Unconventional:Tight gas sandstone in Surkhandarya requires multi-stage fracturing to achieve commercial flow rates.
- Gas Fields:Dry gas developments anchor export pipeline commitments to China and Russia.
Conventional production commands the established base. The steepest expansion runs through Enhanced Recovery.
Service Type:
Application intensity varies by field maturity, with newer developments demanding integrated subsurface characterization.
- Drilling:Turnkey contracting now dominates Uzbekneftegaz tenders, bundling directional services, mud logging, and completion under single-vendor frameworks. Chinese service providers hold capacity advantages for 5,500-meter depth requirements in the Amu Darya basin.
- Geological Services:Reservoir simulation and enhanced recovery design face execution constraints from Soviet-trained specialist scarcity.
- Seismic Analysis:3D acquisition programs front-load project cycles under compressed environmental approval timelines.
- Maintenance:Well workover intensity climbs as artificial lift optimization extends field life in mature sandstone reservoirs.
Drilling absorbs the dominant share of capital allocation. Geological Services face the most acute supply bottleneck.
Technology:
Volume scalability distinguishes legacy vertical designs from multilateral configurations unlocking tight gas reserves.
- Hydraulic Fracturing:Multi-stage treatments in Surkhandarya tight gas sandstones, deployed through CNPC and KOGAS joint ventures, render previously non-commercial reserves extractable. Technology transfer agreements accelerate local crew competency.
- Horizontal Drilling:Extended-reach laterals from fewer surface locations reduce wellhead density requirements in environmentally sensitive terrain.
- Vertical Drilling:Standard completion designs persist in conventional Amu Darya fields where reservoir permeability supports single-bore economics.
- Refractory:Recompletion programs target suspended Fergana Valley wells for low-capex production restarts.
Vertical Drilling retains the installed footprint. Horizontal Drilling delivers the most rapid capability expansion.
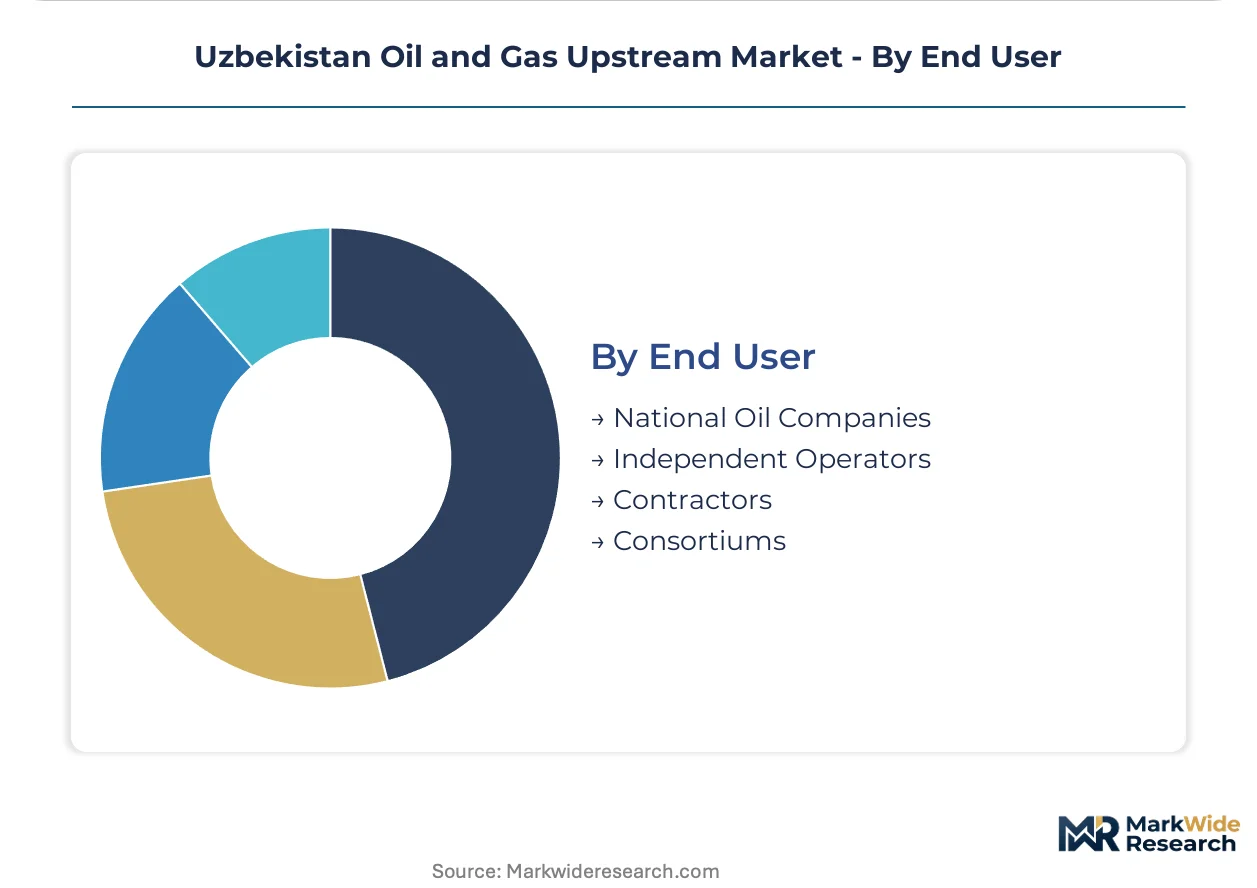
End User:
Customer type determines risk allocation, with state entities controlling license tenure while independents navigate tender volatility.
- National Oil Companies:Uzbekneftegaz holds majority licensed acreage and directs procurement through centralized tender processes. Joint venture structures with Gazprom and KOGAS channel foreign capital into development drilling.
- Consortiums:PSA frameworks permit cost recovery across extended periods, attracting integrated operators to marginal field blocks.
- Independent Operators:Smaller acreage holders focus on shallow gas recompletions and workover-intensive production.
- Contractors:Service companies execute turnkey drilling programs under Uzbekneftegaz-mandated integrated contracting rules.
National Oil Companies anchor operational control. Consortiums are gaining share fastest through PSA renegotiation cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ministry of Energy anchors Uzbekistan's upstream governance through Production Sharing Agreement frameworks that structure foreign operator entry across sedimentary basins. Regional capital deployment concentrates in the Amu Darya and Bukhara-Khiva provinces where enhanced recovery projects absorb technical service capacity.
Surkhandarya Region
Tight gas sandstone development drives drilling intensity through multi-stage fracturing programs. The State Committee for Geology compressed environmental approval timelines from eighteen to nine months, forcing simultaneous seismic and drilling submissions. The Sherabad cluster anchors contractor procurement for CNPC and KOGAS joint ventures deploying extended-reach laterals.
Bukhara-Khiva Region
Waterflooding and gas injection programs target declining legacy fields with extended PSA cost-recovery periods. Uzbekneftegaz mandates turnkey well construction bundling directional drilling, mud logging, and completion services under single-vendor frameworks. The Kandym gas processing complex sustains output through continuous well workover programs managed by Russian-Chinese service consortia.
Fergana Valley
Thousands of suspended wells await recompletion with modern plunger lift systems for low-capex production restarts. Domestic gas-to-liquids feedstock demand from Uzbekneftegaz processing complexes anchors drilling commitments regardless of export price volatility. The Namangan-Andijan corridor concentrates artificial lift optimization campaigns targeting mature sandstone reservoirs.
Karakalpakstan Autonomous Republic
Frontier exploration licenses in the Ustyurt Plateau attract consortium structures through liberalized PSA terms for enhanced oil recovery investments. The Ministry of Energy's draft climate strategy incentivizes CO2 injection for enhanced recovery, aligning with existing compressor station infrastructure. The Kungrad district hosts pilot carbon capture utilization integration projects.
Uzbekistan Oil and Gas Upstream Market Competitive Landscape
Capability concentration sits with integrated national oil companies; scale advantage sits with international operators accessing marginal fields through tender processes. Uzbekneftegaz controls majority licensed acreage and directs procurement through centralized frameworks. Three archetypes dominate: state-directed national champions, Asian integrated operators leveraging drilling-pipeline construction capabilities, and European majors navigating PSA renegotiation cycles. Competitive moves center on integrated service contracting consolidation and technology transfer agreements for tight gas extraction.
Within the national champion tier, JSC Uzbekneftegaz anchors operational control across the Amu Darya basin. Among Asian integrated operators, China National Petroleum Corporation and KOGAS occupy positions deploying multi-stage fracturing in Surkhandarya tight gas sandstones. At the European-major vector, TotalEnergies represents consortium participation through PSA structures in frontier blocks. LLC LUKOIL Uzbekistan Operating Company exemplifies sustained production management through continuous well workover programs at the Kandym complex.
| Leading Market Players |
|---|
| China National Petroleum Corporation |
| Petronas |
| JSC Uzbekneftegaz |
| KOGAS |
| KNOC |
| PJSC Gazprom |
| TotalEnergies |
| Centrex Europe Energy & Gas |
| LLC LUKOIL Uzbekistan Operating Company |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese steel tubular manufacturing is compressing input costs for Uzbek drilling contractors while simultaneously eroding pricing power among domestic rig operators competing for Uzbekneftegaz tenders. This utilization asymmetry forces service providers to absorb margin compression on fixed-price turnkey contracts even as alloy price volatility transmits through casing and tubing procurement budgets.
Pricing Analysis
Domestic wellhead gas prices in Uzbekistan trade at substantial discounts to export netbacks, creating a bifurcated pricing structure across PSA blocks. Contract-based long-term offtake agreements dominate, with price differentiation driven by reservoir depth complexity and domestic supply obligation volumes. Cost compression in standard vertical drilling packages is intensifying because Chinese service providers are undercutting Russian incumbents on day-rate bidding. National oil companies exhibit lowest price sensitivity given state-backed cost recovery guarantees, while independent operators face acute margin pressure on marginal field economics.
Supply Chain Analysis
Extended payment terms from Uzbekneftegaz are forcing drilling contractors to secure supply-chain finance facilities from Chinese equipment lessors, restructuring working capital dynamics across the Amu Darya basin. Heavy-duty land rigs and wellhead assemblies draw from China, Russia, and South Korea, with alloy steel casings and fracturing proppants resting on metallurgical supply from East Asian mills. Single-source vulnerability concentrates in 5,500-meter rated rig availability, where three Chinese providers control deployable fleet capacity. Distribution runs through Tashkent-based procurement hubs with last-mile logistics to Surkhandarya and Bukhara-Khiva field clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Uzbek upstream market rewards operators who can source reservoir engineering talent and deploy advanced recovery technologies faster than competitors. Soviet-trained specialist scarcity creates execution bottlenecks that compound project delays and inflate technical service premiums.
For Market Incumbents: Build switching-cost moats through embedded SCADA and digital telemetry infrastructure across Uzbekneftegaz's mature field portfolio. Deepen well workover service relationships to lock out Schlumberger and Halliburton from enhanced recovery tenders. Anchor capacity additions in the Bukhara-Khiva region where PSA cost-recovery extensions justify long-term capital commitment. For New Entrants and Emerging Players: Establish a beachhead in shallow gas recompletions across the Fergana Valley, where thousands of suspended wells await modern plunger lift deployment. Target independent operators and consortium sub-contractor roles bypassing direct Uzbekneftegaz tender competition. Lead with integrated environmental consultancy offerings to exploit compressed State Committee for Geology approval timelines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among technical service contractors holding multi-year maintenance agreements on gas-to-liquids feedstock supply infrastructure. Long-term viability hinges on exposure to domestic offtake rather than export price volatility. Monitor PSA renegotiation cycles and wholesale gas pricing reform announcements as inflection signals for capital commitment intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Enhanced Recovery Technology Licensing | Schlumberger and Halliburton are transferring waterflooding expertise to local crews under PSA-mandated knowledge transfer clauses. |
| Integrated Service Contracting Consolidation | Uzbekneftegaz-mandated turnkey frameworks are displacing discrete procurement across Bukhara-Khiva drilling campaigns. |
| Carbon Capture Utilization Pilot Deployment | Gazprom's compressor infrastructure in Karakalpakstan enables CO2 injection economics under draft climate strategy incentives. |
| Digital Well Monitoring Infrastructure Buildout | SCADA penetration below 30 percent of active well stock creates aftermarket sensor and analytics demand concentration. |
| Tight Gas Fracturing Capacity Expansion | CNPC and KOGAS joint ventures are deploying multi-stage treatments in Surkhandarya sandstones previously deemed non-commercial. |
Research Methodology
Initial hypotheses were tested against primary input from drilling contractors, reservoir engineering consultants, PSA negotiation advisors, and Uzbekneftegaz procurement officers and refined through secondary validation against customs records, Ministry of Energy licensing disclosures, and State Committee for Geology environmental filings. Bottom-up field development timelines were triangulated with top-down hydrocarbon reserve estimates across the Amu Darya and Fergana basins.
Demand-supply-balance modeling anchored volume projections, with segmentation across production type, service category, technology deployment, and end-user archetype throughout the forecast period. CAGRs were derived from project pipeline analysis and capital commitment intensity tracking. Forecast inputs incorporated well workover frequency assumptions, drilling rig day-rate trajectories, and domestic gas-to-liquids plant feedstock obligation schedules.
Sensitivities concentrate around PSA renegotiation outcomes, wholesale gas pricing reform implementation, and steel tubular alloy price volatility from East Asian mills. Forecasts reflect documented assumptions regarding cost-recovery period extensions and environmental approval timeline compression. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
Floating LNG Power Plant Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Gulf of Mexico Oil & Gas Decommissioning Market
Offshore Oil and Gas
Global Subsea Systems Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
Global Floating LNG Power Vessel Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market