
 Italy Automotive Engine Oils Market | 2026-2036
Italy Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Engine Oils Market Foresight
Low-viscosity synthetic formulations is tilting the Italy automotive engine oils market toward thinner, high-performance lubricants that reduce friction losses in downsized turbocharged engines. Eni SpA leverages its Ravenna refinery complex and proprietary synthetic base stock technology to dominate domestic supply. BP PLC (Castrol) anchors its position through deep workshop channel partnerships across Northern Italy's dense service network. Royal Dutch Shell Plc competes via premium positioning in OEM fill contracts with Stellantis and Ferrari.
Automotive engine oils are formulated lubricants comprising base oils and additive packages designed to reduce friction, dissipate heat, and neutralize combustion byproducts in internal combustion engines, with viscosity grades such as 0W-20 and 5W-30 now specified for newer Italian passenger car parc entries to meet fuel economy targets. Synthetic formulations command the highest margin pools as OEMs and fleet operators specify extended drain intervals, while mineral oils occupy the price-sensitive workshop segment serving older vehicle populations. The aftermarket channel generates volume concentration through Italy's aging vehicle fleet and fragmented independent service landscape, whereas OEM fill relationships with domestic manufacturers sustain strategic pull-through for premium synthetic grades.
Italy's Ministry of Infrastructure and Transport enforces type-approval alignment with EU emissions frameworks, while ACEA oil sequences and REACH chemical registration requirements shape additive chemistry choices and product reformulation cycles for market participants. The National Recovery and Resilience Plan channels investment toward sustainable mobility transitions, pressuring lubricant suppliers to demonstrate biodegradability credentials and circular packaging compliance. Stakeholders must monitor how Euro 7 implementation timelines and domestic bio-based feedstock incentives recalibrate product portfolio priorities and capital allocation across the value chain.
Market Dynamics
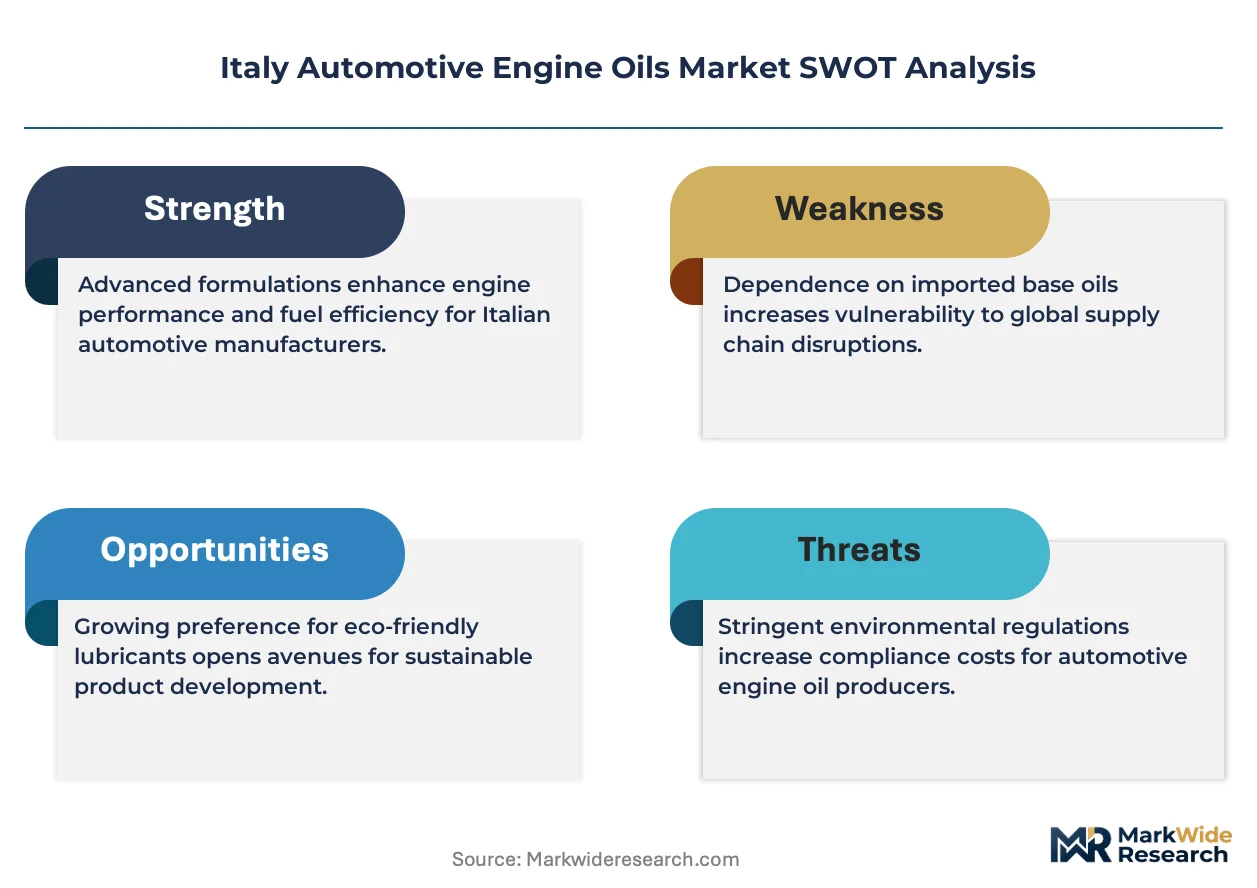
Synthetic base stock adoption is compressing drain intervals across Italy's passenger vehicle fleet while Euro 7 readiness forces additive package reformulation cycles at domestic blenders.
Growth Catalysts
- Turin-Milan-Bologna industrial corridor concentration:Dense OEM and tier-1 presence creates captive demand for high-specification lubricants, with Stellantis and Ferrari operations anchoring premium synthetic offtake.
- ACEA C6 oil sequence alignment:Updated specifications for turbocharged gasoline direct injection engines mandate low-speed pre-ignition protection, driving reformulation investments among Italian compounders.
- National Recovery and Resilience Plan bio-incentives:Circular economy funding streams reward biodegradable lubricant development and post-consumer packaging recovery systems.
Market Restraints
- Group II/III base oil import dependency:Italian refiners lack sufficient hydrocracker capacity for synthetic feedstock production, exposing margins to Rotterdam-Genoa freight volatility and currency fluctuation.
- Euro 7 compliance timeline uncertainty:Pending particulate number limits for gasoline engines create specification freeze risks, delaying capital commitment on next-generation additive investments.
- Electric vehicle powertrain substitution:Battery-electric and fuel-cell commercial vehicle pilots in Lombardy and Emilia-Romagna threaten long-term engine oil volume pools in fleet segments.
Strategic Opportunities
- Southern Italy workshop network penetration:Independent service channels in Campania, Sicily, and Calabria remain fragmented, offering consolidation targets for branded distributor programs.
- REACH-compliant bio-based ester chemistry:Domestic rapeseed and sunflower feedstock incentives under EU Common Agricultural Policy enable locally sourced synthetic alternatives to polyalphaolefin imports.
- Digital fluid monitoring integration:IoT sensor deployment in fleet management systems creates data-driven oil change subscription models, locking in volume commitments through predictive analytics.
Industry Challenges
- Additive chemist talent scarcity:Specialized formulation expertise for low-viscosity, high-durability blends concentrates at Ravenna and Milan R&D centers, constraining regional expansion.
- REACH registration cost burden:Novel friction modifier and antioxidant chemistries face extended ECHA evaluation timelines, compressing product launch windows against Asian competitor cycles.
- Legacy workshop equipment incompatibility:Independent garages serving pre-2010 vehicle populations lack bulk handling systems for 0W-8 and 0W-16 ultra-low viscosity grades, creating service friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Engine Oils Market |
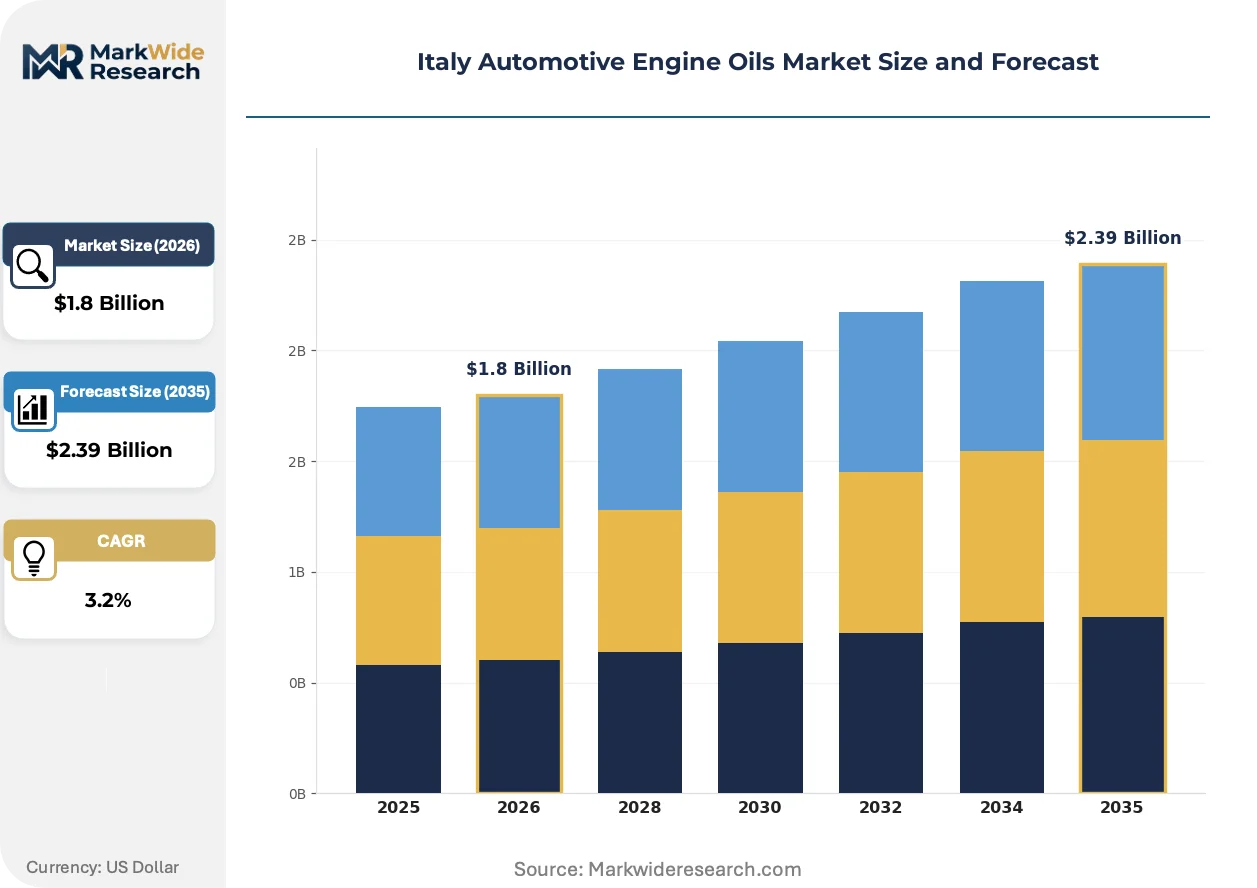
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic, Mineral, Semi-Synthetic, Bio-Based Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Drums, Bottles, Pouches, Bulk End User: OEMs, Aftermarket, Fleet Operators, Workshops |
| Companies Covered | Eni SpA, BP PLC (Castrol), Royal Dutch Shell Plc, PETRONAS Lubricants International, Q8Oils, TotalEnergies, ExxonMobil Corporation, FUCHS, LIQUI MOLY, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Engine Oils Market Shifts & Advancements
Digitalization of lubricant specification management is rewiring how Italian workshops select and procure engine oils, compressing traditional distributor relationships.
Artificial intelligence-driven viscosity grade recommendation engines are virtualizing the traditional counter-based selection process at service points. Northern Italian fleet operators and multi-site workshop chains are piloting these systems fastest. The technology is virtualizing inventory decision-making, compressing working capital requirements for mid-sized distributors.
REACH chemical registration requirements are tightening additive substance restrictions across the European Economic Area. Italian blenders face accelerated substance evaluation timelines for zinc dialkyldithiophosphate alternatives. Passenger car motor oil segments serving Stellantis and Ferrari OEM approvals are responding with pre-registration consortia to share toxicology data costs.
Subscription-based fluid management contracts are displacing spot purchasing at commercial vehicle fleets. Lombardy-based logistics operators are bundling oil changes with telematics-enabled drain interval optimization. This shift is most visible in the Milan-Bergamo-Brescia heavy-duty corridor where fleet consolidation has concentrated buyer power.
Italy Automotive Engine Oils Market Segmentation
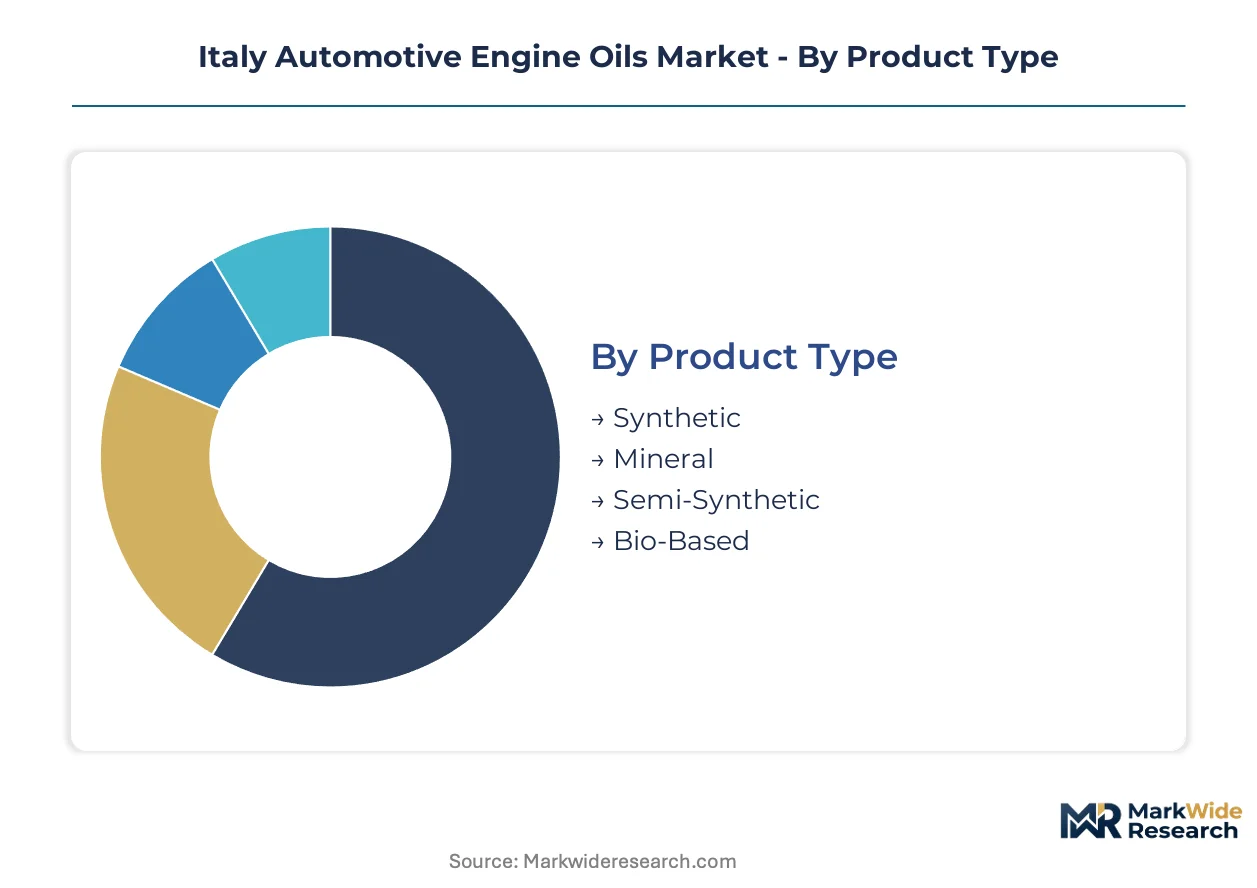
Italy's automotive engine oils market fragments along technical specifications and procurement channels that reflect the country's dual automotive heritage of mass-market Stellantis production and ultra-premium Ferrari manufacturing. Each segmentation dimension carries distinct margin profiles and service intensity requirements that shape supplier positioning strategies across the Turin-Milan-Bologna corridor.
Product Type:
After-sales service intensity varies dramatically across formulation chemistries, with synthetic grades demanding technical consultation and drain interval optimization while mineral oils compete on price and availability.
- Synthetic:Fully formulated polyalphaolefin and Group III base stocks deliver extended drain intervals up to 30,000 kilometers for turbocharged gasoline direct injection engines. Northern Italian fleet operators in Lombardy specify these grades to minimize downtime across the Milan-Bergamo-Brescia logistics corridor, though import dependency on Rotterdam-Genoa shipping lanes compresses blender margins during freight volatility.
- Mineral:Solvent-refined Group I base oils serve Italy's aging pre-2010 vehicle population through price-sensitive independent workshops. Demand concentrates in Southern Italy's Campania and Sicily regions where vehicle replacement cycles lag the North and bulk handling infrastructure remains underdeveloped.
- Semi-Synthetic:Blended formulations balance cost and performance for mid-market passenger vehicles in the 5-15 year age bracket.
- Bio-Based:Rapeseed and sunflower-derived esters qualify for National Recovery and Resilience Plan circular economy incentives targeting biodegradable lubricant development.
Synthetic holds the largest share; momentum sits with bio-based formulations as REACH compliance costs and domestic feedstock incentives recalibrate blender R&D priorities.
Viscosity Grade:
Cost tier differentiation separates premium low-viscosity specifications from standard grades, with OEM fill contracts and aftermarket pricing diverging sharply at the 5W-30 threshold.
- 0W-20:Ultra-low viscosity formulations reduce parasitic friction losses in downsized turbocharged engines meeting Euro 7 fuel economy targets. Stellantis and Ferrari OEM approvals mandate these grades for new vehicle fills, with Ravenna-based compounders holding captive supply relationships.
- 5W-30:The mainstream multi-grade specification balances cold-start protection and high-temperature stability across Italy's variable Alpine-to-Mediterranean climate zones. Volume concentrates in Turin-Milan-Bologna workshop chains serving the 2015-2022 passenger car parc.
- 10W-40:Higher viscosity legacy grade serves Southern Italy's older fleet populations and commercial vehicle segments with elevated operating temperatures.
- 15W-50:Heavy-duty specification for high-performance and classic Ferrari applications requiring enhanced film strength under extreme load conditions.
5W-30 dominates volume; 0W-20 is climbing the fastest as OEM fill specifications cascade into aftermarket replacement demand.
Packaging Type:
Volume concentration patterns align with customer scale, from bulk tanker deliveries to fleet operators down to single-liter pouch sales at rural service stations.
- Drums:205-liter steel containers serve high-throughput workshops and fleet maintenance depots across the industrial North. Milan-based distributor networks maintain drum return logistics for circular packaging compliance under extended producer responsibility frameworks.
- Bottles:Retail-format 1-5 liter polyethylene terephthalate containers dominate consumer DIY purchases and small independent garage spot buying. Campania and Sicily fragmentation drives bottle preference where bulk infrastructure investment remains uneconomic.
- Pouches:Flexible laminate packaging reduces shipping weight for export-oriented Ravenna blender operations targeting Mediterranean basin markets.
- Bulk:Tanker and flexitank deliveries lock in volume commitments from Lombardy fleet operators with centralized maintenance facilities and telemetry-enabled inventory monitoring.
Bottles capture the broadest channel reach; bulk is gaining share fastest as fleet consolidation concentrates procurement power in telematics-integrated operators.
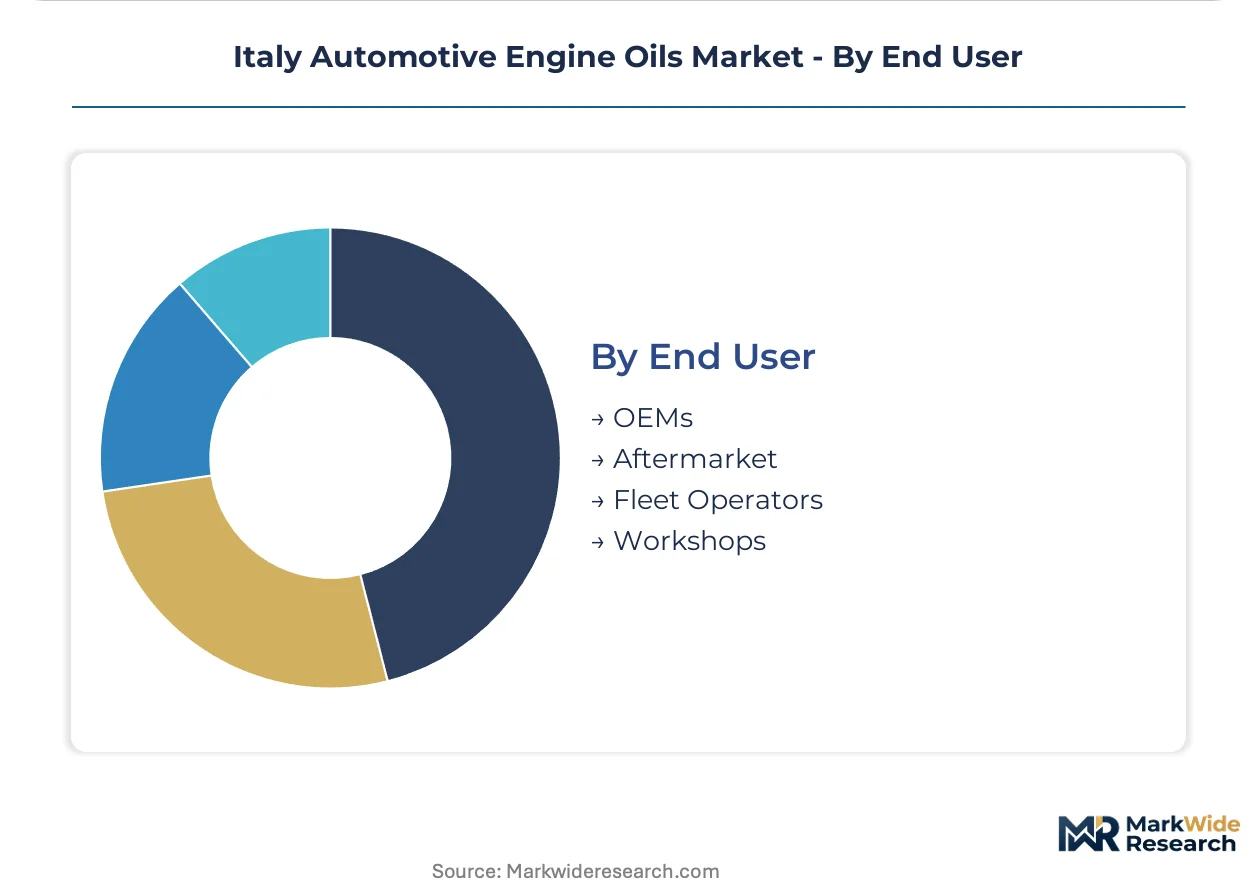
End User:
Customer type determines specification authority, with OEMs controlling first-fill chemistry while workshops and fleet operators exercise aftermarket purchasing discretion.
- OEMs:Stellantis and Ferrari manufacturing operations in Turin and Maranello specify proprietary lubricant formulations for factory fill and warranty service. These relationships generate strategic pull-through for premium synthetic grades and lock competitor blenders out of approved supplier lists.
- Aftermarket:Fragmented independent service channels across Italy's 60,000+ garages drive spot purchasing patterns sensitive to distributor credit terms and promotional pricing. ACEA sequence compliance serves as the primary quality signal in the absence of OEM branding.
- Fleet Operators:Lombardy and Emilia-Romagna logistics companies bundle oil changes with predictive maintenance contracts enabled by IoT sensor deployment.
- Workshops:Branded service chains in Northern Italy negotiate centralized procurement agreements, while Southern independents remain distributor-dependent for inventory and technical support.
Aftermarket generates the highest volume fragmentation; fleet operators show the steepest expansion trajectory as subscription-based fluid management displaces transactional purchasing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian lubricant blenders export formulated products to Mediterranean basin markets through Ravenna port infrastructure, while Rotterdam-Genoa shipping lanes feed synthetic base stock imports that sustain domestic high-performance production.
Lombardy
Milan-Bergamo-Brescia logistics corridors concentrate heavy-duty fleet operators specifying extended-drain synthetic grades. The National Recovery and Resilience Plan channels circular economy funding toward biodegradable lubricant development in this region. Telematics-integrated procurement platforms are consolidating buyer power among Lombardy fleet managers.
Piedmont
Stellantis manufacturing operations in Turin generate captive demand for OEM-approved first-fill formulations. Euro 7 emissions readiness timelines shape lubricant specification requirements for turbocharged gasoline direct injection engines. The Turin metropolitan area anchors premium synthetic offtake through factory fill and warranty service networks.
Emilia-Romagna
Ferrari operations in Maranello drive ultra-premium lubricant specifications for high-performance applications. REACH chemical registration requirements from ECHA constrain additive substance choices for domestic compounders. Bologna-based R&D centers specialize in low-viscosity formulation chemistry for downsized engines.
Veneto
Ravenna refinery complex and port infrastructure enable both domestic supply and Mediterranean export positioning. ACEA oil sequence alignment mandates drive reformulation investments among regional blenders. The Ravenna industrial cluster concentrates proprietary synthetic base stock technology and hydroprocessing capacity.
Italy Automotive Engine Oils Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Italy's fragmented 60,000-garage service network. The market structure tiers between integrated energy majors with refinery-backed supply security and independent compounders serving niche specifications. Three archetypes dominate: refinery-integrated majors leveraging captive base stock production, international lubricant specialists with OEM approval portfolios, and regional distributors controlling Southern Italy workshop access. Competitive moves concentrate on workshop channel partnerships and bio-based formulation credentials.
Among refinery-integrated majors, Eni SpA anchors domestic supply through Ravenna complex verticality. BP PLC (Castrol) and Royal Dutch Shell Plc represent international specialists competing via premium positioning and OEM fill relationships. These three occupy positions across the synthetic formulation tier where extended drain intervals and Euro 7 readiness specifications command margin premiums.
| Leading Market Players |
|---|
| Eni SpA |
| BP PLC (Castrol) |
| Royal Dutch Shell Plc |
| PETRONAS Lubricants International |
| Q8Oils |
| TotalEnergies |
| ExxonMobil Corporation |
| FUCHS |
| LIQUI MOLY |
| Others |
Supply & Pricing Matrix
Ravenna's hydroprocessing capacity and proprietary synthetic base stock technology anchor domestic supply security, translating upstream feedstock control into pricing leverage for compounders serving Stellantis and Ferrari OEM fill contracts. Rotterdam-Genoa freight volatility and currency fluctuation compress blender margins during import cycles, while ACEA C6 sequence compliance costs recalibrate premium tier positioning across Northern Italy's workshop networks.
Pricing Analysis
Current-generation 0W-20 ultra-low viscosity formulations command substantial premiums over legacy 10W-40 grades, while next-generation bio-based esters await REACH registration cost recovery. Three-tier pricing structure across premium synthetic, standard semi-synthetic, and economy mineral levels reflects ACEA certification tiers and drain interval performance. Cost compression in the mineral tier intensifies because Southern Italy's aging fleet replacement cycles lag the North. Independent workshops serving pre-2010 vehicles exhibit highest price sensitivity; OEM-approved synthetic distributors to Lombardy fleet operators show lowest.
Supply Chain Analysis
Extended payment terms from Ravenna blenders to Rotterdam base oil traders stabilize working capital through cyclical freight rate spikes. Geographic supply concentration centers on Netherlands, Belgium, and Germany for Group II/III hydrocracked feedstocks. Raw material dependencies encompass polyalphaolefin base stocks, zinc dialkyldithiophosphate alternatives, and bio-ester chemistries from domestic rapeseed. Single-source vulnerability runs through Rotterdam-Genoa maritime lanes during North Sea weather disruptions. Distribution runs through Milan-based distributor networks with drum return logistics for circular packaging compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Euro 7 emissions readiness and ACEA C6 oil sequence mandates are compressing specification cycles, creating acceleration windows for compounders with captive R&D and refinery-backed feedstock security.
For Market Incumbents: Build formulation moats around low-speed pre-ignition protection chemistry and biodegradable ester pre-registration consortia. Deepen backward integration into Ravenna hydrocracker capacity expansions to offset Rotterdam import dependency. Lock exclusive workshop channel partnerships across Turin-Milan-Bologna before specification freeze risks materialize. For New Entrants and Emerging Players: Build out digital fluid monitoring platforms targeting Lombardy fleet operators with predictive analytics subscription models. Southern Italy's Campania and Sicily workshop fragmentation offers the most penetrable geography. Pursue white-label bio-based formulation partnerships with National Recovery and Resilience Plan circular economy funding recipients. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because REACH registration cost burdens and additive chemist talent scarcity favor scaled compounders with toxicology data sharing capabilities. Target acquisition archetypes include regional distributors controlling Southern Italy garage networks and bio-ester technology specialists with domestic feedstock sourcing. Watch Euro 7 particulate number limit finalization timing as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthetic Base Stock Production | Ravenna hydrocracker investments reduce Rotterdam import exposure and stabilize blender margins. |
| REACH-Compliant Bio-Ester Pre-Registration Consortia | Shared toxicology data costs accelerate novel friction modifier launch timelines against Asian competitors. |
| Digital Fluid Monitoring Platform Deployment | IoT sensor integration locks Lombardy fleet volume through predictive drain interval optimization. |
| Southern Italy Workshop Network Consolidation | Branded distributor programs capture fragmented Campania and Sicily aftermarket demand pools. |
| OEM Fill Contract Extension with Stellantis | Factory fill relationships cascade 0W-20 specifications into warranty service pull-through demand. |
Research Methodology
The analysis maps synthetic formulation tiers, viscosity grade specifications, and packaging format channels, each validated through lubricant blender technical directors, OEM procurement managers, aftermarket distributor operations heads, and fleet maintenance supervisors. Primary fieldwork combined with secondary validation from ACEA oil sequence documentation, ECHA substance registration databases, Italian Ministry of Infrastructure type-approval records, and customs trade data. Bottom-up volume builds across the Turin-Milan-Bologna corridor triangulate against top-down national lubricant consumption estimates.
Assumption sets held Euro 7 implementation timelines and ACEA sequence adoption curves fixed while varying electric vehicle penetration rates and bio-based feedstock incentive intensities across the projection horizon. Segmentation dimensions modeled encompass formulation chemistry, viscosity grade, packaging type, and end-user procurement channel. CAGRs derive from parc-adjusted drain interval compression rates and synthetic grade substitution elasticities. Forecast inputs include Stellantis production schedules, Ferrari factory fill specifications, and National Recovery and Resilience Plan circular economy funding disbursement trajectories.
Stress conditions across Rotterdam-Genoa freight volatility bands, euro currency fluctuation ranges, and REACH registration timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding ACEA C6 sequence adoption and Euro 7 particulate number limit stringency. Macroeconomic contraction, regulatory timeline extension, or accelerated electric vehicle powertrain substitution would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
Ethyl Tertiary Butyl Ether Market
Fuels
South America Commercial Aircraft Aviation Fuel Market
Fuels
Emulsified Fuel Market
Fuels
Middle-East and Africa Defense Aircraft Aviation Fuel Market
Fuels
United States Coal Market
Fuels
Hybrid Propellants Market
Fuels
Gas Feed System Market
Fuels
Europe Wood Pellet Market
Fuels
Europe Defense Aircraft Aviation Fuel Market
Fuels
Aerospace Aviation Fuels Market
Fuels
Commercial Aircraft Aviation Fuel Market
Fuels
Palm Methyl Ester Market
Fuels
Mobile Fuel Delivery Market
Fuels
Wood Charcoal Market
Fuels
Catalytic Hydrothermolysis Jet [CHJ] Fuel Market
Fuels
Gas Pooling Mechanism Market