
 Europe Offshore Energy Market | 2026-2036
Europe Offshore Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Offshore Energy Market Foresight
The EU Green Deal is broadening the cost-of-entry calculus for developers by embedding stricter environmental impact assessments and carbon-accounting requirements into licensing rounds. Ørsted AS leverages its integrated development model across the full project lifecycle to sustain cost discipline in deeper-water zones. Siemens Gamesa Renewable Energy SA anchors turbine supply chains through manufacturing scale in Northern European ports. Vestas Wind Systems AS competes on modular platform architectures that reduce installation vessel days.
Europe offshore energy encompasses electricity generation, hydrocarbon extraction, and marine resource harvesting conducted in territorial and exclusive economic zone waters beyond coastal shallows, typically employing fixed-bottom monopiles in depths under 60 meters and floating semi-submersible platforms for sites exceeding that threshold. Wind farms dominate installed capacity, while floating platforms represent the fastest-expanding technology segment as developers push into deeper Atlantic and Mediterranean basins where seabed conditions preclude conventional foundations. Subsea systems capture concentrated margin pools through cable protection, foundation transition pieces, and inter-array grid infrastructure that commands premium engineering intensity.
EMA marine licensing protocols, REACH substance restrictions on anti-corrosion coatings, and the F-Gas Regulation on switchgear insulating media collectively shape equipment specifications and supplier qualification pathways across European waters. National regulators in Denmark, Germany, and the Netherlands enforce divergent seabed lease auction formats that fragment market access rules. Stakeholders must monitor how the EU AI Act and delegated acts under the CSRD extend reporting obligations to offshore asset environmental performance data.
Market Dynamics
Floating platform technology is redrawing project economics across European waters, compressing installation timelines and unlocking lease zones previously excluded by seabed geology constraints.
Growth Catalysts
- REPowerEU Acceleration:The EU framework compresses permitting timelines for cross-border offshore clusters, particularly in Danish and German waters where interconnection capacity expands.
- Port Infrastructure Modernization:Northern European fabrication hubs in Rotterdam, Esbjerg, and Bremerhaven are scaling heavy-lift quayside capacity to handle 15+ megawatt turbine components.
- Green Hydrogen Integration:Electrolyzer co-location at offshore substations creates offtake certainty for wind developers facing merchant price exposure in North Sea power markets.
Market Restraints
- Specialized Vessel Scarcity:The global fleet of jack-up installation units remains concentrated among Korean and Chinese yards, creating bottlenecks for North Sea construction windows.
- Copper and Rare Earth Volatility:Subsea cable manufacturing depends on copper price stability, while direct-drive generators require neodymium supply security from concentrated Chinese processing.
- Seabed Lease Auction Design:Divergent auction formats between Dutch SDE++ subsidy rounds and German zero-subsidy tenders fragment developer capital allocation strategies.
Strategic Opportunities
- Portuguese and Spanish Atlantic Zones:Deep-water basins off the Iberian Peninsula remain underpenetrated, with floating platform pilots now advancing to commercial scale.
- Grid-Forming Converter Technology:Synthetic inertia provision from offshore wind farms is converging with synchronous condenser retirement across continental European networks.
- Blade Recycling Infrastructure:End-of-life thermoset composite processing represents an emerging service vertical as early offshore installations reach decommissioning phase.
Industry Challenges
- Marine Survey Specialist Shortage:Geophysical and geotechnical vessel crews with North Sea experience command premium wages, extending early-stage project timelines.
- Type Certification Complexity:DNV-ST-0126 and IEC 61400-3-1 validation for floating platforms requires multi-year tank testing and full-scale prototype campaigns.
- Cross-Border Cable Routing:TenneT and National Grid interconnector coordination faces seabed jurisdiction conflicts between Dutch, German, and UK territorial claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Offshore Energy Market |
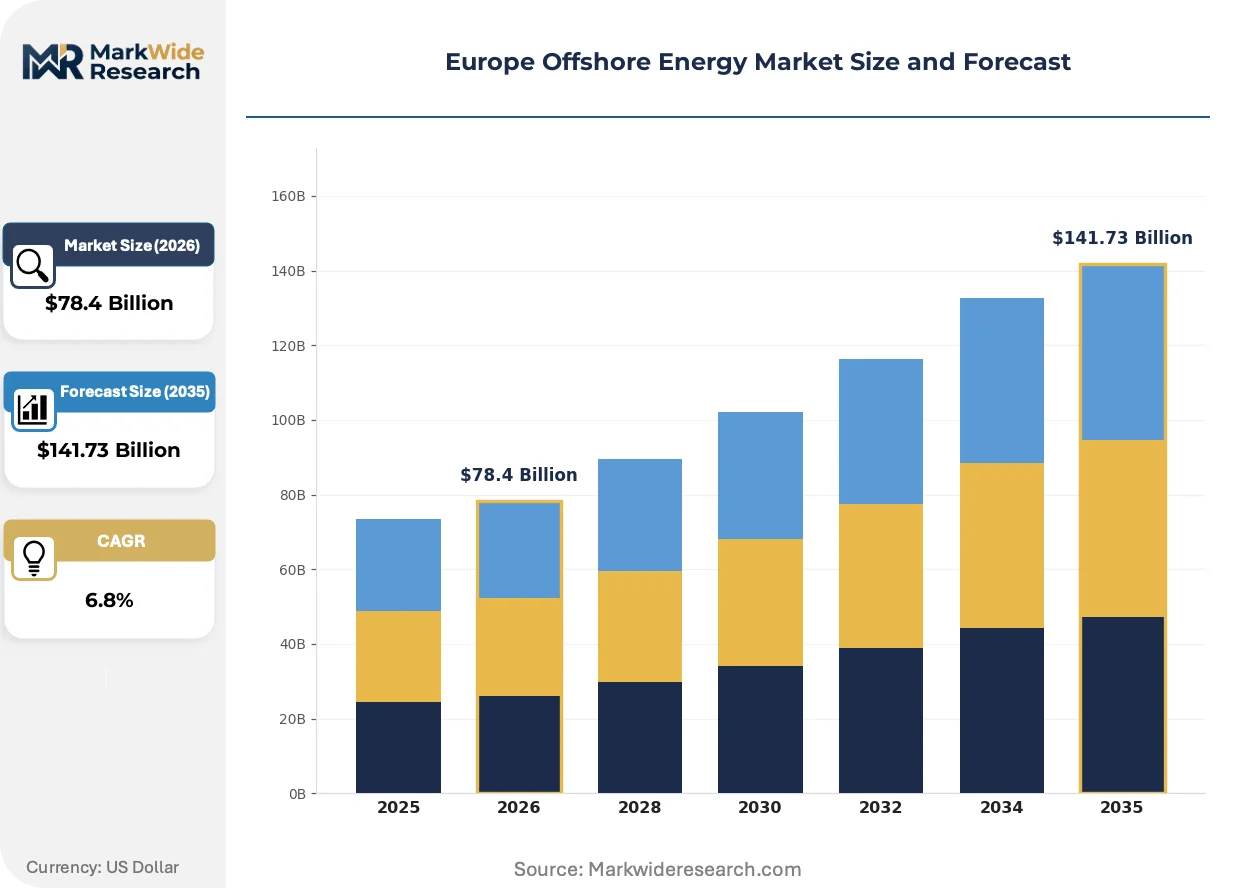
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $141.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Wind Farms, Oil Rigs, Aquaculture, Wave Energy Technology: Floating Platforms, Subsea Systems, Tidal Energy Systems, Hybrid Systems End User: Utilities, Independent Power Producers, Government Agencies, Research Institutions Installation: Fixed Structures, Floating Installations, Modular Systems, Cable Laying |
| Companies Covered | Ørsted AS, Siemens Gamesa Renewable Energy SA, Vestas Wind Systems AS, Iberdrola, RWE, E.ON SE, Nordex SE, Enel, Hydroquest, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Offshore Energy Market Shifts & Advancements
Technology maturation in floating foundations is compressing the cost gap with fixed-bottom systems, while regulatory pressure on supply chain carbon intensity is reshaping procurement specifications across the value chain.
Semi-submersible floating platforms are converging with tension-leg mooring systems to reduce steel tonnage per megawatt in depths exceeding 80 meters. Norwegian and Portuguese project pipelines are adopting these hybrid configurations for Atlantic sites with harsh wave climates. The structural consequence is a reduction in port assembly complexity, allowing smaller fabrication yards to compete for foundation contracts previously reserved for integrated heavy-industry groups.
REACH substance restrictions on anti-corrosion coatings are forcing reformulation of subsea protection systems across European waters. ECHA authorization requirements for chromium trioxide in splash-zone applications are elevating qualification costs for coating suppliers. The offshore wind sector is responding through accelerated qualification of thermally sprayed aluminum alternatives, particularly for monopile transition pieces in German and Danish projects.
Power purchase agreement structures are fragmenting across buyer sophistication levels, with utility offtakers demanding firming guarantees while corporate buyers accept higher merchant exposure for green hydrogen-linked supply. Danish and German procurement teams are unbundling construction risk from operational performance risk, creating separate contracting layers for EPC and O&M phases. The channel shift is most pronounced in Dutch waters, where pension fund direct investment is bypassing traditional utility intermediaries for minority project stakes.
Europe Offshore Energy Market Segmentation
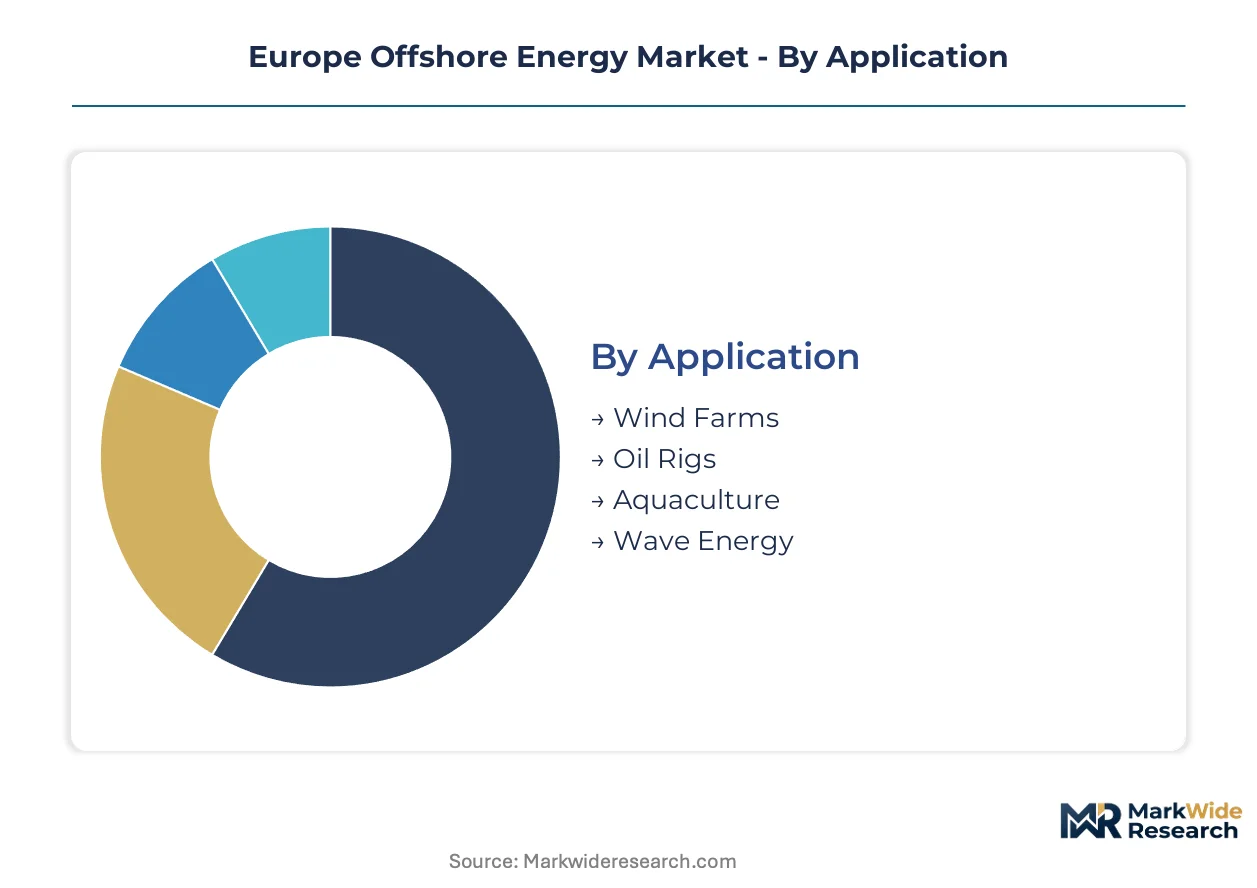
Segmentation in the Europe Offshore Energy Market reveals how capital allocation, regulatory exposure, and technology maturity diverge across deployment contexts. Developers, suppliers, and investors use these boundaries to calibrate risk-return profiles against specific site conditions and offtake structures.
Application:
Supply concentration tilts heavily toward wind farm development, with fabrication yards in Esbjerg, Rotterdam, and Bremerhaven prioritizing turbine foundation contracts over alternative marine energy formats.
- Wind Farms:Fixed-bottom monopiles dominate installations under 60 meters depth, while floating semi-submersibles unlock deeper Atlantic and Mediterranean lease zones. Danish and German waters concentrate procurement volume as Ørsted and RWE advance multi-gigawatt pipelines. The EU Green Deal's 2030 capacity targets tighten turbine supply competition among Northern European ports.
- Oil Rigs:Decommissioning obligations under OSPAR Convention protocols are shifting capital toward platform removal and site restoration. Norwegian North Sea operators face accelerated well abandonment timelines. Electrification of existing production infrastructure creates hybrid demand for offshore substation components.
- Aquaculture:Offshore fish farming installations in Scottish and Norwegian waters require integrated power systems for feeding and monitoring equipment. Environmental licensing under national marine spatial plans limits site expansion.
- Wave Energy:Oscillating water column and point absorber technologies remain at pilot scale, with Portuguese and Scottish test sites hosting demonstration units. Capital intensity and device reliability constraints suppress commercial deployment.
Today's leader: Wind Farms. Tomorrow's challenger: Oil Rigs (via electrification and decommissioning service integration).
Technology:
Cost tier differentiation separates mature foundation systems from emerging platform architectures, with early-mover premiums persisting in floating and hybrid configurations.
- Floating Platforms:Semi-submersible designs with tension-leg mooring systems reduce steel tonnage for depths exceeding 80 meters. Norwegian Equinor and Portuguese WindFloat Atlantic deployments validate commercial scalability. Port assembly simplification allows smaller fabrication yards to compete for foundation contracts.
- Subsea Systems:Cable protection systems, foundation transition pieces, and inter-array grid infrastructure command premium engineering margins. Copper price volatility and rare earth supply concentration shape procurement risk profiles.
- Tidal Energy Systems:Horizontal axis turbines in Pentland Firth and Alderney Race sites exploit predictable current velocities. Device maintenance access and biofouling management constrain operational economics.
- Hybrid Systems:Co-located wind and hydrogen production platforms integrate electrolyzers at offshore substations. Dutch and German project pipelines test technical configurations for green hydrogen offtake certainty.
Floating Platforms command premium pricing today. Hybrid Systems are climbing the fastest as electrolyzer integration matures.
End User:
Volume concentration flows through utility balance sheets, though capital structure innovation is fragmenting traditional sponsor dominance.
- Utilities:Integrated development models spanning development, construction, and operations sustain cost discipline in deeper-water zones. Danish Ørsted and German RWE anchor procurement through long-term turbine supply agreements.
- Independent Power Producers:Project finance structures with pension fund and infrastructure equity participation bypass traditional utility intermediaries. Dutch waters host the most pronounced direct investment channel shift.
- Government Agencies:National seabed lease authorities in Denmark, Germany, and the Netherlands enforce divergent auction formats. Subsidy design and permitting timeline compression vary by jurisdiction.
- Research Institutions:Test site operation and device certification support falls to organizations like the European Marine Energy Centre in Orkney and Wave Energy Scotland. Public funding dependence limits scale.
Utilities retain procurement dominance. Independent Power Producers are gaining share fastest through capital structure innovation.
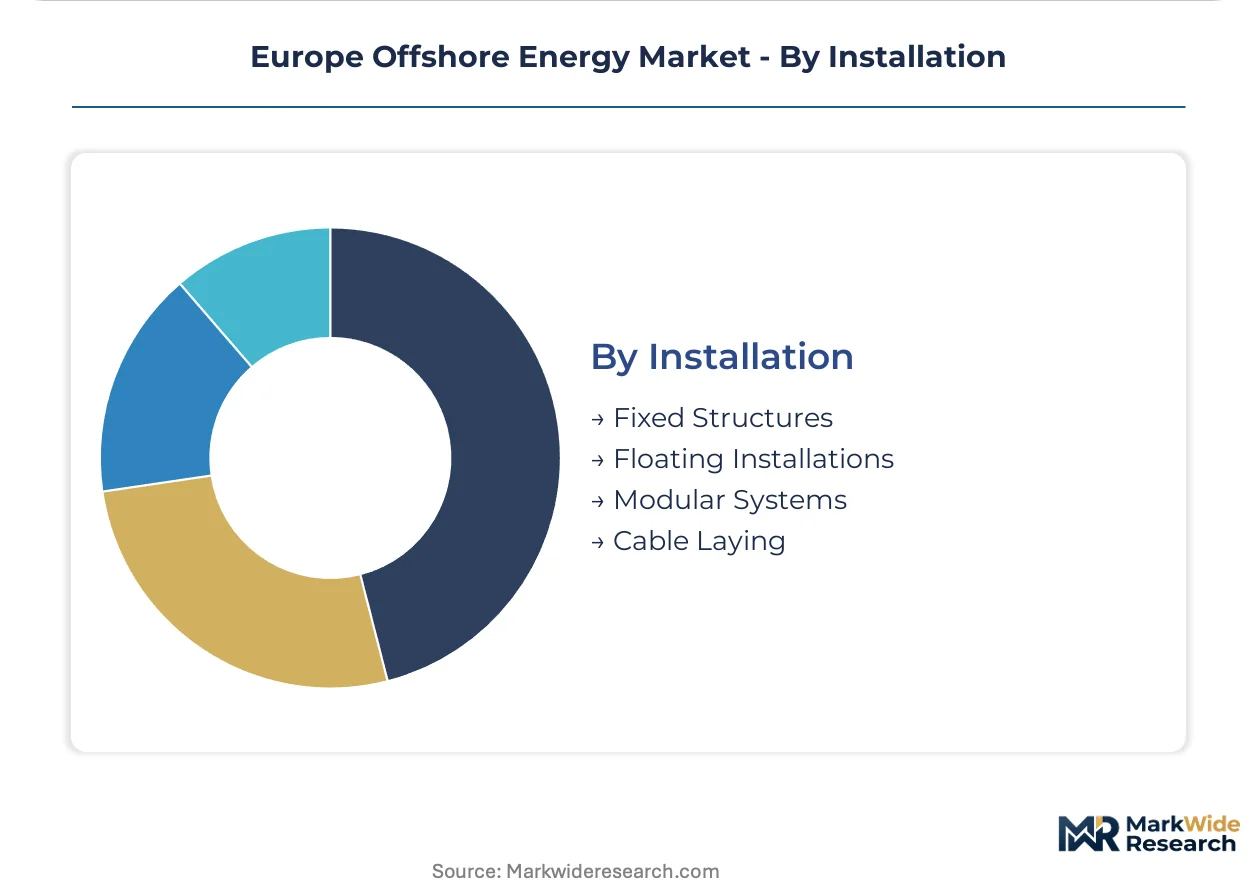
Installation:
Margin distribution favors specialized vessel operators and heavy-lift contractors, with installation method selection determining project schedule risk.
- Fixed Structures:Jack-up vessel dependency creates bottlenecks for North Sea construction windows. Korean and Chinese yard concentration in the global fleet elevates day-rate volatility.
- Floating Installations:Tow-out and dynamic positioning methods compress offshore construction duration. Smaller assembly ports compete through reduced quayside complexity.
- Modular Systems:Pre-commissioned substation topsides and turbine components reduce offshore integration labor. Rotterdam and Bremerhaven fabrication hubs scale heavy-lift capacity.
- Cable Laying:Inter-array and export cable installation requires specialized plough and trenching vessels. Cross-border routing coordination between TenneT and National Grid faces territorial jurisdiction conflicts.
Fixed Structures anchor current installation spend. Floating Installations represent the steepest expansion trajectory as water depth constraints relax.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Marine engineering talent clusters along the North Sea littoral, with Danish, German, and Dutch port cities anchoring the continent's offshore energy workforce concentration.
Germany
Zero-subsidy tender formats and Baltic Sea lease rounds drive developer capital allocation toward merchant price exposure management. The Federal Maritime and Hydrographic Agency enforces streamlined permitting under the WindSeeG framework. Bremerhaven fabrication yards scale heavy-lift quayside capacity for 15+ megawatt turbine components.
United Kingdom
Round 4 and 5 seabed auctions unlock Celtic Sea floating wind zones alongside established North Sea fixed-bottom pipelines. The Offshore Petroleum Regulator for Environment and Decommissioning coordinates OSPAR Convention compliance for platform removal obligations. Aberdeen and Great Yarmouth service hubs concentrate decommissioning and electrification engineering crews.
Netherlands
SDE++ subsidy rounds and Hollandse Kust lease tranches attract pension fund direct investment bypassing traditional utility intermediaries. The Netherlands Enterprise Agency administers offshore wind tender procedures with ecological screening requirements. Rotterdam port infrastructure modernizes to handle floating platform assembly and tow-out operations.
Denmark
Energy island concepts and Kriegers Flak interconnector expansion concentrate procurement volume through integrated utility development models. The Danish Energy Agency compresses permitting timelines for cross-border offshore clusters. Esbjerg fabrication hubs anchor turbine supply chain logistics for Baltic and North Sea deployments.
Norway
Equinor-led floating platform pilots validate commercial scalability for Atlantic depths exceeding 80 meters. The Norwegian Petroleum Directorate regulates electrification of existing production infrastructure alongside new renewable lease awards. Stavanger and Bergen engineering clusters supply tension-leg mooring system design expertise.
Europe Offshore Energy Market Competitive Landscape
The competitive structure tilts toward integrated utilities with full lifecycle development capabilities. Danish and German energy majors anchor procurement volume through multi-gigawatt pipelines, while turbine OEMs compete on modular platform architectures and installation efficiency. Three archetypes dominate: vertically integrated developers controlling project origination through operations, specialized turbine manufacturers scaling Northern European port supply chains, and port-centric fabrication consortia assembling foundation and substation components. Competitive moves concentrate on long-term turbine supply agreements and floating platform technology licensing.
Among integrated developers, Ørsted AS and RWE exemplify the full-lifecycle archetype spanning development, construction, and operations. Siemens Gamesa Renewable Energy SA and Vestas Wind Systems AS occupy positions within the turbine supply tier, with the former anchoring manufacturing scale and the latter competing on modular system design. Iberdrola represents the Southern European utility vector with Atlantic basin expansion exposure.
| Leading Market Players |
|---|
| Ørsted AS |
| Siemens Gamesa Renewable Energy SA |
| Vestas Wind Systems AS |
| Iberdrola |
| RWE |
| E.ON SE |
| Nordex SE |
| Enel |
| Hydroquest |
| Others |
Supply & Pricing Matrix
Floating platform assembly methods are compressing steel tonnage requirements and redistributing fabrication contracts toward smaller Baltic and North Sea ports previously excluded from foundation supply. This production-method transition simultaneously erodes integrated heavy-industry pricing premiums and fragments procurement leverage across dispersed quayside operators.
Pricing Analysis
Bundled EPC contracts covering turbine supply through grid connection command premium margins against unbundled component procurement. Price differentiation rests on installation vessel availability windows and foundation certification tier under DNV-ST-0126 protocols. Cost compression in floating platform tiers is intensifying as Norwegian and Portuguese deployments validate commercial scalability. Corporate offtakers with green hydrogen linkage show lowest price sensitivity; merchant-exposed developers face acute margin pressure.
Supply Chain Analysis
Heavy-lift freight costs from Korean and Chinese fabrication yards to North Sea installation sites amplify total project economics beyond component base pricing. Supply concentration centers on China for rare earth processing, South Korea for jack-up vessel construction, and Northern European ports for turbine assembly. Copper cable manufacturing draws from Chilean concentrate and Chinese smelting capacity. Single-source vulnerability in neodymium magnet supply creates procurement risk. Distribution runs through utility-led development consortia with pension fund co-investment layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REPowerEU timeline compression and EU Green Deal carbon-accounting mandates compound demand visibility for compliant developers.
For Market Incumbents: Acquire specialized marine survey vessel crews and geotechnical certification capabilities to preempt talent scarcity bottlenecks. Secure long-term turbine supply agreements with Siemens Gamesa or Vestas before port capacity constraints tighten. Floating platform technology licensing from Equinor validates commercial scalability and anchors defensive positioning against emerging pure-play developers. For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms bypass traditional EPC intermediary markups in Dutch and German waters. Target Iberian Atlantic floating wind zones where seabed geology excludes established fixed-bottom incumbents. White-space exists in blade recycling infrastructure as early North Sea installations reach decommissioning phase. Lead with electrolyzer co-location expertise to differentiate green hydrogen-linked offtake proposals. For Investors and Strategic Acquirers: Valuations sit cheapest among port-centric fabrication consortia lacking integrated development capabilities but holding heavy-lift quayside capacity in Rotterdam, Esbjerg, and Bremerhaven. Five-to-ten year viability favors hybrid system specialists with electrolyzer integration pipelines over pure turbine OEM exposure. Monitor German zero-subsidy tender participation rates as inflection signal for merchant price risk appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Floating Platform Technology Licensing | Equinor-validated semi-submersible designs unlock Atlantic depths exceeding 80 meters for new entrants. |
| Green Hydrogen Co-location Agreement | Electrolyzer integration at Dutch and German offshore substations creates offtake certainty against merchant exposure. |
| Port Infrastructure Modernization | Rotterdam and Bremerhaven heavy-lift quayside scaling enables 15+ megawatt turbine component handling. |
| Marine Survey Capability Acquisition | Geophysical and geotechnical vessel crew contracts preempt specialist wage inflation in North Sea markets. |
| Blade Recycling Infrastructure Buildout | Thermoset composite processing capacity addresses end-of-life obligations for Danish and German decommissioning pipelines. |
Research Methodology
Coverage spans Denmark, Germany, the Netherlands, the United Kingdom, and Norway, with primary inputs from each regulatory jurisdiction. The research combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators with secondary validation against EIA data, IEA reports, FERC filings, and project development databases. Bottom-up installation capacity tallies triangulate against top-down regulatory target assessments.
Rate-of-change decomposition separates volume drivers from price evolution across the projection horizon. Segmentation dimensions modeled include technology type, water depth tier, end-user capital structure, and national regulatory framework. CAGRs derive from capacity deployment schedules against auction award timelines. Forecast inputs incorporate jack-up vessel fleet utilization rates and copper price trajectory assumptions.
The model assumes a particular technology adoption path; alternative pathways for tension-leg mooring systems would alter the outlook for port assembly complexity and steel tonnage economics. Forecasts reflect assumptions about REPowerEU permitting timeline compression and seabed lease auction participation rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
India Oil and Gas Downstream Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Middle East Offshore MRO Market
Offshore Oil and Gas
Thailand Oil and Gas Downstream Market
Offshore Oil and Gas
Floating Production Storage and Offloading Market
Offshore Oil and Gas
Nigeria Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Oil and Gas Communications Market
Offshore Oil and Gas
West Africa Oil and Gas Upstream Market
Offshore Oil and Gas
Egypt Oil and Gas Upstream Market
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Floating Production System Sales Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Oil and Gas Fishing Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
Asia-Pacific Floating Offshore Wind Power Market