
 Indonesia Oil and Gas Downstream Market | 2026-2036
Indonesia Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Oil and Gas Downstream Market Foresight
Modular fuel-service bundling is broadening buyer choice across Indonesia's downstream sector. PT Pertamina leverages its integrated retail-storage network to anchor national distribution. Shell plc competes through specialized premium gasoline formulations in urban centers. Chandra Asri differentiates via captive petrochemical feedstock supply to plastics manufacturers.
Indonesia Oil and Gas Downstream encompasses refining, processing, storage, and distribution of crude oil and natural gas into finished fuels and petrochemical products. Facilities operate atmospheric distillation units processing up to 150,000 barrels per day, yielding gasoline, diesel, jet fuel, and liquefied petroleum gas for transportation and industrial combustion. Gasoline and diesel product types lead volume throughput due to fleet fuel demand, while jet fuel represents the fastest-growing category as aviation traffic recovers across archipelago routes. Storage and terminal infrastructure commands disproportionate margin pools given Indonesia's island geography and import dependency for refined products.
Indonesia's Ministry of Energy and Mineral Resources enforces biodiesel blending mandates through B20-B35 regulations, directly altering refinery output specifications and import requirements. BIS-equivalent national standards and PLI scheme incentives for domestic refining shape capital deployment toward capacity expansion. Stakeholders must monitor regulatory blending escalation timelines and archipelago logistics bottlenecks to align storage investments with demand geography.
Market Dynamics
Indonesia's B20-B35 biodiesel mandate is compressing conventional diesel margins while forcing refinery reconfiguration toward co-processing units. Storage and terminal operators capture disproportionate value as archipelago logistics constraints intensify.
Growth Catalysts
- Biodiesel Blending Escalation:Indonesia's Ministry of Energy and Mineral Resources enforces progressive B20-B35 mandates, creating guaranteed offtake for domestic palm oil derivatives and requiring refinery hydrotreater investments.
- Aviation Recovery:Jet fuel demand across archipelago routes is accelerating as Garuda Indonesia and low-cost carriers expand fleet utilization, outpacing gasoline growth rates.
- Java Manufacturing Corridor:Industrial diesel consumption in Bekasi, Karawang, and Cilegon manufacturing zones anchors product demand concentration for integrated logistics providers.
Market Restraints
- Crude Import Dependency:Indonesia's refining capacity deficit forces sustained middle distillate imports from Singapore and Middle Eastern suppliers, exposing margins to freight rate volatility and currency fluctuation.
- Feedstock Competition:Palm oil price swings between food, oleochemical, and biodiesel applications create margin instability for fatty acid methyl ester producers serving the blending mandate.
- Refinery Complexity Gap:Existing Cilacap and Balikpapan facilities lack deep conversion capacity, yielding high fuel oil output rather than premium gasoline and diesel.
Strategic Opportunities
- Sumatra Petrochemical Integration:Cilegon and Merak industrial zones offer captive naphtha cracking potential for polyethylene and polypropylene producers seeking feedstock security.
- Eastern Indonesia Storage Gap:Sulawesi, Maluku, and Papua remain critically undersupplied with product terminals, rewarding early-mover investments in floating storage units.
- Renewable Diesel Co-processing:Hydrotreated vegetable oil compatibility with existing refinery infrastructure enables compliance with B35 mandates without standalone biorefinery capex.
Industry Challenges
- Specialized Technician Scarcity:Hydrotreater and delayed coker operations require process engineers with hydrocracking experience that Pertamina's training pipeline struggles to replenish.
- Legacy Terminal Automation:Tanjung Priok and Surabaya storage facilities operate on siloed inventory systems that resist integration with modern supply chain planning platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Oil and Gas Downstream Market |
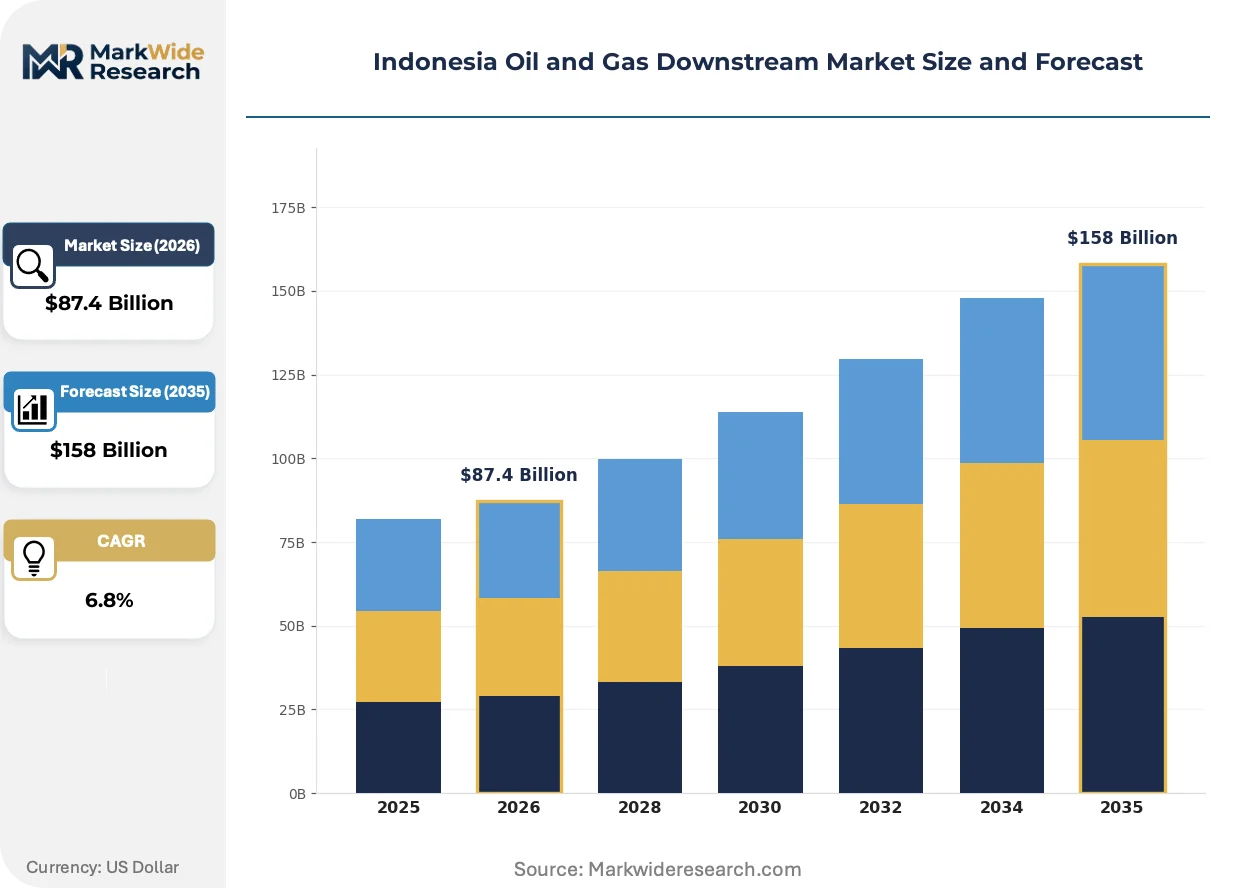
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline, Diesel, Jet Fuel, Liquefied Petroleum Gas End User: Transportation, Industrial, Residential, Commercial Distribution Channel: Retail, Wholesale, Direct Supply, Online Sales Technology: Refining, Blending, Treatment, Storage |
| Companies Covered | ExxonMobil, Chevron, PT Pertamina, ConocoPhillips, PETRONAS, TotalEnergies SE, BP plc, Chandra Asri, Shell plc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Oil and Gas Downstream Market Shifts & Advancements
Digital twin technology and renewable feedstock co-processing are reshaping how Indonesian refineries optimize yield structures and regulatory compliance. Terminal operators simultaneously pursue automation and capacity expansion to capture margin pools.
Advanced process control systems using real-time optimization algorithms are integrating with Pertamina's existing refinery distributed control systems. Operations teams at Cilacap and Balongan facilities deploy these platforms to maximize middle distillate yields during crude slate transitions. The technology is integrating planning and execution workflows that previously operated on monthly cycles, compressing response time to Singapore spot market movements.
Indonesia's Ministry of Energy and Mineral Resources enforces B35 biodiesel mandates through downstream blending obligations and domestic market obligation regulations. Refiners must now certify fatty acid methyl ester traceability from plantation to pump, adding laboratory and documentation overhead. Small-scale distributors in outer island provinces face compliance cost burdens that favor consolidation toward integrated storage-terminal operators with in-house testing capabilities.
Industrial buyers in Java's manufacturing zones are consolidating fuel procurement through annual tender contracts rather than spot market purchases. Large textile and ceramics producers in Bandung and Sidoarjo now bundle diesel, LPG, and lubricant requirements into single-source agreements with logistics providers. This concentration is visible across Bekasi industrial parks where manufacturers prioritize supply security over price optimization given inventory carrying cost constraints.
Indonesia Oil and Gas Downstream Market Segmentation
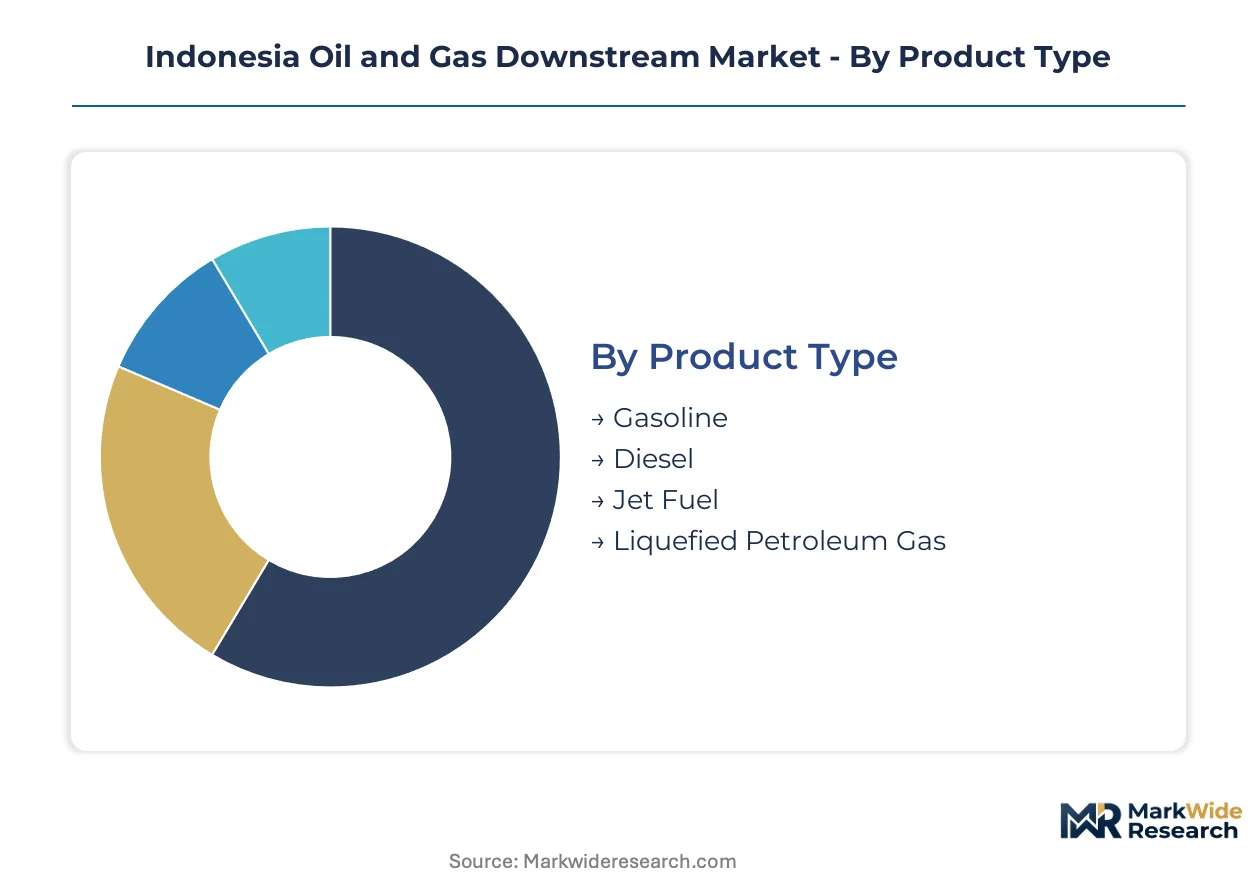
Segmentation in Indonesia's downstream oil and gas sector reveals how product flows, customer requirements, and infrastructure investments align with archipelago geography and regulatory mandates. Understanding these divisions exposes where margin pools concentrate and where capital deployment faces structural constraints.
Product Type:
Standalone fuel products dominate volume throughput, while blended formulations and specialized grades embed within integrated supply chains serving specific industrial clusters.
- Gasoline:RON 88-92 formulations processed through catalytic reforming units supply private vehicle fleets across Java's urban corridors. Demand concentrates in Jakarta, Surabaya, and Bandung metropolitan zones where motorcycle and passenger car density drives retail throughput.
- Diesel:High-speed diesel with sulfur specifications down to 50 ppm serves commercial trucking and captive power generation for textile manufacturers in Bekasi industrial parks. B20-B35 blending mandates force fatty acid methyl ester integration, compressing conventional diesel margins while creating guaranteed offtake for domestic palm oil derivatives.
- Jet Fuel:Jet A-1 kerosene specifications for turbine combustion supply Garuda Indonesia and low-cost carriers operating archipelago routes.
- Liquefied Petroleum Gas:Propane-butane mixtures distributed in pressurized cylinders reach residential cooking markets in outer island provinces lacking pipeline infrastructure.
Gasoline leads volumes today; jet fuel is gaining share fastest.
End User:
Cost tier differentiation separates high-volume contract buyers from fragmented spot purchasers across the customer base.
- Transportation:Fleet operators and individual motorists consuming gasoline, diesel, and jet fuel through retail networks and direct aviation fueling contracts.
- Industrial:Textile, ceramics, and petrochemical manufacturers in Cilegon and Karawang zones purchasing diesel and naphtha through annual tender agreements bundling fuel, lubricant, and logistics services.
- Residential:Household consumers relying on subsidized LPG canisters distributed through Pertamina's agent network in Sulawesi and Papua.
- Commercial:Hotels, hospitals, and retail chains procuring diesel for backup generators and LPG for kitchen operations.
Industrial buyers command premium pricing power; residential segments depend on subsidy mechanisms.
Distribution Channel:
Volume concentration favors wholesale and direct supply arrangements, while retail and emerging digital channels serve fragmented demand pockets.
- Retail:Pertamina's SPBU network and Shell-branded stations dispensing gasoline and diesel to individual motorists through island-wide forecourt infrastructure.
- Wholesale:Terminal-to-terminal transfers and bulk deliveries to industrial zones via Pertamina's integrated storage and vessel fleet.
- Direct Supply:Pipeline connections and dedicated trucking contracts serving Cilegon petrochemical complexes and Java manufacturing corridors.
- Online Sales:Emerging digital platforms for LPG cylinder ordering and commercial fuel procurement in urban centers.
Wholesale channels anchor revenue stability; direct supply contracts are expanding most quickly.
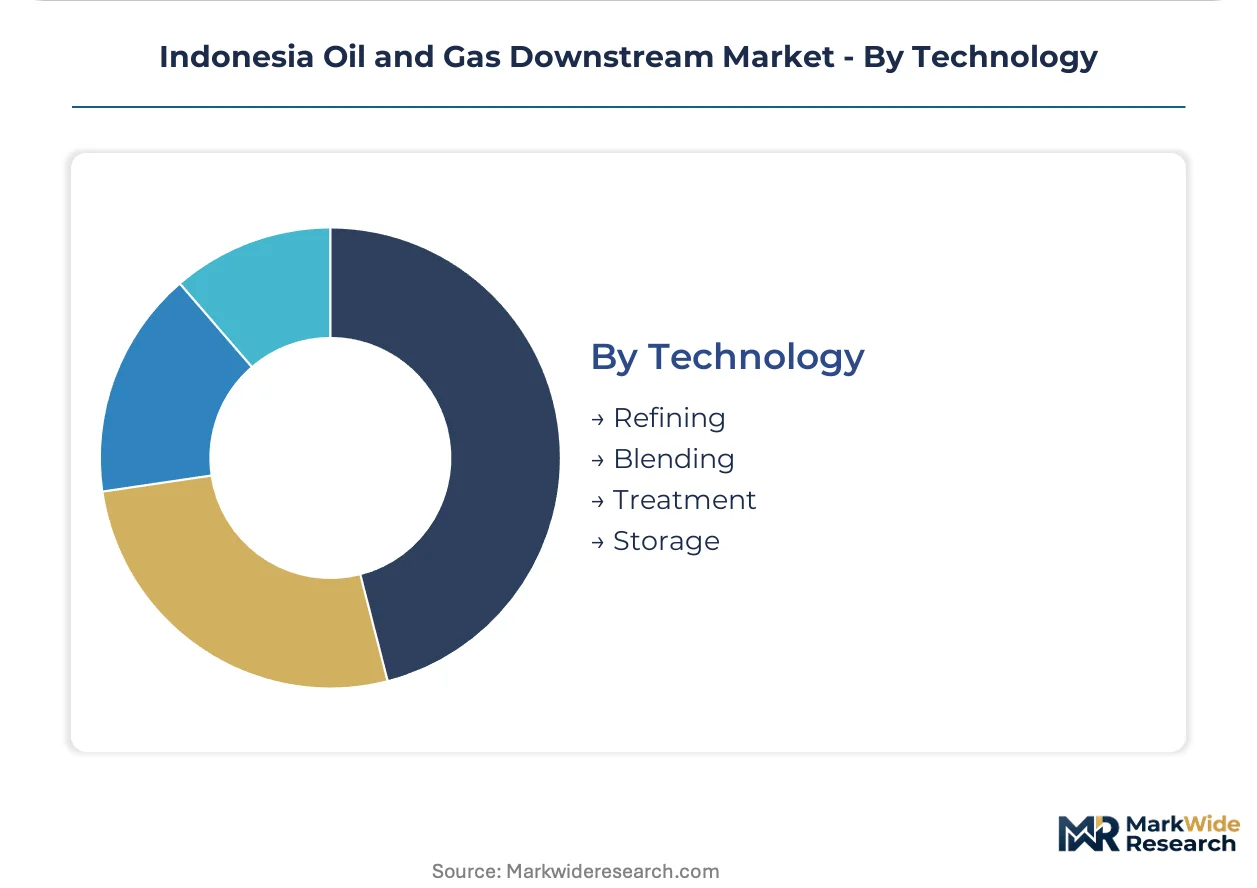
Technology:
Maturity gradients separate established refining infrastructure from advanced treatment and storage investments required by biodiesel mandates.
- Refining:Atmospheric distillation and catalytic cracking units at Cilacap and Balikpapan facilities processing up to 150,000 barrels per day of imported crude.
- Blending:Biodiesel mixing operations integrating fatty acid methyl ester with diesel at storage terminals to meet B20-B35 specifications.
- Treatment:Hydrotreater and desulfurization units upgrading product quality to national standards and reducing sulfur content.
- Storage:Floating roof tanks and terminal infrastructure across Tanjung Priok, Surabaya, and emerging Eastern Indonesia locations.
Refining capacity dominates capital deployment; storage technology is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's downstream oil and gas sector traces its modern foundations to state-led infrastructure buildouts during the 1970s oil boom, when Pertamina established refining and distribution networks across the archipelago. These legacy assets now anchor product flows from Java's industrial heartland to outer island provinces.
Java
Java commands the majority of national fuel consumption through Jakarta's metropolitan sprawl and Surabaya's manufacturing zones. The Ministry of Energy and Mineral Resources enforces B20-B35 biodiesel blending mandates that reshape refinery output specifications for this dense corridor. Cilegon's petrochemical complexes and Bekasi's textile parks absorb diesel and naphtha through pipeline-connected supply agreements.
Sumatra
Sumatra's Riau and North Sumatra provinces host palm oil plantations that feed fatty acid methyl ester production for national biodiesel blending. Pertamina's Dumai refinery processes crude from nearby Duri and Minas fields under domestic market obligation regulations. Medan's industrial estates and Belawan port infrastructure concentrate storage and distribution capacity for northern archipelago supply.
Kalimantan
East Kalimantan's Balikpapan refinery represents the largest conversion facility outside Java, processing imported crude for Borneo and Sulawesi markets. The facility struggles with complexity limitations that yield high fuel oil output rather than premium gasoline. Samarinda's mining operations and palm oil processing plants anchor diesel demand for captive power generation.
Sulawesi
Sulawesi remains critically undersupplied with product terminals despite Makassar's emergence as an eastern logistics hub. The island's nickel processing smelters consume diesel for electricity generation as grid connectivity lags industrial expansion. Bitung and Kendari port developments attract floating storage investment to close supply gaps.
Papua
Papua's remote highland and coastal communities depend on subsidized LPG canister distribution through Pertamina's agent network. The province lacks pipeline infrastructure and relies on coastal tanker deliveries from Sorong and Jayapura terminals. Grasberg mining operations represent the single largest diesel offtake for heavy equipment and power generation.
Indonesia Oil and Gas Downstream Market Competitive Landscape
The competitive structure tilts toward state-anchored integrated operators with captive infrastructure and international majors competing through specialized product formulations. PT Pertamina's control of terminal networks and retail distribution creates structural advantages for domestic supply security. Two archetypes dominate: vertically integrated national champions with refinery-to-pump control, and international oil companies leveraging premium branding and technical formulations. Capacity expansion and strategic partnerships constitute the primary competitive moves as players position for biodiesel mandate compliance and eastern archipelago supply gaps.
Among state-linked integrated operators, PT Pertamina anchors national distribution through its SPBU retail network and Tanjung Priok storage terminals. International majors including Shell plc and TotalEnergies SE occupy positions in premium gasoline and specialized lubricant segments, competing through formulation technology rather than volume scale. Chandra Asri represents the petrochemical specialization archetype, leveraging naphtha cracking capacity for captive plastics manufacturing feedstock supply.
| Leading Market Players |
|---|
| ExxonMobil |
| Chevron |
| PT Pertamina |
| ConocoPhillips |
| PETRONAS |
| TotalEnergies SE |
| BP plc |
| Chandra Asri |
| Shell plc |
| Others |
Supply & Pricing Matrix
Industrial diesel procurement consolidation across Java's manufacturing corridor is compressing spot market premiums and forcing suppliers toward annual contract structures with embedded logistics services. This buyer-driven shift toward bundled fuel-procurement agreements is reshaping how refiners and terminal operators structure pricing and allocate storage capacity.
Pricing Analysis
Contract-based long-term offtake dominates transaction structures, with pricing stratifying across premium, standard, and economy tiers differentiated by sulfur content certification and bundled logistics scope. Price differentiation hinges on B20-B35 biodiesel blend ratios and terminal automation levels. Cost compression in standard-grade diesel is intensifying because palm oil feedstock volatility passes through to fatty acid methyl ester costs. Industrial buyers with annual tender volumes exhibit lowest price sensitivity; fragmented outer-island distributors show highest.
Supply Chain Analysis
Crude supply rests on Middle Eastern and Singaporean refinery output, with high-sulfur fuel oil and middle distillates flowing through archipelago tanker routes. Key inputs include imported crude slate, palm oil derivatives for biodiesel blending, and hydrogen for hydrotreater units. Single-source vulnerability concentrates in Singapore's product storage and blending hub, where regional supply disruptions cascade through Indonesian terminal networks. Distribution runs through Pertamina's integrated vessel fleet and Tanjung Priok storage terminals to wholesale and direct-supply channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in storage-terminal automation and renewable diesel co-processing capabilities, where biodiesel mandate compliance creates premium-tier pricing power for early movers.
For Market Incumbents: Acquire floating storage units in Eastern Indonesia to preempt supply gaps in Sulawesi and Papua. Secure backward integration into palm oil fatty acid methyl ester production to insulate margins from feedstock price swings. Hydrotreater capacity scarcity at existing Cilacap and Balikpapan facilities creates vulnerability to B35 mandate timelines. For New Entrants and Emerging Players: Digital fuel-procurement platforms for industrial buyers in Bandung and Sidoarjo manufacturing zones offer lowest barrier to entry. Target undersupplied LPG cylinder distribution in Maluku and Papua through agent-network partnerships. White-space exists in jet fuel storage at secondary airports as aviation traffic recovers across archipelago routes. For Investors and Strategic Acquirers: Asymmetric upside sits with terminal operators possessing Eastern Indonesia geographic positioning and in-house biodiesel blending certification. Long-term viability favors assets with hydrotreater retrofit compatibility and captive industrial offtake agreements. Watch for Ministry of Energy and Mineral Resources announcements on B35-to-B40 mandate escalation as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Balikpapan refinery complexity upgrades reduce fuel oil yield and improve gasoline output. |
| Backward Integration | Palm oil plantation partnerships secure fatty acid methyl ester supply for B35 blending mandates. |
| Long-term Supply Agreement | Annual tender contracts with Bekasi textile manufacturers lock in diesel volume commitments. |
| Joint Venture | International oil company partnerships with Pertamina accelerate Eastern Indonesia terminal development. |
| Green Certification Program | Hydrotreated vegetable oil co-processing enables B35 compliance without standalone biorefinery investment. |
Research Methodology
Coverage spans Java, Sumatra, Kalimantan, Sulawesi, and Papua, with primary inputs from each region combined with secondary validation. Refinery operations managers, terminal logistics coordinators, industrial procurement leads at textile and ceramics manufacturers, and Ministry of Energy and Mineral Resources officials contributed interview data. Secondary sources include Pertamina annual disclosures, BPS trade statistics, customs import records, and IEA Southeast Asia energy outlooks. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Granularity-level modeling disaggregated projections by product type, end-user segment, distribution channel, and regional demand cluster across the analysis window. Segmentation dimensions included gasoline, diesel, jet fuel, and LPG product categories; transportation, industrial, residential, and commercial end-use sectors; retail, wholesale, direct supply, and online sales channels; and Java, Sumatra, Kalimantan, Sulawesi, and Papua geographies. CAGRs derived from regression analysis against crude price assumptions, biodiesel mandate phase-in schedules, and aviation traffic recovery trajectories. Forecast inputs incorporated refinery utilization rates and terminal capacity expansion pipelines.
The model assumes a particular technology adoption path; alternative pathways for renewable diesel co-processing would alter the outlook. Forecasts reflect assumptions on biodiesel blend ratio enforcement, palm oil price corridors, and refinery upgrade completion schedules. Regulatory acceleration, feedstock supply disruptions, or currency volatility warrant forecast revision. A small set of named triggers—B40 mandate announcements, Balikpapan complexity project milestones, and Eastern Indonesia storage investment commitments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market
Offshore Oil and Gas
Europe Offshore Energy Market
Offshore Oil and Gas
North Sea Offshore Decommissioning Market
Offshore Oil and Gas
North America FLNG Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Natural Oil and Gas Midstream Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Europe Oil and Gas Separation Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market