
 East Africa Oil and Gas Upstream Market | 2026-2036
East Africa Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
East Africa Oil and Gas Upstream Market Foresight
Integrated production-sharing contract structures are recalibrating how upstream value gets captured across East African acreage. TotalEnergies SE leverages its LNG development expertise to anchor mega-project economics in Mozambique's deepwater blocks. Eni SpA specializes in fast-track subsea tieback architectures that compress time-to-first-gas timelines. China National Petroleum Corporation extends its capital deployment through bilateral infrastructure financing tied to offtake agreements.
East Africa oil and gas upstream encompasses the search, drilling, and extraction of crude oil and natural gas reserves from geological formations beneath the region's continental shelf and onshore rift basins, typically involving well depths ranging from 1,500 to 3,500 meters and reservoir temperatures exceeding 120°C in deepwater settings. The primary purpose is to supply feedstock for domestic power generation, regional LNG export, and nascent petrochemical industrialization. Exploration services command premium pricing due to frontier basin uncertainty and limited 3D seismic coverage across the Somali Plate. Offshore technology, particularly floating LNG and subsea processing, attracts disproportionate capital allocation as operators chase gas-condensate discoveries in ultra-deepwater blocks. National oil companies represent the fastest-growing end-user category as Kenya, Tanzania, and Mozambique restructure state equity participation models.
Tanzania's Petroleum Act and Mozambique's petroleum taxation framework, alongside the Extractive Industries Transparency Initiative standards adopted regionally, shape fiscal terms and local content obligations that directly alter project sanction timelines. Environmental impact assessment requirements enforced by national petroleum regulators and the Nairobi Convention Secretariat constrain drilling seasonality and marine protection protocols. Stakeholders must weigh portfolio concentration risk against the pace of pipeline and LNG liquefaction infrastructure commitments that will determine commercialization viability.
Market Dynamics
Integrated production-sharing contract structures are recalibrating how upstream value gets captured across East African acreage, with fiscal terms and local content obligations directly altering project sanction timelines.
Growth Catalysts
- Exploration licensing reforms:Tanzania's Petroleum Act and Mozambique's petroleum taxation framework are accelerating lease-round participation and attracting new capital deployment.
- Floating LNG technology:Ultra-deepwater gas-condensate discoveries in the Rovuma Basin corridor are unlocking commercialization pathways previously deemed uneconomic.
- Power generation utilities:Natural gas offtake agreements from offshore discoveries are scaling across Kenya, Tanzania, and Mozambique as baseload electricity demand expands.
Market Restraints
- Frontier basin uncertainty:Limited 3D seismic coverage across the Somali Plate inflates exploration risk premiums and extends appraisal timelines.
- Environmental impact assessment requirements:The Nairobi Convention Secretariat enforces marine protection protocols that constrain drilling seasonality and operational windows.
- LNG liquefaction infrastructure gaps:Pipeline and liquefaction facility commitments remain insufficient to match discovery scale, creating commercialization bottlenecks.
Strategic Opportunities
- Kenya's nascent petrochemical industrialization:State equity participation model restructuring is creating entry points for downstream integration investments.
- Extractive Industries Transparency Initiative adoption:Regional EITI standards compliance is improving capital access terms for compliant operators.
- Subsea tieback architectures:Fast-track deployment models are compressing time-to-first-gas timelines and improving project economics.
Industry Challenges
- Deepwater drilling technical capacity:Reservoir temperatures exceeding 120°C in ultra-deepwater blocks require specialized well completion expertise that remains scarce regionally.
- Local content obligation compliance:Tanzania's Petroleum Act mandates are forcing rapid supply chain reconfiguration without established vendor bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | East Africa Oil and Gas Upstream Market |
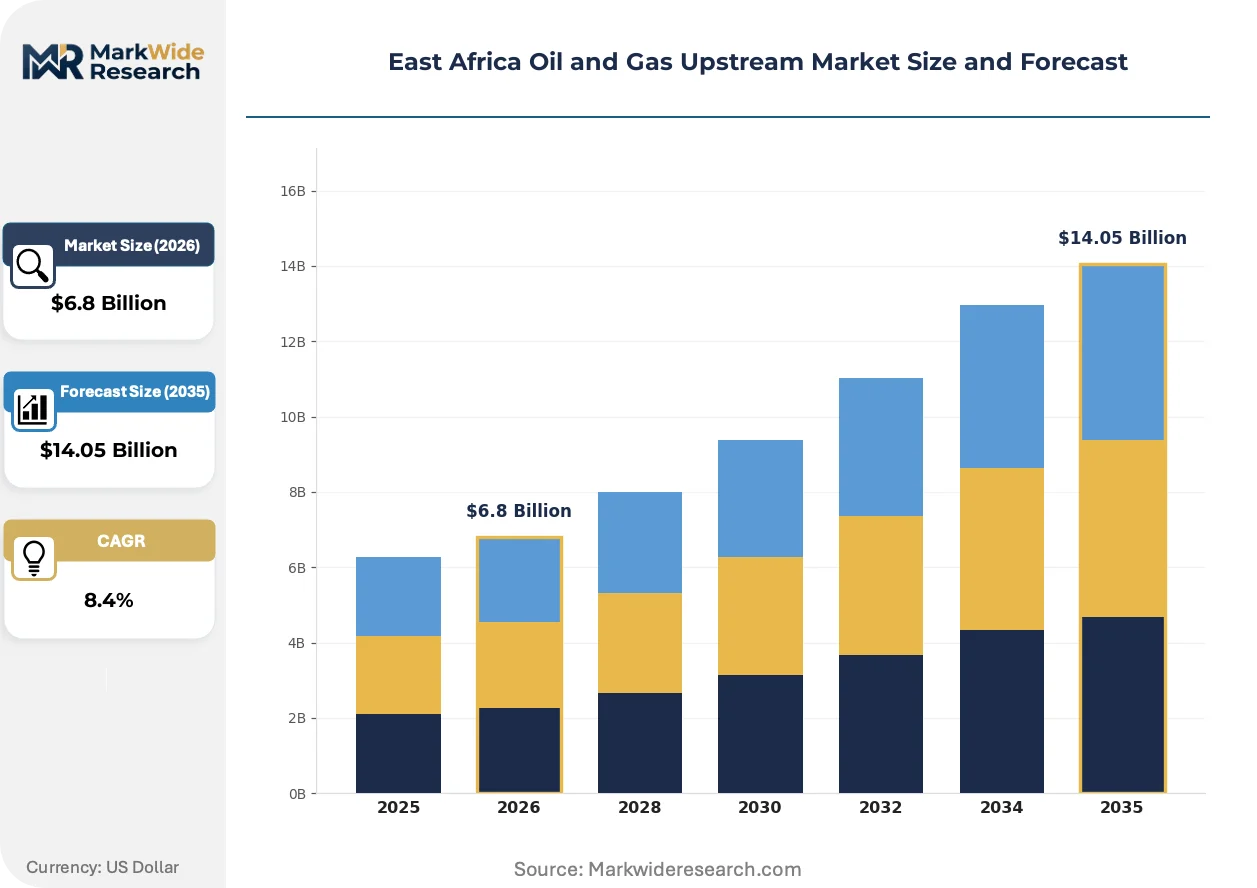
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Exploration, Drilling, Production, Seismic Services Technology: Offshore, Onshore, Enhanced Oil Recovery, Deepwater Drilling End User: Independent Operators, National Oil Companies, Multinational Corporations, Service Providers Application: Hydrocarbon Extraction, Field Development, Refining, Asset Management |
| Companies Covered | TotalEnergies SE, PanAfrican Energy Tanzania Ltd, National Oil Corporation of Kenya, Shell plc, CNOOC Limited, Equinor ASA, China National Petroleum Corporation, Eni SpA, Exxon Mobil Corporation, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
East Africa Oil and Gas Upstream Market Shifts & Advancements
Upstream technology deployment patterns across East Africa are pivoting toward solutions that compress development cycles and reduce surface facility exposure in frontier basin environments.
Subsea processing systems are overtaking conventional platform-based architectures as the preferred development model for ultra-deepwater gas-condensate fields. National oil companies in Mozambique and Tanzania are mandating subsea tieback specifications for new block awards. This technology shift is overtaking traditional capex-intensive platform construction and enabling phased field development that defers major capital commitments until reservoir performance is confirmed.
Tanzania's Petroleum Act local content requirements and Mozambique's petroleum taxation framework are tightening fiscal terms and domestic participation mandates. These regulatory instruments are extending project sanction timelines as operators renegotiate contractor structures and equity positions. Deepwater block operators are responding by front-loading local supplier development programs to preempt compliance delays.
Power purchase agreement structures are displacing traditional spot-market offtake as the dominant commercialization pathway for regional gas discoveries. East African utilities are locking in long-term supply contracts that underpin LNG project financing. Kenya's power sector restructuring is accelerating this contracting model shift, with independent power producers securing dedicated gas supply allocations ahead of liquefaction facility completion.
East Africa Oil and Gas Upstream Market Segmentation
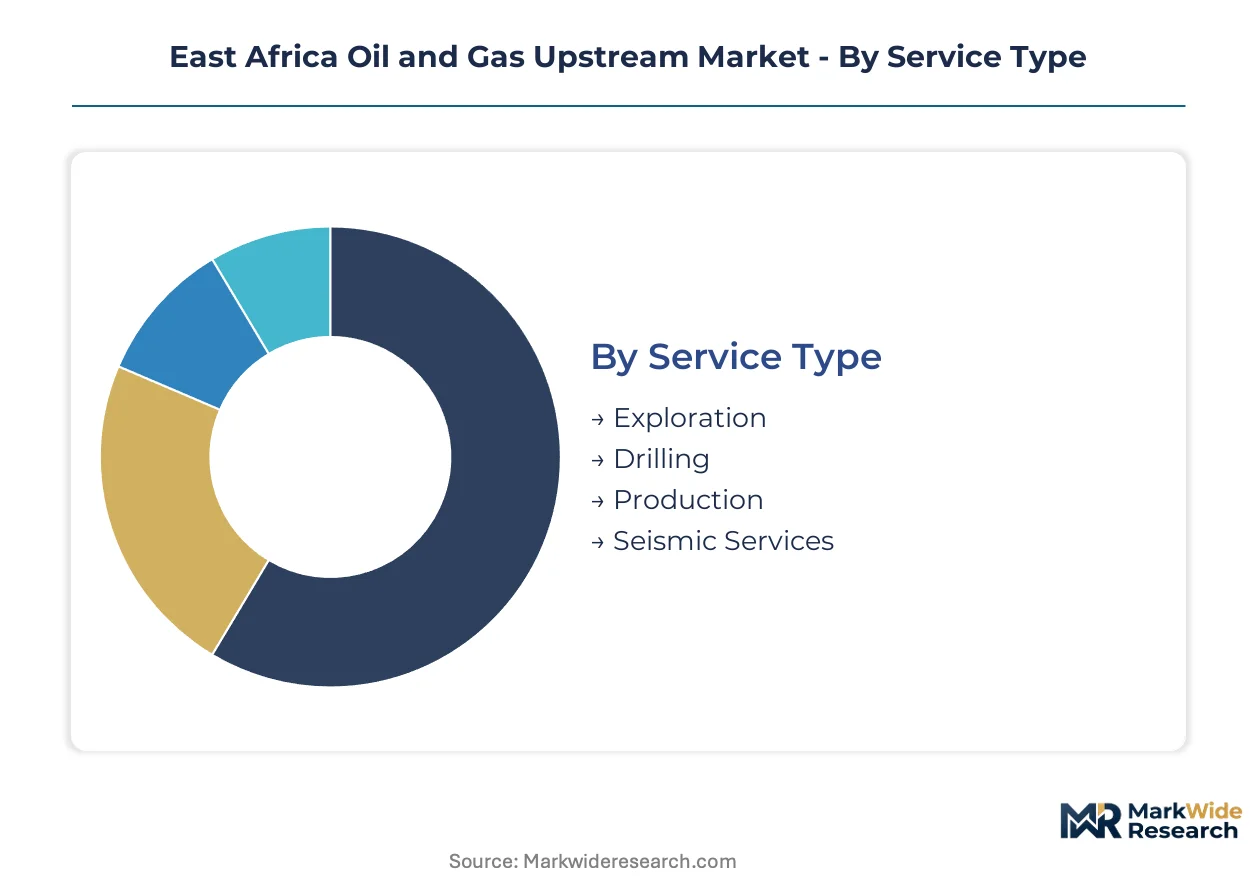
Upstream service procurement in East Africa follows distinct technical and commercial logics that reshape contract structures across the Rovuma Basin corridor. Operators segment vendor selection by reservoir depth, local content compliance capacity, and integration with floating LNG development timelines.
Service Type:
Capital allocation decisions prioritize services that compress time-to-first-gas while managing frontier basin uncertainty premiums.
- Exploration:3D seismic acquisition and frontier basin appraisal dominate early-phase spending, with demand concentrating in northern Mozambique blocks where reservoir confirmation precedes LNG sanction decisions. Limited seismic coverage across the Somali Plate inflates risk premiums and extends contractor qualification timelines.
- Drilling:Deepwater well construction commands premium dayrates due to reservoir temperatures exceeding 120°C and specialized completion requirements. Tanzania's Petroleum Act local content mandates are forcing rapid supply chain reconfiguration for drilling services without established vendor bases.
- Production:Subsea tieback architectures and floating production systems enable phased field development that defers major capital commitments until reservoir performance is confirmed.
- Seismic Services:Multi-client data acquisition programs attract disproportionate investment as operators share frontier basin uncertainty costs across consortium structures.
Exploration leads on scale; drilling leads on momentum.
Technology:
Development economics hinge on surface facility minimization and reservoir recovery optimization in ultra-deepwater settings.
- Offshore:Floating LNG and subsea processing systems displace conventional platform architectures, with Mozambique's deepwater blocks mandating subsea tieback specifications for new awards. Phased development models defer liquefaction facility commitments until offtake agreements are secured.
- Deepwater Drilling:Well depths ranging from 1,500 to 3,500 meters require specialized riser systems and managed pressure drilling capabilities that remain scarce regionally. Kenya's offshore Lamu Basin is accelerating contractor pre-qualification for deepwater-ready rigs.
- Onshore:Rift basin extraction in Uganda and Kenya leverages conventional drilling economics but faces pipeline infrastructure gaps to coastal export terminals.
- Enhanced Oil Recovery:Gas injection and chemical flooding applications remain nascent, with pilot programs concentrated in mature Tanzanian onshore fields.
Offshore technology captures the dominant capital share; deepwater drilling climbs the fastest as block awards accelerate.
End User:
Equity participation models are restructuring as East African states recalibrate state ownership thresholds and local content enforcement mechanisms.
- National Oil Companies:Tanzania Petroleum Development Corporation and Mozambique's ENH are expanding equity stakes and operator roles through production-sharing contract renegotiations. State entities now mandate direct participation in LNG marketing decisions.
- Multinational Corporations:Integrated majors anchor mega-project development through capital deployment tied to offtake agreements and bilateral infrastructure financing arrangements.
- Independent Operators:Mid-cap exploration specialists concentrate on early-phase acreage maturation with exit strategies predicated on farm-out to capitalized developers.
- Service Providers:Engineering and construction contractors are restructuring as equity participants to meet local content mandates and secure long-term maintenance contracts.
National oil companies lead on policy leverage; multinational corporations lead on capital deployment velocity.
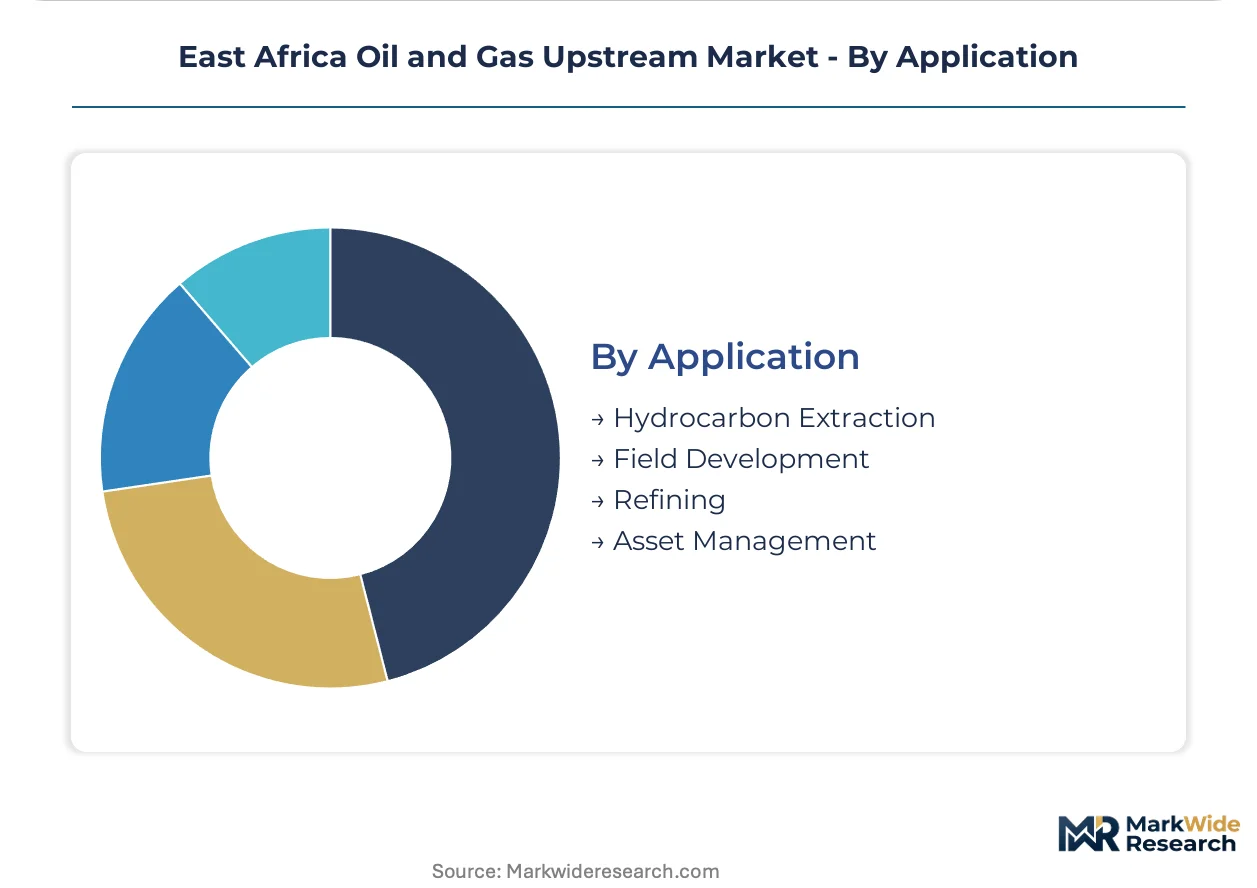
Application:
Commercialization pathways are shifting from spot-market liquidity toward long-term contractual structures that underpin project financing.
- Hydrocarbon Extraction:Gas-condensate production dominates offshore development, with Kenya's power sector restructuring accelerating dedicated supply allocations ahead of liquefaction completion.
- Field Development:Integrated project sanction timelines now synchronize drilling campaigns with pipeline and LNG terminal construction schedules to eliminate stranded asset risk.
- Refining:Domestic processing capacity remains minimal, with Tanzania's proposed Mtwara refinery and Kenya's Lapsset corridor projects attracting feasibility-stage investment.
- Asset Management:Digital twin deployment and predictive maintenance contracts are emerging as differentiated service offerings for subsea infrastructure with limited intervention access.
Hydrocarbon extraction anchors revenue generation; field development gains share fastest as sanction timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production investment migrates toward jurisdictions with streamlined fiscal terms and lower local-content compliance burdens. Tanzania's Petroleum Act revisions and Mozambique's production-sharing contract flexibility create arbitrage opportunities against Kenya's nascent regulatory framework. Operators calibrate capital deployment across the Rovuma Basin corridor based on permit timelines and state equity participation thresholds.
Mozambique
Ultra-deepwater gas-condensate discoveries in the Rovuma Basin drive exploration spending toward the Cabo Delgado offshore blocks. The country's petroleum taxation framework permits accelerated cost recovery schedules that compress project sanction timelines. Pemba and Palma serve as logistics hubs where floating LNG fabrication yards and subsea equipment staging facilities concentrate contractor activity.
Tanzania
Power generation utilities in Dar es Salaam and Mtwara scale natural gas offtake from offshore Songo Songo and Mnazi Bay fields. The Petroleum Act mandates direct state participation in LNG marketing decisions through Tanzania Petroleum Development Corporation equity stakes. The southern coastal corridor from Lindi to Mtwara anchors subsea tieback development and onshore processing infrastructure commitments.
Kenya
Lamu Basin deepwater drilling campaigns accelerate as independent power producers secure dedicated gas supply allocations ahead of LNG terminal completion. The country's national petroleum regulator enforces environmental impact assessment requirements that constrain operational windows during marine migration seasons. The Lapsset corridor projects attract feasibility-stage investment for downstream refining and petrochemical integration.
Uganda
Rift basin oil extraction in the Albertine Graben leverages conventional drilling economics for pipeline feedstock to Tanzanian export terminals. The country's national oil company structures production-sharing contracts with back-in rights that preserve state equity participation flexibility. Hoima and Buliisa districts concentrate upstream service procurement and local supplier development programs.
East Africa Oil and Gas Upstream Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated majors anchoring mega-project economics and national oil companies capturing policy-leveraged equity positions. The vendor base concentrates around three archetypes: capital-deploying integrated majors with LNG development expertise, state-backed entities mandating direct participation in marketing decisions, and fast-track subsea specialists compressing time-to-first-gas timelines. Dominant competitive moves include production-sharing contract renegotiation to recalibrate local content thresholds and bilateral infrastructure financing arrangements tied to offtake agreements.
Among integrated majors with LNG development expertise, TotalEnergies SE and Eni SpA exemplify divergent strategic positioning. TotalEnergies SE anchors mega-project economics in Mozambique's deepwater blocks through capital deployment scaled to liquefaction facility commitments. Eni SpA occupies a position within the fast-track subsea tier, with specialization in tieback architectures that defer surface facility investments until reservoir performance confirmation. China National Petroleum Corporation represents the state-backed financing archetype, extending capital through bilateral infrastructure arrangements that secure long-term offtake positions.
| Leading Market Players |
|---|
| TotalEnergies SE |
| PanAfrican Energy Tanzania Ltd |
| National Oil Corporation of Kenya |
| Shell plc |
| CNOOC Limited |
| Equinor ASA |
| China National Petroleum Corporation |
| Eni SpA |
| Exxon Mobil Corporation |
| Others |
Supply & Pricing Matrix
Subsea tieback architectures displacing conventional platform construction are simultaneously compressing capital deployment timelines and concentrating procurement leverage among specialized engineering contractors. This technology transition in the Rovuma Basin corridor reshapes how operators negotiate service pricing and where supply chain nodes locate.
Pricing Analysis
Direct-to-operator contracting discounts dominate the upstream services tier, with integrated majors leveraging long-term offtake commitments to secure preferential dayrates for deepwater rigs. Pricing stratifies across premium, standard, and economy tiers based on reservoir temperature ratings and local content certification levels. Cost compression in standard-tier drilling services is intensifying because Tanzania's Petroleum Act mandates are forcing rapid supply chain reconfiguration without established vendor bases. National oil companies exhibit the highest price sensitivity due to budget constraints, while multinational corporations prioritize technical specifications over unit economics.
Supply Chain Analysis
Freight costs for subsea equipment from fabrication yards in Singapore, South Korea, and the United Arab Emirates represent a significant landed cost component for East African deepwater projects. The supply chain draws from specialized riser manufacturers in Norway, managed pressure drilling specialists in the United States, and subsea tree fabricators in Brazil. Single-source vulnerability around ultra-deepwater completion technology creates sanction risk if primary contractors face capacity constraints. Distribution runs through Pemba and Palma logistics hubs where equipment staging facilities cluster near floating LNG fabrication sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The East Africa upstream market represents a late-cycle quality story where power purchase agreement structures are displacing spot-market offtake and rewarding operators with contracted revenue streams.
For Market Incumbents: Deepen subsea equipment maintenance capabilities to capture lifecycle revenue as installed base expands across Mozambique's deepwater blocks. Defend against emerging independent operators by accelerating local supplier development programs that preempt Tanzania's Petroleum Act compliance delays. Secure backward integration into subsea tree refurbishment to control critical spare parts availability. For New Entrants and Emerging Players: The gap between premium integrated service pricing and economy-tier local contractor rates creates entry space for mid-cap specialists with hybrid technical-local content capabilities. Target Kenya's Lamu Basin drilling campaigns where contractor pre-qualification timelines remain shorter than established Rovuma Basin blocks. Pursue fast-track subsea tieback deployment models that compress time-to-first-gas and justify premium positioning. For Investors and Strategic Acquirers: Valuations sit cheapest among engineering and construction contractors restructuring as equity participants to meet local content mandates. The five-to-ten year viability window hinges on LNG liquefaction facility completion schedules synchronizing with field development timelines. Acquisition candidates with established Tanzania Petroleum Development Corporation relationships and subsea processing expertise offer the strongest positioning. Watch for power purchase agreement execution rates as the signal indicating project financing viability.| Strategic Initiative | Industry Significance |
|---|---|
| Subsea Tieback Deployment | Compresses time-to-first-gas timelines in Mozambique's ultra-deepwater blocks. |
| Local Content Program Investment | Preempts Tanzania Petroleum Development Corporation sanction delays and secures block awards. |
| Power Purchase Agreement Structuring | Underpins LNG project financing through Kenya's independent power producer allocations. |
| Floating LNG Technology Licensing | Unlocks commercialization pathways for Rovuma Basin gas-condensate discoveries. |
| Subsea Equipment Maintenance Contracting | Captures lifecycle revenue from expanding installed base across East African acreage. |
Research Methodology
Multiple input streams — executive interviews with upstream project developers, technical discussions with subsea engineering specialists, and regulatory consultations with national petroleum authorities — were reconciled against secondary validation from EIA data, IEA reports, and project development databases. Primary engagement encompassed EPC contractors, national oil company planning officers, and independent power producer fuel supply specialists. Bottom-up field development cost modeling and top-down regional demand aggregation were cross-referenced to establish market sizing.
Historical project sanction timelines were cross-referenced against panel input from LNG marketing executives and utility procurement directors. The analytical framework segments by service type, technology deployment, end-user equity model, and application pathway across the projection horizon. CAGRs were derived from facility completion schedules and offtake agreement execution rates. Forecast inputs include reservoir temperature specifications and local content compliance thresholds.
The model assumes a particular technology adoption path; alternative pathways for floating LNG versus onshore liquefaction would alter the outlook for infrastructure capital allocation. Forecasts reflect assumptions regarding regulatory enforcement consistency and bilateral financing availability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
India Oil and Gas Upstream Market
Offshore Oil and Gas
East Africa Oil and Gas Midstream Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Southeast Asia Offshore Seismic Survey Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Oil and Gas Magnetic Ranging Market
Offshore Oil and Gas
Deepwater Subsea Structure Integrity Acoustic Test Platforms Market
Offshore Oil and Gas
Offshore Rental Equipment Market
Offshore Oil and Gas
United Kingdom Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Argentina Oil and Gas Downstream Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Middle East and Africa Offshore Energy Market