
 Oman Oil and Gas Downstream Market | 2026-2036
Oman Oil and Gas Downstream Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Oil and Gas Downstream Market Analytics
Aftermarket lubricant blending and technical services is reshaping margin capture in Oman's downstream sector. OQ Group leverages its integrated refining and petrochemicals footprint to control feedstock costs across multiple governorates. Shell PLC competes through technology licensing for hydroprocessing units at the Sohar refinery complex. Duqm Refinery and Petrochemical Industries Company anchors the Sultanate's capacity expansion with its greenfield complex on the Arabian Sea coast.
Oil and gas downstream operations encompass refining crude oil into fuels, producing petrochemicals from feedstock streams, and manufacturing lubricants and specialty products through thermal and catalytic processes. Cracking units operate at temperatures exceeding 800 degrees Celsius to break heavy hydrocarbons into lighter olefins for polymer production. Petrochemicals represents the fastest-expanding product category as Oman targets import substitution for polyethylene and polypropylene derivatives. Hydroprocessing technology leads capital deployment due to sulfur reduction mandates for refined products sold domestically and exported to Asian markets.
Oman's Ministry of Energy and Minerals sets production quotas and environmental standards for refinery operations, while the Directorate General of Environmental Affairs enforces air quality limits on stack emissions from Sohar and Duqm facilities. The Sultanate's adherence to ISO 14001 environmental management systems shapes operator certification requirements and international offtake agreements. Stakeholders must monitor feedstock allocation policies between domestic refining and petrochemicals integration as OQ Group expands Duqm capacity.
Market Dynamics
Duqm Special Economic Zone is concentrating downstream capacity investments as Oman's Ministry of Energy and Minerals tightens environmental compliance standards for refinery emissions, forcing capital reallocation toward integrated petrochemical complexes.
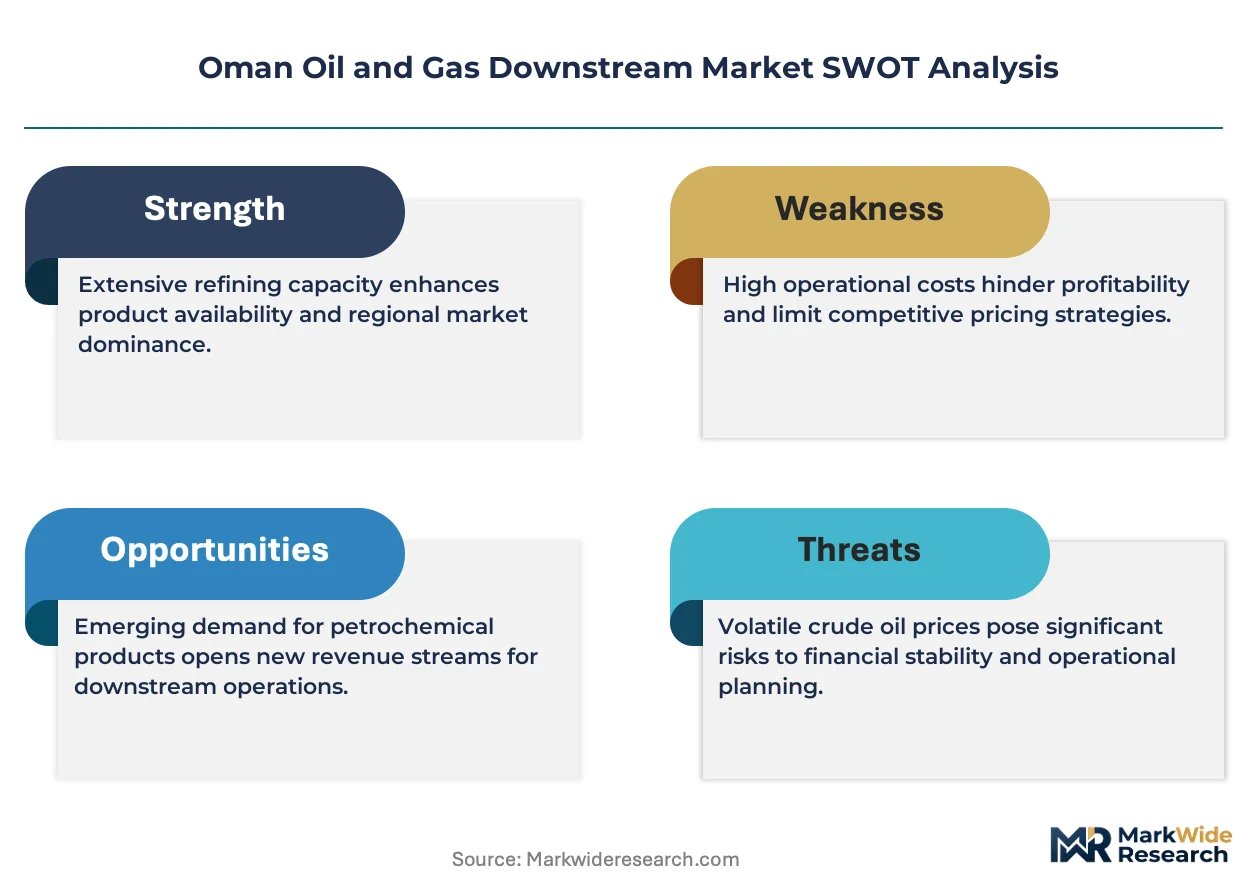
Growth Catalysts
- Petrochemical feedstock demand:Industrial zones across Muscat, Sohar, and Duqm are expanding polymer derivative manufacturing to reduce import dependence for polyethylene and polypropylene.
- ISO 14001 certification requirements:The Sultanate's adherence to international environmental management systems is accelerating operator certification and enabling offtake agreements with Asian buyers.
- Hydroprocessing technology deployment:Sulfur reduction mandates for refined products sold domestically and exported to Asian markets are pulling capital into desulfurization unit upgrades.
Market Restraints
- Crude feedstock allocation constraints:Competition between domestic refining needs and petrochemicals integration limits operational flexibility as OQ Group expands Duqm capacity.
- Specialized technical workforce scarcity:Cracking unit operations requiring temperatures exceeding 800 degrees Celsius demand skilled operators that remain concentrated in established refining hubs.
- Capital intensity of greenfield complexes:Integrated refinery-petrochemical projects on the Arabian Sea coast require multi-year investment horizons with extended payback periods.
Strategic Opportunities
- Aftermarket lubricant services:Technical blending and service unbundling creates margin capture potential in governorates beyond the Sohar refinery complex.
- Duqm SEZ infrastructure:Greenfield site advantages on the Arabian Sea coast enable optimized logistics for Asian market access compared to legacy facilities.
- Polymer derivative manufacturing:Import substitution targets for polyethylene and polypropylene derivatives open captive demand for downstream operators.
Industry Challenges
- Emissions monitoring compliance:The Directorate General of Environmental Affairs enforces air quality limits on stack emissions, requiring continuous monitoring system investments at Sohar and Duqm facilities.
- Feedstock integration complexity:Balancing naphtha streams between refinery gasoline production and petrochemicals cracking demands real-time optimization capabilities.
- Technology licensing negotiations:Hydroprocessing unit upgrades involve complex intellectual property arrangements with technology licensors for catalyst formulations and process designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Oil and Gas Downstream Market |
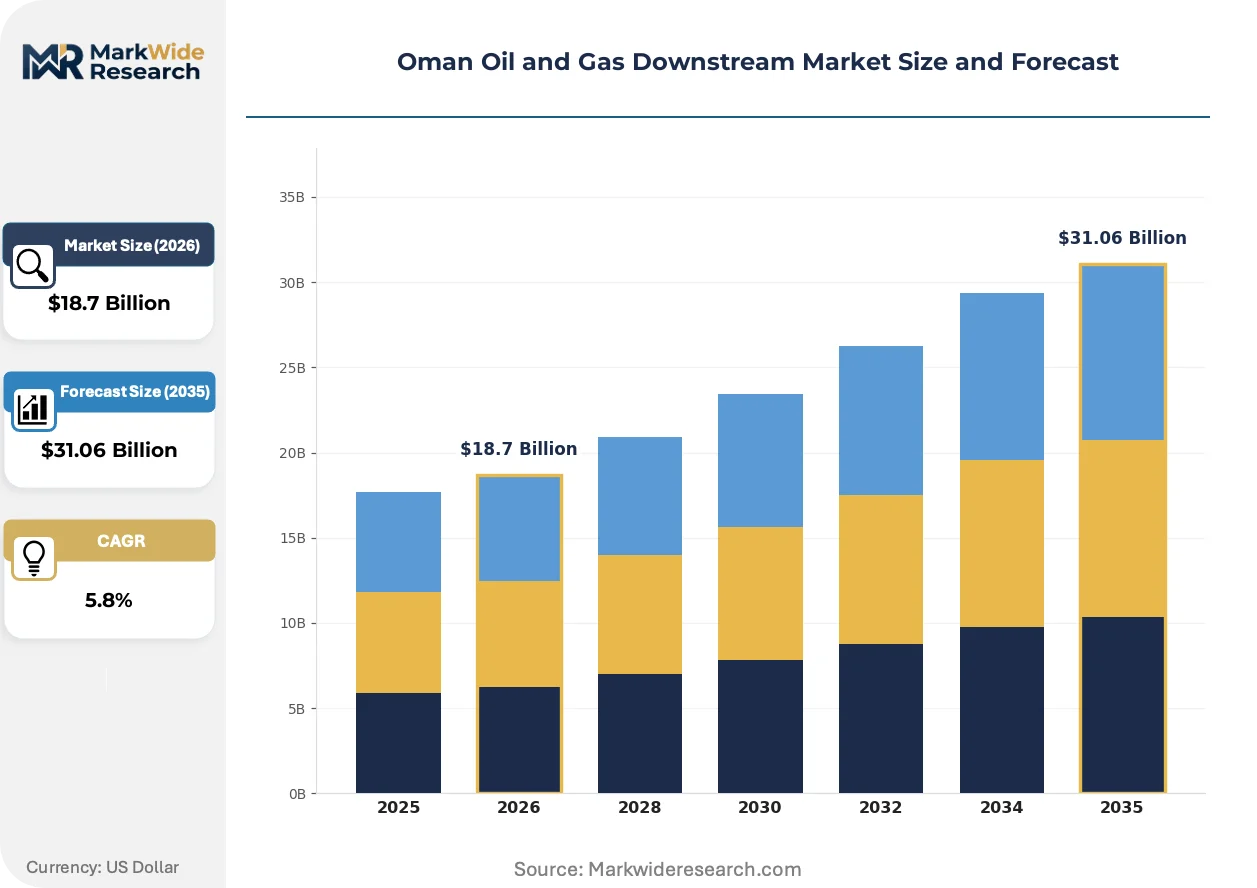
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Oil, Petrochemicals, Gasoline, Lubricants Technology: Cracking, Reforming, Hydroprocessing, Distillation End User: Automotive, Industrial, Power Generation, Aviation Distribution Channel: Retail, B2B Supply, Wholesale, Direct Sales |
| Companies Covered | Shell PLC, OQ Group, Oman Oil Marketing Company SAOG, Kuwait Petroleum International, Duqm Refinery and Petrochemical Industries Company, TotalEnergies SE, Petroleum Development Oman LLC, Occidental Petroleum, OQ8, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Oil and Gas Downstream Market Evolving Landscape
Digital process control systems are penetrating Oman's downstream facilities as operators seek real-time optimization of cracking yields and emissions compliance. Three developments are restructuring competitive positioning.
Advanced process control software is digitizing unit operations across Sohar and Duqm refineries. Operators are deploying predictive analytics platforms to optimize catalytic reformer performance and reduce unplanned downtime. This capability compression is enabling smaller technical teams to manage complex integrated processes.
The Ministry of Energy and Minerals is enforcing stricter stack emission limits through the Directorate General of Environmental Affairs. Refinery operators must install continuous emissions monitoring systems and report real-time data to regulators. Hydroprocessing units face the most intensive compliance timelines due to sulfur reduction mandates for both domestic sales and Asian export contracts.
Buyers are consolidating procurement of technical services and specialty lubricants around certified providers with ISO 14001 credentials. Industrial consumers in Oman's free zones are unbundling aftermarket blending from product supply, creating standalone service contracts. This pattern is most pronounced in Duqm Special Economic Zone where new manufacturing investments demand localized technical support capabilities.
Oman Oil and Gas Downstream Market Segmentation
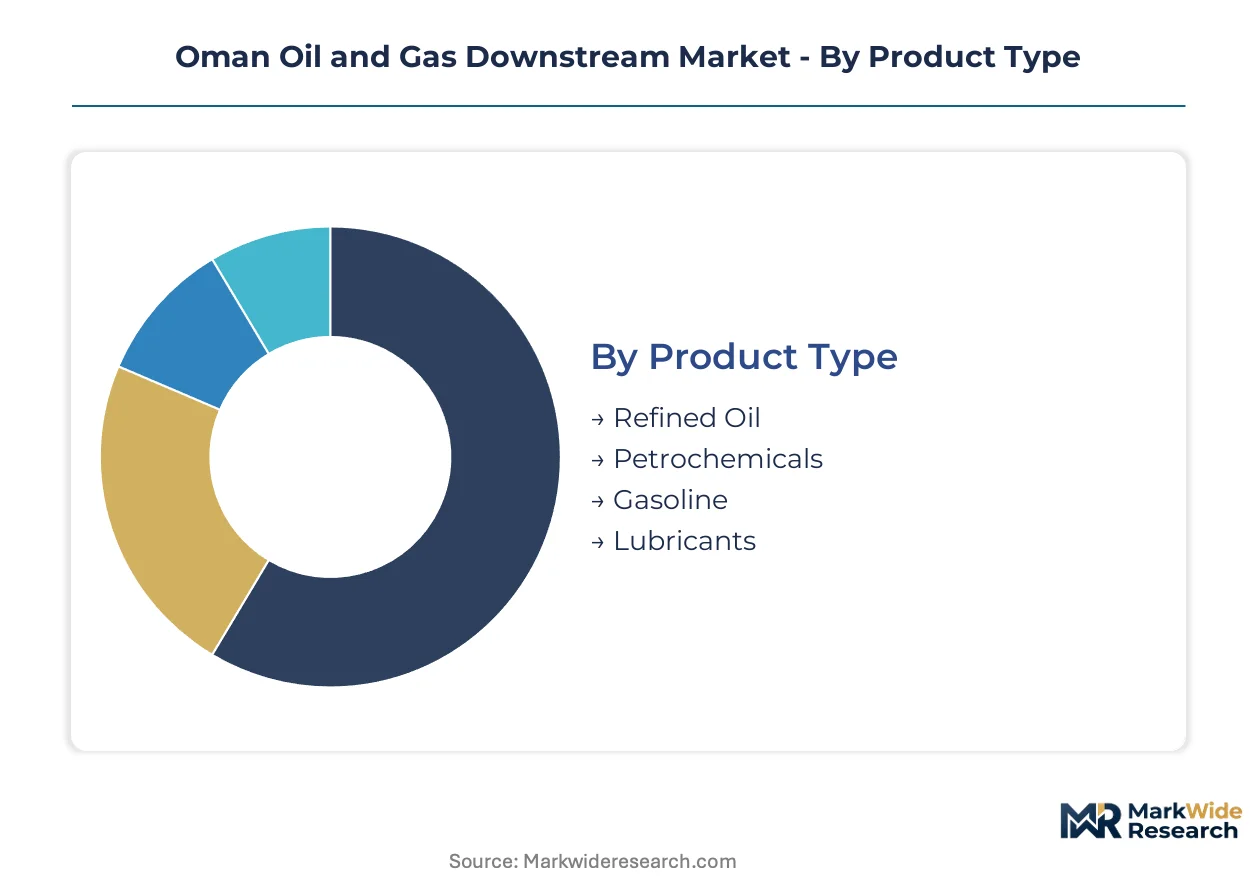
Downstream operators in Oman navigate distinct demand profiles across fuel, chemical, and specialty product streams. Segmentation reveals where capital allocation and margin capture concentrate within the Sultanate's refining and petrochemicals infrastructure.
Product Type:
Product categories span the full use-case spectrum from transportation fuels to industrial feedstocks and precision-formulated lubricants.
- Refined Oil:Diesel and fuel oil outputs serve domestic power generation and marine bunkering demand. Sohar refinery volumes anchor supply contracts with industrial consumers across Al Batinah and Muscat governorates.
- Petrochemicals:Ethylene, propylene, and aromatic streams feed polymer derivative manufacturing in Duqm and Sohar industrial zones. The Ministry of Energy and Minerals prioritizes naphtha allocation to cracking units as import substitution targets tighten for polyethylene and polypropylene.
- Gasoline:Motor gasoline blending meets domestic automotive demand with sulfur specifications aligned to Asian export markets.
- Lubricants:Base oil refining and additive blending supports aftermarket technical services across Oman's free zones.
Established volume favors refined oil; emerging adoption favors petrochemicals.
Technology:
Process technology selection reflects cost tier differentiation between legacy unit operations and capital-intensive conversion investments.
- Cracking:Thermal and catalytic cracking units operate above 800 degrees Celsius to break heavy hydrocarbons into light olefins. Duqm Refinery and Petrochemical Industries Company deploys these units to supply polymer feedstock for the SEZ's manufacturing tenants.
- Reforming:Catalytic reformers upgrade naphtha into high-octane gasoline components and aromatic feedstocks. Sohar refinery operators optimize reformer severity to balance gasoline pool requirements against benzene-toluene-xylene extraction for chemical synthesis.
- Hydroprocessing:Hydrotreating and hydrocracking units reduce sulfur content to meet Directorate General of Environmental Affairs stack emission limits.
- Distillation:Atmospheric and vacuum distillation separates crude fractions for downstream processing.
Margin concentration sits with hydroprocessing given sulfur mandate compliance timelines; capacity expansion concentrates in cracking for petrochemicals integration.
End User:
Customer type segmentation tracks demand concentration across mobility, industrial processing, and energy conversion applications.
- Automotive:Passenger and commercial vehicle fleets consume gasoline and diesel through retail and fleet supply contracts. The Sultanate's vehicle registration growth in Muscat and Al Batinah governorates pulls refined product demand.
- Industrial:Manufacturing operations in Duqm Special Economic Zone and Sohar Free Zone purchase fuel oil, naphtha, and petrochemical derivatives as process inputs and energy sources.
- Power Generation:Grid and captive power plants burn fuel oil and diesel during peak demand periods.
- Aviation:Muscat International Airport and Duqm Airport jet fuel offtake ties to passenger traffic recovery and cargo logistics expansion.
Volume leadership remains with automotive; steepest expansion trajectory belongs to industrial users as Duqm manufacturing capacity comes online.
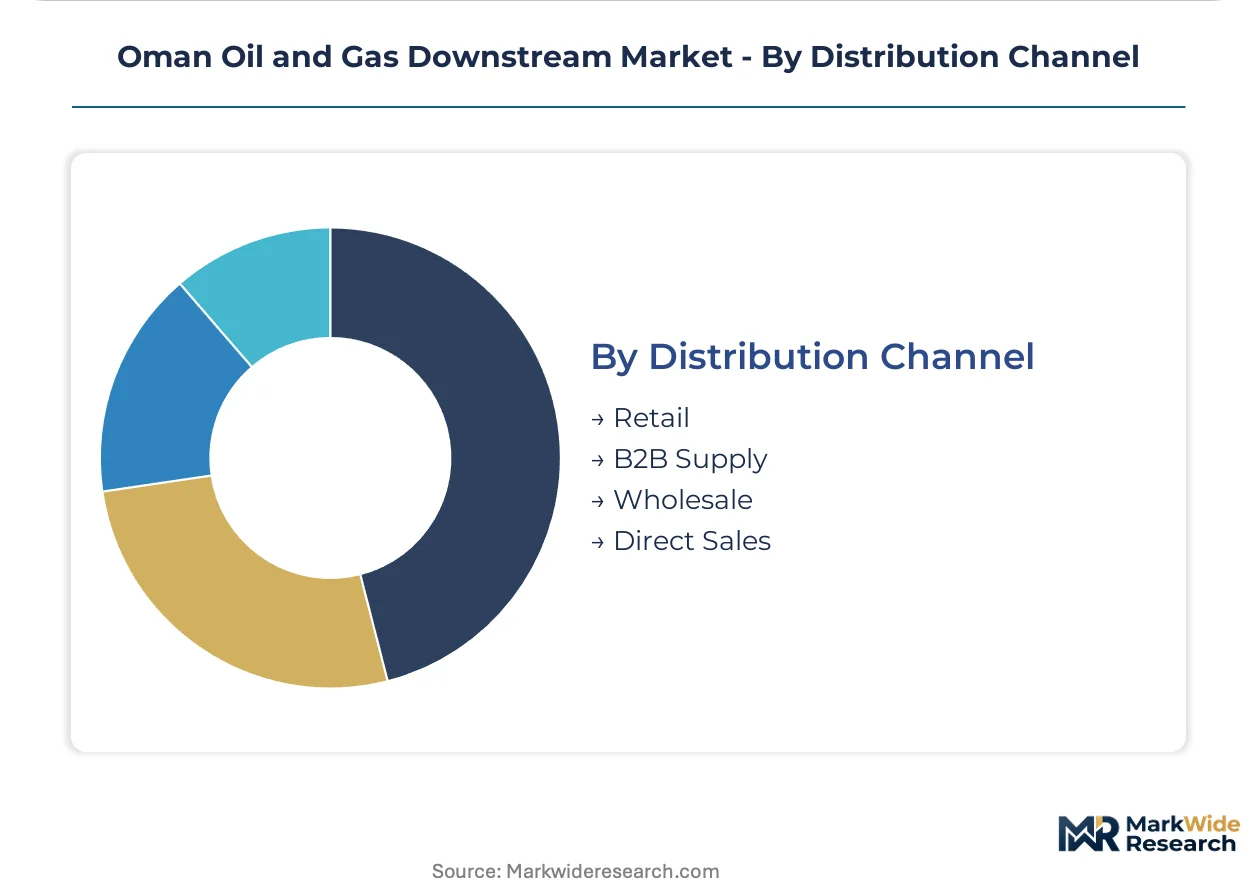
Distribution Channel:
Channel structure varies by customer scale and product specification requirements.
- Retail:Service stations across Oman's governorates deliver gasoline and diesel to consumer and light commercial vehicles. OQ Group operates the dominant retail network with ISO 14001-certified facilities.
- B2B Supply:Direct contracts with industrial consumers and fleet operators move bulk fuel and lubricant volumes. Duqm SEZ manufacturers source petrochemical feedstocks through negotiated term agreements.
- Wholesale:Intermediary distributors handle product resale to smaller commercial accounts and remote governorates.
- Direct Sales:Refinery gate sales and pipeline deliveries serve large-volume industrial offtakers with dedicated storage infrastructure.
Channel preference shifts toward B2B supply as Duqm industrial zone tenants consolidate procurement around certified providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Downstream consumption patterns across Oman diverge sharply between coastal refining clusters and interior industrial zones, with petrochemical feedstock demand concentrating in Special Economic Zones while refined fuels serve dispersed power generation and transport needs.
Muscat Governorate
Retail fuel distribution and aviation jet fuel offtake at Muscat International Airport dominate downstream demand in the capital region. The Ministry of Energy and Minerals allocates refined product quotas to balance domestic supply security against export commitments. Industrial consumers in Rusayl and Seeb free zones source lubricants and specialty products through direct B2B contracts.
Al Batinah Region
Sohar refinery complex anchors refined oil production for domestic power plants and marine bunkering along the Gulf of Oman coastline. The Directorate General of Environmental Affairs enforces stack emission limits on catalytic reformer and hydroprocessing units. Petrochemical derivatives manufacturing in Sohar Free Zone pulls naphtha feedstock away from gasoline blending.
Al Wusta Governorate
Duqm Special Economic Zone concentrates greenfield downstream investments with integrated refinery-petrochemical complexes on the Arabian Sea coast. The Ministry of Energy and Minerals prioritizes feedstock allocation to cracking units serving polymer manufacturing tenants. Duqm Refinery and Petrochemical Industries Company operations create captive demand for technical services and aftermarket lubricant blending.
Dhofar Governorate
Salalah port facilities handle fuel oil and diesel imports for remote southern governorates with limited pipeline connectivity. Industrial zones around Salalah Free Zone develop polymer derivative manufacturing to reduce import dependence. Grid stability requirements sustain fuel oil demand for peak power generation during summer cooling loads.
Ad Dakhiliyah Governorate
Interior transport corridors generate diesel demand for commercial trucking and mining operations serving limestone and gypsum extraction. The absence of refining infrastructure creates wholesale distribution dependencies on coastal supply points. Fleet operators consolidate procurement around certified lubricant providers with ISO 14001 environmental credentials.
Oman Oil and Gas Downstream Market Competitive Landscape
Capability concentration sits with integrated operators controlling refining and petrochemicals footprints; scale advantage sits with international technology licensors and regional marketing networks. The market structures around three tiers: state-backed integrated players with feedstock control, international majors leveraging process technology licensing, and specialized downstream marketers focused on retail and B2B distribution. Competitive dynamics center on feedstock allocation negotiations with the Ministry of Energy and Minerals, plus environmental compliance certification for Asian offtake agreements. Capacity expansion at Duqm and hydroprocessing upgrades at Sohar represent the dominant capital deployment vectors.
Within the integrated operator tier, OQ Group exemplifies state-backed vertical control across refining, petrochemicals, and retail distribution. Shell PLC and TotalEnergies SE occupy positions as international technology licensors with historical presence in Oman's upstream and downstream sectors. Duqm Refinery and Petrochemical Industries Company anchors greenfield capacity development on the Arabian Sea coast.
| Leading Market Players |
|---|
| Shell PLC |
| OQ Group |
| Oman Oil Marketing Company SAOG |
| Kuwait Petroleum International |
| Duqm Refinery and Petrochemical Industries Company |
| TotalEnergies SE |
| Petroleum Development Oman LLC |
| Occidental Petroleum |
| OQ8 |
| Others |
Value Network & Pricing Analysis
Crude feedstock allocation constraints determine both pricing tier spreads and supply chain shape in Oman's downstream sector, as competition between domestic refining and petrochemicals integration forces operators to optimize naphtha stream valuations across integrated complexes.
Pricing Analysis
Long-term offtake contracts dominate refined product transactions between Sohar and Duqm facilities and Asian buyers, while spot market exposure concentrates in fuel oil and marine bunkering volumes. Price differentiation hinges on sulfur content grades aligned to Directorate General of Environmental Affairs mandates and ISO 14001 certification tiers for lubricant blending services. Pricing pressure stems from hydroprocessing unit upgrade costs as operators absorb desulfurization capital deployment. Industrial consumers in Duqm Special Economic Zone exhibit lowest price sensitivity due to captive demand for polymer feedstocks, while wholesale distributors serving interior governorates face margin compression from logistics cost absorption.
Supply Chain Analysis
Export control regimes on hydroprocessing catalyst formulations and cracking unit technology limit technology licensor flows from the United States, Germany, and Japan into Omani refinery expansions. Raw material dependencies center on naphtha feedstock from upstream OQ Group operations, specialized catalyst imports for desulfurization units, and additive packages for lubricant blending. Single-source vulnerability concentrates in catalyst supply for hydroprocessing upgrades mandated by the Ministry of Energy and Minerals. Distribution runs through pipeline networks connecting Sohar and Duqm to coastal storage terminals, with B2B direct sales dominating petrochemical feedstock offtake to SEZ manufacturing tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Duqm Special Economic Zone infrastructure buildout represents a high-growth disruption as integrated refinery-petrochemical complexes reshape feedstock economics and regional supply security calculations.
For Market Incumbents: Build feedstock allocation moats through backward integration into naphtha supply streams and cracking unit capacity expansion at Duqm. OQ Group should consolidate lubricant blending technical services in underpenetrated governorates before specialty marketers establish ISO 14001-certified footprints. Defensive positioning requires continuous emissions monitoring system deployment ahead of Directorate General of Environmental Affairs compliance timelines. For New Entrants and Emerging Players: Dhofar Governorate's polymer derivative manufacturing gap offers white-space entry as Salalah Free Zone tenants seek localized polyethylene and polypropylene supply. Aftermarket lubricant technical services in Ad Dakhiliyah Governorate's mining and transport corridors present penetrable territory with limited certified provider presence. Go-to-market execution should anchor on fleet operator procurement consolidation around ISO 14001 environmental credentials. For Investors and Strategic Acquirers: Ministry of Energy and Minerals sulfur reduction mandates reshape the acquisition landscape toward hydroprocessing technology licensors and catalyst formulation specialists with established Asian export relationships. Long-term viability favors operators with integrated refining-petrochemicals footprints and Duqm SEZ logistics access. Watch feedstock allocation policy shifts between domestic refining and cracking unit prioritization as the inflection signal for capacity utilization trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Duqm SEZ Capacity Buildout | Greenfield refinery-petrochemicals integration captures Asian market access advantages over legacy Gulf of Oman facilities. |
| Hydroprocessing Technology Licensing | Desulfurization unit deployments satisfy Ministry of Energy and Minerals mandates for domestic and export product specifications. |
| Backward Integration into Naphtha Supply | Captive feedstock control across OQ Group operations optimizes cracking unit economics for polymer production. |
| ISO 14001 Certification Program | Environmental management credentials unlock industrial offtake agreements with Duqm SEZ manufacturing tenants. |
| Aftermarket Lubricant Services Expansion | Technical blending unbundling in interior governorates captures margin from fleet and mining operator procurement consolidation. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, petrochemicals procurement leads at Duqm SEZ manufacturers, lubricant blending technical directors, and Ministry of Energy and Minerals policy officials and refined through secondary validation against customs trade data, Directorate General of Environmental Affairs emission filings, SEC disclosures from international technology licensors, and OQ Group infrastructure development records. Bottom-up capacity utilization modeling triangulated against top-down feedstock allocation policy analysis.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, process technology, end-user application, and distribution channel. CAGRs derived from facility expansion timelines, regulatory compliance deadlines, and industrial zone tenant absorption rates. Forecast inputs incorporated hydroprocessing unit deployment schedules and polymer derivative manufacturing capacity ramp assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by international catalyst suppliers or accelerated Duqm SEZ tenant recruitment would shift outcomes. Material shifts in Ministry of Energy and Minerals feedstock allocation priorities or Directorate General of Environmental Affairs emission limit tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Floating Storage and Regasification Unit Market
Offshore Oil and Gas
United Kingdom LNG Bunkering Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
Offshore Equipment Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Asia-Pacific Floating Production Systems Market
Offshore Oil and Gas
Brazil Offshore Energy Market
Offshore Oil and Gas
Gulf of Mexico Subsea Systems Market
Offshore Oil and Gas
Uzbekistan Oil and Gas Upstream Market
Offshore Oil and Gas
Floating Production Systems (FPS) Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Connected Solutions for Oil and Gas Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
High Pressure Oil and Gas Separators Market
Offshore Oil and Gas
South America Oil and Gas Downstream Market
Offshore Oil and Gas
Marine Scrubber Market