
 Fire Pump Test Meters Market | 2026-2036
Fire Pump Test Meters Market Size, Share, and Industry Trends Forecast 2026-2036
Fire Pump Test Meters Market Analysis
Modular sensor configurations bundled with cloud-connected data loggers is rebalancing how fire safety contractors evaluate total cost of ownership. Badger Meter Inc. leverages its ultrasonic platform to anchor premium positioning in municipal accounts. Armstrong Fluid Technology sustains engineering-intensive differentiation through integrated pump-and-meter systems. Victaulic Company competes on channel control, occupying dominant shelf space with North American distributors serving industrial facilities.
Fire pump test meters are precision instrumentation devices that measure flow rate, pressure, and pump performance against rated specifications, typically employing turbine, electromagnetic, or ultrasonic sensing elements with accuracy tolerances of ±0.5% to ±2%. Their primary purpose is to verify that fire suppression pumps deliver adequate water volume and pressure during annual certification testing and emergency readiness audits. Digital meters are capturing the fastest expansion as municipalities replace analog gauges with NIST-traceable electronic units that auto-generate compliance documentation. Electromagnetic technology leads on margin pools due to minimal moving parts and extended calibration intervals, while mechanical meters retain residual share in budget-constrained maintenance applications.
NFPA standards, UL certification requirements, and local AHJ enforcement shape product design and market access across the United States, with China's GB fire protection standards and Germany's VdS Schadenverhütung guidelines imposing parallel conformity burdens in their respective jurisdictions. The EU Machinery Directive and impending CSRD disclosure rules will tighten traceability requirements for safety-critical instrumentation sold into European commercial buildings. Stakeholders must monitor how regulatory digitization of inspection records reshapes meter specification criteria and aftermarket service attach rates.
Market Dynamics
Electromagnetic sensor platforms are compressing calibration intervals and reshaping specification criteria across municipal procurement departments. This displacement of mechanical sensing architectures reconfigures vendor qualification standards and aftermarket service economics.
Growth Catalysts
- NFPA 25 digitization mandates:US municipalities now require NIST-traceable electronic documentation for annual pump certification, forcing analog gauge replacement cycles.
- Industrial safety audit intensification:German chemical processing facilities under VdS Schadenverhütung guidelines are expanding electromagnetic meter deployment for precision flow verification.
- Cloud-connected data logging:Fire safety contractors bundle modular sensor configurations with remote monitoring platforms to reduce total cost of ownership.
Market Restraints
- Copper and rare-earth magnet cost volatility:Electromagnetic meter production faces input price pressure from concentrated Chinese rare-earth processing.
- Legacy mechanical meter installed base:Budget-constrained maintenance departments in smaller US municipalities delay replacement cycles.
- UL certification timeline friction:New electromagnetic designs face extended validation periods for hazardous location approvals.
Strategic Opportunities
- China's GB fire protection standard enforcement:Tier-two Chinese cities are accelerating building code compliance audits, creating replacement demand.
- Predictive maintenance convergence:Vibration sensing and flow metering integration enables condition-based pump monitoring for industrial facilities.
- Direct municipal procurement platforms:State-level cooperative purchasing contracts in the US are disintermediating traditional distributor channels.
Industry Challenges
- Electromagnetic calibration technician scarcity:Specialized field service expertise for digital meter verification remains concentrated among certified contractors.
- Legacy analog system integration complexity:Retrofitting electromagnetic sensors into existing pump control architectures requires custom signal conditioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fire Pump Test Meters Market |
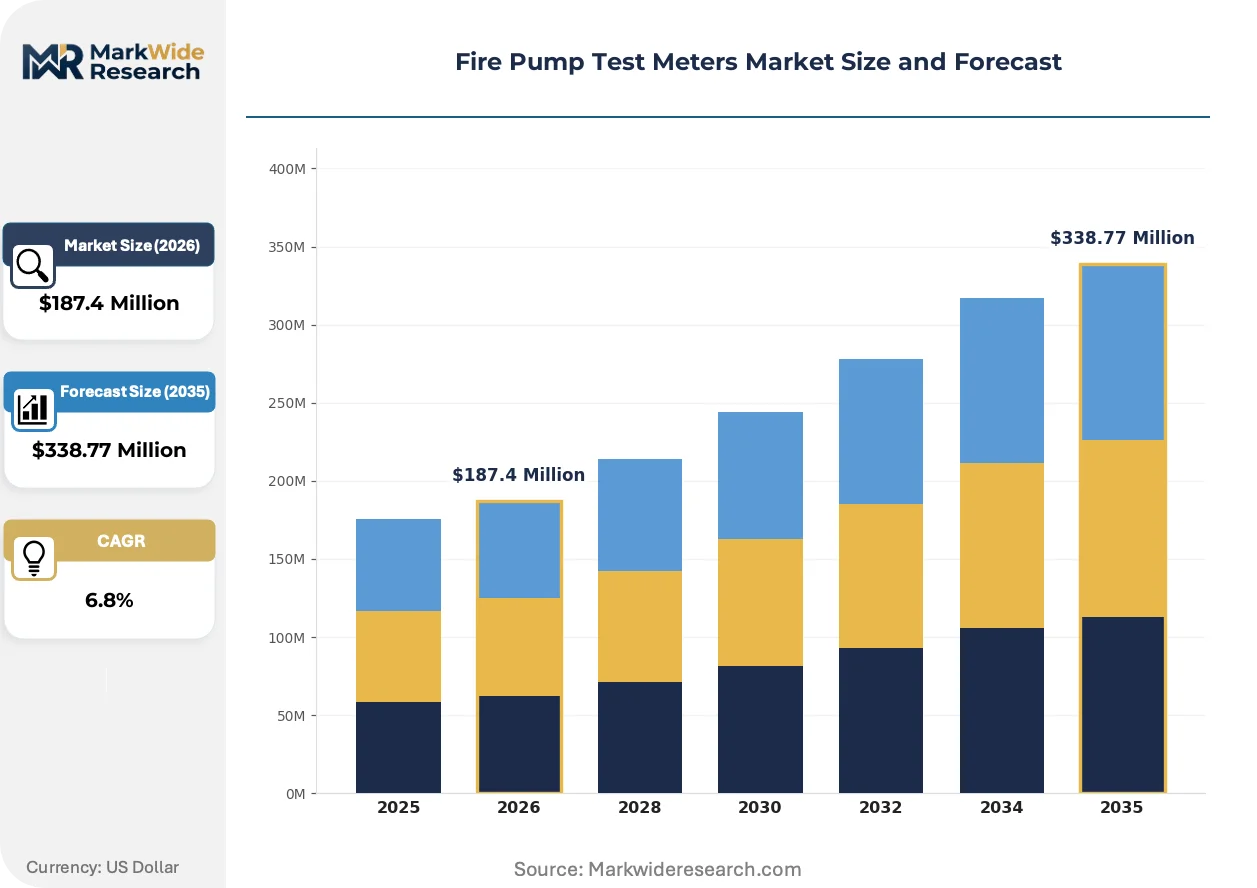
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Stationary Meters, Digital Meters, Mechanical Meters Technology: Ultrasonic, Electromagnetic, Mechanical, Electronic End User: Municipalities, Industrial Facilities, Fire Departments, Commercial Buildings Application: Flow Measurement, Pressure Measurement, System Testing, Maintenance |
| Companies Covered | Badger Meter Inc., Armstrong Fluid Technology, Victaulic Company, Ayvaz, Gerand Engineering, Global Vision Inc. (GVI), Dwyer Instruments Inc., McCrometer, KROHNE Messtechnik GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fire Pump Test Meters Market Emerging Trajectories
Sensor miniaturization and wireless telemetry are converging to redefine how fire pump performance data is captured, transmitted, and archived for regulatory compliance.
Ultrasonic flow measurement is overtaking turbine-based designs in high-precision municipal applications. These clamp-on sensors eliminate pipe intrusion and reduce installation downtime for active fire suppression systems. Water utilities in Germany and the United States are specifying ultrasonic platforms for their extended calibration stability.
The EU CSRD disclosure rules are mandating traceable instrumentation documentation for commercial building safety systems. This regulatory pressure forces meter manufacturers to embed tamper-evident data logging and blockchain-verified inspection records. European facility management firms are prioritizing meters with native compliance reporting functionality.
Service unbundling is fragmenting traditional procurement relationships. Fire safety contractors now separate hardware acquisition from calibration service contracts, enabling competitive bidding on multi-year maintenance agreements. This pattern is most pronounced among US industrial facilities managing distributed pump networks across multiple states.
Fire Pump Test Meters Market Segmentation
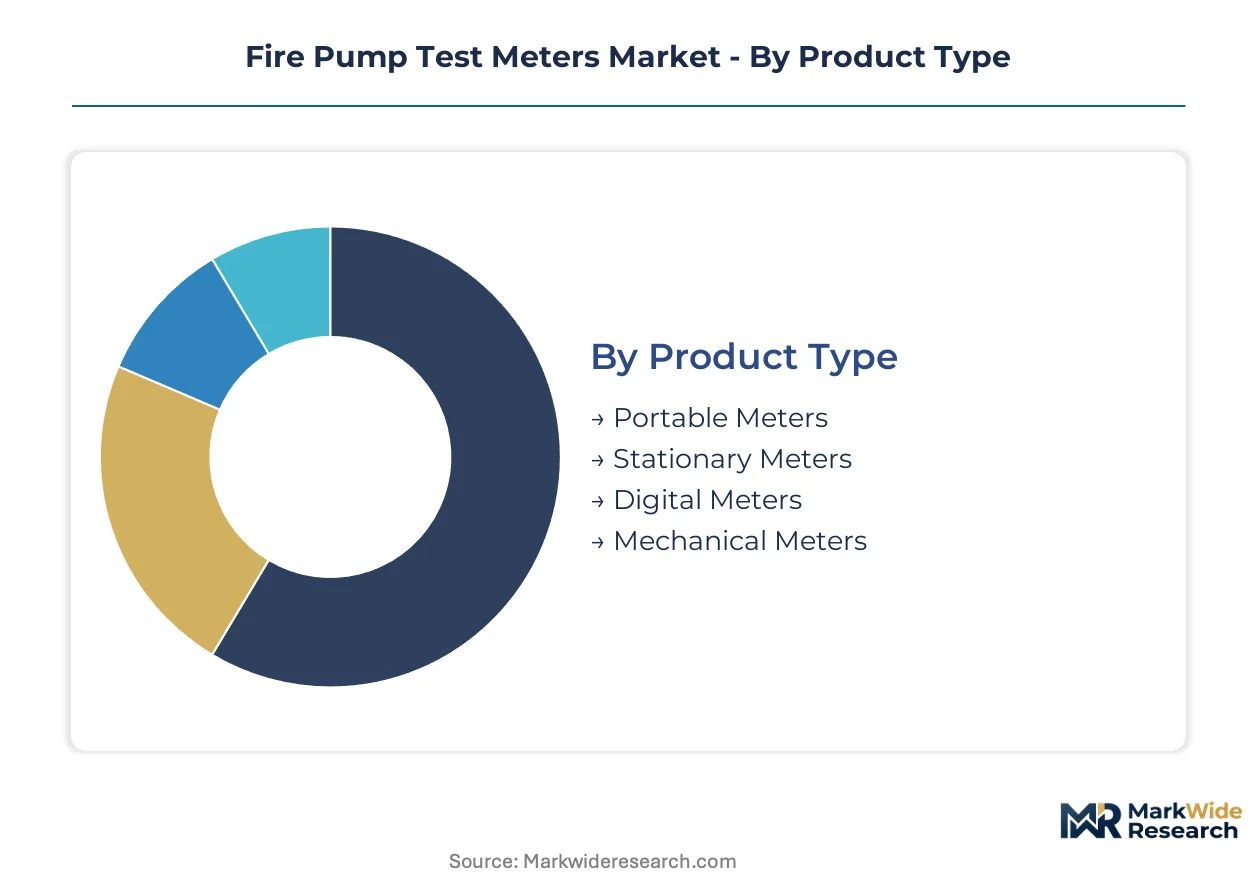
Fire pump test meter procurement patterns diverge sharply across product formats, sensing architectures, and end-user compliance regimes. Understanding these fault lines clarifies where replacement cycles concentrate and which technology migrations reshape vendor economics.
Product Type:
Upgrade cycles favor formats that minimize installation disruption while satisfying documentation mandates.
- Portable Meters:Battery-powered units with clamp-on or quick-connect fittings enable contractors to service dispersed pump networks without system shutdown. German fire safety contractors deploy these across chemical processing clusters in North Rhine-Westphalia to satisfy VdS Schadenverhütung audit frequencies.
- Digital Meters:NIST-traceable electronic units with auto-generated compliance reports are displacing analog gauges in US municipal procurement. NFPA 25 digitization mandates force replacement of mechanical dial indicators in fire departments from California to Texas.
- Stationary Meters:Permanently installed configurations serve high-risk industrial facilities requiring continuous monitoring.
- Mechanical Meters:Legacy dial-and-pointer designs retain residual demand in budget-constrained maintenance departments.
Volume placements concentrate in Digital Meters; the faster expansion belongs to Portable Meters.
Technology:
Margin pools accrue to architectures with extended calibration intervals and minimal moving parts.
- Electromagnetic:Coil-based sensing eliminates mechanical wear and delivers ±0.5% accuracy tolerances for high-precision verification. China's GB fire protection standard enforcement in tier-two cities accelerates deployment for building code compliance audits.
- Ultrasonic:Clamp-on transducers measure flow without pipe intrusion, reducing installation downtime for active suppression systems. US water utilities specify these platforms for extended calibration stability across distributed infrastructure.
- Mechanical:Turbine and paddlewheel designs persist where capital constraints override precision requirements.
- Electronic:Solid-state platforms with integrated data logging bridge the gap between mechanical simplicity and digital documentation.
Revenue concentrates in Electromagnetic; Ultrasonic is climbing the fastest.
End User:
Procurement authority determines specification stringency and service contract attachment rates.
- Municipalities:State-level cooperative purchasing contracts consolidate buying power for fire departments and water utilities. These entities specify NIST-traceable documentation to satisfy AHJ enforcement across multiple jurisdictions.
- Industrial Facilities:German chemical processors under VdS guidelines demand precision flow verification for insurance compliance. Predictive maintenance convergence drives integration of vibration sensing with flow metering.
- Fire Departments:Frontline emergency services prioritize portable formats for rapid deployment during annual certification testing.
- Commercial Buildings:Facility management firms respond to EU CSRD disclosure rules by prioritizing meters with native compliance reporting functionality.
Contract value concentrates in Municipalities; Industrial Facilities are gaining share fastest.
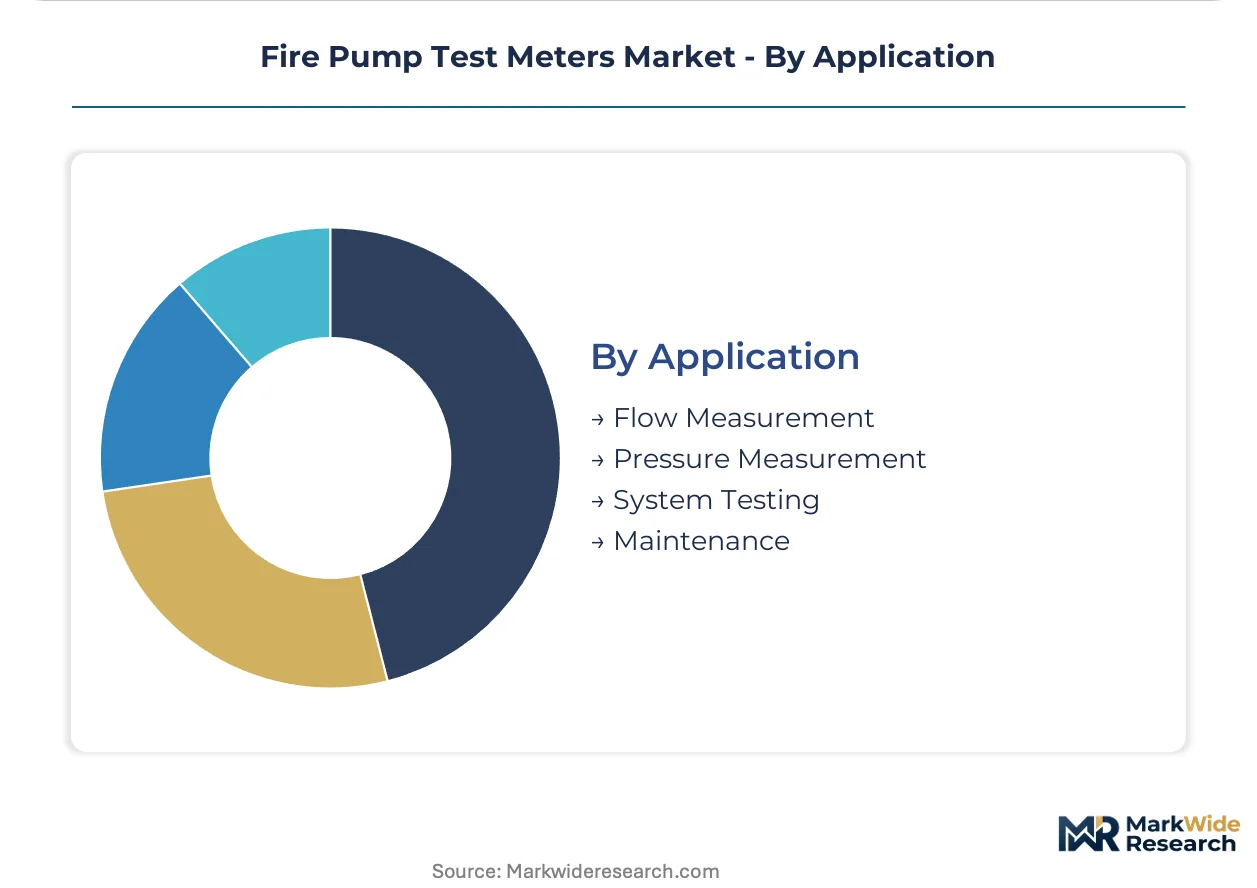
Application:
Use case specificity dictates sensor configuration and data output requirements.
- Flow Measurement:Volumetric rate verification against rated pump curves constitutes the core compliance function. Electromagnetic and ultrasonic platforms dominate where ±1% accuracy is mandatory.
- System Testing:Integrated pressure-flow logging captures comprehensive performance signatures for regulatory archives. Cloud-connected data loggers rebundle how contractors evaluate total cost of ownership.
- Pressure Measurement:Static and dynamic head verification complements flow data for complete pump characterization.
- Maintenance:Condition-based monitoring applications leverage trending data to predict component degradation before failure.
Deployment frequency concentrates in Flow Measurement; System Testing shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentrates in Germany and the United States, while consumption clusters in China, India, and the Gulf states where infrastructure buildouts outpace domestic precision instrumentation capacity.
United States
State-level cooperative purchasing contracts consolidate procurement authority for municipal fire departments across California, Texas, and Florida. NFPA 25 digitization mandates force replacement of analog gauges with NIST-traceable electronic units. Houston's petrochemical corridor drives precision meter demand for insurance-mandated pump certification.
Germany
VdS Schadenverhütung guidelines impose stringent flow verification requirements on chemical processing facilities in North Rhine-Westphalia and Bavaria. The EU Machinery Directive tightens traceability standards for safety-critical instrumentation. BASF's Ludwigshafen complex anchors industrial demand for electromagnetic platforms with extended calibration intervals.
China
GB fire protection standard enforcement accelerates in tier-two cities including Chengdu, Xi'an, and Wuhan. MIIT's smart building initiatives prioritize digital instrumentation for fire safety audits. The Yangtze River Delta's high-rise construction boom generates replacement cycles for legacy mechanical meters in Shanghai and Suzhou commercial towers.
India
BIS certification requirements and state-level fire safety audits expand procurement in Maharashtra and Gujarat. The country's national fire protection regulator tightens enforcement in Delhi-NCR and Bangalore IT corridors. Mumbai's coastal refinery cluster demands portable electromagnetic units for distributed pump network testing.
United Arab Emirates
Dubai's civil defense authority mandates annual pump certification for all high-rise buildings above 15 stories. MOHAP's building safety standards extend similar requirements to Abu Dhabi's healthcare and hospitality sectors. The Dubai South logistics district drives demand for cloud-connected data loggers integrated with facility management platforms.
Fire Pump Test Meters Market Vendor Landscape
The competitive structure tilts toward technology-differentiated specialists over volume commodity producers. Three tiers separate electromagnetic platform leaders, ultrasonic innovators, and residual mechanical meter suppliers. Consolidation pressure concentrates among municipal procurement channels where specification stringency favors established certification holders. Dominant competitive moves include sensor-software bundling and cooperative purchasing contract capture.
Within the precision instrumentation tier, Badger Meter Inc., Armstrong Fluid Technology, and Victaulic Company exemplify divergent positioning strategies. Badger Meter anchors premium municipal positioning through ultrasonic platform specialization. Armstrong Fluid Technology occupies the integrated systems vector with pump-and-meter bundling. Victaulic Company represents channel control dominance through distributor shelf space occupation in North American industrial facilities.
| Leading Market Players |
|---|
| Badger Meter Inc. |
| Armstrong Fluid Technology |
| Victaulic Company |
| Ayvaz |
| Gerand Engineering |
| Global Vision Inc. (GVI) |
| Dwyer Instruments Inc. |
| McCrometer |
| KROHNE Messtechnik GmbH |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up specialists in precision instrumentation have compressed distributor margins while extending payment terms to upstream coil manufacturers, embedding pricing discipline through captive service networks that lock municipal buyers into multi-year calibration contracts.
Pricing Analysis
Margin tightening in electromagnetic meter tiers reflects copper and rare-earth magnet cost volatility concentrated in Chinese processing facilities. Three-tier pricing structure across NIST-traceable premium units, standard digital configurations, and residual mechanical gauges separates procurement by certification grade and after-sales bundling intensity. Cost-down pressure on municipal accounts accelerates as state cooperative purchasing contracts consolidate volume and squeeze vendor margins. Fire safety contractors exhibit lowest price sensitivity due to compliance documentation requirements, while budget-constrained maintenance departments in smaller US municipalities drive economy-tier residual demand.
Supply Chain Analysis
Dual-sourcing requirements from German chemical processors and US water utilities mandate qualified suppliers across electromagnetic coil production in China, precision machining in Germany, and sensor assembly in the United States. Raw material dependencies center on neodymium magnets, copper windings, and specialized electronics from Taiwan semiconductor foundries. Single-source vulnerability in Chinese rare-earth processing creates supply chain risk exposure for electromagnetic platform manufacturers. Distribution runs through North American industrial distributors and direct municipal procurement platforms that disintermediate traditional channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
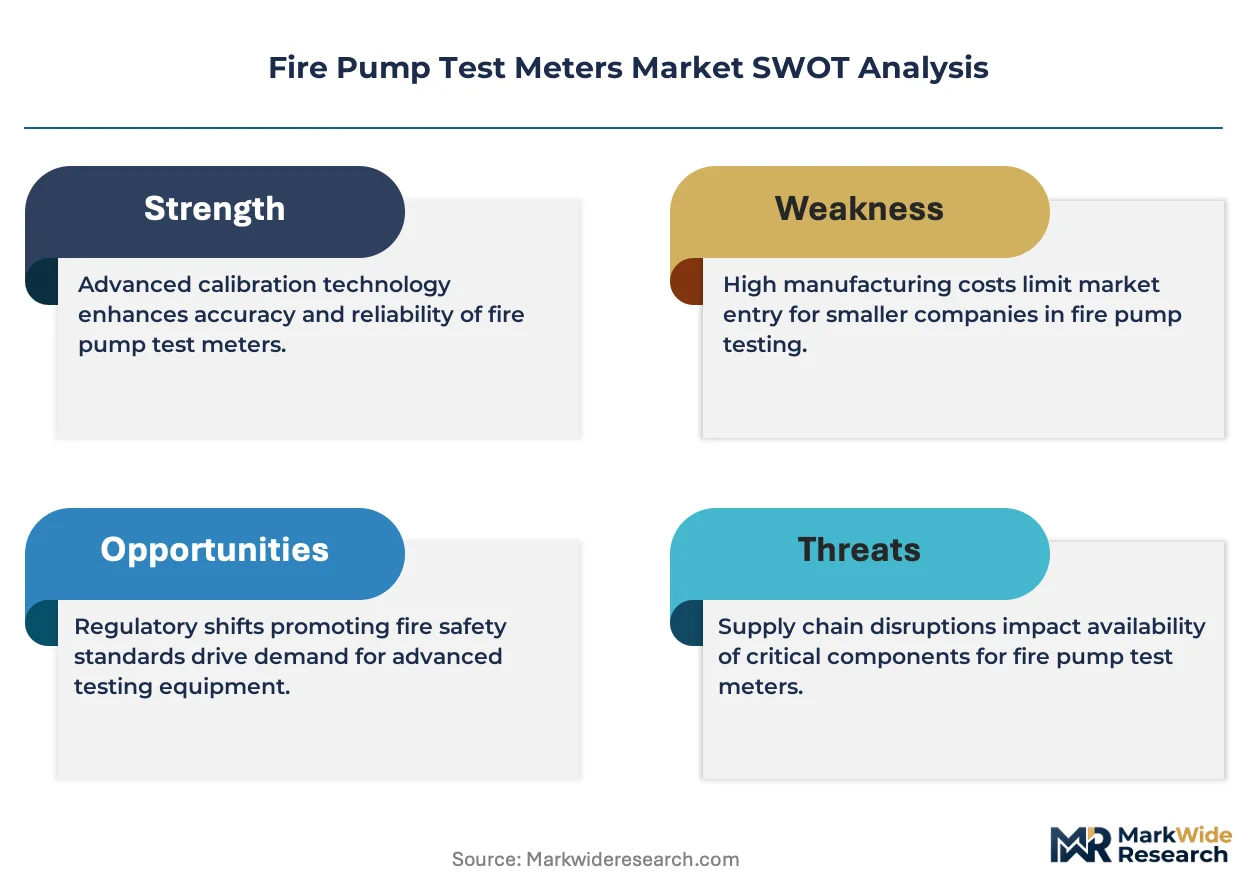
This market consolidates around certification-holding specialists as NFPA 25 digitization mandates and UL validation timelines force undercapitalized mechanical meter suppliers toward exit.
For Market Incumbents: Acquire field service calibration networks to anchor recurring revenue streams and defend against ultrasonic platform substitution. Deepen backward integration into electromagnetic coil production to offset Chinese rare-earth processing concentration. Capture state-level cooperative purchasing contracts before direct municipal procurement platforms fully disintermediate distributor channels. For New Entrants and Emerging Players: Launch via portable ultrasonic clamp-on configurations targeting tier-two Chinese cities accelerating GB standard enforcement. Exploit white-space in cloud-connected data logger bundling for US fire safety contractors managing distributed pump networks. Penetrate Indian industrial facilities in Maharashtra and Gujarat through BIS-certified electromagnetic platforms with localized calibration support. For Investors and Strategic Acquirers: Distressed-cycle entries favor electromagnetic platform specialists with UL certification and established municipal relationships in Texas and Florida. Long-term viability hinges on sensor-software convergence and predictive maintenance integration. Watch for inflection signals in tier-two Chinese city procurement acceleration and EU CSRD disclosure rule enforcement tightening traceability requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Software Bundling | Cloud-connected data loggers from Badger Meter reconfigure contractor total cost of ownership calculations. |
| Certification Investment | UL hazardous location approvals for electromagnetic designs extend validation timelines but lock out unqualified competitors. |
| Backward Integration | Captive coil production insulates Armstrong Fluid Technology from Chinese rare-earth magnet price volatility. |
| Channel Control Expansion | Victaulic's distributor shelf space dominance in North American industrial facilities limits entrant access. |
| Geographic Manufacturing Footprint | Regional assembly in Germany satisfies EU Machinery Directive traceability for BASF Ludwigshafen procurement. |
Methodological Framework
Independent corroboration across fire safety contractor interviews, municipal procurement officer consultations, and precision instrumentation distributor discussions underwrites the qualitative findings. Primary fieldwork engaged calibration technicians, plant engineers at chemical processing facilities, and aftermarket service heads at electromagnetic meter specialists. Secondary validation drew from NFPA technical committee filings, UL certification databases, VdS Schadenverhütung audit protocols, and Chinese MIIT smart building policy disclosures. Bottom-up unit demand modeling triangulated against top-down market sizing across technology and end-user segments.
Comparable-period anchoring to historical NFPA 25 enforcement waves and municipal replacement cycle timing established the forecast window baseline. The analytical framework segments by product format, sensing architecture, end-user compliance regime, and regional regulatory cluster throughout the projection horizon. CAGRs derive from technology migration curves calibrated to electromagnetic displacement rates and ultrasonic adoption trajectories. Forecast inputs incorporate copper price volatility indices and tier-two Chinese city building code audit acceleration patterns.
The model assumes a particular technology adoption path; alternative pathways for ultrasonic clamp-on platforms would alter the outlook if installation cost advantages accelerate beyond electromagnetic precision benefits. Forecasts reflect assumptions about NFPA digitization mandate enforcement consistency and rare-earth supply chain stability. Deviation in Chinese export restriction policy or US municipal budget contraction would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pumps and Control Devices
Sealless Magnetic Drive Pump Market
Pumps and Control Devices
Oil and Gas Pumps Market
Pumps and Control Devices
Middle East and Africa Positive Displacement Pumps Market
Pumps and Control Devices
Multistage Pump Market
Pumps and Control Devices
Sea Water Injection Pumps Market
Pumps and Control Devices
Ultra High Pressure Water Pump Market
Pumps and Control Devices
Plunger Pumps Market
Pumps and Control Devices
Global Variable Displacement Pumps Market
Pumps and Control Devices
Pumps and Trigger Spray Market
Pumps and Control Devices
Pressure Washer Pump Oil Market
Pumps and Control Devices
Liquid Dispensing Pump Market
Pumps and Control Devices
Spin-On Hydraulic Filter Market
Pumps and Control Devices
North America Submersible Pumps Market
Pumps and Control Devices
Vertical Inline Pumps Market
Pumps and Control Devices
Global Leak Detection Solutions Market
Pumps and Control Devices
Positive Displacement (PD) Sanitary Pumps Market