
 Oil and Gas Fishing Market | 2026-2036
Oil and Gas Fishing Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Fishing Market Intelligence
North American fishing tool manufacturers is expanding capacity to serve resurgent Permian Basin activity and offshore decommissioning campaigns. Schlumberger Ltd. leverages integrated drilling and evaluation portfolios to bundle fishing services with broader well construction contracts. Baker Hughes Co. anchors its position through advanced jar technology and real-time downhole telemetry systems. Halliburton Co. competes via specialized fishing assemblies designed for extended-reach horizontal wells.
Oil and gas fishing encompasses the retrieval of stuck drill pipe, casing, and downhole tools from wellbores using mechanical gripping devices, hydraulic jars, and milling assemblies typically rated for pressures exceeding 15,000 psi and temperatures above 350°F. The practice eliminates costly sidetracks and preserves original wellbore architecture in both conventional and unconventional reservoirs. Drill bits and fishing spears command the largest share of tool type revenue due to their universal deployment across intervention scenarios. Offshore operators represent the fastest-growing end user category as subsea completions and tieback systems multiply mechanical complexity and retrieval frequency.
The US Bureau of Safety and Environmental Enforcement enforces well control and equipment verification rules that elevate inspection and restoration service volumes. API Specification 7-1 governs tool dimensional tolerances and material grades, creating compliance barriers for non-certified suppliers. The EPA's offshore discharge limitations shape washover string design and fluid selection for marine environments. Stakeholders must monitor regulatory harmonization between the US Gulf of Mexico and North Sea jurisdictions as dual-certification requirements reshape procurement criteria for international service companies.
Market Dynamics
Deepwater decommissioning obligations in the US Gulf of Mexico are compressing intervention timelines and forcing operators to pre-position fishing assets closer to aging subsea infrastructure, reshaping service logistics and inventory deployment patterns across the value chain.
Growth Catalysts
- API Specification 7-1:Certification mandates for tool dimensional tolerances and material grades are elevating procurement standards, disqualifying uncertified suppliers and consolidating demand toward verified manufacturers.
- Subsea tieback proliferation:Complex completions in deepwater basins multiply mechanical failure points, elevating retrieval frequency and sustaining service contract volumes.
- US Bureau of Safety and Environmental Enforcement well integrity rules:Mandatory documentation and verification protocols drive inspection and remedial work, embedding fishing services into regulatory compliance workflows.
Market Restraints
- Specialized alloy supply concentration:Premium-grade chromium-molybdenum steel for high-pressure tools concentrates among a limited supplier base, exposing manufacturers to input cost volatility and lead time extensions.
- Technical limitation in ultra-HPHT environments:Standard fishing assemblies face reliability thresholds above 20,000 psi and 400°F, constraining addressable well depth and temperature ranges.
- EPA offshore discharge limitations:Fluid selection constraints for marine environments increase washover string complexity and compliance costs, compressing margins on standard intervention packages.
Strategic Opportunities
- Brazil pre-salt basin expansion:Underdeveloped deepwater reserves require specialized retrieval capabilities, creating white space for fishing service providers with HPHT-certified tool portfolios.
- Real-time downhole telemetry convergence:Integration of sensor arrays with jar technology enables predictive stuck-pipe avoidance, opening premium service tiers tied to drilling optimization contracts.
- EU Green Deal decommissioning timelines:Accelerated North Sea platform removal mandates are elevating demand for plug-and-abandonment fishing packages, rewarding early-mover certification under dual US-EU standards.
Industry Challenges
- HPHT systems engineering talent scarcity:The specialized skill set for designing retrieval tools rated above 15,000 psi concentrates among a shrinking cohort of experienced engineers, constraining R&D velocity.
- Dual-certification timeline compression:Service companies pursuing simultaneous US Gulf of Mexico and North Sea qualifications face extended validation cycles, delaying market entry and tying up capital in testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Fishing Market |
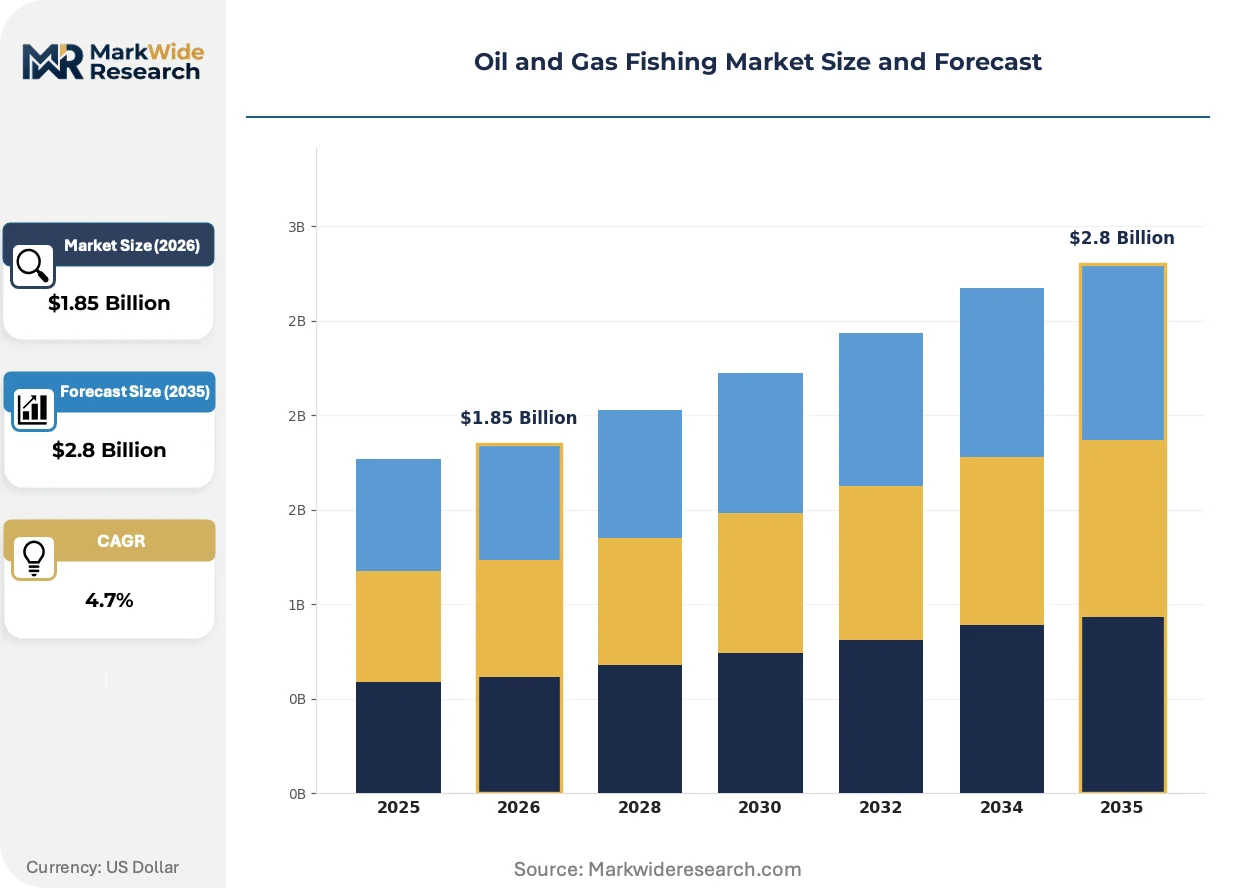
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Overhaul, Repair, Restoration, Inspection Tool Type: Drill Bits, Fishing Spears, Jars, Washover Strings End User: Offshore Operators, Onshore Operators, Service Companies, Drilling Contractors Application: Well Intervention, Remedial Operations, Fishing Operations, Recovery Operations |
| Companies Covered | Schlumberger Ltd., Baker Hughes Co., Halliburton Co., Weatherford International Plc, NOV Inc., Archer Norge AS, Bilco Tools Inc., Expro Group Holdings NV, Tasman Oil Tools Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Fishing Market Strategic Shifts & Innovations
Digital integration and predictive capability are displacing reactive intervention models, with operators demanding fishing systems that prevent stuck-pipe incidents rather than merely resolving them after occurrence.
Modular jar technology is modularizing intervention architecture by separating power generation, telemetry, and gripping functions into interchangeable subassemblies. Offshore contractors in the US Gulf of Mexico are adopting these configurations to reduce deck footprint and accelerate tool string reconfiguration between wells. This modularity is compressing mobilization timelines and enabling single-vessel deployment across multiple well architectures without shore-based refurbishment.
REACH substance restrictions in Europe are reshaping material specifications for fishing tools deployed in North Sea waters, particularly regarding chromium plating and lubricant formulations. Manufacturers serving EU-UK dual jurisdictions must maintain parallel inventory streams or absorb reformulation costs. The washover string segment faces the steepest compliance burden, as fluid systems fall under both offshore discharge and chemical registration frameworks.
Integrated service contracting is consolidating procurement decisions, with exploration companies bundling fishing services within broader well construction agreements rather than sourcing standalone retrieval packages. This compression is displacing independent tool rental channels in favor of vertically capable drilling contractors. The Permian Basin exhibits this pattern most acutely, where private equity-backed operators prioritize single-point accountability over specialized vendor fragmentation.
Oil and Gas Fishing Market Segmentation
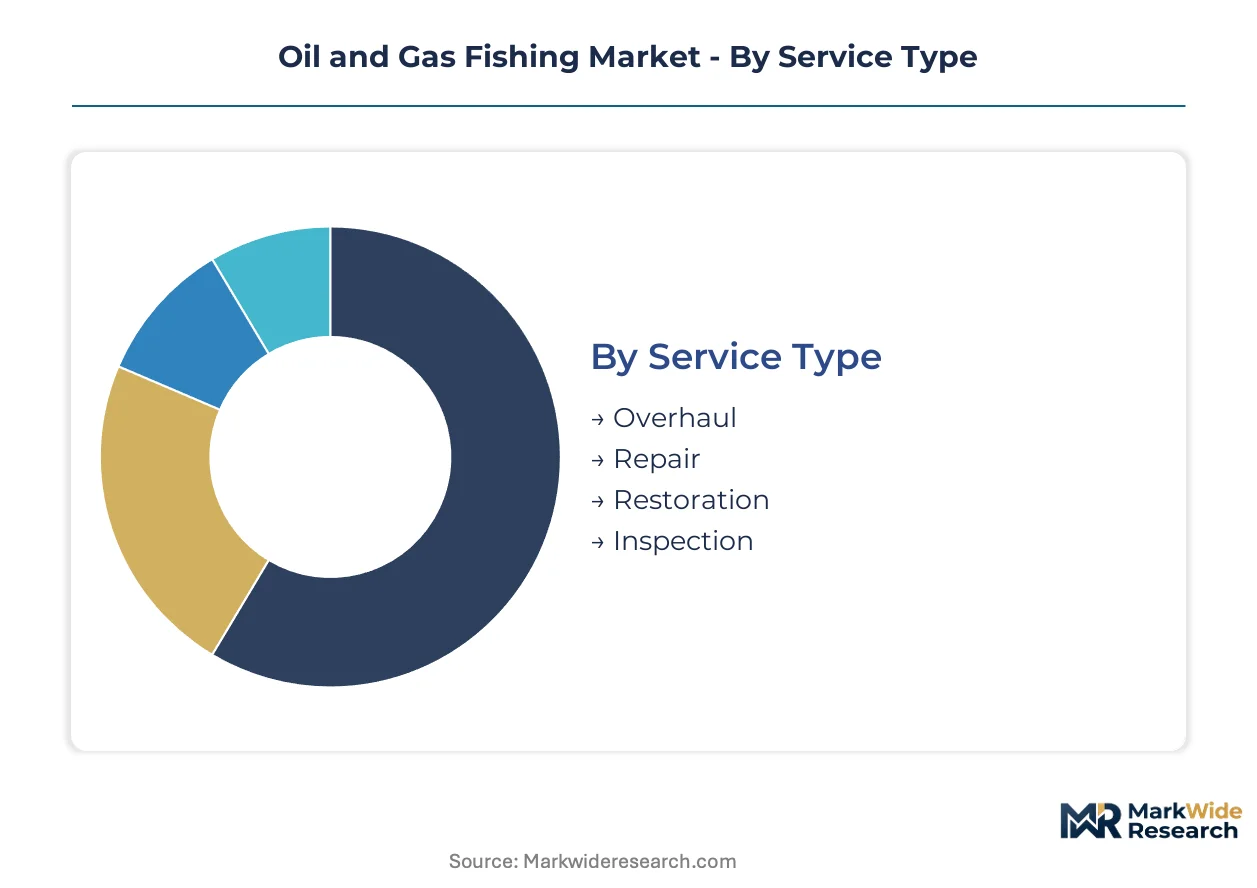
Segmentation in oil and gas fishing services reveals how procurement decisions split between reactive emergency response and planned maintenance cycles. Tool specifications, service bundling, and end-user sophistication create distinct commercial channels with diverging margin profiles and contract structures.
Service Type:
Standardization dominates overhaul and inspection workflows, while restoration demands bespoke engineering tailored to specific wellbore conditions and failure modes.
- Overhaul:Systematic refurbishment of retrieved fishing tools to OEM specifications, typically performed at shore-based facilities in Port Fourchon and Houston. Demand concentrates among drilling contractors operating standardized jar fleets across multiple basins, driven by asset utilization targets and capital preservation mandates.
- Repair:Field-level remediation of damaged gripping assemblies and jar components without full disassembly. Onshore operators in the Permian Basin represent the primary demand pool, prioritizing rapid turnaround over comprehensive refurbishment to minimize non-productive time during multi-well pad drilling.
- Restoration:Complex reconstruction of corroded or mechanically compromised downhole equipment, often requiring metallurgical analysis and welding of specialized alloys. Offshore operators facing decommissioning deadlines in the US Gulf of Mexico drive contract volumes.
- Inspection:Non-destructive testing and dimensional verification mandated by BSEE well integrity protocols. Service companies bundle these services with broader well construction contracts to satisfy regulatory documentation requirements.
Most installed capacity flows through Overhaul. Expansion is steepest in Inspection.
Tool Type:
Volume tiers separate universal deployment tools from specialized assemblies rated for extreme pressure-temperature environments.
- Drill Bits:Polycrystalline diamond compact and roller cone configurations constitute the most frequently retrieved objects, requiring fishing spears and washover strings for extraction. Offshore operators in deepwater basins generate sustained demand as bit failure rates climb in abrasive pre-salt and subsalt formations.
- Fishing Spears:Mechanical gripping devices with retractable slips designed to engage internal pipe diameters across multiple weight grades. Drilling contractors in the Permian Basin deploy these most intensively during extended-reach horizontal drilling where differential sticking incidents multiply.
- Jars:Hydraulic and mechanical impact tools delivering controlled upward or downward force to free stuck pipe. Advanced configurations integrate real-time telemetry for force monitoring.
- Washover Strings:Heavy-wall casing used to mill over and retrieve stuck objects, with marine-discharge-compliant fluid systems required for EPA-regulated offshore operations.
Procurement concentrates in Drill Bits. Technology investment is heaviest in Jars.
End User:
Customer sophistication spans integrated majors with captive engineering capabilities to independent contractors sourcing turnkey packages.
- Offshore Operators:Supermajors and independents operating subsea infrastructure in the US Gulf of Mexico, Brazil, and West Africa. These entities demand HPHT-certified tool portfolios and real-time operational support, driving premium service tiers.
- Onshore Operators:Privately held exploration companies and PE-backed producers concentrated in the Permian, Bakken, and Eagle Ford basins. Procurement favors bundled well construction contracts over standalone fishing services.
- Service Companies:Specialized intervention contractors maintaining tool inventories for rental and operated deployment. These intermediaries face margin compression as integrated drilling contractors absorb fishing capabilities.
- Drilling Contractors:Offshore and onshore rig operators with growing in-house fishing expertise, particularly among tier-one contractors with global fleet coverage.
Contract value aggregates highest with Offshore Operators. Account expansion is most rapid among Drilling Contractors.
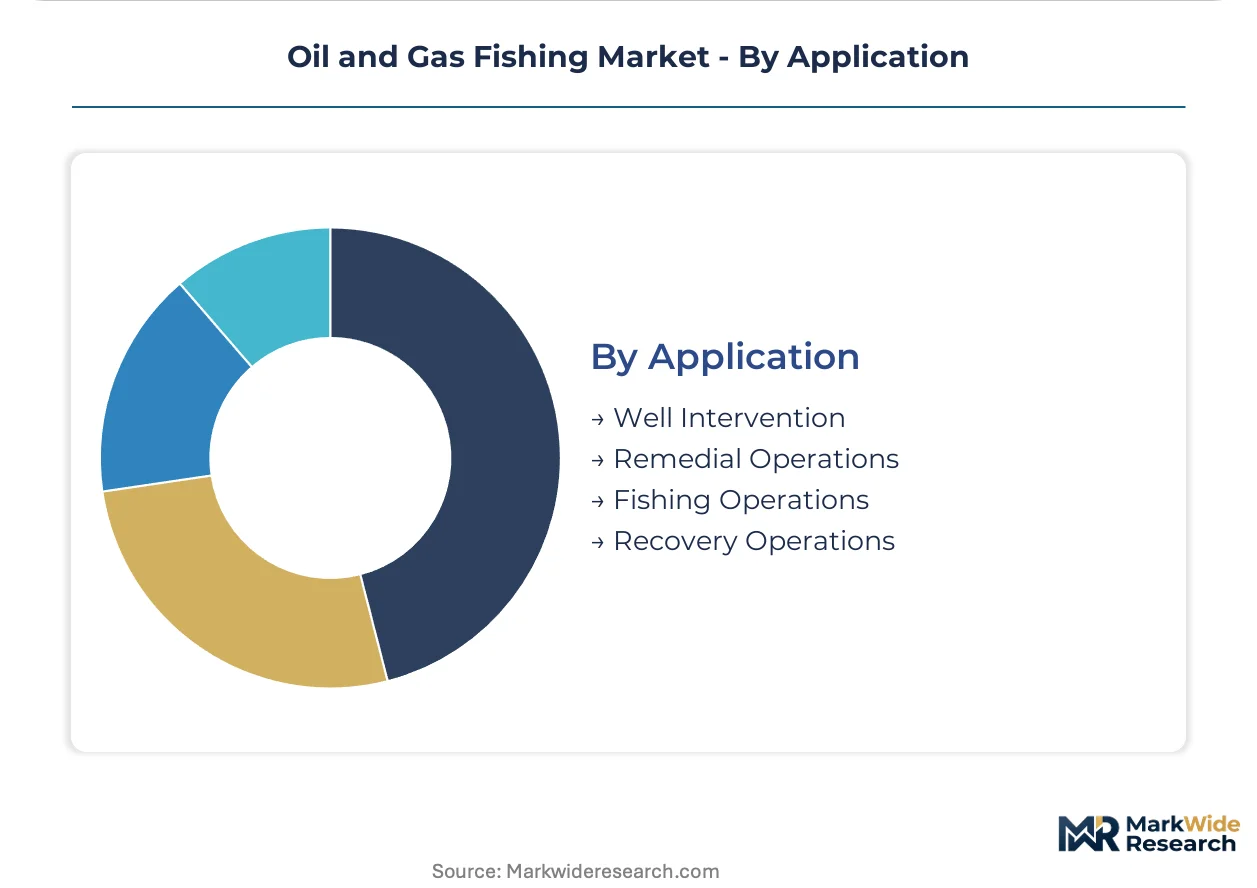
Application:
Operational urgency distinguishes planned interventions from emergency response, with diverging preparation timelines and pricing structures.
- Well Intervention:Scheduled retrieval operations during planned maintenance windows or completion modifications. Offshore tieback systems in the US Gulf of Mexico require frequent intervention as subsea trees age and mechanical complexity accumulates.
- Remedial Operations:Corrective work following well control incidents or equipment failures, often under regulatory scrutiny. BSEE documentation mandates elevate service intensity.
- Fishing Operations:Emergency retrieval of stuck drill string or downhole tools during active drilling, commanding premium mobilization rates and 24-hour operational coverage.
- Recovery Operations:Decommissioning-phase extraction of abandoned equipment prior to plug-and-abandonment certification, accelerating as US Gulf of Mexico infrastructure reaches end-of-design life.
Service hours accumulate most heavily in Well Intervention. Revenue per job is highest in Fishing Operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deepwater decommissioning timelines in the United States outpace Brazilian pre-salt field development, creating divergent procurement patterns across Atlantic basin markets. Regulatory stringency in the North Sea contrasts with Middle Eastern capacity expansion, fragmenting certification standards and service deployment models.
United States
Offshore operators in the Gulf of Mexico confront aging subsea infrastructure and compressed plug-and-abandonment schedules. The US Bureau of Safety and Environmental Enforcement mandates well integrity documentation that elevates inspection service volumes. Service companies cluster in Houston and Port Fourchon to pre-position fishing assets near decommissioning obligations.
Brazil
Pre-salt basin expansion drives specialized retrieval demand as ultra-deepwater completions multiply mechanical failure points. ANVISA and environmental licensing protocols shape tool qualification timelines for foreign service providers. Equipment fabricators concentrate in Rio de Janeiro state to support Petrobras-led intervention campaigns.
Norway
North Sea platform removal mandates under EU Green Deal timelines accelerate fishing package procurement. REACH substance restrictions reshape material specifications for chromium plating and lubricant formulations. Stavanger and Bergen anchor specialized tool refurbishment capacity serving dual US-EU certification requirements.
United Kingdom
Decommissioning expenditure in the UK Continental Shelf exceeds exploration budgets, redirecting service company focus toward recovery operations. The Health and Safety Executive enforces well abandonment standards that embed fishing services into regulatory compliance. Aberdeen maintains Europe's densest concentration of subsea intervention engineering talent.
Saudi Arabia
Aramco's offshore field development in the Arabian Gulf generates demand for HPHT-certified retrieval capabilities. Saudi Arabia's national oil company procurement standards favor integrated service contractors with captive tool manufacturing. Dammam and Jubail Industrial City host expanding fishing tool overhaul facilities serving regional drilling campaigns.
Oil and Gas Fishing Market Key Industry Players
US Gulf Coast producers anchor the premium-tier service segment; European specialists hold certification-intensive positions in North Sea decommissioning. The market exhibits consolidated tiering around integrated drilling contractors with captive fishing capabilities, alongside independent tool rental channels facing margin compression. Three archetypes dominate: vertically integrated majors bundling services within well construction contracts; specialized jar and telemetry technology developers; and regional overhaul facilities serving standardized fleet maintenance. Competitive dynamics center on dual-certification pursuit for US-EU market access and modular tool architecture development to compress mobilization timelines.
Among Houston-headquartered service conglomerates, Schlumberger Ltd., Baker Hughes Co., and Halliburton Co. occupy positions exemplifying the integrated contractor archetype. These entities represent the bundling strategy that displaces standalone fishing procurement in favor of single-point accountability within broader drilling contracts. Their scale enables parallel certification maintenance under API Specification 7-1 and North Sea regulatory frameworks, a capability that smaller regional competitors struggle to replicate.
| Leading Market Players |
|---|
| Schlumberger Ltd. |
| Baker Hughes Co. |
| Halliburton Co. |
| Weatherford International Plc |
| NOV Inc. |
| Archer Norge AS |
| Bilco Tools Inc. |
| Expro Group Holdings NV |
| Tasman Oil Tools Ltd. |
| Others |
Cost & Logistics Intelligence
HPHT systems engineering talent scarcity in Houston and Port Fourchon compresses R&D velocity while widening spreads between premium-certified and economy-tier service rates, as specialized labor costs feed directly into project-based pricing differentials across the Gulf of Mexico intervention market.
Pricing Analysis
Capacity additions in Brazil are reshaping price floors for HPHT-certified tool portfolios as ANVISA licensing timelines extend qualification costs for foreign entrants. Project-based contracting dominates, with price differentiation driven by API Specification 7-1 certification tier and real-time telemetry integration. Margins are tightening in standard jar segments due to integrated drilling contractor bundling. Onshore Permian operators exhibit highest price sensitivity; offshore supermajors prioritize performance guarantees over unit economics.
Supply Chain Analysis
API Specification 7-1 and REACH substance restrictions function as dual-certification gates that fragment supplier bases between US Gulf Coast and North Sea jurisdictions. Manufacturing concentrates in the United States, Norway, and Saudi Arabia. Raw material sourcing draws from chromium-molybdenum steel suppliers, polycrystalline diamond compact substrate providers, and marine-discharge-compliant fluid formulators. Single-source vulnerability runs through premium alloy supply channels. Distribution runs through shore-based facilities in Port Fourchon, Houston, and Aberdeen serving rig-adjacent logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil and gas fishing market operates as a regulatory compounder where BSEE well integrity mandates and EU Green Deal decommissioning timelines structurally embed service demand into compliance workflows regardless of drilling cycle volatility.
For Market Incumbents: Cement dual-certification maintenance under API Specification 7-1 and REACH frameworks as the primary defensive moat against regional specialists. Expand modular jar technology R&D to compress mobilization timelines for integrated drilling contractors. Counter margin pressure from bundled well construction contracts by embedding predictive telemetry capabilities that command premium service tiers.
For New Entrants and Emerging Players: The price-point gap between premium HPHT-certified and standard economy-tier services creates entry space for mid-market specialists. Target Brazil pre-salt basin expansion where ANVISA licensing delays disadvantage established players with rigid qualification timelines. Pursue washover string specialization under EPA marine-discharge frameworks as a differentiated go-to-market angle with lower capital intensity than full jar technology development.
For Investors and Strategic Acquirers: Integrated drilling contractors with captive fishing capabilities are the most active acquirer in this space, seeking technology tuck-ins that complete bundled service portfolios. Long-term viability rests on decommissioning obligation acceleration across Atlantic basin markets. Monitor BSEE plug-and-abandonment timeline compression as the inflection signal for recovery operations demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | API Specification 7-1 and REACH compliance unlocks US Gulf of Mexico and North Sea procurement channels simultaneously. |
| Modular Jar Technology Development | Separating power generation and telemetry functions reduces deck footprint for offshore contractors in Port Fourchon. |
| Real-Time Downhole Telemetry Integration | Sensor arrays with jar technology enable predictive stuck-pipe avoidance tied to drilling optimization contracts. |
| Brazil Pre-Salt Basin Market Entry | ANVISA licensing protocols create white space for HPHT-certified tool providers with flexible qualification timelines. |
| Decommissioning-Focused Recovery Operations | EU Green Deal platform removal mandates elevate plug-and-abandonment fishing package demand in Aberdeen and Stavanger. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drilling contractors, subsea intervention engineers, BSEE compliance officers, and tool manufacturing procurement leads with secondary validation through API specification databases, BSEE well integrity filings, SEC 10-K disclosures from integrated service providers, and offshore project development registries. Bottom-up segment sizing and top-down market triangulation cross-verified volume estimates across service type, tool category, and end-user archetype dimensions.
Historical reference periods anchored the projection horizon across the analysis window, with segmentation modeling spanning service type, tool specification tier, end-user sophistication level, and application urgency category. CAGRs were derived from fitted growth curves incorporating basin-specific drilling activity, regulatory milestone schedules, and fleet deployment patterns. Forecast inputs included subsea tieback proliferation rates and HPHT well count trajectories in deepwater basins.
Caveats apply where ANVISA licensing timeline shifts or BSEE enforcement intensity changes could materially shift the outlook. Forecasts reflect documented assumptions regarding decommissioning obligation schedules and alloy supply chain stability. A model refresh is warranted upon material change in dual-certification harmonization progress between US and EU regulatory frameworks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
United Arab Emirates Oil and Gas Market
Offshore Oil and Gas
Abyssinian Oil Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
China Oil and Gas Upstream Market
Offshore Oil and Gas
Offshore Oilfield Services Market
Offshore Oil and Gas
South America Offshore Seismic Survey Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Subsea Equipment Market
Offshore Oil and Gas
Asia Pacific Oil and Gas CAPEX Market
Offshore Oil and Gas
Equatorial Guinea Oil and Gas Downstream Market
Offshore Oil and Gas
Global Mobile Offshore Drilling Units Market
Offshore Oil and Gas
Marine Mining Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
India Oil and Gas Upstream Market