
 Dedicated Server Hosting Market | 2026-2036
Dedicated Server Hosting Market Size, Share, and Industry Trends Forecast 2026-2036
Dedicated Server Hosting Market Intelligence
The gap between bare-metal commodity servers and fully managed enterprise-grade infrastructure is realigning procurement patterns across the hosting industry. Liquid Web leverages premium support tiers and managed security stacks to sustain margins in the mid-market segment. Hetzner anchors European price-competitive positioning through automated provisioning and owned datacenter assets in Germany and Finland.
Dedicated server hosting delivers single-tenant physical compute resources with guaranteed CPU, RAM, and storage allocations, typically housed in carrier-neutral facilities with redundant power and network connectivity. The primary commercial purpose centers on predictable performance for latency-sensitive applications and regulatory isolation requirements. Rack servers dominate volume shipments for hyperscale and colocation deployments, while blade configurations concentrate in high-density financial services and media rendering environments. Managed hosting services capture disproportionate margin pools as enterprises outsource infrastructure operations to specialized providers.
GDPR data residency rules, the EU AI Act infrastructure transparency requirements, and Germany's BSI IT-Grundschutz certification framework shape European procurement specifications and facility location decisions. In the United States, NIST cybersecurity frameworks and SEC disclosure rules for material cloud dependencies are elevating due diligence requirements for financial services deployments. Stakeholders must monitor evolving sovereignty mandates and energy efficiency standards that will determine facility viability and customer retention across key European and North American markets.
Market Dynamics
Data sovereignty mandates are fragmenting procurement patterns across the dedicated server hosting landscape, forcing providers to establish certified facilities in jurisdiction-specific locations rather than optimizing for cost alone.
Growth Catalysts
- EU AI Act infrastructure transparency:The regulation mandates documented hardware provenance for high-risk AI deployments, driving demand for auditable single-tenant environments with chain-of-custody documentation.
- Financial services latency arbitrage:High-frequency trading firms require sub-millisecond connectivity to exchange matching engines, creating premium pricing power for strategically located bare-metal deployments.
- Germany's BSI IT-Grundschutz certification:Federal procurement rules require this baseline security standard, channeling public sector workloads toward certified domestic facilities.
Market Restraints
- Electricity cost volatility:Datacenter power represents 60-70% of operational expenditure in European markets, exposing margins to grid pricing fluctuations and carbon levy escalations.
- Subsea cable concentration:Transatlantic connectivity depends on a handful of landing stations in Portugal, Ireland, and the United Kingdom, creating single-point-of-failure risks for intercontinental latency guarantees.
- Server hardware lead times:GPU-accelerated and high-core-count processor availability remains constrained by foundry capacity allocation, extending deployment timelines for compute-intensive workloads.
Strategic Opportunities
- Nordic renewable energy arbitrage:Norway and Finland offer surplus hydroelectric and wind capacity at sub-European-average rates, enabling carbon-neutral positioning without renewable energy certificate purchases.
- Confidential computing hardware:AMD SEV and Intel TDX enable encrypted memory processing, opening regulated healthcare and government segments previously blocked by data-in-use security requirements.
- Edge federation models:Distributed micro-datacenters in secondary cities reduce last-mile latency for autonomous vehicle telemetry and industrial IoT command loops.
Industry Challenges
- Datacenter engineering talent scarcity:Facility design, thermal management, and high-voltage electrical expertise command premium compensation, constraining expansion velocity for mid-tier operators.
- Legacy workload migration friction:Mainframe-dependent financial institutions face multi-year refactoring timelines to achieve cloud-native portability, delaying infrastructure refresh cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dedicated Server Hosting Market |
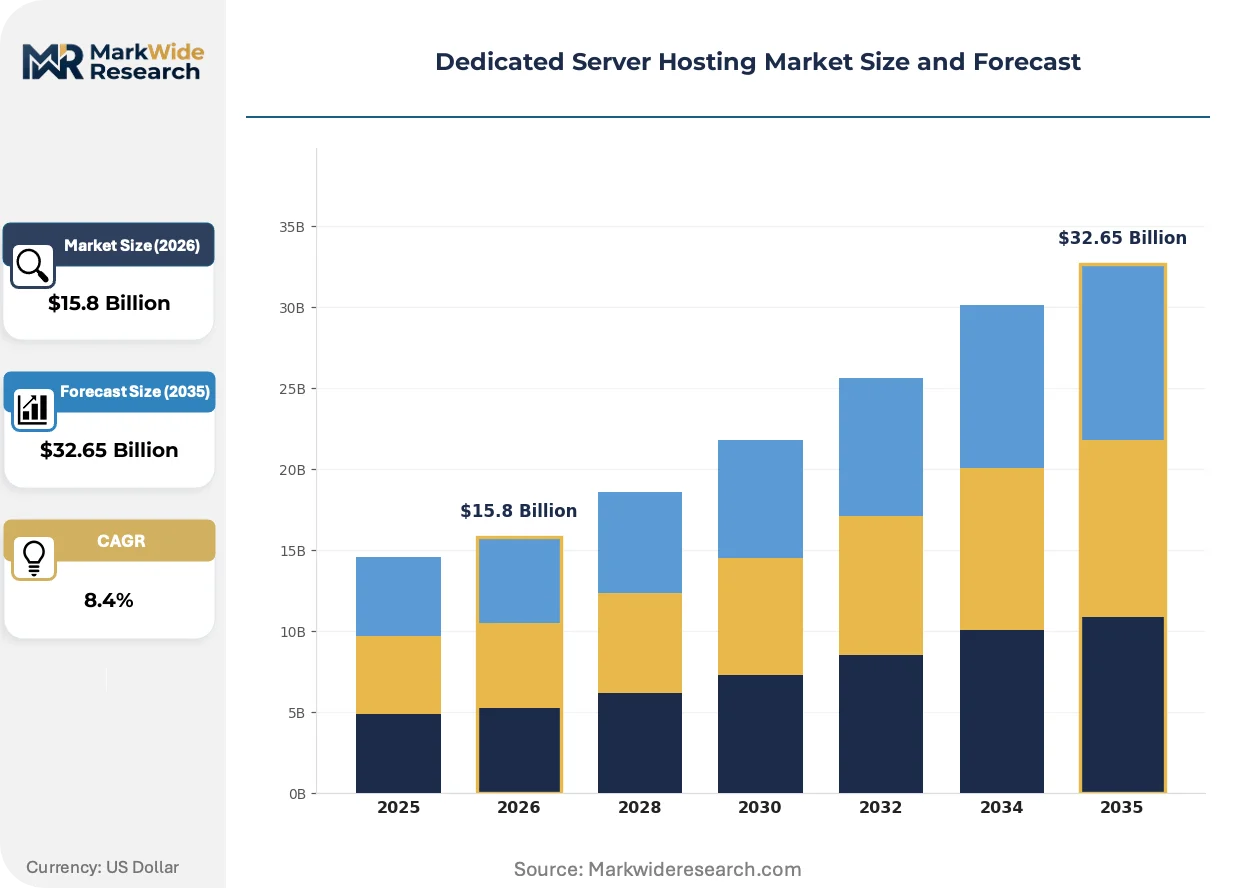
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $32.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Colocation, Managed Hosting, Cloud-Integrated, Hybrid Server Type: Single Processor, Dual Processor, Blade Servers, Rack Servers, Tower Servers Application: Web Hosting, Big Data Analytics, E-commerce Platforms, Gaming Servers, Content Delivery End User: Telecom Providers, Financial Services, Government Agencies, Media & Entertainment, Educational Institutions |
| Companies Covered | Liquid Web, Unihost, ServerMO, InMotion Hosting, ReliableSite, Hetzner, ColoCrossing, Atlantic.Net, OVHcloud, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dedicated Server Hosting Market Strategic Shifts & Innovations
Liquid cooling architectures and sovereignty-compliant facility designs are redrawing competitive boundaries, separating capital-intensive specialists from commodity colocation providers.
Direct-to-chip liquid cooling is absorbing thermal loads from 500W+ processors and accelerators that air-cooled systems cannot manage. Hyperscale cloud builders and AI training clusters are adopting this technology fastest. The shift is absorbing rack density limitations that previously constrained floor space efficiency in premium urban locations.
CSRD sustainability disclosure rules now mandate Scope 3 emissions reporting for EU-headquartered enterprises using third-party infrastructure. This forces hosting customers to demand verified power usage effectiveness metrics and renewable energy certificates from suppliers. Financial services and pharmaceutical verticals in Frankfurt and Amsterdam are screening providers against Science Based Targets initiative alignment.
Reserved capacity contracts with take-or-pay structures are displacing month-to-month bare-metal rentals among enterprise buyers. Procurement teams in regulated industries prioritize cost predictability over elasticity, locking three-to-five-year terms with fixed unit pricing. This pattern concentrates most visibly in German automotive and industrial automation sectors sourcing manufacturing execution system hosting.
Dedicated Server Hosting Market Segmentation
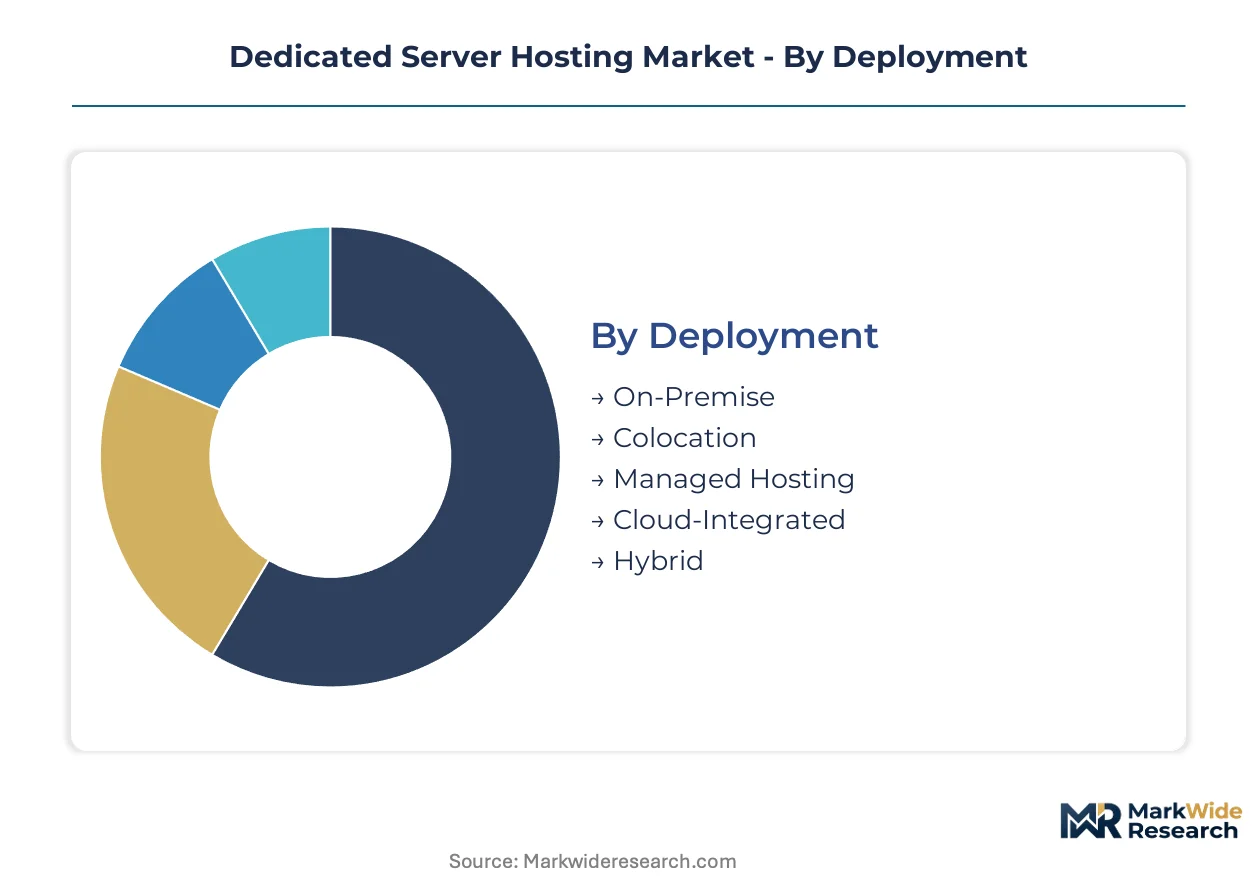
Dedicated server hosting procurement splits across deployment models, hardware configurations, and vertical requirements. Each segmentation axis reveals distinct margin structures, compliance obligations, and vendor specialization patterns that shape competitive positioning.
Deployment:
Technology ownership and operational responsibility define the deployment spectrum from captive facilities to fully outsourced infrastructure.
- On-Premise:Enterprise-owned datacenters with self-managed power, cooling, and network infrastructure. Financial services firms in Frankfurt and Singapore maintain captive facilities for sub-millisecond trading latency and regulatory isolation from multi-tenant environments.
- Managed Hosting:Providers assume full operational responsibility including hardware procurement, patch management, and security monitoring. Healthcare and pharmaceutical enterprises in Germany favor this model to satisfy BSI IT-Grundschutz certification requirements without building internal SRE teams.
- Colocation:Customers supply servers while providers deliver rack space, power, and cross-connects. Demand clusters in Amsterdam and London where carrier-neutral facilities offer dense peering fabrics for content delivery networks.
- Cloud-Integrated:Bare-metal resources provisioned through API-driven control planes with hourly billing granularity. AI training workloads and batch analytics pipelines drive adoption among autonomous vehicle developers and quantitative research funds.
- Hybrid:Orchestrated workloads spanning owned infrastructure and third-party dedicated resources. German automotive manufacturers deploy this architecture to keep proprietary CAD data on-premises while bursting rendering workloads to external GPU clusters.
Mature deployment sits with Colocation. Newer deployment is concentrated in Cloud-Integrated.
Server Type:
Physical form factor and processor density determine thermal design power, floor space efficiency, and suitability for specific workload profiles.
- Rack Servers:Standard 1U to 4U chassis dominating volume shipments across hyperscale and enterprise deployments. Frankfurt and Amsterdam facilities report highest concentration for general-purpose compute and storage-heavy applications.
- Blade Servers:High-density shared infrastructure with centralized power and cooling delivering 10-20 servers per chassis. Investment banks and media rendering studios in London and Paris deploy these for HPC clusters where space constraints override per-unit cost premiums.
- Single Processor:Entry-tier configurations for light web serving and development environments. Small SaaS vendors and regional e-commerce platforms represent primary demand concentration.
- Dual Processor:Mainstream enterprise workhorse with balanced core count and memory bandwidth. Database hosting and virtualization consolidation drive procurement across mid-market IT departments.
- Tower Servers:Standalone vertical chassis for branch office and remote site deployments. Retail chains and distributed manufacturing facilities with limited rack infrastructure favor this form factor.
Volume leadership belongs to Rack Servers. Steepest expansion trajectory is observed in Blade Servers for AI inference workloads.
Application:
Workload characteristics dictate hardware specifications, network topology requirements, and service level agreement structures.
- E-commerce Platforms:Transaction-intensive environments requiring guaranteed compute isolation and PCI-DSS compliant network segmentation. German and UK retailers prioritize dedicated infrastructure over multi-tenant cloud during peak shopping periods.
- Big Data Analytics:Storage-heavy configurations with high-memory footprints for in-memory processing frameworks. Pharmaceutical research consortiums and quantitative hedge funds in Switzerland and the Netherlands drive specialized cluster procurement.
- Web Hosting:Standardized LAMP stack and containerized application serving. Marketing agencies and publishing houses represent price-sensitive demand concentrating in cost-optimized facilities.
- Gaming Servers:Low-latency multiplayer session hosting with DDoS mitigation and global anycast distribution. Nordic providers capture this segment through renewable-energy positioning and sub-20ms reach into Central European population centers.
- Content Delivery:Edge-optimized caching and origin shielding for video streaming and software distribution. Media platforms negotiate dedicated capacity at internet exchange points in Frankfurt, London, and Amsterdam.
Established revenue concentration rests with Web Hosting. Gaining share fastest is Big Data Analytics for enterprise AI pipelines.
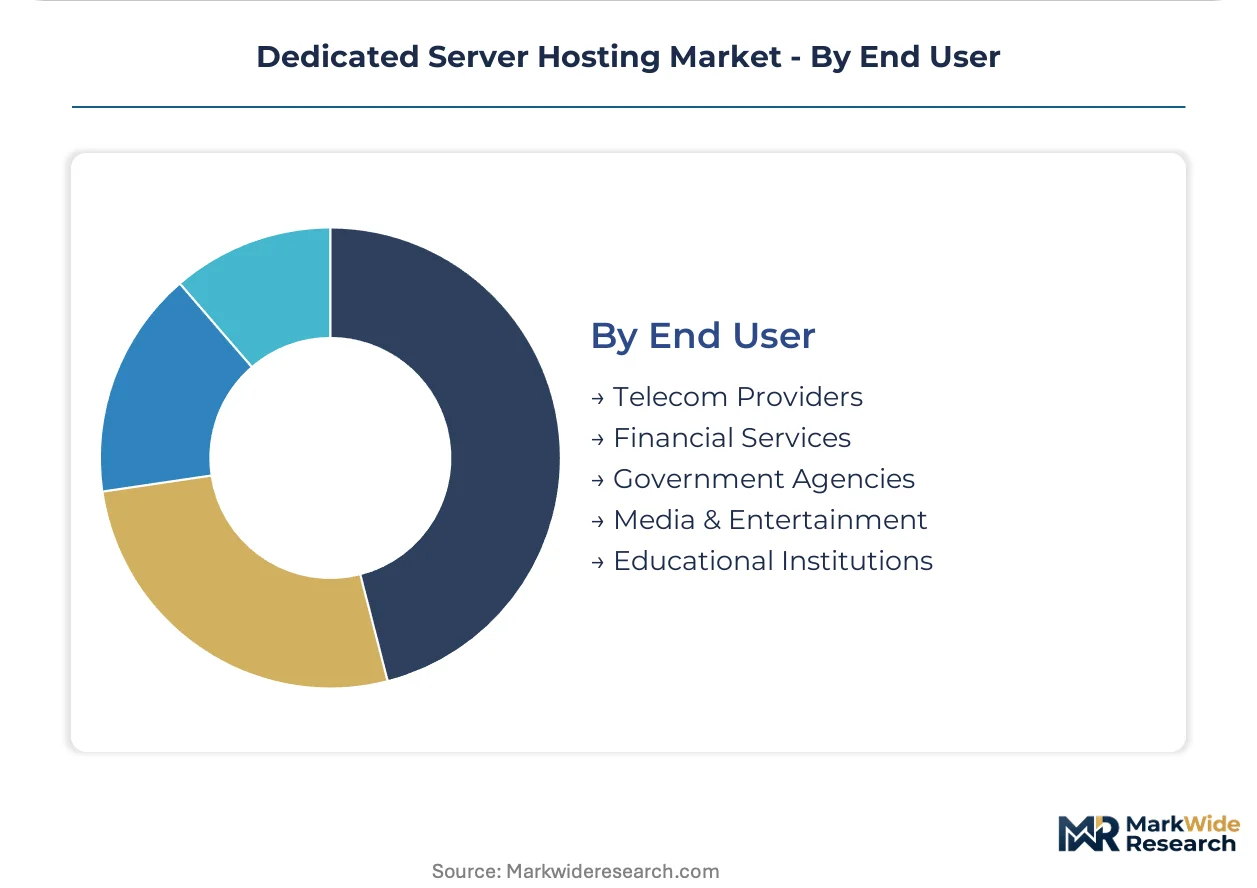
End User:
Vertical-specific compliance mandates and performance requirements create distinct procurement patterns across customer categories.
- Financial Services:Regulated institutions with mandatory audit trails, encryption standards, and geographic data residency. Basel III operational risk frameworks and SEC disclosure rules for material cloud dependencies elevate due diligence requirements.
- Government Agencies:Sovereign infrastructure with classified processing tiers and citizen data protection obligations. Germany's federal procurement rules channel workloads toward BSI-certified domestic facilities exclusively.
- Telecom Providers:Network function virtualization infrastructure and subscriber data management systems. Incumbent operators in France and Italy maintain dedicated compute adjacent to core network elements.
- Media & Entertainment:Rendering farms and live streaming infrastructure with burst capacity requirements. Post-production houses in London and Munich negotiate reserved GPU clusters for film and broadcast workloads.
- Educational Institutions:Research computing and campus IT with grant-funded procurement cycles. University consortia in the Netherlands and Switzerland pool resources for shared HPC access.
Procurement maturity centers on Financial Services. Emerging demand is concentrating in Government Agencies responding to data sovereignty mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European dedicated server procurement through its dense concentration of financial exchanges and BSI-certified facilities serving latency-sensitive trading infrastructure.
United States
Financial services firms in Chicago and New York Metro drive demand for sub-millisecond connectivity to exchange matching engines. SEC disclosure rules for material cloud dependencies elevate due diligence requirements. Northern Virginia's datacenter corridor concentrates hyperscale and enterprise deployments adjacent to major internet exchange points.
Germany
Federal procurement rules mandate BSI IT-Grundschutz certification for public sector workloads. GDPR data residency requirements channel enterprise workloads toward domestic facilities exclusively. Hetzner operates owned datacenter clusters in Falkenstein and Nuremberg serving price-competitive European compute demand.
United Kingdom
Investment banks and media rendering studios in London deploy blade server configurations for HPC clusters where space constraints override cost premiums. The Financial Conduct Authority's operational resilience rules mandate documented infrastructure provenance. Slough and Docklands facilities concentrate carrier-neutral colocation capacity.
Netherlands
Amsterdam's AMS-IX peering density attracts content delivery networks and gaming platforms requiring edge-optimized caching. CSRD sustainability disclosure rules mandate Scope 3 emissions reporting for EU-headquartered enterprises. Science Based Targets initiative alignment now screens provider selection in pharmaceutical verticals.
France
Telecom providers maintain dedicated compute adjacent to core network elements in Paris and Marseille. The EU AI Act's infrastructure transparency requirements drive demand for auditable single-tenant environments. OVHcloud operates facilities in Roubaix and Strasbourg serving sovereign cloud procurement.
Dedicated Server Hosting Market Key Industry Players
Premium-margin players sit above commodity-margin players across managed service depth and certification breadth. The vendor base organizes into three tiers: hyperscale cloud integrators with API-driven provisioning, regional specialists with owned facility assets, and managed security providers with vertical-specific compliance expertise. Strategic moves concentrate on reserved capacity contracting with take-or-pay structures and direct-to-chip liquid cooling deployments for AI training clusters.
Within the European price-competitive tier, Hetzner and OVHcloud exemplify facility-ownership archetypes leveraging automated provisioning and renewable energy positioning. Liquid Web occupies a position in the managed security tier with premium support structures serving mid-market healthcare and financial services verticals.
| Leading Market Players |
|---|
| Liquid Web |
| Unihost |
| ServerMO |
| InMotion Hosting |
| ReliableSite |
| Hetzner |
| ColoCrossing |
| Atlantic.Net |
| OVHcloud |
| Others |
Cost & Logistics Intelligence
Facility ownership with captive power infrastructure anchors both supply security and pricing power for European providers serving sovereignty-sensitive workloads. Hetzner's owned datacenters in Falkenstein and Nuremberg demonstrate how vertical integration into renewable energy sourcing and automated provisioning creates defensible margin structures against wholesale-reliant competitors.
Pricing Analysis
Uptime guarantees and latency SLAs function as the core value-based pricing anchor for financial services deployments. Three-tier pricing structure across premium managed security, standard colocation, and economy bare-metal tiers separates compliance-certified facilities from commodity compute pools. Price differentiation rests on BSI IT-Grundschutz certification status and renewable energy verification under CSRD rules. Cost compression in the economy bare-metal tier is intensifying because Hetzner and OVHcloud automate provisioning at scale. Small SaaS vendors and regional e-commerce platforms exhibit highest price sensitivity; regulated financial institutions and federal agencies demonstrate lowest sensitivity due to mandatory compliance requirements.
Supply Chain Analysis
Dual-sourcing requirements for GPU accelerators and high-core-count processors are mandating multi-supplier qualification across AMD and Intel foundry allocations. Server hardware supply concentrates in Taiwan, South Korea, and the United States for advanced semiconductor fabrication. Raw material dependencies include silicon wafers, rare earth elements for magnetics, and copper for high-voltage power distribution. Single-source vulnerability in foundry capacity allocation creates deployment timeline risk for AI training clusters. Distribution runs through direct OEM relationships with Dell, HPE, and Supermicro for enterprise configurations, supplemented by white-box assemblers for hyperscale volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
A vertical-integration race is reshaping competitive positioning as providers pursue captive renewable energy supply to neutralize electricity cost volatility and satisfy carbon disclosure mandates.
For Market Incumbents: To counter margin erosion from automated provisioning at facility-ownership competitors, Liquid Web and premium managed hosting specialists should deepen backward integration into security operations centers and compliance documentation workflows. Capacity addition in Nordic hydroelectric zones offers carbon-neutral positioning without renewable energy certificate purchases. Certification investment in confidential computing hardware enables healthcare and government segment expansion previously blocked by data-in-use security requirements. For New Entrants and Emerging Players: The price-point gap between premium managed security tiers and economy bare-metal rentals creates white-space opportunity for mid-market hybrid orchestration specialists. Edge federation models in secondary European cities represent the most penetrable geography, serving autonomous vehicle telemetry and industrial IoT command loops with sub-10ms latency. A channel partnership strategy with systems integrators serving German automotive manufacturers accelerates customer acquisition without captive sales infrastructure. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by hyperscale cloud integrators seeking bare-metal API capabilities and regional facility assets. Long-term viability favors providers with owned renewable energy supply and BSI-certified domestic footprints in Germany. The signal to watch is reserved capacity contract volume with take-or-pay structures in automotive and industrial automation verticals, indicating durable revenue predictability.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Chip Liquid Cooling Deployment | Enables 500W+ processor density in premium urban locations where floor space constraints previously limited expansion. |
| Confidential Computing Hardware Certification | AMD SEV and Intel TDX unlock regulated healthcare and government segments blocked by data-in-use security requirements. |
| Reserved Capacity Contract Structuring | Take-or-pay terms with German automotive manufacturers deliver cost predictability preferred over elasticity. |
| Nordic Renewable Energy Sourcing | Norway and Finland hydroelectric positioning satisfies CSRD Scope 3 disclosure without certificate purchases. |
| Edge Federation Micro-Datacenter Buildout | Secondary city deployments reduce last-mile latency for autonomous vehicle telemetry and industrial IoT. |
Research Approach
SEC filings from publicly traded hosting providers, hyperscaler capex disclosures, and EU regulatory databases formed the secondary backbone for market sizing and competitive positioning assessment. Primary interviews with datacenter operations directors, cloud procurement officers at financial services firms, and facility engineering specialists validated infrastructure cost structures and deployment timelines. Bottom-up triangulation across server shipment data, power consumption metrics, and colocation lease rates reconciled with top-down spending estimates from enterprise IT budget surveys.
Bottom-up modeling of server unit economics and facility-level operational expenditures anchored volume and value outputs across the analysis window. Segmentation dimensions included deployment model, server type configuration, application workload, and end-user vertical with geographic regulatory cluster overlay. CAGRs were derived from fitted growth curves against historical infrastructure spending patterns and forward procurement intentions. Forecast inputs incorporated electricity pricing trajectories, foundry capacity allocation schedules, and sovereign compliance mandate implementation timelines.
Inputs from datacenter operators and enterprise procurement teams were available through the study window; gaps in confidential contract pricing and actual utilization rates introduce uncertainty bands around revenue concentration estimates. Deviation in Germany's BSI certification enforcement stringency or Nordic electricity export policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Global Telecommunication Equipment Cabinet and Racks Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Datacenter Infrastructure Services Market
Data Center Infrastructure
Norway Data Center Power Market
Data Center Infrastructure
Global Software Defined Infrastructure (SDI) Market
Data Center Infrastructure
Data Processing and Hosting Services Market
Data Center Infrastructure
China Data Center Construction Market
Data Center Infrastructure
Australia Data Center Market
Data Center Infrastructure
Switzerland Data Center Rack Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
Singapore Data Center Server Market
Data Center Infrastructure
Singapore Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market