
 Switzerland Data Center Rack Market | 2026-2036
Switzerland Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Data Center Rack Market Insights
Edge computing architectures and AI inference workloads is reconfiguring rack density requirements across Swiss facilities. Schneider Electric leverages integrated power and cooling modules to anchor premium positioning in Zurich's financial district. Rittal sustains manufacturing proximity advantages through its German-Swiss supply corridor. Green Datacenter differentiates via alpine-cooled, carbon-neutral facilities that attract ESG-mandated enterprise buyers.
A data center rack is a standardized metal frame engineered to mount servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications with load ratings between 1,000 and 3,000 pounds. Its primary purpose is to optimize spatial efficiency, cable management, and thermal airflow within controlled environments. Enclosed racks command margin pools where EMI shielding and physical security compliance drive specification decisions among Swiss banking clients. Colocation facilities represent the fastest-growing end-user channel as hyperscalers and regional cloud providers expand presence in Geneva and Basel. Modular installation types are displacing conventional on-premises builds where speed-to-deploy and capital flexibility outweigh customization requirements.
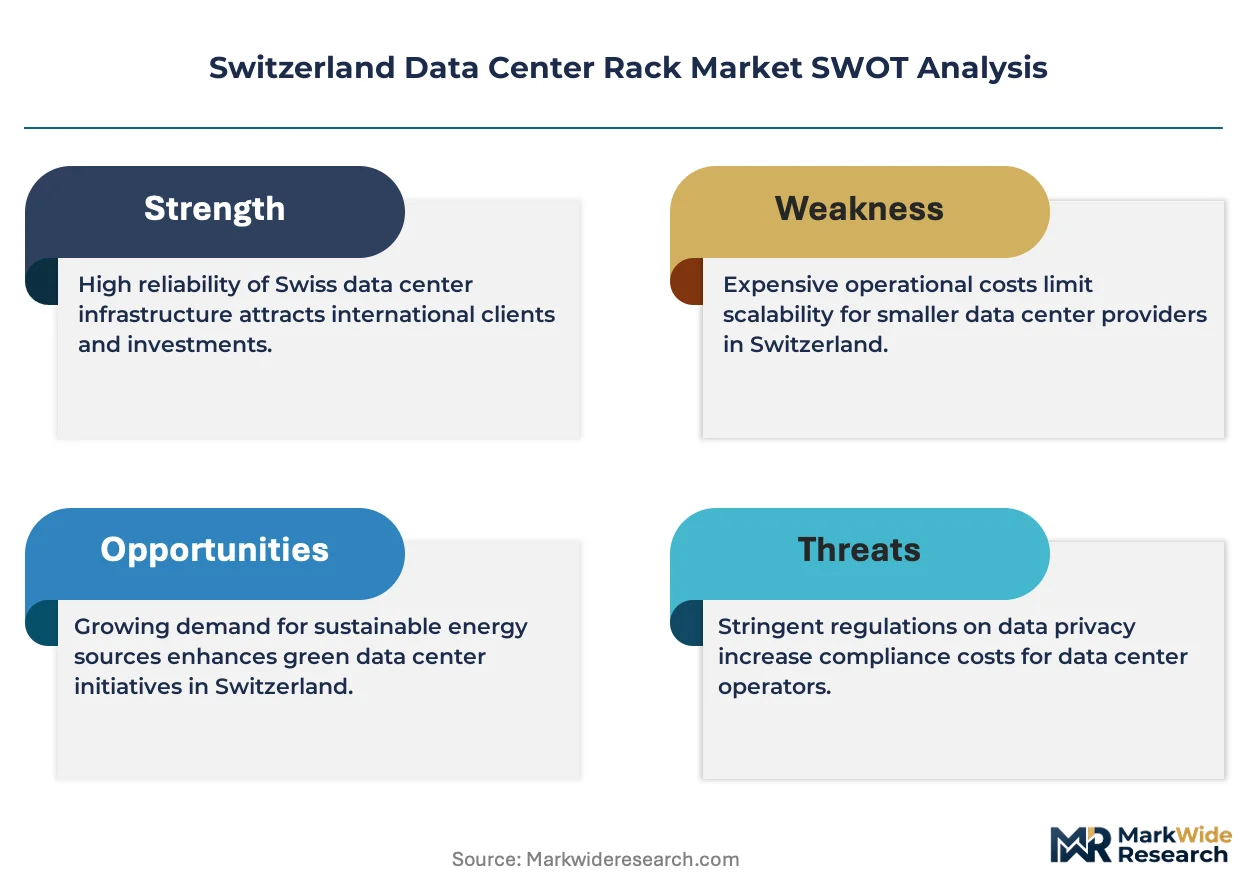
Swissmedic, the Swiss Federal Office of Communications (OFCOM), and FINMA collectively shape data handling standards that mandate domestic physical infrastructure for sensitive financial and health records. The country's adherence to GDPR-aligned Federal Act on Data Protection (FADP) revisions tightens cross-border data flow restrictions, reinforcing local rack demand. Stakeholders must weigh thermal design power trajectories against Switzerland's phased nuclear exit and renewable energy intermittency when sizing long-term capacity commitments.
Market Dynamics
Edge computing architectures and AI inference workloads are reconfiguring rack density requirements across Swiss facilities. The Swiss Federal Office of Communications enforces strict data sovereignty rules that favor domestic rack procurement over cross-border alternatives.
Growth Catalysts
- Financial services expansion:Zurich and Geneva banking clusters are expanding colocation footprints to host latency-sensitive trading infrastructure. This generates sustained demand for high-density, EMI-shielded rack configurations.
- FADP revisions:Switzerland's GDPR-aligned Federal Act on Data Protection tightens cross-border data flow restrictions. The regulation reinforces local rack demand for sensitive financial and health records.
- Modular build-outs:Speed-to-deploy and capital flexibility priorities are displacing conventional on-premises installations. Swisscom and Green Datacenter channel investment into modular configurations.
Market Restraints
- Energy intermittency:Switzerland's phased nuclear exit creates thermal design power trajectory uncertainty. Stakeholders must weigh long-term capacity commitments against renewable energy intermittency.
- Supply corridor concentration:Rittal's German-Swiss manufacturing proximity advantages create supplier concentration risk. Disruptions along this corridor would constrain domestic rack availability.
- Domestic procurement mandates:Swissmedic and FINMA data handling standards mandate domestic physical infrastructure. These requirements limit sourcing flexibility and extend procurement timelines.
Strategic Opportunities
- Alpine cooling integration:Green Datacenter's carbon-neutral facilities demonstrate alpine-cooled rack deployment viability. ESG-mandated enterprise buyers prioritize these configurations.
- Geneva-Basel expansion:Hyperscalers and regional cloud providers are expanding presence in secondary Swiss markets. Colocation facilities in these cities represent underpenetrated deployment zones.
- Integrated power-cooling modules:Schneider Electric's Zurich financial district positioning anchors premium rack-plus-infrastructure bundles. Technology convergence between rack, power, and cooling systems creates margin expansion potential.
Industry Challenges
- Specialized installation talent:Modular rack deployment requires technicians skilled in integrated power-cooling integration. The Swiss market faces constrained availability of certified installation specialists.
- Compliance timeline compression:FINMA and Swissmedic certification requirements for financial and health data infrastructure extend deployment cycles. Rack procurement must accommodate extended validation periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Data Center Rack Market |
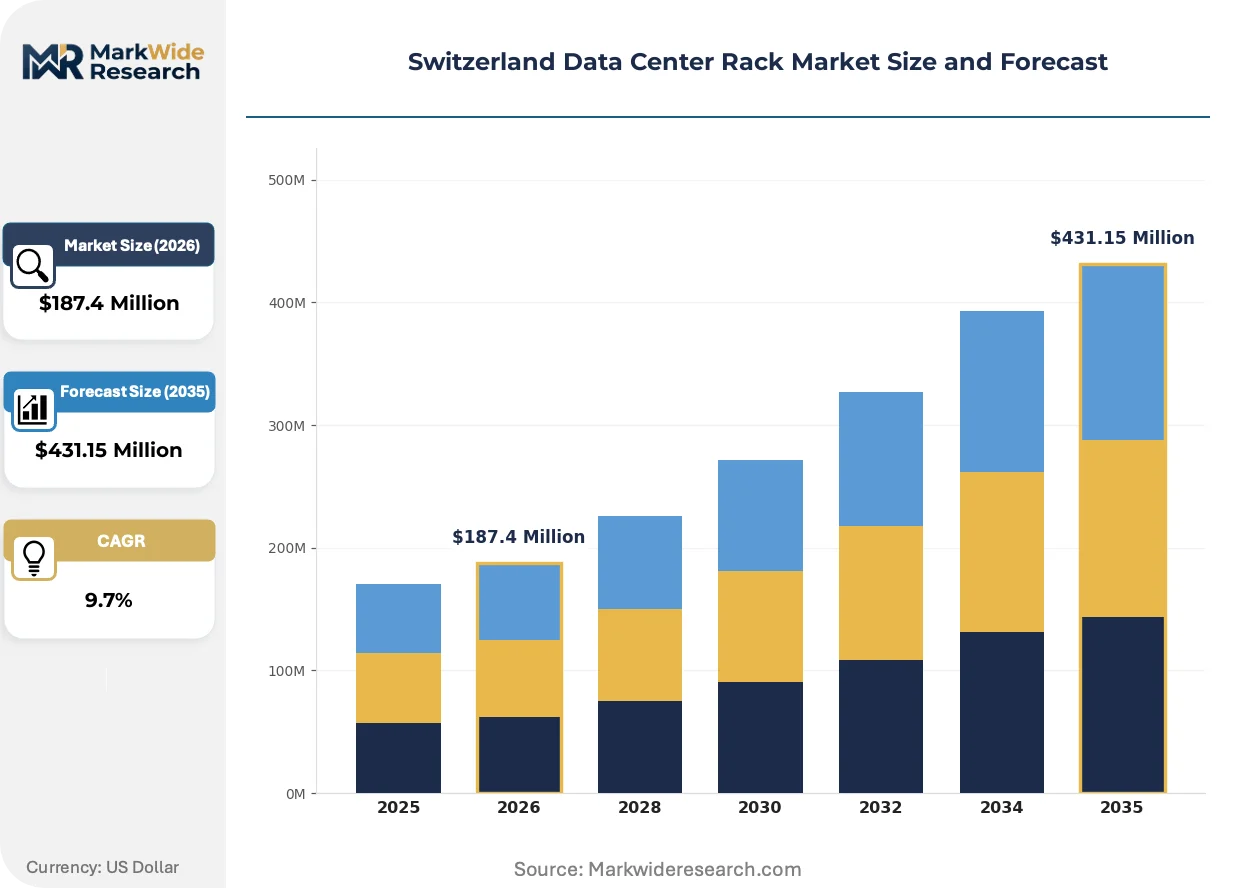
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $431.15 Million |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Rack, Enclosed Rack, Wall-Mounted Rack, Specialty Rack End User: Telecommunications, Cloud Service Providers, Enterprises, Colocation Facilities Rack Size: 42U, 45U, 48U, 24U Installation Type: On-Premises, Prefabricated, Modular, Custom-Built |
| Companies Covered | Schneider Electric, Eaton Corporation, Rittal, Vertiv Group, Equinix, Digital Realty, Green Datacenter, NTT Communications, Swisscom, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Data Center Rack Market Trends and Innovations
Liquid cooling integration and AI-optimized rack configurations are actively reshaping Swiss data center infrastructure specifications. These developments compress traditional thermal management paradigms while elevating power density thresholds.
Direct-to-chip liquid cooling systems are penetrating high-performance computing deployments across Zurich's financial district. Swiss banking clients are adopting these configurations to support GPU-intensive AI inference workloads. The technology is rendering obsolete air-cooled rack architectures above 30kW per cabinet.
FADP enforcement by Swiss Federal Office of Communications is tightening physical infrastructure localization mandates. The regulation requires domestic rack deployment for sensitive data categories. Financial services and healthcare verticals are responding with accelerated domestic colocation contracting.
Enterprise buyers are unbundling rack procurement from bundled facility contracts. Colocation customers now specify rack configurations independently of space and power agreements. This pattern is most visible among Geneva-based pharmaceutical and wealth management firms seeking vendor flexibility.
Switzerland Data Center Rack Market Segmentation
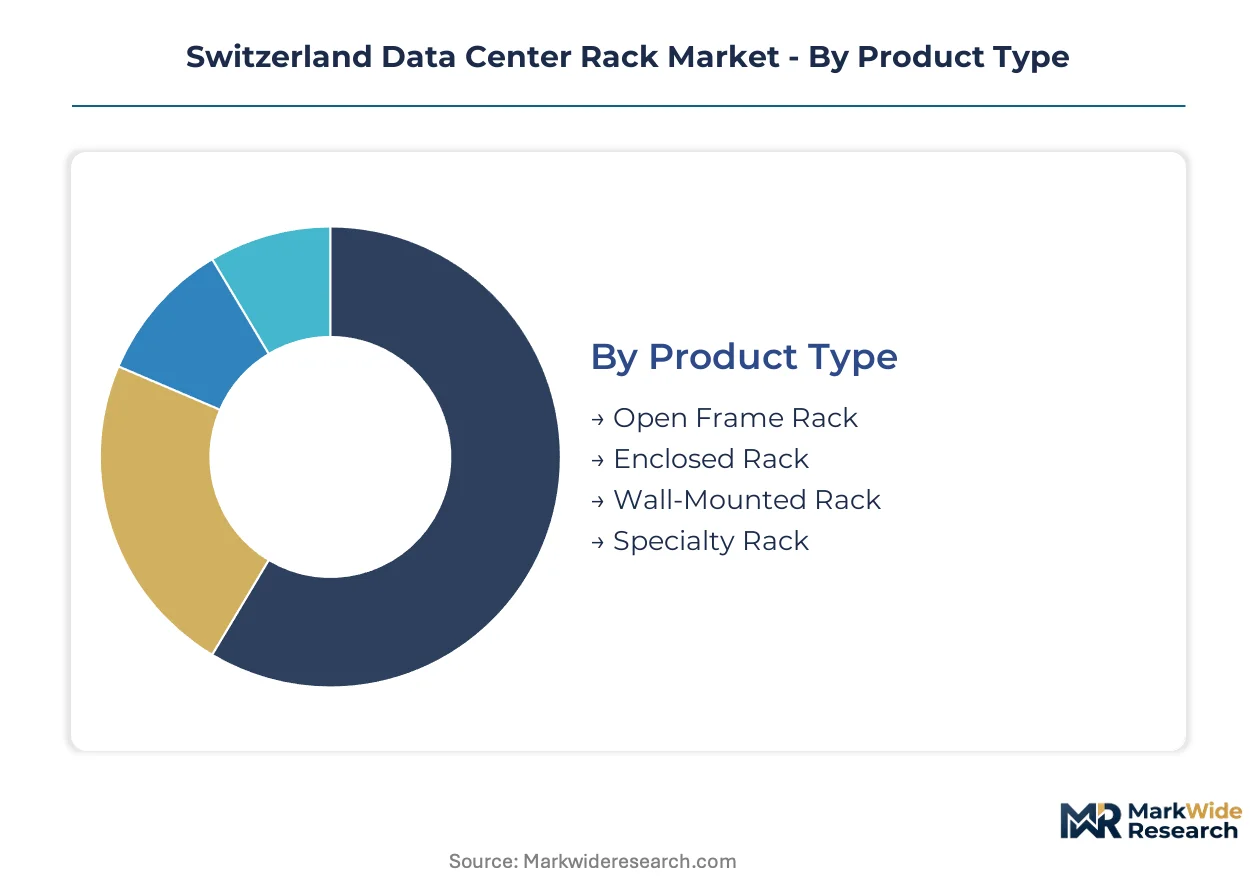
Swiss data center rack procurement patterns diverge sharply across product architectures and deployment models. FINMA compliance timelines and alpine facility constraints create distinct replacement cycles that reshape inventory planning for domestic suppliers.
Product Type:
Open frame racks turn inventory fastest in Zurich's trading floors where thermal loads shift quarterly, while enclosed racks lock in capital for years under Swiss banking security mandates.
- Enclosed Rack:EMI-shielded metal housings with lockable side panels and integrated cable management channels. Swiss private banks in Geneva specify these for client data segregation under FINMA physical security guidelines.
- Open Frame Rack:Four-post skeletal structures without side panels enabling unrestricted airflow. Cloud providers in Basel favor these for rapid GPU cluster reconfiguration as AI inference workloads evolve.
- Wall-Mounted Rack:Compact swing-out frames securing 12U-18U capacity to structural walls. Retail banking branches across Lausanne deploy these for edge transaction processing.
- Specialty Rack:Custom-width or seismic-rated variants for non-standard equipment. CERN's Geneva research campus sources these for particle detector data acquisition systems.
Enclosed rack configurations anchor the volume base while open frame architectures gain share at the steepest rate.
End User:
Cost tier stratification separates hyperscale cloud procurement from Swiss enterprise capital budgeting cycles.
- Colocation Facilities:Wholesale and retail datacenter operators providing rack-space-by-contract. Green Datacenter's alpine sites and Swisscom's Zurich facilities drive standardization demands for multi-tenant interoperability.
- Cloud Service Providers:Hyperscale and regional cloud operators deploying owned infrastructure. Microsoft and AWS expansion in Geneva-Basel corridor concentrates demand for 48U high-density configurations.
- Enterprises:Corporate IT departments maintaining captive data centers. Pharmaceutical headquarters in Basel prioritize FADP-compliant domestic rack deployment for clinical trial data.
- Telecommunications:Mobile and fixed-line carriers upgrading central office facilities. Swisscom's 5G edge rollout in Ticino shapes compact rack specifications for street cabinet integration.
Colocation facilities dominate current procurement volumes while cloud service providers expand most aggressively.
Rack Size:
Application-driven sizing splits financial services density requirements from distributed edge constraints.
- 48U:Extended-height cabinets accommodating liquid cooling manifolds and accelerated computing nodes. Zurich trading floors adopt these for AI-enhanced risk analytics clusters.
- 42U:Standard EIA-310-D height with broad equipment compatibility. Enterprise refresh cycles in Bern and Lucerne sustain baseline demand for this configuration.
- 45U:Intermediate height optimizing vertical space without facility retrofit. Regional banks in St. Gallen select these for branch consolidation projects.
- 24U:Half-height enclosures for constrained floorplates and edge locations. Retail POS aggregation points across Swiss Romandy deploy these under counter-height restrictions.
42U specifications retain the installed base majority while 48U formats climb the fastest.
Installation Type:
Supply concentration varies sharply between captive construction and outsourced modular delivery.
- Modular:Factory-integrated power and cooling modules shipped as complete units. Green Datacenter's Lupfig expansion demonstrates 12-week deployment timelines versus 18-month traditional builds.
- Prefabricated:Pre-wired rack assemblies with integrated PDUs and cable arms. Swisscom's enterprise colocation sales bundle these for speed-to-market advantages.
- On-Premises:Conventional site-built data centers with rack procurement separate from construction. Legacy pharmaceutical manufacturing facilities in Basel maintain this approach for GMP validation continuity.
- Custom-Built:Bespoke rack configurations for non-standard equipment or heritage building constraints. Private wealth management vaults in Zurich's Paradeplatz district require these for structural integration.
On-premises installation retains legacy dominance while modular approaches expand most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German-Swiss manufacturing corridors channel rack assemblies into Zurich and Geneva colocation facilities, while alpine cooling advantages concentrate deployment in central Swiss cantons.
Zurich Metropolitan Area
Private banking clusters and AI-enhanced trading infrastructure drive 48U high-density rack procurement. FINMA physical security guidelines mandate enclosed, EMI-shielded configurations for client data segregation. Paradeplatz financial district facilities integrate liquid cooling manifolds for GPU-intensive risk analytics workloads.
Geneva
Wealth management vaults and pharmaceutical headquarters generate demand for custom-built rack configurations under FADP data localization requirements. CERN's research campus sources specialty seismic-rated variants for particle detector systems. Hyperscale cloud expansion along the Geneva-Basel corridor concentrates 48U deployments.
Basel
Pharmaceutical manufacturing facilities maintain on-premises installations for GMP validation continuity. Clinical trial data hosting drives FADP-compliant domestic rack procurement. Regional banks select 45U intermediate-height enclosures for branch consolidation projects.
Central Switzerland (Lucerne, Zug, Schwyz)
Alpine-cooled carbon-neutral facilities attract ESG-mandated enterprise buyers seeking modular build-outs. Green Datacenter's Lupfig expansion demonstrates 12-week deployment timelines. Swisscom channels investment into prefabricated rack assemblies for speed-to-market advantages.
Ticino and Swiss Romandy
5G edge rollout shapes compact rack specifications for street cabinet integration. Retail banking branches deploy wall-mounted 12U-18U enclosures for edge transaction processing. Retail POS aggregation points utilize 24U half-height enclosures under counter-height restrictions.
Switzerland Data Center Rack Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Colocation operators and telecommunications carriers anchor the demand-side channel, while electrical infrastructure conglomerates and precision metalwork specialists populate the supply base. Consolidation pressure emanates from integrated power-cooling module convergence, with technology licensing and alpine facility partnerships representing dominant competitive moves.
Among electrical infrastructure conglomerates, Schneider Electric and Eaton Corporation occupy positions anchoring premium bundled offerings. Rittal exemplifies manufacturing-proximity advantages through German-Swiss supply corridor integration. Vertiv Group sits within the thermal management specialist tier alongside modular infrastructure providers.
| Leading Market Players |
|---|
| Schneider Electric |
| Eaton Corporation |
| Rittal |
| Vertiv Group |
| Equinix |
| Digital Realty |
| Green Datacenter |
| NTT Communications |
| Swisscom |
| Others |
Pricing and Supply Chain Analysis
The German-Swiss manufacturing corridor's freight cost dynamics compress margin pools for domestic rack suppliers while amplifying price differentiation between integrated power-cooling bundles and standalone frame procurement. Rittal's proximity advantages translate into cost-plus contract leverage that hyperscale buyers in Geneva-Basel increasingly index to aluminum and steel input benchmarks.
Pricing Analysis
Cost-plus contracts with steel and aluminum indexation dominate procurement between Swisscom and integrated infrastructure suppliers. Price differentiation rests on FINMA certification tier and liquid cooling manifold integration, with EMI-shielded enclosed racks commanding premium positioning over open frame alternatives. Pricing pressure stems from modular build-out speed demands compressing traditional on-premises margins. Cloud service providers exhibit highest price sensitivity, while private banking clients in Zurich's Paradeplatz district prioritize security compliance over unit cost.
Supply Chain Analysis
Supplier-financing facilities with 90-day extended terms have become standard for modular rack assemblies shipped through the German-Swiss corridor. Manufacturing concentrates in Germany, China, and the United States, with cold-rolled steel and aluminum extrusions as primary raw material dependencies. Single-source vulnerability runs through Rittal's cross-border assembly nodes, where customs clearance delays would constrain domestic availability. Distribution feeds from manufacturer-direct contracts into colocation operator procurement teams, bypassing traditional electrical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native liquid cooling architectures that bypass traditional rack frames entirely. Defense requires insulating core positioning against disintermediation.
For Market Incumbents: Insulate market position by deepening captive supply of integrated power distribution units and securing exclusive alpine cooling partnerships with Green Datacenter. Certification investment in FINMA-compliant EMI shielding creates switching costs that modular entrants cannot replicate quickly. For New Entrants and Emerging Players: Pursue white-space expansion in Ticino's 5G edge cabinet segment, where wall-mounted 12U-18U specifications remain underpenetrated by established suppliers. Target retail banking branch consolidation through prefabricated rack assemblies bundled with Swisscom channel partnerships. For Investors and Strategic Acquirers: Alpine-cooled modular infrastructure specialists with existing OFCOM compliance track records represent the priority acquisition archetype. Long-term viability hinges on renewable energy intermittency mitigation capabilities across the projection horizon. The signal to monitor is hyperscaler direct-to-chip liquid cooling adoption rates in Zurich financial district deployments.| Strategic Initiative | Industry Significance |
|---|---|
| Alpine Cooling Partnership | Green Datacenter's carbon-neutral facilities anchor ESG-mandated enterprise procurement decisions. |
| FINMA Certification Investment | EMI-shielded rack compliance creates defensible positioning in Geneva private banking vaults. |
| Modular Build-Out Expansion | Swisscom's 12-week deployment timelines displace conventional on-premises construction cycles. |
| Liquid Cooling Integration | Direct-to-chip systems above 30kW per cabinet render air-cooled architectures obsolete. |
| Geneva-Basel Corridor Presence | Hyperscaler cloud expansion concentrates 48U high-density demand in underpenetrated secondary markets. |
Research Methodology
The analysis maps enclosed rack, open frame, and modular installation segments, each validated through primary interviews with colocation facility operators, data center construction contractors, and FINMA compliance officers. Secondary validation draws from OFCOM regulatory filings, Swiss Federal Customs Administration trade data, hyperscaler capex disclosures, and SEC 10-K infrastructure segments. Bottom-up rack shipment estimates triangulate against top-down facility power capacity buildouts.
Assumptions held fixed include Switzerland's phased nuclear exit trajectory and FADP enforcement intensity, while renewable energy intermittency and hyperscaler entry timing were varied across scenarios. The projection horizon models product type, end user vertical, rack size tier, and installation type dimensions. CAGRs derive from segment-level shipment trajectories weighted by average selling price evolution, with thermal design power thresholds and alpine cooling adoption as key industry-specific inputs.
Macroeconomic conditions sit as an overlay; deviation in Swiss franc exchange rates or EU aluminum tariff schedules would shift the trajectory. Forecasts reflect documented assumptions, with regulatory enforcement intensity, hyperscaler buildout acceleration, and liquid cooling technology maturation as specific risk factors that could prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Taiwan Data Center Rack Market
Data Center Infrastructure
Poland Data Center Construction Market
Data Center Infrastructure
Saudi Arabia Data Center Rack Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
France Data Center Power Market
Data Center Infrastructure
Hong Kong Data Center Rack Market
Data Center Infrastructure
Taiwan Data Center Power Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market
Data Center Infrastructure
Norway Data Center Physical Security Market
Data Center Infrastructure
Italy Data Center Physical Security Market
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Germany Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Rack Market