
 Global Web Hosting Service Market | 2026-2036
Global Web Hosting Service Market Size, Share, and Industry Trends Forecast 2026-2036
Global Web Hosting Service Market Foresight
Subscription-based managed hosting is broadening what providers bundle into recurring contracts. Amazon Web Services anchors enterprise-grade infrastructure through its global data center footprint. Google Cloud differentiates with AI-integrated workload optimization. Alibaba Cloud dominates Asia-Pacific delivery through localized compliance architectures.
Web hosting service denotes the provision of server space, bandwidth, and infrastructure management that enables websites and applications to remain accessible via the internet, typically measured by uptime guarantees exceeding 99.9% and latency thresholds under 200 milliseconds. Cloud Hosting and Managed Hosting command premium positioning as enterprises migrate from capital-intensive on-premises models to operational expenditure frameworks. Shared Hosting retains volume leadership among price-sensitive SMBs and individual developers. Hybrid Cloud deployment models capture expanding margin pools from regulated industries requiring partitioned data sovereignty.
EU GDPR, China's Cybersecurity Law administered by the Cyberspace Administration of China, and US state-level privacy statutes including California's CCPA constrain how providers architect multi-tenant environments and cross-border data flows. Compliance certification costs now figure prominently in provider pricing and regional market entry decisions. Stakeholders must weigh data localization mandates against the operational economies of centralized global infrastructure.
Market Dynamics
Enterprise workload migration to operational expenditure frameworks is compressing traditional colocation margins while elevating managed service attach rates. Providers now compete on compliance certification depth rather than raw infrastructure scale.
Growth Catalysts
- GDPR and EU Digital Operational Resilience Act:European financial institutions must maintain operational continuity standards that favor certified managed hosting partners over self-managed infrastructure.
- Container orchestration:Kubernetes-native deployment patterns accelerate hybrid cloud adoption among SaaS developers seeking portability across hyperscaler environments.
- India:Digital infrastructure buildout under the PLI scheme and data center corridor development in Mumbai and Chennai attracts hyperscaler localization investments.
Market Restraints
- Electricity cost volatility:Data center power purchase agreements face repricing pressure from grid instability in Germany and Texas, compressing facility-level EBITDA.
- Hyperscaler concentration:Three providers control over 60% of global IaaS capacity, creating vendor lock-in risk for enterprise multi-cloud strategies.
- Latency physics:Sub-50 millisecond edge computing requirements challenge centralized hyperscaler architectures for autonomous vehicle and industrial IoT workloads.
Strategic Opportunities
- Saudi Arabia:Vision 2030 data center localization mandates and giga-project construction create demand for sovereign cloud architectures compliant with SFDA and financial regulator requirements.
- AI training clusters:GPU-dense hosting configurations command 3-4x revenue per rack unit versus general compute, attracting specialized facility investment.
- Green hydrogen power purchase agreements:EU taxonomy alignment and CSRD disclosure requirements favor providers with verified renewable energy matching.
Industry Challenges
- Site selection and permitting:Grid interconnection queues in Virginia and Frankfurt extend facility commissioning timelines by 18-24 months.
- Legacy mainframe integration:Financial services migration to cloud-native stacks requires specialized middleware expertise that commands premium labor costs.
- Cross-border data flow certification:China's cybersecurity law and EU GDPR create conflicting localization requirements for multinational enterprise architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Web Hosting Service Market |
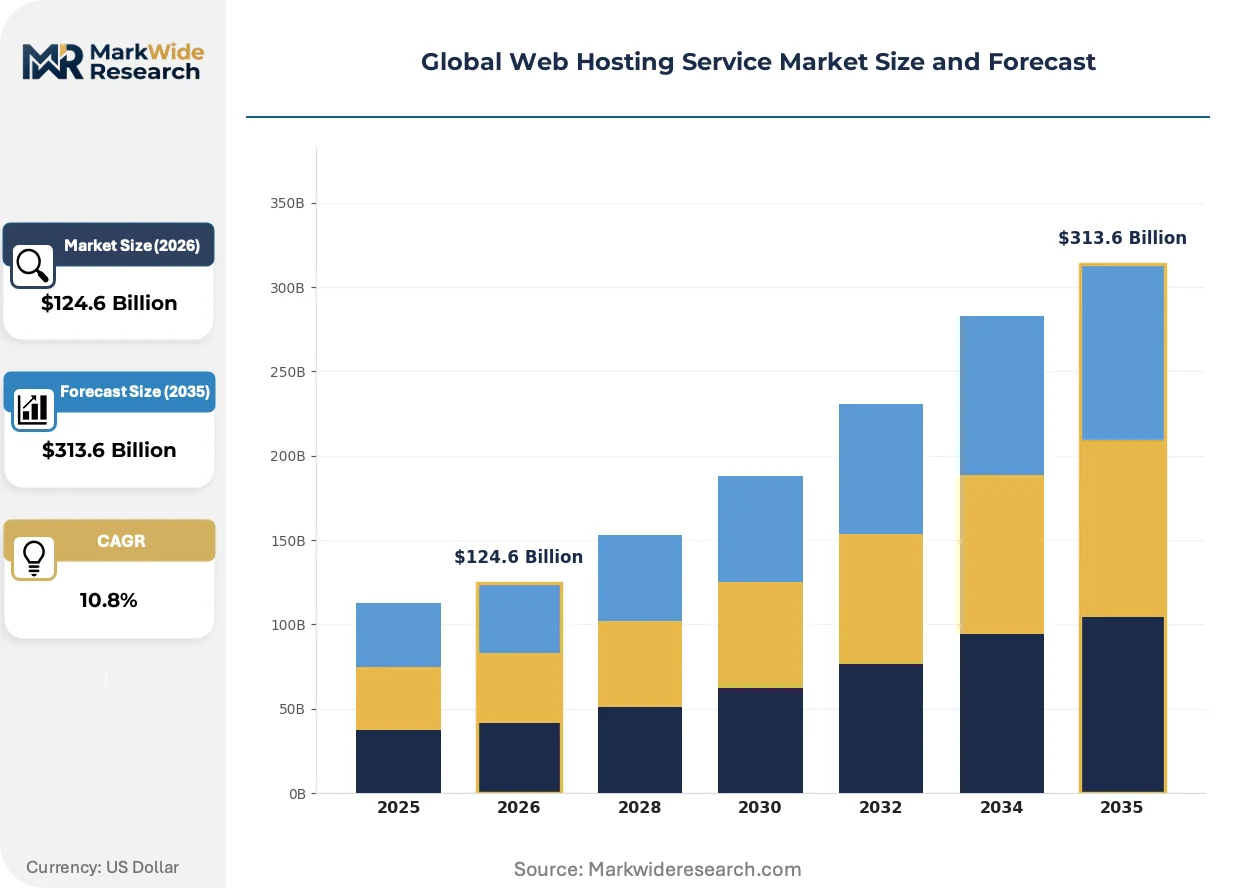
| Market Size in 2026 | $124.6 Billion |
| Market Size in 2035 | $313.6 Billion |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Shared Hosting, VPS Hosting, Dedicated Hosting, Cloud Hosting, Managed Hosting, Reseller Hosting Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, Multi-Cloud, On-Premises End User Industry: SMBs, Large Enterprises, E-Commerce Platforms, Educational Institutions, Non-Profit Organizations Pricing Model: Pay-As-You-Go, Subscription-Based, Freemium, Tiered Pricing, Usage-Based Billing |
| Companies Covered | Amazon Web Services, GoDaddy Operating Company, Google Cloud, Alibaba Cloud, 1&1 IONOS, Hostinger International, Liquid Web, Equinix, WPEngine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Web Hosting Service Market Shifts & Advancements
Serverless computing architectures and sovereign cloud mandates are fragmenting the traditional three-tier hosting model. Providers now differentiate through vertical-specific compliance stacks rather than generic uptime guarantees.
Arm-based processor deployments are expanding into high-density computing environments previously dominated by x86 architectures. Hyperscalers now offer Graviton and Cobalt instances at 20-40% lower per-compute-hour pricing. This silicon diversification is expanding into AI inference workloads where power efficiency outweighs raw single-thread performance.
EU AI Act risk classification tiers are forcing hosting providers to implement technical documentation and audit trail capabilities for high-risk AI system deployments. German automotive manufacturers now require hosting partners to demonstrate conformity assessment procedures. This regulatory segmentation is expanding into medical device hosting where MDR Article 17 mandates explicit infrastructure qualification.
Consumption-based billing models are displacing committed-use discount structures among mid-market SaaS vendors. Finance teams now prioritize granular cost allocation tags over volume commitment flexibility. This procurement evolution is most visible among Series B and C software companies in the United States and United Kingdom where venture capital discipline demands precise unit economics tracking.
Global Web Hosting Service Market Segmentation
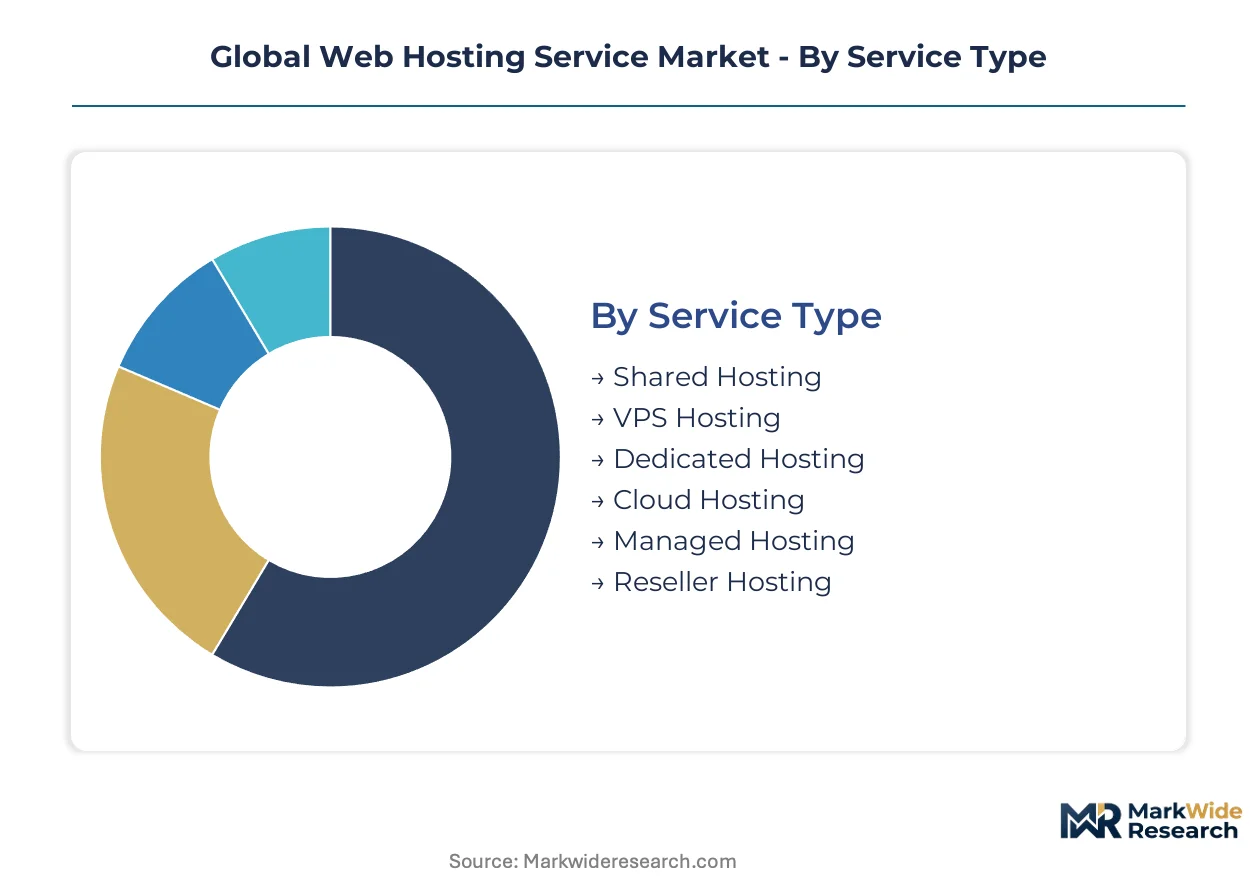
Web hosting service segmentation reflects divergent infrastructure maturity across customer tiers. Providers calibrate resource allocation, compliance depth, and support intensity based on deployment complexity and regulatory exposure rather than uniform service delivery.
Service Type:
Standardization dominates entry-level tiers while customization intensity escalates through enterprise-grade offerings.
- Shared Hosting:Multi-tenant server environments partition compute resources across hundreds of websites per physical node. Demand concentrates among individual developers and micro-businesses in India and Southeast Asia where capital constraints favor operational expenditure minimization over performance guarantees.
- Cloud Hosting:Distributed infrastructure pools resources across redundant nodes with automatic failover capabilities. SaaS developers in Germany and the United States drive adoption seeking horizontal scalability without hardware procurement cycles.
- VPS Hosting:Virtual private servers allocate dedicated resource slices within shared physical infrastructure.
- Dedicated Hosting:Single-tenant physical servers provide complete hardware isolation for compliance-sensitive workloads.
- Managed Hosting:Providers assume operational responsibility for patching, monitoring, and optimization.
- Reseller Hosting:White-label infrastructure enables third-party branding and sub-account management.
Leading the category by volume: Shared Hosting. Expanding most quickly: Cloud Hosting.
Deployment Model:
Control granularity determines pricing architecture, with sovereignty requirements fragmenting previously centralized infrastructure decisions.
- Public Cloud:Shared infrastructure pools deliver elastic capacity through hyperscaler platforms. E-commerce platforms in the United States and United Kingdom prioritize this model for traffic spike accommodation during seasonal demand windows.
- Hybrid Cloud:Partitioned architectures combine on-premises sovereignty with burst capacity to public infrastructure. Financial institutions across Germany and Switzerland mandate this configuration under EU Digital Operational Resilience Act continuity requirements.
- Private Cloud:Single-tenant virtualized environments dedicated to one organization.
- Multi-Cloud:Deliberate distribution across competing hyperscaler platforms to mitigate vendor concentration risk.
- On-Premises:Self-managed hardware within customer-controlled facilities.
Dominating revenue contribution: Public Cloud. Steepest expansion trajectory: Hybrid Cloud.
End User Industry:
Compliance sophistication scales with organizational complexity and regulatory scrutiny intensity.
- SMBs:Organizations under 500 employees prioritize cost predictability over customization depth. Adoption accelerates across North America and Europe as managed service providers bundle security tooling previously inaccessible to resource-constrained IT departments.
- Large Enterprises:Complex procurement frameworks negotiate bespoke service level agreements and dedicated account architectures. Demand concentrates in financial services and healthcare verticals where data residency requirements override cost optimization.
- E-Commerce Platforms:Transactional workloads require sub-200 millisecond latency guarantees and PCI-DSS certification.
- Educational Institutions:Seasonal usage patterns and grant-funded procurement cycles shape contract structures.
- Non-Profit Organizations:Donor transparency requirements and restricted funding streams constrain technology investment.
Highest absolute contract value: Large Enterprises. Gaining share fastest: E-Commerce Platforms.
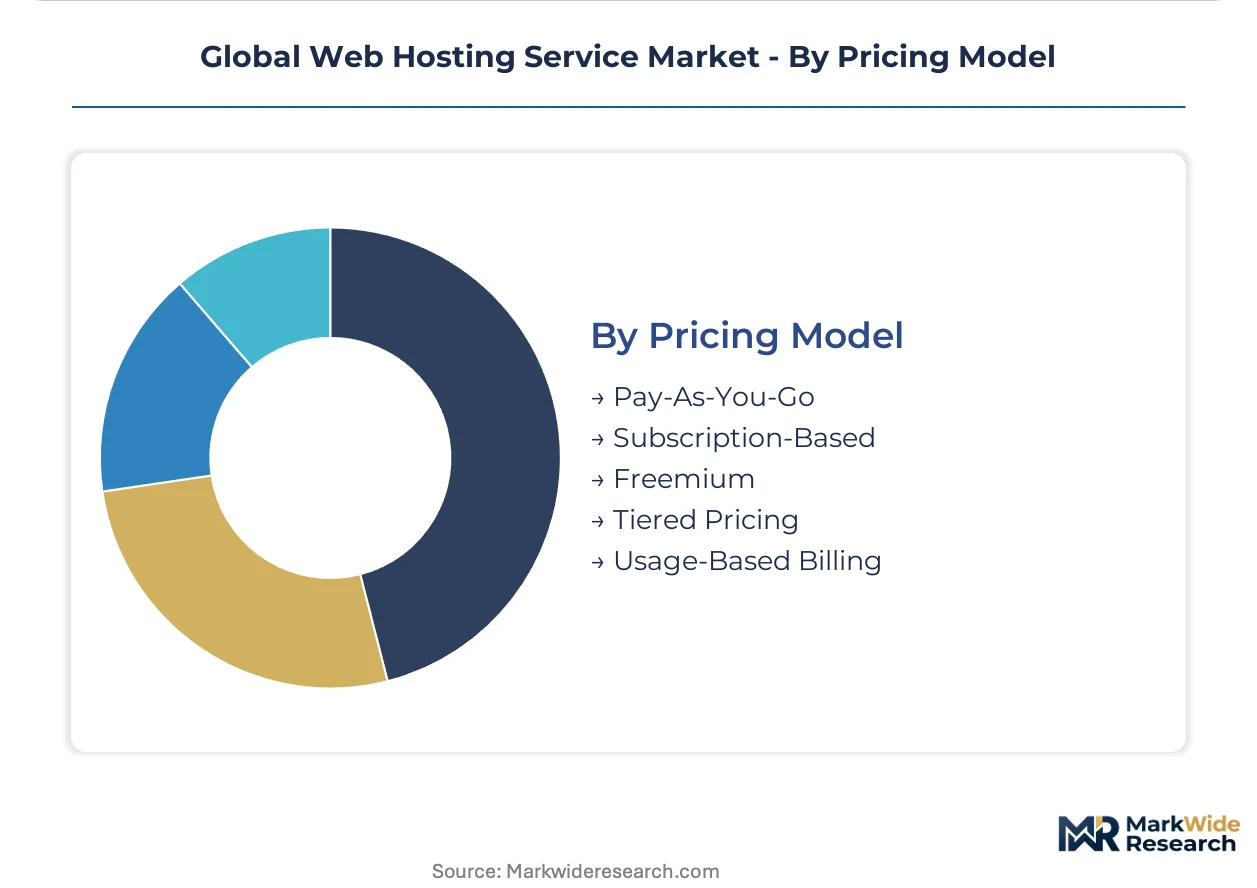
Pricing Model:
Consumption measurement precision determines customer finance team acceptance and provider revenue predictability.
- Subscription-Based:Fixed recurring fees cover predetermined resource allocations and support tiers. Large enterprises in Germany and France prefer this structure for budget certainty under CSRD disclosure requirements.
- Pay-As-You-Go:Metered consumption billing aligns costs directly with utilization patterns. SaaS vendors in the United States and United Kingdom adopt this model to preserve capital efficiency through growth phases.
- Tiered Pricing:Discrete capability bundles separate entry-level from premium feature access.
- Usage-Based Billing:Granular resource metering enables precise cost allocation to business units or product lines.
- Freemium:Zero-cost entry tiers convert to paid subscriptions through feature limitation thresholds.
Generating highest revenue stability: Subscription-Based. Climbing the fastest: Pay-As-You-Go.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Frankfurt anchors European hyperscaler expansion with the continent's densest fiber interconnection hub and 60-plus data centers clustered along the Rhine-Main corridor.
United States
Virginia's Loudoun County hosts the world's largest concentration of cloud infrastructure with over 10 million square feet of data center space. State-level renewable portfolio standards in California and Texas reshape power purchase agreement structures for facility operators. Northern Virginia's Data Center Alley continues absorbing hyperscaler investment despite 18-month grid interconnection queues.
Germany
Financial institutions in Frankfurt and Stuttgart mandate hybrid cloud architectures under EU Digital Operational Resilience Act continuity requirements. The Federal Financial Supervisory Authority enforces operational resilience standards that elevate certified managed hosting above self-managed alternatives. Bavaria's Munich-Cologne corridor attracts specialized AI training cluster investments from automotive manufacturers.
India
Mumbai and Chennai data center corridors expand under the PLI scheme for IT hardware with 4-6% incentive rates on incremental sales. The Ministry of Electronics and Information Technology mandates data localization for government and financial sector workloads. Telangana's Hyderabad cluster captures hyperscaler investments seeking South Asian latency optimization.
Saudi Arabia
Vision 2030 giga-projects in Riyadh and NEOM generate sovereign cloud demand compliant with SFDA and Saudi Central Bank requirements. The Communications, Space and Technology Commission issues cloud service provider licenses with explicit data residency conditions. King Abdullah Financial District anchors financial services hosting migration from legacy on-premises infrastructure.
United Kingdom
London's Docklands and Slough corridor retains European financial services hosting despite post-Brexit regulatory fragmentation. The Financial Conduct Authority operational resilience rules mirror EU DORA timelines with 2025 implementation deadlines. Manchester and Birmingham emerge as secondary nodes for media and SaaS workload distribution.
Global Web Hosting Service Market Competitive Landscape
Capital-heavy infrastructure operators compete with asset-light platform aggregators across divergent margin structures. The market consolidates around three hyperscalers controlling majority IaaS capacity while specialized providers capture regulated vertical premiums. Strategic archetypes separate sovereign cloud specialists, GPU-dense AI training hosts, and compliance-certified managed service operators. Capacity expansion and vertical-specific certification acquisition dominate competitive positioning as raw infrastructure scale commoditizes.
Within the hyperscaler tier, Amazon Web Services, Google Cloud, and Alibaba Cloud exemplify divergent geographic and technological positioning. AWS anchors enterprise infrastructure through global facility footprint. Google Cloud occupies the AI-integrated optimization vector. Alibaba Cloud represents Asia-Pacific localized compliance architecture. These three entities collectively shape pricing benchmarks and certification standards that cascade through downstream provider tiers.
| Leading Market Players |
|---|
| Amazon Web Services |
| GoDaddy Operating Company |
| Google Cloud |
| Alibaba Cloud |
| 1&1 IONOS |
| Hostinger International |
| Liquid Web |
| Equinix |
| WPEngine |
| Others |
Supply & Pricing Matrix
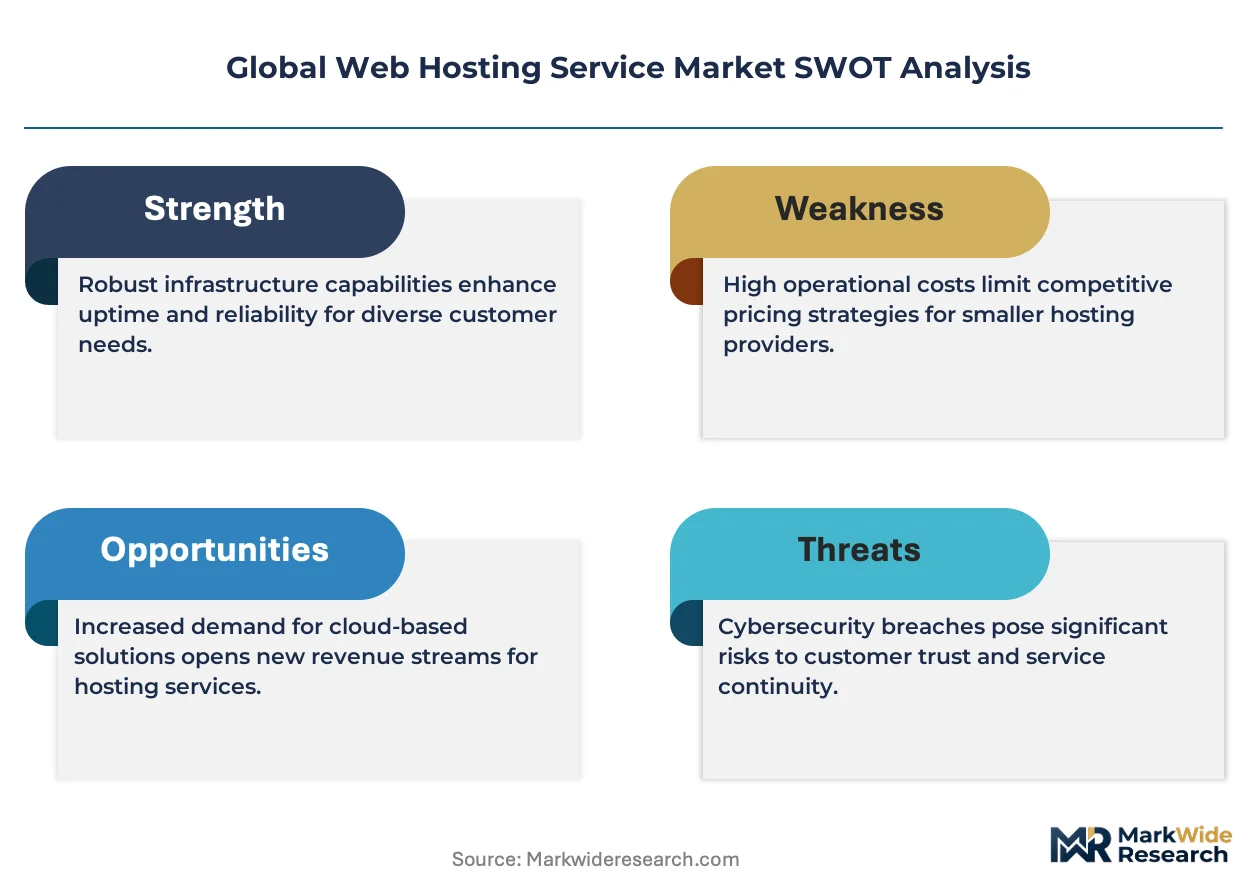
Hyperscaler-backed infrastructure platforms anchor supply-side concentration while exerting downward pricing pressure on specialized managed hosting tiers. Sovereign cloud mandates in Germany and Saudi Arabia fragment procurement patterns, forcing providers to absorb compliance certification costs that compress margins at the facility level.
Pricing Analysis
Uptime-guarantee pricing anchors enterprise contracts, with 99.99% availability thresholds commanding 40-60% premiums over standard 99.9% tiers. Subscription-based SaaS-tiered structures dominate mid-market procurement, while hyperscaler spot instances erode committed-use pricing power. Price differentiation hinges on compliance certification depth—GDPR, DORA, and SFDA attestation tiers—and geographic data residency guarantees. Cost compression in shared hosting intensifies as Indian and Southeast Asian providers compete on operational expenditure minimization. SMBs exhibit highest price sensitivity, deferring to freemium tiers, whereas financial institutions prioritize budget certainty over unit cost optimization.
Supply Chain Analysis
Cross-border bandwidth costs and subsea cable capacity constraints shape facility location economics for latency-sensitive workloads. Server hardware concentrates in Taiwan, South Korea, and China, with GPU accelerators facing allocation bottlenecks from NVIDIA and AMD foundry partners. Power infrastructure draws from grid interconnection queues in Virginia and Frankfurt that extend commissioning timelines. Single-source vulnerability in Arm-based processor supply—Graviton, Cobalt, and Ampere Altra—creates silicon diversification risk. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and managed service provider channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around compliance-certified operators as electricity cost volatility and grid interconnection delays force subscale facility operators toward distressed exits. Hyperscaler concentration above 60% IaaS capacity leaves limited oxygen for undifferentiated infrastructure plays.
For Market Incumbents: Anchor defensive positioning through vertical integration into renewable power generation, securing green hydrogen purchase agreements that satisfy EU taxonomy alignment. Acquire specialized compliance certifications—DORA operational resilience attestation, SFDA sovereign cloud licensing—that create switching costs for financial services clients. Counter GPU-dense AI training cluster entrants by locking long-term rack commitments with automotive manufacturers in Bavaria.
For New Entrants and Emerging Players: Launch via sovereign cloud specialization targeting Saudi Vision 2030 giga-projects and King Abdullah Financial District migration demand. Target India's PLI scheme corridors in Mumbai and Chennai where hyperscaler localization investments outpace indigenous capacity. Pursue white-label managed hosting partnerships with European SaaS vendors seeking DORA-compliant infrastructure without self-managed complexity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor hybrid cloud specialists with existing Frankfurt or London financial services footprints and unexpired grid interconnection agreements. Five-to-ten year viability hinges on renewable energy matching verification and vertical-specific certification depth rather than raw megawatt scale. Monitor hyperscaler capex allocation shifts toward AI training clusters as signal for general compute oversupply inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Compliance Certification Acquisition | DORA and SFDA attestation unlocks financial services procurement frameworks in Frankfurt and Riyadh. |
| GPU-Dense Facility Buildout | AI training cluster configurations command premium revenue per rack unit from automotive manufacturers. |
| Renewable Power Integration | Green hydrogen purchase agreements satisfy EU taxonomy alignment and CSRD disclosure requirements. |
| Sovereign Cloud Localization | Data residency mandates in India and Saudi Arabia create captive demand for in-country infrastructure. |
| Managed Service Provider Partnership | White-label channels extend reach to SMBs lacking internal compliance expertise across North America. |
Research Methodology
Document review covered hyperscaler capex disclosures, data center permitting databases, and regulatory filings from BaFin and CSTC, complemented by interviews with facility operations directors, cloud procurement officers at financial institutions, and managed service provider channel heads. Secondary validation drew from EU DORA implementation guidance, Saudi Vision 2030 project announcements, and PLI scheme administrative records. Bottom-up facility capacity aggregation and top-down enterprise IT spend allocation were triangulated against reported hyperscaler revenue segmentation.
Segmentation outputs reflect deployment model, service type, end-user industry, and geographic regulatory cluster dimensions across the projection horizon. CAGRs were derived from elasticity-adjusted demand curves incorporating workload migration velocity and compliance mandate implementation timelines. Forecast inputs included grid interconnection queue data from PJM and Bundesnetzagentur, plus GPU accelerator supply allocation patterns from foundry partners.
Regulatory enforcement variance, electricity grid instability, and hyperscaler pricing aggression are the dominant revision risks to modeled outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
API Monetization Platform Market
Digital Solutions
Virtual Hiring Tools Market
Digital Solutions
Global Smart Offices Market
Digital Solutions
Global Corporate Volunteering Platform Market
Digital Solutions
Crowdsourcing Market
Digital Solutions
Kuwait ICT Market
Digital Solutions
Mobile Dating Apps Market
Digital Solutions
Saudi Arabia Digital Twin Market
Digital Solutions
Function As a Service (Faas) Market
Digital Solutions
Global Continuous Delivery Market
Digital Solutions
Digital Assistant Market
Digital Solutions
AI Infrastructure Market
Digital Solutions
Fuel Management Software Market
Digital Solutions
Digital Check Scanning Solutions Market
Digital Solutions
Managed File Transfer (MFT) Market
Digital Solutions
Cinema Point of Sale (POS) Solutions Market