
 Datacenter Infrastructure Services Market | 2026-2036
Datacenter Infrastructure Services Market Size, Share, and Industry Trends Forecast 2026-2036
Datacenter Infrastructure Services Market Outlook
Modular facility design is hardening as the dominant procurement pattern for enterprise buyers evaluating colocation and build-to-suit options. Schneider Electric leverages its integrated power and cooling portfolio to anchor turnkey module deliveries across Europe and Asia. Equinix sustains interconnection density as its core differentiator, operating carrier-neutral campuses that dominate cloud on-ramp positioning. Digital Realty competes through hyperscale-ready shell capacity, controlling land and power entitlements in primary and secondary markets.
Datacenter infrastructure services encompass the physical and operational layers that house, power, cool, and connect enterprise IT equipment, typically maintaining ambient temperatures within strict ranges and delivering power usage effectiveness ratios below industry baselines. Colocation remains the largest revenue pool within service type, though managed services commands higher recurring margins as staffing and uptime guarantees deepen customer stickiness. Hybrid deployment models are expanding fastest among deployment options, as enterprises retain sensitive workloads on-premise while bursting transactional loads to cloud nodes.
The EPA ENERGY STAR program and EU Code of Conduct for Data Centres shape facility efficiency benchmarks, while OSHA electrical safety standards govern technician work practices during live infrastructure maintenance. The SEC climate disclosure rules and EU CSRD extend reporting obligations to Scope 2 emissions from leased and owned datacenter footprints. Stakeholders must monitor how emerging grid interconnection queues and utility rate reforms alter site selection economics before committing capital to new ground-up developments.
Market Dynamics
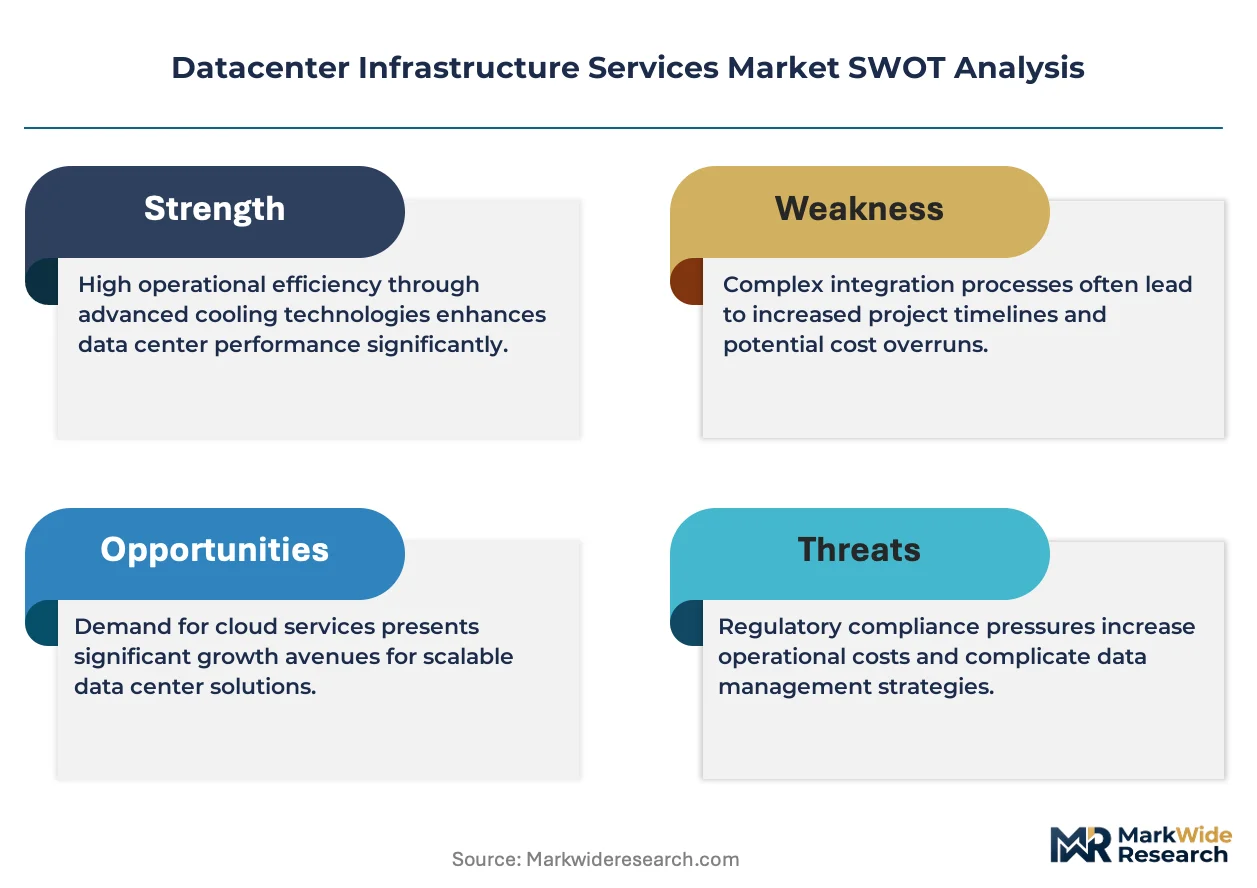
Liquid cooling architectures are compressing facility power density limits while grid interconnection queues in primary markets stretch beyond 36 months, forcing developers toward secondary locations with available substation capacity.
Growth Catalysts
- AI Training Clusters:Hyperscale deployments of GPU-intensive workloads are pulling demand for 50kW-plus rack densities across Northern Virginia, Singapore, and Frankfurt.
- EU Energy Efficiency Directive:Mandatory power usage effectiveness reporting is accelerating retrofit cycles in existing European facilities.
- Hybrid Cloud Orchestration:Enterprise IT organizations are distributing workloads across on-premise, colocation, and public cloud nodes to optimize latency and compliance.
Market Restraints
- Copper and Electrical Steel Volatility:Raw material price swings for transformer core components are squeezing equipment supplier margins.
- Taiwan Semiconductor Concentration:Dependency on single-source advanced chip fabrication creates vulnerability in server and networking hardware supply.
- Permitting Timelines:Local zoning and environmental review processes in dense markets add 18-24 months to greenfield project schedules.
Strategic Opportunities
- Nordic Secondary Markets:Norway and Sweden offer sub-100ms latency to continental Europe with abundant renewable power and streamlined permitting.
- Edge Micro-Modular Units:Pre-fabricated 100-500kW deployments are addressing latency-sensitive manufacturing and autonomous vehicle workloads.
- US Inflation Reduction Act:Investment tax credits for clean energy property are improving project returns for solar-plus-storage powered facilities.
Industry Challenges
- Critical Facilities Technician Shortage:Specialized electrical and mechanical trades required for live infrastructure maintenance are in acute undersupply across developed markets.
- Legacy DCIM Integration:Proprietary building management systems from incumbent vendors resist interoperability with cloud-native monitoring platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Datacenter Infrastructure Services Market |
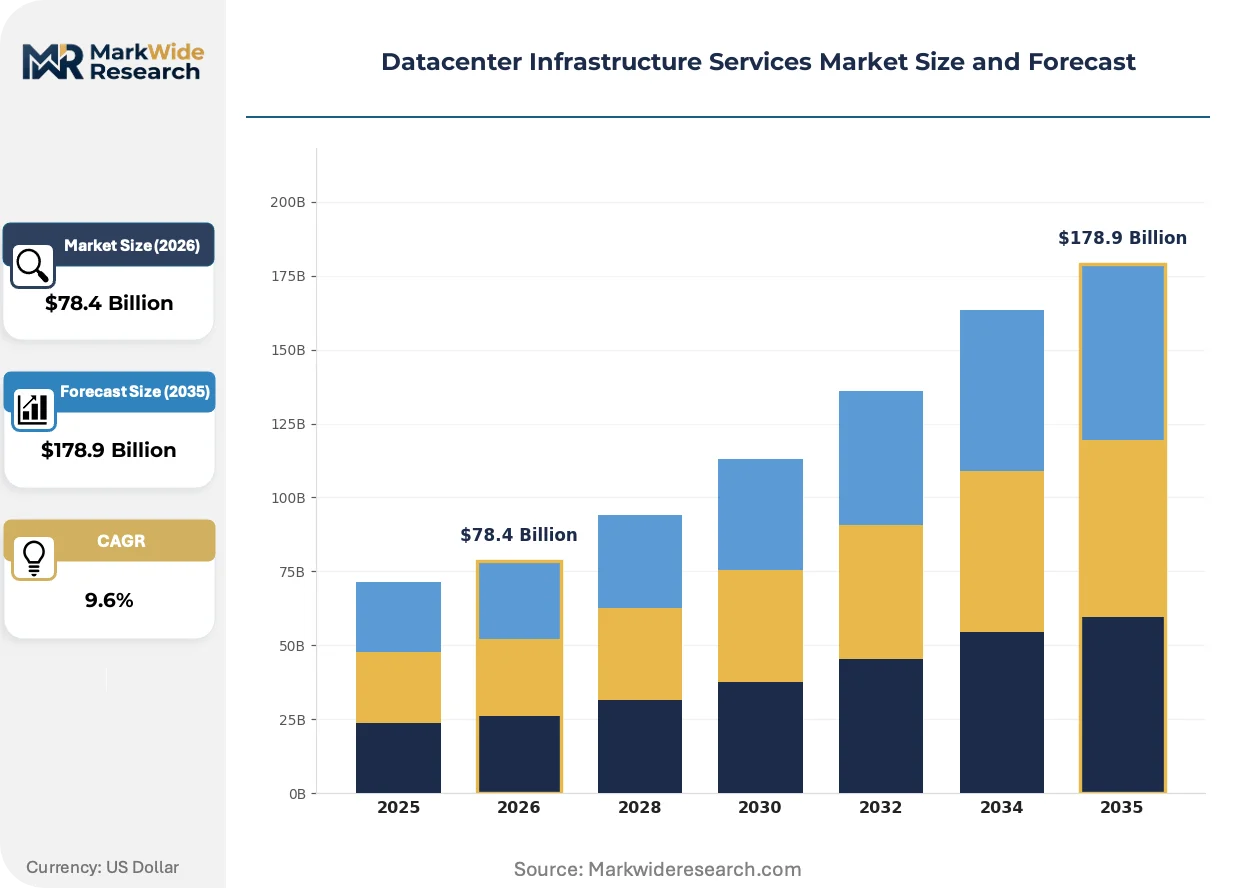
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $178.9 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Managed Services, Cloud Services, Disaster Recovery Deployment Model: On-Premise, Hybrid, Multi-Cloud, Private Cloud End User: Retail, BFSI, Healthcare, Government Technology: Virtualization, Networking, Storage Solutions, Security Tools |
| Companies Covered | Kyndryl, CBRE, JLL, Schneider Electric, DXC Technology, Equinix, Digital Realty, NTT Global Data Centers, Hewlett Packard Enterprise, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Datacenter Infrastructure Services Market Strategic Shifts
Facility architecture is bifurcating between hyperscale megacampus designs and distributed edge nodes, with thermal management and grid interconnection emerging as the decisive technical battlegrounds.
Direct liquid cooling is overtaking air-cooled architectures in high-density compute halls. Cold plate and immersion systems transfer heat directly from processors to dielectric fluid, eliminating the energy penalty of air handlers. Hyperscale operators are specifying liquid-cooled racks for all new AI training deployments. This transition is compressing mechanical infrastructure footprints by 40 percent while enabling 100kW-plus rack densities previously unachievable with conventional cooling.
The EU Corporate Sustainability Reporting Directive is mandating granular Scope 2 emissions disclosure from datacenter operators with significant European footprints. Facility owners must now track and report electricity consumption by tenant and by hour, creating audit-grade carbon accounting requirements. Colocation providers are responding by installing sub-metering infrastructure and procuring 24/7 matched renewable energy rather than annual renewable energy certificate offsets.
Enterprise sourcing patterns are fragmenting across multiple facility tiers rather than consolidating with single vendors. Large buyers are segmenting workloads across premium interconnection campuses, standard colocation halls, and wholesale shell space based on latency, compliance, and cost requirements. This portfolio approach is most pronounced in financial services and healthcare verticals, where regulatory data residency rules prevent full cloud migration.
Datacenter Infrastructure Services Market Segmentation
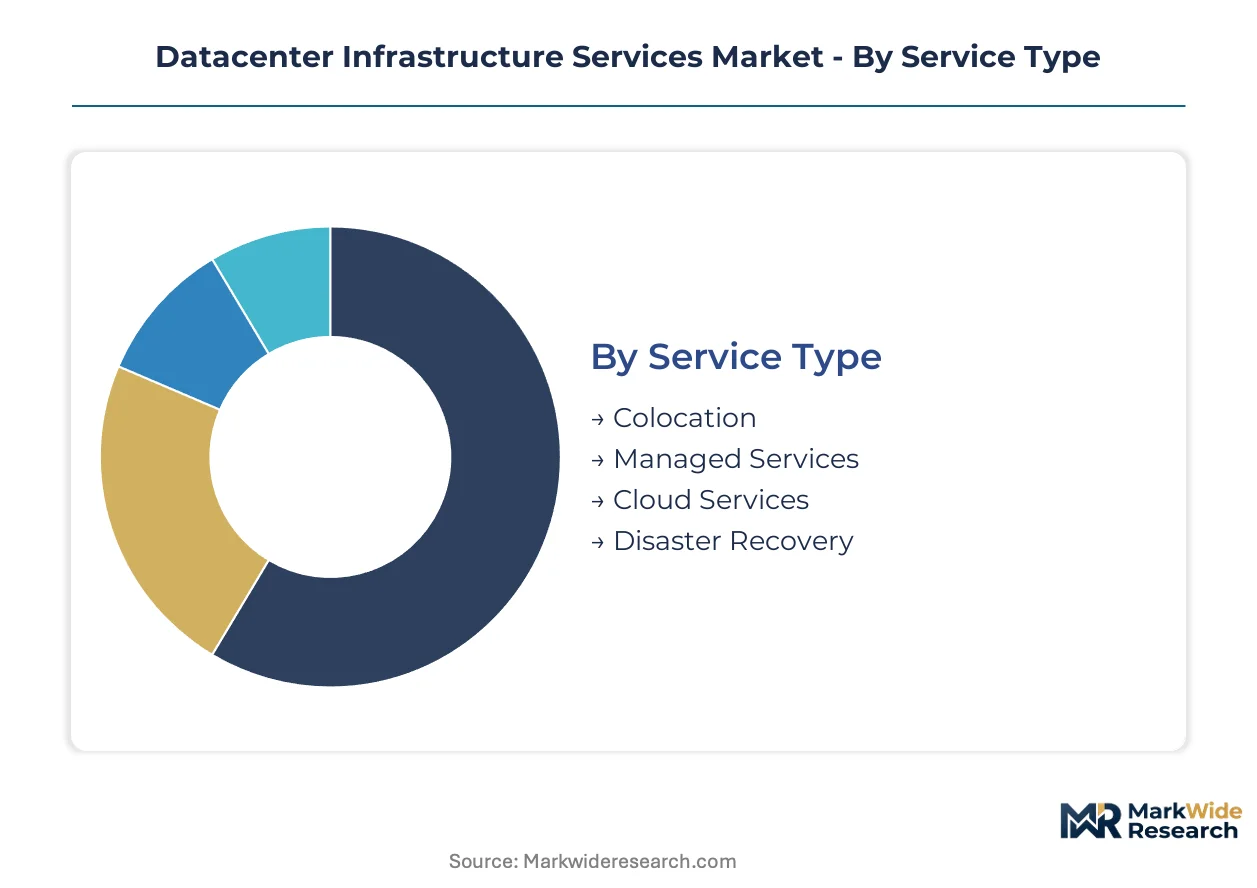
Segmentation reveals how procurement patterns split across operational models and technical architectures. Buyers evaluate service tiers against internal capabilities, compliance requirements, and workload sensitivity.
Service Type:
Facility upgrade cycles and contract renewals are driving migration between operational models as enterprises reassess internal versus outsourced infrastructure management.
- Colocation:Physical space leasing with power, cooling, and physical security provided by the operator. Demand concentrates in Northern Virginia and Frankfurt as hyperscale cloud providers expand carrier-neutral campuses for low-latency interconnection.
- Managed Services:Operational staffing, monitoring, and maintenance bundled with infrastructure tenancy. Financial services firms in Singapore are adopting managed service contracts to meet strict uptime SLAs while offloading specialist technician recruitment.
- Cloud Services:Consumption-based compute and storage delivered from multi-tenant facilities.
- Disaster Recovery:Secondary site replication and failover orchestration for business continuity.
Volume placements concentrate in Colocation; the faster expansion belongs to Managed Services.
Deployment Model:
Cost tiering separates enterprise buyers by capital intensity and operational control preferences, with hybrid architectures commanding premium pricing over pure on-premise or public cloud alternatives.
- Hybrid:Workload distribution across owned infrastructure and third-party facilities. Healthcare providers in the United States deploy hybrid models to retain patient data on-premise while bursting analytics workloads to cloud nodes, satisfying HIPAA requirements.
- On-Premise:Fully owned and operated facilities with direct capital deployment.
- Multi-Cloud:Orchestration across two or more public cloud providers to avoid vendor lock-in.
- Private Cloud:Single-tenant cloud infrastructure operated for exclusive use.
Private Cloud absorbs the largest capital commitments; Hybrid is climbing the fastest as compliance-sensitive verticals seek operational flexibility.
End User:
Application-specific latency and data residency requirements shape facility selection, with regulated industries prioritizing certified Tier III and Tier IV designs.
- BFSI:Banking, financial services, and insurance with stringent audit and recovery requirements. Frankfurt-based colocation providers report strongest demand from BFSI tenants seeking EU data sovereignty and proximity to European Central Bank infrastructure.
- Healthcare:Patient data systems with HIPAA and GDPR compliance obligations.
- Government:Sovereign cloud and classified workload hosting with security clearance requirements.
- Retail:E-commerce platforms and supply chain systems with seasonal demand volatility.
BFSI dominates committed power reservations; Retail is gaining share fastest through edge micro-modular deployments for inventory management.
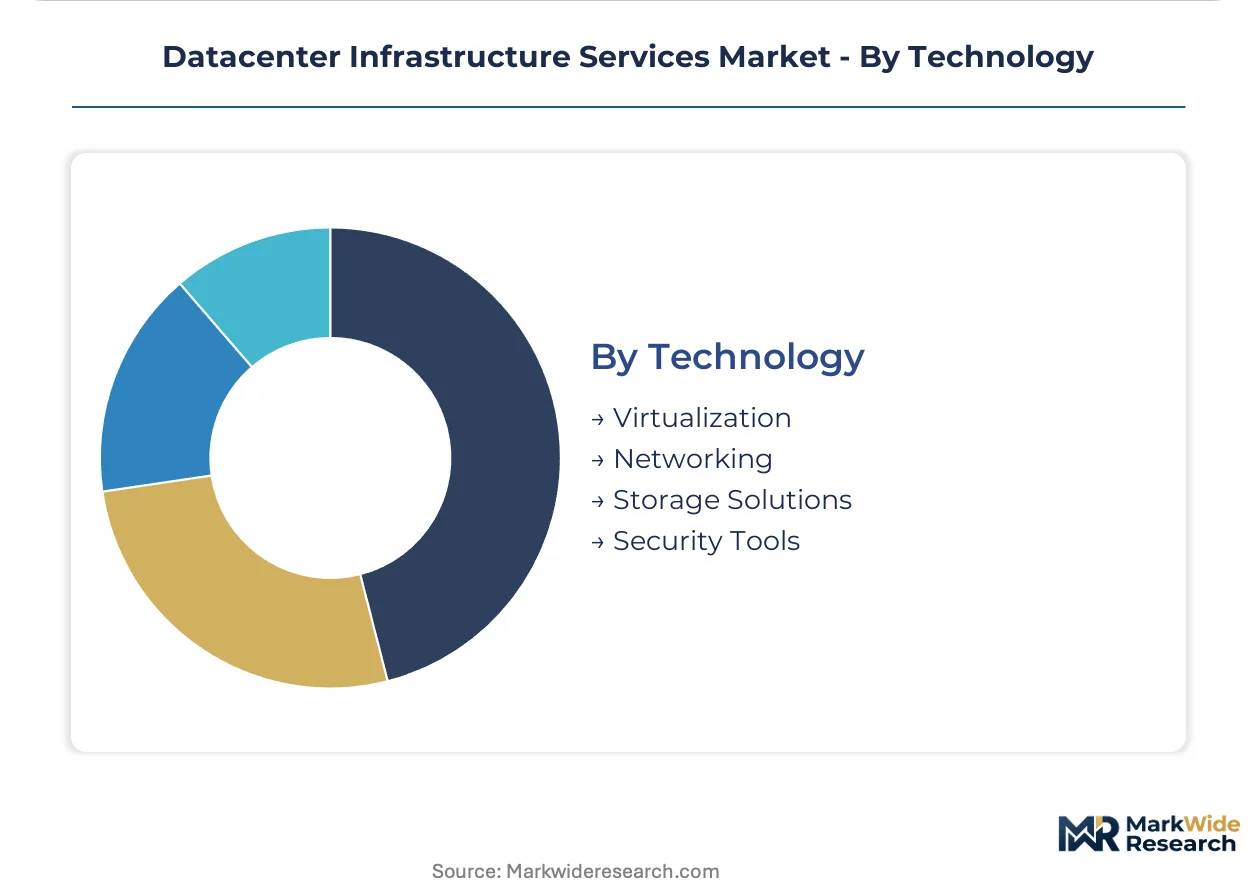
Technology:
Supply concentration in virtualization software and networking hardware is consolidating vendor relationships, with storage and security procurement fragmenting across specialist providers.
- Networking:Interconnection fabrics, SD-WAN, and cross-connect provisioning. Singapore datacenter operators are densifying networking infrastructure to serve as Asia-Pacific peering hubs for submarine cable landings.
- Virtualization:Hypervisor and container orchestration platforms abstracting physical compute.
- Storage Solutions:All-flash arrays, object storage, and tape archival systems.
- Security Tools:Perimeter firewalls, intrusion detection, and zero-trust access controls.
Networking claims the highest recurring revenue per rack; Security Tools show the steepest expansion trajectory as regulatory audit requirements multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility construction concentrates in markets with available substation capacity and streamlined interconnection queues, while enterprise consumption spreads across primary and secondary locations seeking latency optimization and cost arbitrage.
United States
Northern Virginia hosts the densest concentration of hyperscale campuses globally, driven by cloud provider expansion and submarine cable landings. The SEC climate disclosure rules mandate Scope 2 emissions reporting for leased datacenter footprints. Ashburn and Loudoun County submarkets absorb over 35 percent of national absorption.
Germany
Frankfurt anchors European interconnection demand as financial services firms seek proximity to ECB infrastructure and EU data sovereignty compliance. The EU Energy Efficiency Directive requires mandatory power usage effectiveness reporting for facilities above 500kW IT load. New construction concentrates in Offenbach and Eschborn submarkets with available grid capacity.
Singapore
The city-state functions as Asia-Pacific peering hub for submarine cable systems linking ASEAN markets to global networks. The Infocomm Media Development Authority lifted moratorium restrictions on new datacenter construction in 2022 with sustainability conditions. Tuas and Changi North industrial zones host expanding carrier-neutral campuses.
Norway
Sub-100ms latency to continental Europe and abundant hydroelectric power attract secondary market development. The country's national energy regulator streamlined grid connection procedures for renewable-powered facilities. Oslo and Stavanger regions report expanding enterprise colocation commitments from Nordic financial services tenants.
Sweden
Free air cooling potential and 100 percent renewable grid supply support cost-competitive facility operations. The Swedish Energy Agency provides investment support for energy-efficient datacenter infrastructure under national climate targets. Luleå and Stockholm regions host hyperscale deployments leveraging Arctic climate advantages.
Datacenter Infrastructure Services Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across facility ownership, equipment supply, and operational services segments. The vendor base organizes into three tiers: integrated infrastructure conglomerates with power and cooling portfolios, carrier-neutral interconnection specialists, and hyperscale-focused wholesale developers. Market consolidation proceeds through land and power entitlement acquisitions, while technology differentiation centers on liquid-cooled rack densities and renewable energy matching capabilities.
Among diversified infrastructure conglomerates, Schneider Electric exemplifies integrated power and cooling portfolio anchoring. Equinix and Digital Realty occupy distinct positions within the facility ownership tier, with the former representing carrier-neutral interconnection density and the latter exemplifying hyperscale-ready shell capacity strategies. These three entities illustrate how competitive positioning fragments across technical specialization and customer segmentation vectors.
| Leading Market Players |
|---|
| Kyndryl |
| CBRE |
| JLL |
| Schneider Electric |
| DXC Technology |
| Equinix |
| Digital Realty |
| NTT Global Data Centers |
| Hewlett Packard Enterprise |
| Others |
Value Chain & Pricing Dynamics
Backward integration into power and cooling equipment anchors supply positioning and pricing power for integrated infrastructure conglomerates, while modular procurement patterns fragment buyer leverage across colocation tiers. Equipment suppliers with captive transformer and switchgear production command margin premiums against pure-play facility operators dependent on spot electrical component markets.
Pricing Analysis
Margin tightening in wholesale shell capacity reflects copper and electrical steel volatility squeezing transformer suppliers. Three-tier pricing structure across premium interconnection, standard colocation, and economy wholesale tiers separates buyers by latency sensitivity and compliance requirements. Cost-down pressure on managed services accelerates because hyperscale cloud providers internalize operational staffing. Financial services firms show lowest price sensitivity due to uptime SLA requirements, while retail edge deployments exhibit highest elasticity.
Supply Chain Analysis
Transformer core supply rests on Japanese and German electrical steel producers with limited secondary sourcing. Critical input dependencies span copper winding, silicon steel laminations, and dielectric cooling fluids. Single-source vulnerability concentrates in Taiwan semiconductor fabrication for server and networking hardware. Distribution runs through direct OEM relationships for hyperscale operators and tiered distributor networks for mid-market enterprise procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The datacenter infrastructure services market operates as a vertical-integration race, with power equipment control and renewable energy procurement emerging as decisive upstream levers for margin defense.
For Market Incumbents: Deepen captive production of liquid-cooled rack systems to offset commodity electrical component volatility. Expand interconnection density in Northern Virginia and Frankfurt carrier-neutral campuses to defend against emerging Nordic secondary market entrants. Prioritize 24/7 renewable energy matching capabilities to meet EU CSRD disclosure requirements. For New Entrants and Emerging Players: Edge micro-modular thermal management systems offer technology-first wedge into latency-sensitive manufacturing and autonomous vehicle workload segments. Target Norway and Sweden secondary markets with streamlined permitting and abundant hydroelectric supply. Pursue direct utility partnerships bypassing congested grid interconnection queues. For Investors and Strategic Acquirers: Exit pathways concentrate in land and power entitlement portfolios with secured substation capacity. Long-term viability hinges on regulatory compliance infrastructure and renewable energy procurement capabilities. Watch grid interconnection queue lengths as inflection indicator for site selection economics.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Direct liquid cooling enables 100kW-plus rack densities for AI training clusters. |
| Renewable Energy Procurement | 24/7 matched renewable energy satisfies EU CSRD Scope 2 disclosure mandates. |
| Secondary Market Expansion | Nordic facilities leverage sub-100ms latency and streamlined permitting. |
| Modular Facility Design | Pre-fabricated units compress deployment timelines for edge workloads. |
| Grid Interconnection Partnership | Direct utility relationships bypass 36-month queue delays in primary markets. |
Study Parameters
SEC filings, EIA power market data, and EU regulatory databases formed the secondary backbone for this analysis. Primary interviews with datacenter facility operators, electrical infrastructure procurement leads, and utility interconnection planners combined with secondary validation. Bottom-up and top-down triangulation anchored market sizing across service type and deployment model segments.
Bottom-up modeling tracked facility construction pipelines and power reservation commitments by hyperscale operators. Segmentation dimensions included service tier, deployment architecture, end-user vertical, and regional grid capacity constraints. CAGRs derived from facility absorption rates and equipment shipment trajectories across the projection horizon. Forecast inputs incorporated interconnection queue lengths and renewable energy procurement contract volumes.
Several conditions sit outside the modeled scope, including unannounced hyperscale capacity expansions and abrupt utility rate reforms. Forecasts reflect documented assumptions about permitting timelines and raw material availability. Supply chain disruptions in Taiwan semiconductor fabrication or electrical steel markets warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Fiber Management Systems Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Data Center Solutions Market
Data Center Infrastructure
Vietnam Data Center Physical Security Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Mumbai Data Center Market
Data Center Infrastructure
Data Center Renovation Market
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Mini Data Center Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Europe Data Center Rack Market
Data Center Infrastructure
IT Infrastructure Management Tools Market
Data Center Infrastructure
Belgium Data Center Power Market
Data Center Infrastructure
United Arab Emirates Data Center Physical Security Market
Data Center Infrastructure
Switzerland Data Center Server Market