
 Data Processing and Hosting Services Market | 2026-2036
Data Processing and Hosting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Processing and Hosting Services Market Insights
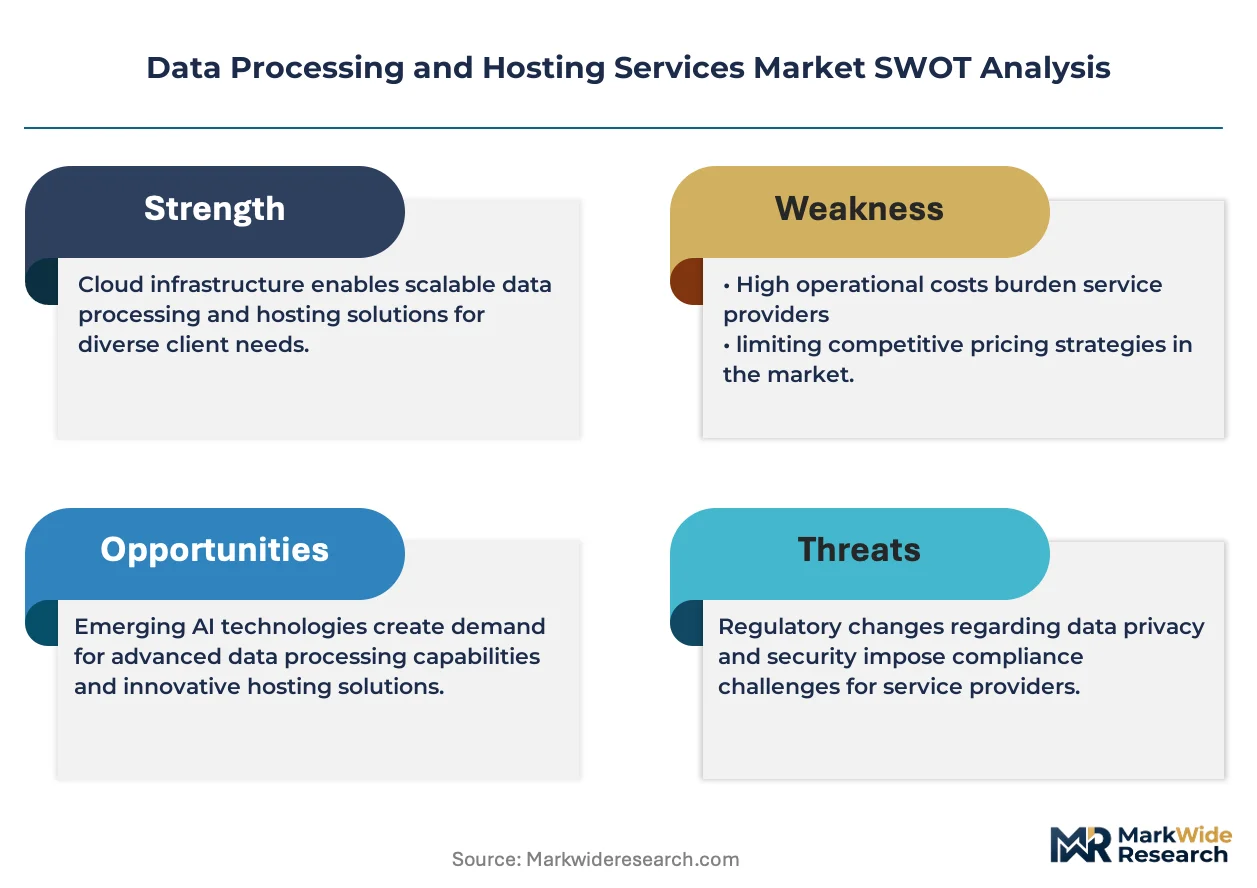
Software-defined networking capabilities in managed hosting packages is realigning what enterprises purchase as a bundled service rather than discrete infrastructure. Amazon Web Services leverages its global fiber backbone to sustain low-latency delivery at scale. Microsoft anchors enterprise trust through extensive compliance certification portfolios across regulated industries. Equinix differentiates via interconnection density that reduces cross-connect costs for multi-cloud architectures.
Data processing and hosting services encompass the computational infrastructure, storage systems, and network orchestration layers that ingest, transform, and serve digital information at scale, typically operating within facilities maintaining N+1 or 2N redundancy in power and cooling subsystems. These services enable organizations to offload capital-intensive IT operations while maintaining transactional throughput, analytical query performance, or real-time stream processing as core commercial functions. Cloud Computing commands the largest revenue pool among service types, though Hybrid Cloud deployment models are capturing disproportionate growth as regulated entities seek workload portability between on-premises and off-premises environments. Colocation Services retain structural importance for latency-sensitive workloads requiring physical proximity to financial exchanges or manufacturing control systems.
FDA 21 CFR Part 11 requirements shape validation protocols for hosting providers serving pharmaceutical clinical trial data, while EU GDPR and the EU AI Act impose data residency and algorithmic accountability obligations that constrain cross-border processing architectures. In the US, SEC cybersecurity disclosure rules now mandate incident reporting timelines that pressure hosted infrastructure operators to demonstrate detection and response capabilities. Stakeholders must evaluate whether their provider's compliance scope matches the regulatory perimeter of each workload category they deploy.
Market Dynamics
Financial services firms are consolidating data infrastructure procurement around sovereign cloud architectures as EU AI Act and GDPR compliance deadlines compress vendor selection timelines. This regulatory pressure is modularizing provider offerings into certifiable workload bundles.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Providers are engineering explainable infrastructure stacks that satisfy conformity assessment requirements for high-risk AI deployments in automated trading and credit scoring systems.
- Hyperscale fiber backbone expansion:Low-latency connectivity investments into Frankfurt, Amsterdam, and Dublin clusters enable real-time analytics for quantitative hedge funds and high-frequency trading platforms.
- Pharmaceutical clinical trial digitization:FDA 21 CFR Part 11 validation requirements drive demand for compliant hosting environments that maintain audit trails and electronic signature integrity across distributed research sites.
Market Restraints
- Data center power density constraints:N+1 and 2N redundancy requirements in cooling subsystems limit facility expansion in grid-constrained metropolitan zones including London and Singapore.
- Cross-border data transfer friction:GDPR adequacy decision uncertainty and Schrems II litigation create legal exposure for multi-region workload orchestration across US-EU architectures.
- Specialized engineering talent scarcity:Shortages of certified cloud architects and Site Reliability Engineers extend deployment timelines for hybrid cloud migrations in regulated sectors.
Strategic Opportunities
- India's data localization mandates:RBI and SEBI requirements for financial data residency create demand for in-country hyperscale regions and certified managed hosting facilities in Mumbai and Chennai.
- Edge computing convergence with 5G:Manufacturing control systems and autonomous vehicle telemetry require micro-data centers positioned within single-digit millisecond proximity to industrial zones and smart city infrastructure.
- CSRD sustainability disclosure requirements:EU corporate reporting mandates on digital infrastructure emissions create market for carbon-accounted hosting services with verified renewable energy matching.
Industry Challenges
- Legacy mainframe integration complexity:Financial institutions maintaining COBOL-based core banking systems face interoperability gaps when migrating transaction processing to containerized cloud environments.
- Multi-cloud security posture fragmentation:CISOs struggle to maintain consistent identity management, encryption key governance, and threat detection across AWS, Azure, and Google Cloud deployments.
Report Scope
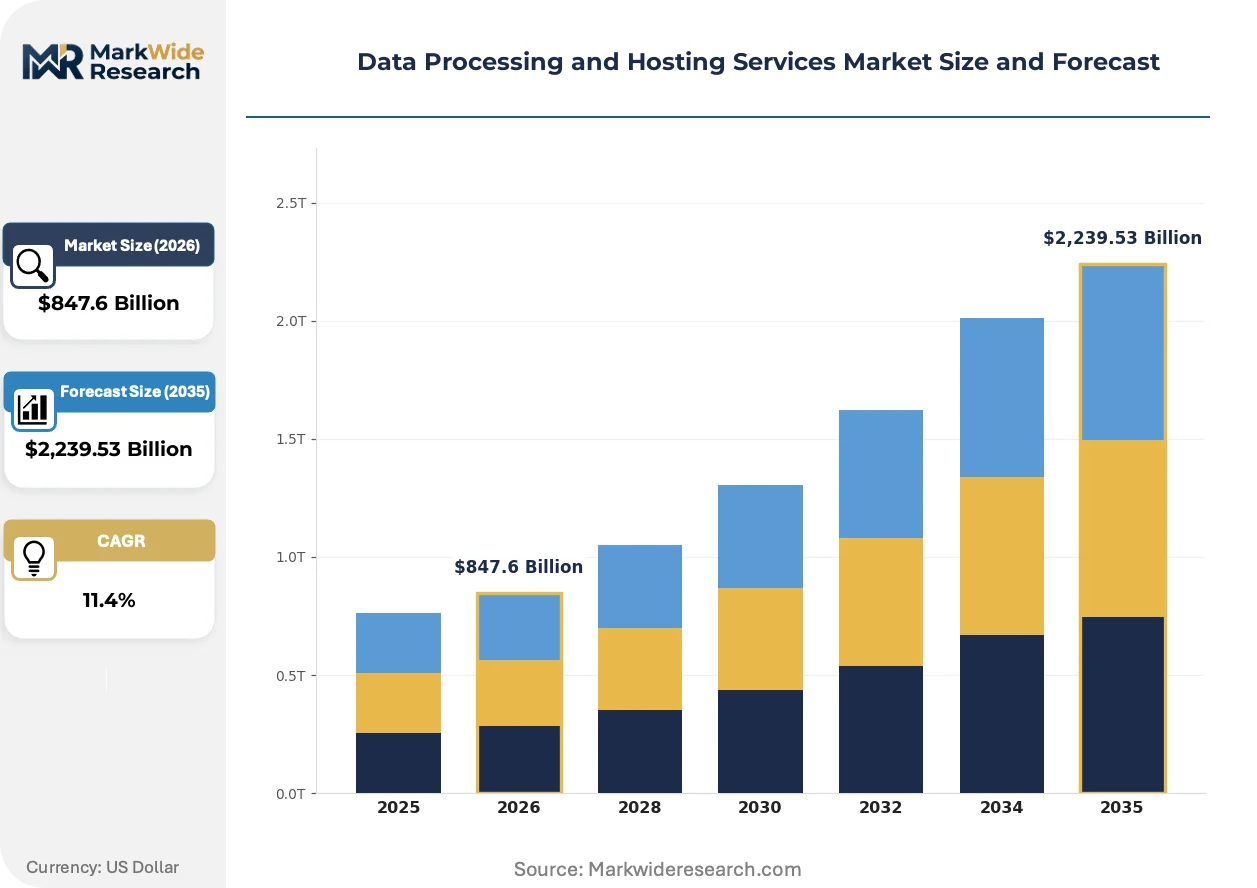
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Processing and Hosting Services Market |
| Market Size in 2026 | $847.6 Billion |
| Market Size in 2035 | $2,239.53 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cloud Computing, Managed Hosting, Colocation Services, Data Backup Client Type: Small Businesses, Enterprises, Governments, Startups Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Data Type: Structured Data, Unstructured Data, Big Data, Real-Time Data |
| Companies Covered | Digital Realty, NTT Global Data Centers, Amazon Web Services, IONOS, CyrusOne, Microsoft, Google Cloud Platform, Cloudways, Equinix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Processing and Hosting Services Market Trends and Innovations
Infrastructure software is decoupling from hardware ownership models, with enterprises purchasing computational outcomes rather than capitalizing physical assets. This shift is compressing procurement cycles and elevating vendor accountability for performance guarantees.
Software-defined networking is modularizing network orchestration into programmable layers that enterprises consume as subscription services rather than engineering in-house. Managed service providers are packaging SD-WAN and zero-trust architectures into bundled offerings for mid-market manufacturers and healthcare networks. The technology is modularizing traditional telco relationships and collapsing multi-year circuit contracts into elastic, usage-adjusted arrangements.
The EU AI Act's risk-based classification system is forcing providers to engineer segregated infrastructure tiers with differentiated compliance attestations. High-risk AI workloads now require dedicated environments with enhanced logging, human oversight interfaces, and third-party audit rights. Pharmaceutical and automated credit decisioning deployments in Germany and France are absorbing the earliest certification costs and establishing templates for cross-border replication.
Enterprise buyers are unbundling managed services from infrastructure commitments, selecting specialized operators for security operations, database administration, and cost optimization while retaining direct cloud contracts. This disintermediation pressures traditional systems integrators to demonstrate measurable workload performance improvements rather than relationship-based retention. The pattern is most pronounced among US healthcare networks and European automotive suppliers with mature cloud centers of excellence.
Data Processing and Hosting Services Market Segmentation
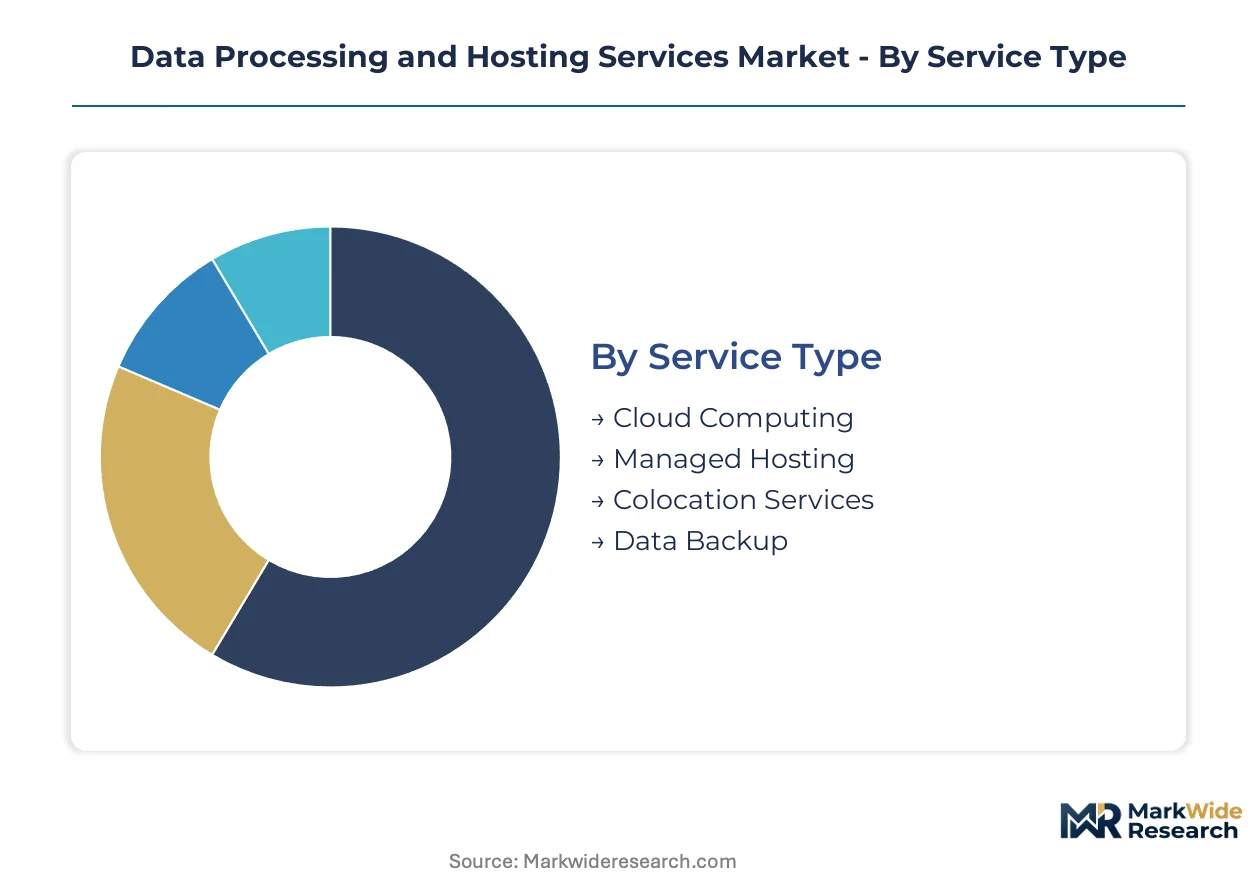
Segmentation in data processing and hosting services reveals how procurement patterns diverge between capital-intensive infrastructure commitments and operational expenditure models. Understanding these splits enables providers to architect service tiers that match regulatory exposure, performance requirements, and budget cycles across buyer categories.
Service Type:
Cloud Computing commands the volume position while Managed Hosting retains premium pricing power through operational accountability.
- Cloud Computing:Self-service computational resources delivered via API-driven orchestration layers with metered consumption billing. Demand concentrates among US healthcare networks modernizing electronic health record systems under HIPAA security rule pressures.
- Managed Hosting:Provider-operated physical or virtual infrastructure with bundled operational support including patching, monitoring, and incident response. Financial services firms in Germany and France absorb premium pricing to satisfy EU AI Act conformity assessment requirements for algorithmic trading infrastructure.
- Colocation Services:Facility space leasing with power, cooling, and physical security while customers retain server ownership. Latency-sensitive trading platforms in Frankfurt and London maintain deployments for proximity to financial exchanges.
- Data Backup:Replication and recovery services protecting against ransomware and operational failures. Pharmaceutical sponsors running FDA 21 CFR Part 11 compliant trials require immutable audit trail preservation.
Today's leader: Cloud Computing. Tomorrow's challenger: Managed Hosting.
Client Type:
Enterprise procurement patterns anchor infrastructure economics while startup growth rates reshape capacity planning.
- Enterprises:Multi-year contracts with customized service level agreements governing availability, recovery time objectives, and regulatory attestation scope. Manufacturing conglomerates in Japan and Germany drive hybrid cloud demand for operational technology convergence.
- Small Businesses:Standardized packages with self-service provisioning and limited support tiers. India's RBI data localization mandates push these buyers toward domestic cloud regions in Mumbai.
- Governments:Sovereign cloud requirements with citizenship-verified personnel and air-gapped infrastructure. EU member states specify GDPR-compliant hosting for citizen data processing.
- Startups:Elastic consumption models with minimal upfront commitment and rapid scaling pathways. Venture-backed fintechs in Singapore and Dubai prioritize low-latency connectivity to payment networks.
Enterprises dominate contract value. Startups expand most quickly.
Deployment Model:
Public Cloud captures transactional volume while Hybrid Cloud climbs fastest on regulatory workload portability requirements.
- Hybrid Cloud:Orchestrated workload placement across on-premises and off-premises environments with unified management planes. Automated credit decisioning systems in France and Germany require this architecture to satisfy EU AI Act high-risk AI segregation mandates.
- Public Cloud:Shared multi-tenant infrastructure with global region availability and consumption-based economics. US SEC cybersecurity disclosure rules pressure listed companies toward providers with demonstrated incident response capabilities.
- Private Cloud:Single-tenant dedicated infrastructure with customized security controls and physical isolation. Defense contractors and intelligence agencies mandate this model for classified processing.
- On-Premises:Customer-owned and operated facilities retaining full capital burden and operational responsibility. Legacy COBOL-based core banking systems in US financial institutions resist migration due to integration complexity.
Public Cloud holds current share. Hybrid Cloud gains share fastest.
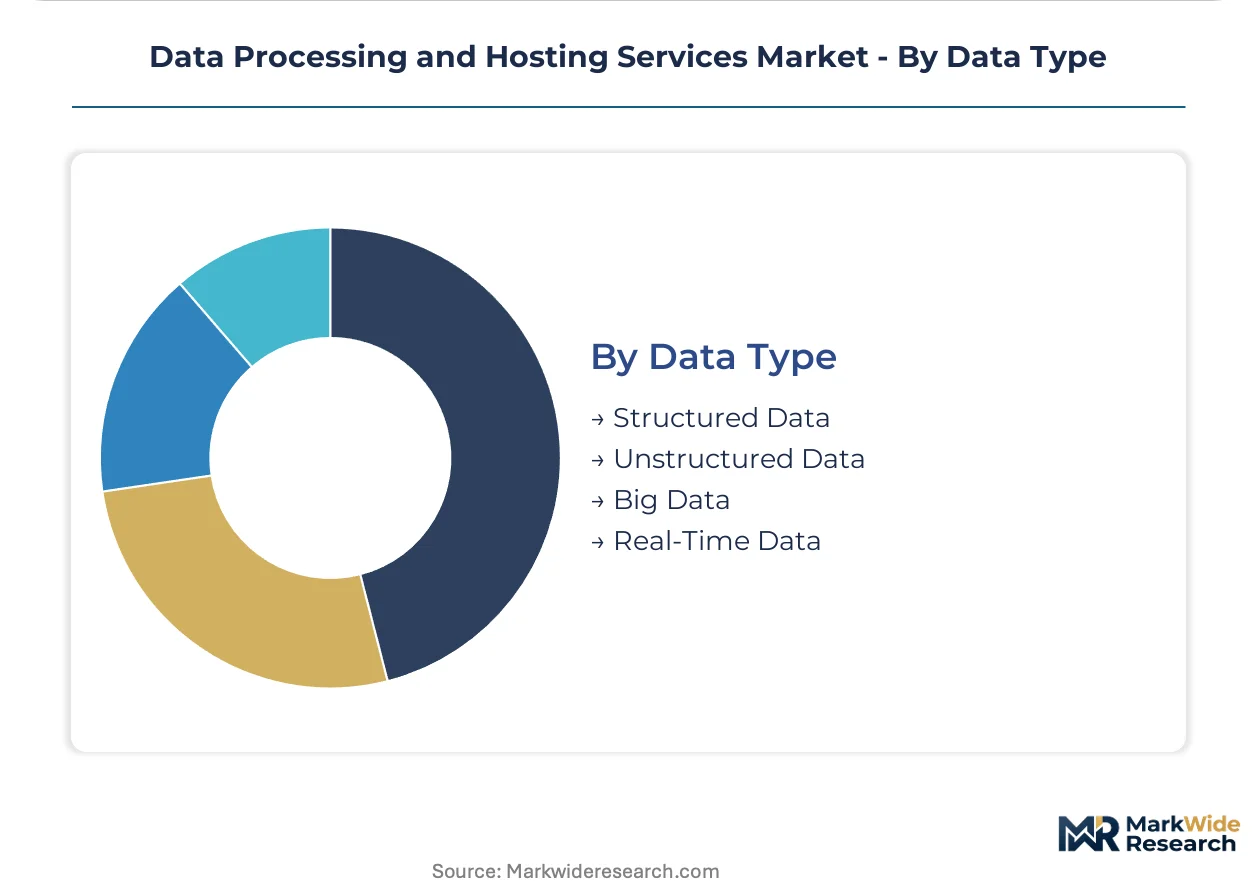
Data Type:
Structured Data anchors transactional throughput economics while Real-Time Data commands premium pricing for latency-sensitive processing.
- Real-Time Data:Sub-second ingestion and analytical processing with stream processing engines and in-memory compute tiers. Quantitative hedge funds in Frankfurt and Amsterdam absorb infrastructure costs for microsecond-level trading signal generation.
- Big Data:Distributed storage and computational frameworks handling petabyte-scale analytical workloads. Pharmaceutical genomic research across Switzerland and the UK drives demand for compliant high-performance computing environments.
- Structured Data:Relational database systems with defined schemas supporting transactional consistency and ACID guarantees. ERP systems in manufacturing supply chains remain the dominant consumption pattern.
- Unstructured Data:Document, image, video, and log file repositories requiring object storage and content analytics. Clinical trial imaging archives at US research sites expand storage procurement.
Structured Data maintains volume leadership. Real-Time Data shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping infrastructure deployment patterns as providers migrate capacity toward jurisdictions offering clearer compliance cost structures. The EU AI Act and GDPR have elevated Germany and France as preferred hubs for algorithmic accountability-certified hosting, while India's data localization mandates redirect financial services workloads toward domestic facilities.
United States
SEC cybersecurity disclosure rules and FDA 21 CFR Part 11 requirements drive demand for compliant hosting among listed companies and pharmaceutical sponsors. Financial services firms in New York and Chicago maintain substantial colocation footprints for proximity to equity exchanges. Northern Virginia's data center corridor sustains hyperscale expansion despite grid interconnection delays.
Germany
Frankfurt's interconnection density attracts quantitative hedge funds and automated trading platforms requiring microsecond latency. The EU AI Act's high-risk AI classification system pressures providers to engineer segregated infrastructure tiers with enhanced logging capabilities. Bavaria and Hesse host certified sovereign cloud facilities serving automotive suppliers and industrial conglomerates.
India
RBI and SEBI data localization mandates for financial services create demand for in-country hyperscale regions. Mumbai and Chennai emerge as primary clusters for certified managed hosting facilities serving domestic banks and fintechs. Telangana's Hyderabad hosts government cloud infrastructure for citizen data processing under national digital sovereignty frameworks.
United Kingdom
Post-Brexit regulatory divergence creates friction for cross-border data flows with EU member states, elevating domestic facility requirements. London's financial district maintains colocation deployments for proximity to derivatives exchanges. Scotland's renewable energy access supports carbon-accounted hosting services targeting CSRD-compliant EU corporate buyers.
Singapore
Grid constraints and tropical cooling requirements limit facility expansion despite strong demand from regional hedge funds and commodity trading platforms. The Monetary Authority of Singapore's technology risk management guidelines shape provider certification requirements. Johor Bahru across the Strait attracts overflow capacity seeking lower land and power costs.
Data Processing and Hosting Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hyperscale cloud operators commanding volume positions and colocation providers retaining premium pricing through interconnection density. The market structures around three tiers: global fiber backbone owners with integrated software stacks, interconnection-focused facility operators, and regional managed hosting specialists. Consolidation pressures intensify as enterprise procurement teams unbundle services and demand measurable workload performance guarantees. Capacity expansion and compliance certification portfolios represent the dominant competitive vectors as regulated buyers compress vendor selection timelines.
Among hyperscale cloud operators, Amazon Web Services and Microsoft exemplify the integrated infrastructure-software archetype, while Equinix occupies a position representing interconnection density specialization. Digital Realty and CyrusOne sit within the wholesale colocation tier serving cloud on-ramps and enterprise hybrid deployments. NTT Global Data Centers anchors the Asia-Pacific regional specialist category with Japan-originated engineering capabilities.
| Leading Market Players |
|---|
| Digital Realty |
| NTT Global Data Centers |
| Amazon Web Services |
| IONOS |
| CyrusOne |
| Microsoft |
| Google Cloud Platform |
| Cloudways |
| Equinix |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up colocation specialists have consolidated fragmented facility portfolios across Northern Virginia and Frankfurt, concentrating bargaining power over power purchasing agreements and compressing margin structures for independent operators unable to match scale economies in renewable energy procurement.
Pricing Analysis
Capacity additions in Northern Virginia and Singapore are reshaping price floors for hyperscale compute contracts as power interconnection delays extend commissioning timelines. Three-tier pricing structure across premium certified, standard compliant, and economy utility tiers dominates managed hosting procurement, with EU AI Act high-risk AI certification commanding substantial premiums. Cost compression in standard-tier colocation is intensifying because hyperscale cloud operators are bypassing intermediaries for direct land and power acquisitions. Mid-market manufacturers exhibit highest price sensitivity, while quantitative hedge funds absorb premium pricing for sub-millisecond latency guarantees.
Supply Chain Analysis
Server refresh cycles and decommissioned hardware refurbishment flows create secondary markets for memory modules and storage controllers, extending component lifecycles and moderating capital intensity for edge computing deployments. Manufacturing concentrates in Taiwan, China, and South Korea for advanced semiconductors, with Malaysia and Mexico assembling rack-scale systems. Supply chains draw from specialized silicon foundries, precision cooling equipment, and high-density power distribution units. Single-source vulnerability in advanced chip packaging creates exposure for AI training infrastructure procurement. Distribution runs through direct OEM relationships for hyperscale operators and channel partners serving mid-market colocation tenants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through certified sovereign cloud tiering, as EU AI Act compliance costs filter down to buyers through premium pricing while automation in facility operations compresses labor intensity.
For Market Incumbents: To counter hyperscale cloud operator vertical integration into facility ownership, Equinix-class interconnection providers should deepen fiber backbone control through dark fiber acquisitions in Frankfurt and Mumbai corridors. Certification investment in EU AI Act high-risk AI attestation creates defensible pricing power for German and French financial services workloads. For New Entrants and Emerging Players: Enter via India's RBI-mandated financial data localization requirements, where domestic hyperscale capacity lags demand from Mumbai-based fintechs. Target sovereign cloud certifications for government workloads in Telangana and Karnataka as the most penetrable segment, leveraging partnership structures with state-owned telecommunications infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among regional managed hosting specialists with compliance certification gaps but established customer relationships in regulated verticals. Long-term viability hinges on successful tiering into algorithmic accountability-certified infrastructure. Monitor EU AI Act conformity assessment body accreditation timelines as the critical inflection signal for pricing power reallocation.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | EU AI Act attestation unlocks premium pricing for Frankfurt algorithmic trading infrastructure. |
| Fiber Backbone Expansion | Dark fiber acquisitions into Amsterdam and Dublin reduce cross-connect costs for multi-cloud architectures. |
| Edge Computing Convergence | Micro-data center positioning near industrial zones captures 5G-enabled manufacturing telemetry workloads. |
| Carbon-Accounted Hosting Services | Verified renewable energy matching satisfies CSRD disclosure requirements for EU corporate buyers. |
| Legacy Mainframe Integration | Containerization bridges for COBOL systems enable gradual migration paths for US financial institutions. |
Research Methodology
Direct dialogue with data center facility operators, cloud platform engineering directors, financial services infrastructure procurement leads, and regulatory compliance officers grounded qualitative assessments in operational reality. Secondary validation drew from hyperscaler capital expenditure disclosures, SEC cybersecurity incident filings, EU AI Act implementing regulation drafts, and data center power interconnection queue records. Bottom-up and top-down triangulation reconciled facility-level capacity additions with segment-level demand projections.
Bottom-up modeling aggregated individual facility power commitments and certification statuses across identified clusters, while top-down analysis tracked enterprise IT outsourcing budget allocations and regulatory compliance spending patterns. Segmentation dimensions included service type, deployment model, client size tier, and data sensitivity classification. CAGRs were derived from regression analysis against historical infrastructure spending correlations with GDP and regulatory implementation timelines. Forecast inputs incorporated power interconnection delay distributions and EU AI Act conformity assessment cost estimates.
Inputs from hyperscaler engineering executives and central bank technology risk officers were available through the study window; gaps in proprietary facility-level profitability data introduce uncertainty bands around margin expansion projections. Forecasts reflect documented assumptions regarding regulatory implementation pacing and power grid expansion timelines. Practitioners should monitor EU AI Act delegated act publication schedules and FERC interconnection queue clearance rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
White Box Server Market
Data Center Infrastructure
Data Center Monitoring Systems Market
Data Center Infrastructure
Netherlands Data Center Power Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
Poland Data Center Power Market
Data Center Infrastructure
Netherlands Data Center Rack Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Sweden Data Center Rack Market
Data Center Infrastructure
Europe Hyperscale Data Center Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Asia-Pacific Data Center Power Market
Data Center Infrastructure
Low-Cost Energy Data Center Market
Data Center Infrastructure
Dedicated Server Hosting Market
Data Center Infrastructure
United States Data Center Power Market
Data Center Infrastructure
Chennai Data Center Market