
 Global Telecommunication Equipment Cabinet and Racks Market | 2026-2036
Global Telecommunication Equipment Cabinet and Racks Market Size, Share, and Industry Trends Forecast 2026-2036
Global Telecommunication Equipment Cabinet and Racks Market Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD), which mandates transparent energy consumption reporting, is rebalancing demand toward more thermally efficient cabinet and rack designs. Schneider Electric leverages its extensive portfolio in power management and cooling to address these efficiency requirements. Rittal GmbH & Co. KG specializes in modular enclosure systems that support high-density server configurations in demanding environments. Vertiv Group Corp. competes with integrated solutions that combine power, thermal management, and IT infrastructure monitoring for enterprise and colocation data centers.
Telecommunication equipment cabinets and racks are standardized enclosure systems designed to house, organize, and protect critical networking hardware, servers, and associated peripherals. These structures are typically fabricated from steel or aluminum, conforming to 19-inch or 23-inch width standards and measured in rack units (U) to ensure equipment compatibility. In terms of product segments, floor-standing racks command the largest share, essential for deployments within large-scale data centers. Wall-mount cabinets and open frame racks serve specialized applications in network operations closets and edge computing sites where space is constrained.
Compliance with standards from the International Electrotechnical Commission (IEC) and adherence to regional regulations like the EU's RoHS directive are critical for market access. Concurrently, manufacturers must also consider China's GB standards for electronic equipment safety and performance. These frameworks govern material composition, electrical safety, and physical durability, influencing product design and manufacturing. Future profitability will hinge on developing solutions that balance higher power density requirements with stricter energy efficiency mandates from regulators and clients.
Market Dynamics
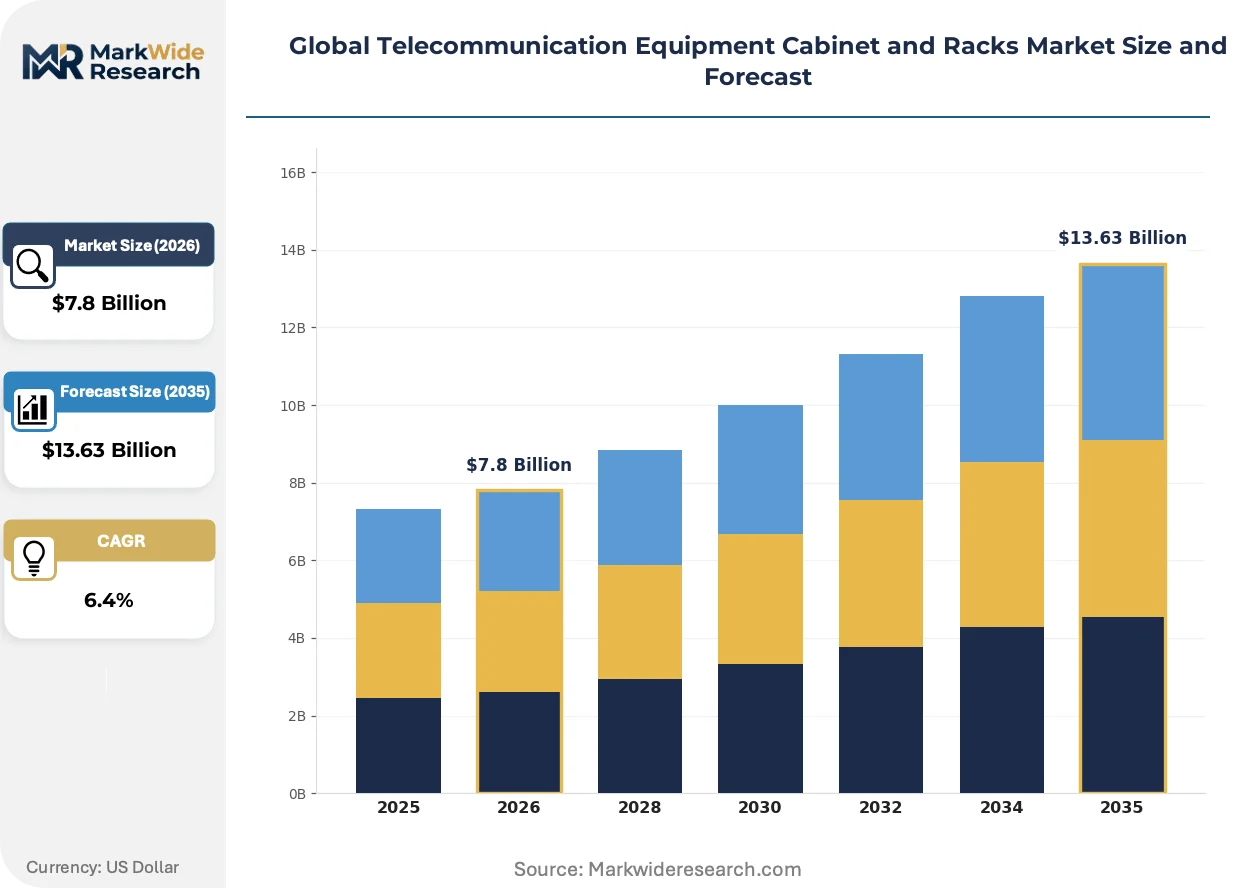
The market's central dynamic is the conflict between escalating power density requirements from hyperscale data centers and the imperative for greater thermal efficiency. This tension is amplified by sustainability mandates like the EU's CSRD and operational cost pressures, forcing a re-evaluation of traditional cabinet design.
Growth Catalysts
- 5G Network Rollouts:The global expansion of 5G infrastructure requires vast numbers of new outdoor cabinets to protect sensitive radio and baseband equipment.
- Hyperscale Data Center Projects:Concentrated in the United States, these projects generate high-volume demand for standardized floor-standing racks supporting high-density server configurations.
- Edge Computing Growth:The proliferation of IoT devices fuels demand for micro data centers and wall-mount cabinets at the network edge.
Market Restraints
- Raw Material Price Volatility:Fluctuations in steel and aluminum costs directly impact manufacturer margins and create pricing instability, complicating project budgets for end-users.
- Cloud Services Substitution:The migration of enterprise workloads to public cloud platforms reduces the market for on-premise racks within corporate data centers.
- Thermal Management Limits:Rising power densities per rack exceed the capabilities of conventional air cooling, creating a technical barrier for standard cabinet designs.
Strategic Opportunities
- Emerging Market Penetration:Data localization laws in India and Brazil are driving new data center construction, creating greenfield opportunities for rack and cabinet suppliers.
- Liquid Cooling Systems:Designing cabinets with integrated support for liquid cooling addresses the extreme power density needs of AI and high-performance computing workloads.
- Sustainability-Driven Design:The EU's CSRD creates demand for premium, thermally efficient cabinets that help clients meet energy reporting and sustainability goals.
Industry Challenges
- Complex Regulatory Compliance:Manufacturers must navigate a fragmented landscape of standards, including IEC for safety, the EU's RoHS for materials, and China's GB standards for market access.
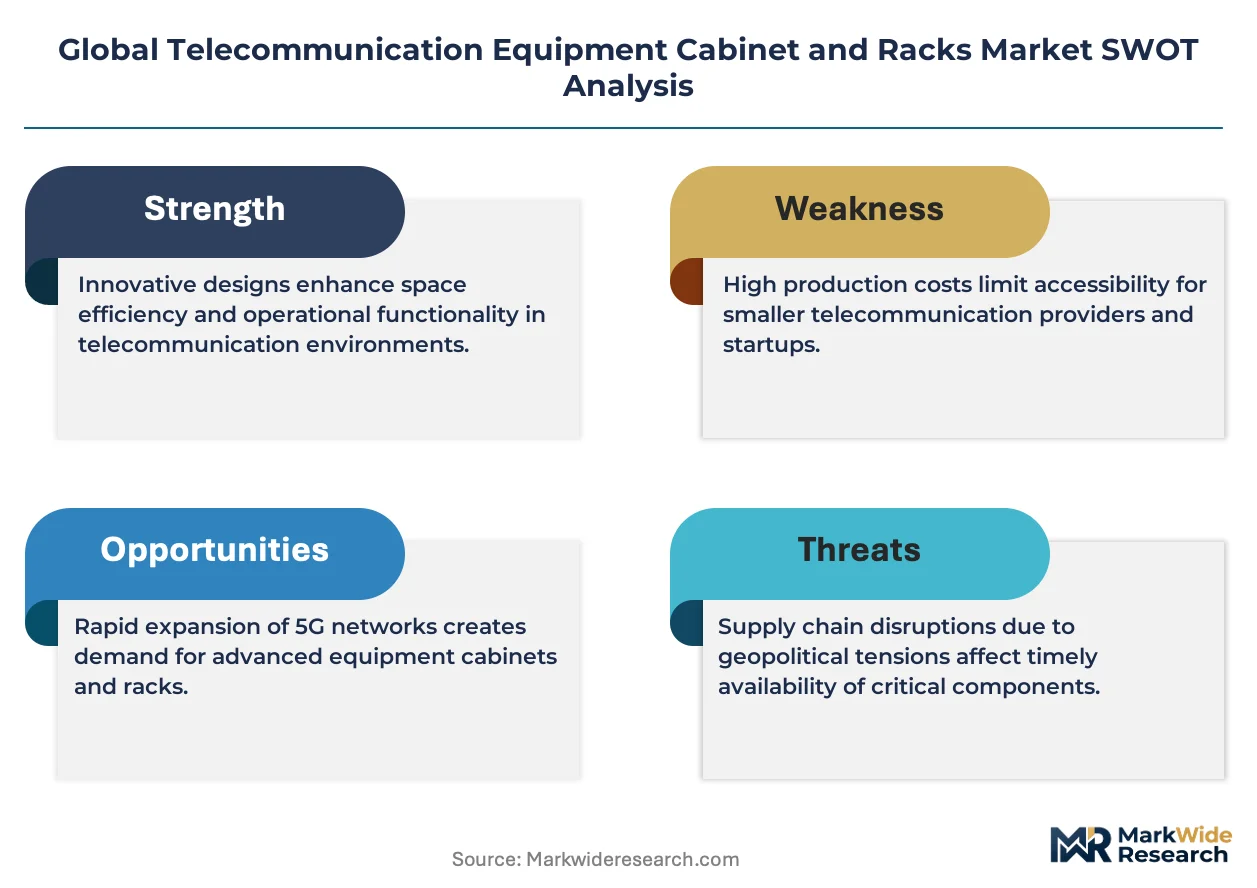
- Supply Chain Resilience:Managing extended lead times for specialized components like intelligent power distribution units and cooling fans requires sophisticated inventory and logistics management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Telecommunication Equipment Cabinet and Racks Market |
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mount Cabinets, Floor-Standing Racks, Open Frame Racks, Enclosed Racks, Server Cabinets Technology: Fiber Optic Cable Management, Airflow Cooling Systems, Cable Routing Accessories, Shock Absorption Features, Temperature Control Units Application: Data Centers, Network Operations, Broadcasting Stations, Telecommunications Exchanges, Cloud Service Providers End User: Internet Service Providers, Wireless Network Operators, Satellite Communications Firms, Managed Service Providers, System Integrators |
| Companies Covered | Schneider Electric, Rittal GmbH & Co. KG, Vertiv Group Corp., Eaton Corporation, Hewlett Packard Enterprise, Dell Technologies, Cisco Systems, Fujitsu, Legrand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Telecommunication Equipment Cabinet and Racks Market Strategic Shifts & Innovations
Transformation from a passive structural enclosure into an active, intelligent component of the IT ecosystem marks the current era for cabinets. This shift is driven by the need to manage higher thermal loads and integrate more sophisticated power and monitoring systems directly.
Intelligent rack systems embed sensors for real-time environmental and power monitoring. Hyperscale and colocation providers rapidly adopt these systems to improve operational visibility. This integration is unifying the physical infrastructure layer with DCIM software, turning the cabinet from a passive box into an active network node.
The European Union's Corporate Sustainability Reporting Directive (CSRD) mandates detailed disclosure of energy consumption. This regulation creates an urgent need for auditable data on infrastructure efficiency for large enterprises. Consequently, data center operators in the EU are prioritizing cabinet solutions offering superior thermal performance to aid compliance.
A notable demand-side shift is the move toward procuring pre-integrated rack systems. This model disrupts traditional on-site assembly, favoring vendors that deliver fully populated and tested "rack-and-roll" solutions. This approach is most visible in the hyperscale segment, where rapid deployment is a critical competitive factor.
Global Telecommunication Equipment Cabinet and Racks Market Segmentation
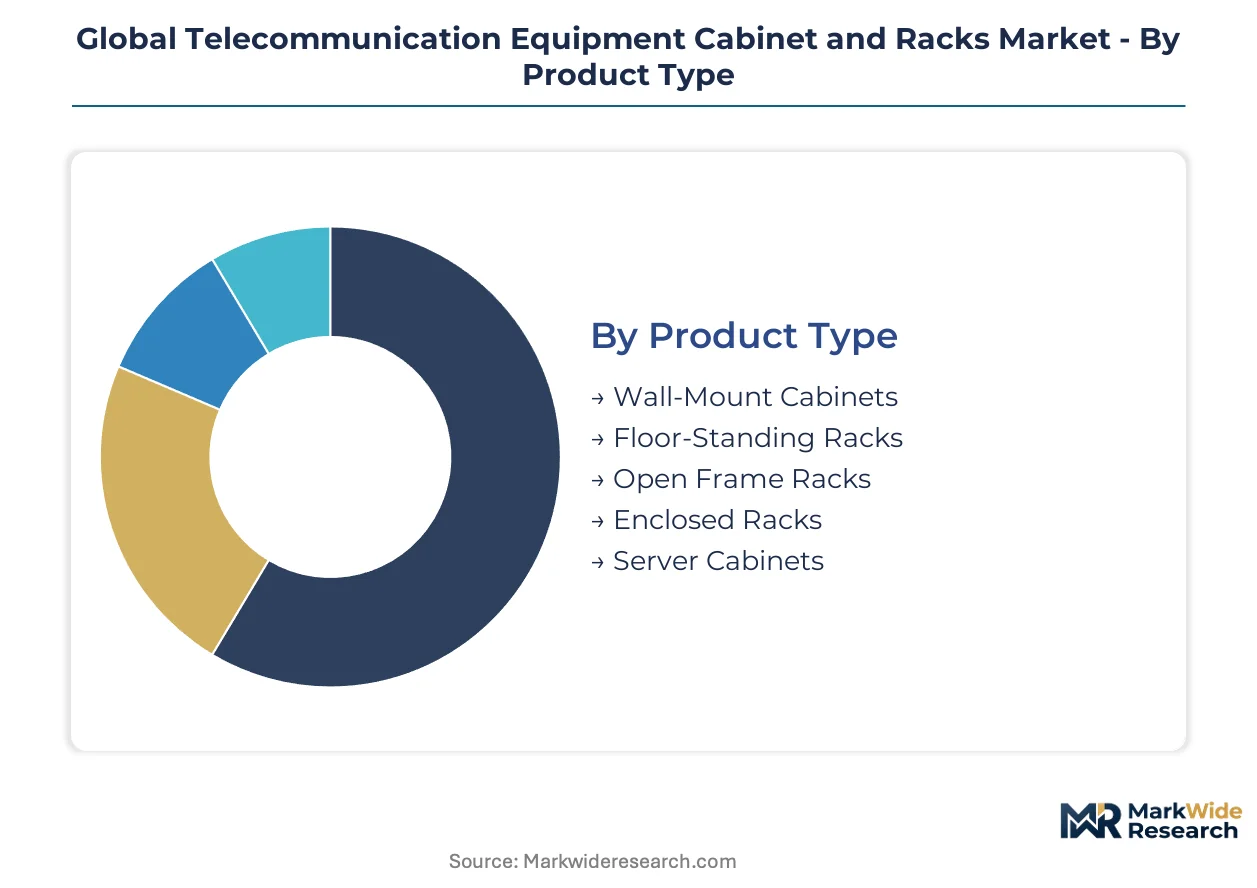
The segmentation of the global telecommunication equipment cabinet and racks market provides a granular view into the diverse product offerings and their strategic applications. This analysis differentiates between high-volume, standardized solutions and specialized, performance-driven enclosures that cater to specific operational demands.
Product Type:
The product type segmentation highlights the volume-driven solutions versus premium, specialized enclosures in the telecommunication equipment cabinet and racks market.
- Floor-Standing Racks:These robust, standardized enclosure systems are typically fabricated from steel or aluminum, conforming to 19-inch or 23-inch width standards. Hyperscale data centers in the United States generate high-volume demand for these racks, supporting high-density server configurations.
- Enclosed Racks:Designed with front and rear doors and side panels, these racks provide enhanced security, airflow management, and noise reduction for sensitive IT equipment. Demand from colocation providers and enterprise data centers in Europe prioritizes these racks for their superior thermal performance and regulatory compliance.
- Wall-Mount Cabinets:These compact enclosures attach directly to walls, saving floor space in network closets and edge computing sites.
- Open Frame Racks:Offering maximum airflow and easy access to equipment, these racks are suitable for controlled environments where security is less critical.
- Server Cabinets:Specifically designed to house servers, these cabinets often include advanced thermal management features and cable routing options.
Today's leader: Floor-Standing Racks. Tomorrow's challenger: Enclosed Racks.
Technology:
Technology differentiation in this market centers on enhancing thermal management and data integrity for housed equipment.
- Airflow Cooling Systems:These integrated solutions manage heat dissipation through fans, baffles, and optimized rack layouts, crucial for maintaining operational temperatures within high-density environments. Data centers increasingly deploy these systems to mitigate rising power densities while adhering to stricter energy efficiency mandates.
- Temperature Control Units:Specialized units, often integrated into cabinets, actively regulate internal temperatures using refrigeration or advanced heat exchange mechanisms. Hyperscale facilities and high-performance computing clusters in North America rely on these units to prevent thermal throttling and ensure hardware longevity.
- Fiber Optic Cable Management:These systems organize and protect delicate fiber optic cables within the rack, preventing damage and simplifying maintenance.
- Cable Routing Accessories:Components like cable trays, managers, and ties ensure organized and efficient power and data cable distribution within enclosures.
- Shock Absorption Features:Integrated dampening mechanisms protect sensitive equipment from vibrations and physical impacts, particularly in industrial or mobile deployments.
Airflow Cooling Systems are expanding most quickly, while Shock Absorption Features are gaining market share.
Application:
Application segmentation reveals how telecommunication equipment cabinets and racks are deployed across various critical infrastructure types.
- Data Centers:These facilities house centralized computing and networking equipment, utilizing floor-standing racks and enclosed cabinets for high-density server deployments. Hyperscale data centers in the United States represent a significant portion of the demand for these solutions.
- Cloud Service Providers:Companies offering cloud computing services deploy vast arrays of servers and networking gear, often requiring custom or pre-integrated rack systems for rapid scaling. This segment drives demand for flexible and energy-efficient cabinet designs.
- Network Operations:Control centers for managing telecommunication networks use cabinets for housing routing, switching, and monitoring equipment.
- Broadcasting Stations:These facilities utilize specialized racks to organize audio, video, and transmission equipment, ensuring signal integrity and operational reliability.
- Telecommunications Exchanges:Central offices for telecommunication services house critical switching and transmission infrastructure within robust, secure cabinets.
Data Centers exhibit the steepest expansion trajectory, with Broadcasting Stations showing consistent growth.
End User:
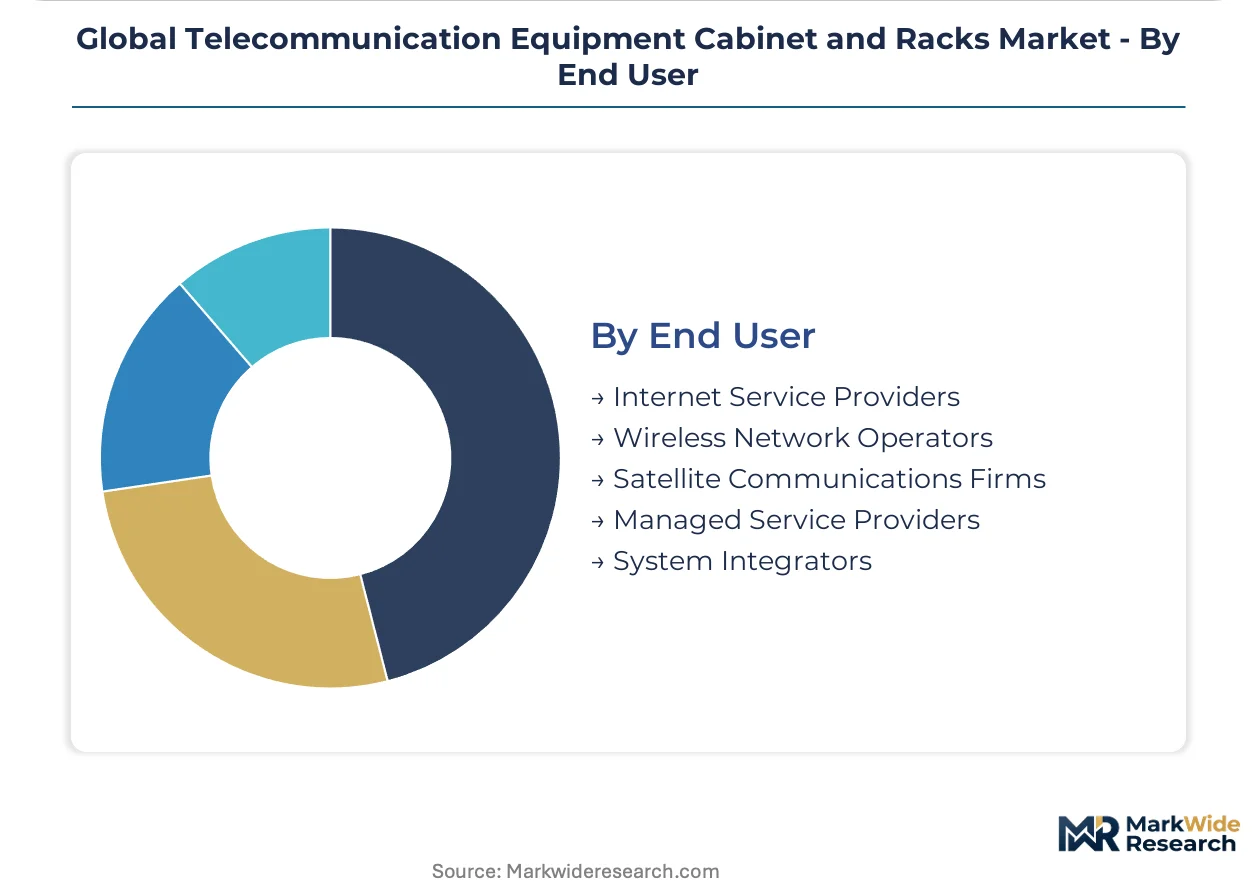
The end-user segment delineates the primary operators and service providers leveraging telecommunication equipment cabinet and rack solutions.
- Internet Service Providers:These entities provide internet access to consumers and businesses, deploying extensive network infrastructure housed in various cabinet and rack types. Global 5G network rollouts are driving new demand for outdoor cabinets among these providers.
- Wireless Network Operators:Companies managing cellular and other wireless communication networks utilize cabinets for base stations, antennas, and associated radio equipment. The ongoing expansion of 5G infrastructure necessitates vast numbers of these protective enclosures.
- Satellite Communications Firms:Operators of satellite networks employ specialized racks for ground station equipment and data processing units.
- Managed Service Providers:These firms offer outsourced IT services, deploying and managing client infrastructure within their own data centers or colocation facilities.
- System Integrators:Companies specializing in assembling and deploying complex IT solutions often procure cabinets and racks as part of larger project installations.
Internet Service Providers command the largest share, while System Integrators are demonstrating rapid market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The telecommunication equipment cabinet and racks market, while globally distributed, finds its foundational demand in regions pioneering high-density computing and advanced network infrastructure. Early scaling of data center technology in the United States established critical design precedents. Today, diverse regulatory and technological forces shape regional market trajectories.
United States
Hyperscale data center projects and the rapid expansion of edge computing drive substantial demand for advanced rack solutions. The FCC's regulatory framework influences telecom infrastructure deployment and equipment standards. Silicon Valley continues to foster innovation, particularly in high-density server configurations and thermal management.
Germany
European enterprises and colocation providers in Germany increasingly seek thermally efficient cabinet designs to meet stringent operational requirements. The EU's Corporate Sustainability Reporting Directive (CSRD) mandates transparent energy consumption reporting for large organizations. Frankfurt's prominent data center cluster actively adopts solutions that enhance infrastructure efficiency.
China
China's aggressive 5G network buildouts and the expansion of domestic cloud services fuel significant demand for telecommunication equipment cabinets. Compliance with China's GB standards is essential for market access, influencing material composition and electrical safety. Metropolitan areas like Beijing and Shanghai are seeing widespread deployment of next-generation telecom infrastructure.
India
Data localization laws and a surge in new data center construction are creating greenfield opportunities for rack and cabinet suppliers across India. The PLI scheme incentivizes local manufacturing and technology adoption within the digital infrastructure sector. Bengaluru's dynamic tech ecosystem drives demand for robust and secure rack systems for various applications.
Brazil
Brazil's expanding digital infrastructure and growing cloud service adoption necessitate increased deployment of telecommunication equipment. National data protection laws and ANVISA regulations guide equipment safety and quality standards. São Paulo serves as a primary hub for data center development, attracting investment in advanced rack and cabinet solutions.
Global Telecommunication Equipment Cabinet and Racks Market Key Industry Players
Premium-margin players sit above commodity-margin players across the solution integration spectrum, distinguishing between high-value, integrated offerings and standardized, volume-driven products. The market structure is tiered, featuring global integrated solutions providers, specialized modular system manufacturers, and regional fabricators. Dominant competitive moves include portfolio diversification into power management and cooling, alongside strategic geographic expansion into emerging markets.
Among global integrated solution providers, Schneider Electric and Vertiv Group Corp. exemplify companies offering comprehensive power, thermal, and IT infrastructure management. Schneider Electric leverages its extensive portfolio in power management and cooling to address efficiency requirements. Vertiv Group Corp. competes with integrated solutions combining power, thermal management, and IT infrastructure monitoring for enterprise and colocation data centers. Rittal GmbH & Co. KG, a German-based company, represents specialized modular enclosure systems designed for high-density server configurations in demanding environments. These firms often focus on delivering integrated solutions that address both performance and sustainability requirements for enterprise and hyperscale clients globally.
| Leading Market Players |
|---|
| Schneider Electric |
| Rittal GmbH & Co. KG |
| Vertiv Group Corp. |
| Eaton Corporation |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Cisco Systems |
| Fujitsu |
| Legrand |
| Others |
Cost & Logistics Intelligence
The European Union's Corporate Sustainability Reporting Directive (CSRD) gates both qualified supply and premium-tier pricing access for telecommunication equipment cabinets and racks. This mandate drives manufacturers toward higher energy efficiency, impacting material choices and design complexities.
Pricing Analysis
Project-based contract pricing dominates the telecommunication equipment cabinet and racks market for large-scale deployments. Price differentiation stems from customization level for specific power densities and the brand premium associated with integrated solution providers. Pricing softness reflects raw material price volatility, particularly for steel and aluminum, impacting manufacturer margins. Hyperscale data centers demonstrate the least price sensitivity due to their focus on rapid deployment and high performance, while smaller colocation providers are more price-sensitive.
Supply Chain Analysis
Compliance with IEC and China's GB standards serves as a critical qualification gate for component suppliers, ensuring product safety and performance across global markets. Geographic supply concentration for raw materials like steel and aluminum resides primarily in China and India. The supply chain relies on specialized components such as intelligent power distribution units and cooling fans. Commodity price volatility for metals represents a significant structural risk. Distribution runs through a blend of direct sales to large data center operators and a network of system integrators for smaller deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a late-cycle quality story, with demand shifting toward premium specifications driven by strict energy efficiency mandates. Data center operators increasingly prioritize solutions that offer superior thermal performance and auditable energy consumption data.
For Market Incumbents: To counter the threat of commoditization in standard rack segments, incumbents should deepen their portfolio diversification into advanced thermal management and intelligent power solutions. Investing in R&D for integrated liquid cooling systems offers a lever to capture high-value AI and HPC workloads. Expanding certified manufacturing capacity in emerging markets like India will also mitigate supply chain risks.
For New Entrants and Emerging Players: Specialized equipment distributors represent a viable channel to penetrate underserved regional markets for wall-mount cabinets and open frame racks. Targeting edge computing sites and network operations closets, where space is constrained, offers a penetrable segment. A go-to-market strategy focusing on rapid customization and local support can differentiate new players.
For Investors and Strategic Acquirers: Roll-up economics work for specialized modular system manufacturers because structural fragmentation exists within niche product categories. Long-term viability extends over a 5-10 year window, driven by continuous infrastructure upgrades and 5G network expansion. A signal to watch is the increasing adoption rate of integrated liquid cooling solutions in hyperscale projects, indicating future market direction.
| Strategic Initiative | Industry Significance |
|---|---|
| Portfolio Diversification into Liquid Cooling | This move addresses extreme power density needs for AI and HPC, expanding revenue streams for providers. |
| Geographic Expansion into Emerging Markets | New data center construction in India and Brazil opens greenfield opportunities for rack and cabinet suppliers. |
| Investment in Modular Enclosure Systems | Enhancing modularity supports high-density server configurations and simplifies deployment for colocation providers. |
| Strategic Partnerships for DCIM Integration | Integrating physical infrastructure with DCIM software transforms cabinets into active, intelligent network nodes. |
| Certification for Sustainability Standards | Achieving compliance with directives like the EU's CSRD enables access to premium, efficiency-driven market segments. |
Research Approach
Multiple input streams — primary interviews with industry stakeholders, secondary market research, and proprietary databases — were reconciled to build a comprehensive market view. This involved engaging with CTOs, IT procurement officers, data center operators, and telecom network engineers. Secondary validation drew from regulatory filings, industry association reports, and technical publications.
The analytical framework triangulated volume and value outputs across the analysis window, integrating historical data with forward-looking projections. Segmentation dimensions modeled included product type, technology, application, end-user, and regional demand patterns. Compound Annual Growth Rates were derived from a multi-stage forecasting model, incorporating factors like 5G rollout schedules and hyperscale data center investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and technological advancements in cooling solutions. The analysis reflects assumptions regarding sustained digital infrastructure investment and evolving regulatory landscapes. A model refresh is warranted upon material change in global data center construction rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
New Zealand Data Center Rack Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Green Data Center Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
Sweden Data Center Construction Market
Data Center Infrastructure
Canada Data Center Market
Data Center Infrastructure
South Africa Data Center Power Market
Data Center Infrastructure
Taiwan Data Center Physical Security Market
Data Center Infrastructure
South Africa Data Center Rack Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Malaysia Data Center Networking Market
Data Center Infrastructure
Managed Data Center Services Market
Data Center Infrastructure
Nigeria Data Center Physical Security Market
Data Center Infrastructure
France Data Center Server Market