
 Indonesia Data Center Server Market | 2026-2036
Indonesia Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Server Market Insights
Jakarta's hyperscale corridor is consolidating around purpose-built facilities with dual power feeds and liquid cooling readiness. Dell Inc anchors the premium rack server segment through direct enterprise relationships with Indonesian banks. Huawei Technologies Co Ltd competes aggressively on converged systems bundling virtualization with security solutions. Lenovo Group Limited leverages its ThinkSystem line to target mid-market IT service companies seeking standardized deployments.
Data center servers are compute nodes housed in standardized chassis, typically supporting Intel Xeon or AMD EPYC processors with DDR5 memory and NVMe storage, designed for continuous operation in controlled environments with N+1 redundancy. Rack servers dominate Indonesian procurement due to density requirements in leased colocation space, while blade servers retain share among telecom providers optimizing for cable management and shared power infrastructure. Edge computing installations are gaining traction among e-commerce firms requiring sub-20 millisecond latency for payment verification and inventory synchronization.
BIS certification requirements for electromagnetic compatibility shape import timelines for server hardware entering Indonesia, while the Ministry of Communication and Informatics enforces data localization rules that mandate domestic storage for financial and public sector workloads. PLI scheme incentives for electronics manufacturing are attracting assembly investments that could shorten supply chains for locally deployed units. Stakeholders must weigh domestic assembly partnerships against direct import strategies as localization requirements tighten and energy efficiency standards for data center operations take effect.
Market Dynamics
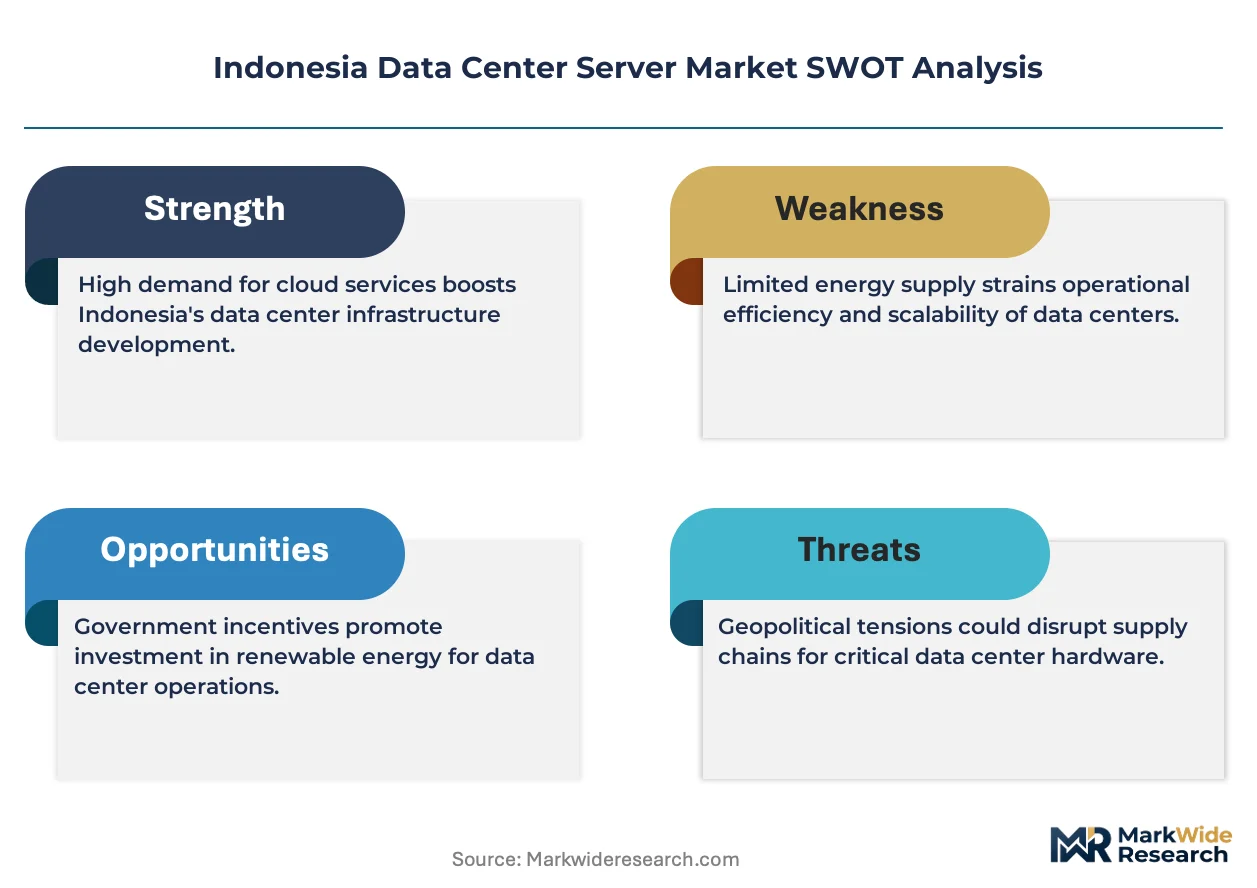
Data localization mandates from Indonesia's Ministry of Communication and Informatics are forcing hyperscale cloud providers to deploy domestic server infrastructure rather than serving Indonesian workloads from Singapore or Hong Kong facilities.
Growth Catalysts
- Financial sector digitization:Indonesian banks are expanding real-time transaction processing infrastructure to support instant payment rails and mobile banking penetration.
- Submarine cable proximity:Hyperscale facilities cluster near landing stations in Greater Jakarta, reducing latency for international connectivity.
- PLI scheme incentives:Electronics manufacturing incentives are attracting server assembly investments that shorten supply chains for locally deployed units.
Market Restraints
- BIS certification timelines:Electromagnetic compatibility testing requirements extend import lead times for server hardware entering Indonesian customs.
- Limited domestic silicon:Processor and memory component supply concentrates among Taiwanese and South Korean foundries, creating concentration risk.
- Power infrastructure gaps:Grid reliability outside Greater Jakarta limits data center site selection for secondary Indonesian markets.
Strategic Opportunities
- Edge computing for e-commerce:Sub-20 millisecond latency requirements for payment verification and inventory synchronization are driving distributed server deployments.
- Liquid cooling readiness:Purpose-built facilities with dual power feeds are integrating immersion and direct-to-chip cooling for next-generation thermal management.
- Mid-market standardization:IT service companies seek standardized rack server deployments that reduce configuration complexity and accelerate provisioning cycles.
Industry Challenges
- Energy efficiency compliance:New standards for data center power usage effectiveness are forcing facility operators to retrofit cooling and power distribution systems.
- Skill gaps in advanced cooling:Liquid cooling deployment requires specialized technicians that remain scarce in Indonesian labor markets.
- Legacy system integration:Financial institutions must bridge on-premise core banking infrastructure with cloud-native server architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Server Market |
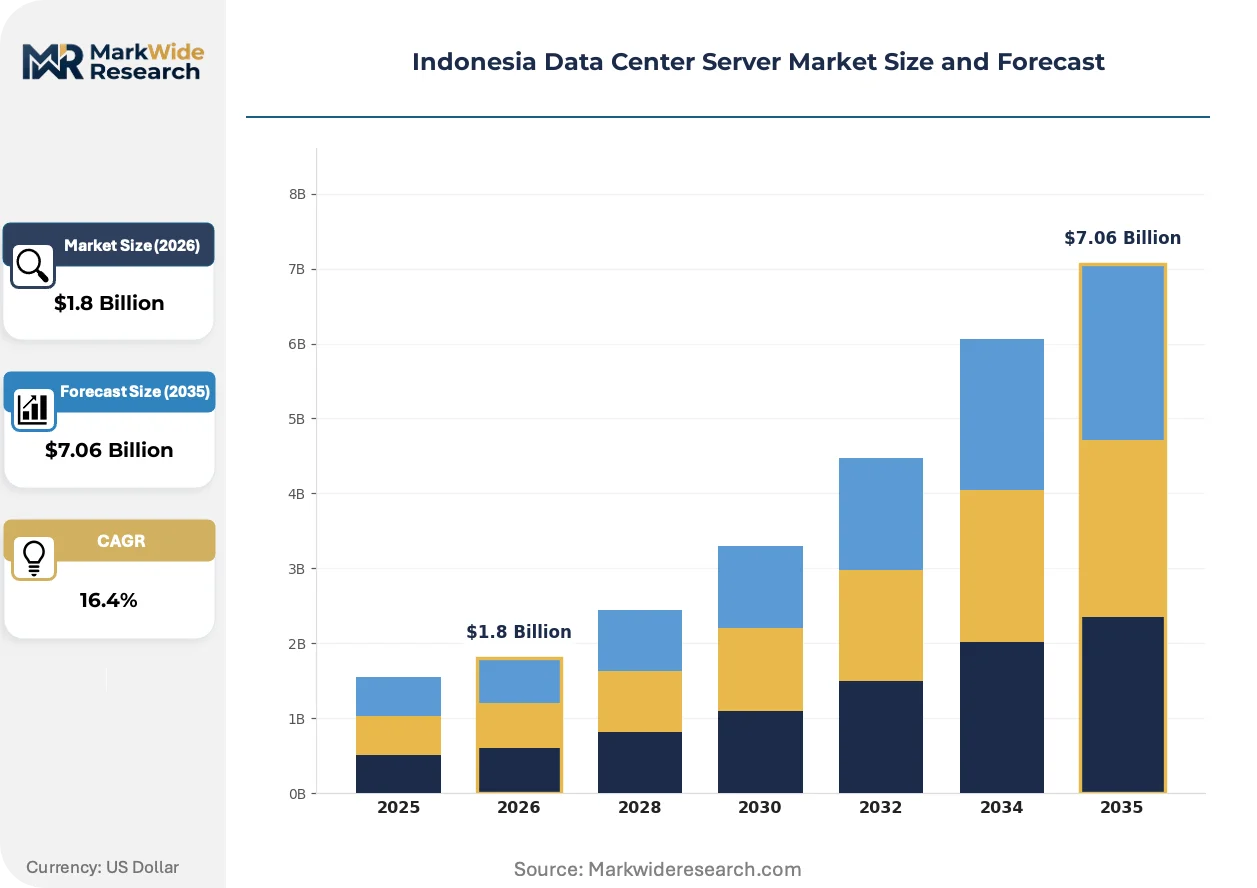
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blade Servers, Rack Servers, Tower Servers, Converged Systems End User: Telecom Providers, IT Service Companies, Financial Institutions, E-commerce Firms Installation: On-premises, Cloud-based, Hybrid, Edge Computing Technology: Virtualization, High-Performance Computing, Storage Solutions, Security Solutions |
| Companies Covered | Lenovo Group Limited, Huawei Technologies Co Ltd, HP Enterprise, Super Micro Computer Inc, Inspur Group, IBM Corporation, Fujitsu Limited, Kingston Technology Corporation, Dell Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Server Market Trends and Innovations
Liquid cooling technologies and edge-optimized server form factors are compressing deployment timelines while Indonesian regulators tighten operational standards for data center energy efficiency.
Direct-to-chip and immersion cooling systems are integrating with high-density rack configurations to manage thermal loads from AMD EPYC and Intel Xeon processors exceeding 300 watts per socket. Indonesian hyperscale operators are adopting these systems ahead of tropical climate constraints that strain traditional air-cooled designs. The technology is integrating facility-level power and cooling management with server telemetry to enable dynamic workload placement based on real-time thermal conditions.
Indonesia's Ministry of Communication and Informatics data localization rules are mandating domestic server storage for financial transactions and public sector workloads. Foreign cloud providers are responding by constructing owned facilities rather than leasing colocation space. Banking and fintech segments face the steepest compliance timelines as regulators phase in audit requirements for cross-border data flows.
Leasing structures are displacing capital purchases among mid-market enterprises seeking to avoid stranded asset risk from rapid generational transitions in processor architecture. Colocation providers are responding with managed server offerings that bundle hardware refresh cycles with facility operations. This pattern concentrates most visibly among Jakarta-based e-commerce platforms and logistics operators scaling infrastructure for peak transaction periods.
Indonesia Data Center Server Market Segmentation
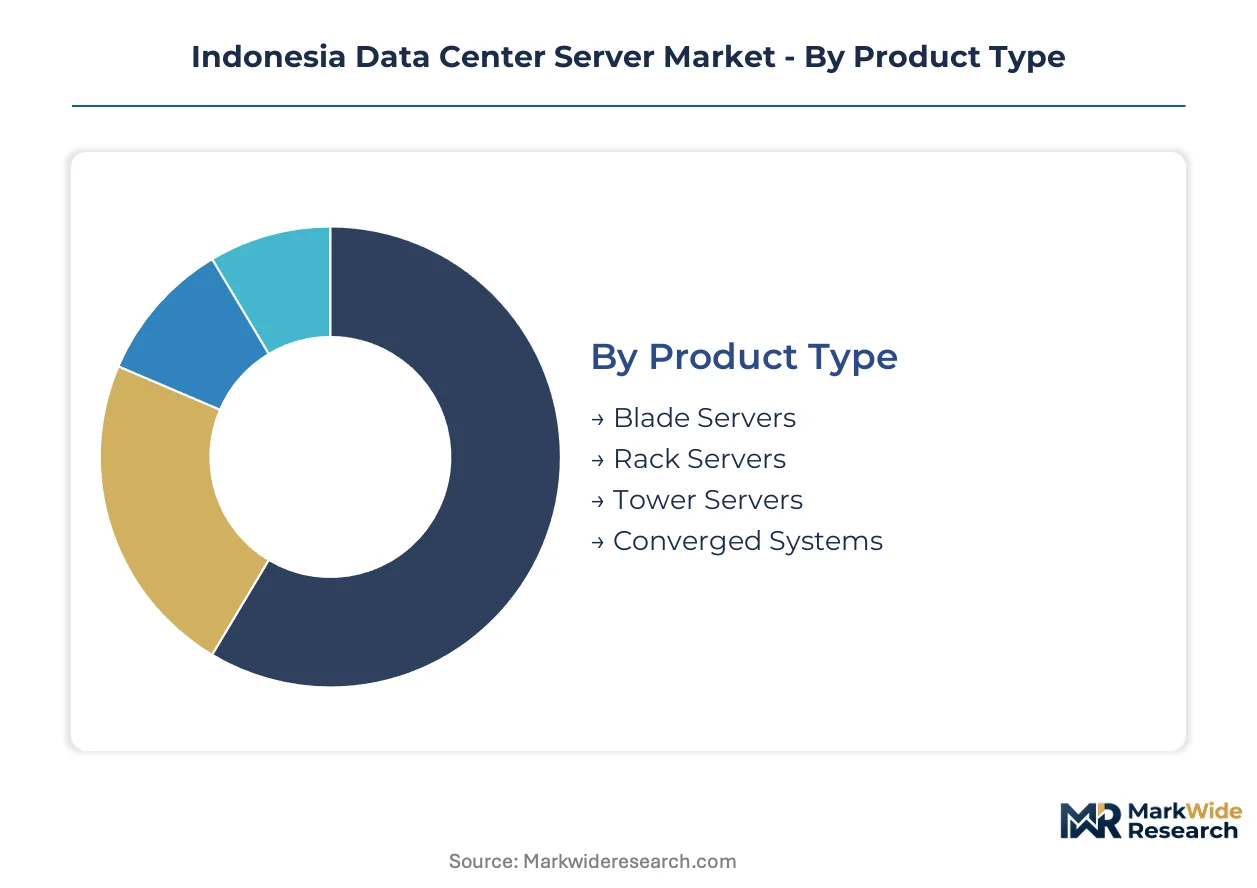
Server procurement patterns in Indonesia diverge sharply across deployment contexts, with hyperscale operators prioritizing density and thermal efficiency while mid-market buyers emphasize standardization and lease flexibility. Understanding these segment boundaries reveals where procurement power concentrates and which technical specifications dominate purchasing criteria.
Product Type:
Form factor selection in Indonesian data centers hinges on power density constraints, cable management requirements, and cooling architecture compatibility with tropical operating conditions.
- Rack Servers:Standardized chassis supporting Intel Xeon or AMD EPYC processors with DDR5 memory and NVMe storage, optimized for 42U to 48U cabinet deployment. Indonesian banks and hyperscale operators in Greater Jakarta specify these units for leased colocation space where floor loading and power feed density limit alternatives. The Ministry of Communication and Informatics data localization mandates are accelerating rack server procurement for domestic cloud infrastructure buildouts.
- Blade Servers:Modular compute nodes sharing chassis-level power and cooling infrastructure, enabling dense packaging of multiple independent servers. Telecom providers across Java deploy blade architectures to optimize cable management in facilities with constrained raised-floor space and shared power distribution units. BIS electromagnetic compatibility certification timelines affect import scheduling for blade chassis with integrated networking backplanes.
- Tower Servers:Standalone vertical chassis designed for small-scale deployments without rack infrastructure. Regional bank branches and provincial government offices outside Greater Jakarta specify tower units where dedicated server rooms lack raised flooring or precision cooling.
- Converged Systems:Pre-integrated compute, storage, and networking bundles with unified management platforms. Mid-market IT service companies seeking rapid deployment without specialized integration labor favor these configurations for standardized service offerings.
Rack servers lead on scale; converged systems lead on momentum among buyers prioritizing deployment velocity over customization depth.
End User:
Procurement authority and technical specification authority vary significantly across buyer categories, with regulated industries facing mandatory domestic infrastructure requirements that reshape vendor selection criteria.
- Financial Institutions:Indonesian banks expanding real-time transaction processing infrastructure for instant payment rails and mobile banking penetration. Regulatory mandates from the central bank and Ministry of Communication and Informatics require domestic server storage for transaction data, compelling on-premise and local cloud deployments rather than regional hub reliance.
- Telecom Providers:National operators optimizing core network functions and subscriber data management in facilities with constrained physical footprints. Blade server architectures dominate procurement for cable management efficiency and shared power infrastructure utilization.
- IT Service Companies:Managed service providers and systems integrators delivering standardized infrastructure to mid-market enterprises. These buyers prioritize rack server standardization to reduce configuration complexity and accelerate provisioning cycles across heterogeneous client environments.
- E-commerce Firms:Digital commerce platforms requiring sub-20 millisecond latency for payment verification and inventory synchronization. Edge computing installations are gaining traction among Jakarta-based operators scaling infrastructure for peak transaction periods during promotional campaigns.
Financial institutions lead on scale; e-commerce firms lead on momentum as distributed edge deployment accelerates.
Installation:
Deployment model selection reflects risk tolerance for capital intensity, regulatory compliance obligations, and workload latency requirements across Indonesian market verticals.
- On-premises:Owned and operated server infrastructure within enterprise-controlled facilities. Financial institutions and government agencies mandate on-premise deployment for regulated workloads subject to Ministry of Communication and Informatics audit requirements for cross-border data flow restrictions.
- Cloud-based:Server resources provisioned from hyperscale provider facilities with utility pricing models. Foreign cloud providers are constructing owned facilities in Greater Jakarta rather than leasing colocation space to satisfy data localization compliance.
- Hybrid:Workload distribution across owned infrastructure and cloud resources with orchestration layer integration. Banks bridging legacy core banking systems with cloud-native architectures favor hybrid configurations during multi-year migration timelines.
- Edge Computing:Distributed server deployments positioned close to data generation or consumption points. E-commerce logistics operators and payment processors deploy edge nodes for inventory synchronization and transaction verification latency reduction.
On-premises leads on scale; edge computing leads on momentum as latency-sensitive applications proliferate.
Technology:
Functional capability layers determine competitive differentiation and pricing architecture, with security and virtualization features commanding premium positioning in regulated Indonesian sectors.
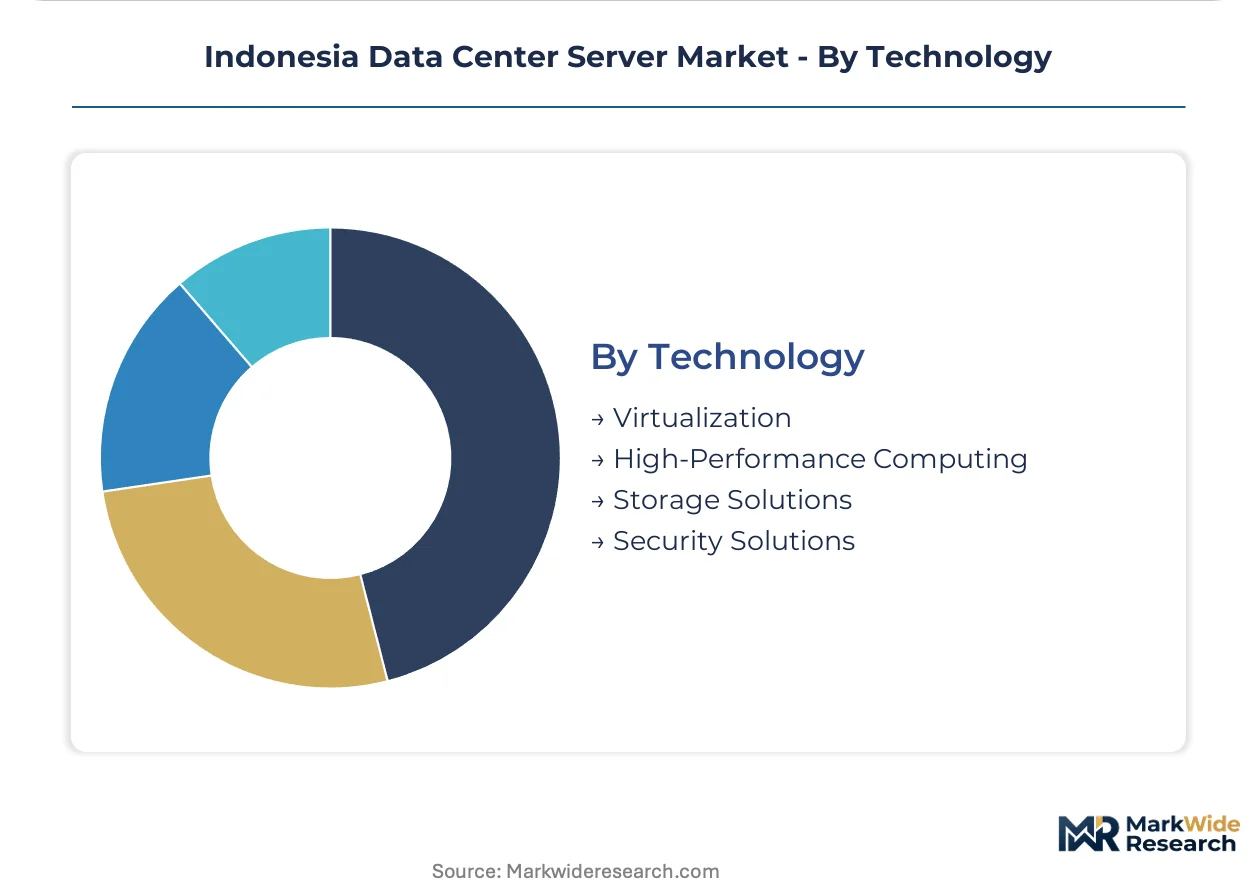
- Virtualization:Software abstraction enabling multiple operating environments on shared physical hardware. IT service companies and cloud providers standardize on virtualization platforms to maximize hardware utilization and enable rapid workload migration.
- Security Solutions:Hardware-rooted encryption, secure boot, and trusted execution environments. Financial institutions specify security-enhanced processors and firmware to satisfy central bank cybersecurity audit requirements for transaction processing infrastructure.
- High-Performance Computing:Accelerated compute architectures with GPU or FPGA integration for parallel processing workloads. Research institutions and petroleum exploration companies deploy HPC clusters for seismic processing and reservoir simulation.
- Storage Solutions:Software-defined storage and NVMe-over-fabrics integration for high-throughput data access. Hyperscale operators in Greater Jakarta specify all-flash configurations to minimize latency for real-time analytics workloads.
Virtualization leads on scale; security solutions lead on momentum as regulatory compliance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping server deployment patterns as data localization mandates in Indonesia create compliance cost gaps that favor domestic infrastructure buildouts over regional hub reliance. Foreign cloud providers face escalating penalties for cross-border data flows, redirecting capital toward owned facilities in Greater Jakarta rather than leased capacity in Singapore.
Greater Jakarta
Hyperscale operators cluster server deployments near submarine cable landing stations to minimize latency for international connectivity. The Ministry of Communication and Informatics enforces strict data localization audit requirements for financial workloads processed in this corridor. Cikarang and Bekasi industrial zones are absorbing liquid-cooled facility investments from cloud providers seeking tropical climate resilience.
West Java
Mid-market IT service companies standardize rack server procurement for heterogeneous client environments across Bandung and surrounding tech parks. PLI scheme incentives for electronics manufacturing are attracting assembly investments that shorten supply chains for locally deployed units. The region is emerging as a secondary hub for edge computing nodes serving e-commerce logistics networks.
East Java
Regional bank branches and provincial government offices specify tower server deployments where dedicated facilities lack precision cooling infrastructure. Grid reliability constraints outside the capital limit data center site selection, concentrating smaller-scale installations in Surabaya's emerging digital zones. Telecom providers optimize blade server architectures for cable management in constrained raised-floor environments.
Bali and Eastern Indonesia
Tourism-dependent digital service providers deploy edge computing installations for payment verification latency reduction across hospitality networks. Limited submarine cable connectivity creates infrastructure gaps that favor distributed server topologies over centralized hyperscale models. Local regulators are phasing in data localization requirements that will compel domestic storage for visitor transaction data.
Sumatra
Petroleum exploration companies in Riau and Aceh deploy high-performance computing clusters for seismic processing and reservoir simulation workloads. The island's industrial corridors face power infrastructure gaps that constrain large-scale data center development outside Medan. Provincial governments are negotiating with hyperscale providers for edge node placement to support agricultural commodity trading platforms.
Indonesia Data Center Server Market Competitive Landscape
US-based producers anchor the premium enterprise tier; Chinese specialists hold converged systems and mid-market standardization segments. The vendor base stratifies across three functional layers: direct enterprise relationship holders, integrated solution bundlers, and hardware-as-a-service platform operators. Strategic moves concentrate on domestic assembly partnerships to satisfy PLI scheme localization requirements and liquid cooling technology licensing for tropical climate deployments.
Within the premium rack server tier, Dell Inc anchors direct enterprise relationships with Indonesian financial institutions facing strict central bank cybersecurity audit requirements. Huawei Technologies Co Ltd occupies a position among converged system specialists bundling virtualization with security solutions for regulated sectors. Lenovo Group Limited exemplifies the mid-market standardization archetype, with its ThinkSystem line targeting IT service companies seeking reduced configuration complexity and accelerated provisioning cycles.
| Leading Market Players |
|---|
| Lenovo Group Limited |
| Huawei Technologies Co Ltd |
| HP Enterprise |
| Super Micro Computer Inc |
| Inspur Group |
| IBM Corporation |
| Fujitsu Limited |
| Kingston Technology Corporation |
| Dell Inc |
| Others |
Pricing and Supply Chain Analysis
Premium-commodity bifurcation between liquid-cooled hyperscale deployments and air-cooled mid-market rack units manifests in divergent margin structures and sourcing strategies across Indonesian server procurement. Ministry of Communication and Informatics data localization mandates concentrate pricing power with domestic assembly partners qualifying for PLI scheme incentives, while direct import channels face BIS certification timeline penalties that compress distributor margins.
Pricing Analysis
Distributor markups on imported server hardware absorb BIS electromagnetic compatibility testing delays and customs clearance variability, while direct enterprise relationships with financial institutions command premium positioning through security-enhanced processor configurations. Three-tier pricing structure across liquid-cooled hyperscale, standard rack, and tower server tiers reflects certification grade differentiation and volume scale. Cost compression in mid-market standard rack segments intensifies as IT service companies consolidate procurement around Lenovo ThinkSystem and comparable standardized chassis. Banks and hyperscale operators exhibit lowest price sensitivity due to compliance-driven specification requirements, while provincial government offices outside Greater Jakarta demonstrate highest elasticity.
Supply Chain Analysis
Regional distribution centers in Singapore and Hong Kong feed Indonesian hyperscale builds through submarine cable landing stations, with hub-and-spoke patterns concentrating inventory staging in Greater Jakarta's Cikarang and Bekasi industrial zones. Processor and memory component supply draws from Taiwan, South Korea, and mainland China foundries, creating single-source vulnerability for advanced node silicon. DDR5 memory modules and NVMe storage controllers face logistics chokepoint exposure through the Strait of Malacca shipping corridor. Distribution runs through direct OEM relationships with financial institutions and managed service provider channels for mid-market standardization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's data center server market represents a late-cycle quality story as financial sector digitization shifts procurement toward security-enhanced, liquid-cooled premium specifications with domestic assembly requirements. Data localization enforcement from the Ministry of Communication and Informatics anchors this premium migration.
For Market Incumbents: Hedge stranded asset risk in air-cooled rack inventory by accelerating liquid cooling technology licensing partnerships for tropical climate deployments. Secure PLI scheme qualification through domestic assembly joint ventures before regulatory timelines tighten. Channel control over direct enterprise relationships with Indonesian banks provides defensive moats against converged system bundlers. For New Entrants and Emerging Players: Mid-market IT service companies represent the most penetrable channel partner type for standardized rack server offerings with accelerated provisioning cycles. Target edge computing nodes for e-commerce logistics networks in West Java's Bandung tech corridor as white-space expansion. White-label managed server leasing structures offer go-to-market velocity without capital-intensive facility construction. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic assembly specialists capturing PLI scheme incentives and shortening supply chains for hyperscale cloud providers. Long-term viability favors operators with liquid cooling deployment capabilities and Ministry of Communication and Informatics compliance infrastructure. Watch BIS certification timeline compression as inflection signal for import-dependent margin pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | PLI scheme qualification shortens supply chains for hyperscale cloud providers building in Greater Jakarta. |
| Liquid Cooling Technology Licensing | Tropical climate resilience enables next-generation thermal management for AMD EPYC and Intel Xeon deployments. |
| Security-Enhanced Processor Certification | Central bank cybersecurity audit requirements mandate hardware-rooted encryption for transaction processing infrastructure. |
| Edge Computing Node Expansion | Sub-20 millisecond latency specifications drive distributed server topology for e-commerce payment verification. |
| Managed Server Leasing Structure | Colocation bundling eliminates stranded asset risk for mid-market enterprises during generational processor transitions. |
Research Methodology
Bottom-up financial institution and hyperscale operator modeling reconciled against top-down server shipment tracking forms the analytical core of this study. Primary interviews with data center facility operators, IT procurement officers at Indonesian banks, channel distribution managers, and Ministry of Communication and Informatics regulatory affairs specialists combined with secondary validation from BIS certification databases, PLI scheme disclosure filings, and submarine cable landing station capacity reports. Triangulation between demand-side deployment schedules and supply-side import manifests anchored volume estimates.
Historical trendline analysis of rack server, blade server, and converged system procurement patterns informed projection frameworks across the analysis window. Segmentation dimensions modeled include form factor tier, end-use vertical, deployment model, and cooling architecture specification. CAGRs derived from elasticity-adjusted adoption curves for data localization compliance and real-time transaction processing infrastructure buildouts. Forecast inputs incorporated PLI scheme incentive phase-in schedules and BIS electromagnetic compatibility testing capacity constraints.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Ministry of Communication and Informatics enforcement intensity and Taiwan Strait logistics disruption scenarios. Outputs reflect documented assumptions around submarine cable capacity expansion and domestic assembly partnership formation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Middle East and Africa Containerized Data Center Market
Data Center Infrastructure
Airflow Management Equipment Market
Data Center Infrastructure
China Internet Data Center Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Composable Infrastructure Market
Data Center Infrastructure
Sweden Data Center Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
Chile Data Center Server Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
GCC Data Center Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Australia Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Hong Kong Data Center Server Market
Data Center Infrastructure
Data Center Outsourcing and Infrastructure Utility Services Market