
 Global Domain and Hosting Market | 2026-2036
Global Domain and Hosting Market Size, Share, and Industry Trends Forecast 2026-2036
Global Domain and Hosting Market Foresight
Buyer concentration is pivoting as enterprise procurement consolidates around hyperscale cloud contracts while millions of small businesses and freelancers fragment demand across low-cost shared hosting tiers. Amazon Web Services, Inc. leverages its global data center footprint to anchor premium enterprise workloads. Google LLC competes through deep integration with advertising and productivity ecosystems. Hostinger International, Ltd. specializes in automated onboarding tools that capture price-sensitive independent operators.
Domain and hosting services encompass the infrastructure, software platforms, and management tools that store website files, route domain name system queries, and deliver content to end users with target latency thresholds below 200 milliseconds for acceptable user experience. Cloud Hosting now captures the fastest expansion as organizations prioritize elastic compute scaling over fixed-capacity dedicated servers. Managed Hosting concentrates margin pools by bundling security patching, performance optimization, and compliance monitoring into recurring service contracts.
The US Federal Trade Commission scrutinizes deceptive pricing in domain renewal and hosting subscription practices, while the EU General Data Protection Regulation mandates data residency controls that influence provider data center placement decisions. China's Ministry of Industry and Information Technology enforces ICP licensing requirements that restrict foreign hosting operators from serving domestic websites without local partnership structures. Stakeholders must monitor evolving data localization mandates and carbon disclosure rules that will reshape provider capital allocation toward certified green data centers.
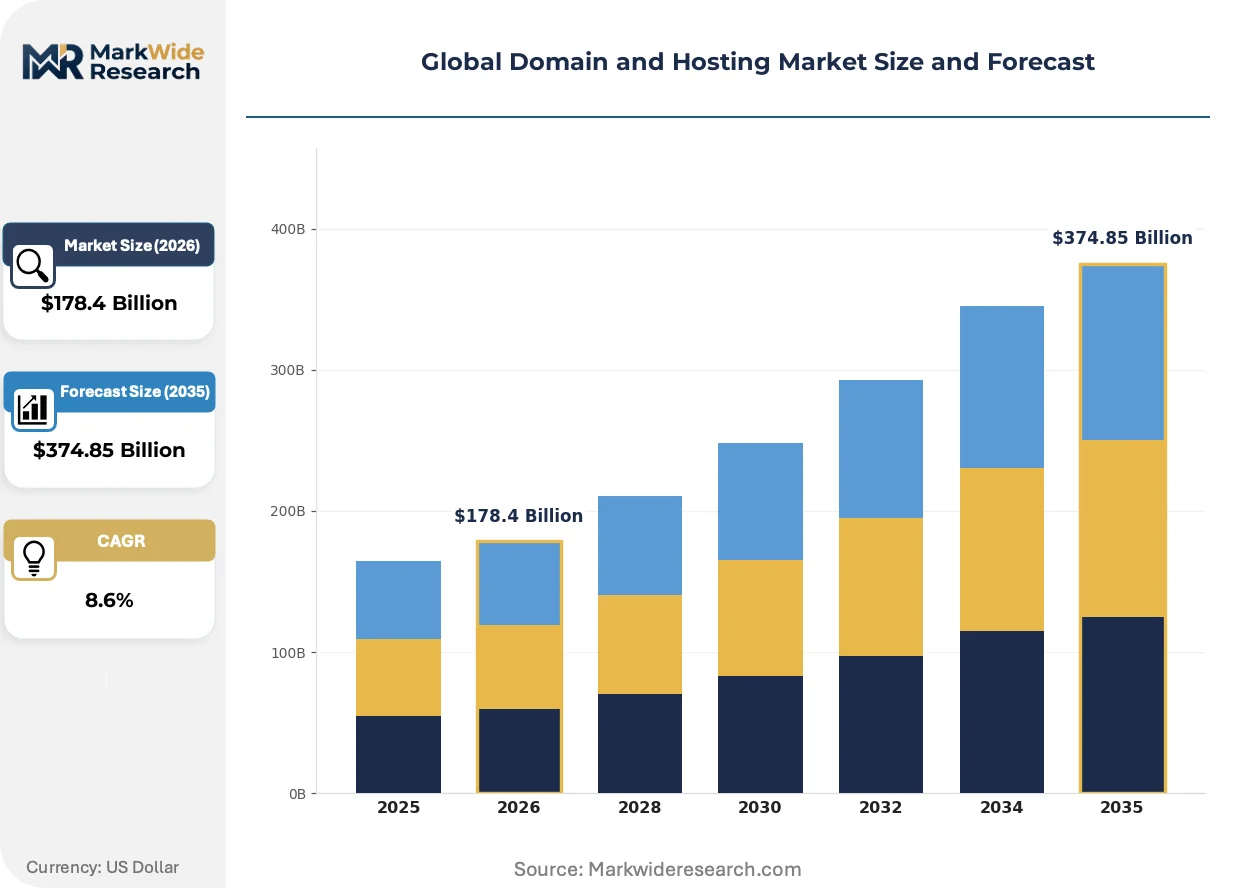
Market Dynamics
Enterprise workload migration to distributed cloud architectures is fragmenting traditional hosting revenue pools while forcing providers to rebuild margin structures around edge compute and sovereign data zones.
Growth Catalysts
- GDPR Data Residency Mandates:European enterprises now require localized hosting infrastructure, compelling providers to expand certified data center footprints across Germany, France, and the Netherlands.
- Container Orchestration Adoption:Kubernetes-native platforms enable developers to deploy microservices across multi-cloud environments without vendor lock-in.
- SME Digital Onboarding:India's Micro, Small and Medium Enterprises sector generates sustained demand for low-code website builders bundled with domain registration.
Market Restraints
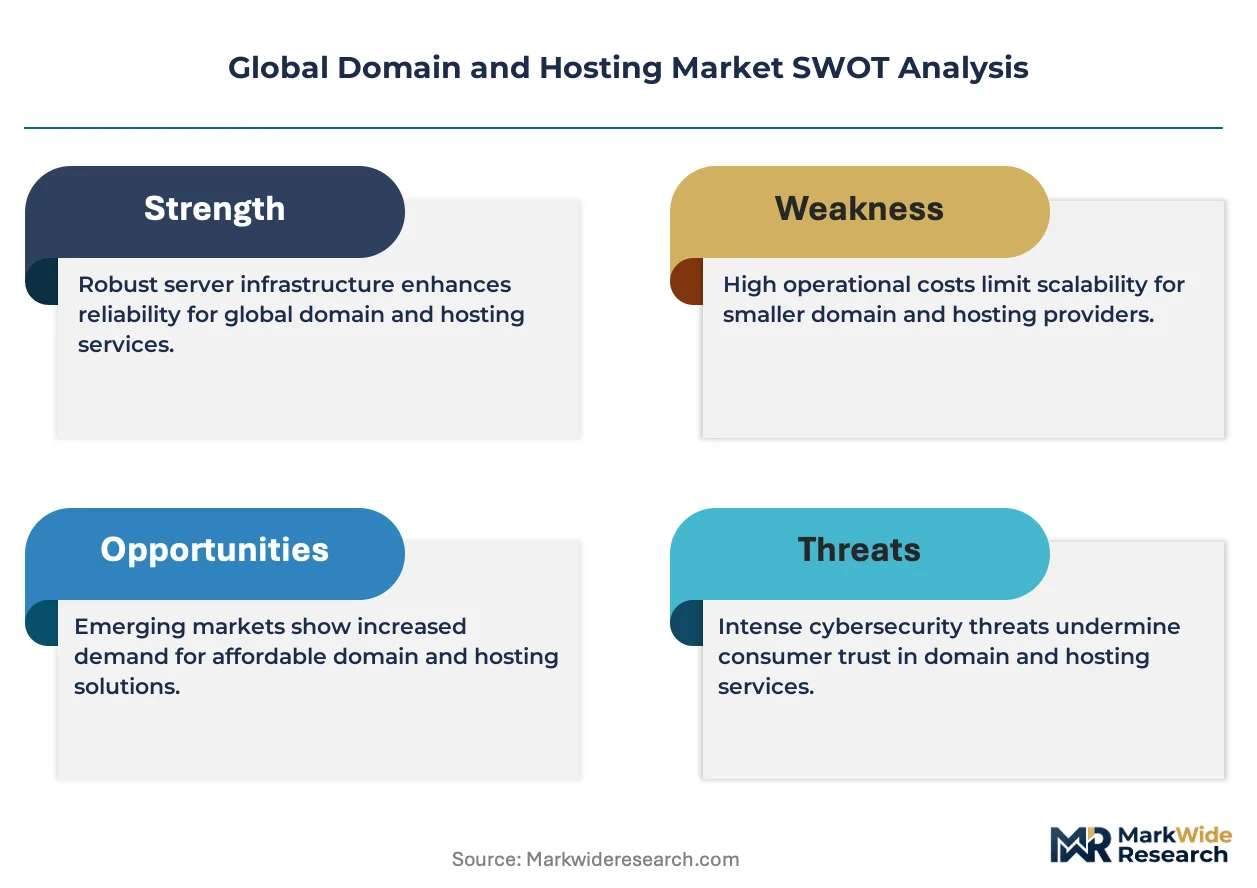
- Energy Cost Volatility:Data center operators face unpredictable electricity pricing that compresses gross margins on power-intensive dedicated server offerings.
- IPv4 Address Exhaustion:Regional Internet Registries have depleted available IPv4 blocks, forcing costly IPv6 migration or secondary market purchases.
- Cross-Border Data Transfer Friction:China's cybersecurity law restricts data flows outside its territory, complicating multinational hosting architectures.
Strategic Opportunities
- Indonesia's Underpenetrated SME Base:Southeast Asia's largest economy shows sub-40% business website penetration, creating whitespace for localized hosting providers.
- Green Data Center Certification:EU Green Deal carbon disclosure requirements reward operators achieving ISO 14001 environmental management standards.
- AI Inference Edge Deployment:Convergence of GPU-accelerated servers with 5G network slicing enables low-latency machine learning hosting at metropolitan edge nodes.
Industry Challenges
- Cloud-Native Talent Scarcity:Site reliability engineering and infrastructure-as-code expertise command premium compensation, inflating operational costs.
- Legacy System Integration:Enterprises maintaining on-premise mainframe workloads face complex API bridging requirements when adopting hybrid cloud models.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Domain and Hosting Market |
| Market Size in 2026 | $178.4 Billion |
| Market Size in 2035 | $374.85 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Shared Hosting, VPS Hosting, Dedicated Hosting, Cloud Hosting, Reseller Hosting, Managed Hosting Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises Customer Type: Small Businesses, Enterprises, Startups, Freelancers, Nonprofit Organizations Service Type: Domain Registration, SSL Certificates, Email Hosting, Website Builder, DNS Management, Backup Solutions |
| Companies Covered | GoDaddy Inc., Amazon Web Services, Inc., Newfold Digital, Inc., Google LLC, Alibaba Cloud Computing Co., Ltd., Hostinger International, Ltd., IONOS, Inc., Microsoft Azure, DigitalOcean, LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Domain and Hosting Market Shifts & Advancements
Serverless computing architectures and sovereign cloud requirements are compressing traditional managed hosting margins while opening specialized service tiers around compliance automation and carbon-transparent infrastructure.
Edge computing infrastructure is modularizing how content delivery networks deploy caching and compute resources. Retail and media enterprises now provision workloads across hundreds of metropolitan edge nodes rather than centralized hyperscale regions. This distribution is modularizing provider capital allocation away from mega-campus builds toward smaller, latency-optimized facilities.
REACH chemical restrictions and EU AI Act transparency requirements now govern data center hardware procurement and automated decision-making systems. European operators must document supply chain substance compliance and algorithmic audit trails for customer-facing AI tools. German and French enterprise buyers increasingly demand CSRD-aligned sustainability reporting from hosting partners.
Consumption-based billing models now displace fixed-term contracts across mid-market segments. Finance and SaaS verticals prefer metered infrastructure spending tied to actual compute utilization rather than provisioned capacity. This shift concentrates in the United States and United Kingdom, where CFOs prioritize operational expenditure flexibility over capital-intensive server ownership.
Global Domain and Hosting Market Segmentation
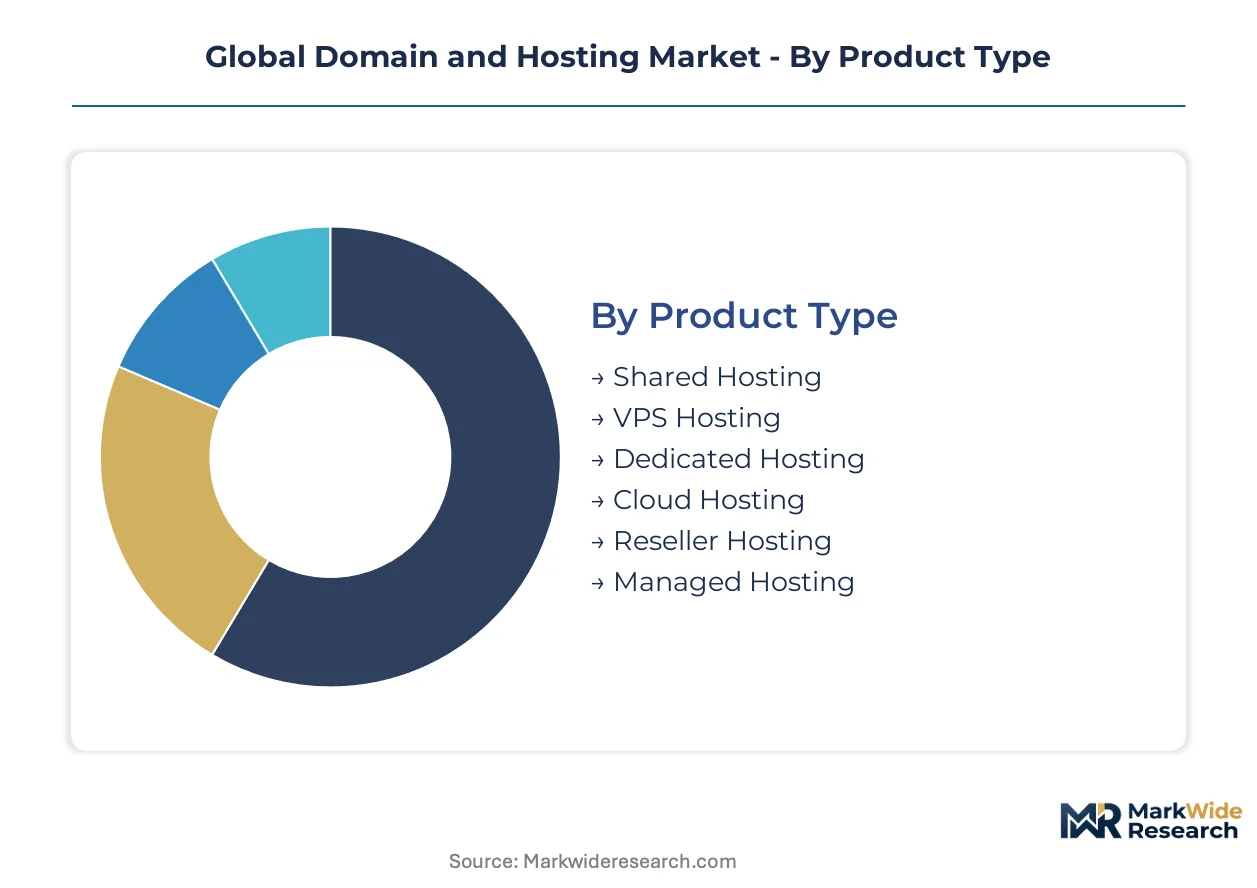
Segmentation in the domain and hosting market reveals how procurement logic splits between price-sensitive independents seeking bundled entry-level packages and enterprises demanding sovereign infrastructure with compliance guarantees. Understanding these divides illuminates where providers must rebuild margin structures versus where volume aggregation still works.
Product Type:
Cost tier determines whether buyers prioritize absolute price floors or operational flexibility at higher spend levels.
- Cloud Hosting:Elastic compute pools scale resources on demand through distributed server networks. Demand concentrates among SaaS developers in the United States and Germany where Kubernetes-native deployment patterns require pay-as-you-grow infrastructure rather than fixed-capacity provisioning.
- Managed Hosting:Providers bundle security patching, performance optimization, and compliance monitoring into recurring contracts. European financial services firms in Frankfurt and London drive procurement here as GDPR mandates force outsourced expertise over in-house infrastructure teams.
- Shared Hosting:Multi-tenant servers partition resources across hundreds of low-traffic websites at minimal cost entry points.
- VPS Hosting:Virtual private servers isolate allocated resources on shared physical hardware for mid-tier performance requirements.
- Dedicated Hosting:Single-tenant physical servers deliver maximum control for latency-sensitive workloads.
- Reseller Hosting:White-label infrastructure enables web agencies and consultants to bundle hosting into client service packages.
Volume sits with Shared Hosting; growth tilts toward Cloud Hosting.
Deployment Model:
Application criticality and data sensitivity govern whether organizations accept multi-tenancy or demand isolated infrastructure stacks.
- Hybrid Cloud:Workloads split between on-premise systems and public cloud resources through orchestrated management layers. German automotive manufacturers and Japanese industrial conglomerates favor this model to keep proprietary design data local while bursting compute to cloud during peak simulation cycles.
- Private Cloud:Single-organization infrastructure delivers virtualization benefits without shared hardware exposure. China's state-owned enterprises and Saudi government entities mandate this architecture under cybersecurity laws restricting foreign data center access.
- Public Cloud:Shared infrastructure pools serve variable workloads through standardized service tiers.
- On-Premises:Self-managed hardware in owned or leased facilities persists where regulatory latency requirements or legacy system constraints block cloud migration.
Public Cloud captures current spend concentration; Hybrid Cloud is gaining share fastest among regulated industries.
Customer Type:
Customer maturity and technical staffing levels determine whether buyers need full-service management or raw infrastructure access.
- Small Businesses:Owner-operators with minimal technical expertise require one-click deployment tools bundled with domain registration and email. India's Micro, Small and Medium Enterprises sector generates sustained demand here through government digitalization incentives and low-code website builders.
- Enterprises:Procurement teams negotiate multi-year contracts with stringent SLA requirements and dedicated account management. Multinational corporations across the United States, United Kingdom, and Germany consolidate spending here to achieve volume discounts and compliance certification.
- Startups:Venture-backed companies prioritize speed-to-market over cost optimization in early growth phases.
- Freelancers:Individual contractors and consultants need portable, cancellable hosting for client project work.
- Nonprofit Organizations:Budget-constrained mission-driven entities seek discounted or donated infrastructure tiers.
Enterprises dominate contract value; Small Businesses drive transaction volume expansion.
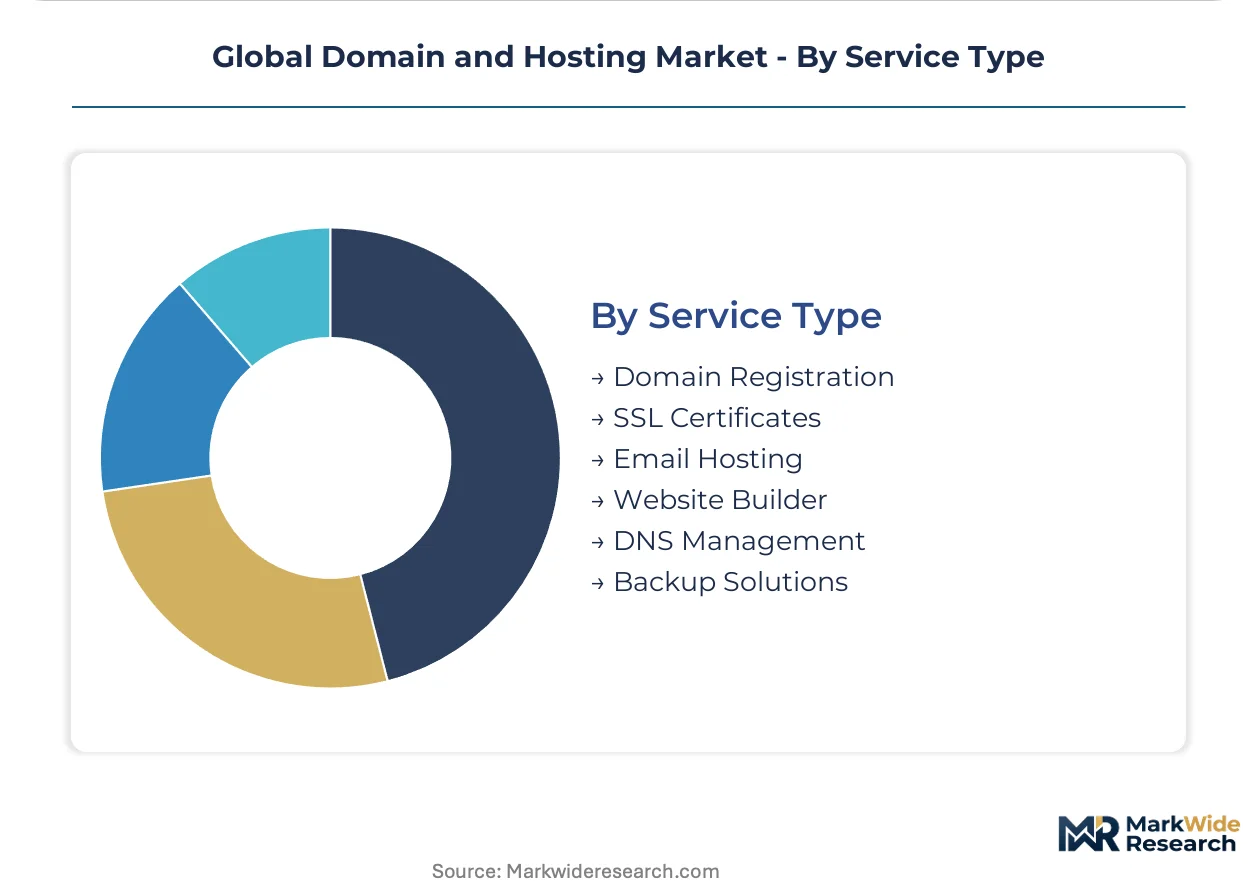
Service Type:
Margin pools concentrate where technical complexity forces buyers to outsource specialized functions rather than self-manage.
- SSL Certificates:Encryption credential provisioning and renewal automation secure data transmission between servers and browsers. E-commerce merchants across Brazil and Southeast Asia drive procurement here as browser warnings on non-HTTPS sites directly suppress conversion rates.
- Backup Solutions:Automated data replication and disaster recovery orchestration protect against ransomware and operational failures. Healthcare providers in the United States facing HIPAA requirements and financial institutions under ECB supervision mandate these services for audit compliance.
- Domain Registration:DNS namespace leasing with WHOIS management and transfer protection.
- Email Hosting:Business-grade messaging infrastructure with spam filtering and archival compliance.
- Website Builder:Drag-and-drop design tools with pre-configured templates and mobile responsiveness.
- DNS Management:Traffic routing optimization and DDoS protection through anycast networks.
Domain Registration anchors baseline revenue; Backup Solutions show the steepest expansion trajectory as ransomware frequency escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's hyperscale data center clusters anchor North American infrastructure investment, while submarine cable landing points in Portugal and Singapore direct intercontinental traffic flows toward emerging digital economies.
United States
Enterprise SaaS developers and financial services firms in New York and San Francisco drive cloud hosting procurement at scale. The FTC enforces deceptive pricing disclosure rules for subscription renewals and domain transfers. Northern Virginia's Data Center Alley hosts the world's densest concentration of server capacity, with operators expanding into Phoenix and Columbus for power cost arbitrage.
Germany
Automotive manufacturers and industrial conglomerates in Stuttgart and Munich require sovereign infrastructure for proprietary design data protection. The GDPR mandates strict data residency controls that prevent cross-border processing without adequacy decisions. Frankfurt's DE-CIX exchange anchors continental internet traffic, while operators build certified facilities in Berlin and Hamburg for federal compliance workloads.
India
Micro, Small and Medium Enterprises across Maharashtra and Karnataka generate sustained demand for bundled domain and website builder packages. The Ministry of Electronics and Information Technology promotes data center parks through infrastructure status and PLI scheme incentives. Mumbai and Chennai host submarine cable landings that reduce latency for domestic cloud users, with Hyderabad emerging as a secondary cluster for government cloud contracts.
China
State-owned enterprises and platform companies in Beijing and Shenzhen mandate private cloud architectures under cybersecurity law restrictions. The Ministry of Industry and Information Technology enforces ICP licensing that blocks foreign hosting operators without local partnership structures. Shanghai's Yangshan and Zhangjiang zones concentrate domestic hyperscale builds, while operators in Guiyang leverage cool climate for energy efficiency certification.
Brazil
E-commerce merchants and fintech startups in São Paulo and Rio de Janeiro drive SSL certificate and backup solution procurement for conversion optimization and compliance. ANVISA and the central bank impose data localization expectations for healthcare and financial records. The São Paulo metro anchors Latin America's largest data center market, with Campinas and Curitiba attracting secondary investments for disaster recovery redundancy.
Global Domain and Hosting Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue edge compute specialization and sovereign cloud certification to differentiate beyond commodity infrastructure. The market structures around three concentration poles: hyperscale clouds with global data center footprints, regional specialists with compliance depth in single jurisdictions, and automated low-cost platforms targeting price-sensitive independents. Strategic archetypes include infrastructure aggregators bundling adjacent services, compliance-forward operators capturing regulated verticals, and developer-experience platforms optimizing deployment velocity. Competitive moves concentrate on data center capacity expansion in certified green facilities and strategic partnerships with telecommunications carriers for edge node placement.
Within the hyperscale tier, Amazon Web Services, Inc. and Google LLC exemplify infrastructure aggregators with global reach and deep ecosystem integration. Hostinger International, Ltd. occupies a position among automated onboarding specialists capturing independent operators through price-optimized tooling. These three entities represent the dominant competitive archetypes shaping procurement patterns across enterprise and small business segments respectively.
| Leading Market Players |
|---|
| GoDaddy Inc. |
| Amazon Web Services, Inc. |
| Newfold Digital, Inc. |
| Google LLC |
| Alibaba Cloud Computing Co., Ltd. |
| Hostinger International, Ltd. |
| IONOS, Inc. |
| Microsoft Azure |
| DigitalOcean, LLC |
| Others |
Supply & Pricing Matrix
Enterprise procurement consolidation around hyperscale cloud contracts forces smaller hosting providers to unbundle managed services from raw infrastructure, compressing margins on commodity tiers while creating pricing power for compliance-certified sovereign offerings. This demand-side pressure reshapes supply chain investment toward certified data center builds in regulated jurisdictions.
Pricing Analysis
Warranty and service-bundling differentiation separates premium managed hosting from bare-metal infrastructure tiers. Three-tier pricing structure across premium, standard, and economy levels anchors on SLA guarantees, with European financial services firms paying premiums for GDPR-compliant security patching while Indian SMEs gravitate toward unbundled entry-level shared hosting. Price differentiation rests on ISO 27001 certification status and dedicated account management availability. Cost compression in shared hosting intensifies as automated onboarding tools reduce customer acquisition expenses. Freelancers and micro-businesses exhibit highest price sensitivity; multinational enterprises negotiating multi-year contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from German automotive manufacturers and Japanese industrial conglomerates mandate qualified secondary suppliers for critical data center hardware. Server manufacturing concentrates in Taiwan, China, and South Korea. Raw material dependencies include high-purity silicon for chip fabrication, lithium-ion battery systems for backup power, and specialized cooling fluids. Supply chain risk centers on single-source vulnerability for advanced GPU accelerators used in AI inference workloads. Distribution runs through direct hyperscaler procurement channels and regional systems integrators serving mid-market segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as energy cost volatility and carbon disclosure mandates force sub-scale operators toward acquisition or exit. Margin compression in commodity hosting tiers accelerates competitive attrition.
For Market Incumbents: Anchor defensive positioning through backward integration into renewable energy supply for data center power, securing cost predictability against electricity price volatility. Prioritize ISO 14001 certification investment to capture EU Green Deal procurement preferences. Expand certified facilities in Frankfurt and Singapore to defend against regional specialists capturing sovereign cloud mandates.
For New Entrants and Emerging Players: GDPR in Europe opens a window for compliance-forward operators to capture mid-market financial services firms seeking alternatives to hyperscale dependency. Target Indonesia's underpenetrated SME base where sub-40% business website penetration creates whitespace for localized hosting bundles. Pursue telecommunications carrier partnerships for edge node placement as the primary go-to-market angle.
For Investors and Strategic Acquirers: The window for entry favors regional specialists with deep compliance expertise in single jurisdictions. Long-term viability hinges on data center assets in carbon-certified facilities with established renewable power purchase agreements. Monitor ICP licensing enforcement intensity in China as the inflection signal for multinational hosting architecture viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Data Center Certification | EU Green Deal carbon disclosure requirements reward operators achieving ISO 14001 environmental management standards. |
| Edge Node Expansion | 5G network slicing convergence with GPU-accelerated servers enables low-latency machine learning hosting at metropolitan facilities. |
| Sovereign Cloud Partnership | Local partnership structures satisfy China's MIIT ICP licensing requirements blocking foreign operators from domestic websites. |
| Managed Security Bundling | Ransomware frequency escalation drives steepest expansion trajectory in automated backup and disaster recovery orchestration. |
| Low-Code Platform Integration | India's MSME digitalization incentives sustain demand for website builders bundled with domain registration and email. |
Research Methodology
Multi-period observation of hyperscaler capital expenditure disclosures and data center permitting activity anchored the trend analysis, supplemented by interviews with infrastructure procurement officers at financial services firms, platform engineering leads at SaaS developers, and regulatory compliance directors at hosting operators. Secondary validation drew from SEC filings of publicly traded data center REITs, TRAI spectrum allocation records, and EU energy efficiency certification databases. Bottom-up triangulation across customer segment spend patterns converged with top-down macroeconomic indicators.
Segment-weighting applied deployment model splits across public, private, and hybrid cloud architectures, with customer type stratification between enterprise procurement teams and small business owner-operators. Product type differentiation across cloud, managed, and shared hosting tiers informed volume allocation. CAGRs derived from elasticity-adjusted demand curves incorporating SME digital onboarding rates and sovereign data residency mandate expansion. Forecast inputs included renewable energy cost trajectories and IPv6 migration timelines.
The model assumes a particular technology adoption path; alternative pathways for serverless computing architectures would alter the outlook toward container orchestration platform concentration. Forecasts reflect documented assumptions on data localization policy enforcement intensity and carbon disclosure rule implementation pace. Deviation in China's cybersecurity law enforcement or EU Green Deal certification timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Canada Digital Twin Market
Digital Solutions
Engineering Information Management Solutions Market
Digital Solutions
Defense IT Spending Market
Digital Solutions
Cloud Monetization Market
Digital Solutions
Global Genealogy Products and Services Market
Digital Solutions
Global Work Order Management Systems Market
Digital Solutions
Barcode Software Market
Digital Solutions
Water Level and Storage Monitoring Software Market
Digital Solutions
Email Marketing Market
Digital Solutions
Enterprise Application Integration (EAI) Market
Digital Solutions
Account Based Marketing Market
Digital Solutions
Software Defined Application and Infrastructure Market
Digital Solutions
Clientless Remote Support Software Market
Digital Solutions
Revops Platform Market
Digital Solutions
Public Relations (PR) Tools Market
Digital Solutions
North America Digital Pen Market