
 Data Center Blocks Market | 2026-2036
Data Center Blocks Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Blocks Market Analysis
Capital-intensity divergence between hyperscale-optimized and enterprise-grade modular infrastructure is redrawing competitive boundaries in the Data Center Blocks Market. Schneider Electric leverages integrated power and cooling architectures to anchor large-scale deployments across multiple continents. Vertiv competes through thermal management specialization, while Eaton sustains its position via critical power distribution expertise.
Data center blocks are prefabricated, factory-integrated modules containing power, cooling, and IT infrastructure that deploy as standardized units with specifications typically ranging from 250 kW to 2 MW per module, designed to accelerate facility commissioning and reduce on-site construction complexity. Modular Units and Cooling Systems command the dominant share of product-type revenue pools, with liquid cooling technology segments expanding fastest as AI training workloads intensify heat density requirements. Deployment patterns show Hybrid and Edge Computing configurations capturing incremental growth as latency-sensitive applications proliferate beyond centralized hyperscale campuses.
Regulatory frameworks including the EU Green Deal efficiency mandates, EPA ENERGY STAR certification requirements in the United States, and BIS electrical safety standards in India are tightening product compliance thresholds and reshaping procurement specifications across major demand centers. Stakeholders must monitor evolving carbon disclosure rules and locality-specific grid interconnection standards to preserve market access and avoid retrofit liabilities.
Market Dynamics
AI training clusters are forcing thermal density thresholds past 50 kW per rack, compelling modular infrastructure providers to redesign cooling architectures before liquid-cooled legacy retrofits become economically prohibitive.
Growth Catalysts
- EU Green Deal PUE mandates:The EU Green Deal's tightening energy efficiency thresholds are accelerating replacement cycles for legacy data center infrastructure across Germany, France, and the Netherlands.
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are deploying prefabricated modules at 3x the pace of enterprise colocation builds to compress commissioning timelines.
- Edge computing latency requirements:Autonomous vehicle networks and industrial IoT deployments in Dallas-Fort Worth and Northern Virginia are pulling modular capacity toward distributed metro nodes.
Market Restraints
- Copper and aluminum input volatility:Busbar and electrical distribution component costs swing 15-30% quarterly, compressing module margins before contracts reprice.
- Taiwan semiconductor concentration:Power conversion and control chip supply bottlenecks from TSMC and MediaTek create 6-9 month lead time vulnerability for intelligent PDU integration.
- Local grid interconnection standards:FERC Order 2023 interconnection queue reforms in the United States and divergent utility requirements across Indian states fragment deployment playbooks.
Strategic Opportunities
- Saudi Arabia NEOM and Qiddiya developments:Sovereign wealth-backed giga-projects are specifying factory-integrated data center blocks for rapid digital infrastructure scaling with 100% renewable energy targets.
- Direct liquid cooling convergence with AI workloads:Immersion cooling and cold plate architectures are merging with GPU cluster designs, opening premium module tiers for training infrastructure.
- India PLI scheme for electronics manufacturing:Production-linked incentives for semiconductor and component assembly are enabling localized module production to serve domestic cloud demand and ASEAN export markets.
Industry Challenges
- Commissioning engineer scarcity:Factory acceptance testing and on-site integration of multi-vendor power and cooling subsystems require cross-trained technicians that Siemens, Schneider Electric, and Vertiv compete to retain.
- UL 2743 and IEC 61508 certification timelines:Safety integrity level verification for power distribution modules adds 4-6 months to product release cycles, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Blocks Market |
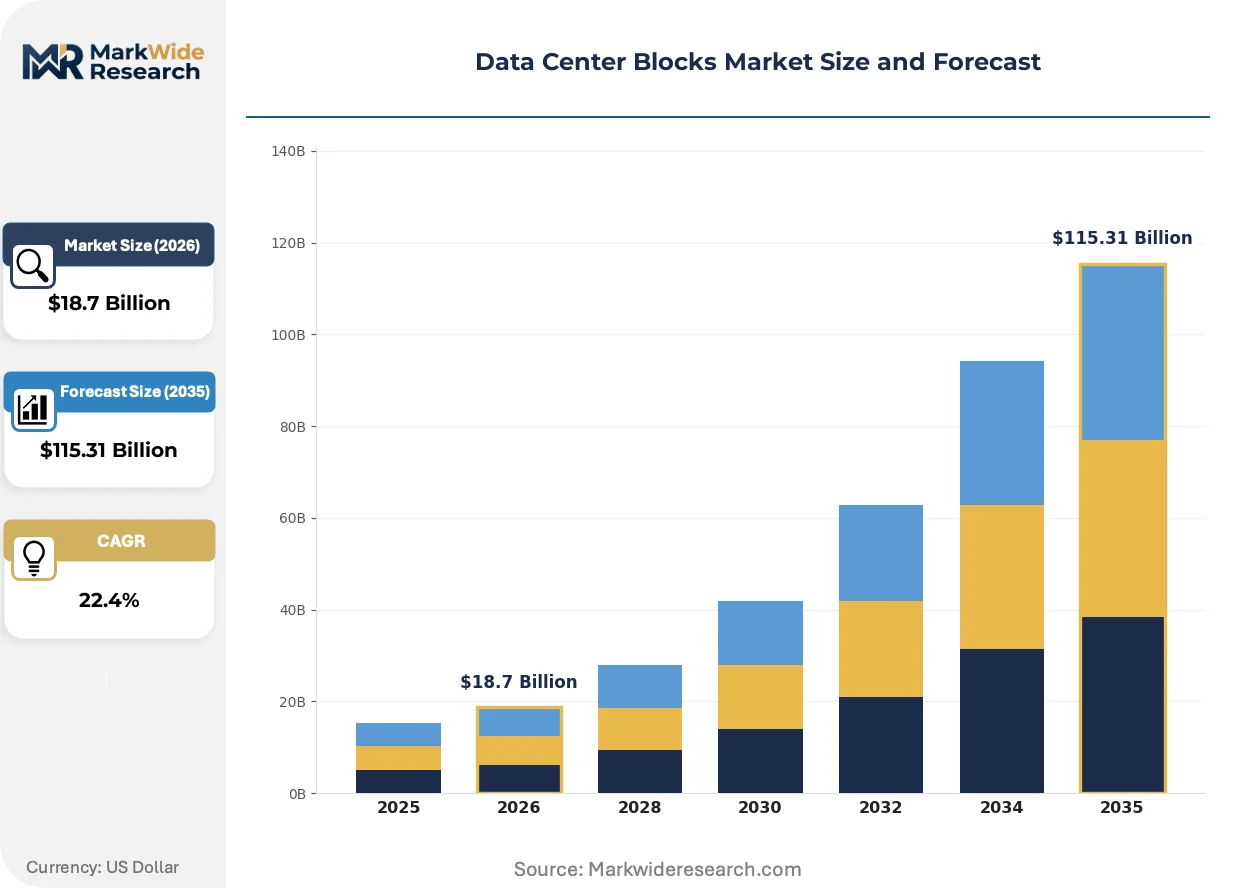
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $115.31 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Units, Racks, Cooling Systems, Power Distribution Units Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Enterprises, Colocation Providers, Telecommunication Companies, Government Agencies Technology: Liquid Cooling, Air Cooling, Virtualization, Automation |
| Companies Covered | Schneider Electric, Hewlett Packard Enterprise, Rittal, Eaton, Vertiv, Legrand, Dell Technologies, Chatsworth Products, Panduit, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Blocks Market Emerging Trajectories
Liquid cooling architectures are rewriting thermal design specifications while regulatory pressure on embodied carbon and operational efficiency compresses technology refresh cycles across deployment categories.
Direct-to-chip liquid cooling is supplanting traditional CRAH and CRAC air-handling units in AI training clusters above 30 kW per rack. Hyperscale operators in Northern Virginia and Dallas-Fort Worth are specifying immersion and cold plate systems for 80% of new module orders. This transition is supplanting legacy chilled water infrastructure and reducing facility water consumption by 40-60% in high-density deployments.
The EU F-Gas Regulation phasedown is banning refrigerants with global warming potential above 150 for new data center cooling systems from 2027. Module manufacturers are accelerating CO2 and ammonia-based chiller development to preserve European market access. German and French procurement specifications now require GWP disclosure for all cooling subsystem components, shifting competitive advantage toward suppliers with refrigerant-free architectures.
Cloud operators are consolidating vendor relationships from 12-15 module suppliers per region to 3-4 strategic partners with full-stack power, cooling, and software integration capabilities. This concentration is eliminating pure-play mechanical or electrical component vendors from hyperscale qualification lists. The United States and Western Europe show the most aggressive supplier base compression, with Middle Eastern markets following 18-24 months behind.
Data Center Blocks Market Segmentation
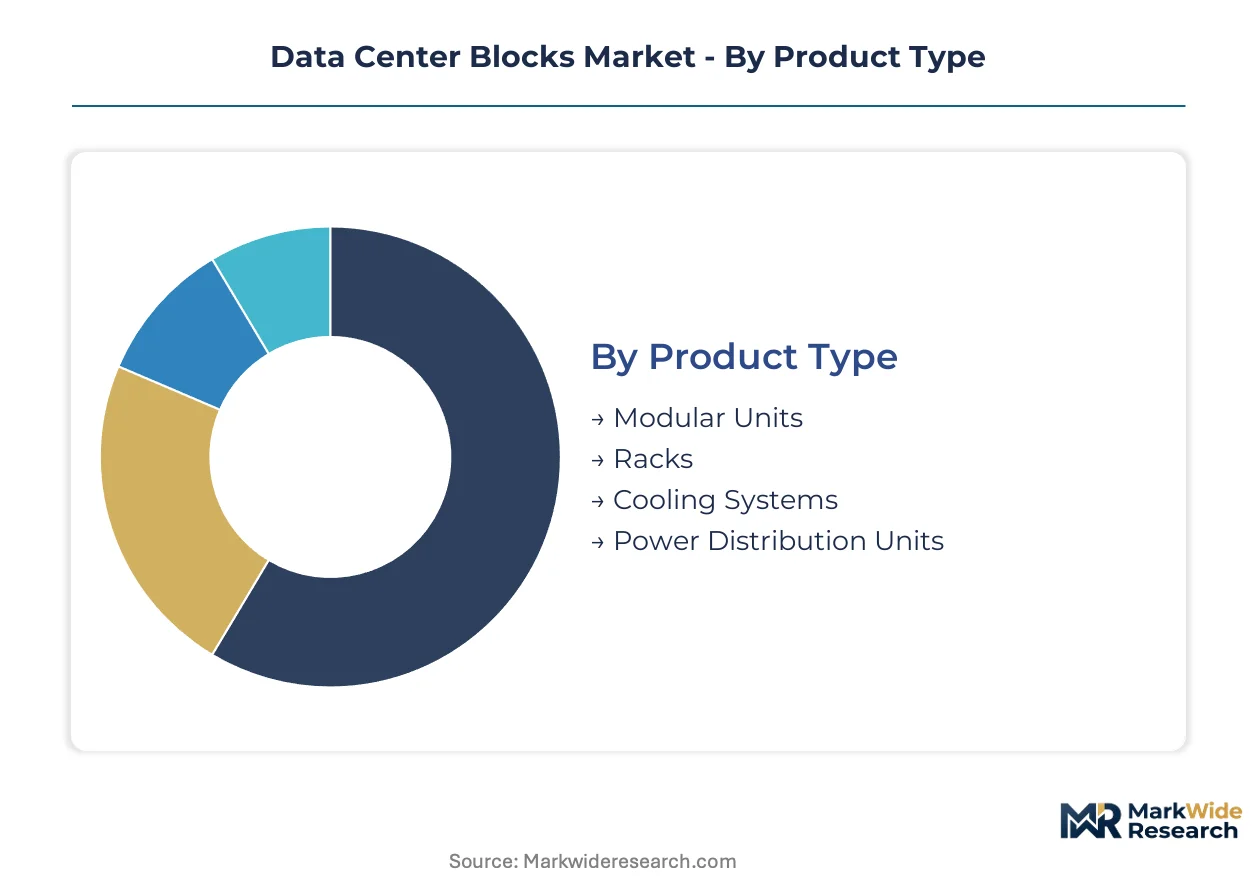
Segmentation in the Data Center Blocks Market reveals how modular infrastructure providers allocate engineering resources and pricing power across distinct technical and customer dimensions. Understanding these splits exposes where procurement consolidation is concentrating and which technology transitions are compressing legacy margins.
Product Type:
Margin pools concentrate in integrated cooling and power subsystems where thermal density requirements are forcing architectural redesigns.
- Modular Units:Factory-integrated enclosures housing power, cooling, and IT infrastructure in standardized 250 kW to 2 MW configurations. Demand concentrates in Northern Virginia and Dallas-Fort Worth hyperscale campuses where AWS, Microsoft Azure, and Google Cloud are compressing commissioning timelines to under 12 weeks.
- Cooling Systems:Liquid cooling architectures including immersion and cold plate systems are supplanting traditional CRAH/CRAC units as AI training clusters exceed 30 kW per rack. German and French procurement specifications under EU F-Gas Regulation now require GWP disclosure, shifting competitive advantage toward refrigerant-free CO2 and ammonia-based designs.
- Racks:Structural enclosures with integrated cable management and thermal containment for high-density server deployments.
- Power Distribution Units:Intelligent PDUs with remote monitoring capabilities, though Taiwan semiconductor concentration from TSMC creates 6-9 month lead time vulnerability for control chip integration.
The dominant share belongs to Modular Units, while Cooling Systems is closing the gap fastest as thermal density thresholds force liquid-cooled retrofits.
Deployment:
Customer archetypes split between centralized hyperscale builds and distributed latency-sensitive infrastructure.
- Hybrid:Blended on-premises and cloud-resident workloads requiring seamless workload portability. Enterprises in financial services and healthcare are specifying hybrid-configured blocks to maintain data sovereignty while bursting to cloud.
- Edge Computing:Metro-distributed modular capacity deployed within 10 milliseconds of end users. Autonomous vehicle networks and industrial IoT deployments in Dallas-Fort Worth are pulling capacity toward distributed nodes as latency requirements tighten below 20 milliseconds.
- On-Premises:Enterprise-owned facilities with captive infrastructure management.
- Cloud-Based:Fully cloud-resident deployments without physical customer infrastructure.
Hybrid configurations capture the largest procurement volumes currently, though Edge Computing is expanding most quickly as latency-sensitive applications proliferate beyond centralized campuses.
End User:
Purchasing power concentrates with entities operating at facility scale above 5 MW where modular standardization delivers measurable TCO compression.
- Colocation Providers:Multi-tenant facility operators leasing space to enterprise customers. Equinix and Digital Realty are deploying prefabricated modules at 3x the pace of enterprise builds to accelerate revenue recognition.
- Enterprises:Single-occupant operators in financial services, healthcare, and manufacturing verticals.
- Telecommunication Companies:Network operators integrating edge compute with 5G infrastructure.
- Government Agencies:Federal and state entities with classified workload requirements.
Colocation Providers command the dominant procurement volumes, while Government Agencies are gaining share fastest as sovereign cloud mandates accelerate classified infrastructure spending.
Technology:
Technology selection tracks directly to rack power density, with thresholds above 50 kW forcing liquid-cooled architectures.
- Liquid Cooling:Direct-to-chip and immersion systems reducing facility water consumption by 40-60% in high-density deployments. Hyperscale operators in Northern Virginia are specifying liquid-cooled blocks for 80% of new AI training cluster orders.
- Air Cooling:Traditional CRAH and CRAC units retaining relevance in legacy enterprise facilities below 15 kW per rack.
- Virtualization:Software-defined infrastructure abstraction layers enabling workload portability.
- Automation:AI-driven thermal and power optimization with predictive maintenance capabilities.
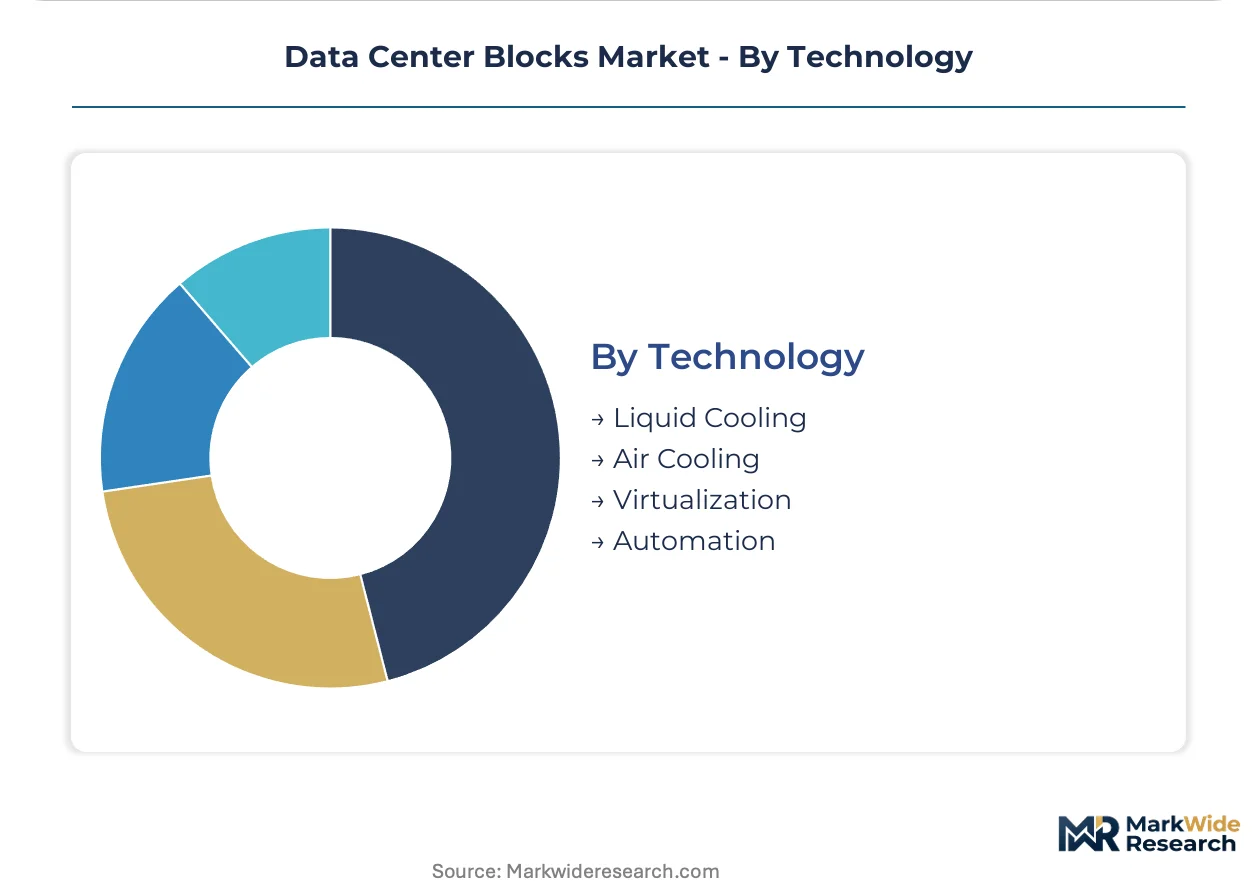
Air Cooling retains installed base dominance, while Liquid Cooling is climbing the fastest as GPU cluster designs merge with immersion and cold plate module specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as hyperscale cloud operators prioritize deployment velocity over unit cost, while procurement in India and Southeast Asia remains acutely sensitive to capital expenditure compression. This divergence reshapes how modular infrastructure providers allocate manufacturing capacity and service resources across demand centers.
United States
Northern Virginia and Dallas-Fort Worth hyperscale clusters are absorbing prefabricated modules at triple the rate of enterprise colocation builds as AWS, Microsoft Azure, and Google Cloud compress commissioning timelines. FERC Order 2023 interconnection queue reforms are reshaping utility procurement specifications. Northern Virginia's Loudoun County specifically hosts the densest concentration of modular data center deployments worldwide.
Germany
Industrial cloud demand from automotive and precision manufacturing verticals is pulling modular capacity toward Frankfurt and Munich metro nodes. EU F-Gas Regulation phasedown mandates are eliminating refrigerants with global warming potential above 150 from 2027, forcing CO2 and ammonia-based chiller adoption. The Rhine-Main cluster around Frankfurt anchors continental Europe's largest data center block procurement volumes.
India
Domestic cloud operators and telecom providers are deploying edge-configured modules within 10 milliseconds of Tier-2 city populations as latency requirements tighten. BIS electrical safety standards and state-level utility interconnection requirements are fragmenting deployment playbooks across Maharashtra, Karnataka, and Telangana. Mumbai's Navi Mumbai sub-region specifically concentrates colocation provider modular builds serving financial services demand.
Saudi Arabia
NEOM and Qiddiya sovereign wealth-backed giga-projects are specifying factory-integrated data center blocks with 100% renewable energy targets for rapid digital infrastructure scaling. The country's national investment fund mandates are accelerating localized module assembly partnerships. The Tabuk Province NEOM development zone specifically requires liquid-cooled modular architectures for AI training cluster deployments.
France
Paris and Marseille metro zones are capturing hybrid cloud workload demand from healthcare and government agencies requiring data sovereignty compliance. EU Green Deal PUE mandates are accelerating replacement cycles for legacy chilled water infrastructure. The Greater Paris Île-de-France region specifically concentrates enterprise procurement of refrigerant-free cooling module configurations.
Data Center Blocks Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the Data Center Blocks Market, with integrated full-stack providers commanding premium positioning while component specialists compete on manufacturing scale. The vendor base separates into three strategic tiers: multinational electrical infrastructure conglomerates with captive module divisions, pure-play thermal and power management specialists, and regional fabrication houses serving price-sensitive procurement. Competitive dynamics center on supplier base compression from 12-15 vendors per region to 3-4 strategic partners, alongside accelerated certification investments for liquid-cooled architectures.
Among the integrated infrastructure tier, Schneider Electric, Vertiv, and Eaton occupy anchor positions representing distinct competitive archetypes. Schneider Electric exemplifies the full-stack power-cooling-software integration model that hyperscale operators increasingly mandate. Vertiv sits within the thermal management specialization vector where liquid-cooled retrofit demand is concentrating procurement influence. Eaton represents the critical power distribution expertise archetype that underpins module reliability specifications. These three entities collectively illustrate how vendor consolidation is eliminating pure-play mechanical or electrical component vendors from qualification lists.
| Leading Market Players |
|---|
| Schneider Electric |
| Hewlett Packard Enterprise |
| Rittal |
| Eaton |
| Vertiv |
| Legrand |
| Dell Technologies |
| Chatsworth Products |
| Panduit |
| Others |
Supply Flow & Price Mechanics
Long-term capacity reservation contracts with hyperscale operators lock in copper and aluminum busbar supply while freezing module pricing across 18-24 month commissioning windows, insulating Schneider Electric and Vertiv from quarterly commodity swings that erode spot-market competitors.
Pricing Analysis
After-sales service contracts for liquid cooling maintenance and intelligent PDU firmware updates now drive lifetime value exceeding initial module hardware sales. Three-tier pricing structure across premium liquid-cooled, standard air-cooled, and economy refurbished configurations stratifies procurement tiers, with hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth showing lowest price elasticity. Cost compression in standard air-cooled tiers intensifies because Taiwanese semiconductor bottlenecks extend intelligent PDU lead times. Enterprise colocation providers in India demonstrate highest price sensitivity, squeezing margin on legacy CRAH-based configurations.
Supply Chain Analysis
Taiwan and South Korea anchor power conversion semiconductor fabrication, while China and Mexico concentrate sheet metal enclosure and cable assembly production. Copper and aluminum busbar sourcing draws from Chilean mining operations and Chinese smelters, with electrical distribution components resting on TSMC and MediaTek control chip supply. Single-source vulnerability from Taiwan semiconductor concentration creates deployment bottlenecks for intelligent PDU integration. Distribution runs through direct OEM relationships with hyperscale operators and regional system integrators serving enterprise colocation builds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineer scarcity for factory acceptance testing and multi-vendor subsystem integration constrains deployment velocity, creating a capability bottleneck that favors incumbents with captive training pipelines over aspirant competitors.
For Market Incumbents: Shield liquid-cooled architecture margins by accelerating UL 2743 and IEC 61508 certification investments before EU F-Gas Regulation phasedown eliminates refrigerant-dependent competitors. Consolidate supplier relationships from 12-15 vendors per region to 3-4 strategic partners with full-stack integration capabilities, eliminating pure-play component vendors from hyperscale qualification lists. Backward integration into Taiwanese semiconductor sourcing mitigates MediaTek and TSMC lead time vulnerability. For New Entrants and Emerging Players: Edge computing service-layer gaps in Tier-2 Indian cities and Saudi Arabian NEOM development zones offer white-space penetration where hyperscale incumbents under-serve latency requirements below 20 milliseconds. Target modular unit refurbishment and secondary life-cycle markets in Germany and France where EU Green Deal PUE mandates accelerate replacement cycles. Pursue channel partnerships with regional system integrators possessing BIS electrical safety certification expertise rather than direct hyperscale qualification. For Investors and Strategic Acquirers: Thermal management specialists with captive liquid cooling IP and established hyperscale qualification relationships represent priority acquisition targets as AI training cluster demand concentrates procurement influence. Long-term viability hinges on refrigerant-free architecture development and direct-to-chip cooling convergence with GPU cluster designs. Watch for FERC Order 2023 interconnection queue reform implementation velocity as inflection indicator for US deployment pace.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Architecture Certification | UL 2743 and IEC 61508 verification preserves EU market access under F-Gas Regulation mandates. |
| Backward Integration into Semiconductor Sourcing | Captive TSMC and MediaTek relationships mitigate 6-9 month intelligent PDU lead time vulnerability. |
| Regional System Integrator Partnership | BIS-certified channel partners unlock fragmented Indian state-level utility interconnection requirements. |
| Refrigerant-Free Chiller Development | CO2 and ammonia-based designs secure German and French procurement specifications post-2027. |
| Edge Computing Module Localization | Tier-2 Indian city deployment within 10 milliseconds of populations captures latency-sensitive demand. |
Methodological Framework
A spread of perspectives from hyperscale facility planners, colocation procurement directors, thermal management engineers, and electrical distribution specialists converged on the working assumptions driving module demand forecasts. Primary interviews with commissioning technicians and factory acceptance testing supervisors combined with secondary validation against FERC interconnection filings, EPA ENERGY STAR certification databases, EU F-Gas Regulation implementation guidance, and hyperscaler capex disclosures. Bottom-up unit deployment modeling and top-down infrastructure investment triangulation anchored volume projections.
Segmentation dimensions modeled span product type, deployment configuration, end-user archetype, and cooling technology density tier across the analysis window. CAGRs derived from installation velocity patterns in Northern Virginia and Dallas-Fort Worth hyperscale clusters, liquid cooling retrofit penetration rates in German automotive cloud deployments, and edge computing latency requirement tightening in Indian telecom networks. Forecast inputs incorporate EU Green Deal PUE mandate compliance timelines and Saudi Arabian sovereign wealth giga-project specification trajectories.
Forecasts assume regulatory continuity in EPA ENERGY STAR certification requirements, EU F-Gas Regulation phasedown schedules, and BIS electrical safety standards; material policy shifts would require re-modeling deployment velocity assumptions. Semiconductor supply concentration risk and copper price volatility represent primary forecast revision triggers. Recalibration cycles align with material shifts in hyperscale commissioning timelines and liquid cooling technology certification milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Water Leak Detection System for Server Rooms and Data Centers Market
Data Center Infrastructure
Brazil Data Center Market
Data Center Infrastructure
US Multi-Tenant (Colocation) Data Center Market
Data Center Infrastructure
Austria Data Center Power Market
Data Center Infrastructure
Global Terminal Management System Market
Data Center Infrastructure
Converged Infrastructure Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Global Data Center Rack Server Market
Data Center Infrastructure
Europe Green Data Center Market
Data Center Infrastructure
Singapore Data Center Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Internet Data Center Market
Data Center Infrastructure
Composable-Disaggregated Infrastructure Market
Data Center Infrastructure
New Zealand Data Center Market