
 Europe in-Memory Database Market | 2026-2036
Europe in-Memory Database Market Size, Share, and Industry Trends Forecast 2026-2036
Europe in-Memory Database Market Insights
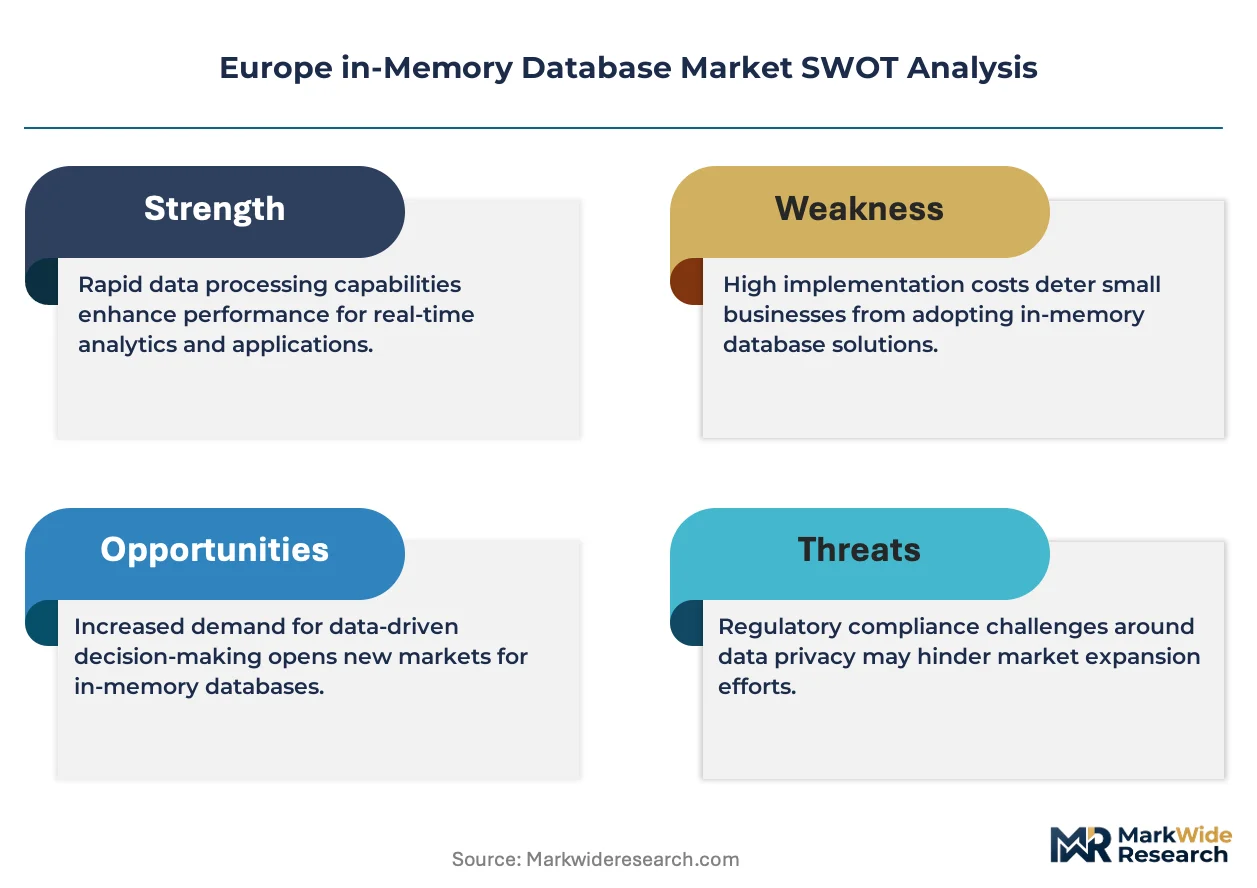
European cloud infrastructure buildouts are hardening the supply base for low-latency data platforms. SAP SE leverages its HANA footprint to anchor enterprise deployments across German manufacturing and public sector accounts. Oracle Corporation competes through database consolidation plays that extend its on-premises install base into managed cloud services. Redis Ltd. specializes in open-source caching layers that dominate real-time application stacks among fintech developers in London and Amsterdam.
An in-memory database stores data directly in RAM rather than disk-based storage, enabling microsecond-range query response times for transactional and analytical workloads. These systems employ compressed columnar formats and parallel processing architectures to handle high-velocity data streams from IoT sensors, trading platforms, and customer-facing applications. NoSQL deployments are capturing the fastest expansion as graph and key-value stores address unstructured data workloads in telecommunications fraud detection. Relational in-memory systems retain the largest margin pools within financial services compliance reporting, where ACID guarantees command premium pricing. Cloud-based delivery is displacing on-premises installations among mid-market retailers seeking elastic capacity without datacenter capital expenditure.
The EU AI Act, GDPR, and CSRD collectively mandate explainable processing trails and data residency controls that shape procurement specifications for European buyers. EMA pharmacovigilance requirements and ECB stress-testing protocols further institutionalize real-time data validation as a regulatory necessity. Stakeholders must evaluate whether sovereign cloud certifications or edge-localized deployments offer more durable compliance positioning as member-state implementations diverge.
Market Dynamics
EU AI Act and GDPR compliance mandates are forcing financial institutions to abandon cross-border data flows in favor of sovereign cloud architectures. This regulatory compression is reshaping procurement specifications across German banking clusters and French insurance headquarters.
Growth Catalysts
- EU AI Act explainability requirements:Financial services firms in Frankfurt and Paris must maintain auditable processing trails. In-memory architectures deliver millisecond-range query logging that satisfies algorithmic accountability mandates.
- Real-time fraud detection:Telecommunications operators deploy graph-based in-memory stores to trace transaction patterns across subscriber networks. Velocity demands exceed disk-based system capabilities.
- Compressed columnar formats:Manufacturing IoT sensor streams in Bavaria require parallel ingestion architectures. RAM-resident column stores enable sub-second anomaly detection on high-velocity production lines.
Market Restraints
- DDR5 memory cost volatility:Server-grade RAM pricing fluctuates with semiconductor fab capacity allocation. European buyers face input cost uncertainty that complicates multi-year infrastructure planning.
- Skill scarcity in distributed systems engineering:Talent pools for in-memory cluster administration concentrate in London and Amsterdam. Continental firms compete for limited implementation expertise.
- Legacy mainframe integration friction:Established core banking systems in Munich and Milan resist real-time data pipeline connectivity. Rip-and-replace timelines extend deployment cycles.
Strategic Opportunities
- Edge-localized pharmacovigilance:EMA requirements for real-time adverse event reporting create demand for hospital-proximate processing nodes. Pharmaceutical manufacturers in Basel and Lyon seek compliant edge deployments.
- Hybrid transactional/analytical convergence:HTAP architectures merge operational and analytical workloads. Retail banking segments in Madrid and Barcelona eliminate separate data warehouse infrastructure.
- CSRD sustainability data validation:Corporate sustainability reporting mandates require real-time emissions calculation. Industrial conglomerates in the Ruhr Valley invest in in-memory carbon accounting platforms.
Industry Challenges
- ACID compliance at scale:Distributed in-memory clusters struggle to maintain transactional guarantees across geographically separated nodes. Financial institutions in Frankfurt demand solutions that reconcile performance with consistency.
- Data residency verification complexity:Member-state implementations of GDPR diverge on cloud localization requirements. Procurement teams face certification ambiguity when evaluating sovereign cloud claims.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe in-Memory Database Market |
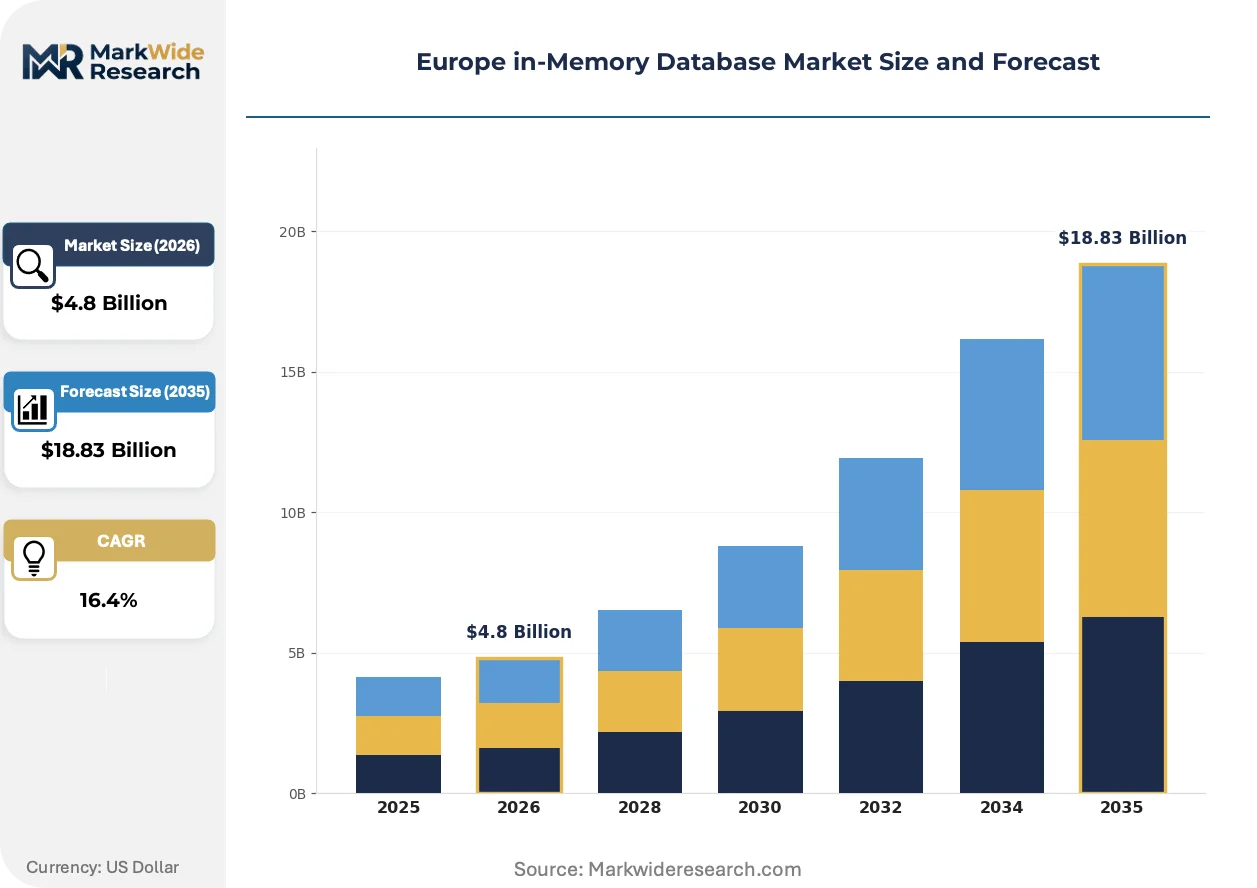
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $18.83 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Relational Databases, NoSQL Databases, NewSQL, Data Warehouses Deployment Model: On-Premises, Cloud-Based, Hybrid Cloud, Managed Services End User: Retail, Telecommunications, Financial Services, Healthcare Functionality: Real-Time Analytics, Data Processing, Data Integration, Reporting |
| Companies Covered | SAP SE, Oracle Corporation, Microsoft Corporation, IBM Corporation, Redis Ltd., VoltDB Inc., Aerospike Inc., Altibase Corp., ENEA AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe in-Memory Database Market Trends and Innovations
Memory-centric computing architectures are displacing disk-bound analytics across European regulated industries. Three distinct vectors—unified data platforms, compliance automation, and procurement transformation—are compressing vendor selection cycles.
Hybrid transactional/analytical processing is unifying operational and analytical workloads into single-tier architectures. German automotive manufacturers adopt HTAP engines to collapse the latency between shop-floor sensor ingestion and predictive maintenance analytics. This convergence eliminates ETL pipeline maintenance and reduces total data infrastructure footprint by half.
CSRD and EU AI Act documentation requirements are mandating automated audit trail generation. Financial services compliance teams in Paris and Amsterdam now specify real-time lineage tracking as a non-negotiable procurement criterion. Vendors respond with embedded governance layers that capture query provenance without performance degradation.
Buying committees are consolidating vendor relationships to reduce integration complexity. Mid-market retailers in Northern Italy and the Netherlands now favor managed service contracts over self-operated deployments. This preference shift favors providers with sovereign cloud certifications and localized support presence.
Europe in-Memory Database Market Segmentation
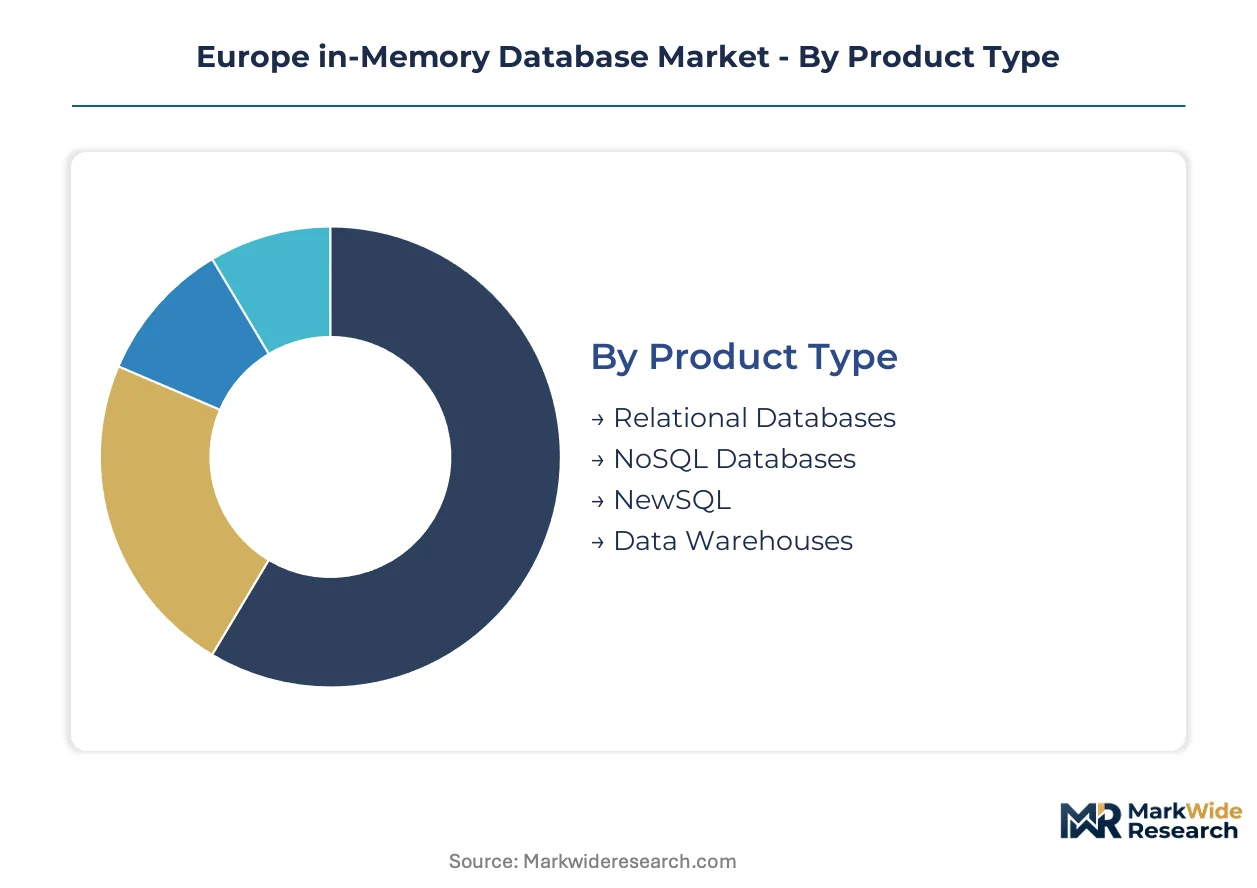
European procurement teams evaluate in-memory platforms through four intersecting lenses: data model architecture, infrastructure sovereignty, sector-specific compliance loads, and workload latency requirements. These dimensions determine pricing premiums and vendor selection criteria across Frankfurt banking clusters and Parisian insurance headquarters.
Product Type:
Relational systems command margin premiums where ACID guarantees matter; NoSQL alternatives win on velocity for unstructured workloads.
- Relational Databases:Columnar compression engines store tabular data in RAM-optimized formats. German financial services firms in Frankfurt deploy these for ECB stress-testing compliance where transactional integrity is non-negotiable.
- NoSQL Databases:Key-value and document stores handle schema-flexible ingestion at microsecond latency. Telecommunications operators in Amsterdam trace fraud patterns across subscriber graphs that relational schemas cannot navigate efficiently.
- NewSQL:Distributed SQL engines merge horizontal scalability with ACID semantics. Spanish retail banking clusters evaluate these for HTAP consolidation.
- Data Warehouses:Analytical appliances optimized for aggregation-heavy queries. French pharmaceutical headquarters near Paris deploy these for EMA pharmacovigilance reporting.
Today's leader: Relational Databases. Tomorrow's challenger: NoSQL Databases.
Deployment Model:
Sovereignty requirements tilt decisions toward localized infrastructure; elasticity demands pull toward managed consumption.
- On-Premises:Dedicated hardware installations within client-controlled facilities. Bavarian automotive manufacturers favor these for production line sensor processing where milliseconds determine quality control outcomes.
- Cloud-Based:Multi-tenant public cloud consumption with geographic zone selection. Dutch fintech developers in Amsterdam leverage these for elastic capacity during trading volume spikes.
- Hybrid Cloud:Split architectures with sensitive data on-premises and burst workloads in cloud. Italian insurance groups in Milan adopt these for GDPR-compliant customer analytics.
- Managed Services:Fully operated deployments with vendor-assumed operational burden. Mid-market retailers in Northern Italy select these to avoid distributed systems hiring constraints.
Cloud-Based deployments are expanding most quickly; Hybrid Cloud offers the steepest pricing premiums.
End User:
Sector regulatory intensity shapes functionality requirements and procurement cycle length.
- Retail:Real-time inventory and personalization engines. Spanish fashion retailers in Barcelona deploy in-memory recommendation layers that collapse click-to-purchase latency.
- Telecommunications:Network optimization and fraud detection at subscriber scale. Operators in London and Amsterdam process billions of daily events through graph-based stores.
- Financial Services:Algorithmic trading and compliance reporting with audit trails. Frankfurt banking clusters drive the steepest ACID requirements and corresponding price tolerance.
- Healthcare:Clinical decision support and pharmacovigilance processing. Basel pharmaceutical manufacturers invest in edge-localized deployments for EMA adverse event reporting.
Financial Services anchor current revenue concentration; Healthcare represents the steepest expansion trajectory.
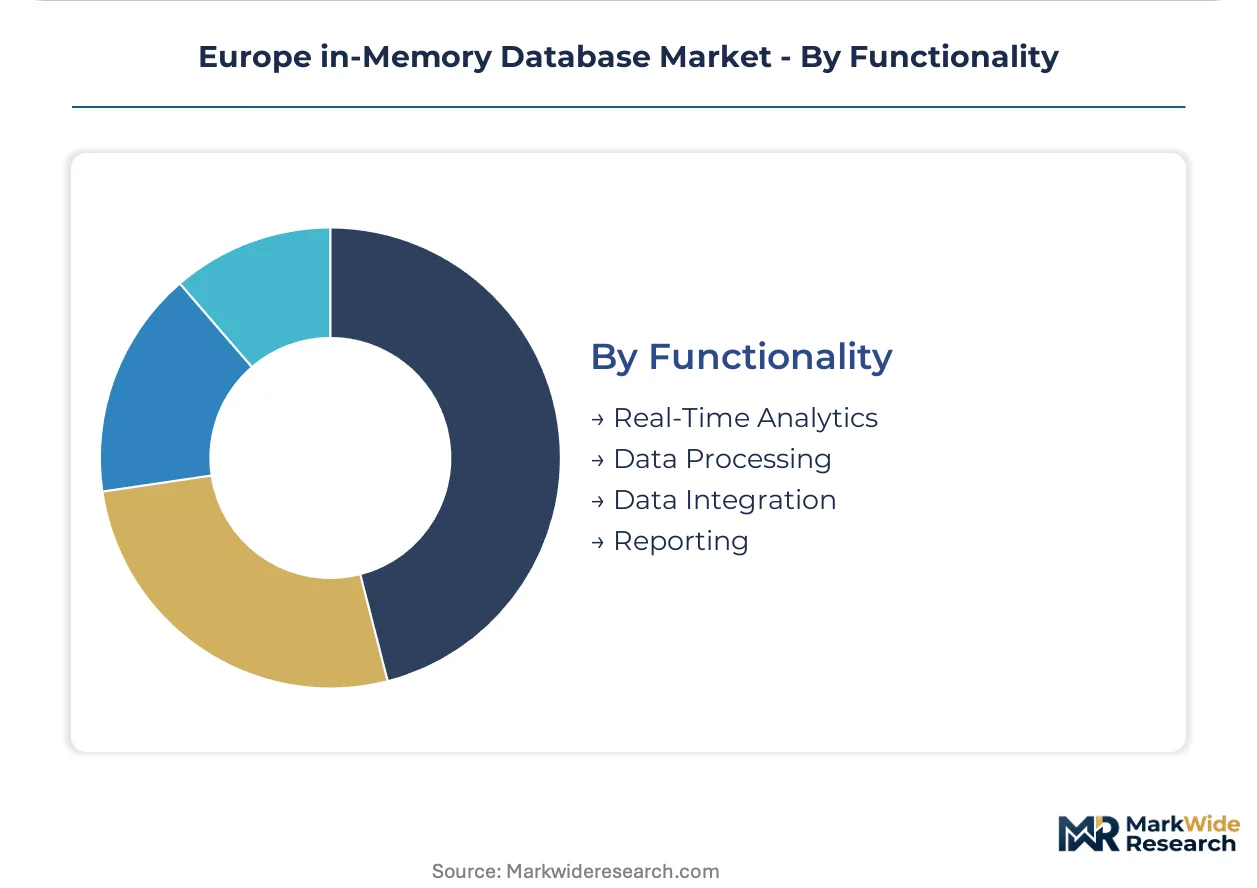
Functionality:
Workload type determines memory architecture and parallel processing topology.
- Real-Time Analytics:Sub-second query response on streaming data. German automotive plants in Stuttgart use these for predictive maintenance on robotic assembly lines.
- Data Processing:High-velocity ingestion and transformation. French logistics hubs near Lyon process IoT telemetry from refrigerated transport fleets.
- Data Integration:Unified access across disparate source systems. Italian banking groups consolidate core mainframe data with digital channel streams.
- Reporting:Scheduled and ad-hoc analytical output generation. Dutch energy traders generate CSRD-compliant emissions documentation through automated lineage capture.
Real-Time Analytics commands the largest deployment footprint; Data Integration is climbing fastest as legacy modernization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing in-memory database deployments across European jurisdictions as compliance cost differentials widen between member states with divergent GDPR enforcement intensity and sovereign cloud certification timelines.
Germany
Frankfurt banking clusters drive ACID-compliant relational deployments for ECB stress-testing protocols. The national financial regulator BaFin mandates real-time audit trails that favor RAM-resident architectures. Munich automotive manufacturers deploy HTAP engines for predictive maintenance on robotic assembly lines.
France
Parisian insurance headquarters prioritize explainable AI processing under EU AI Act algorithmic accountability rules. The national data protection authority CNIL enforces strict cross-border transfer limitations that localize deployment decisions. Lyon pharmaceutical manufacturers invest in edge nodes for EMA pharmacovigilance compliance.
United Kingdom
London fintech developers dominate open-source caching layers for real-time trading applications. The Financial Conduct Authority's operational resilience requirements compress recovery time objectives toward in-memory speeds. Amsterdam-adjacent cloud regions capture spillover demand from Brexit-relocated financial services operations.
Netherlands
Amsterdam telecommunications operators process billions of daily events through graph-based fraud detection stores. The Dutch central bank DNB mandates instant payment infrastructure that exceeds disk-based system capabilities. Eindhoven semiconductor equipment manufacturers deploy sensor analytics for sub-second quality control.
Switzerland
Basel pharmaceutical headquarters seek edge-localized deployments for Swissmedic adverse event reporting requirements. The country's non-EU status creates data residency verification complexity for cross-border cloud architectures. Zurich private banking clusters demand hybrid configurations balancing performance with jurisdictional control.
Europe in-Memory Database Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue sovereign cloud specialization and HTAP convergence as differentiation vectors. The vendor base stratifies across three maturity levels: legacy database incumbents with on-premises install bases, cloud-native challengers with managed service portfolios, and open-source specialists with developer-centric distribution. Two dominant competitive moves define current positioning: backward integration into semiconductor supply chains to secure DDR5 allocation certainty, and strategic partnerships with sovereign cloud operators to satisfy data residency verification requirements.
Within the legacy incumbent tier, SAP SE and Oracle Corporation exemplify enterprise consolidation strategies that extend historical footprints into regulated European accounts. Redis Ltd. occupies a position among open-source specialists dominating real-time application stacks. These three anchors represent distinct competitive archetypes—vertical software integration, database platform breadth, and developer ecosystem capture—rather than direct substitutability.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| IBM Corporation |
| Redis Ltd. |
| VoltDB Inc. |
| Aerospike Inc. |
| Altibase Corp. |
| ENEA AB |
| Others |
Pricing and Supply Chain Analysis
Distributed systems engineering talent pools in London and Amsterdam create labor-cost differentials that widen pricing-tier spreads between premium managed-service contracts and self-operated deployments. Frankfurt banking clusters absorb ACID-compliant premiums while mid-market retailers in Northern Italy negotiate economy-tier SaaS rates.
Pricing Analysis
Distributor margins on sovereign cloud certifications command substantial markups over standard public-cloud deployments. Three-tier pricing structure across premium, standard, and economy levels separates BaFin-mandated audit-trail bundles from basic caching layers. Cost compression in the standard tier is intensifying because DDR5 memory pricing volatility complicates multi-year contract structures. Mid-market retailers exhibit highest price sensitivity; Frankfurt financial services firms demonstrate least sensitivity due to regulatory non-compliance penalties.
Supply Chain Analysis
Refurbishment flows for server-grade DDR5 modules remain underdeveloped across European distribution networks. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States. European deployments draw from Taiwanese foundry output, South Korean memory packaging, and Dutch lithography equipment. Single-source vulnerability in advanced node production creates supply chain risk. Distribution runs through Frankfurt and Amsterdam hyperscaler regions with localized edge nodes in Munich and Paris.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act compliance deadline functions as a regulatory compounder, mandating explainable processing trails that accelerate procurement cycles for audit-capable architectures.
For Market Incumbents: Lock in sovereign cloud certifications before member-state implementations diverge further. Defensive consolidation through backward integration into DDR5 supply agreements secures allocation certainty against semiconductor fab capacity constraints. Channel control via localized support presence in Frankfurt and Paris protects margin pools from cloud-native challengers. For New Entrants and Emerging Players: CSRD in the European Union opens a window for carbon-accounting platform specialization targeting Ruhr Valley industrial conglomerates. White-space concentration in edge-localized pharmacovigilance for Basel and Lyon pharmaceutical manufacturers offers penetrable entry points. Go-to-market through managed service contracts bypasses continental skill scarcity in distributed systems engineering. For Investors and Strategic Acquirers: Hyperscaler cloud divisions are the most active acquirer in this space, seeking sovereign certification capabilities for European public sector eligibility. Long-term viability centers on regulatory moat durability rather than feature differentiation. Acquisition target archetype: HTAP specialists with BaFin-validated audit architectures. Monitor EMA adverse-event reporting mandate enforcement as inflection indicator for edge-deployment demand.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Certification | BaFin and CNIL validation unlocks Frankfurt and Paris financial services procurement. |
| HTAP Platform Convergence | Bavarian automotive manufacturers collapse ETL pipelines for predictive maintenance. |
| Backward Integration into DDR5 Supply | Allocation certainty protects margin pools against semiconductor fab volatility. |
| Edge Localization Partnership | Swissmedic and EMA compliance positions Basel pharmaceutical deployments. |
| Managed Service Portfolio Expansion | Northern Italian retailers avoid distributed systems hiring constraints. |
Research Methodology
Direct dialogue with CTOs at Frankfurt banking clusters, IT procurement officers in Parisian insurance headquarters, platform engineers at Amsterdam fintechs, and integration specialists across German automotive manufacturers grounded qualitative findings. Secondary validation drew from ECB stress-testing protocol disclosures, EMA pharmacovigilance guidance documents, hyperscaler European capex filings, and CSRD implementation timelines. Bottom-up deployment counts triangulated against top-down infrastructure spending estimates.
Segmentation outputs across relational, NoSQL, NewSQL, and data warehouse architectures combined with deployment model splits and vertical adoption patterns. CAGRs derived from regression against DDR5 price elasticity, regulatory compliance cost curves, and cloud migration velocity. Industry-specific inputs included BaFin real-time audit mandates and EMA edge-localization requirements.
Revisions become necessary when member-state GDPR implementations diverge beyond current baselines or DDR5 supply constraints exceed projected fab capacity. Forecasts embed assumptions around sovereign cloud certification timelines and EU AI Act enforcement intensity. Practitioners should monitor EMA pharmacovigilance mandate rollout and BaFin operational resilience deadlines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Storage Solutions
Poland Data Center Storage Market
Storage Solutions
Global Ethernet Storage Fabric Market
Storage Solutions
Automated Storage and Retrieval System (AS & RS) Market
Storage Solutions
Virtual Machine Backup and Recovery Market
Storage Solutions
Global Enterprise File Sharing and Synchronization (EFSS) Market
Storage Solutions
Storage and Backup Software Market
Storage Solutions
Thailand Data Center Storage Market
Storage Solutions
New Zealand Data Center Storage Market
Storage Solutions
Storage Software Market
Storage Solutions
Indonesia Data Center Storage Market
Storage Solutions
Scale-Out NAS Market
Storage Solutions
Philippines Data Center Storage Market
Storage Solutions
Hong Kong Data Center Storage Market
Storage Solutions
Stand Alone Cloud Storage Market
Storage Solutions
Global Virtual Data Storage Market
Storage Solutions
Italy Data Center Storage Market