
 Singapore Data Center Power Market | 2026-2036
Singapore Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Power Market Insights
Cloud service providers is restructuring the buyer landscape for data center power infrastructure in Singapore. Schneider Electric SE leverages its integrated power management portfolio to anchor large-scale deployments across the island. Vertiv Holdings Co competes through thermal and power integration expertise tailored to tropical climates. Cummins Inc. specializes in backup generator systems that sustain uptime during grid instability events.
Singapore Data Center Power encompasses the generation, conditioning, distribution, and backup systems that ensure continuous electrical supply to server facilities, typically operating at 380/400V three-phase AC with redundancy tiers from N to 2N configurations. Its primary purpose is to eliminate downtime for digital infrastructure serving financial services, cloud computing, and telecommunications. Diesel generators retain dominant installed base share among power source categories, though renewable energy integration is accelerating fastest as operators respond to carbon disclosure requirements. Colocation providers represent the deepest margin pool within end user segments, given their multi-tenant model demands standardized, scalable power architectures.
Singapore's Energy Market Authority and the Infocomm Media Development Authority jointly govern data center power standards, with the former regulating grid connection capacity and the latter imposing sustainability benchmarks on new facility approvals. The Building and Construction Authority's Green Mark certification further shapes equipment selection by mandating energy efficiency thresholds for cooling and power distribution. Stakeholders must monitor how regulatory caps on total data center power consumption interact with artificial intelligence workload growth to determine viable expansion pathways.
Market Dynamics
Artificial intelligence workload density is compressing power deployment timelines across Singapore's data center clusters, forcing operators to secure multi-megawatt capacity ahead of traditional build schedules.
Growth Catalysts
- IMDA Sustainability Standards:The Infocomm Media Development Authority's carbon disclosure mandates are accelerating renewable energy procurement by colocation providers seeking facility approvals.
- Jurong Cluster Concentration:Existing fiber and power infrastructure in western Singapore is pulling hyperscale investments toward established industrial zones with verified grid capacity.
- Liquid Cooling Adoption:Direct-to-chip thermal management is enabling 100kW+ rack densities that justify premium power architecture investments.
Market Restraints
- Grid Interconnection Queues:Singapore Power's approval timelines for new substations now extend 24-36 months, freezing expansion for uncertified projects.
- Diesel Generator Dependence:Backup power systems retain 85% installed base share, locking operators into fuel supply chains with volatile carbon tax exposure.
- Land Scarcity Premium:Industrial plot availability in Tanjong Klang has compressed below 5 hectares, concentrating bargaining power with state land agencies.
Strategic Opportunities
- Solar-Plus-Storage Integration:Building and Construction Authority Green Mark certification rewards on-site renewable generation, creating procurement advantages for early adopters.
- Edge Computing Nodes:Distributed micro-data centers in Punggol and Tampines offer lower power density entry points for latency-sensitive financial services.
- Waste Heat Recovery:District cooling network partnerships with JTC Corporation enable revenue diversification through thermal energy export to adjacent industrial tenants.
Industry Challenges
- Specialized Electrical Talent:High-voltage commissioning engineers with tropical climate experience command 40% wage premiums, constraining deployment velocity.
- Legacy UPS Synchronization:Retrofitting 10-15 year old static switchgear for lithium-ion battery compatibility requires extended outage windows that violate tenant SLA terms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Power Market |
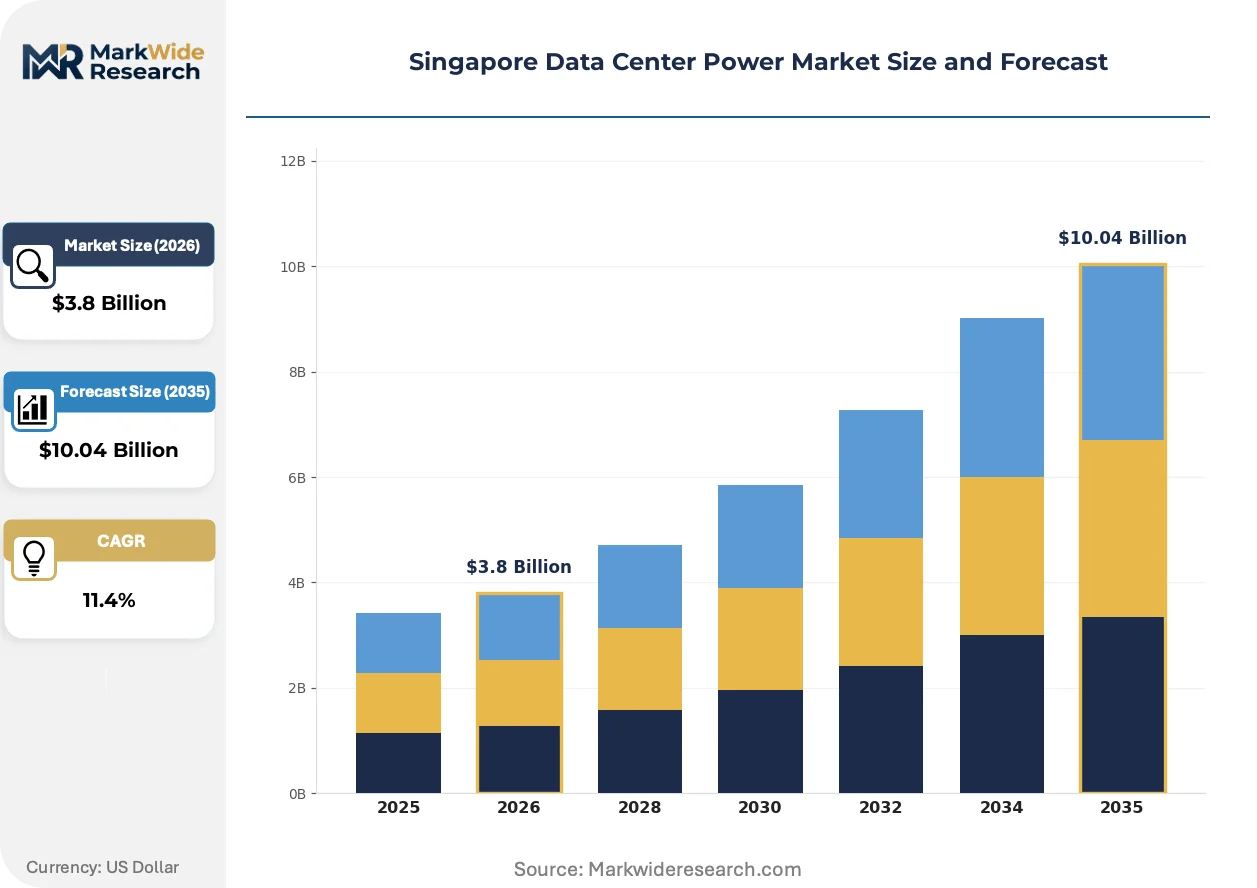
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable Energy, Diesel Generators, UPS, Grid Power End User: Colocation Providers, Cloud Service Providers, Enterprises, Telecommunication Companies Capacity: Below 1 MW, 1-5 MW, 5-10 MW, Above 10 MW Power Type: AC Power, DC Power, Hybrid Power, Others |
| Companies Covered | ABB Ltd, Schneider Electric SE, Eaton Corporation plc, Cummins Inc., Caterpillar Inc., Legrand SA, Vertiv Holdings Co, Generac Holdings Inc, GE Aerospace, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Power Market Trends and Innovations
Power infrastructure design is pivoting from redundancy-centric architectures toward efficiency-optimized systems that prioritize carbon intensity metrics alongside uptime guarantees.
Solid-state transformer technology is rewriting voltage conversion economics for hyperscale facilities. Google Cloud and Microsoft Azure are piloting silicon carbide-based distribution systems in Singapore's Tuas development zone. This semiconductor advance is rewriting the trade-off between power quality and conversion losses that has dominated three-decade-old facility designs.
Singapore's Energy Market Authority introduced a carbon intensity disclosure mandate for grid-connected data centers above 5MW capacity. The regulation forces operators to report hourly marginal emissions factors alongside traditional PUE metrics. Colocation providers serving multinational financial tenants face the steepest compliance burden as these clients embed the data into Scope 3 supply chain audits.
Power purchase agreement structures are fragmenting procurement responsibility between facility operators and their cloud tenant customers. Amazon Web Services and ByteDance now contract directly with Sembcorp Industries for solar generation credits, bypassing traditional landlord-mediated utility arrangements. This disintermediation is most visible in the Jurong cluster where land-scarce operators compete on renewable energy access rather than base rack rates.
Singapore Data Center Power Market Segmentation
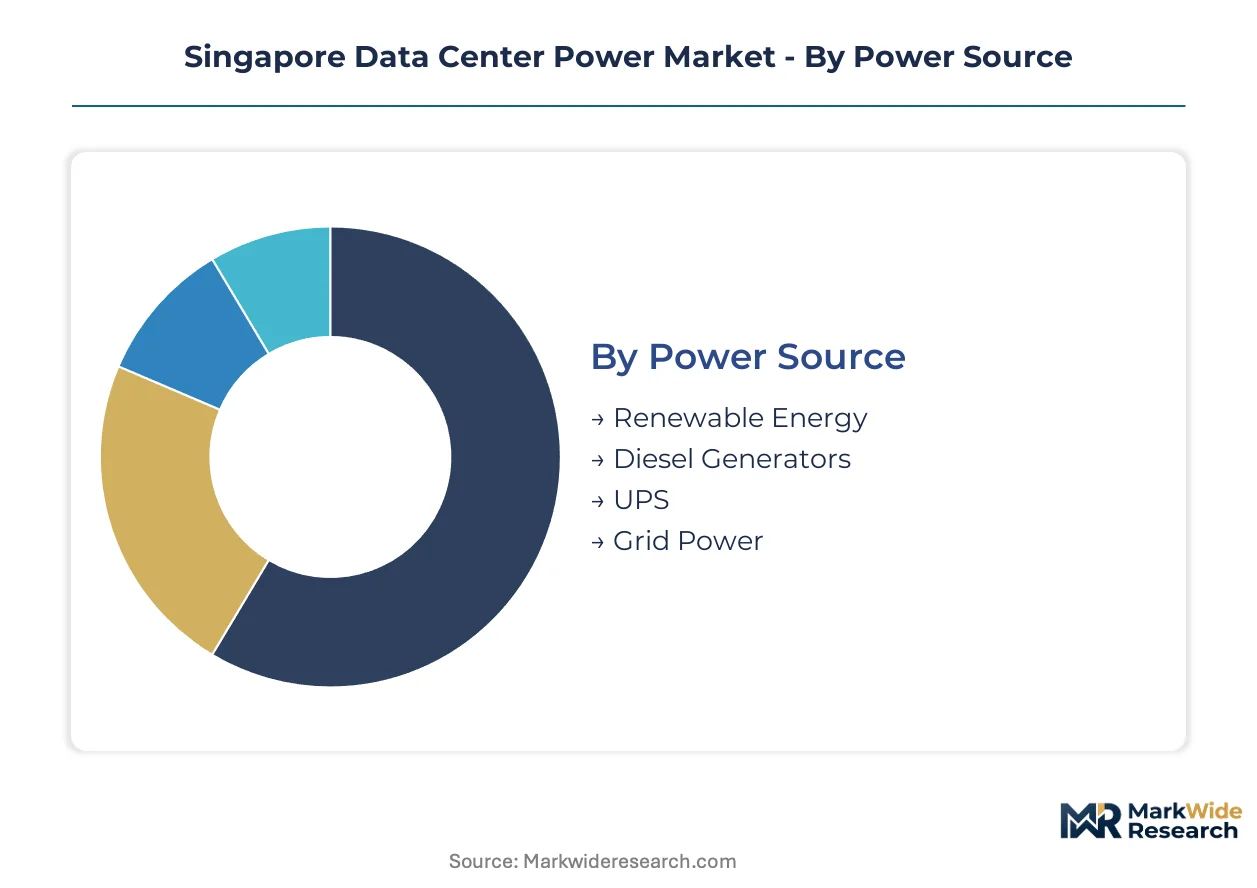
Singapore's data center power market segments along four critical dimensions that determine procurement patterns and infrastructure design. Power source and capacity classifications shape capital allocation priorities, while end user type and power configuration dictate technical specifications and margin structures.
Power Source:
Standardization dominates renewable energy and grid power procurement, while diesel generators and UPS systems demand customized engineering for tropical climate resilience.
- Diesel Generators:These backup systems provide 380/400V three-phase output with N+1 or 2N redundancy configurations. Demand concentrates among colocation providers in Jurong and Tanjong Klang clusters where grid instability risks and tenant SLA requirements mandate sustained uptime guarantees. Operators face mounting carbon tax exposure as Singapore's Energy Market Authority tightens emissions disclosure mandates.
- Renewable Energy:Solar-plus-storage arrays and green power purchase agreements supply marginal grid demand. Cloud service providers including Amazon Web Services and ByteDance now contract directly with Sembcorp Industries for solar generation credits, bypassing traditional landlord-mediated arrangements in land-scarce western Singapore.
- UPS:Static and rotary uninterruptible power systems condition electricity between grid and rack distribution. Financial services tenants in Punggol edge nodes specify lithium-ion battery configurations for reduced footprint.
- Grid Power:Singapore Power's 22kV and 66kV substation connections form the primary supply foundation. Grid interconnection queues now extend 24-36 months, freezing expansion timelines for uncertified projects.
Most installed capacity flows through diesel generators. Expansion is steepest in renewable energy procurement as IMDA sustainability standards harden facility approval requirements.
End User:
Volume concentration and margin capture diverge sharply across tenant types, with hyperscale clouds driving megawatt-scale deployments against enterprise preference for standardized colocation.
- Colocation Providers:These multi-tenant operators demand standardized, scalable power architectures that accommodate diverse client specifications. Equinix and ST Telemedia facilities in Jurong cluster anchor the deepest margin pool through premium pricing for certified redundancy tiers and renewable energy access.
- Cloud Service Providers:Google Cloud and Microsoft Azure are piloting silicon carbide-based distribution systems in Tuas development zone. Direct power purchase agreements and custom substation designs characterize their procurement approach.
- Enterprises:Single-tenant financial institutions and regional headquarters favor predictable opex models through colocation partnerships rather than self-built infrastructure.
- Telecommunication Companies:Singtel and StarHub integrate data center power with 5G edge computing nodes, requiring lower density configurations than hyperscale facilities.
Revenue concentrates with colocation providers. Cloud service providers are gaining share fastest through direct renewable energy contracting and custom infrastructure development.
Capacity:
Scale thresholds determine grid connection complexity, with sub-5MW facilities accessing standardized utility processes while larger deployments trigger bespoke regulatory negotiation.
- Above 10 MW:Hyperscale campuses require dedicated 66kV substations and individual carbon intensity disclosure under Energy Market Authority mandates. These facilities anchor Singapore's approved data center capacity allocation.
- 5-10 MW:Mid-scale deployments serve regional cloud availability zones and large enterprise requirements. Jurong cluster concentration reflects verified grid capacity in this tier.
- 1-5 MW:Edge computing and financial services nodes populate this segment. Punggol and Tampines distributed facilities favor lower power density entry points.
- Below 1 MW:Micro-data centers and network point-of-presence sites operate here. Limited land availability constrains greenfield development.
Construction activity clusters in the 5-10 MW and above 10 MW tiers. The below 1 MW segment faces steepest land scarcity constraints.
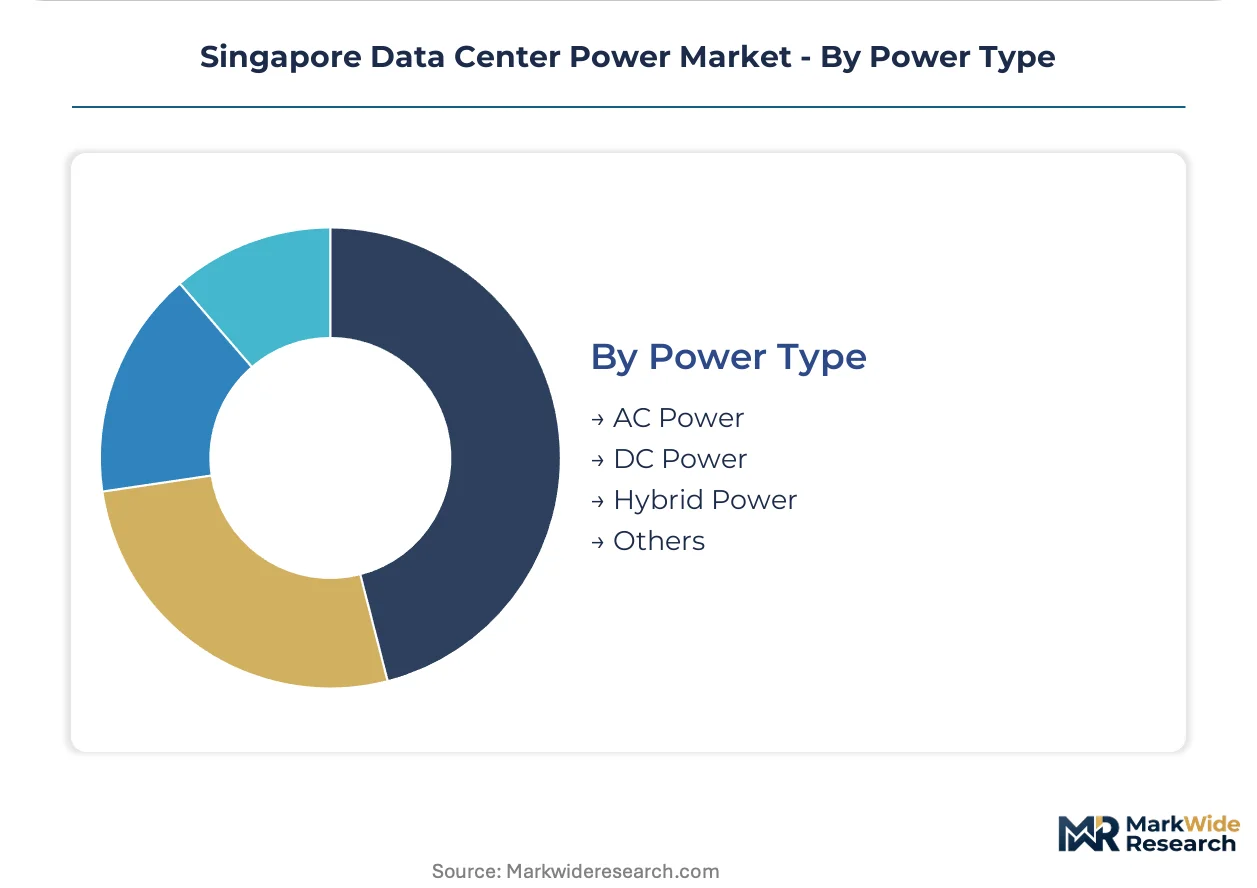
Power Type:
AC dominance persists for legacy compatibility, though DC and hybrid configurations gain traction in efficiency-optimized designs targeting carbon intensity metrics.
- AC Power:380/400V three-phase distribution remains the universal standard for server rack compatibility. Existing facility retrofits and tenant equipment requirements lock in AC architecture.
- DC Power:380V DC eliminates conversion losses between battery storage and IT equipment. Direct-to-chip liquid cooling integration enables 100kW+ rack densities that justify premium DC infrastructure investment.
- Hybrid Power:AC distribution with DC point-of-load conversion optimizes efficiency for artificial intelligence workload densities. Google Cloud pilots this architecture in Tuas.
- Others:Solid-state transformer technology and silicon carbide-based systems represent emerging configurations not yet standardized.
Installed base remains overwhelmingly AC. DC and hybrid configurations are climbing the fastest as liquid cooling adoption justifies infrastructure overhaul.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping data center power infrastructure deployment across Southeast Asia, as Singapore's tightening carbon disclosure mandates and grid interconnection queues push operators toward neighboring jurisdictions with faster approval timelines and lower compliance costs.
Malaysia
Iskandar Malaysia and Cyberjaya are capturing overflow demand from Singapore-constrained hyperscalers seeking sub-24-month grid connection timelines. The Malaysia Digital Economy Corporation's MD Status incentive program grants tax holidays and streamlined permitting for data center investments above 500MW capacity. Johor Bahru's Sedenak Tech Park anchors the fastest-growing cluster, with direct fiber links to Singapore's Jurong exchange points.
Indonesia
Batam and Nongsa Digital Park exploit proximity to Singapore's fiber landing stations while operating outside its jurisdictional carbon caps. The Coordinating Ministry for Maritime and Investment Affairs issued Regulation 5/2021 easing foreign ownership restrictions for data center investments in special economic zones. Batam's Hang Nadim International Airport corridor concentrates ongoing hyperscale negotiations for 100MW+ campus developments.
Thailand
Eastern Economic Corridor provinces Chonburi and Rayong leverage Board of Investment incentives for digital infrastructure investments, including eight-year corporate income tax exemptions. The National Broadcasting and Telecommunications Commission's 2023 data center licensing framework mandates disaster resilience standards that favor Tier III+ power redundancy configurations. Amata City and Asia Industrial Estate host the deepest pipeline of certified projects.
Philippines
Clark Freeport Zone and Cebu IT Park attract disaster recovery deployments seeking geographic diversification from Singapore's single-point-of-failure risk profile. The Philippine Economic Zone Authority's Memorandum Circular 74-2021 grants renewable energy self-generation permits to data center operators, bypassing utility intermediation. Manila's congested power grid pushes new investment toward Luzon northern provinces with verified geothermal availability.
Vietnam
Ho Chi Minh City and Hanoi face regulatory uncertainty as Decree 72 on internet services lacks implementing guidance for data center power standards. The Ministry of Information and Communications' draft national data center strategy proposes renewable energy quotas that would replicate Singapore's IMDA sustainability trajectory. Cau Giay and Thu Duc districts concentrate existing carrier-neutral facilities serving regional content delivery networks.
Singapore Data Center Power Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated power management portfolios commanding premium positioning in colocation deployments while component suppliers compete on tropical climate engineering credentials. Market structure concentrates around three strategic archetypes: full-stack infrastructure integrators, backup power system specialists, and thermal-electrical convergence players. Capacity expansion and direct renewable energy contracting constitute the dominant competitive vectors as land scarcity intensifies site access competition.
Among the integrated infrastructure tier, Schneider Electric SE and ABB Ltd occupy positions exemplifying power distribution and automation convergence for hyperscale specifications. Vertiv Holdings Co and Eaton Corporation plc represent the thermal-electrical integration archetype, with tropical climate engineering credentials concentrated in their service portfolios. Cummins Inc. anchors the backup power specialist category, with diesel generator and energy storage configurations serving continuity requirements across Singapore's certified facility base.
| Leading Market Players |
|---|
| ABB Ltd |
| Schneider Electric SE |
| Eaton Corporation plc |
| Cummins Inc. |
| Caterpillar Inc. |
| Legrand SA |
| Vertiv Holdings Co |
| Generac Holdings Inc |
| GE Aerospace |
| Others |
Pricing and Supply Chain Analysis
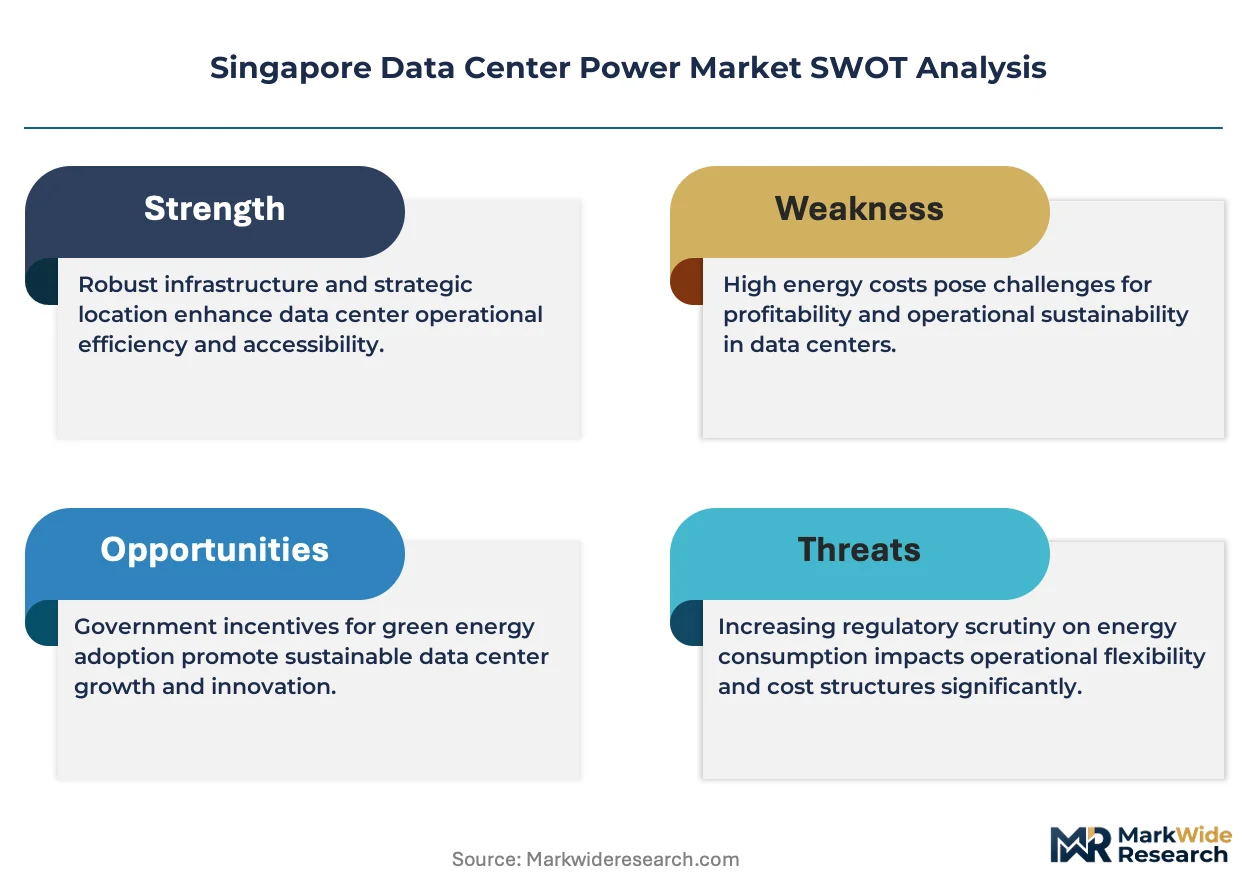
Silicon carbide wafer spot prices cascade through Singapore's data center power supply chain, compressing margins for static switchgear assemblers while amplifying pricing power for solid-state transformer integrators serving hyperscale direct contracts.
Pricing Analysis
Distributor margins on backup generator sets absorb carbon tax pass-through volatility, creating three-tier pricing structure across premium certified redundancy, standard N+1 configurations, and economy colocation specifications. Price differentiation hinges on Green Mark certification tier and tropical climate engineering credentials. Cost compression in mid-tier UPS systems is intensifying because lithium-ion battery commoditization erodes legacy lead-acid bundling power. Enterprise financial services tenants exhibit highest price sensitivity, while hyperscale cloud providers prioritize energy density metrics over rack-rate negotiation.
Supply Chain Analysis
High-voltage commissioning engineer shortages in Singapore, Malaysia, and Vietnam constrain deployment velocity for 66kV substation projects. Manufacturing draws from German precision switchgear, Chinese silicon carbide substrates, and Japanese power semiconductor foundries. Single-source vulnerability concentrates in tropical-hardened diesel generator engine blocks from European OEMs. Distribution runs through integrated infrastructure integrators for hyperscale direct sales and electrical distributors serving mid-tier colocation retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's data center power market represents a late-cycle quality story as artificial intelligence workload density shifts procurement criteria toward liquid-cooled, high-redundancy premium specifications over cost-optimized legacy designs.
For Market Incumbents: Hedge carbon tax exposure by accelerating renewable energy procurement ahead of IMDA disclosure mandate tightening. Secure captive supply of tropical-hardened generator engines through backward integration into Southeast Asian assembly partnerships. Defend margin position against solid-state transformer disintermediation by embedding silicon carbide distribution into full-stack service contracts. For New Entrants and Emerging Players: Begin with edge computing nodes in Punggol and Tampines where land scarcity pressures are lower and 1-5 MW capacity tiers face less incumbent saturation. Target financial services latency-sensitive deployments as the most penetrable segment given tenant preference for standardized opex models. Pursue direct renewable energy contracting as the primary go-to-market angle to bypass established landlord-mediated utility arrangements. For Investors and Strategic Acquirers: Asymmetric upside sits with thermal-electrical convergence specialists possessing tropical climate engineering IP and active service contracts in Jurong cluster facilities. Long-term viability favors acquisition targets with demonstrated lithium-ion battery integration capabilities and Green Mark certification track records. Monitor grid interconnection queue clearance rates as the critical inflection signal for capacity expansion feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Solid-State Transformer Deployment | Google Cloud and Microsoft Azure pilots in Tuas rewrite voltage conversion economics for tropical hyperscale facilities. |
| Direct Renewable Energy Contracting | Amazon Web Services and ByteDance bypass landlord mediation through Sembcorp Industries solar credit arrangements. |
| Liquid Cooling Infrastructure Integration | Direct-to-chip thermal management enables 100kW+ rack densities justifying premium DC power architecture investment. |
| Grid Interconnection Capacity Securement | 24-36 month Singapore Power approval timelines freeze expansion for uncertified projects lacking verified substation access. |
| High-Voltage Talent Pipeline Development | 40% wage premiums for tropical-experienced commissioning engineers constrain deployment velocity across all tiers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, utility planning officers at Singapore Power, procurement leads at colocation providers, and EPC contractors specializing in tropical electrical infrastructure with secondary validation against Energy Market Authority regulatory filings, Building and Construction Authority Green Mark databases, Infocomm Media Development Authority facility approval records, and hyperscaler capital expenditure disclosures. Bottom-up installation base modeling and top-down regulatory capacity allocation triangulation anchored market sizing.
Segment-weighting applied differential growth coefficients across power source, end user, capacity tier, and power type dimensions over the projection horizon. Analytical framework incorporated carbon intensity disclosure mandate compliance costs, grid interconnection queue dynamics, and liquid cooling adoption curves as industry-specific forecast inputs. CAGRs derived from capacity expansion pipelines cross-referenced against regulatory approval velocity and land availability constraints.
Several conditions sit outside the modeled scope, including potential relaxation of IMDA sustainability standards, breakthrough solid-state battery commercialization timelines, and regional geopolitical disruption to Malaysia-Singapore fiber interconnection. Forecasts reflect documented assumptions regarding continued artificial intelligence workload growth and stable carbon tax trajectories. Material deviation in grid interconnection clearance rates or renewable energy credit pricing warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Canada Data Center Construction Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Data Center Blade Server Market
Data Center Infrastructure
Jakarta Data Center Market
Data Center Infrastructure
Vietnam Data Center Market
Data Center Infrastructure
Mexico Data Center Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
Indonesia Data Center Physical Security Market
Data Center Infrastructure
Data Center Blocks Market
Data Center Infrastructure
Data Center Fabric Market
Data Center Infrastructure
Middle East Data Center Market
Data Center Infrastructure
New Zealand Data Center Physical Security Market
Data Center Infrastructure
High Frequency Trading Server Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Sweden Data Center Server Market
Data Center Infrastructure
LAMEA Virtual Desktop Infrastructure Market