
 Norway Data Center Power Market | 2026-2036
Norway Data Center Power Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Data Center Power Market Insights
Norwegian hydroelectric generation capacity is broadening the addressable market for data center power infrastructure. Schneider Electric SE leverages its integrated power distribution portfolio to serve colocation builds across the Oslofjord corridor. ABB Ltd. anchors medium-voltage switchgear supply for facilities tapping directly into the national grid. Eaton Corporation competes on uninterruptible power systems sized for hyperscaler redundancy requirements.
Data center power encompasses electrical infrastructure from substation to rack, including transformers, switchgear, UPS units, and power distribution units engineered for uptime exceeding 99.999 percent. Norway's near-zero carbon grid intensity makes the country a preferred location for energy-intensive artificial intelligence training clusters. Liquid cooling integration with power systems represents the fastest-growing configuration as rack densities exceed 50 kilowatts. Hyperscaler end users command the largest margin pools through multi-megawatt contracts with integrated efficiency guarantees. Diesel backup systems face structural decline as battery energy storage duration improves and grid reliability reduces outage risk.
EU Green Deal targets and Norway's national renewable energy certificates shape procurement mandates for zero-carbon power sourcing. The Norwegian Water Resources and Energy Directorate regulates grid connection standards and capacity allocation for large industrial consumers. Stakeholders must monitor evolving efficiency certification thresholds under BREEAM and ISO 50001 as hyperscalers embed sustainability metrics into supplier qualification.
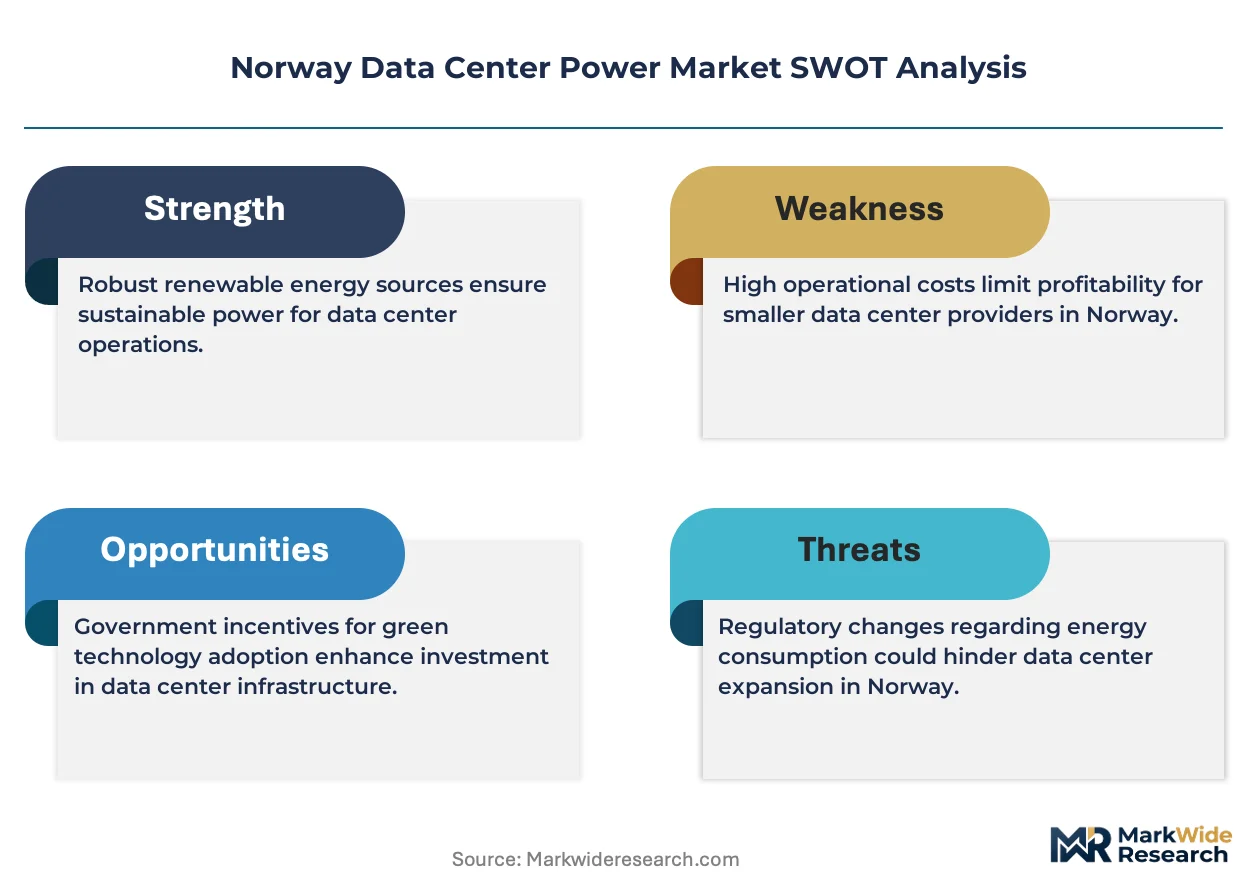
Market Dynamics
Norway's near-zero carbon grid intensity is pulling hyperscale artificial intelligence training clusters away from coal-heavy European alternatives, reshaping power infrastructure procurement patterns across the Oslofjord corridor.
Growth Catalysts
- EU Green Deal compliance mandates:Carbon border adjustment mechanisms penalize data center operators sourcing from fossil-heavy grids, redirecting workload placement toward Norwegian hydroelectric zones.
- Liquid cooling integration:Rack densities exceeding 50 kilowatts demand power distribution units engineered for thermal-electric convergence, opening specification windows for integrated suppliers.
- Oslo submarine cable landing stations:Low-latency Nordic connectivity through NO-UK, Havfrue, and Skagerrak cables positions eastern Norway as a natural compute aggregation point.
Market Restraints
- Grid connection queuing delays:The Norwegian Water Resources and Energy Directorate allocates transmission capacity through industrial consumer priority tiers, creating 18-24 month lead times for multi-megawatt facilities.
- Skilled electrical technician scarcity:Medium-voltage switchgear commissioning and protection relay programming expertise concentrates in Stavanger oil services clusters, not data center construction zones.
- Copper and rare earth magnet price volatility:Transformer core materials and permanent magnet UPS systems face input cost swings that compress fixed-price contract margins.
Strategic Opportunities
- Tromsø Arctic Circle positioning:Free air cooling potential and stranded hydroelectric capacity in northern Norway offer untapped sites for latency-tolerant batch computing workloads.
- Battery energy storage duration improvements:Lithium iron phosphate systems with four-hour discharge capability are displacing diesel rotary uninterruptible power supplies in redundancy architectures.
- ISO 50001 energy management certification:Hyperscaler supplier qualification programs embed efficiency verification requirements that favor vendors with integrated metering and analytics platforms.
Industry Challenges
- BREEAM-NOR certification timeline compression:Sustainability scoring thresholds for mechanical and electrical systems require documentation cycles that outpace standard equipment procurement schedules.
- Legacy diesel backup integration with battery-dominant architectures:Hybrid redundancy designs demand control system harmonization between rotating machines and solid-state inverters, complicating commissioning protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Data Center Power Market |
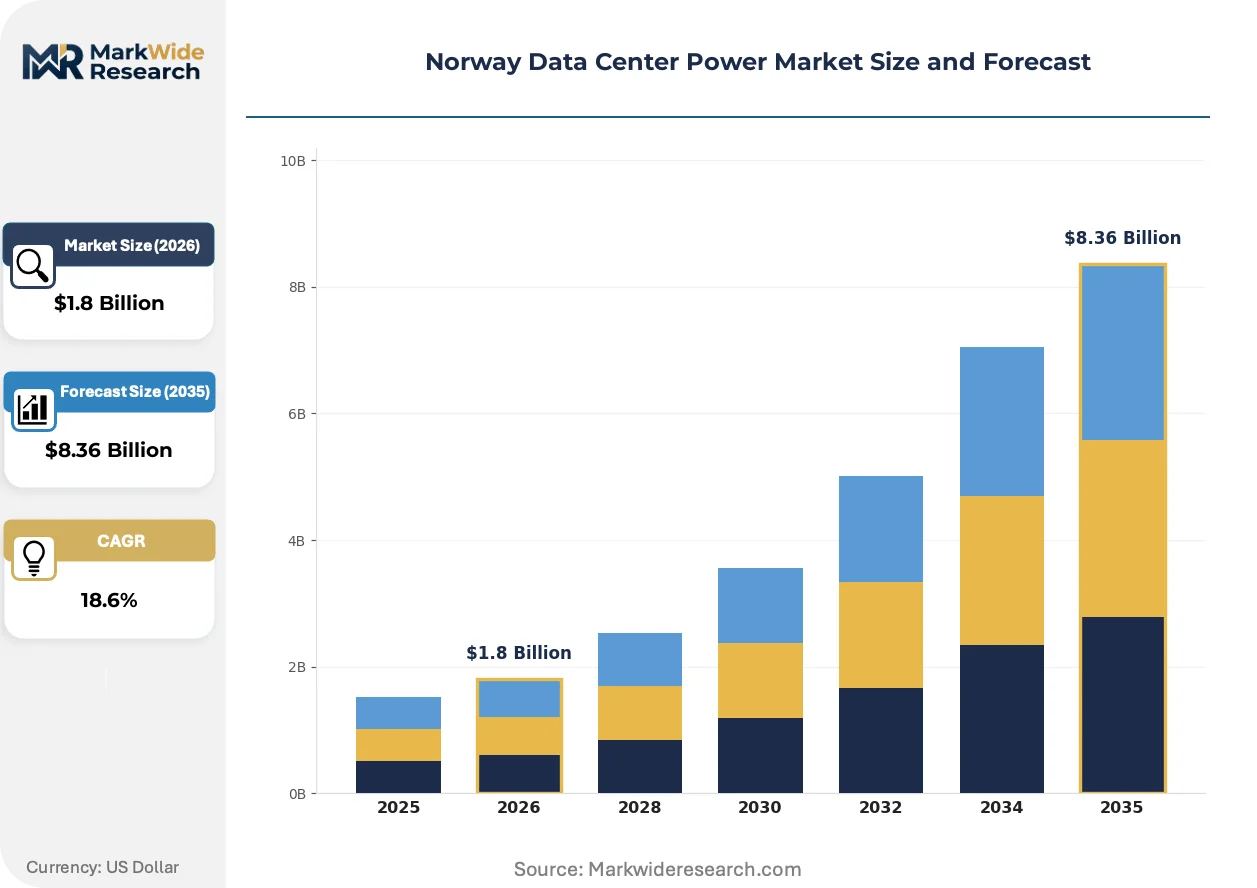
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Source: Renewable, Diesel, Grid, UPS End User: Colocation Providers, Enterprises, Managed Service Providers, Hyperscalers Energy Efficiency Standard: LEED, BREEAM, Energy Star, ISO 50001 Cooling Technology: Air Cooling, Liquid Cooling, Evaporative Cooling, Immersion Cooling |
| Companies Covered | Schneider Electric SE, ABB Ltd., Eaton Corporation, Cisco Systems Inc., Fujitsu Limited, Vertiv, Delta Electronics, Cummins, Caterpillar, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Data Center Power Market Trends and Innovations
Power infrastructure in Norwegian data centers is converging around thermal-electric integration and carbon-accounting transparency, compressing procurement cycles for vendors who can certify full-stack efficiency.
Direct liquid cooling manifolds paired with high-voltage DC bus architectures are expanding into hyperscale facilities targeting artificial intelligence training loads. Microsoft and Google procurement teams specify 380V DC distribution to eliminate AC-DC conversion losses at the rack level. This technology is expanding into colocation contracts that previously standardized on traditional three-phase AC infrastructure.
Norway's renewable energy certificate system (GOs) now requires hourly matching rather than annual aggregation for facilities claiming carbon-neutral operations. The Norwegian Water Resources and Energy Directorate tightened verification protocols in response to greenwashing investigations across European data center markets. Operators in the Oslo region are responding by procuring firm hydroelectric contracts with real-time generation telemetry rather than certificate-only offset structures.
Hyperscale end users now unbundle equipment procurement from engineering-procurement-construction contracts, creating direct vendor relationships for power distribution components. Colocation providers lose margin capture on electrical infrastructure as cloud operators specify switchgear, UPS, and rack PDUs through approved manufacturer lists. This pattern is most visible in Stavanger and Drammen municipality projects where Amazon Web Services and Meta Platforms have taken direct contracting roles.
Norway Data Center Power Market Segmentation
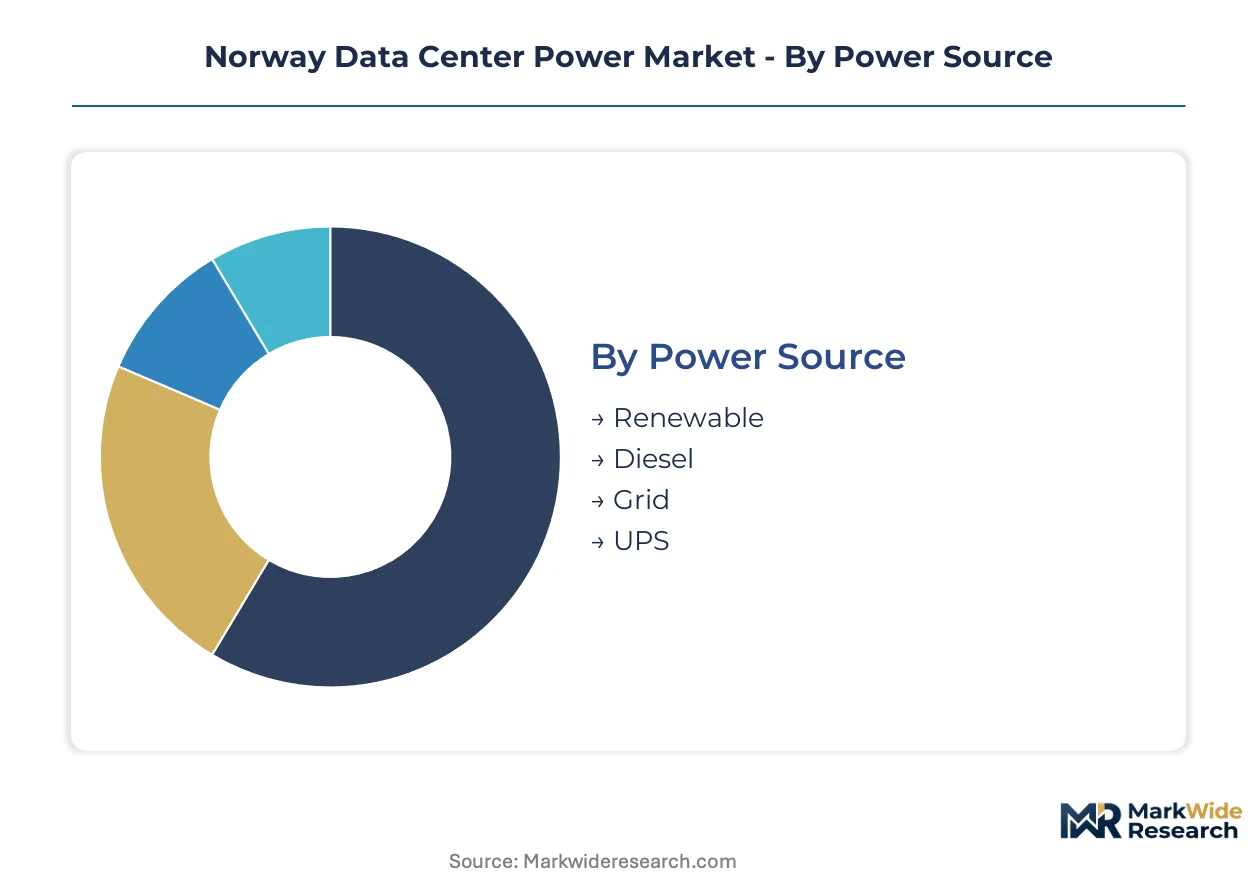
Norway's data center power market fragments across procurement philosophies that separate carbon-accounting hyperscalers from cost-optimized colocation tenants. Technical specifications diverge sharply between legacy air-cooled enterprise facilities and liquid-cooled AI training clusters driving Oslofjord corridor expansion.
Power Source:
Procurement priority distinguishes buyers optimizing for carbon intensity against those securing backup redundancy at minimum capital outlay.
- Renewable:Hydroelectric contracts with hourly generation telemetry satisfy EU Green Deal compliance and Norwegian Water Resources and Energy Directorate verification protocols. Hyperscalers in Drammen and Stavanger municipalities mandate firm renewable supply with real-time matching rather than annual certificate aggregation.
- UPS:Lithium iron phosphate battery systems with four-hour discharge capability are displacing diesel rotary architectures in hyperscale redundancy designs. Rack-level integration with 380V DC bus infrastructure eliminates conversion losses for AI training workloads.
- Grid:Direct medium-voltage connection through national transmission infrastructure serves colocation providers with blended renewable and imported Nordic power.
- Diesel:Backup generators face structural decline as battery duration improves and grid reliability reduces outage risk, though legacy enterprise facilities maintain rotating machine redundancy.
Volume sits with Grid connections; growth tilts toward Renewable firm contracts with hourly matching.
End User:
Contract scale and technical specification authority separate direct-procuring cloud operators from infrastructure-dependent tenants.
- Hyperscalers:Amazon Web Services and Meta Platforms unbundle electrical infrastructure from EPC contracts, specifying switchgear, UPS, and rack PDUs through approved manufacturer lists. Direct vendor relationships compress procurement cycles and capture efficiency guarantees.
- Colocation Providers:Multi-tenant facilities in Oslo and surrounding municipalities aggregate fragmented enterprise demand through standardized three-phase AC infrastructure, losing margin capture as hyperscalers bypass intermediary procurement.
- Enterprises:Single-tenant deployments in financial services and healthcare verticals prioritize BREEAM-NOR certification compliance over rack density optimization.
- Managed Service Providers:Regional cloud resellers and IT outsourcing firms occupy mid-scale facilities with hybrid redundancy requirements balancing capital constraints against uptime commitments.
Revenue concentrates with Hyperscalers; specification authority is expanding fastest among Colocation Providers adapting to direct-procurement pressure.
Energy Efficiency Standard:
Certification tier determines supplier qualification thresholds and documentation burden for electrical system commissioning.
- BREEAM:Norwegian adaptation mandates sustainability scoring for mechanical and electrical systems with documentation cycles that compress standard equipment procurement schedules. Oslo-region projects face timeline pressure from evolving threshold requirements.
- ISO 50001:Energy management certification embeds efficiency verification into hyperscaler supplier qualification programs, favoring vendors with integrated metering and analytics platforms.
- LEED:North American-originated standard sees limited adoption in Norwegian projects prioritizing EU-aligned certification frameworks.
- Energy Star:Equipment-level efficiency labeling guides UPS and power distribution unit selection without facility-wide certification requirements.
Adoption clusters around BREEAM-NOR; ISO 50001 is climbing fastest as hyperscalers embed energy management into procurement mandates.
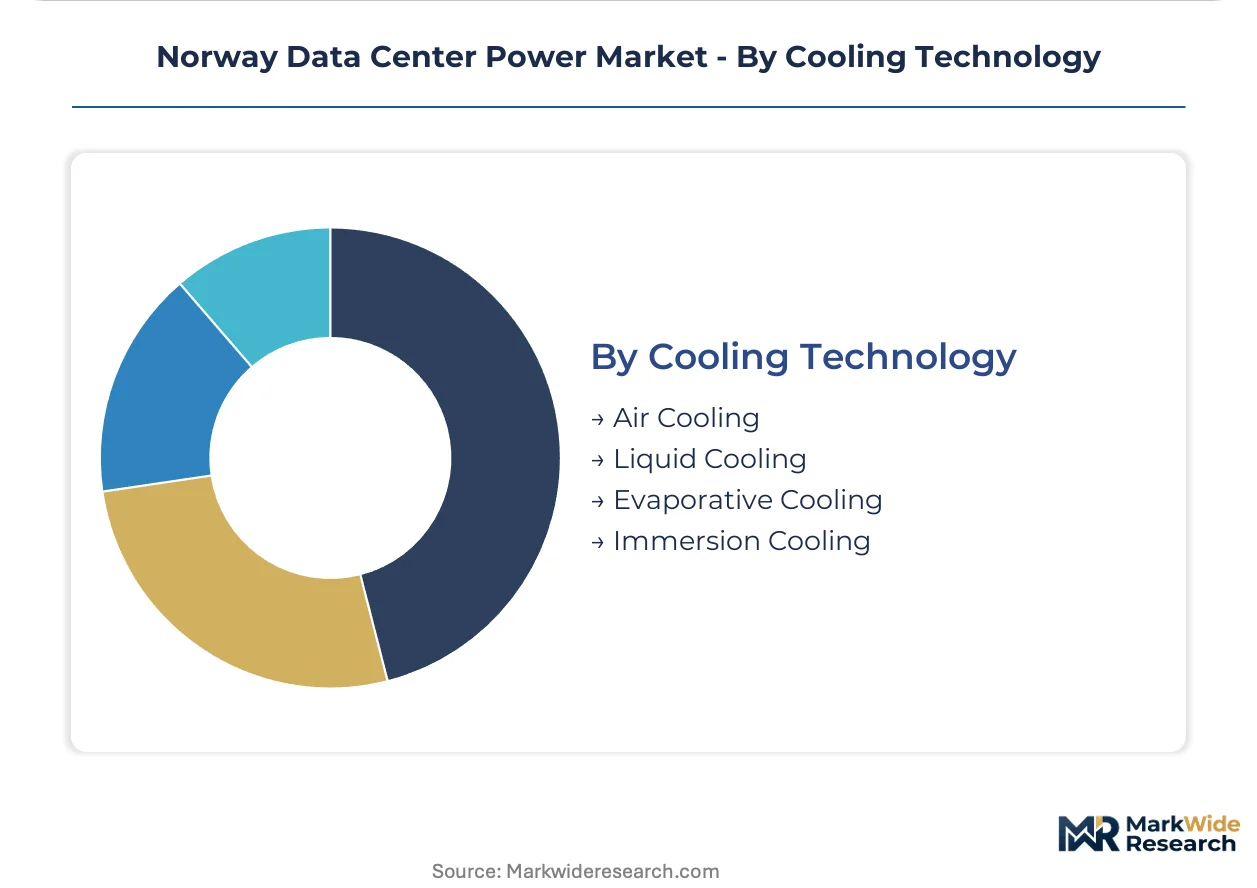
Cooling Technology:
Thermal load density dictates power distribution architecture and drives convergence between electrical and mechanical infrastructure specification.
- Liquid Cooling:Direct-to-chip manifolds paired with high-voltage DC bus architectures serve AI training clusters exceeding 50 kilowatts per rack. Microsoft and Google procurement teams specify thermal-electric integration for Oslofjord corridor facilities.
- Air Cooling:Traditional raised-floor configurations dominate legacy enterprise and colocation builds with rack densities below 15 kilowatts, preserving standard three-phase AC distribution.
- Immersion Cooling:Dielectric fluid submersion for highest-density compute nodes remains niche in Norway despite free air cooling advantages in Tromsø Arctic Circle positioning.
- Evaporative Cooling:Adiabatic systems supplement air handling in facilities exploiting Norwegian ambient temperature profiles for partial free cooling.
Deployment volume favors Air Cooling; specification momentum is shifting fastest toward Liquid Cooling as rack densities climb.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian hydroelectric reservoirs in Hardangervidda and Sognefjord catchments anchor the country's data center power infrastructure. Grid connection capacity concentrates in watersheds with surplus generation and submarine cable landing proximity.
Oslofjord Corridor
Hyperscale AI training clusters drive medium-voltage switchgear demand across Drammen, Lillestrøm, and Fredrikstad municipalities. The Norwegian Water Resources and Energy Directorate allocates transmission priority to facilities with hourly renewable matching contracts. NO-UK and Havfrue submarine cables position Oslo as a Nordic compute aggregation point with sub-10 millisecond London latency.
Stavanger Region
Offshore oil services electrical expertise migrates toward data center commissioning as North Sea exploration contracts decline. Rogaland county hosts stranded hydroelectric capacity from Lyse Kraft and Statkraft installations. Skagen Teknopark and Forus Industrial Park attract colocation builds exploiting existing 132kV substation infrastructure.
Tromsø Arctic Circle
Free air cooling potential and 100% renewable hydroelectric supply from Barduvann and Takvann reservoirs draw latency-tolerant batch computing. Troms Kraft grid connections face shorter queuing than southern zones. The Norwegian Polar Institute's computational infrastructure anchors a nascent high-performance computing cluster ecosystem.
Bergen Western Fjords
Statnett's 420kV transmission ring supplies surplus generation from Sogn og Fjordane hydroelectric complexes. Osterøy and Modalen municipalities market industrial zones with dedicated substation capacity. Skagerrak cable landing at Mongstad refinery site enables Danish and German market interconnection.
Trondheim Central Norway
NTNU research computing demand and Statkraft's Nea and Nidelv watershed generation create anchor tenancy for pilot liquid-cooled facilities. Trøndelag county's lower land costs attract secondary site selection for Oslo-region hyperscalers. Fosen Vind offshore wind integration tests grid balancing for variable renewable data center loads.
Norway Data Center Power Market Competitive Landscape
Global majors compete with regional champions across integrated power distribution portfolios, with European electrical infrastructure conglomerates holding technical specification authority in Norwegian hyperscale procurement. Market structure tilts toward consolidated supply for medium-voltage switchgear and uninterruptible power systems, while rack-level power distribution remains contested among specialized vendors. Three archetypes dominate: integrated electrical infrastructure conglomerates, power quality and conditioning specialists, and diesel backup generator manufacturers facing structural displacement. Competitive moves center on direct contracting relationships with hyperscalers and liquid cooling-integrated product development.
Among integrated infrastructure suppliers, Schneider Electric SE and ABB Ltd. exemplify the conglomerate archetype with end-to-end substation-to-rack portfolios. Eaton Corporation occupies a position representing power quality specialization, particularly in battery energy storage redundancy architectures. These three anchors demonstrate how vendor qualification for hyperscale approved manufacturer lists has become the decisive competitive gate, displacing traditional engineering-procurement-construction intermediary relationships across the Oslofjord corridor.
| Leading Market Players |
|---|
| Schneider Electric SE |
| ABB Ltd. |
| Eaton Corporation |
| Cisco Systems Inc. |
| Fujitsu Limited |
| Vertiv |
| Delta Electronics |
| Cummins |
| Caterpillar |
| Others |
Pricing and Supply Chain Analysis
Certification-tier divergence between BREEAM-NOR verified installations and standard electrical infrastructure manifests in both procurement premiums and supplier qualification pathways. Hyperscale direct-contracting patterns compress intermediary margins while elevating integrated vendors with real-time carbon accounting telemetry.
Pricing Analysis
Warranty and commissioning-service bundling separates premium-tier suppliers from commodity switchgear vendors competing on unit cost alone. Project-based contracting dominates medium-voltage infrastructure, with price differentiation driven by ISO 50001 certification status and four-hour battery discharge guarantees. Pricing pressure stems from copper and rare earth magnet cost volatility eroding fixed-price contract margins. Colocation providers exhibit highest price sensitivity as hyperscaler bypassing eliminates infrastructure markup capture.
Supply Chain Analysis
Regional distribution centers in Germany and the Netherlands anchor European electrical component warehousing for Norwegian project sites. Transformer core materials draw from China and India, while lithium iron phosphate battery cells source primarily from South Korean and Chinese manufacturers. Single-source vulnerability in permanent magnet supply chains poses structural risk to UPS system delivery schedules. Distribution runs through Oslo-based logistics hubs serving the Drammen-Stavanger construction corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norwegian data center power infrastructure sits in a technology-transition phase as lithium iron phosphate battery systems displace diesel rotary architectures across redundancy designs.
For Market Incumbents: Lock in hyperscaler approved manufacturer list status through integrated liquid cooling-380V DC bus product development. Battery energy storage duration improvements threaten legacy diesel generator manufacturers with structural displacement; prioritize backward integration into lithium iron phosphate cell supply through long-term offtake agreements with Korean and Chinese producers. For New Entrants and Emerging Players: Capture stranded hydroelectric capacity in Tromsø Arctic Circle positioning for latency-tolerant batch computing workloads. Troms Kraft grid connections face shorter queuing than southern zones; target municipal industrial zone marketing in Osterøy and Modalen municipalities with dedicated substation capacity messaging. For Investors and Strategic Acquirers: Exit pathways concentrate in integrated electrical infrastructure conglomerates with end-to-end substation-to-rack portfolios and direct hyperscaler contracting relationships. Long-term viability favors vendors with thermal-electric convergence capabilities and hourly renewable matching certification infrastructure. Watch battery energy storage cost curves as the inflection indicator for diesel backup generator manufacturer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Integration | Microsoft and Google procurement teams specify thermal-electric convergence for AI training clusters exceeding 50 kilowatts per rack. |
| Hourly Renewable Matching Certification | Norwegian Water Resources and Energy Directorate verification protocols now require real-time generation telemetry rather than annual certificate aggregation. |
| Battery Energy Storage Scale-Up | Four-hour discharge lithium iron phosphate systems displace diesel rotary UPS in hyperscale redundancy architectures. |
| Direct Hyperscaler Contracting | Amazon Web Services and Meta Platforms unbundle electrical infrastructure from EPC contracts, specifying components through approved manufacturer lists. |
| Arctic Circle Site Development | Tromsø positioning exploits free air cooling and stranded Barduvann hydroelectric capacity for latency-tolerant workloads. |
Research Methodology
Multi-period observation of grid connection queuing durations, hourly renewable certificate pricing, and hyperscaler capex allocation patterns anchored the trend analysis, supplemented by interviews with data center engineering directors, medium-voltage switchgear procurement leads, EPC contractors, and Norwegian Water Resources and Energy Directorate planning officers. Secondary validation drew from Statnett transmission data, NVE capacity allocation records, EU Green Deal compliance documentation, and hyperscaler sustainability disclosures. Bottom-up facility-level capacity tracking and top-down national grid load forecasts enabled triangulation.
Segment-weighting across power source, end user, energy efficiency standard, and cooling technology dimensions informed the analytical framework. Modeled segmentation captured renewable contract structures against grid-connected and backup-redundant configurations; hyperscaler direct-procuring cloud operators against colocation intermediaries; BREEAM-NOR and ISO 50001 certification tiers; and liquid-cooled AI clusters against air-cooled legacy facilities. CAGRs were derived from facility pipeline tracking and power infrastructure spend-per-megawatt estimates across the projection horizon. Forecast inputs incorporated battery energy storage cost decline curves and submarine cable landing station expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to rare earth supply chain disruptions and EU carbon border adjustment mechanism enforcement intensity. Forecasts reflect documented assumptions regarding grid reliability trends and battery duration improvement trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Global Data Colocation Market
Data Center Infrastructure
Denmark Data Center Market
Data Center Infrastructure
Beijing Data Center Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Ireland Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Physical Security Market
Data Center Infrastructure
Taiwan Data Center Server Market
Data Center Infrastructure
North America Green Data Center Market
Data Center Infrastructure
North America Data Center Construction Market
Data Center Infrastructure
Next Generation Data Center Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Switzerland Data Center Power Market
Data Center Infrastructure
Data Center Direct-to-Chip Coolant Fluids Market
Data Center Infrastructure
London Data Center Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Spain Data Center Rack Market