
 Japan Data Center Rack Market | 2026-2036
Japan Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Data Center Rack Market Insights
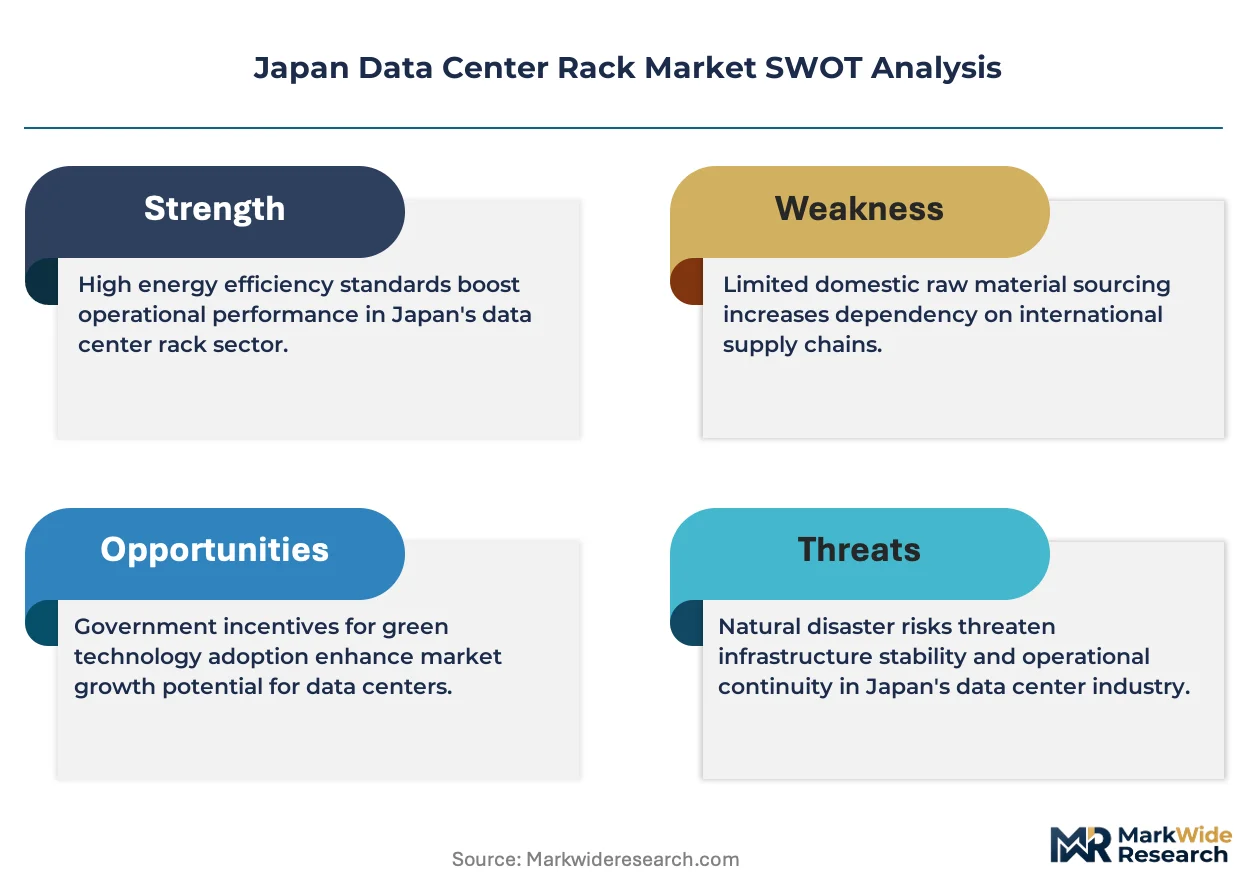
The Japan data center rack market is recalibrating around a widening split between premium liquid-cooled enclosures and standard air-cooled commodity units. Schneider Electric SE leverages its integrated power and cooling portfolio to dominate high-density deployments for domestic cloud operators. Fujitsu Limited anchors its position through deep vertical integration into server manufacturing and custom rack integration for enterprise clients. Nitto Kogyo Corporation specializes in precision steel fabrication, sustaining long-term supply relationships with telecommunications carriers building edge facilities across Japan.
Data center racks are standardized structural frames designed to house servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications for equipment mounting width and 600mm or 800mm external widths for aisle compatibility. Steel remains the dominant material due to its load-bearing capacity and electromagnetic shielding properties, though aluminum gains traction in weight-sensitive edge deployments. Open frame configurations lead volume for hyperscale builds where unrestricted airflow and cable access reduce cooling overhead, while enclosed racks command margin premiums from financial services and government end users requiring physical security compliance. Co-location racks represent the fastest-growing product type as operators standardize multi-tenant cabinet configurations to accelerate lease-up timelines.
METI enforces energy efficiency standards under the Act on Rationalizing Energy Use, directly shaping rack-level power distribution and thermal management requirements for new data center construction. JIS standards govern structural load ratings and seismic resistance, creating compliance barriers for imported rack systems lacking Japan-specific certification. PMDA oversight of medical data hosting adds sector-specific physical security mandates that filter into rack specification requirements for healthcare cloud deployments. Stakeholders must monitor how METI's carbon neutrality roadmaps recast cooling architecture decisions and whether domestic steel supply constraints alter material sourcing strategies for rack manufacturers serving the Japanese market.
Market Dynamics
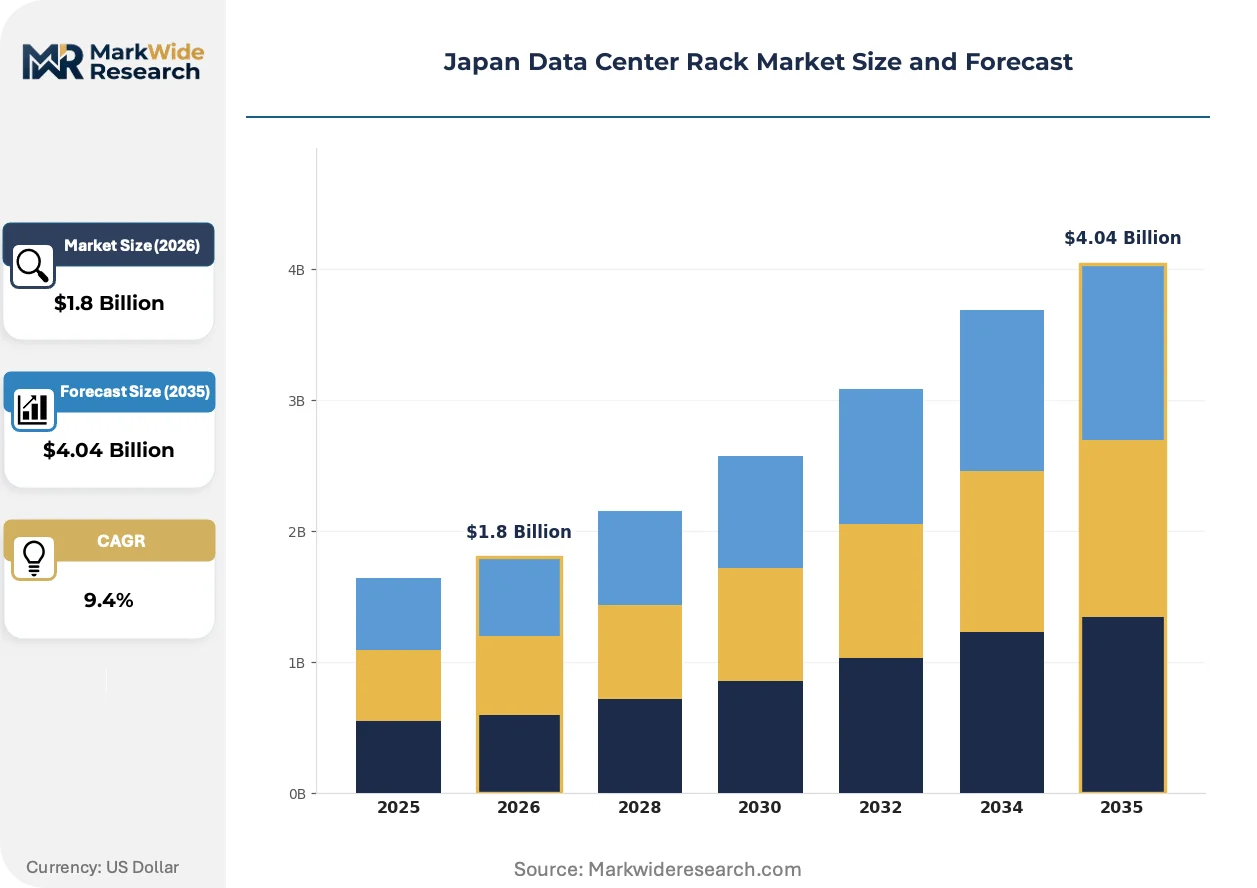
The Japan data center rack market pivots on METI's Green Transformation mandate, which compresses thermal design cycles and forces rack manufacturers to integrate liquid-cooling compatibility into standard enclosure specifications ahead of hyperscale deployment timelines.
Growth Catalysts
- Hyperscale cloud expansion:Domestic cloud operators are accelerating rack procurement in Tokyo and Osaka metropolitan zones to support generative AI training clusters and inference nodes.
- METI energy efficiency standards:The Act on Rationalizing Energy Use mandates rack-level power distribution monitoring, creating pull-through demand for intelligent PDUs and thermal sensors.
- Edge facility buildout:Telecommunications carriers are deploying standardized multi-tenant cabinets across regional prefectures to support 5G latency requirements and local data residency.
Market Restraints
- Domestic steel supply concentration:Specialty cold-rolled steel for seismic-rated frames depends on a concentrated supplier base in eastern Japan, exposing lead times to mill capacity constraints.
- JIS certification barriers:Imported rack systems face structural load testing and seismic resistance validation requirements that extend qualification timelines by six to twelve months.
- Liquid-cooling retrofit complexity:Existing air-cooled facilities require extensive infrastructure reconfiguration to accommodate direct-to-chip cooling manifolds, dampening upgrade velocity.
Strategic Opportunities
- Hokkaido renewable-powered clusters:Cooler ambient temperatures and geothermal energy availability position northern prefectures for sustainable hyperscale campus development with reduced mechanical cooling loads.
- Healthcare cloud physical security:PMDA oversight of medical data hosting creates demand for biometric-access enclosed racks with audit-trail capabilities in hospital and pharmaceutical deployments.
- Aluminum edge enclosures:Weight-sensitive distributed sites in mountainous terrain favor aluminum-frame racks that reduce transport and installation labor requirements.
Industry Challenges
- Thermal engineering talent scarcity:Liquid-cooling system design and computational fluid dynamics modeling skills are concentrated among a limited pool of specialists serving domestic server manufacturers.
- Multi-standard integration complexity:Rack suppliers must simultaneously support EIA-310-D, JIS seismic, and METI energy reporting protocols without fragmenting product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Data Center Rack Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame, Enclosed Rack, Wall-Mounted Rack, Co-location Rack Material: Steel, Aluminum, Plastic, Composite Capacity: 1U, 2U, 3U, 4U End User: Telecommunications, Cloud Providers, Enterprises, Internet Service Providers |
| Companies Covered | Black Box Corporation, nVent Electric PLC, Eaton Corporation, Hewlett Packard Enterprise, Dell Inc., Schneider Electric SE, Nitto Kogyo Corporation, Fujitsu Limited, Rittal GMBH & Co.KG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Data Center Rack Market Trends and Innovations
Liquid-cooling integration is reshaping enclosure architecture as power densities exceed air-cooling thresholds. Rack manufacturers are repositioning thermal management from facility infrastructure to cabinet-level responsibility.
Direct-to-chip liquid cooling is electrifying rack specification conversations between hyperscale operators and enclosure suppliers. Domestic cloud providers now require factory-installed coolant distribution units and blind-mate quick disconnects as standard features. This capability compression is forcing air-cooled specialists to license thermal engineering IP or exit high-density segments entirely.
METI's carbon neutrality roadmaps are tightening energy efficiency verification requirements for new data center construction. Rack-level power monitoring and thermal telemetry must now feed directly into facility-wide energy management systems. Financial services and government end users are prioritizing suppliers with demonstrated compliance documentation to accelerate permitting timelines.
Co-location operators are unbundling rack procurement from facility lease agreements. Enterprise tenants increasingly specify and source cabinets independently, then contract for space and power separately. This disintermediation is most visible in Tokyo's Otemachi and Marunouchi districts where multinational corporations demand brand-standardized configurations across global footprints.
Japan Data Center Rack Market Segmentation
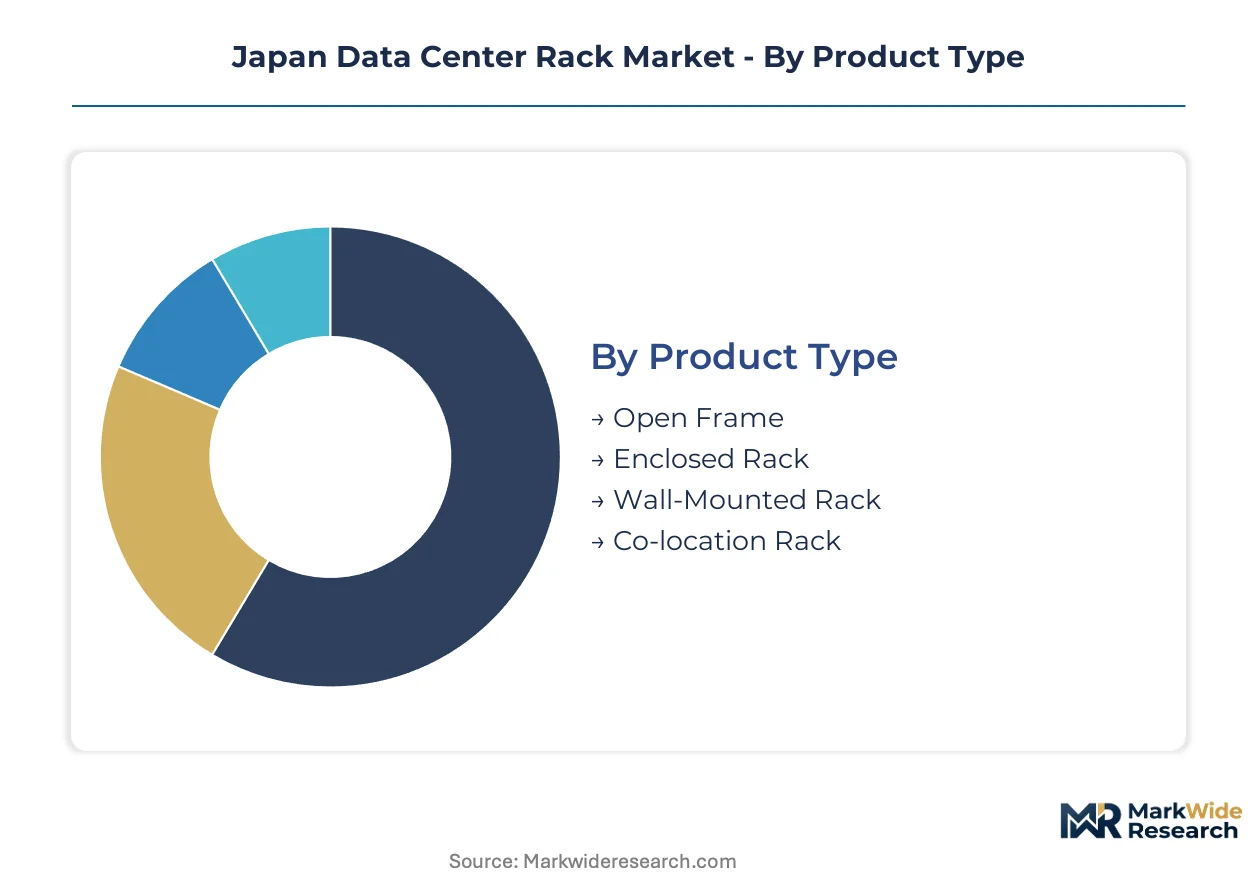
Rack segmentation in Japan reflects divergent certification burdens across deployment contexts. METI energy standards and JIS seismic ratings filter product eligibility differently for hyperscale campuses versus edge facilities, forcing manufacturers to maintain parallel qualification tracks.
Product Type:
JIS structural load testing applies unevenly across enclosure formats, with seismic-rated frames requiring six-to-twelve-month validation cycles that advantage domestic fabricators.
- Open Frame:Unrestricted airflow configurations dominate hyperscale builds in Tokyo and Osaka metropolitan zones. Cloud operators prioritize cable access and cooling overhead reduction over physical security, accepting open structures that simplify thermal management for generative AI clusters.
- Co-location Rack:Standardized multi-tenant cabinets accelerate lease-up timelines for facility operators. METI energy reporting mandates drive integration of intelligent PDUs and thermal sensors as baseline features rather than options.
- Enclosed Rack:Physical security compliance commands margin premiums from financial services and government end users. Biometric access and audit-trail capabilities satisfy PMDA oversight requirements for medical data hosting.
- Wall-Mounted Rack:Compact form factors serve distributed edge sites with space constraints. Regional telecommunications carriers deploy these across prefectures for 5G latency-sensitive applications.
Leading the category by volume: Open Frame. Growing fastest: Co-location Rack.
Material:
Cost tiers separate commodity steel from premium lightweight alternatives, with transport economics and installation labor driving material selection at distributed sites.
- Steel:Cold-rolled specialty grades provide load-bearing capacity and electromagnetic shielding for seismic-rated frames. Eastern Japanese mill concentration exposes lead times to capacity constraints.
- Aluminum:Weight-sensitive edge deployments in mountainous terrain favor aluminum-frame racks that reduce transport and installation labor requirements. Cooler ambient temperatures in Hokkaido renewable-powered clusters extend aluminum's viability through reduced thermal load stress.
- Plastic:Limited to non-structural components and cable management accessories. JIS load rating requirements exclude plastic from primary frame applications.
- Composite:Emerging formulations target specific electromagnetic interference shielding applications. Healthcare cloud deployments with PMDA physical security mandates drive early adoption for specialized enclosures.
Highest volume concentration: Steel. Steepest expansion trajectory: Aluminum.
Capacity:
Application requirements dictate unit specification, with power density trends compressing rack-level decisions upward through the capacity spectrum.
- 4U:High-density enclosures accommodate liquid-cooling manifolds and direct-to-chip cooling infrastructure. Hyperscale operators in Tokyo metropolitan zones require factory-installed coolant distribution units as standard.
- 2U:Standard server form factor dominates enterprise procurement for general compute workloads. Cloud providers balance density against thermal management complexity in mixed-deployment facilities.
- 1U:Slim configurations persist in legacy installations and specific networking equipment applications. Edge facility buildout favors denser alternatives where power and cooling permit.
- 3U:Intermediate capacity serves storage-optimized and GPU-accelerated workloads. Financial services enterprises in Otemachi and Marunouchi districts specify these for hybrid compute-storage nodes.
Dominant by deployment count: 2U. Gaining share fastest: 4U.
End User:
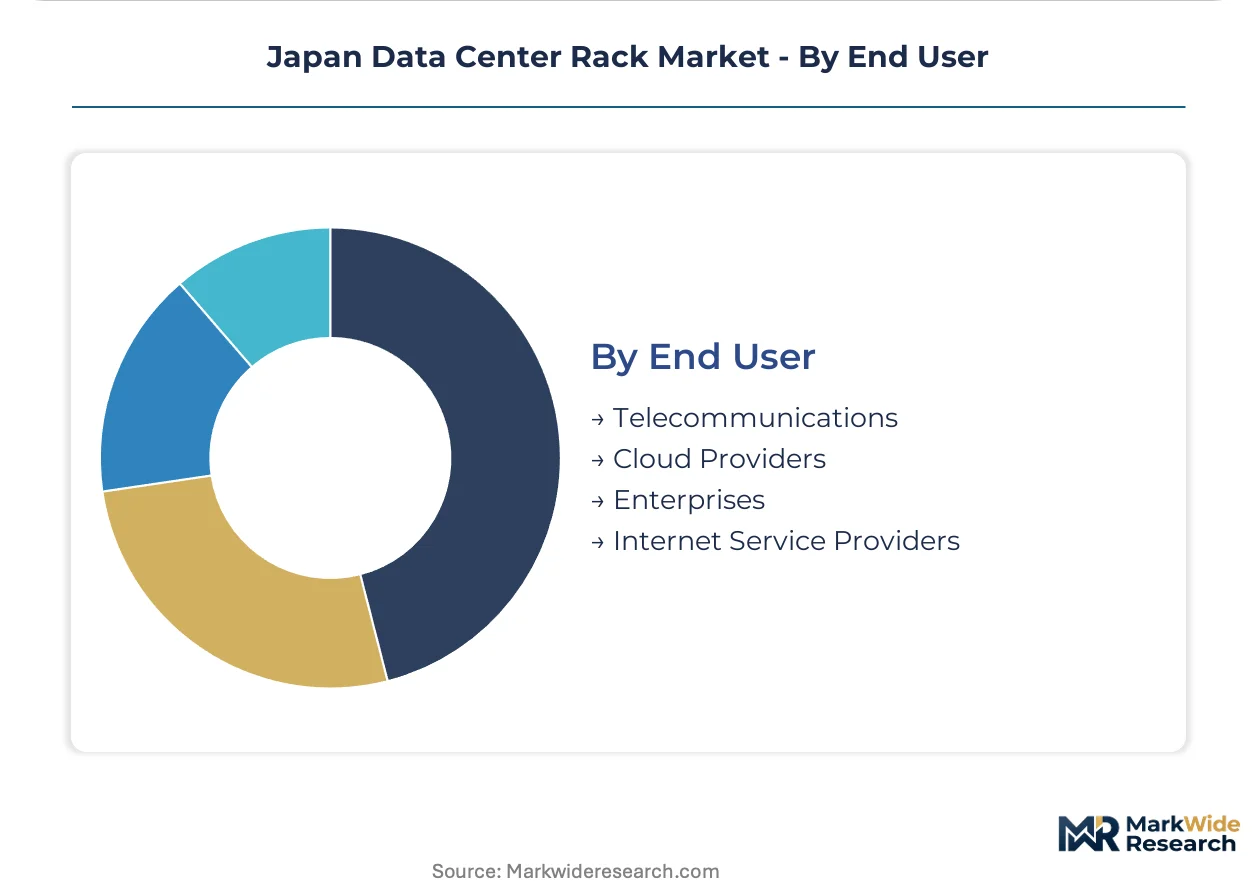
Customer type determines procurement patterns, with cloud providers disaggregating rack specification from facility lease agreements while telecommunications carriers standardize across regional footprints.
- Cloud Providers:Hyperscale operators drive liquid-cooling integration requirements and factory-installed thermal management features. Domestic operators accelerate rack procurement across Kanto region campuses for generative AI infrastructure.
- Telecommunications:Carriers deploy standardized multi-tenant cabinets across prefectures to support 5G latency requirements and local data residency mandates. Edge facility standardization reduces supply chain complexity.
- Enterprises:Multinational corporations demand brand-standardized configurations across global footprints. Independent rack procurement separate from space and power contracting is most visible in Tokyo's central business districts.
- Internet Service Providers:Regional network operators prioritize cost-optimized enclosures for content delivery and peering infrastructure. JIS certification barriers favor established domestic supplier relationships.
Largest procurement volume: Cloud Providers. Expanding most quickly: Telecommunications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tokyo anchors Japan's data center rack demand through hyperscale cloud expansion across the Kanto metropolitan corridor. METI's Green Transformation initiative compresses thermal design cycles while JIS seismic standards filter product eligibility for domestic deployment.
Kanto/Tokyo
Hyperscale operators accelerate rack procurement for generative AI training clusters and inference nodes. METI's Act on Rationalizing Energy Use mandates rack-level power distribution monitoring. The Otemachi and Marunouchi districts concentrate co-location facilities where multinational corporations demand brand-standardized configurations.
Kansai/Osaka
Cloud providers expand rack deployments to support regional latency requirements for financial services workloads. JIS structural load testing requirements advantage domestic fabricators with established certification relationships. The Osaka metropolitan zone hosts accelerating hyperscale facility construction with liquid-cooling integration specifications.
Chubu/Nagoya
Manufacturing enterprises drive demand for custom rack integration tied to enterprise server deployments. PMDA oversight of medical data hosting creates pull-through for biometric-access enclosed racks with audit-trail capabilities. The Nagoya industrial corridor concentrates precision steel fabrication capacity serving telecommunications carrier edge builds.
Hokkaido
Cooler ambient temperatures and geothermal energy availability position northern prefectures for sustainable hyperscale campus development. METI carbon neutrality roadmaps recast cooling architecture decisions toward reduced mechanical cooling loads. Renewable-powered clusters here favor aluminum-frame racks that reduce transport and installation labor requirements.
Kyushu
Regional telecommunications carriers deploy standardized multi-tenant cabinets across prefectures to support 5G latency requirements. JIS certification barriers for imported systems extend qualification timelines, reinforcing domestic supplier relationships. Fukuoka metropolitan area anchors edge facility buildout for local data residency mandates.
Japan Data Center Rack Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across Japan's data center rack market. Domestic steel fabricators with JIS certification capabilities face specialized precision manufacturers serving telecommunications edge deployments. Three archetypes dominate: integrated power-cooling portfolio suppliers, vertical server-to-rack specialists, and precision fabrication contractors. Competitive moves concentrate on liquid-cooling technology licensing and seismic-rated frame certification acceleration.
Within the integrated infrastructure tier, Schneider Electric SE represents the power-cooling convergence archetype. Among domestic fabricators, Nitto Kogyo Corporation exemplifies precision steel specialists serving telecommunications carriers. Fujitsu Limited occupies a position bridging server manufacturing and custom rack integration for enterprise clients.
| Leading Market Players |
|---|
| Black Box Corporation |
| nVent Electric PLC |
| Eaton Corporation |
| Hewlett Packard Enterprise |
| Dell Inc. |
| Schneider Electric SE |
| Nitto Kogyo Corporation |
| Fujitsu Limited |
| Rittal GMBH & Co.KG |
| Others |
Pricing and Supply Chain Analysis
A pronounced bifurcation between JIS-certified seismic-rated frames and uncertified commodity imports shapes both margin structures and sourcing configurations across the Japan data center rack market. This certification ladder concentrates pricing power with domestic fabricators possessing established METI compliance documentation, while forcing hyperscale operators to absorb six-to-twelve-month qualification premiums for imported alternatives.
Pricing Analysis
Uptime guarantees and thermal performance thresholds anchor value-based pricing for liquid-cooled enclosures serving Tokyo hyperscale campuses. Three-tier pricing structure across premium, standard, and economy levels separates factory-installed coolant distribution units from air-cooled commodity frames and basic open-frame configurations. Cost compression in standard air-cooled segments is intensifying because telecommunications carriers are consolidating procurement volumes across regional prefectures. Cloud providers exhibit lowest price sensitivity due to density-driven total cost of ownership calculations, while regional internet service providers face acute margin pressure on rack-level procurement.
Supply Chain Analysis
Refurbishment flows for seismic-rated steel frames remain minimal given JIS recertification complexity, though edge deployment aluminum racks increasingly circulate through secondary channels. Cold-rolled specialty steel draws from eastern Japanese mill concentration, while aluminum extrusion feeds from South Korean and Chinese smelter capacity. Single-source vulnerability permeates the seismic-grade steel supplier base concentrated in Chubu prefecture. Distribution runs through direct OEM relationships for hyperscale contracts and telecommunications carrier framework agreements for standardized edge cabinets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic cold-rolled steel mill capacity constraints prop pricing premiums for JIS-certified seismic frames, creating a supply-constrained environment where qualification timelines function as de facto capacity allocation mechanisms.
For Market Incumbents: Anticipate liquid-cooling retrofit demand acceleration by pre-qualifying coolant distribution unit integration at factory level rather than field-installation stage. Accelerate JIS certification pipeline for aluminum-frame edge configurations before Hokkaido renewable cluster procurement waves materialize. METI energy reporting mandate expansion threatens margin compression for suppliers lacking intelligent PDU integration capabilities.
For New Entrants and Emerging Players: Factory-sealed liquid-cooling manifolds with blind-mate quick disconnects offer the most penetrable wedge for hyperscale procurement committees seeking to reduce field integration risk. Target wall-mounted rack specifications for mountainous terrain 5G edge sites where weight-sensitive aluminum configurations command transport cost premiums. Pursue co-location operator direct procurement relationships in Tokyo's Otemachi district where facility lease disintermediation is most advanced.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision fabrication specialists with established telecommunications carrier relationships and JIS certification infrastructure. Long-term viability hinges on thermal engineering talent acquisition and liquid-cooling IP licensing positions rather than commodity steel fabrication scale. Monitor METI carbon neutrality roadmap revisions for early signals of direct-to-chip cooling mandate acceleration that would reshape acquisition target valuation frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid-Cooling IP Licensing | Schneider Electric's integrated power-cooling portfolio demonstrates margin capture from thermal management convergence. |
| JIS Certification Acceleration | Nitto Kogyo's seismic-rated frame validation timelines create competitive moats against imported alternatives. |
| Aluminum Edge Enclosure Development | Hokkaido renewable cluster specifications favor lightweight frames reducing mountainous terrain installation labor. |
| Intelligent PDU Integration | METI Act on Rationalizing Energy Use mandates position power monitoring as baseline rather than optional feature. |
| Telecommunications Carrier Framework Agreements | Standardized multi-tenant cabinet procurement across prefectures locks in volume commitments for compliant suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with data center facility operators, rack procurement managers at cloud providers, telecommunications carrier infrastructure planners, and precision steel fabrication executives. METI energy efficiency disclosures, JIS certification registries, and hyperscaler capital expenditure reports provided demand-side validation. Bottom-up installation tracking across Tokyo, Osaka, and Nagoya metropolitan zones was triangulated against top-down steel consumption estimates from eastern Japanese mill reporting.
Granularity-level modeling proceeded at rack-type, material-grade, and end-user archetype dimensions across the projection horizon. Product-type segmentation captured open-frame, co-location, enclosed, and wall-mounted configurations. Capacity-tier splits reflected 1U through 4U specifications with liquid-cooling integration flags. CAGRs were derived from installation run-rate analysis and hyperscale deployment pipeline tracking. Power density trajectories from generative AI cluster specifications and METI carbon neutrality compliance timelines served as key forecast inputs.
Several conditions sit outside the modeled scope, including potential revisions to JIS seismic standards, abrupt steel tariff implementations, and breakthrough immersion-cooling adoption curves that could displace direct-to-chip architectures. Forecasts reflect assumptions regarding continued Kanto hyperscale concentration and stable METI regulatory enforcement intensity. Practitioners should monitor Hokkaido renewable cluster procurement announcements and telecommunications carrier 5G edge deployment cadence for early demand inflection signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Blade Server Market
Data Center Infrastructure
Data Center Modeling and Simulation Tools Market
Data Center Infrastructure
Australia Data Center Power Market
Data Center Infrastructure
South Korea Data Center Power Market
Data Center Infrastructure
United States Data Center Market
Data Center Infrastructure
Canada Data Center Server Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Global Data Center Structured Cabling Market
Data Center Infrastructure
South Korea Data Center Physical Security Market
Data Center Infrastructure
Vietnam Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
Hong Kong Data Center Market
Data Center Infrastructure
Data Center Life Cycle Services Market
Data Center Infrastructure
Data Center Colocation Market
Data Center Infrastructure
UAE Data Center Construction Market
Data Center Infrastructure
South America Data Center Rack Market