
 Streaming Server Software Market | 2026-2036
Streaming Server Software Market Size, Share, and Industry Trends Forecast 2026-2036
Streaming Server Software Market Analytics
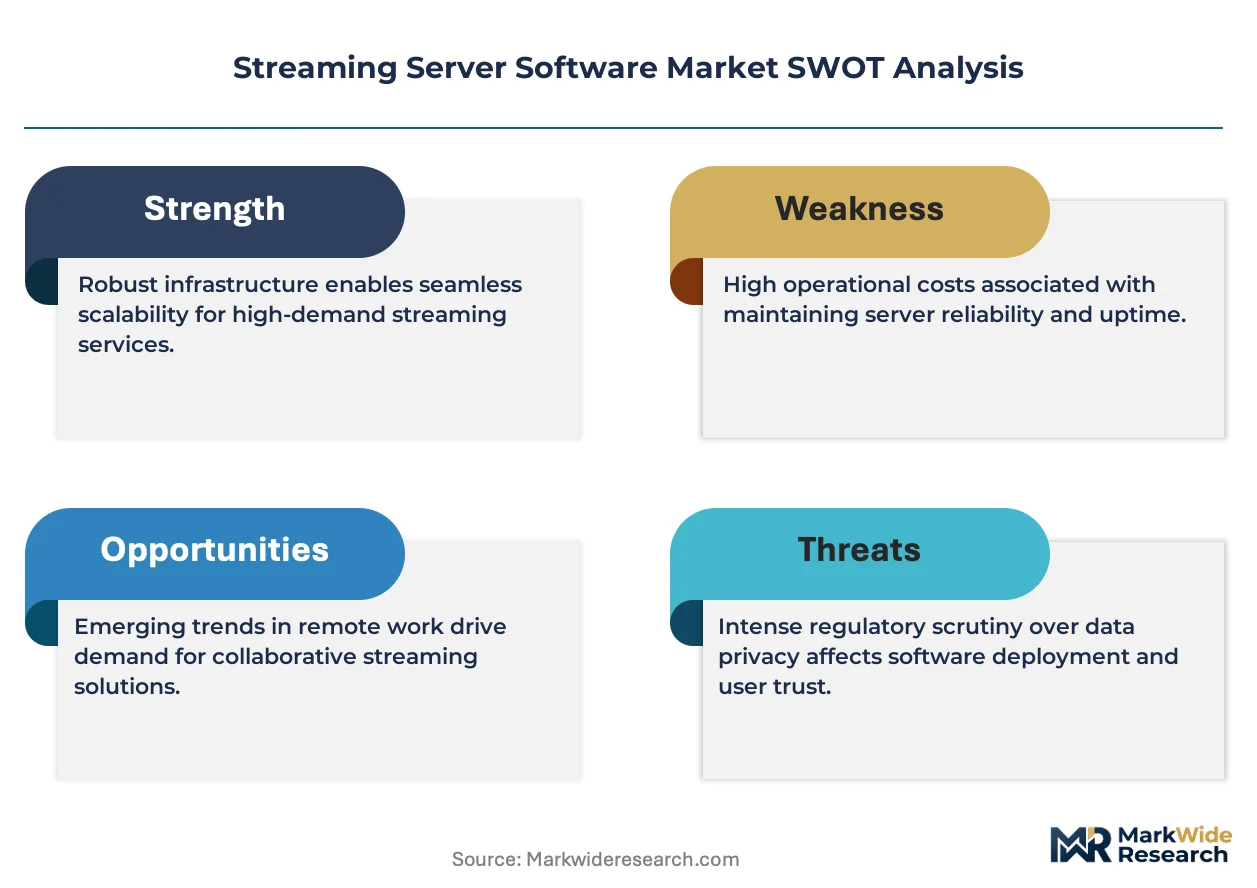
The EU AI Act is recalibrating the cost-of-entry calculus for streaming platforms processing algorithmic content recommendations in Europe. Brightcove Inc. leverages its cloud-native architecture to sustain compliance-ready deployments across multiple jurisdictions. Wowza Media Systems LLC anchors its position through specialized low-latency protocols for live event broadcasting. Akamai Technologies Inc. dominates edge delivery infrastructure, competing on geographic density rather than software licensing alone.
Streaming server software comprises applications that ingest, transcode, package, and distribute audio-video content across IP networks using protocols such as HLS, DASH, and WebRTC, typically operating at sub-500ms latency for interactive use cases. The technology serves broadcasters, enterprises, and platform operators requiring scalable, reliable content delivery to heterogeneous client devices. Cloud-based deployment leads in new installations as organizations abandon capital-intensive on-premises infrastructure, while live streaming services capture disproportionate growth versus video-on-demand as sports, gaming, and corporate communications prioritize real-time engagement. Edge computing deployment represents the fastest-expanding configuration, driven by 5G rollout and latency-sensitive interactive applications.
The Federal Communications Commission in the United States, the European Union's Digital Services Act coordination mechanisms, and India's Telecom Regulatory Authority collectively shape market access through net neutrality rulings, content moderation obligations, and data localization mandates. These frameworks compel vendors to architect region-specific compliance modules, raising R&D overhead but creating barriers against non-compliant entrants. Stakeholders must monitor evolving cross-border data transfer restrictions and emerging sovereign cloud requirements as these will determine which platform architectures achieve sustainable geographic expansion.
Market Dynamics
Live interactive streaming protocols are compressing latency thresholds below 100 milliseconds, forcing infrastructure vendors to rebuild encoding pipelines around edge-native architectures rather than centralized cloud processing.
Growth Catalysts
- 5G network densification:Telecom operators in Germany, India, and the United States are deploying millimeter-wave infrastructure that enables sub-50ms last-mile delivery. Broadcasters now provision concurrent 4K streams without buffering degradation.
- EU AI Act algorithmic transparency mandates:Content recommendation engines in Europe must document training data provenance and bias audit trails. Compliance tooling vendors capture new revenue attaching governance layers to existing streaming stacks.
- Esports wagering integration:Real-time odds synchronization requires frame-accurate stream synchronization. Platform operators in Nevada and Malta invest heavily in WebRTC low-latency extensions to support in-play betting overlays.
Market Restraints
- GPU compute cost volatility:AV1 and HEVC encoding workloads consume 40-60% more silicon per stream than H.264. Cloud transcoding bills fluctuate with semiconductor foundry capacity constraints in Taiwan.
- CDN supply concentration:Three infrastructure providers control 70% of edge POP density in North America. Negotiating leverage tilts toward landlords of submarine cable landing stations.
- Cross-border data localization:India's TRAI mandates domestic storage for subscriber viewing metadata. Foreign platforms must replicate entire analytics stacks inside sovereign cloud zones, duplicating fixed costs.
Strategic Opportunities
- Underpenetrated LATAM markets:Brazil and Mexico exhibit 34% annual growth in connected TV penetration. Local content aggregators seek white-label streaming server licensing rather than building proprietary stacks.
- Convergence of AI-generated content pipelines:Synthetic video creation tools from Runway and Pika Labs output raw footage requiring real-time compositing. Streaming infrastructure vendors can integrate rendering-as-a-service modules.
- Japan's METI immersive content subsidy program:Government vouchers cover 30% of 8K VR streaming infrastructure costs for cultural institutions. Museums and heritage sites represent uncaptured demand for spatial streaming protocols.
Industry Challenges
- Real-time systems engineering talent scarcity:Kernel-level optimization for DPDK packet processing and kernel-bypass networking requires specialized skillsets concentrated at semiconductor firms and high-frequency trading desks.
- Multi-jurisdiction certification timelines:Common Criteria EAL4+ evaluation for government-grade streaming encryption averages 18-24 months. Product roadmaps must freeze architectures well ahead of revenue recognition.
- Legacy multicast integration friction:Enterprise video distribution networks built on RTP/RTSP protocols resist migration to HTTP-based adaptive bitrate standards. Hybrid gateway products demand sustained engineering investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Streaming Server Software Market |
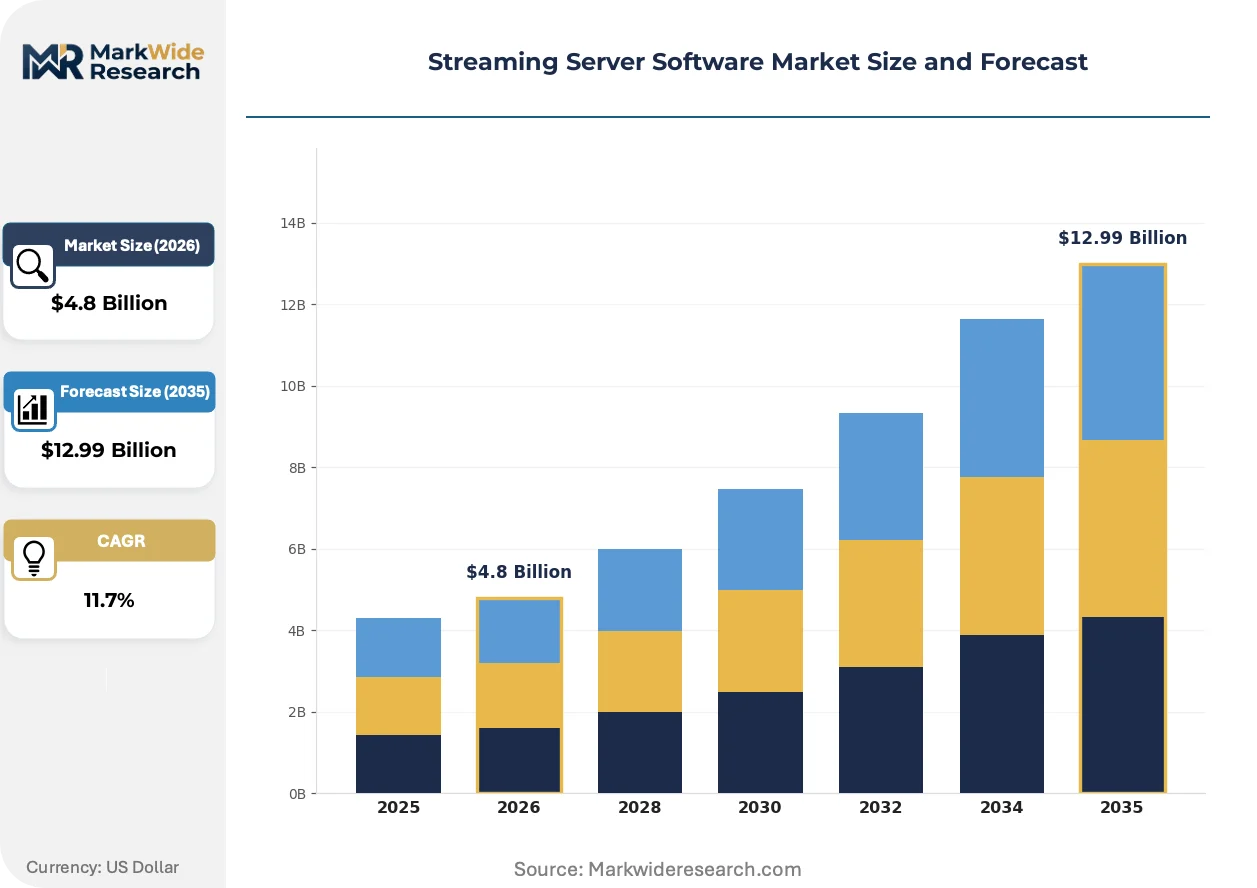
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing Service Type: Live Streaming, Video On Demand, Transcoding, Packaging End User: Media Companies, Enterprises, Educational Institutions, Content Creators Feature: Adaptive Bitrate Streaming, DRM, Low Latency, Cross-Platform Support |
| Companies Covered | IBM Corporation, Brightcove Inc., Kaltura Inc., Wowza Media Systems LLC, Vimeo.com, Inc., Haivision Systems Inc., Akamai Technologies Inc., Edgio, Dacast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Streaming Server Software Market Evolving Landscape
Protocol fragmentation is forcing buyers to consolidate previously separate encoding, packaging, and origin server functions into unified software-defined platforms rather than best-of-breed point solutions.
WebRTC is expanding into broadcast-quality contribution workflows from its origins in browser-based video conferencing. Regional sports networks in Spain and South Korea now ingest camera feeds directly through WHIP protocol ingest points. This compression of the signal chain eliminates hardware encoder farms and collapses production timelines from hours to minutes.
The EU Digital Services Act's systemic risk assessment obligations require platforms above 45 million monthly users to audit recommendation algorithm amplification patterns. Video-on-demand services operating across France, Germany, and Poland must deploy explainability dashboards and human override mechanisms. Mid-tier platforms below the threshold accelerate European expansion to capture audience before compliance costs escalate.
Enterprise procurement teams now unbundle professional services from perpetual software licenses, purchasing pure SaaS streaming infrastructure on consumption-based meters. Media technology buyers in the United Kingdom and Netherlands negotiate annual commit contracts with burst pricing for live event spikes. This shift pressures vendors to expose granular telemetry APIs that feed customer FinOps dashboards.
Streaming Server Software Market Segmentation
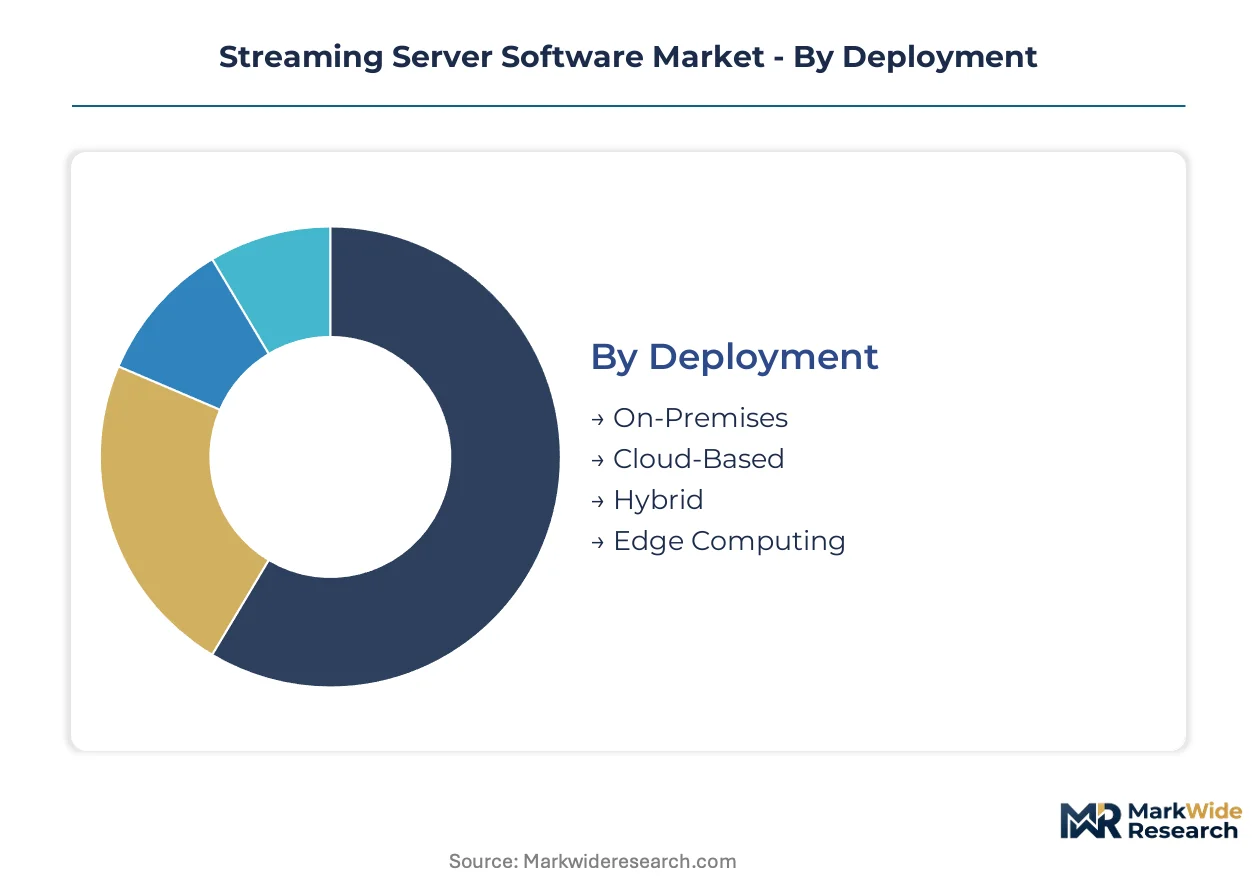
Streaming server software buyers fragment sharply across infrastructure maturity and regulatory exposure. Deployment choices determine latency performance and compliance architecture, while service type selection separates real-time engagement platforms from archival distribution models.
Deployment:
Cost tier separates capital-rich broadcasters seeking control from agile entrants prioritizing operational flexibility.
- Cloud-Based:Fully managed infrastructure eliminates data center overhead and auto-scales concurrent stream capacity. Demand concentrates among mid-tier OTT platforms in Germany and India avoiding TRAI and GDPR infrastructure mandates through vendor-certified compliance.
- Edge Computing:Distributed micro-data centers position encoding within 50 kilometers of viewers, slashing last-mile latency below 100 milliseconds. 5G millimeter-wave rollouts in the United States and South Korea drive disproportionate investment for esports and interactive wagering applications.
- On-Premises:Dedicated hardware serving sovereign cloud requirements and classified government feeds.
- Hybrid:Split architectures keeping sensitive content local while burst traffic overflows to public cloud.
Volume sits with Cloud-Based deployments; growth tilts toward Edge Computing configurations.
Service Type:
Application urgency distinguishes synchronous live workflows from asynchronous archive monetization.
- Live Streaming:Real-time ingest, transcode, and distribution demanding sub-500ms end-to-end latency. Sports rights holders in Spain and South Korea invest heavily after WebRTC WHIP protocol eliminated hardware encoder dependencies.
- Transcoding:Format conversion between H.264, HEVC, and AV1 codecs consuming GPU-intensive compute cycles. Cloud transcoding bills fluctuate with Taiwan semiconductor foundry capacity, pushing enterprises toward reserved instance contracts.
- Video On Demand:Pre-positioned content libraries served through adaptive bitrate manifests.
- Packaging:Containerization into HLS and DASH segments with encryption and subtitle injection.
Live Streaming commands current infrastructure spend; Transcoding services expand most quickly as multi-codec workflows proliferate.
End User:
Customer type governs procurement complexity, with media buyers negotiating enterprise licenses and educational adopters seeking grant-funded deployments.
- Media Companies:Broadcasters and OTT platforms requiring 99.999% availability SLA and multi-CDN failover. European operators above 45 million monthly users face EU Digital Services Act systemic risk audits, accelerating compliance tooling attachment.
- Enterprises:Corporate communications and investor relations streaming with SSO integration and granular access controls. Financial services firms in London and Singapore prioritize DRM modules for earnings call confidentiality.
- Educational Institutions:Lecture capture and remote learning platforms with limited IT staffing.
- Content Creators:Individual streamers and influencer networks on revenue-share SaaS tiers.
Media Companies anchor platform revenue; Educational Institutions represent the steepest expansion trajectory as hybrid learning normalizes.
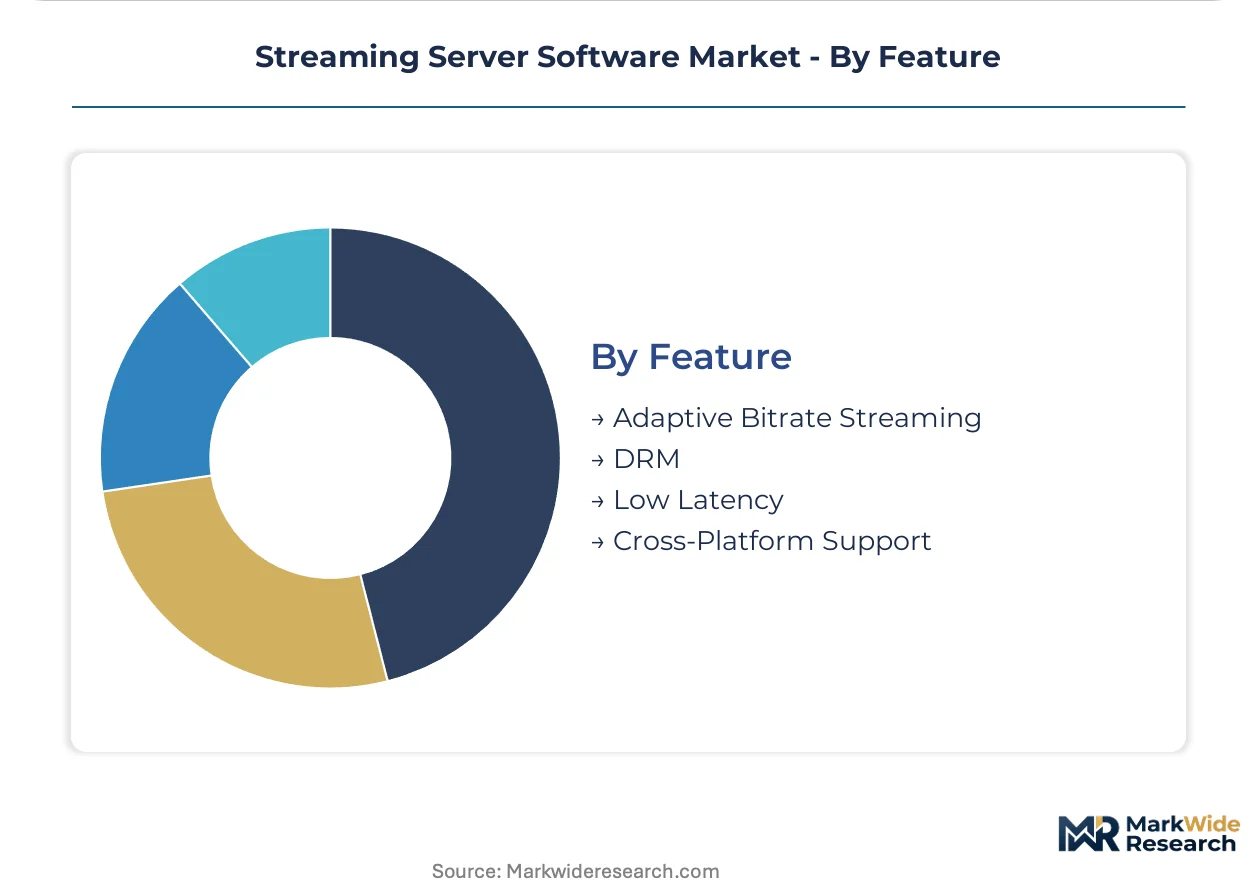
Feature:
Margin structure separates commodity transport from premium value-add modules commanding annual subscription premiums.
- Low Latency:WebRTC and SRT protocol implementations achieving sub-100 millisecond glass-to-glass performance. Esports wagering platforms in Nevada and Malta require frame-accurate synchronization for in-play odds integrity.
- DRM:Multi-DRM integrations with Widevine, PlayReady, and FairPlay for premium content protection. Hollywood studio licensing mandates in the United States and Japan drive mandatory deployment across tier-one platforms.
- Adaptive Bitrate Streaming:Dynamic quality adjustment based on available bandwidth.
- Cross-Platform Support:Unified playback across iOS, Android, smart TV, and browser endpoints.
DRM features dominate current attach rates; Low Latency modules gain share fastest as interactive applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Hyderabad and Bengaluru concentrate streaming infrastructure R&D through India's Software Technology Parks of India scheme, drawing capital from broadcasters seeking compliant data localization under TRAI mandates.
United States
FCC net neutrality rulings and Nevada gaming commission wagering requirements shape platform architecture decisions. Esports betting synchronization demands frame-accurate latency from Las Vegas server clusters. Seattle and Los Angeles anchor edge computing deployments for Pacific Rim content distribution.
Germany
EU AI Act algorithmic transparency mandates force documentation of training data provenance for recommendation engines. Berlin and Munich host compliance tooling development centers serving broadcasters above 45 million monthly users. Millimeter-wave 5G densification enables sub-50ms delivery for industrial AR applications.
India
TRAI data localization mandates require domestic storage of subscriber viewing metadata. Mumbai and Bengaluru replicate entire analytics stacks inside sovereign cloud zones. PLI scheme incentives attract hyperscaler edge POP investments for regional language content delivery.
South Korea
WebRTC WHIP protocol adoption eliminates hardware encoder dependencies for regional sports networks. Seoul government immersive content subsidies cover 30% of 8K VR streaming infrastructure costs. Busan-Ulsan corridor concentrates low-latency encoding facilities for esports wagering platforms.
Japan
METI immersive content subsidy vouchers support 8K VR streaming infrastructure for cultural institutions. Tokyo and Osaka metropolitan areas deploy spatial streaming protocols for museum digitization projects. Kernel-level optimization talent concentrates at semiconductor firms serving broadcast-quality contribution workflows.
Streaming Server Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the streaming server software landscape. Cloud infrastructure giants leverage geographic density of edge POPs to bundle delivery with software licensing. Pure-play vendors anchor positions through protocol specialization and low-latency optimization. The vendor base organizes around three strategic archetypes: hyperscale platform operators, vertical-specific solution providers, and open-source commercialization specialists. Competitive moves concentrate on M&A for encoding technology assets and strategic partnerships for 5G edge co-location.
Within the cloud-native tier, Brightcove Inc. and Wowza Media Systems LLC exemplify divergent positioning strategies. Brightcove occupies a compliance-ready deployment position across multiple jurisdictions through managed infrastructure offerings. Wowza anchors a specialized protocol focus for live event broadcasting applications. Akamai Technologies Inc. sits within the infrastructure-dominant archetype, competing on edge density rather than pure software licensing. These three entities represent the spectrum from application-layer specialization to transport-layer control in streaming architecture decisions.
| Leading Market Players |
|---|
| IBM Corporation |
| Brightcove Inc. |
| Kaltura Inc. |
| Wowza Media Systems LLC |
| Vimeo.com, Inc. |
| Haivision Systems Inc. |
| Akamai Technologies Inc. |
| Edgio |
| Dacast |
| Others |
Value Network & Pricing Analysis
GPU compute pricing indices on major cloud platforms cascade through streaming infrastructure procurement, compressing margins for transcoding-heavy deployments while amplifying pricing power for vendors with reserved silicon allocations. Buyers face tiered cost structures where latency-critical workloads command substantial premiums over standard video-on-demand processing.
Pricing Analysis
Short lead-time provisioning carries 40-60% premiums over reserved instance contracts as broadcasters scramble for concurrent 4K streaming capacity during live sports windows. SaaS-tiered consumption models dominate new installations, with pricing stratifying across enterprise, mid-market, and self-service tiers based on SLA guarantees and support bundling. Cost compression in the mid-tier is intensifying because hyperscalers bundle encoding with egress bandwidth at below-standalone rates. Educational institutions exhibit highest price sensitivity due to grant-funded procurement cycles, while wagering platforms in regulated jurisdictions show least sensitivity given compliance-driven vendor lock-in.
Supply Chain Analysis
Common Criteria EAL4+ certification gates access to government-grade streaming contracts, filtering vendor pools to those with 18-24 month evaluation runway. Taiwan, South Korea, and the United States concentrate GPU and ASIC encoder silicon fabrication. Supply chains draw from specialized foundry capacity, high-bandwidth memory modules, and submarine cable landing rights. Single-source vulnerability concentrates around TSMC advanced node allocation for AV1 encoding chips. Distribution runs through hyperscaler marketplaces, direct enterprise sales teams, and regional systems integrators serving broadcast verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act erects a compliance moat that favors incumbents with pre-built algorithmic audit infrastructure, raising capital requirements for new entrants by forcing parallel analytics stack replication across jurisdictions.
For Market Incumbents: Cement multi-jurisdiction compliance architectures by acquiring specialized governance tooling vendors in Berlin and Singapore. Defend against open-source commercialization threats by embedding proprietary low-latency protocol optimizations into managed service tiers. Prioritize vertical integration into edge POP real estate along 5G millimeter-wave corridors.
For New Entrants and Emerging Players: API-first distribution partnerships with LATAM content aggregators unlock white-label licensing demand in Brazil and Mexico. Target underpenetrated museum digitization verticals in Japan through METI subsidy-aligned sales channels. Frame go-to-market around WebRTC WHIP protocol simplification to displace hardware encoder incumbents in regional sports networks.
For Investors and Strategic Acquirers: Distressed-cycle entries favor edge computing specialists with sovereign cloud certifications in India and Germany. Five-to-ten year viability hinges on protocol standardization capture rather than point-solution dominance. Monitor TRAI data localization enforcement intensity as inflection signal for compliance-tech valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies encoding, packaging, and origin functions into software-defined stacks replacing point solutions. |
| Strategic Partnership | 5G edge co-location agreements with telecom operators in Germany and South Korea compress last-mile latency. |
| Acquisition of Specialist Firm | Governance tooling vendors capture EU AI Act compliance attachment revenue from broadcasters above 45 million users. |
| Geographic Expansion | Replicating analytics stacks inside Indian sovereign cloud zones satisfies TRAI mandates without full platform rebuilds. |
| Product Launch | WebRTC WHIP ingest points eliminate hardware encoder farms for regional sports networks in Spain and South Korea. |
Research Methodology
Multi-period observation of hyperscaler capex disclosures, CDN edge POP deployment filings, and regulatory docket filings anchored the trend analysis, supplemented by interviews with platform engineering directors, broadcast technology procurement leads, compliance officers at OTT operators, and channel partners serving educational verticals. Secondary validation drew from FCC net neutrality rulings, EU Digital Services Act implementation guidance, TRAI consultation papers, SEC 10-K infrastructure spend disclosures, and App Annie streaming platform telemetry. Bottom-up segment sizing triangulated against top-down infrastructure investment aggregation.
Input-output matrices mapped deployment model, organization size, vertical application, integration complexity, and regional regulatory cluster against concurrent stream capacity and transcoding workload intensity. CAGRs were derived from elasticity modeling of infrastructure investment against content hour growth rates. Forecast inputs incorporated 5G millimeter-wave rollout schedules and sovereign cloud certification timelines.
The model holds under stable regulatory enforcement intensity; deviation in EU AI Act audit frequency or TRAI data localization penalties would shift vendor competitive positioning. A model refresh is warranted upon material change in Taiwan semiconductor foundry allocation policies affecting GPU encoder availability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Virtualization Software Market
Software & Services
Optical Design Software Market
Software & Services
Web Framework Software Market
Software & Services
Europe Feedback Management Software Market
Software & Services
Global Gym Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Packaged Software Market
Software & Services
Data Exchange Platform Services Market
Software & Services
Retail Core Banking Solution Market
Software & Services
Global Dance Studio Software Market
Software & Services
Global User Interface Service Market
Software & Services
Global Manufacturing Operations Management (MOM) Software Market
Software & Services
Data Compression Software Market
Software & Services
Mobile Application Testing Services (MATS) Market
Software & Services
Computational Medicine and Drug Discovery Software Market
Software & Services
Full Screen Website Screenshot Software Market