
 Taiwan Data Center Rack Market | 2026-2036
Taiwan Data Center Rack Market Size, Share, and Industry Trends Forecast 2026-2036
Taiwan Data Center Rack Market Insights
Taiwanese server OEM supply chains is restructuring around AI-optimized rack systems as hyperscaler demand intensifies. Schneider Electric SE leverages its three-phase power distribution expertise to anchor large-scale deployments in Kaohsiung's emerging data center zone. Rittal GMBH & Co.KG sustains competitive positioning through precision thermal management systems designed for tropical humidity conditions. Vertiv Group Corp. differentiates via integrated rack-and-power architectures that reduce field assembly time for cloud operators.
A data center rack is a standardized metal framework engineered to mount servers, networking equipment, and power distribution units, typically conforming to 19-inch EIA-310-D specifications with load ratings from 1,000 to 3,000 pounds. Its primary purpose is to optimize spatial density, cable management, and cooling airflow in controlled environments housing mission-critical IT infrastructure. Enclosed rack configurations command premium positioning due to integrated containment requirements for AI training clusters with power densities exceeding 30 kW per cabinet. Colocation providers represent the fastest-expanding end user category as regional cloud operators outsource physical infrastructure to Taipei-based facility operators.
Taiwan's Bureau of Energy enforces data center PUE thresholds under the Greenhouse Gas Reduction and Management Act, compelling rack vendors to certify thermal performance metrics. The National Communications Commission governs telecommunications infrastructure standards that affect rack-mounted network equipment interoperability. BIS-equivalent electrical safety certifications from Taiwan's Bureau of Standards, Metrology and Inspection dictate access for imported rack power components. Stakeholders must monitor evolving liquid cooling interface standards and local content requirements as the government advances domestic server manufacturing targets.
Market Dynamics
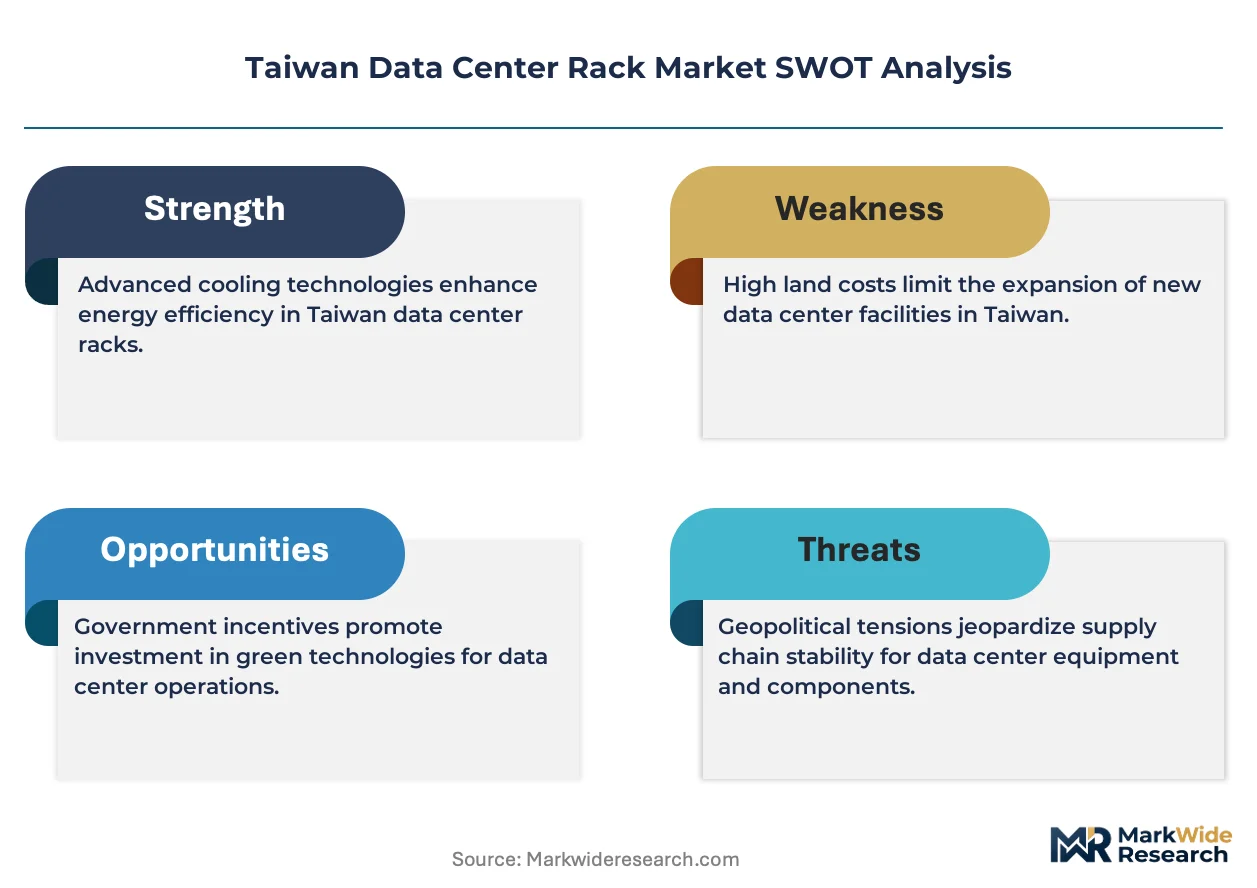
Taiwan's Greenhouse Gas Reduction and Management Act is forcing rack vendors to redesign thermal architectures around liquid cooling interfaces, compressing product development cycles while hyperscaler procurement timelines accelerate.
Growth Catalysts
- Semiconductor cluster density:The Hsinchu-Taichung corridor concentrates advanced packaging and AI chip foundries that require high-density rack configurations exceeding 30 kW per cabinet.
- Bureau of Energy PUE mandates:Taiwan's enforcement of power usage effectiveness thresholds accelerates replacement cycles for legacy air-cooled infrastructure across colocation facilities.
- Cloud service provider expansion:Hyperscalers are deploying standardized rack footprints across Taipei and Taichung science parks to support regional AI inference workloads.
Market Restraints
- Steel and aluminum input volatility:Rack frame manufacturing depends on imported specialty metals subject to Taiwan's Bureau of Foreign Trade tariff adjustments.
- Liquid cooling component supply concentration:Cold plate and manifold sourcing clusters in mainland China, creating geopolitical exposure for Taiwanese OEMs.
- Electrical safety certification friction:Taiwan's Bureau of Standards, Metrology and Inspection testing timelines for imported power distribution units extend market entry by six to nine months.
Strategic Opportunities
- Kaohsiung emerging zone:Southern Taiwan's underdeveloped data center corridor offers greenfield rack deployment opportunities with favorable land and power pricing.
- AI training cluster containment:Integrated rack-and-chamber systems for 100 kW-plus GPU densities represent a white space underserved by standard cabinet vendors.
- Domestic content incentives:Taiwan's Ministry of Economic Affairs local manufacturing targets create procurement preference for rack systems with certified Taiwan-sourced steel and assembly.
Industry Challenges
- Thermal engineering talent scarcity:Liquid cooling system design requires computational fluid dynamics expertise that outpaces Taiwan's vocational training pipeline output.
- Legacy facility retrofit complexity:Existing Taipei colocation sites face structural load and clearance constraints incompatible with next-generation high-density rack footprints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Taiwan Data Center Rack Market |
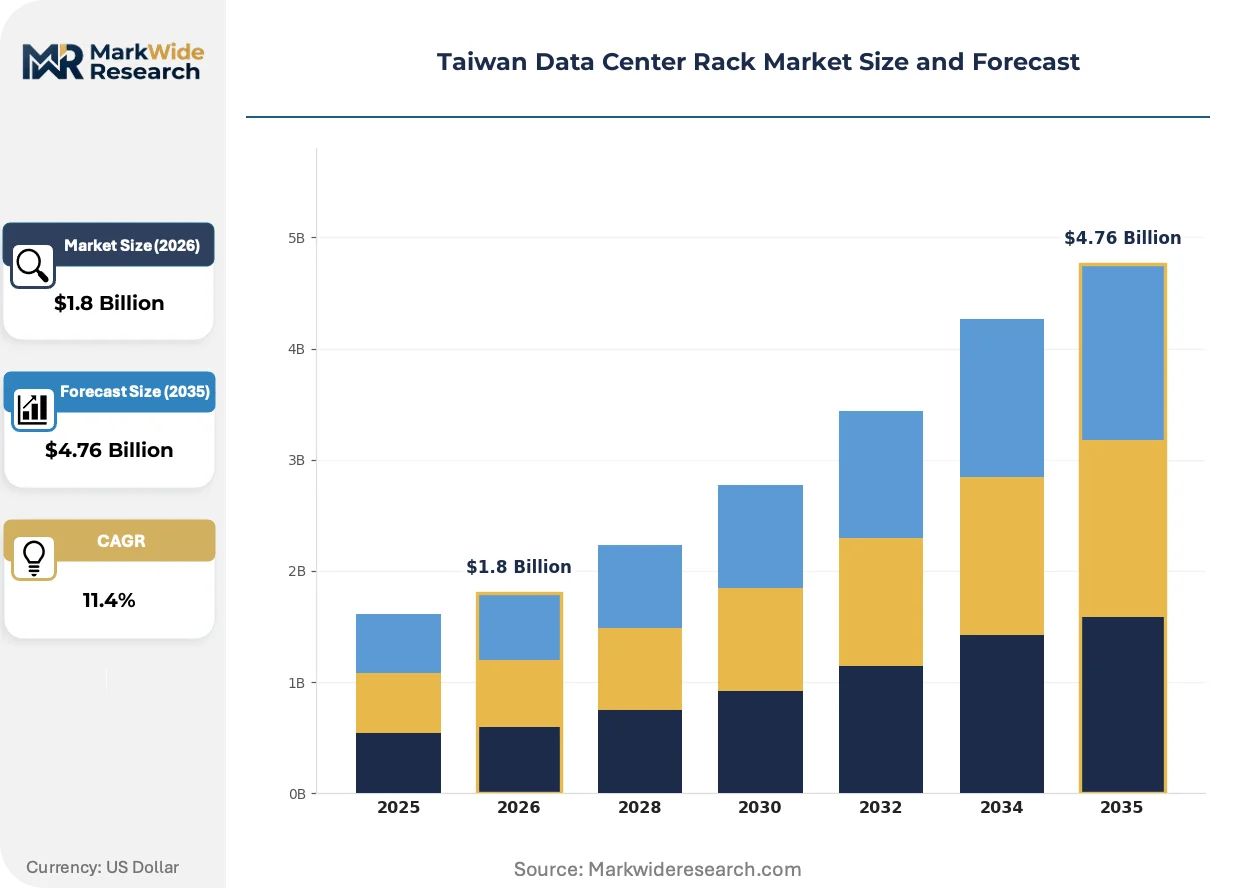
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Frame Rack, Enclosed Rack, Wall-Mount Rack, Custom Rack Installation Type: Free Standing, Rack-Mounted, Modular, Mobile End User: Enterprises, Colocation Providers, Cloud Services, Telecom Operators Connectivity Standards: Ethernet, Fibre Channel, InfiniBand, Others |
| Companies Covered | Eaton Corporation, Rittal GMBH & Co.KG, Schneider Electric SE, Vertiv Group Corp., Dell Inc., Black Box Corporation, Huawei Technologies, Hewlett Packard Enterprise, Cisco Systems, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Taiwan Data Center Rack Market Trends and Innovations
Rack infrastructure is converging with power and cooling systems into pre-integrated factory-tested units, eliminating field assembly while Taiwan's regulatory environment tightens thermal performance verification requirements.
Liquid cooling distribution units with integrated manifolds and quick-disconnect couplings are modularizing rack-level thermal management. Cloud operators in Taichung science parks are specifying these units for 50 kW-plus AI training clusters. This architecture is modularizing the traditional separation between rack OEMs and cooling system vendors into unified supplier relationships.
Taiwan's Bureau of Energy is tightening PUE verification protocols under the Greenhouse Gas Reduction and Management Act, requiring third-party thermal performance certification for rack systems deployed after 2026. This compels vendors to pre-test containment configurations in climate chambers simulating Taiwan's tropical humidity conditions. Colocation providers bear the highest compliance burden as they retrofit existing halls with liquid-ready rack footprints.
Hyperscalers are consolidating rack procurement under direct OEM contracts, bypassing traditional systems integrators that previously specified mixed-vendor configurations. This disintermediation concentrates volume with Schneider Electric, Vertiv, and Rittal while compressing margin pools for local assembly houses. The shift is most visible in Taipei, where Microsoft and Google have established direct vendor qualification programs for standardized 52U AI-optimized cabinets.
Taiwan Data Center Rack Market Segmentation
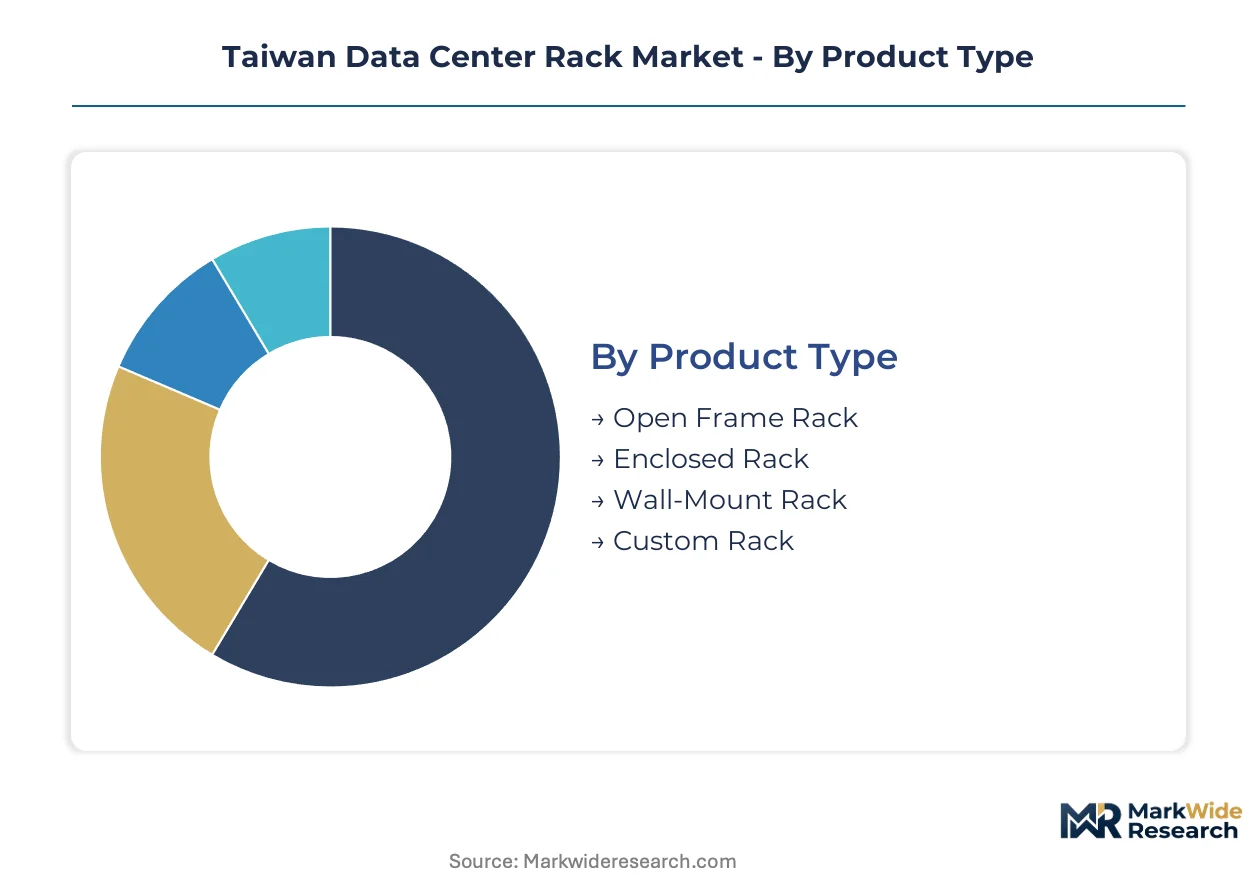
Segmentation in Taiwan's data center rack market reflects divergent infrastructure requirements between legacy enterprise facilities and emerging AI training clusters. Procurement patterns split between standardized footprints for hyperscale deployments and customized configurations for semiconductor foundry-adjacent computing.
Product Type:
Standardization dominates volume production while customization captures premium positioning for high-density thermal containment.
- Open Frame Rack:Four-post metal frameworks without side panels maximize airflow for legacy air-cooled servers under 15 kW density. Enterprises in Taipei retain this configuration for cost-sensitive refresh cycles despite Bureau of Energy PUE pressure.
- Enclosed Rack:Lockable cabinet designs with integrated containment support liquid cooling manifolds and chimney exhaust for GPU clusters exceeding 30 kW per cabinet. Cloud operators in Taichung science parks specify these for AI inference workloads requiring tropical humidity sealing.
- Wall-Mount Rack:Compact 12U-18U enclosures serve edge computing nodes in telecom central offices with space constraints.
- Custom Rack:Non-standard footprints accommodate specialized semiconductor test equipment and heterogeneous server configurations.
Most installed capacity flows through Open Frame Rack configurations. Expansion is steepest in Enclosed Rack systems.
Installation Type:
Structural mounting methods align with facility vintage and load-bearing capacity across Taiwan's data center corridors.
- Free Standing:Bolted floor-mounted frames support 2,000-3,000 pound dynamic loads for standard cabinet rows. Legacy Taipei colocation facilities rely on this proven architecture despite seismic retrofit requirements.
- Rack-Mounted:Equipment integrates directly into facility infrastructure frames, common in carrier hotels with shared meet-me-room spaces.
- Modular:Pre-integrated power and cooling blocks enable rapid hall construction in Kaohsiung's greenfield zones.
- Mobile:Castor-mounted cabinets serve temporary staging and maintenance operations.
Free Standing deployments retain the largest base. Modular installations are climbing the fastest as greenfield development accelerates.
End User:
Procurement authority concentrates with infrastructure operators while semiconductor manufacturers drive specification intensity.
- Enterprises:Financial services and manufacturing firms in Hsinchu maintain captive data centers with mixed-vendor rack configurations. Bureau of Energy compliance deadlines are forcing accelerated replacement of pre-2020 air-cooled infrastructure.
- Colocation Providers:Taipei-based facility operators aggregate demand from regional cloud tenants and specify standardized 52U cabinets. These providers bear the highest retrofit burden for liquid cooling readiness.
- Cloud Services:Hyperscalers deploy direct OEM contracts for AI-optimized rack systems with integrated busway power distribution.
- Telecom Operators:Chunghwa Telecom and regional carriers specify wall-mount and compact rack formats for 5G edge nodes.
Colocation Providers channel the majority of current procurement volume. Cloud Services are gaining share fastest through direct vendor consolidation.
Connectivity Standards:
Network interface specifications fragment between legacy enterprise protocols and high-performance computing interconnects.
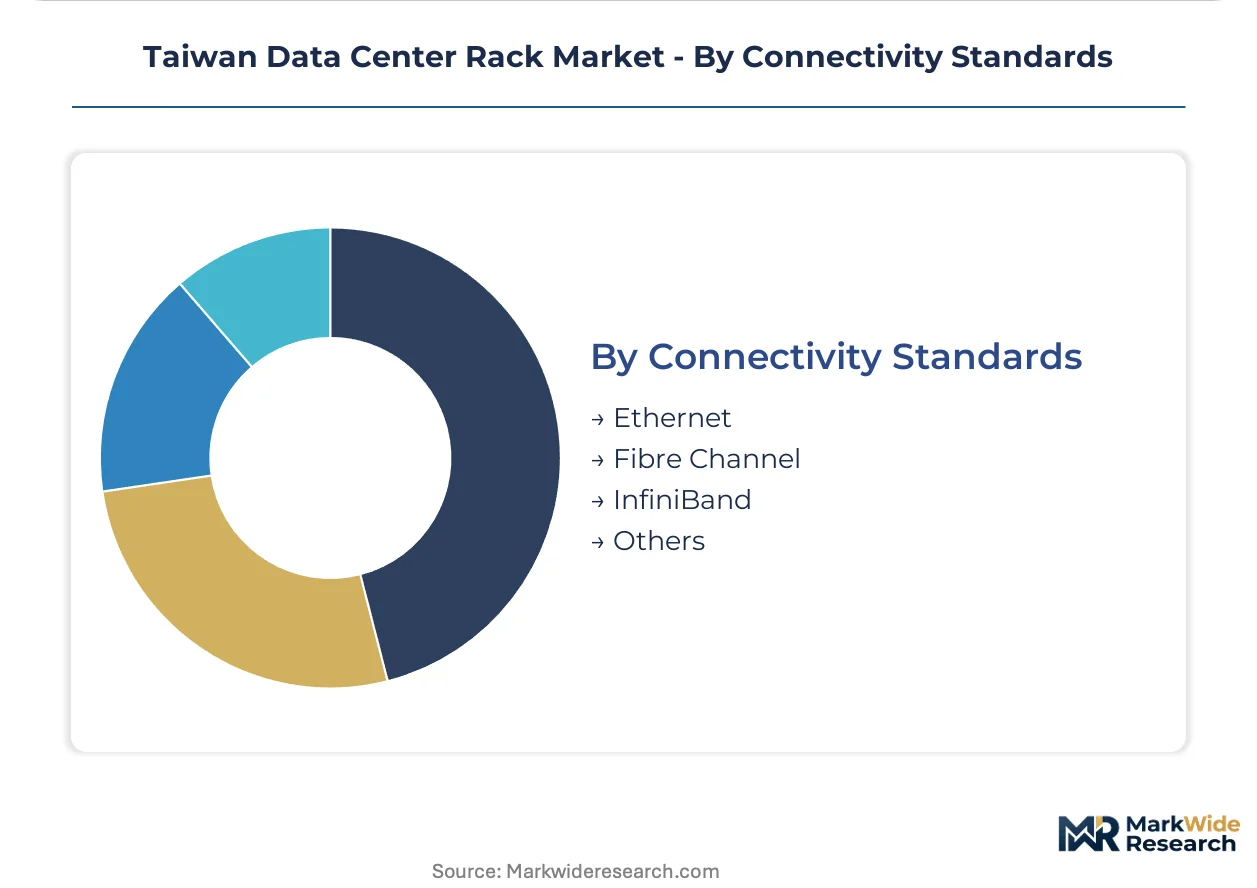
- Ethernet:1G-400G copper and optical interfaces dominate enterprise and cloud connectivity with standardized RJ45 and QSFP form factors. National Communications Commission interoperability mandates ensure cross-vendor compatibility for rack-mounted switches.
- Fibre Channel:32G-64G storage networking persists in financial services and healthcare enterprise deployments.
- InfiniBand:400G-800G NDR and XDR variants serve AI training clusters requiring sub-microsecond latency between GPU nodes.
- Others:Proprietary interconnects include CXL memory fabrics and optical circuit switching for specialized workloads.
Ethernet accounts for the broadest deployment base. InfiniBand is expanding most quickly alongside AI training infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping data center rack procurement patterns as cloud operators migrate capacity toward jurisdictions with favorable energy efficiency compliance costs. Taiwan's Bureau of Energy mandates are accelerating this shift across the Asia-Pacific corridor.
United States
Hyperscaler expansion in Northern Virginia and Phoenix drives demand for 52U AI-optimized cabinets exceeding 30 kW density. The EPA's ENERGY STAR for Data Centers program influences procurement specifications for liquid-cooled rack systems. Ashburn's Data Center Alley concentrates the majority of new rack deployments for training cluster infrastructure.
Germany
Frankfurt's financial services sector sustains demand for enclosed rack configurations with integrated containment. The EU Energy Efficiency Directive and national implementation through BAFA funding programs accelerate replacement of legacy air-cooled infrastructure. Berlin-Brandenburg's emerging cloud corridor attracts modular rack deployments from international operators.
Japan
Tokyo's dense urban colocation market favors compact high-density rack footprints with seismic-rated structural designs. METI's Green Transformation initiative mandates PUE reporting that favors liquid-ready cabinet specifications. Osaka's Kansai Science City clusters semiconductor-adjacent computing requiring custom thermal containment solutions.
Singapore
Jurong and Tuas data center zones impose strict land-use efficiency requirements that drive vertical rack density above 40 kW per cabinet. The Infocomm Media Development Authority's sustainability standards for data centers mandate thermal performance certification. Changi Business Park hosts regional cloud headquarters specifying standardized rack footprints across ASEAN operations.
South Korea
Pangyo's G-Valley technology corridor concentrates AI training infrastructure procurement for GPU-dense rack systems. The Ministry of Trade, Industry and Energy's carbon neutrality roadmap for data centers accelerates liquid cooling adoption. Busan's emerging submarine cable landing zone creates greenfield opportunities for modular rack-and-power integration.
Taiwan Data Center Rack Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue integrated thermal-power architectures that compress deployment timelines. The vendor base clusters around three strategic archetypes: European industrial conglomerates with three-phase power distribution expertise, German precision thermal specialists, and American integrated infrastructure providers. Consolidation pressure intensifies as hyperscalers consolidate procurement under direct OEM contracts, displacing traditional systems integrators. Competitive moves center on factory pre-integration of cooling manifolds and accelerated certification programs for tropical climate performance.
Within the European industrial tier, Rittal GMBH & Co.KG and Schneider Electric SE exemplify precision thermal and power distribution positioning respectively. Vertiv Group Corp. anchors the integrated infrastructure archetype with American operational heritage. These three entities collectively represent the vendor consolidation pattern visible in direct hyperscaler qualification programs across Taipei and Taichung deployment zones.
| Leading Market Players |
|---|
| Eaton Corporation |
| Rittal GMBH & Co.KG |
| Schneider Electric SE |
| Vertiv Group Corp. |
| Dell Inc. |
| Black Box Corporation |
| Huawei Technologies |
| Hewlett Packard Enterprise |
| Cisco Systems |
| Others |
Pricing and Supply Chain Analysis
Liquid cooling engineering talent concentration in the Hsinchu-Taichung corridor creates labor-cost differentials that widen pricing-tier spreads between standard air-cooled racks and certified high-density configurations. Taiwan's Bureau of Energy PUE mandates compress margin pools for legacy products while rewarding thermal performance premiums.
Pricing Analysis
Distributor margin compression in traditional systems integrator channels is accelerating direct-to-OEM discount structures as hyperscalers consolidate procurement under factory-direct contracts. Three-tier pricing structure across premium liquid-cooled, standard enclosed, and economy open-frame levels reflects certification grade and tropical climate testing investment. Pricing pressure stems from steel and aluminum input volatility subject to Taiwan's Bureau of Foreign Trade adjustments. Colocation providers exhibit highest price sensitivity due to retrofit capital constraints, while cloud services prioritize performance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with mainland China cold plate and manifold sourcing clusters, creating geopolitical exposure for Taiwanese OEMs dependent on liquid cooling component imports. Specialty steel and aluminum feedstock draws from Japan, South Korea, and domestic Taiwan mills, while electrical power distribution units hinge on German and American component supply. Tariff exposure through cross-strait trade friction represents the dominant structural risk. Distribution runs through Taipei-based facility operators and direct hyperscaler qualification programs, bypassing traditional integrator networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Taiwan's data center rack market functions as a geographic-arbitrage play where Kaohsiung's greenfield land and power costs undercut Taipei retrofit premiums by meaningful margins. Bureau of Energy compliance timelines in the northern corridor accelerate replacement demand that southern zones absorb with lower total cost of ownership.
For Market Incumbents: Anchor factory pre-integration capabilities to defend against modular rack-and-power entrants compressing field assembly timelines. Deepen backward integration into Taiwan-sourced steel certification to capture Ministry of Economic Affairs domestic content incentives. Threat substitution from integrated thermal-power architectures demands accelerated tropical climate chamber testing investment. For New Entrants and Emerging Players: Capture Kaohsiung's emerging data center zone where greenfield liquid-ready specifications outpace established vendor qualification cycles. The most penetrable segment sits with AI training cluster containment systems exceeding 100 kW densities underserved by standard cabinet vendors. Go-to-market angle centers on direct OEM partnerships with cloud operators bypassing traditional systems integrator channels. For Investors and Strategic Acquirers: Cloud service providers and semiconductor foundry operators are the most active acquirer categories in this space, pursuing captive supply of thermal infrastructure. Long-term viability over a five-to-ten year window rests on liquid cooling interface standardization and local content compliance capability. Acquisition target archetype: precision thermal engineering firms with computational fluid dynamics talent pipelines. Signal to watch: Bureau of Energy protocol tightening on third-party thermal performance verification thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Factory Pre-Integration of Cooling Manifolds | Compresses field assembly timelines for hyperscaler deployments in Taichung science parks. |
| Tropical Climate Chamber Certification | Satisfies Bureau of Energy PUE verification protocols for post-2026 rack deployments. |
| Domestic Steel Sourcing Certification | Unlocks Ministry of Economic Affairs procurement preference for local content compliance. |
| Liquid Cooling Interface Standardization | Reduces cold plate sourcing vulnerability to mainland China supply concentration. |
| Kaohsiung Greenfield Facility Partnership | Captures favorable land and power pricing in Taiwan's underdeveloped southern corridor. |
Research Methodology
Multiple input streams — hyperscaler procurement officer interviews, colocation facility operator surveys, and supplier technical documentation — were reconciled across primary and secondary validation protocols. Stakeholder engagement encompassed data center infrastructure directors, thermal engineering specialists, Bureau of Energy compliance officers, and cloud platform architects. Secondary sources included Taiwan Bureau of Standards electrical safety filings, science park development authority records, and hyperscaler capital expenditure disclosures. Bottom-up rack deployment estimates and top-down infrastructure investment flows were triangulated for consistency.
Historical deployment patterns were cross-referenced against panel input from facility operators and OEM technical directors across the projection horizon. Segmentation modeling incorporated product type, installation configuration, end-user category, and connectivity standard dimensions alongside power density tier and tropical climate certification status. CAGRs were derived from infrastructure investment trajectories and replacement cycle compression under regulatory mandates. Forecast inputs included Bureau of Energy PUE threshold enforcement timelines and hyperscaler direct procurement consolidation rates.
Steel tariff adjustments, cross-strait trade friction escalation, and liquid cooling component supply disruption are the dominant revision risks to modeled outputs. Forecasts reflect underlying assumptions about regulatory enforcement continuity and hyperscaler capacity expansion commitment. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Spain Data Center Market
Data Center Infrastructure
Middle East Data Center Physical Security Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Mexico Data Center Physical Security Market
Data Center Infrastructure
Data Center Support Infrastructure Market
Data Center Infrastructure
Canada Data Center Rack Market
Data Center Infrastructure
Asia-Pacific Containerized Data Center Market
Data Center Infrastructure
United Kingdom Data Center Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Malaysia Data Center Market
Data Center Infrastructure
Retail Colocation Market
Data Center Infrastructure
Norway Data Center Market
Data Center Infrastructure
Italy Data Center Construction Market
Data Center Infrastructure
Global Micro Mobile Data Center Market
Data Center Infrastructure
Thailand Data Center Power Market
Data Center Infrastructure
Italy Data Center Rack Market