
 Data Center Colocation and Managed Hosting Services Market | 2026-2036
Data Center Colocation and Managed Hosting Services Market Size, Share, and Industry Trends Forecast 2026-2036
Data Center Colocation and Managed Hosting Services Market Analysis
Financial services demand is shifting toward low-latency colocation facilities adjacent to major exchanges. Equinix leverages its interconnection density to anchor trading ecosystem proximity in key financial districts. Digital Realty sustains global scale through hyperscale campus developments across multiple continents. NTT Data competes on hybrid cloud integration, blending managed hosting with native cloud orchestration layers.
Data center colocation and managed hosting services encompass the provision of third-party physical infrastructure space, power, cooling, and remote operational management for enterprise IT equipment, typically delivered through facilities with redundant electrical systems, precision HVAC, and cross-connect fabrics enabling carrier-neutral network access. Dedicated hosting and managed hosting segments command premium pricing due to labor-intensive operational support and security compliance overhead, while hybrid cloud deployments represent the fastest-expanding architecture as enterprises straddle private infrastructure with public cloud burst capacity. Edge deployment models are gaining structural importance for latency-bound applications including autonomous systems and industrial IoT, though on-premises legacy footprints retain steady share in regulated sectors with strict data residency mandates.
EU GDPR requirements and the EU AI Act impose stringent data localization and algorithmic transparency obligations that directly shape provider site selection and customer contract structures in Europe. In the United States, FERC interconnection standards and state-level utility regulations influence power sourcing strategies and renewable energy commitments for facility operators. Stakeholders must monitor evolving carbon disclosure rules under CSRD and emerging efficiency standards from ISO and IEC working groups as sustainability metrics become embedded in procurement criteria.
Market Dynamics
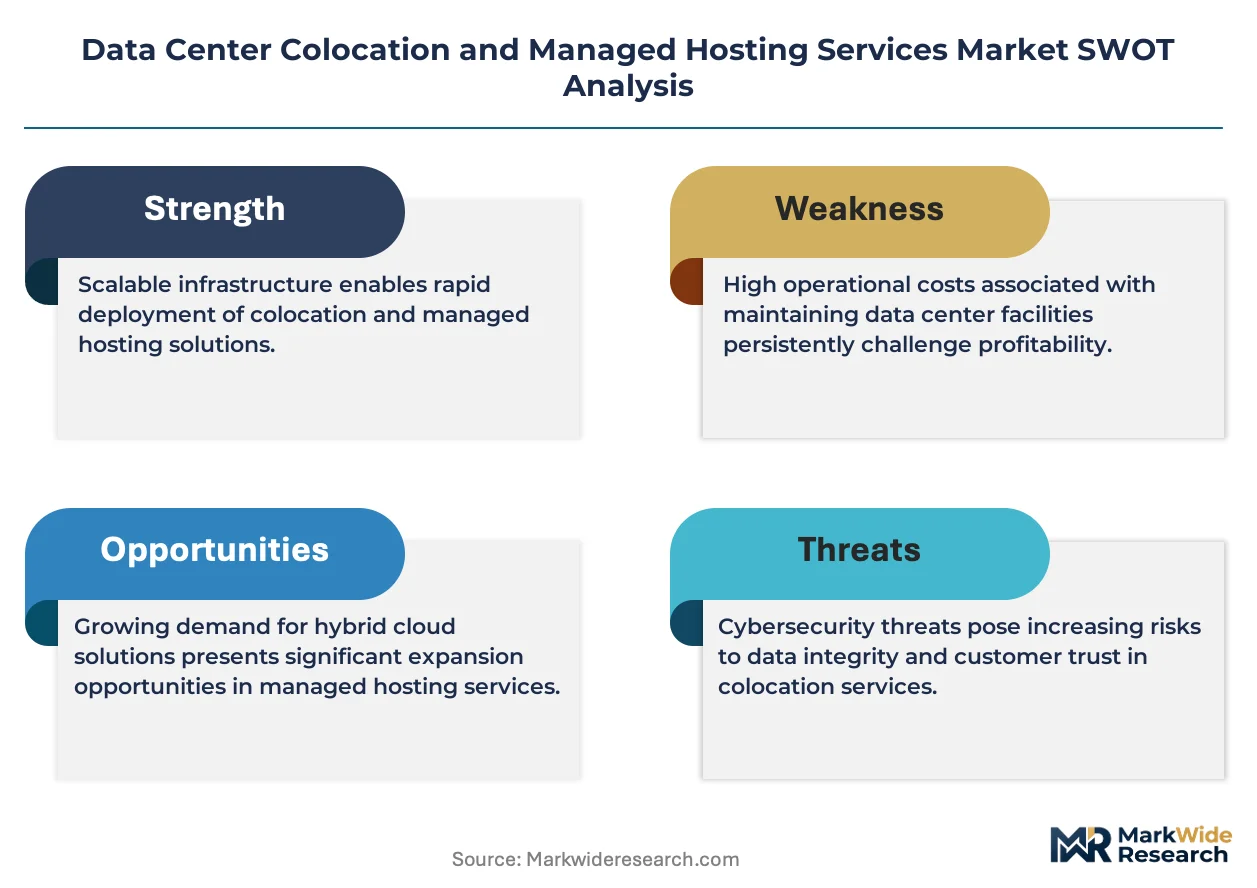
Hyperscaler demand concentration is compressing provider margins while forcing rapid capacity expansion across primary hub markets. The EU AI Act and parallel data sovereignty mandates are rewriting certification requirements and site selection criteria for European deployments.
Growth Catalysts
- Algorithmic Trading Latency Requirements:Financial services firms require sub-millisecond proximity to exchange matching engines. Frankfurt, London, and Singapore financial districts anchor new facility development.
- CSRD Carbon Disclosure Mandates:Corporate Sustainability Reporting Directive rules force enterprises toward certified green data center providers. Renewable power purchase agreements now dominate procurement evaluation.
- GPU Cluster Density:AI training workloads demand 50-100kW per rack configurations. Liquid cooling retrofits and purpose-built AI-ready facilities capture premium lease rates.
Market Restraints
- Grid Interconnection Queues:FERC standard interconnection timelines stretch 36-48 months in Texas and Virginia primary markets. Delayed utility infrastructure bottlenecks facility commissioning schedules.
- Lithium-Ion Battery Supply Concentration:Uninterruptible power system battery procurement depends on Chinese cathode material processing. Geopolitical friction threatens backup power system delivery reliability.
- Legacy Copper Network Substitution:Dark fiber and wavelength services displace traditional cross-connect revenue streams. Carrier-neutral facilities face pricing pressure on interconnection services.
Strategic Opportunities
- Indonesia Archipelago Edge:Jakarta and Batam subsea cable landings create underpenetrated Southeast Asian capacity. Government data localization rules mandate domestic processing for financial and telecom sectors.
- Nuclear Small Modular Reactor Co-location:Baseload carbon-free power contracts align with hyperscaler net-zero commitments. Tennessee Valley Authority and Ontario Power Generation sites attract development interest.
- Modular Prefabrication Convergence:Factory-built power modules and cooling skids compress construction timelines. Standardized designs reduce engineering redundancy across multi-site deployments.
Industry Challenges
- Critical Facilities Engineering Talent Scarcity:Experienced data center design engineers and commissioning specialists command 40% wage premiums. Training pipeline gaps extend project staffing timelines.
- Multi-Cloud Orchestration Complexity:Enterprise hybrid architectures require seamless workload portability across private colocation and three-plus public cloud environments. Integration tooling standardization remains fragmented.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Data Center Colocation and Managed Hosting Services Market |
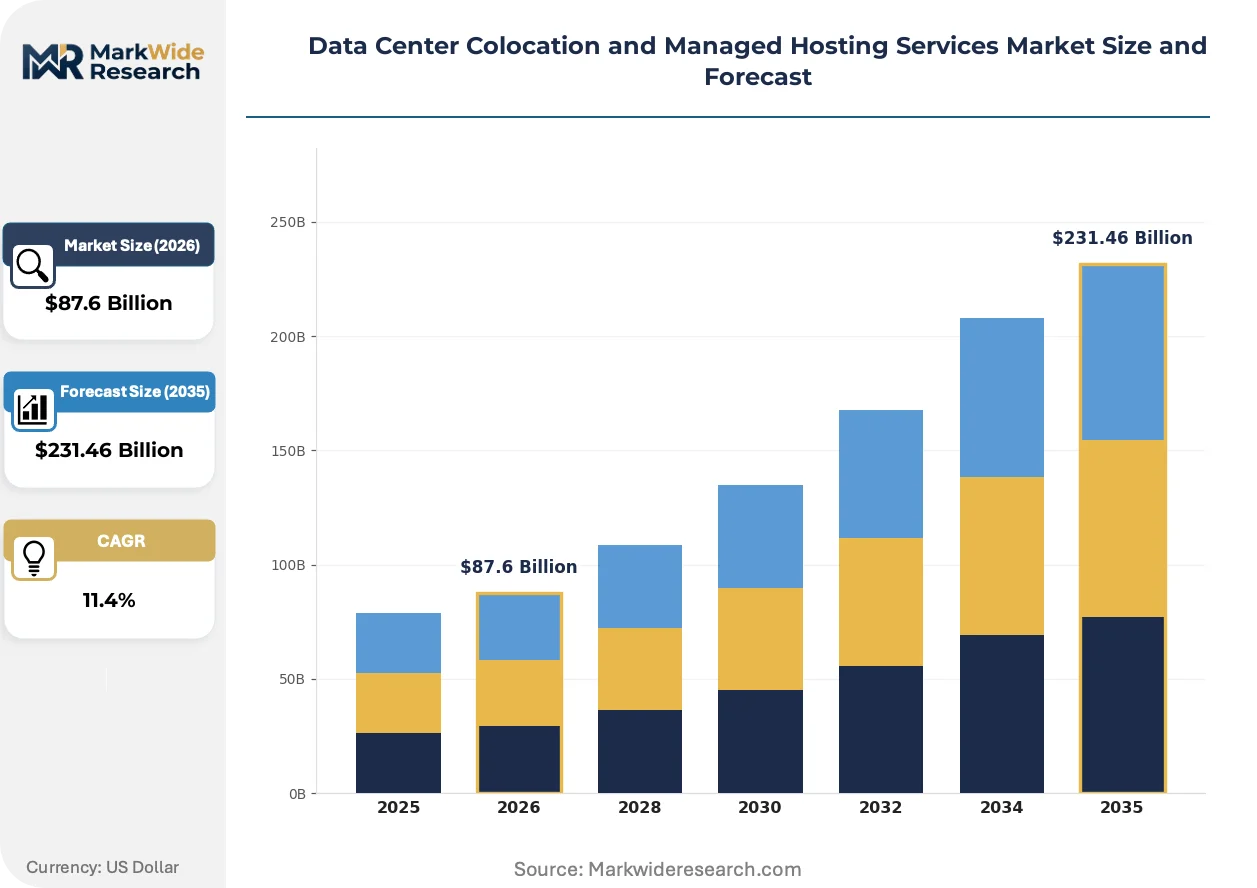
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Colocation, Dedicated Hosting, Managed Hosting, Hybrid Cloud End User: IT Providers, Telecommunications, Enterprises, Government Agencies Deployment Model: On-Premises, Off-Premises, Virtual, Edge Infrastructure Type: Server, Storage, Networking, Security |
| Companies Covered | Rackspace Technology, Kyndryl, Equinix, NTT Data, QTS Data Centers, Digital Realty, Flexential, ServerMania, NTT Global Data Centers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Data Center Colocation and Managed Hosting Services Market Emerging Trajectories
Software-defined infrastructure is collapsing traditional boundaries between compute, storage, and networking layers. Provider differentiation increasingly depends on API-native automation and cross-platform orchestration capabilities.
Immersion cooling systems are unifying thermal management with power density scaling requirements. Hyperscale operators deploy single-phase and two-phase dielectric fluid solutions at 100kW-plus rack densities. This technology is unifying facility design around heat rejection architecture rather than traditional air-side economization.
The EU AI Act imposes algorithmic transparency and training data documentation obligations on AI system deployers. Data center operators must implement audit trails for GPU cluster utilization and model training logs. German and French financial services firms are pre-negotiating contract amendments to allocate compliance liability between host and tenant.
Consumption-based billing models are displacing traditional per-rack or per-cabinet fixed pricing. Enterprise procurement teams negotiate burstable power and cross-connect pricing tied to actual metered utilization. This shift is most visible among North American SaaS providers with unpredictable workload scaling patterns.
Data Center Colocation and Managed Hosting Services Market Segmentation
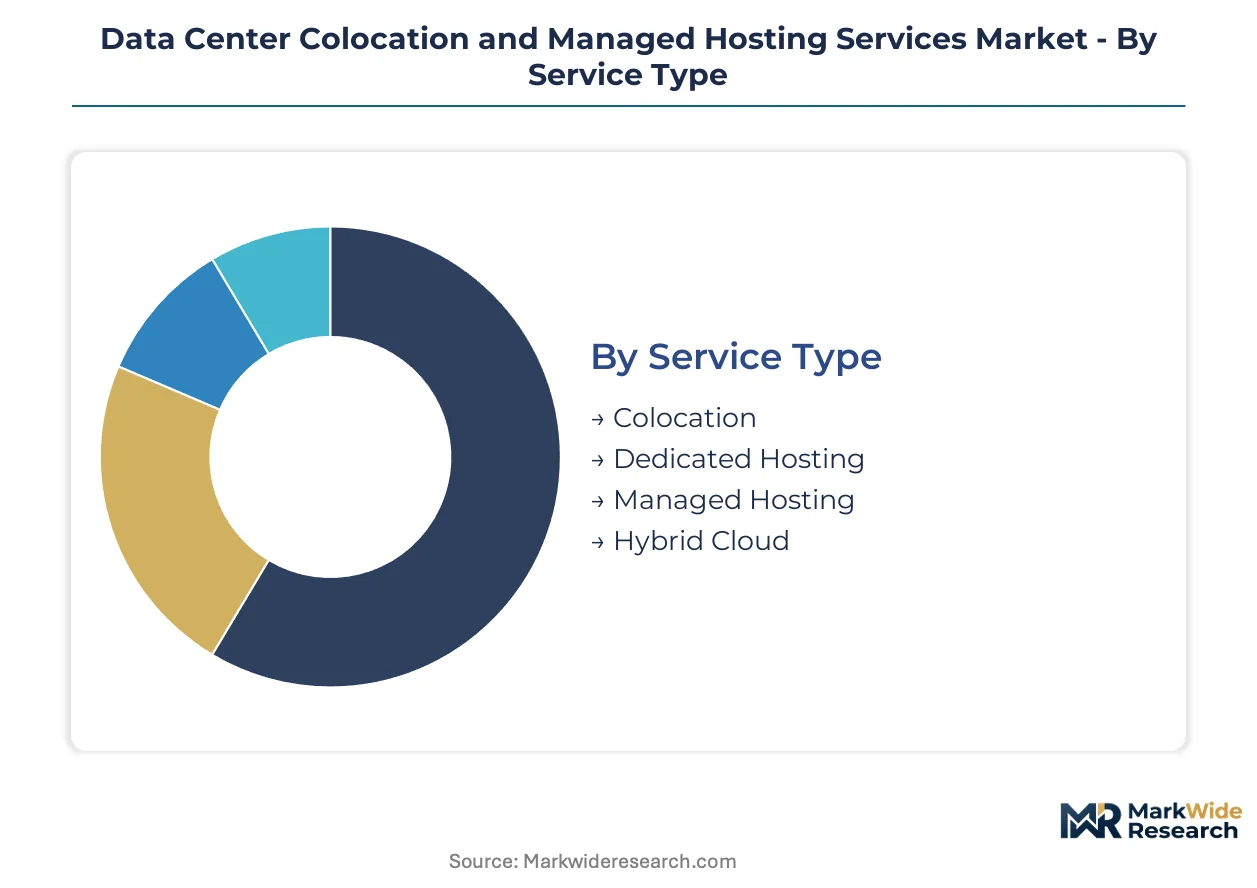
Segmentation in data center services reveals how buyer priorities diverge across latency sensitivity, compliance burden, and workload portability requirements. Procurement teams evaluate providers through fundamentally different lenses depending on whether they anchor trading infrastructure, consolidate enterprise IT, or burst into public cloud.
Service Type:
Buyers in this category separate by operational control preference and the internal IT labor they retain versus outsource.
- Colocation:Tenants supply and manage their own server hardware within provider facilities, purchasing only space, power, cooling, and physical security. Financial services firms in Frankfurt and Singapore financial districts drive premium pricing for sub-millisecond exchange proximity. FERC interconnection queues in Virginia and Texas constrain new supply despite hyperscaler pre-leasing commitments.
- Managed Hosting:Providers assume full operational responsibility for hardware procurement, patching, monitoring, and incident response. German and French enterprises under EU AI Act documentation obligations favor this model for audit trail centralization. Labor-intensive delivery commands 40-60% pricing premiums over raw colocation.
- Dedicated Hosting:Single-tenant physical or virtual servers with guaranteed resource isolation. US healthcare organizations under HIPAA technical safeguards requirements prefer dedicated infrastructure for PHI segregation.
- Hybrid Cloud:Orchestrated workload portability between private colocation and public cloud burst capacity. GPU cluster density requirements from AI training workloads accelerate adoption of fluid capacity contracts.
Colocation leads volumes today; hybrid cloud is gaining share fastest.
End User:
Demand concentration varies sharply by sector-specific latency mandates and data sovereignty enforcement intensity.
- IT Providers:SaaS vendors and platform operators requiring elastic infrastructure scaling. North American SaaS procurement teams negotiate burstable power pricing tied to metered utilization rather than fixed rack commitments.
- Telecommunications:Carriers deploying 5G core network functions and edge computing nodes. Indonesian government data localization rules for telecom sectors mandate domestic processing infrastructure.
- Enterprises:Fortune 500 manufacturers and retailers consolidating fragmented data center footprints. CSRD carbon disclosure requirements redirect procurement toward certified green facility providers with renewable power purchase agreements.
- Government Agencies:Defense, intelligence, and civilian agencies with strict data residency and personnel clearance requirements. FedRAMP and StateRAMP certifications gate provider eligibility for US federal contracts.
Enterprises dominate current contract value; IT providers show the steepest expansion trajectory.
Deployment Model:
Physical proximity to data sources and end-users determines architecture selection more than cost optimization alone.
- On-Premises:Customer-owned facilities with full operational autonomy. Regulated sectors including Swiss banking and Japanese healthcare retain steady share due to strict data residency mandates.
- Off-Premises:Third-party data center facilities delivering economies of scale. Hyperscaler demand concentration compresses provider margins while forcing rapid capacity expansion across primary hub markets.
- Virtual:Abstracted compute resources decoupled from physical infrastructure location. Multi-cloud orchestration complexity fragments integration tooling standardization.
- Edge:Distributed micro-facilities positioned within 10-50ms of endpoints. Autonomous systems and industrial IoT latency requirements drive structural importance despite higher per-kW delivery costs.
Off-Premises anchors installed base; Edge deployment is climbing the fastest.
Infrastructure Type:
Technology refresh cycles and density scaling requirements differentiate buyer investment priorities.
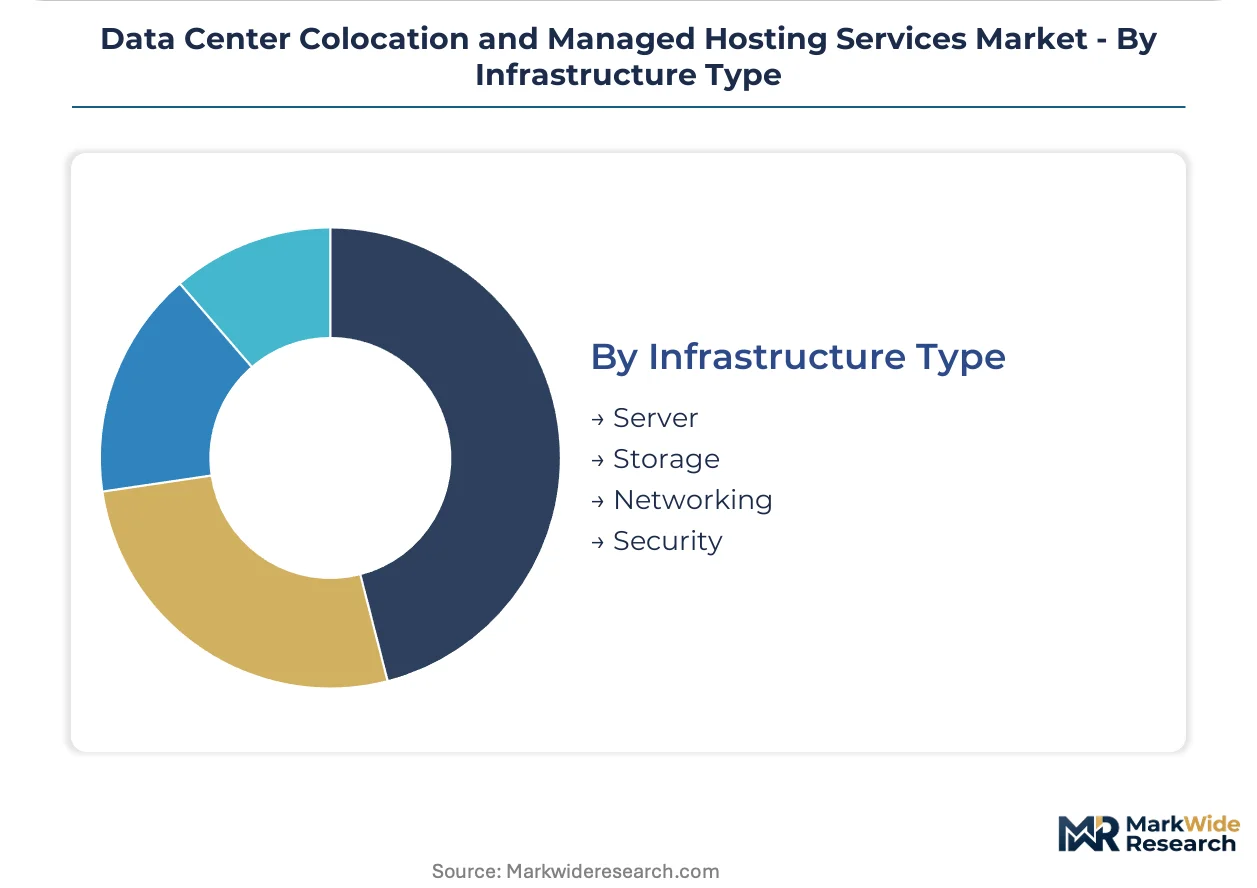
- Server:Compute hardware including CPU and GPU clusters for general and accelerated workloads. AI training configurations demand 50-100kW per rack, forcing liquid cooling retrofits and purpose-built facility designs.
- Storage:Block, file, and object storage systems with tiered performance characteristics. GDPR data retention obligations extend storage lifecycle management complexity for European deployments.
- Networking:Cross-connect fabrics, software-defined WAN, and interconnection exchange fabrics. Dark fiber and wavelength services displace traditional copper cross-connect revenue streams.
- Security:Physical access controls, DDoS mitigation, and zero-trust network segmentation. EU AI Act algorithmic transparency mandates require audit trails for GPU cluster utilization and model training logs.
Server infrastructure commands the largest capital allocation; security services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping facility investment flows as hyperscalers migrate workloads toward jurisdictions with streamlined permitting and renewable energy access. Compliance cost differentials between the EU AI Act enforcement zone and alternative markets are accelerating site selection recalibration.
United States
Virginia's Loudoun County and Texas's Dallas-Fort Worth metroplex anchor hyperscale pre-leasing commitments. FERC interconnection queues stretching 36-48 months constrain new supply despite sustained demand from financial services and cloud operators. The Tennessee Valley Authority's nuclear small modular reactor sites attract development interest for baseload carbon-free power contracts.
Germany
Frankfurt's financial district commands premium pricing for sub-millisecond exchange proximity serving algorithmic trading ecosystems. EU AI Act documentation obligations and GDPR data localization mandates reshape provider certification requirements. German enterprises favor managed hosting models for centralized audit trail compliance under emerging algorithmic transparency rules.
Singapore
The city-state's subsea cable landing density anchors Southeast Asian interconnection demand. Government data localization rules for financial and telecom sectors mandate domestic processing infrastructure. Marina Bay and Changi Business Park clusters concentrate GPU-intensive AI training workloads requiring liquid cooling retrofits.
Indonesia
Jakarta and Batam subsea cable landings create underpenetrated capacity for archipelago edge deployment. Government data localization mandates for financial and telecom sectors require domestic processing infrastructure. Batam's free trade zone status offers tariff advantages for imported server hardware.
Japan
Tokyo and Osaka financial districts sustain latency-sensitive trading infrastructure demand. METI efficiency standards and data residency expectations from Japanese healthcare and banking sectors retain steady on-premises footprint. Osaka's emerging hyperscale campus developments target AI training workload migration from capacity-constrained Tokyo.
Data Center Colocation and Managed Hosting Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with interconnection density operators commanding premium positioning against scale-driven wholesale providers. Market structure concentrates around three tiers: hyperscale campus developers, metro interconnection specialists, and hybrid cloud integrators. Dominant competitive moves include rapid capacity pre-leasing in primary hub markets and vertical integration into renewable energy sourcing to meet CSRD-aligned procurement criteria.
Within the interconnection density tier, Equinix anchors trading ecosystem proximity through financial district adjacencies. Digital Realty exemplifies hyperscale campus development across multiple continental markets. NTT Data occupies a position blending managed hosting operational responsibility with native cloud orchestration layers, representing the hybrid integration archetype.
| Leading Market Players |
|---|
| Rackspace Technology |
| Kyndryl |
| Equinix |
| NTT Data |
| QTS Data Centers |
| Digital Realty |
| Flexential |
| ServerMania |
| NTT Global Data Centers |
| Others |
Supply Flow & Price Mechanics
Critical facilities engineering talent scarcity in Northern Virginia and Frankfurt financial districts widens pricing-tier spreads between premium managed hosting and raw colocation offerings. Labor-cost differentials of 40% for commissioning specialists translate directly into 40-60% service premiums for operational-heavy delivery models.
Pricing Analysis
Direct-to-tenant contracting dominates hyperscale relationships, bypassing traditional channel margins that persist in mid-market segments. Three-tier pricing structure across premium, standard, and economy levels separates financial district proximity sites with sub-millisecond latency guarantees from secondary metro facilities. Pricing pressure stems from hyperscaler demand concentration compressing provider margins in primary hub markets. SaaS vendors with burstable workload patterns exhibit highest price sensitivity, while algorithmic trading firms accept premiums for exchange adjacency.
Supply Chain Analysis
Indonesian and Vietnamese domestic-content mandates for data center infrastructure are reshaping equipment sourcing patterns across Southeast Asian deployments. Uninterruptible power system procurement draws from Chinese cathode material processing, Taiwanese power electronics manufacturing, and South Korean battery cell assembly. Single-source vulnerability in lithium-ion battery supply threatens backup power system delivery reliability. Distribution runs through carrier-neutral facility operators with cross-connect fabrics enabling tenant-direct procurement of dark fiber and wavelength services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion pathways through liquid cooling retrofits commanding premium lease rates for GPU-dense AI configurations. Standardized modular prefabrication compresses construction timelines and reduces engineering redundancy costs.
For Market Incumbents: Extend interconnection density advantages in financial districts through rapid capacity pre-leasing before FERC interconnection queues lengthen further. Anchor renewable power purchase agreements to defend positioning against CSRD-aligned procurement criteria. Invest in immersion cooling capabilities to capture 50-100kW rack density premiums from AI training workloads.
For New Entrants and Emerging Players: Enter via Indonesia's underpenetrated archipelago edge market where government data localization rules create captive demand for domestic processing infrastructure. Target Batam's free trade zone for tariff-advantaged server hardware import. Lead with modular prefabrication capabilities to compress commissioning timelines against established providers.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional wholesale operators lacking interconnection density or renewable energy sourcing scale. Long-term viability favors assets with nuclear small modular reactor power contracts aligning to hyperscaler net-zero commitments. Monitor FERC interconnection queue clearance rates as inflection indicator for supply-constrained primary markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Liquid Cooling Infrastructure Deployment | Enables 100kW-plus rack densities for AI training workloads in Frankfurt and Singapore clusters. |
| Renewable Power Purchase Agreement | Aligns facility operators with CSRD carbon disclosure mandates from European enterprise procurement teams. |
| Modular Prefabrication Standardization | Compresses construction timelines through factory-built power modules and cooling skids. |
| Nuclear SMR Co-location Contract | Secures baseload carbon-free power for hyperscaler net-zero commitments at Tennessee Valley Authority sites. |
| Edge Facility Development | Positions micro-facilities within 10-50ms of endpoints for autonomous systems and industrial IoT latency requirements. |
Methodological Framework
Multiple input streams — facility operations executives, hyperscaler procurement officers, data center design engineers, and interconnection exchange managers — were reconciled against SEC 10-K filings, FERC interconnection queue data, hyperscaler capex disclosures, and EU regulatory filings. Bottom-up capacity installation tracking and top-down enterprise IT spend analysis provided triangulation anchors across the modeling period.
Historical deployment patterns were cross-referenced against panel input from infrastructure investors and EPC contractors to derive growth trajectories across service type, deployment model, and infrastructure type segments. CAGRs were derived from facility commissioning schedules, pre-leasing commitment timelines, and power density scaling curves. GPU cluster density requirements and liquid cooling adoption rates served as industry-specific forecast inputs.
Inputs from hyperscaler procurement teams and facility operators were available through the study window; gaps in forward interconnection queue clearance timelines introduce uncertainty bands around capacity expansion forecasts. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Cloud Network Infrastructure Market
Data Center Infrastructure
Data Center Asset Management Market
Data Center Infrastructure
Italy Data Center Rack Market
Data Center Infrastructure
Thailand Data Center Market
Data Center Infrastructure
India Data Center Rack Market
Data Center Infrastructure
United Arab Emirates Data Center Market
Data Center Infrastructure
Philippines Data Center Physical Security Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
France Data Center Construction Market
Data Center Infrastructure
Singapore Data Center Rack Market
Data Center Infrastructure
Iaas/Hosting Infrastructure Services Market
Data Center Infrastructure
New Zealand Data Center Power Market
Data Center Infrastructure
Belgium Data Center Rack Market
Data Center Infrastructure
Rugged Servers Market
Data Center Infrastructure
Hosting Infrastructure Services Market
Data Center Infrastructure
Data Center IT Asset Disposition Market