
 China Data Center Construction Market | 2026-2036
China Data Center Construction Market Size, Share, and Industry Trends Forecast 2026-2036
China Data Center Construction Market Insights
GB 50174 certification for data center design is collapsing the field of qualified domestic contractors. DPR Construction leverages its international hyperscale experience to anchor premium design-build contracts in Tier-1 cities. Gammon Construction sustains competitive positioning through deep vertical integration into mechanical and electrical systems. M+W Shanghai dominates the high-reliability segment with specialized cleanroom-adjacent expertise for semiconductor-linked facilities.
China data center construction encompasses the engineering, procurement, and physical build-out of facilities housing servers, storage, and networking equipment, with power densities now routinely exceeding 15 kW per rack in new hyperscale halls. The primary purpose is creating controlled environments that maintain 99.999% uptime availability while managing thermal loads across expanding compute footprints. Infrastructure type segments reveal modular and containerized formats capturing disproportionate growth as land scarcity in core cities accelerates prefabricated deployment timelines. Service type analysis shows design-build integration yielding superior margin pools compared to discrete construction-only contracts, with operations and management services extending revenue visibility post-handover.
MIIT's dual carbon goals, SAMR's GB standards enforcement, and NMPA-adjacent environmental compliance frameworks collectively reshape equipment specifications and energy efficiency thresholds for new builds. These regulations are forcing rapid substitution of air-cooled legacy designs with liquid cooling architectures in facilities above 50 MW capacity. Stakeholders must monitor power grid interconnection queues and provincial carbon intensity benchmarks as gatekeepers for project viability.
Market Dynamics
MIIT's dual carbon goals are forcing a wholesale architectural transition from air-cooled to liquid-cooled infrastructure, compressing deployment timelines and disqualifying legacy contractors unable to certify under GB 50174-2017 standards.
Growth Catalysts
- Hyperscale cloud expansion:Alibaba Cloud, Tencent Cloud, and ByteDance are commissioning 50+ MW facilities in Shanghai and Shenzhen, driving demand for specialized design-build contractors with international hyperscale credentials.
- MIIT dual carbon mandates:The ministry's 2030 carbon peak targets are accelerating liquid cooling adoption in facilities above 50 MW capacity, creating premium pricing power for certified mechanical integrators.
- Semiconductor-linked data halls:AI training clusters for domestic chip foundries require cleanroom-adjacent construction expertise, pulling M+W Shanghai and specialized contractors into high-margin reliability segments.
Market Restraints
- Power interconnection queues:Grid connection approvals in Beijing and Shanghai now stretch 18-24 months, freezing project starts regardless of capital availability or land secured.
- Copper and electrical steel volatility:Raw material input costs for busbar and transformer assemblies have swung 40% since 2022, eroding fixed-price contract margins for mid-tier EPCs.
- Land scarcity in Tier-1 cities:Municipal zoning in Shenzhen and Guangzhou now restricts data center development to designated industrial parks with 100+ MW minimum thresholds, excluding sub-scale domestic players.
Strategic Opportunities
- Western China renewable corridors:Qinghai and Gansu provinces offer sub-0.25 yuan/kWh wind and solar power, attracting hyperscale operators seeking carbon-neutral compute for export-oriented cloud services.
- Prefabricated modular formats:Containerized and skid-mounted data halls are compressing deployment from 24 months to 8-12 months, opening procurement to logistics-optimized contractors outside traditional construction.
- Guangdong-Hong Kong-Macao Greater Bay Area integration:Cross-border data flow regulations are easing for Hong Kong-licensed operators, creating demand for facilities with dual-jurisdiction compliance architecture.
Industry Challenges
- Liquid cooling technician shortage:GB 50174-2017 certification requires specialized plumbing and refrigerant handling skills that fewer than 2,000 workers nationally currently possess, constraining build velocity.
- Legacy air-cooled asset stranding:Operators with 2018-2020 vintage facilities face 40% efficiency gaps versus new liquid-cooled designs, complicating portfolio refresh decisions under carbon accounting rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Data Center Construction Market |
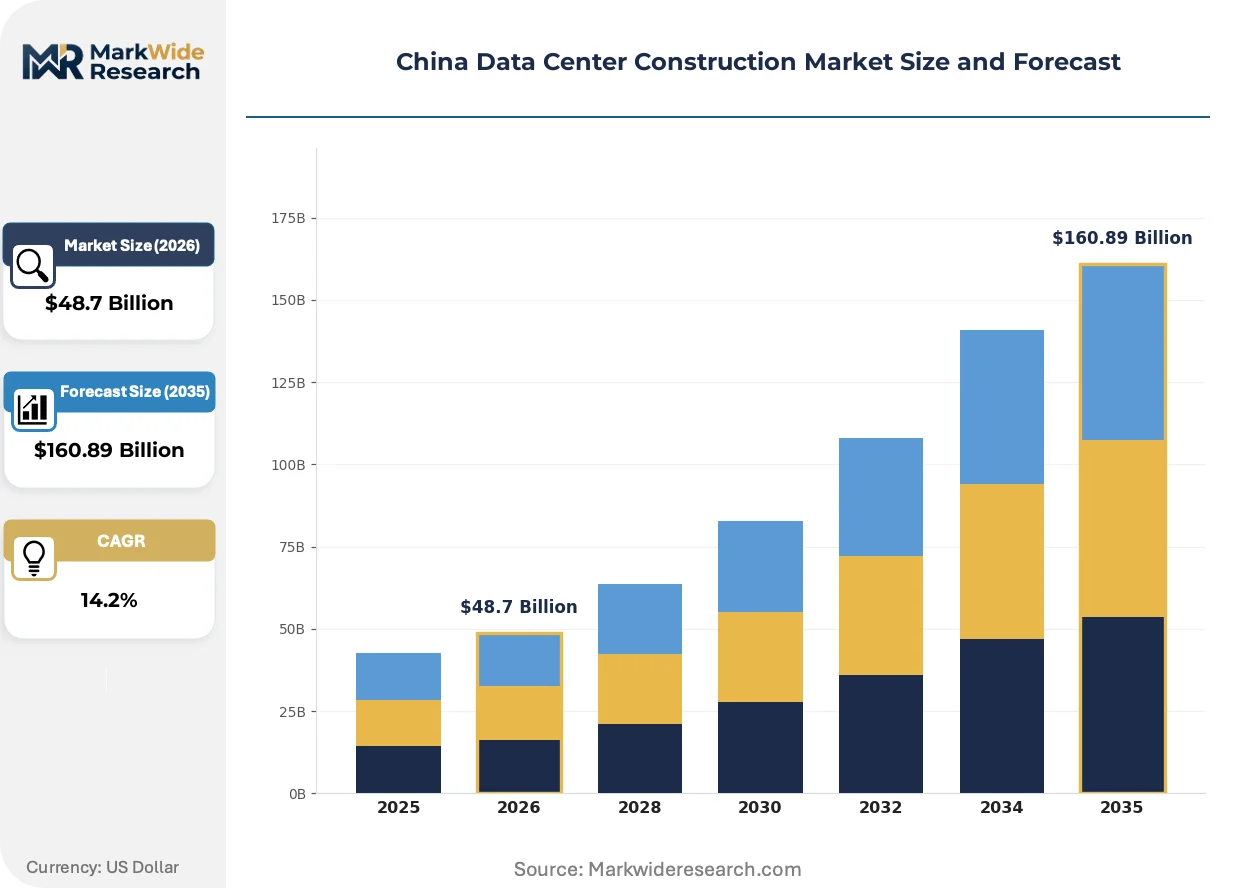
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $160.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Infrastructure Type: Modular, Containerized, Traditional, Hybrid Service Type: Design, Build, Management, Operations End User: Cloud Providers, Enterprises, Government, Telecom Cooling Technology: Air Cooling, Liquid Cooling, Hybrid Cooling, Others |
| Companies Covered | AECOM, DPR Construction, Aurecon Group, Goodman Group, Turner & Townsend, DSCO Group, Hensel Phelps, M+W Shanghai, Gammon Construction, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Data Center Construction Market Trends and Innovations
Construction methodology is pivoting from stick-built to factory-integrated modular systems, while regulatory pressure on embodied carbon and operational PUE is reshaping material specifications and mechanical architecture simultaneously.
Immersion cooling dielectric fluids are replacing traditional air-handling units in high-density compute zones. ByteDance and Huawei Cloud are piloting two-phase immersion at 50+ kW per rack in Inner Mongolia facilities. This thermal architecture is miniaturizing mechanical footprint requirements by 60% versus conventional chilled-water designs, enabling data hall construction on constrained urban parcels previously deemed unviable.
MIIT's 2023 GB 40879 energy efficiency standard mandates PUE below 1.3 for new facilities in eastern provinces, with annual compliance audits and public disclosure requirements. The regulation is disqualifying air-cooled designs from greenfield permitting in Jiangsu and Zhejiang. Operators are responding with direct-to-chip liquid cooling and waste heat recovery integration, often sourcing European heat pump technology to meet the threshold.
State-owned enterprises and hyperscalers are consolidating procurement under framework agreements with 3-5 year master service contracts, displacing project-by-project tendering. This concentration is squeezing mid-tier contractors unable to scale balance sheets to 500+ million yuan bonding capacity. The shift is most visible in Beijing and Shanghai, where China Telecom and China Unicom have moved 80% of new build volume to pre-qualified design-build partners.
China Data Center Construction Market Segmentation
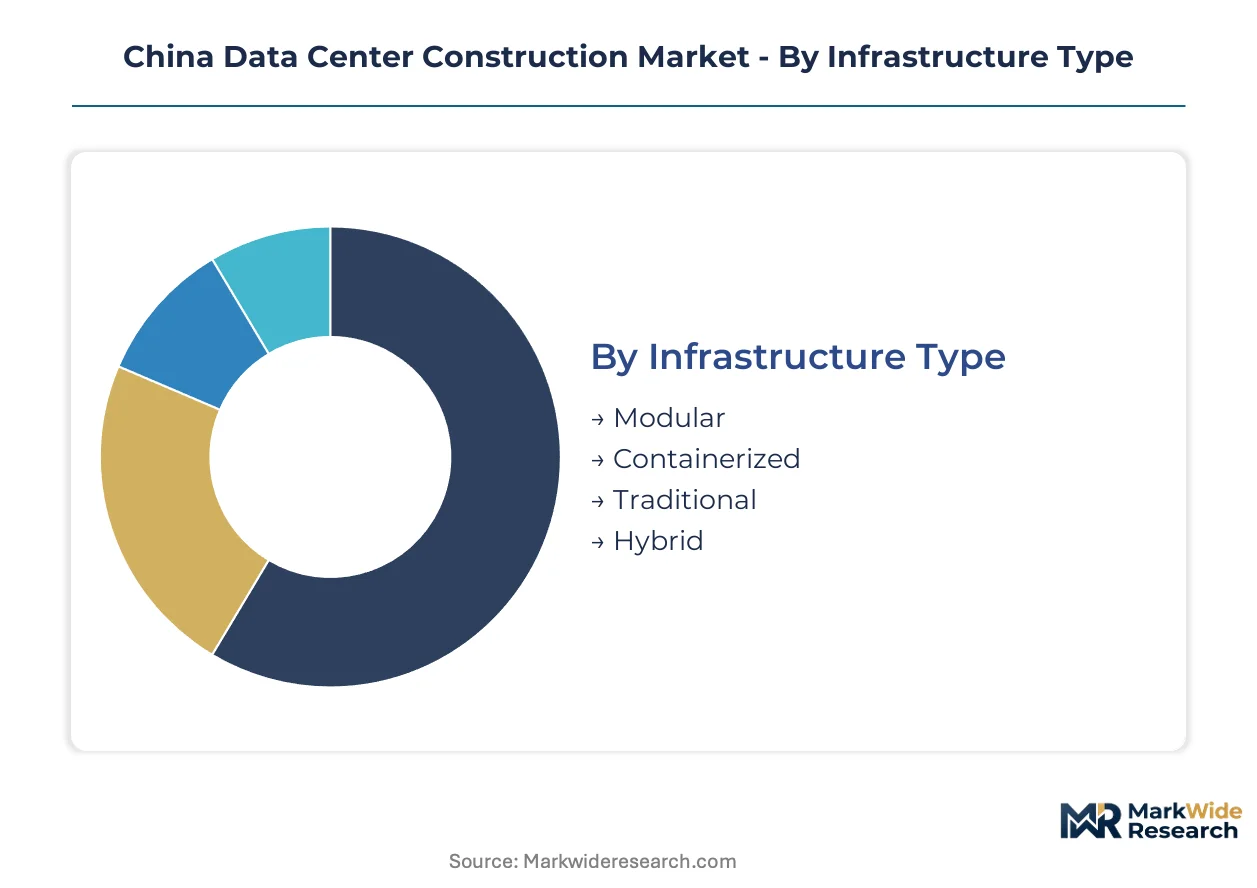
Segmentation in the China data center construction market reveals distinct procurement channels and margin structures. Infrastructure format and cooling technology decisions now flow through hyperscale framework agreements rather than project-by-project tendering, reshaping contractor qualification requirements.
Infrastructure Type:
Channel mix varies sharply by deployment speed requirements, with hyperscalers routing urgent capacity needs through modular specialists while traditional EPCs retain legacy enterprise relationships.
- Modular:Prefabricated data hall components assembled on-site under factory quality control. Demand clusters in Shanghai and Shenzhen where land scarcity compresses deployment timelines to 8-12 months versus 24 months for stick-built alternatives.
- Containerized:Fully integrated skid-mounted systems delivered as complete units. Cloud providers in Beijing deploy these for rapid 50+ MW expansions where grid interconnection queues already stretch 18-24 months and construction acceleration offsets permitting delays.
- Traditional:Conventional stick-built concrete and steel structures with on-site mechanical integration.
- Hybrid:Blended approaches combining permanent core infrastructure with modular expansion wings.
By volume, Traditional leads. By growth pace, Modular is expanding most quickly.
Service Type:
Cost tier stratification separates premium design-build integrators from commodity construction-only contractors, with bonding capacity above 500 million yuan becoming the threshold for hyperscale participation.
- Design:Architectural and engineering services encompassing electrical, mechanical, and structural planning. MIIT's GB 50174-2017 certification requirements are collapsing the field of qualified domestic designers, concentrating premium contracts with international-experienced firms.
- Build:Physical construction execution including civil works, MEP installation, and commissioning. Raw material volatility in copper and electrical steel has swung input costs 40% since 2022, eroding fixed-price margins for mid-tier EPCs lacking upstream supply agreements.
- Management:Owner's representative and project oversight services.
- Operations:Post-handover facility management and maintenance contracts.
By revenue contribution, Build dominates current procurement. By margin expansion, Design-build integration is climbing the fastest.
End User:
Application concentration shapes facility specifications, with AI training clusters demanding cleanroom-adjacent reliability while enterprise colocation accepts standard Tier III architectures.
- Cloud Providers:Hyperscale operators including Alibaba Cloud, Tencent Cloud, and ByteDance commissioning 50+ MW facilities. These customers consolidate procurement under 3-5 year framework agreements, displacing project-by-project tendering and squeezing contractors unable to scale balance sheets.
- Enterprises:Private corporations building captive data infrastructure. Financial services and semiconductor foundries in the Yangtze River Delta drive demand for high-reliability construction with specialized mechanical redundancy.
- Government:State-owned entities and public sector facilities.
- Telecom:China Telecom and China Unicom infrastructure deployments.
By project count, Telecom maintains the largest pipeline. By contract value concentration, Cloud Providers are gaining share fastest.
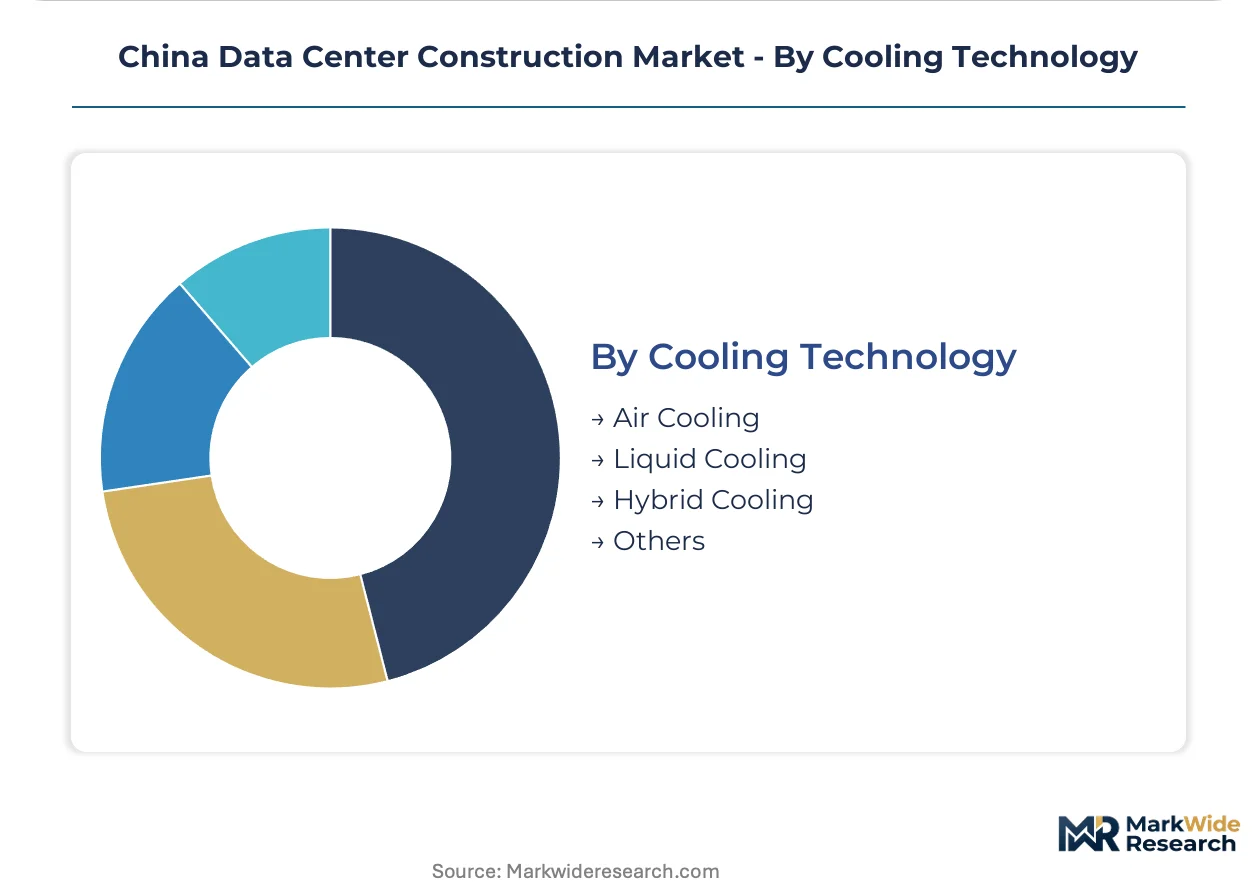
Cooling Technology:
Supply concentration in certified mechanical integrators is producing a two-tier market, with liquid-cooling specialists commanding premium pricing power against legacy air-cooled contractors facing obsolescence.
- Liquid Cooling:Direct-to-chip and immersion architectures using dielectric fluids or water-glycol mixtures. ByteDance and Huawei Cloud pilot two-phase immersion at 50+ kW per rack in Inner Mongolia, miniaturizing mechanical footprints by 60% versus chilled-water designs.
- Air Cooling:Traditional air-handling units and precision HVAC systems. Legacy facilities from 2018-2020 face 40% efficiency gaps versus new liquid-cooled designs, complicating portfolio refresh decisions under MIIT carbon accounting rules.
- Hybrid Cooling:Combined air and liquid systems for mixed-density workloads.
- Others:Emerging thermal management approaches including phase-change materials and waste heat recovery integration.
By installed base, Air Cooling retains dominance. By regulatory mandate alignment, Liquid Cooling shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale cloud operators and state-owned telecoms concentrate procurement in three coastal megacity clusters where land scarcity and power constraints favor modular construction formats.
Yangtze River Delta
Alibaba Cloud and Tencent Cloud drive 50+ MW facility commissioning across Shanghai and Jiangsu province. MIIT's GB 40879 standard mandates PUE below 1.3 for new builds, disqualifying air-cooled designs from greenfield permitting in Jiangsu and Zhejiang. Suzhou and Hangzhou host the densest concentration of liquid-cooled hyperscale halls under active construction.
Pearl River Delta
ByteDance and Huawei Cloud anchor demand for high-density AI training infrastructure in Shenzhen and Guangzhou. Municipal zoning restricts data center development to designated industrial parks with 100+ MW minimum thresholds, excluding sub-scale domestic players. Dongguan and Huizhou emerge as secondary sites for facilities requiring dual-jurisdiction compliance architecture.
Beijing-Tianjin-Hebei
China Telecom and China Unicom consolidate procurement under framework agreements with pre-qualified design-build partners. Grid connection approvals now stretch 18-24 months, freezing project starts regardless of capital availability. Zhangjiakou and Langfang absorb overflow demand from core Beijing restrictions.
Western China Renewable Corridors
Qinghai and Gansu provinces attract hyperscale operators seeking carbon-neutral compute with sub-0.25 yuan/kWh wind and solar power. Two-phase immersion cooling pilots at 50+ kW per rack proceed in Inner Mongolia facilities. Xining and Lanzhou function as primary hubs for export-oriented cloud services.
Sichuan-Chongqing
Chengdu anchors semiconductor-linked data hall construction for domestic chip foundries requiring cleanroom-adjacent reliability. Provincial carbon intensity benchmarks gatekeep project viability alongside power grid interconnection queues. Chongqing's western logistics hub status supports containerized modular deployment to coastal markets.
China Data Center Construction Market Competitive Landscape
Player mix skews toward international-experienced design-build integrators and specialized mechanical contractors with GB 50174-2017 certification. The field compresses around two dominant tiers: premium contractors with 500+ million yuan bonding capacity capturing hyperscale framework agreements, and mid-tier EPCs facing margin erosion from raw material volatility. Strategic archetypes include liquid-cooling mechanical specialists, modular prefabrication firms, and cleanroom-adjacency contractors. Competitive moves center on backward integration into electrical and mechanical systems, and geographic expansion to Western China renewable corridors.
Among international-experienced design-build firms, DPR Construction, M+W Shanghai, and Gammon Construction occupy positions across the premium tier. DPR Construction anchors design-build contracts in Tier-1 cities through international hyperscale credentials. M+W Shanghai exemplifies the high-reliability specialist archetype with cleanroom-adjacent expertise for semiconductor-linked facilities. Gammon Construction represents mechanical systems integration strength through in-house production of electrical and plumbing assemblies.
| Leading Market Players |
|---|
| AECOM |
| DPR Construction |
| Aurecon Group |
| Goodman Group |
| Turner & Townsend |
| DSCO Group |
| Hensel Phelps |
| M+W Shanghai |
| Gammon Construction |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four-month grid interconnection queues in Beijing and Shanghai compress contractor pricing power while concentrating procurement leverage among hyperscalers with 500+ million yuan bonding capacity. This lead-time bottleneck reshapes supply chain sourcing patterns as operators accelerate modular formats to offset permitting delays.
Pricing Analysis
Cost-plus contracts with copper and electrical steel indexation dominate EPC procurement, insulating mid-tier contractors from 40% raw material volatility swings. Price differentiation separates GB 50174-2017 certified design-build integrators from uncertified construction-only vendors. Pricing pressure stems from hyperscaler framework agreements consolidating 80% of Beijing and Shanghai volume. Cloud providers exhibit lowest price sensitivity; sub-scale domestic players face acute margin compression.
Supply Chain Analysis
Yangtze River Delta port congestion and inland logistics chokepoints constrain dielectric fluid and precision HVAC component delivery to liquid cooling projects. Manufacturing concentrates in China, Germany, and Japan for immersion cooling systems, electrical steel, and semiconductor-grade cleanroom materials. Supply chain risk centers on single-source dependency for specialized refrigerant handling equipment. Distribution runs through state-owned telecom procurement frameworks and hyperscale master service agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China data center construction functions as a regulatory entrenchment market where GB 50174-2017 certification creates switching costs that lock out unqualified competitors. This structural moat rewards early certification investment with multi-year framework agreement visibility.
For Market Incumbents: Secure liquid cooling technician certification pipelines to address the sub-2,000 certified worker shortage constraining national build velocity. Anchor framework agreement renewals by integrating backward into electrical and mechanical systems production. Defend against modular prefabrication entrants by compressing design-build handover timelines below 12 months. For New Entrants and Emerging Players: Differentiate on Western China renewable corridor deployment speed where sub-0.25 yuan/kWh power attracts carbon-neutral compute demand. Target Qinghai and Gansu provinces for containerized modular formats that bypass 18-24 month coastal grid queues. Pursue logistics-optimized contracting models that compress deployment from 24 months to 8-12 months. For Investors and Strategic Acquirers: Carve-out targets emerge from state-owned enterprise construction subsidiaries seeking non-core asset divestiture in Tier-2 and Tier-3 cities. Long-term viability favors mechanical integrators with captive supply of liquid cooling components and cleanroom-adjacent expertise. Monitor provincial carbon intensity benchmark tightening as the inflection signal for accelerated liquid cooling retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| GB 50174-2017 Certification Investment | MIIT enforcement collapses qualified contractor field, concentrating premium contracts with certified design-build integrators. |
| Liquid Cooling Technician Workforce Development | Specialized plumbing and refrigerant handling skills shortage constrains build velocity for 50+ MW hyperscale facilities. |
| Western China Renewable Corridor Expansion | Qinghai and Gansu wind-solar power pricing attracts carbon-neutral compute demand from export-oriented cloud operators. |
| Modular Prefabrication Format Adoption | Containerized systems compress deployment timelines from 24 months to 8-12 months, offsetting coastal grid interconnection delays. |
| Backward Integration into Electrical Systems | In-house production of busbar and transformer assemblies insulates margins from 40% copper and electrical steel volatility. |
Research Methodology
A spread of perspectives from hyperscale cloud procurement officers, state-owned telecom infrastructure planners, GB 50174-certified mechanical contractors, and provincial MIIT regulatory officials converged on the working assumptions. Primary fieldwork combined with secondary validation from MIIT policy circulars, SAMR standard enforcement records, hyperscaler capital expenditure disclosures, and provincial power grid interconnection databases. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume and value estimates.
Segmentation dimensions modeled include infrastructure format, cooling technology architecture, service type integration level, and end-user procurement channel across the projection horizon. CAGRs derived from facility commissioning timelines, power density evolution curves, and regulatory compliance cost trajectories. Forecast inputs incorporated liquid cooling adoption rates and provincial carbon intensity benchmark enforcement schedules.
Material uncertainties — grid interconnection queue extensions, raw material cost spikes, and MIIT standard revision timing — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and hyperscaler capital commitment continuity. Practitioners should keep alternative scenarios live as dual carbon goal implementation pace and Western China renewable power availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Poland Data Center Rack Market
Data Center Infrastructure
Europe Containerized Data Center Market
Data Center Infrastructure
Virtualized Data Center Market
Data Center Infrastructure
Indonesia Enterprise Network Infrastructure Market
Data Center Infrastructure
South Africa Data Center Construction Market
Data Center Infrastructure
Ireland Data Center Market
Data Center Infrastructure
Global Hyper-Converged Infrastructure Market
Data Center Infrastructure
Data Center Colocation and Managed Hosting Services Market
Data Center Infrastructure
Australia Data Center Rack Market
Data Center Infrastructure
Belgium Data Center Market
Data Center Infrastructure
Malaysia Data Center Storage Market
Data Center Infrastructure
China Data Center Power Market
Data Center Infrastructure
Japan Data Center Rack Market
Data Center Infrastructure
IT Infrastructure Market
Data Center Infrastructure
Europe Data Center Power Market
Data Center Infrastructure
Singapore Data Center Rack Market