
 Singapore Data Center Server Market | 2026-2036
Singapore Data Center Server Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Data Center Server Market Insights
Singapore's Green Mark for Data Centres certification is recalibrating procurement criteria across the island-state's server market. Dell Inc. leverages its liquid-cooled PowerEdge portfolio to anchor sustainability-led tenders, while HP Enterprise competes through modular architectures that slash power usage effectiveness ratios. Super Micro Computer, Inc. specializes in high-density configurations purpose-built for tropical climates, extending its footprint among local colocation operators.
Singapore data center servers are enterprise-grade compute platforms engineered for 24/7 operation in high-humidity, tropical environments, typically rated for ambient temperatures up to 35°C and integrating redundant power supplies with N+1 resilience. Their primary purpose is to host mission-critical workloads for financial trading, sovereign cloud, and regional content delivery networks. Rack servers dominate hardware shipments due to hyperscale facility standardization, while blade servers capture premium margin pools in space-constrained downtown deployments. Hybrid deployment models now outpace pure on-premises installations as banks and government agencies pursue workload portability between private cages and public cloud zones.
IMDA's data centre energy efficiency standards and BCA Green Mark requirements shape server procurement through mandated power usage effectiveness thresholds and carbon disclosure obligations. The country's national cybersecurity regulator enforces supply chain assurance protocols that restrict certain foreign-origin firmware, tightening vendor qualification processes. Stakeholders must monitor how Singapore's carbon tax trajectory and land-use constraints reshape the economics of refreshes versus relocations to neighboring Johor or Batam facilities.
Market Dynamics
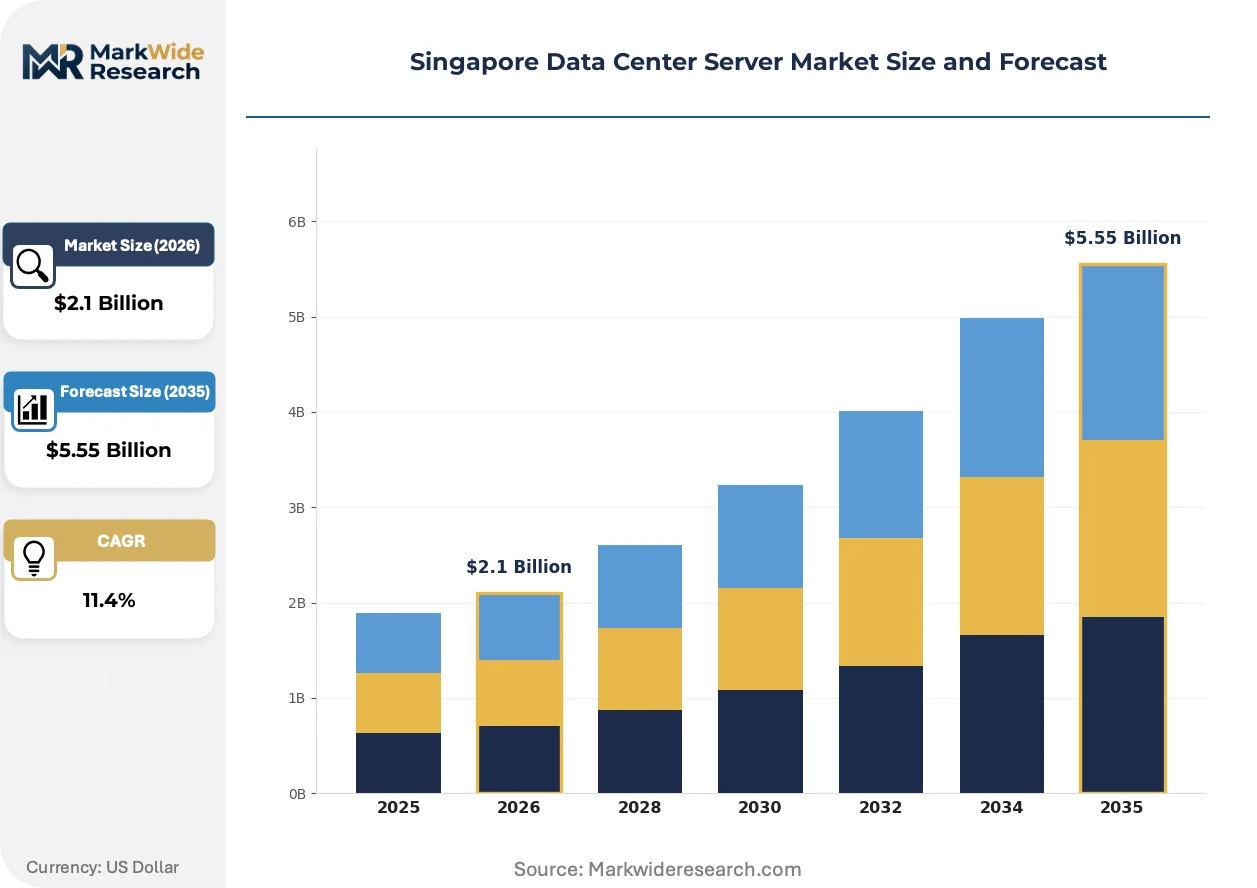
Singapore's land scarcity and carbon tax regime are compressing data center economics, forcing server procurement toward liquid-cooled, high-density configurations that maximize compute per square meter while staying within IMDA energy efficiency mandates.
Growth Catalysts
- Digital banking expansion:Financial services firms are scaling server infrastructure to support real-time payment rails and algorithmic trading platforms, driving enterprise-grade rack deployments.
- BCA Green Mark certification:The building efficiency framework rewards facilities that deploy servers with power usage effectiveness below 1.6, accelerating refreshes of legacy air-cooled estates.
- Hyperscale clustering in Jurong:Concentrated demand from cloud operators in this western enterprise zone creates procurement scale that pulls through direct liquid cooling and modular architectures.
Market Restraints
- Land-use moratoriums:Singapore's temporary suspension of new data center approvals through 2022-2024 has created a supply bottleneck that limits greenfield server deployment opportunities.
- Copper and rare earth volatility:Server power distribution and magnet components face input cost pressure from concentrated Chinese processing capacity.
- Thermal engineering constraints:Ambient humidity levels above 80% year-round degrade conventional air-cooled server reliability, requiring specialized tropical-rated designs that carry cost premiums.
Strategic Opportunities
- Sovereign cloud mandates:Government agencies must retain sensitive data onshore, creating captive demand for secure private cage deployments with certified supply chains.
- Liquid-to-chip cooling convergence:Integration of direct liquid cooling with high-wattage GPU servers enables 50kW+ rack densities that unlock stranded power capacity in existing facilities.
- Johor cross-border expansion:Malaysian enterprise zones 30 kilometers north offer land and power arbitrage for Singapore-headquartered operators seeking workload overflow capacity.
Industry Challenges
- Certification timeline compression:BCA Green Mark and IMDA efficiency audits now require 18-24 month pre-commitment cycles, delaying revenue recognition for server deployments.
- Legacy infrastructure integration:Hybrid cloud architectures force interoperability between 10-15 year-old on-premises estates and API-native colocation environments, complicating workload orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Data Center Server Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $5.55 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rack Servers, Blade Servers, Tower Servers, Modular Servers Deployment Model: On-Premises, Colocation, Hybrid, Cloud End User: IT & Telecom, BFSI, Government, Healthcare Service Type: Managed Services, Maintenance & Support, Consulting Services, Integration Services |
| Companies Covered | Dell Inc., Fujitsu Limited, HP Enterprise, Lenovo Group Limited, Super Micro Computer, Inc., Cisco Systems, Inc., Oracle Corporation, Huawei Technologies Co., Ltd., Kingston Technology Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Data Center Server Market Trends and Innovations
Server technology in Singapore is pivoting from air-cooled standardization toward liquid-cooled specialization, driven by thermal physics, regulatory efficiency floors, and the island-state's unique constraints on physical expansion.
Direct liquid cooling is integrating cold plate and immersion technologies to manage 500W+ CPU and GPU thermal loads in tropical ambient conditions. Hyperscale operators in Changi and Jurong are deploying these systems at rack scale, while enterprise colocation customers pilot smaller configurations. This thermal architecture is integrating with building-level heat recovery systems to satisfy BCA Green Mark requirements for waste heat utilization.
IMDA's data centre energy efficiency standards are tightening power usage effectiveness thresholds and mandating granular carbon disclosure for facilities above 500kW capacity. The regulation forces server procurement toward equipment with embedded power telemetry and real-time efficiency monitoring. Financial services and government verticals face the steepest compliance curves, with procurement teams now requiring vendor proof of tropical-environment reliability testing.
Workload portability contracts are displacing traditional colocation leases as banks and regulators demand contractual flexibility between private cages and public cloud zones. This hybrid consumption model fragments server ownership between capital-intensive on-premises refresh cycles and operational expenditure-based cloud commitments. The shift is most visible in the financial services vertical, where Monetary Authority of Singapore guidelines encourage multi-cloud resilience architectures.
Singapore Data Center Server Market Segmentation
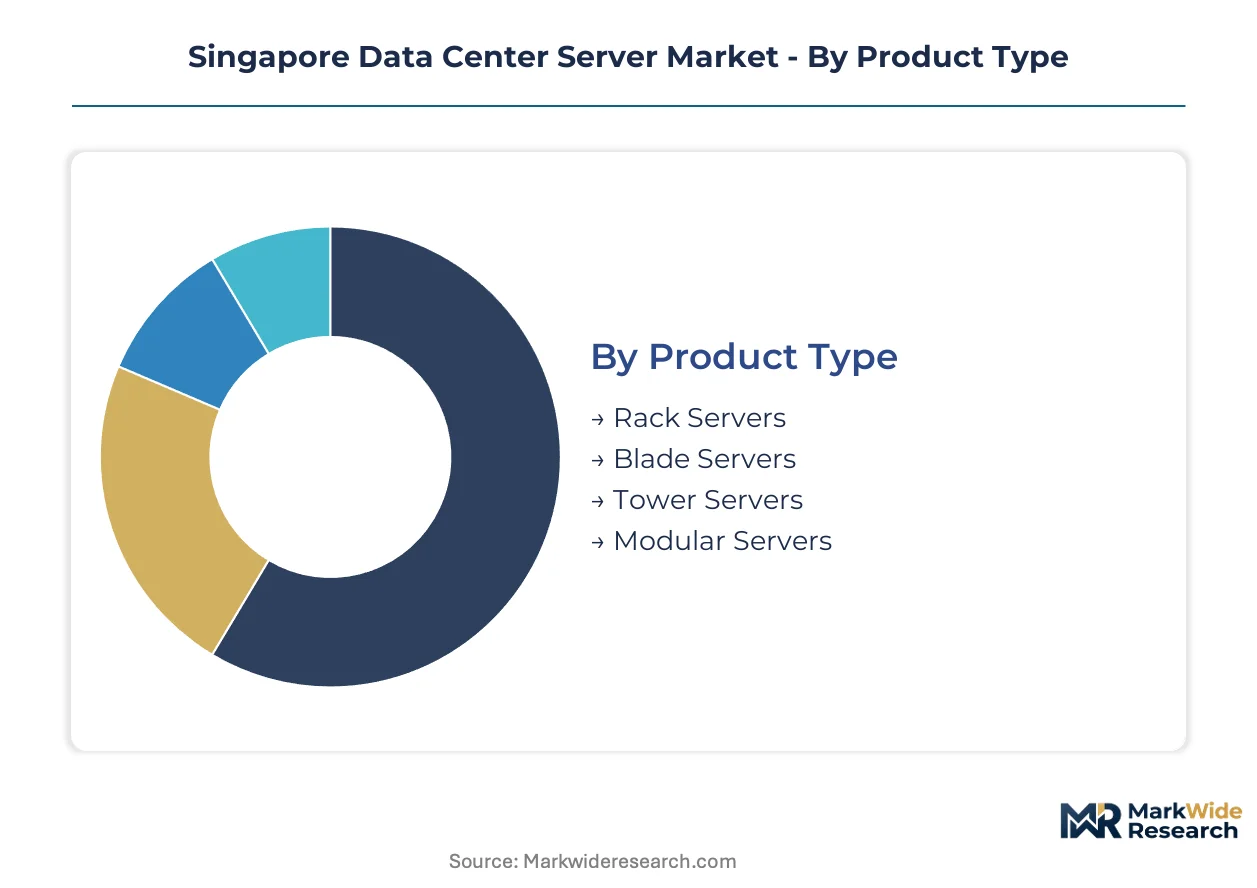
Server procurement patterns in Singapore diverge sharply between hyperscale cloud operators and regulated enterprises, with thermal constraints and BCA Green Mark compliance reshaping hardware selection across every category. Understanding these segment boundaries reveals where liquid-cooled premium configurations command margin versus where standardized rack units dominate volume.
Product Type:
Rack servers anchor volume shipments while blade configurations capture premium pricing in space-constrained deployments.
- Rack Servers:Standardized 1U-4U enclosures rated for 35°C ambient operation dominate hyperscale procurement in Jurong and Changi facilities. Financial services firms drive demand for N+1 redundant power configurations as algorithmic trading platforms require 99.999% availability.
- Blade Servers:High-density chassis integrating shared power and cooling infrastructure maximize compute per square meter in downtown colocation cages where land costs peak. Government agencies favor these for sovereign cloud deployments requiring physical security certification.
- Tower Servers:Standalone pedestal units serve small enterprise edge deployments and disaster recovery sites with sub-10kW power footprints.
- Modular Servers:Disaggregated compute sleds enable independent refresh cycles for CPU, memory, and storage resources in facilities pursuing circular economy certifications.
Today's leader: Rack Servers. Tomorrow's challenger: Modular Servers.
Deployment Model:
Capital intensity separates ownership models, with hybrid architectures now displacing pure on-premises estates among regulated verticals.
- On-Premises:Fully owned server infrastructure in dedicated facilities persists among banks meeting Monetary Authority of Singapore data sovereignty requirements. These deployments carry 5-7 year refresh cycles and dedicated operations staff.
- Colocation:Leased cage or rack space in certified facilities allows enterprises to offload physical security and cooling engineering while retaining hardware ownership. Keppel Data Centres and ST Telemedia operate the island-state's largest colocation campuses.
- Hybrid:Workload portability contracts split processing between private cages and public cloud zones, with orchestration layers managing burst capacity. This model is expanding most quickly among insurers and asset managers.
- Cloud:Pure operational expenditure models through AWS, Azure, and Google Cloud regions eliminate capital commitment but limit customization for low-latency trading workloads.
Deployment gravity centers on hybrid configurations as regulated industries balance sovereignty with elasticity.
End User:
Vertical-specific compliance obligations fragment procurement criteria across cooling density, supply chain certification, and cybersecurity assurance.
- IT & Telecom:Content delivery networks and regional cloud operators drive the highest rack density requirements, with 50kW+ liquid-cooled configurations now standard in new Changi builds.
- BFSI:Banks face dual pressure from real-time payment rails and MAS cyber resilience guidelines, forcing refreshes of legacy air-cooled estates toward tropical-rated, telemetry-embedded servers.
- Government:IMDA's data centre energy efficiency standards and supply chain assurance protocols restrict vendor qualification to firmware-audited equipment.
- Healthcare:Patient data protection requirements under the Personal Data Protection Act limit deployment flexibility, with most infrastructure remaining on-premises or in certified private cages.
BFSI verticals currently drive premium server spend. Healthcare represents the most constrained expansion pathway.
Service Type:
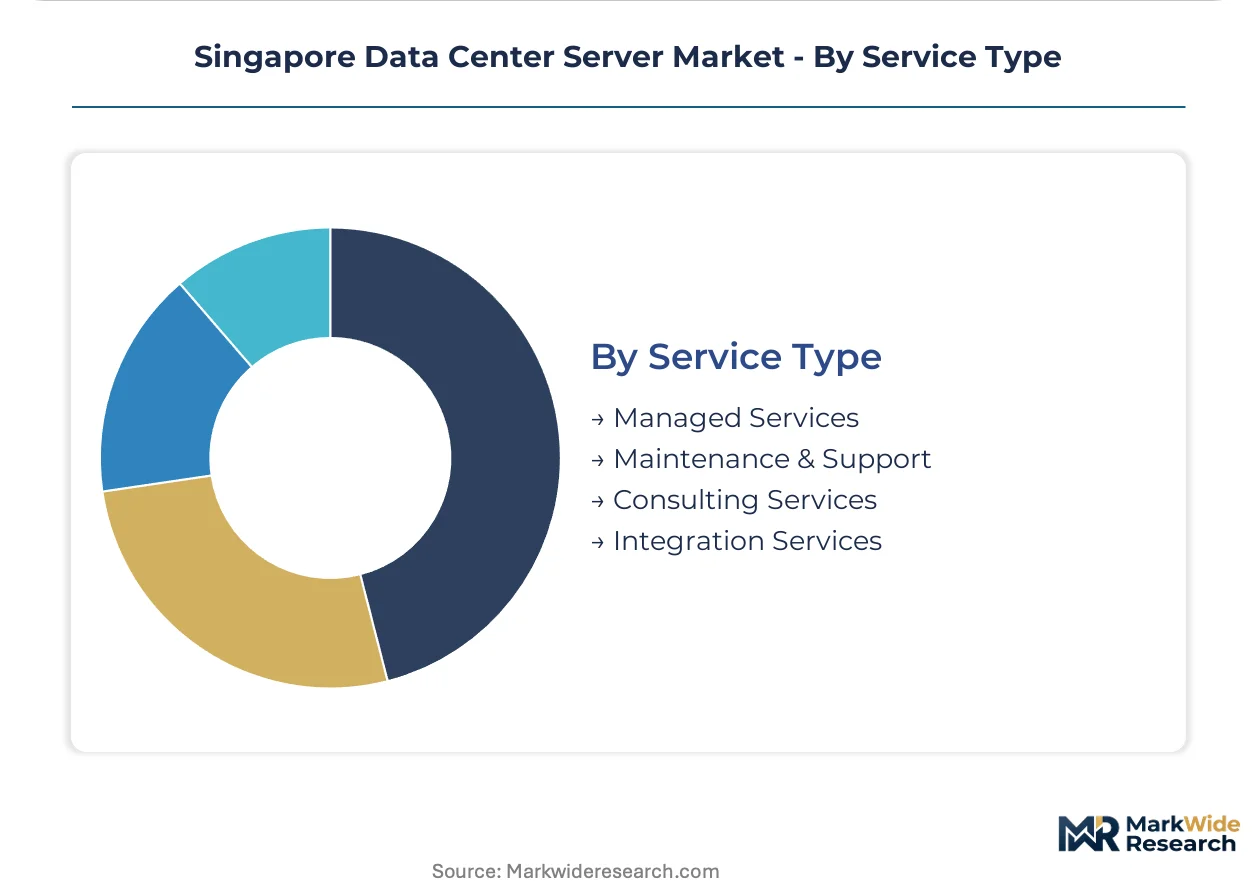
Operational complexity shifts value capture from hardware margins toward lifecycle management and integration capabilities.
- Managed Services:24/7 remote monitoring, patch management, and capacity planning contracts reduce in-house operations burden for enterprises lacking tropical data center engineering expertise.
- Maintenance & Support:Next-business-day and 4-hour response SLAs for critical financial trading infrastructure command substantial premiums over standard depot service.
- Consulting Services:Thermal engineering and BCA Green Mark compliance advisory helps facilities optimize server placement for heat recovery integration.
- Integration Services:Hybrid cloud orchestration and legacy estate migration projects accelerate as banks dismantle 10-15 year-old mainframe environments.
Managed services currently capture the largest service attach rate. Integration services face the steepest demand acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's data center server industry traces its origins to the island-state's emergence as a submarine cable hub during the 1990s internet buildout. Early carrier hotels in the Central Business District seeded the tropical-rated server expertise that now defines procurement standards across Southeast Asia. This historical foundation shapes how neighboring markets calibrate their own infrastructure requirements.
Malaysia
Johor's Iskandar Puteri corridor absorbs Singapore overflow demand as land and power arbitrage attract hyperscale operators seeking expansion capacity. The Malaysian Investment Development Authority offers tax incentives for data center investments exceeding MYR 500 million. Nusajaya Tech Park now hosts facilities from Singapore-headquartered operators running liquid-cooled server deployments at 40% lower land costs than Jurong equivalents.
Indonesia
Batam's free trade zone leverages submarine cable proximity to Singapore for low-latency financial workloads requiring tropical-rated hardware. Indonesia's Ministry of Communication and Informatics enforces data localization requirements through Government Regulation No. 71 of 2019. The Nongsa Digital Park cluster concentrates server deployments for Indonesian banks maintaining disaster recovery nodes within 50 kilometers of Singapore primary sites.
Thailand
Bangkok's eastern corridor attracts regional content delivery networks seeking Thai-language edge capacity with Singapore-standard reliability specifications. The Digital Economy Promotion Agency certifies data centers through its DEPA Tier III program modeled on Singapore's IMDA standards. Amata City Industrial Estate now hosts facilities specifying tropical-rated servers identical to Jurong procurement criteria.
Vietnam
Ho Chi Minh City's Thu Duc district emerges as an alternative for fintech operators requiring ASEAN presence outside Singapore's land-constrained market. Vietnam's Ministry of Information and Communications implements cybersecurity law provisions restricting cross-border data flows for specific categories. The Saigon Hi-Tech Park draws colocation investment specifying server hardware tested to 35°C ambient standards developed for Singapore deployment.
Philippines
Manila's Bonifacio Global City attracts business process outsourcing operators requiring server infrastructure for voice and data workloads serving Singapore-headquartered clients. The Department of Information and Communications Technology promotes data center investment through fiscal incentives under the CREATE Act. Facilities in Taguig now specify N+1 redundant power configurations matching Monetary Authority of Singapore availability requirements for financial services workloads.
Singapore Data Center Server Market Competitive Landscape
Capital-heavy integrated manufacturers compete with asset-light design specialists across Singapore's server procurement ecosystem. Dell Inc. and HP Enterprise anchor the consolidated tier through direct liquid cooling portfolios and modular architectures, while Super Micro Computer, Inc. occupies a specialist position in high-density tropical configurations. The vendor base stratifies across three archetypes: integrated systems vendors with full-stack thermal engineering, modular specialists optimizing power usage effectiveness ratios, and component-agnostic assemblers serving price-sensitive colocation operators. Competitive dynamics center on BCA Green Mark certification pre-qualification and 18-24 month audit timeline navigation.
Among US-based systems vendors, Dell Inc., HP Enterprise, and Super Micro Computer, Inc. exemplify contrasting approaches to Singapore's regulatory environment. Dell Inc. represents the integrated engineering archetype with liquid-cooled PowerEdge portfolios purpose-built for tropical ambient operation. HP Enterprise occupies the modular architecture position emphasizing disaggregated refresh cycles aligned with circular economy certifications. Super Micro Computer, Inc. anchors the high-density specialization tier with configurations engineered specifically for 80%+ humidity environments. These three vendors collectively illustrate how procurement criteria fragment across thermal performance, sustainability credentialing, and supply chain assurance protocols enforced by Singapore's national cybersecurity regulator.
| Leading Market Players |
|---|
| Dell Inc. |
| Fujitsu Limited |
| HP Enterprise |
| Lenovo Group Limited |
| Super Micro Computer, Inc. |
| Cisco Systems, Inc. |
| Oracle Corporation |
| Huawei Technologies Co., Ltd. |
| Kingston Technology Corporation |
| Others |
Pricing and Supply Chain Analysis
Captive integration into liquid-cooled thermal engineering anchors vendor pricing power in Singapore's data center server market, with Dell Inc., HP Enterprise, and Super Micro Computer commanding premium positioning through in-house cold plate and immersion technology development that locks out modular assemblers from BCA Green Mark-certified tenders.
Pricing Analysis
Three-tier pricing structure across liquid-cooled premium, air-cooled standard, and refurbished economy levels segments procurement budgets across hyperscale operators and regulated enterprises. Price differentiation centers on BCA Green Mark certification tier and tropical-environment reliability testing depth, with certified configurations carrying substantial premiums over generic rack units. Cost compression in air-cooled standard tiers is intensifying because IMDA efficiency mandates accelerate legacy estate obsolescence. Financial services firms exhibit lowest price sensitivity due to Monetary Authority of Singapore availability requirements, while regional colocation operators in Jurong drive hardest bargain on volume procurement.
Supply Chain Analysis
Singapore's national cybersecurity regulator enforces supply chain assurance protocols that reshape component sourcing toward firmware-audited vendors with domestic technical support presence. Server manufacturing concentrates in Taiwan, China, and Malaysia, with Nusajaya Tech Park emerging as assembly hub for Singapore-bound liquid-cooled configurations. Critical dependencies span copper power distribution busbars, rare earth magnet components for cooling pumps, and tropical-grade conformal coatings. Single-source vulnerability in Chinese rare earth processing capacity exposes lead times to geopolitical friction. Distribution runs through direct vendor relationships with hyperscale operators and authorized distributor networks serving enterprise colocation customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore data center server procurement functions as a geographic-arbitrage play between the city-state's land-constrained, carbon-taxed environment and Johor's 40% lower facility costs across the strait.
For Market Incumbents: To counter modular specialists encroaching on standardized rack volumes, Dell Inc. and HP Enterprise should deepen captive integration into direct liquid cooling component manufacturing, securing cold plate supply chains against rare earth volatility while accelerating BCA Green Mark pre-certification timelines to compress 18-24 month audit cycles.
For New Entrants and Emerging Players: The 35-50% price-point gap between liquid-cooled premium and air-cooled refurbished tiers creates entry space for tropical-rated modular server specialists targeting mid-market financial services firms in downtown colocation cages. New entrants should prioritize ST Telemedia and Keppel Data Centres partnership channels over direct hyperscale pursuit.
For Investors and Strategic Acquirers: Roll-up economics work for thermal engineering specialists because IMDA efficiency mandates and BCA Green Mark requirements fragment vendor qualification across firmware auditing, tropical testing, and heat recovery integration capabilities that scale poorly. Investors should monitor Johor cross-border deployment announcements as inflection signal for Singapore facility saturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct Liquid Cooling Portfolio Expansion | BCA Green Mark certification thresholds below 1.6 PUE mandate cold plate and immersion technology deployment at rack scale. |
| Johor Cross-Border Facility Development | Malaysian land and power arbitrage enables Singapore-headquartered operators to capture overflow workload demand. |
| Firmware Supply Chain Assurance Program | Cybersecurity regulator protocols restrict vendor qualification to audited component origins, tightening procurement pools. |
| Modular Architecture Standardization | Disaggregated compute sleds align with circular economy certifications through independent CPU, memory, and storage refresh cycles. |
| Heat Recovery System Integration | Building-level thermal reuse satisfies BCA Green Mark waste heat utilization requirements for new facility approvals. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center engineering directors, colocation procurement managers, BCA Green Mark auditors, IMDA compliance officers, and hyperscale facility operators with secondary validation through IMDA energy efficiency disclosures, BCA certification databases, hyperscaler capital expenditure filings, and regional customs import records for server equipment. Bottom-up facility-level capacity modeling and top-down market sizing triangulated volume estimates.
Comparable-period anchoring linked projection assumptions to historical deployment patterns across the analysis window, with segmentation modeling across product type, deployment model, end-user vertical, and service type dimensions. CAGRs derived from facility pipeline tracking and refresh cycle analysis incorporated tropical-environment reliability testing adoption curves and liquid-cooled rack density trajectories as industry-specific inputs.
The model assumes a particular technology adoption path; alternative pathways for immersion cooling versus cold plate architectures would alter the outlook if heat recovery integration costs shift materially. Forecasts reflect assumptions around IMDA efficiency threshold enforcement intensity and Johor infrastructure buildout pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Infrastructure
Japan Data Center Power Market
Data Center Infrastructure
South America Data Center Market
Data Center Infrastructure
Israel Data Center Server Market
Data Center Infrastructure
Sweden Data Center Physical Security Market
Data Center Infrastructure
Global Containerized Data Center Market
Data Center Infrastructure
Paris Data Center Market
Data Center Infrastructure
Netherlands Data Center Market
Data Center Infrastructure
Indonesia Data Center Server Market
Data Center Infrastructure
Australia Data Center Physical Security Market
Data Center Infrastructure
Saudi Arabia Data Center Construction Market
Data Center Infrastructure
Converged Infrastructure Management Market
Data Center Infrastructure
Canada Data Center Storage Market
Data Center Infrastructure
South Korea Data Center Market
Data Center Infrastructure
High Availability Server Market
Data Center Infrastructure
Advanced Data Center Infrastructure Market
Data Center Infrastructure
Europe Containerized Data Center Market