
 Automotive Power Semiconductor Market | 2026-2036
Automotive Power Semiconductor Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Power Semiconductor Market Intelligence
Procurement influence for power semiconductors is rotating from traditional Tier-1 suppliers towards direct specification by automotive OEMs. This shift allows vehicle manufacturers greater control over powertrain and battery management system performance. Infineon Technologies AG leverages its extensive portfolio to secure long-term OEM agreements. STMicroelectronics differentiates through its focus on advanced Silicon Carbide (SiC) and Gallium Nitride (GaN) technologies for EV applications.
Automotive power semiconductors are electronic components designed to manage high-voltage and high-current applications within a vehicle's electrical system. These devices, often operating at voltages above 600V, are critical for controlling energy flow in powertrains and charging systems. Within the technology segment, Silicon Carbide (SiC) devices are gaining share over traditional Silicon due to superior thermal performance. In terms of application, Battery Management Systems and on-board chargers represent the fastest-growing segments.
Regulatory mandates are central to market development, with frameworks like the US EPA's emissions standards and the EU Green Deal accelerating the shift to electric mobility. China's MIIT policies also promote New Energy Vehicle (NEV) production, directly influencing component demand. These regulations establish stringent reliability and lifecycle requirements for all power electronics. Consequently, securing a resilient supply of qualified, wide-bandgap semiconductor materials is becoming a primary strategic concern for automotive manufacturers.
Market Dynamics
The central force driving market evolution is the shift in design authority from Tier-1 suppliers to automotive OEMs. This change grants carmakers direct control over critical powertrain components, fundamentally altering supplier relationships and technology roadmaps for power semiconductors.
Growth Catalysts
- EV Adoption Mandates:Regulatory frameworks like the EU Green Deal and emissions standards from the US EPA directly compel a transition to electric vehicles, creating baseline demand for high-voltage power components in powertrains and charging infrastructure.
- Wide-Bandgap Materials:The adoption of Silicon Carbide (SiC) and Gallium Nitride (GaN) in applications like on-board chargers and DC-DC converters enables higher power density and efficiency, which are critical performance differentiators for automakers.
- China's NEV Ecosystem:Government policies promoting New Energy Vehicle (NEV) production have established China as the largest single market for automotive power semiconductors, supported by a massive domestic battery and vehicle manufacturing base.
Market Restraints
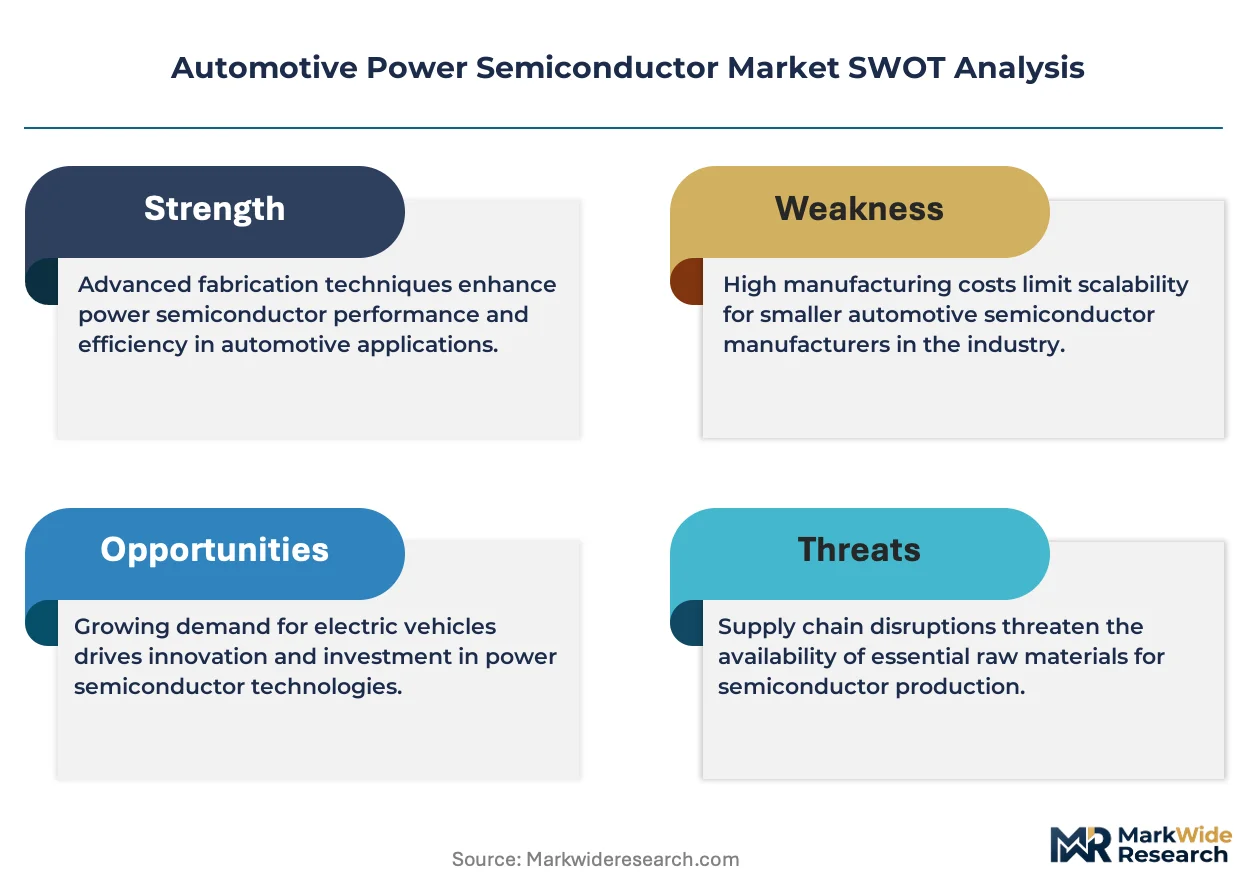
- Substrate Cost and Availability:The high cost and constrained supply of high-quality Silicon Carbide substrates act as a significant barrier to mass-market adoption, limiting deployment primarily to premium vehicle segments and creating input cost volatility.
- Manufacturing Concentration:A heavy concentration of advanced semiconductor fabrication and packaging capabilities in specific East Asian geographies exposes the automotive supply chain to significant geopolitical and logistical disruption risks.
- Technical Integration Hurdles:The faster switching speeds of wide-bandgap semiconductors require more complex gate driver designs and introduce electromagnetic interference (EMI) challenges, increasing system-level design and validation costs for Tier-1s and OEMs.
Strategic Opportunities
- Commercial Vehicle Electrification:The transition of medium- and heavy-duty trucks and buses to electric powertrains opens a substantial new market for high-power modules capable of handling extreme voltage and current requirements, a segment currently underserved.
- New Production Geographies:Government incentives, such as India's PLI scheme for semiconductors, present an opportunity for manufacturers to diversify their global production footprint, de-risk supply chains, and serve emerging regional automotive hubs.
- System-in-Package (SiP) Solutions:Integrating power devices, gate drivers, and monitoring sensors into a single, compact module offers a path to reduce system complexity, improve reliability, and simplify sourcing for automotive manufacturers.
Industry Challenges
- Specialized Talent Scarcity:A shortage of power electronics engineers with deep expertise in wide-bandgap materials, high-voltage system design, and automotive functional safety standards creates a bottleneck for product development and innovation.
- Lengthy Qualification Cycles:The stringent reliability and longevity requirements of the automotive industry, formalized in standards like AEC-Q101, result in multi-year qualification timelines that can slow the introduction of new materials and device technologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Power Semiconductor Market |
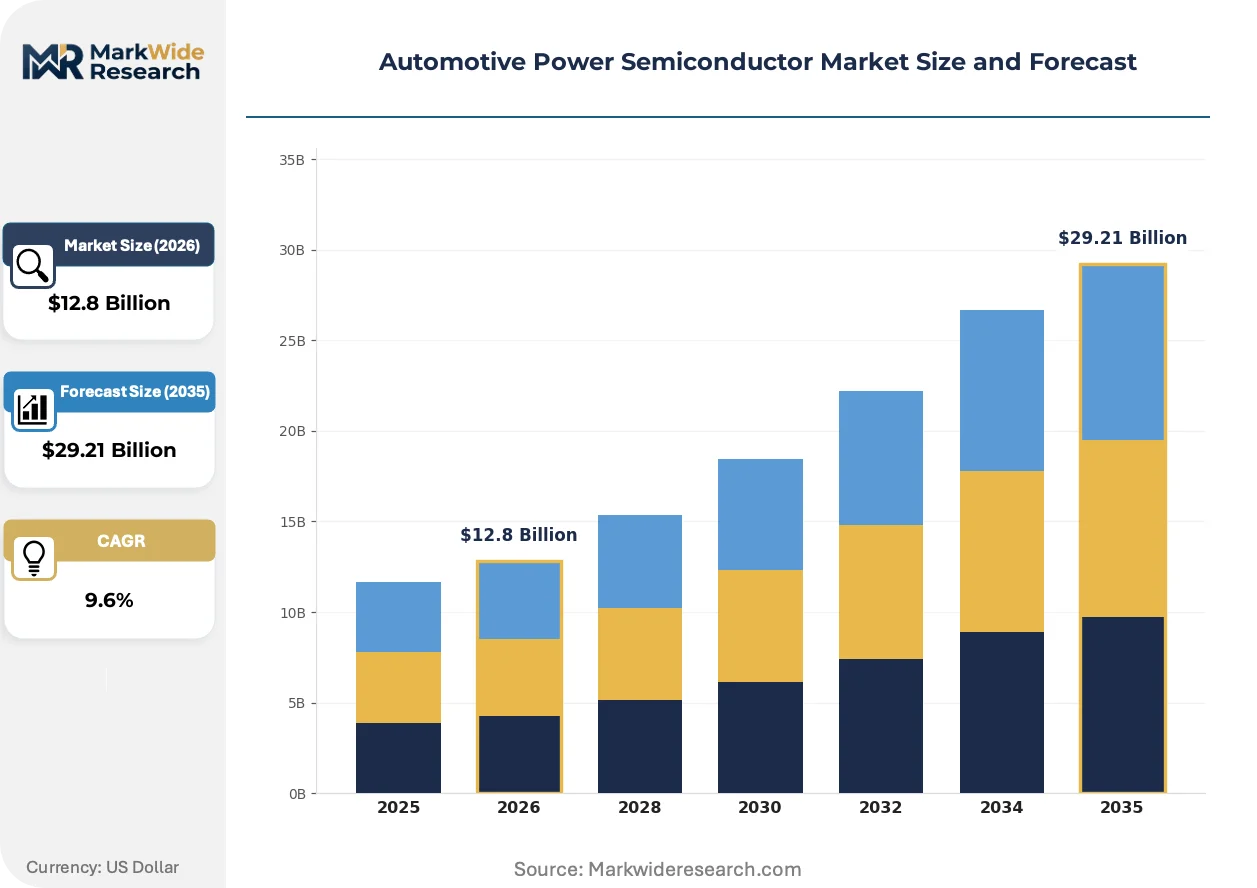
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $29.21 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: IGBT, MOSFET, Diodes, Thyristors, Rectifiers Technology: Silicon Carbide, Gallium Nitride, Silicon, Bipolar Junction, Insulated-Gate Application: Electric Vehicles, Hybrid Systems, Powertrain Control, Battery Management, Charging Infrastructure End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers, Maintenance Workshops |
| Companies Covered | Infineon Technologies AG, NXP Semiconductors, STMicroelectronics, Texas Instruments Incorporated, Renesas Electronics Corporation, Semiconductor Components Industries, ON Semiconductor Corporation, Robert Bosch GmbH, Analog Devices, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Power Semiconductor Market Strategic Shifts & Innovations
Material science advancements and new models of direct engagement between component suppliers and vehicle manufacturers are redefining the competitive landscape. This evolution prioritizes system-level performance and supply chain resilience over traditional component-level purchasing.
Silicon Carbide (SiC) technology offers superior thermal conductivity and lower switching losses for high-voltage automotive inverters. Leading automotive OEMs are accelerating its adoption in premium electric vehicle platforms to extend range and efficiency. This development is bifurcating the market between advanced SiC-based powertrains and legacy silicon IGBTs used in hybrid and lower-cost EV models.
China's "dual carbon" policy framework, enforced through MIIT's New Energy Vehicle mandates, sets aggressive targets for electrification. These regulations compel automakers to prioritize high-efficiency components, creating sustained demand for advanced power semiconductors. The domestic powertrain segment is most impacted, with Chinese OEMs favoring local semiconductor partners to ensure compliance and supply security.
Automotive OEMs are increasingly specifying power semiconductor devices directly, a departure from historic reliance on Tier-1 suppliers for component selection. This pattern disintermediates the traditional supply chain, giving carmakers greater control over powertrain architecture and performance. The trend is most prominent among European and North American automakers focused on optimizing battery management systems and inverters.
Automotive Power Semiconductor Market Segmentation
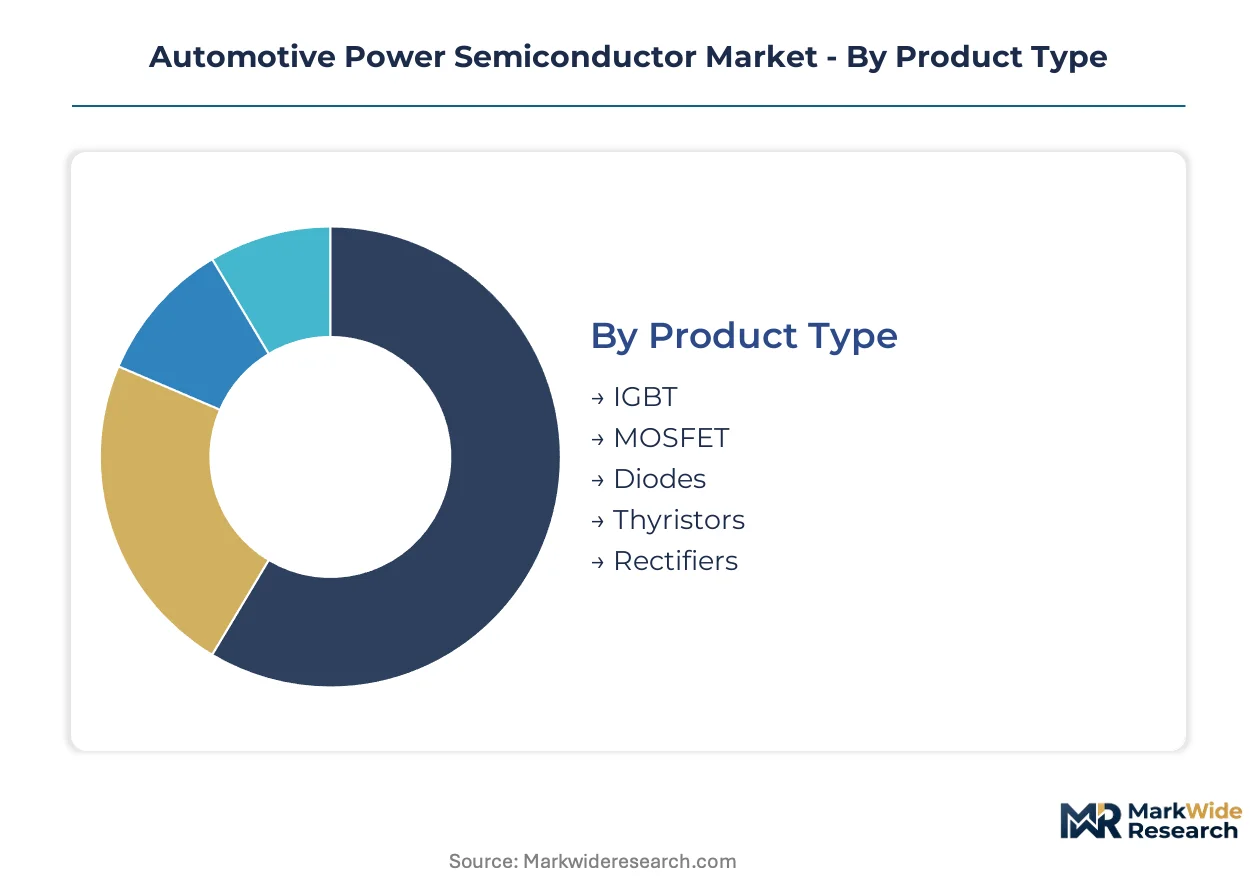
Understanding the segmentation of the automotive power semiconductor market is crucial for identifying areas of concentrated demand and emerging technological shifts. This analysis dissects the market by product type, underlying technology, specific application areas, and the key end-users driving procurement decisions.
Product Type:
The geographic distribution of product type demand reflects varied regional electrification strategies and legacy platform dependencies.
- IGBT (Insulated Gate Bipolar Transistor):These devices combine the high-current capability of a bipolar transistor with the high input impedance of a MOSFET, making them ideal for high-power switching applications. Demand concentrates heavily in China due to its massive EV production, driven by MIIT policies promoting NEV manufacturing.
- MOSFET (Metal-Oxide-Semiconductor Field-Effect Transistor):MOSFETs are voltage-controlled devices offering high switching speeds and low on-resistance, crucial for efficient power conversion in automotive systems. European automakers prioritize MOSFETs for advanced battery management systems, seeking enhanced efficiency and compact designs.
- Diodes:These components allow current flow in one direction, essential for rectification and protection circuits within vehicle electronics.
- Thyristors:Thyristors function as high-power switches, finding use in specific high-voltage applications like charging infrastructure and industrial vehicle power control.
- Rectifiers:Rectifiers convert alternating current (AC) to direct current (DC), vital for onboard chargers and auxiliary power supplies in electric vehicles.
IGBTs command the established base in high-power automotive applications. The steepest expansion runs through MOSFETs, particularly in advanced EV platforms.
Technology:
Technology choices reflect a spectrum of performance and cost considerations, influencing vehicle segment adoption.
- Silicon Carbide (SiC):SiC devices offer superior thermal performance, higher power density, and lower switching losses compared to traditional silicon, extending EV range and efficiency. Premium EV platforms in Germany and the United States are accelerating SiC adoption, despite higher substrate costs.
- Silicon:Traditional silicon-based semiconductors remain cost-effective and widely adopted for many automotive power applications, especially in hybrid and lower-cost EV models. China's domestic automotive industry still heavily utilizes silicon for a broad range of vehicle electronics due to established supply chains.
- Gallium Nitride (GaN):GaN technology provides even higher switching speeds and efficiency than SiC, targeting specialized high-frequency applications like DC-DC converters.
- Bipolar Junction:Bipolar junction transistors (BJTs) are current-controlled devices used in specific lower-power or legacy control circuits within vehicles.
- Insulated-Gate:This category encompasses devices like IGBTs, combining gate control with high current handling, central to modern power electronics.
Silicon technology currently holds the largest market share due to its maturity and cost efficiency. Silicon Carbide is gaining share fastest, driven by performance demands in premium electric vehicles.
Application:
Application volumes for power semiconductors are directly correlated with electrification rates and system complexity across vehicle types.
- Electric Vehicles (EVs):EVs represent the largest and fastest-growing application segment, requiring high-voltage power semiconductors for inverters, DC-DC converters, and motor control units. Regulatory mandates like the EU Green Deal and China's MIIT policies compel significant investment in EV component development, driving semiconductor demand.
- Battery Management Systems (BMS):BMS applications are critical for monitoring and controlling battery health, charge, and discharge cycles in electric and hybrid vehicles. North American and European OEMs are pushing for advanced BMS solutions to enhance safety and optimize battery performance, necessitating high-precision power devices.
- Hybrid Systems:Hybrid vehicles utilize power semiconductors for managing energy flow between internal combustion engines, electric motors, and battery packs.
- Powertrain Control:This segment involves power devices regulating motor speed, torque, and overall power delivery in both traditional and electrified powertrains.
- Charging Infrastructure:Power semiconductors are essential for efficient and reliable operation of both AC and DC charging stations, converting grid power for vehicle batteries.
Electric Vehicles serve as the primary demand driver for power semiconductors. Charging Infrastructure represents a rapidly emerging segment with significant future growth potential.
End User:
End-user procurement patterns are shifting, reflecting a move towards greater direct control over component specification by vehicle manufacturers.
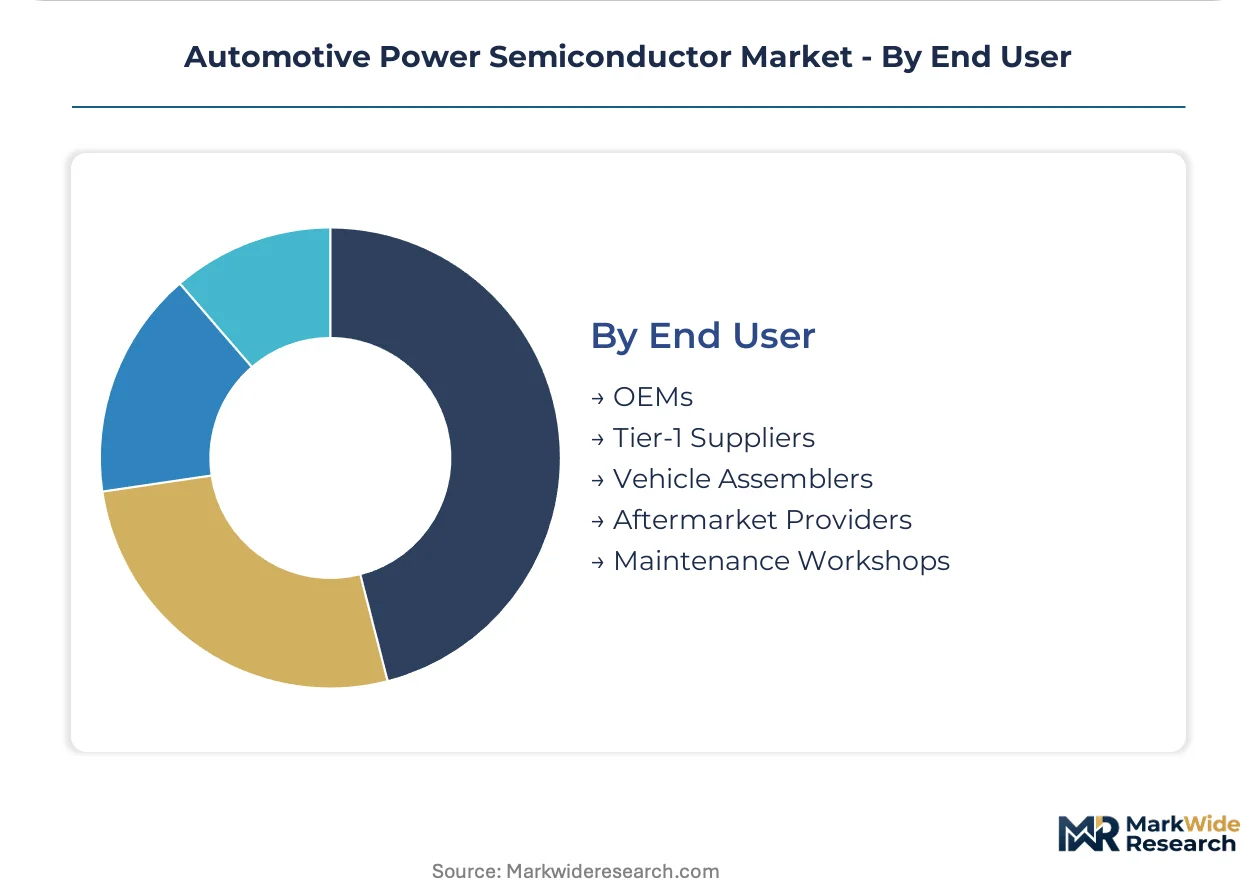
- OEMs (Original Equipment Manufacturers):Automotive OEMs are increasingly specifying power semiconductor devices directly, influencing design and performance of critical powertrain and battery systems. European and North American automakers are driving this shift to gain greater control over vehicle performance and differentiate their electric offerings.
- Tier-1 Suppliers:Traditional Tier-1 suppliers integrate power semiconductors into larger modules and subsystems, providing complex solutions to OEMs. Their demand remains substantial, particularly for established silicon-based components and standard power modules supplied to diverse global markets.
- Vehicle Assemblers:Vehicle assemblers integrate pre-built modules and systems containing power semiconductors into the final vehicle structure.
- Aftermarket Providers:These entities supply replacement power electronic components and modules for vehicle repairs and upgrades, serving a broad installed base.
- Maintenance Workshops:Maintenance workshops require power semiconductor components for repair and servicing of complex electrical systems in modern vehicles.
Tier-1 Suppliers account for the largest volume of power semiconductor procurement. OEMs represent the most strategic end-user segment, dictating future technology roadmaps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global grid interconnectivity strongly underpins the widespread adoption of electric vehicles, directly fueling demand for automotive power semiconductors. This infrastructure enables efficient energy distribution, supporting charging networks and advanced vehicle electronics. Regional policies and technological advancements further shape market dynamics across key automotive manufacturing hubs.
China
China's massive electric vehicle production and extensive battery manufacturing base drive substantial demand for power semiconductors. The MIIT's New Energy Vehicle mandates and "dual carbon" policies compel automakers to integrate high-efficiency components. The Yangtze River Delta region concentrates significant NEV component production and semiconductor fabrication facilities.
Germany
Germany's focus on premium electric vehicle platforms and advanced SiC adoption creates strong demand for high-performance power semiconductors. The EU Green Deal and national emissions standards accelerate the transition to electric mobility, requiring efficient power electronics. Bavaria serves as a key hub for automotive electronics development, with OEMs driving direct specification of power devices.
United States
The United States' EV adoption mandates and pursuit of advanced Battery Management Systems (BMS) necessitate sophisticated power semiconductor devices. US EPA emissions standards and the Inflation Reduction Act (IRA) incentivize domestic EV manufacturing and component sourcing. Michigan and California lead in EV powertrain innovation, with OEMs directly influencing semiconductor technology roadmaps.
Japan
Japan's strong focus on hybrid systems and specialized high-frequency GaN applications generates consistent demand for power semiconductors. METI policies support automotive technology advancement, encouraging investment in efficient power electronics for next-generation vehicles. The Kanto region is a significant center for power module integration and advanced material research for automotive applications.
Automotive Power Semiconductor Market Key Industry Players
Concentration sits with established semiconductor giants and specialized power electronics firms in the automotive sector. The market exhibits a tiered structure, with a few large integrated device manufacturers alongside numerous niche players. Strategic archetypes include broad-portfolio suppliers, advanced material specialists focusing on SiC, and regional component providers. Companies actively pursue capacity expansion and strategic partnerships to secure long-term OEM agreements and diversify their supply chains.
Within the broad-portfolio supplier archetype, Germany's Infineon Technologies AG exemplifies extensive product offerings across various automotive applications. Switzerland-based STMicroelectronics, a prominent integrated device manufacturer, represents a key player specializing in advanced Silicon Carbide and Gallium Nitride technologies for EV applications. Furthermore, Netherlands-headquartered NXP Semiconductors occupies a strong position, particularly in microcontrollers and analog solutions for automotive systems. These firms anchor significant portions of the global power semiconductor supply chain.
| Leading Market Players |
|---|
| Infineon Technologies AG |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments Incorporated |
| Renesas Electronics Corporation |
| Semiconductor Components Industries |
| ON Semiconductor Corporation |
| Robert Bosch GmbH |
| Analog Devices |
| Others |
Cost & Logistics Intelligence
Lengthy qualification cycles for automotive power semiconductors, often extending beyond two years, directly influence long-term contract pricing and shape supply chain resilience. This extended timeline necessitates strategic partnerships between OEMs and component manufacturers.
Pricing Analysis
Volume-based contract pricing structures dominate the automotive power semiconductor market, reflecting the scale required by vehicle manufacturers. Price differentiation stems from device performance, particularly for advanced Silicon Carbide (SiC) components, and stringent AEC-Q101 qualification levels. Pricing pressure intensifies on legacy silicon devices due to oversupply and competition, while SiC maintains a premium. Premium EV OEMs exhibit lower price sensitivity for high-performance SiC, contrasting with cost-sensitive hybrid and entry-level EV segments.
Supply Chain Analysis
The concentrated fabrication of advanced wide-bandgap substrates in specific East Asian regions represents a significant supply chain chokepoint for automotive power semiconductors. Supply relies heavily on raw materials like silicon carbide wafers and specialized gallium nitride precursors. Geopolitical instability and trade restrictions pose a structural risk to this highly specialized production network. Distribution runs through a dual model of direct OEM procurement and integrated modules from Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense, as traditional silicon-based power semiconductors face displacement by superior wide-bandgap materials like Silicon Carbide. Incumbents must strategically adapt to this technological shift to maintain market relevance.
For Market Incumbents: Compound existing strengths in Silicon (Si) manufacturing by aggressively investing in next-generation SiC and GaN production capabilities and securing raw material supply. Establish long-term OEM agreements to lock in demand for advanced power modules, mitigating competitive threats from specialized wide-bandgap start-ups. Deepen vertical integration from SiC substrate production to final module assembly. Prioritize R&D in advanced packaging to optimize thermal management for high-power applications.
For New Entrants and Emerging Players: AEC-Q101 certification fast-track programs for innovative wide-bandgap devices offer new entrants a critical pathway to market entry. Target underserved segments like commercial vehicle electrification, which demand high-power modules with extreme voltage and current handling capabilities. Focus on System-in-Package (SiP) solutions to reduce system complexity for OEMs and simplify sourcing. Adopt a direct OEM engagement model to accelerate design-in cycles and build early customer loyalty.
For Investors and Strategic Acquirers: Long-term, this sits as a technology transformation play because the automotive industry's electrification trend is irreversible, driving demand for high-performance power electronics. Identify acquisition targets that possess proprietary wide-bandgap material IP, advanced packaging expertise, or established relationships with leading EV OEMs. The signal to watch is the consistent reduction in SiC substrate manufacturing costs, which will unlock mass-market adoption beyond premium vehicles.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for SiC | Secures future supply for rapidly growing EV demand. |
| Long-term OEM Agreements | Locks in significant volume and design-wins with major vehicle manufacturers. |
| System-in-Package Development | Reduces complexity and improves reliability for automotive integrators. |
| Diversify Production Geographies | Mitigates geopolitical and logistical risks in concentrated supply chains. |
| Advanced GaN R&D | Positions for future high-frequency applications beyond current SiC capabilities. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory documents, industry reports, and company financial disclosures. Primary interviews involved OEM procurement leads, Tier-1 engineering directors, power semiconductor R&D specialists, and battery system integrators. This approach ensures robust data validation through bottom-up market sizing and top-down corroboration of industry trends.
Segmentation dimensions modeled include product type, underlying technology, specific application areas, end-user categories, and regional production clusters across the analysis window. Compound Annual Growth Rates (CAGRs) were derived using regression analysis on historical data and projected market share shifts. Key industry-specific inputs include Electric Vehicle adoption rates and the penetration of Silicon Carbide technology in premium vehicle platforms.
Underlying assumptions cover regulatory stability and consistent raw material supply, with deviation risk concentrated in geopolitical tensions and rapid technological shifts. Practitioners should keep alternative scenarios live as government incentives and material science advancements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Grid Forming Inverters Market
Power Systems
Automotive Power Electronics Market
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Nimh Rechargeable Battery Market
Power Systems
Traction Inverter Market
Power Systems
Digital Inverter Market
Power Systems
Europe Shunt Reactors Market
Power Systems
Medium Voltage Drives Market
Power Systems
Global Inverter Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
Japan Surge Protector Market