
 Battery Cyclers Market | 2026-2036
Battery Cyclers Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Cyclers Market Insights
Modular channel configurations is recalibrating how buyers configure test floor capacity, letting laboratories add current ranges without replacing entire cabinets. HIOKI E.E. Corporation leverages its precision measurement heritage to dominate high-accuracy segments for research laboratories. Chroma ATE Inc. anchors its position through integrated power electronics and software ecosystems that span formation to end-of-line testing. Arbin Instruments differentiates via specialized high-current architectures that serve electric vehicle cell qualification protocols.
Battery cyclers are precision electronic instruments that apply controlled charge and discharge profiles to cells and packs, typically spanning microamp to kiloamp current ranges with voltage resolution below one millivolt, to characterize capacity fade, internal resistance growth, and thermal behavior under repeatable conditions. Their primary purpose is to generate standardized performance data that certifies cells for integration into battery management systems and warranty programs. The automatic product category leads current revenue contribution because automotive manufacturers require unattended 24-hour test sequences across thousands of channels. Modular architectures represent the fastest-expanding configuration as contract laboratories seek flexible capacity that scales with program volatility. Research laboratories constitute a concentrated margin pool since academic and government facilities prioritize measurement fidelity over throughput and accept premium pricing for extended voltage and temperature ranges.
The EU Battery Regulation and CE marking requirements are mandating standardized cycle life documentation for cells sold in member states, directly expanding cycler deployment at European manufacturing and import verification sites. The EPA and OSHA in the United States enforce thermal runaway containment protocols during high-stress cycling, which shapes facility layout and drives demand for integrated safety monitoring. China's SAMR and GB standards enforce domestic testing before market release, creating a captive equipment base for cyclers certified to local electrical and data format specifications. Stakeholders must monitor how evolving solid-state cell formats alter current-voltage profiles and whether existing cycler architectures require fundamental hardware redesign.
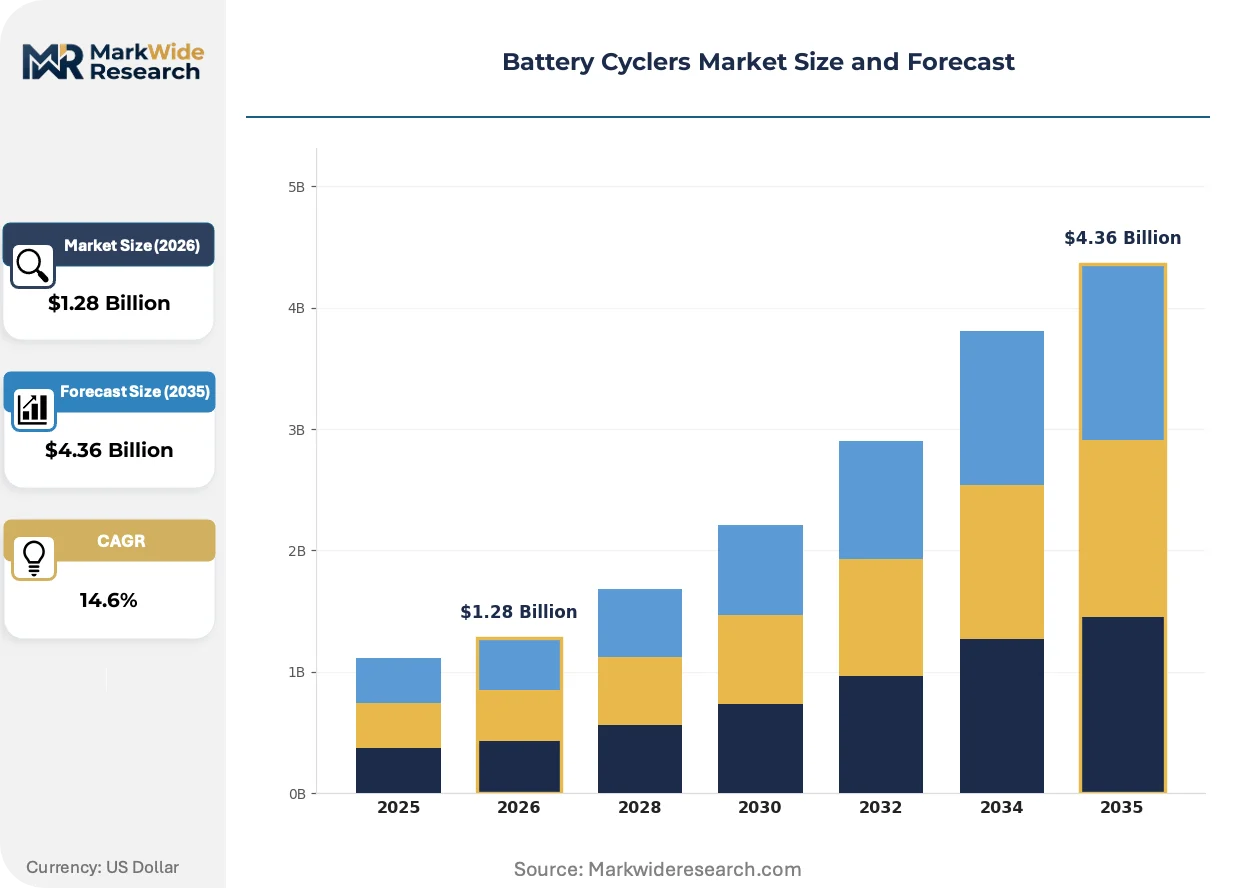
Market Dynamics
Modular channel configurations are recalibrating how buyers configure test floor capacity, letting laboratories add current ranges without replacing entire cabinets while automotive OEMs expand qualification programs for next-generation cell chemistries.
Growth Catalysts
- EU Battery Regulation:Mandates standardized cycle life documentation for cells sold in member states, directly expanding cycler deployment at European manufacturing and import verification sites.
- Solid-state cell development:Electric vehicle manufacturers require expanded testing capacity to validate next-generation chemistries with altered current-voltage profiles.
- China's NMPA certification:Domestic testing requirements before market release create captive equipment demand for cyclers certified to local electrical and data format specifications.
Market Restraints
- High-precision analog front-end costs:Input cost volatility for specialized ADCs and precision resistors compresses margins on mid-range channel configurations.
- Power electronics supply concentration:IGBT and SiC module sourcing clusters in East Asian foundries expose lead time risks for high-current architectures.
- Legacy software integration friction:Proprietary data formats from incumbent vendors create switching costs that slow laboratory procurement cycles.
Strategic Opportunities
- Second-life battery testing:Stationary storage and grid-scale repurposing applications create demand for cyclers that simulate degraded cell conditions.
- India's PLI scheme for ACC batteries:Domestic cell manufacturing incentives will require parallel testing infrastructure buildout at greenfield facilities.
- Cloud-native test management:Remote monitoring and multi-site data aggregation platforms enable distributed laboratory networks without on-site IT infrastructure.
Industry Challenges
- Calibration technician scarcity:Specialized expertise in high-precision current sourcing and thermal validation commands premium wages that strain laboratory operating budgets.
- Multi-protocol firmware complexity:Supporting simultaneous CAN, Modbus, and proprietary BMS communication standards extends development cycles and certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Cyclers Market |
| Market Size in 2026 | $1.28 Billion |
| Market Size in 2035 | $4.36 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Modular End User: Manufacturers, Research Laboratories, Educational Institutions, Repair Shops Technology: Li-ion, NiCd, NiMH, Lead Acid Application: Electric Vehicles, Consumer Electronics, Renewable Energy, Aerospace |
| Companies Covered | HIOKI E.E. Corporation, EnerSys, Chroma ATE Inc., Maccor Inc., DIGATRON Industrie-Elektronik GmbH, Arbin Instruments, Kikusui Electronics, National Instruments, Neware Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Cyclers Market Trends and Innovations
Hardware architectures and software ecosystems are converging to support unattended test sequences, with vendors embedding thermal runaway detection and predictive maintenance algorithms directly into channel controllers.
Silicon carbide power stages are integrating into high-current cycler designs, enabling faster switching frequencies that reduce thermal losses and shrink cabinet footprints. Automotive qualification laboratories in Germany's Stuttgart corridor are adopting these architectures to compress cell validation timelines. The technology is integrating formation and end-of-line testing into unified hardware platforms that eliminate redundant power electronics.
China's SAMR enforcement of GB standards for battery safety certification is mandating domestic pre-market testing that reshapes equipment procurement at cell manufacturing sites. The regulation requires documented thermal abuse profiles that exceed prior international protocols. European import verification facilities are responding by deploying cyclers with extended temperature range capabilities to preempt compliance gaps.
Contract laboratories are unbundling equipment ownership from test execution, with equipment-as-a-service models spreading among mid-tier cell developers in South Korea. Arbin Instruments and Chroma ATE are piloting subscription-based channel access that replaces capital expenditure with per-cycle pricing. This consumption-pattern shift is most visible among solid-state battery startups seeking to conserve runway during extended R&D phases.
Battery Cyclers Market Segmentation
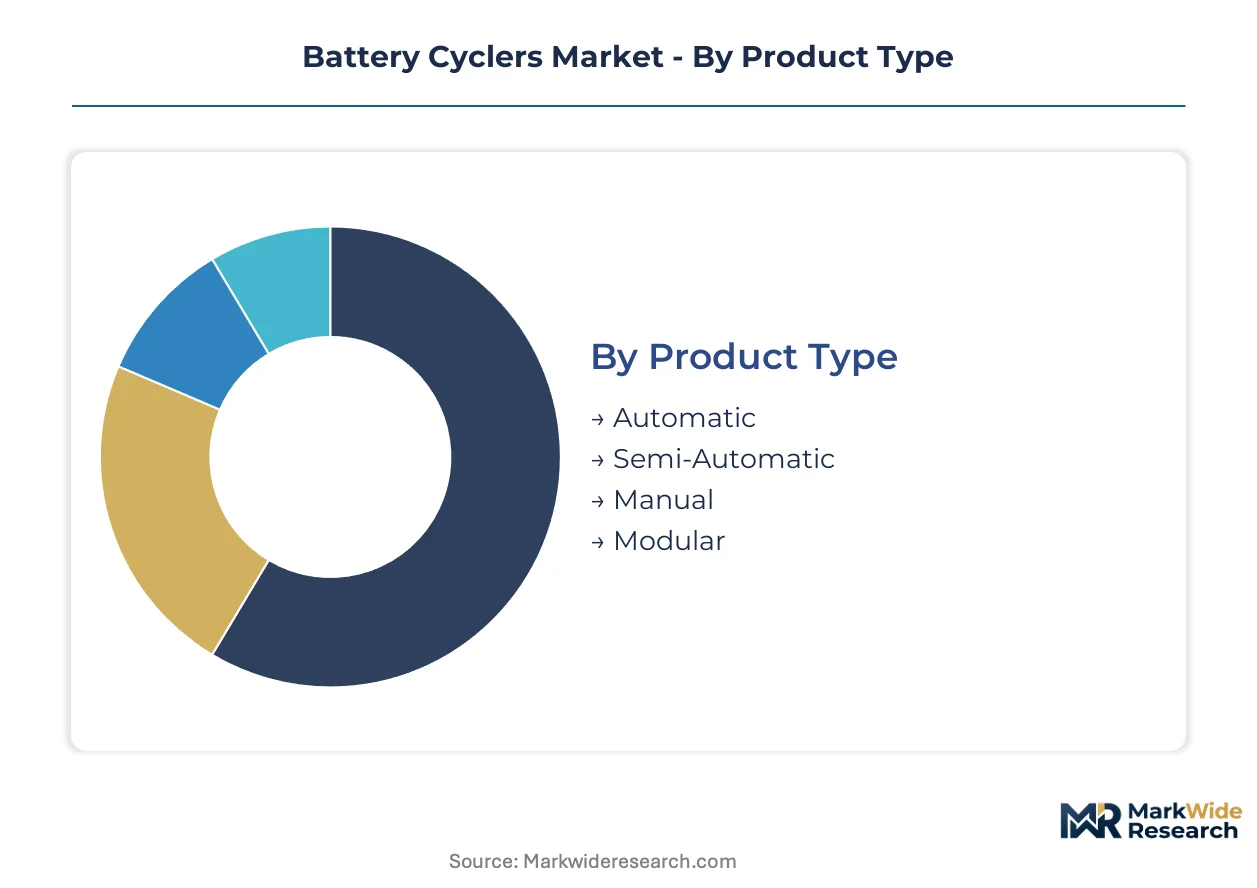
Battery cycler segmentation reveals how capital deployment priorities diverge across testing workflows. Equipment specifications, end-user sophistication, and application duty cycles create distinct procurement patterns that vendors must address through differentiated channel architectures.
Product Type:
Capital intensity varies sharply across product architectures, with high-current cabinets demanding precision analog front-ends that dominate upfront investment.
- Automatic:Systems execute unattended charge-discharge sequences across thousands of channels with embedded thermal runaway detection. Automotive manufacturers in Germany's Stuttgart corridor deploy these for 24-hour qualification programs that validate cells for warranty documentation.
- Modular:Configurations let laboratories add current ranges without replacing entire cabinets, preserving capital flexibility as program requirements shift. Contract laboratories favor this architecture for its ability to scale with volatile solid-state battery R&D timelines.
- Semi-Automatic:Hybrid designs blend operator oversight with programmable profiles for mid-volume validation workflows.
- Manual:Entry-level units serve educational and small-scale repair applications with limited throughput requirements.
Most installed capacity flows through Automatic systems. Expansion is steepest in Modular configurations.
End User:
Customer sophistication determines pricing tolerance, with research laboratories accepting premium instrumentation for extended measurement fidelity.
- Research Laboratories:Academic and government facilities prioritize voltage resolution below one millivolt and extended temperature ranges over throughput. These concentrated margin pools fund development of next-generation cycler architectures.
- Manufacturers:Cell producers and automotive OEMs require high-channel-count installations for qualification programs. China's NMPA certification mandates domestic pre-market testing that shapes equipment procurement at manufacturing sites.
- Educational Institutions:Training programs and undergraduate laboratories drive demand for entry-level manual and semi-automatic units.
- Repair Shops:Aftermarket battery service operations require portable cyclers for diagnostic cycling and capacity verification.
Manufacturers command the largest share of channel volume. Research Laboratories deliver the highest margins per installed unit.
Technology:
Cell chemistry specifications dictate current-voltage profile requirements and thermal management protocols.
- Li-ion:Dominant chemistry for electric vehicle and consumer electronics testing, requiring precision control over charge termination voltages and thermal runaway containment. Solid-state variants are altering current-voltage profiles and forcing hardware redesigns.
- NiMH:Remains relevant for hybrid vehicle applications and industrial backup systems with established cycling protocols.
- Lead Acid:Stationary storage and automotive starter battery testing drives continued demand for high-current discharge capabilities.
- NiCd:Niche applications in aerospace and industrial settings with legacy equipment requirements.
Li-ion absorbs the majority of new equipment investment. NiCd represents the most constrained expansion trajectory.
Application:
Duty cycle severity and certification requirements create divergent equipment specifications across end markets.
- Electric Vehicles:Cell qualification protocols demand high-current architectures that simulate fast-charge and deep-discharge profiles under thermal stress. The EU Battery Regulation mandates standardized cycle life documentation that expands cycler deployment at European manufacturing sites.
- Renewable Energy:Grid-scale storage validation requires extended calendar-life testing and second-life battery condition simulation for stationary repurposing applications.
- Consumer Electronics:High-volume, lower-current testing for smartphone and laptop cells emphasizes throughput over extended range capabilities.
- Aerospace:Specialized high-reliability protocols with stringent documentation requirements for manned and unmanned vehicle applications.
Electric Vehicles concentrate the heaviest equipment investment. Renewable Energy is climbing the fastest as grid storage deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Precision battery testing infrastructure originated in German automotive engineering centers during the 1990s, then expanded through Japanese electronics manufacturing corridors before establishing dominant manufacturing footprints across East Asian industrial zones.
China
Domestic cell production expansion and NMPA battery safety certification requirements are driving equipment procurement at manufacturing sites. SAMR enforcement of GB standards mandates pre-market thermal abuse testing that exceeds prior international protocols. The Yangtze River Delta concentration around Shanghai hosts the densest cycler installation base for export verification and domestic qualification programs.
Germany
Automotive OEM qualification programs and EU Battery Regulation cycle life documentation mandates are expanding test floor capacity. CE marking requirements for standardized cell validation are reshaping procurement specifications at manufacturing and import sites. The Stuttgart-Wolfsburg automotive corridor operates the highest concentration of high-channel-count installations for warranty documentation.
United States
EPA and OSHA thermal runaway containment protocols during high-stress cycling are shaping facility layout requirements at qualification laboratories. Solid-state battery R&D pipelines are demanding expanded current-voltage profile capabilities. The Pacific Northwest and Greater Boston clusters concentrate contract testing capacity for next-generation chemistry validation.
South Korea
Equipment-as-a-service models are spreading among mid-tier cell developers seeking to conserve capital during extended R&D phases. Domestic chaebol battery manufacturing expansion is driving formation and end-of-line testing infrastructure buildout. The Seoul Capital Area and Busan-Ulsan corridor anchor the highest density of subscription-based channel access pilots.
Japan
METI-supported solid-state battery development programs are requiring precision measurement instrumentation for laboratory validation. JIS standards compliance for domestic cell certification maintains captive equipment demand. The Kanto and Kansai industrial zones concentrate research laboratory procurement for extended voltage and temperature range capabilities.
Battery Cyclers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across measurement fidelity and software integration depth. The vendor base stratifies into three tiers: precision instrumentation specialists, integrated power electronics platforms, and regional fabrication houses. Strategic archetypes include research-laboratory specialists, automotive qualification integrators, and contract manufacturing service providers. Dominant competitive moves encompass silicon carbide power stage integration and cloud-native test management platform development.
Within the precision instrumentation tier, HIOKI E.E. Corporation and Kikusui Electronics exemplify Japanese heritage in high-accuracy measurement segments. Chroma ATE Inc. anchors the integrated platform category through its power electronics and software ecosystem spanning formation to end-of-line testing. Arbin Instruments occupies a specialized position in high-current architectures serving electric vehicle cell qualification protocols.
| Leading Market Players |
|---|
| HIOKI E.E. Corporation |
| EnerSys |
| Chroma ATE Inc. |
| Maccor Inc. |
| DIGATRON Industrie-Elektronik GmbH |
| Arbin Instruments |
| Kikusui Electronics |
| National Instruments |
| Neware Technology Limited |
| Others |
Pricing and Supply Chain Analysis
IGBT and SiC module spot price volatility cascades through battery cycler manufacturing tiers, compressing margins on mid-range channel configurations while premium research-laboratory segments absorb cost pass-through through extended voltage and temperature range bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates research-laboratory instrumentation with sub-millivolt resolution from automotive qualification cabinets and entry-level educational units. Price differentiation rests on measurement fidelity grade and CE marking certification tier. Pricing pressure stems from high-precision analog front-end cost volatility in ADC and precision resistor sourcing. Contract laboratories exhibit highest price sensitivity due to equipment-as-a-service adoption, while research facilities show lowest sensitivity given grant-funded procurement cycles.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from automotive manufacturers in Germany and China, while distributor networks serve mid-tier contract laboratories and educational institutions. Manufacturing concentrates in China, Japan, and Germany for precision power electronics and channel controller assemblies. Raw material dependencies draw from Taiwan for semiconductor foundry capacity, South Korea for SiC substrate supply, and Japan for precision measurement components. Single-source vulnerability in IGBT module sourcing from East Asian foundries exposes lead time risks. Distribution runs through authorized system integrators for qualification laboratory deployments and direct vendor relationships for high-volume OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery cycler vendors operate in a margin-expansion environment as silicon carbide power stage integration reduces thermal losses and enables premium pricing for compressed validation timelines.
For Market Incumbents: Acquire cloud-native test management platform capabilities to preempt subscription-based channel access disruption from Arbin Instruments and Chroma ATE pilots. Consolidate calibration technician training programs through backward integration into precision current sourcing expertise, defending against wage inflation that strains laboratory operating budgets. Prioritize firmware development for multi-protocol BMS communication standards to extend switching costs that slow competitor procurement cycles. For New Entrants and Emerging Players: Enter via second-life battery testing applications for stationary storage repurposing, where degraded cell condition simulation creates unmet demand outside incumbent automotive qualification focus. Target India's PLI scheme for ACC battery manufacturing buildout, where greenfield facilities require parallel testing infrastructure without legacy vendor relationships. Deploy equipment-as-a-service models to conserve customer capital during extended solid-state R&D phases. For Investors and Strategic Acquirers: Asymmetric upside sits with modular channel architecture specialists serving volatile solid-state battery R&D timelines. Long-term viability centers on vendors integrating formation and end-of-line testing into unified hardware platforms that eliminate redundant power electronics. Watch NMPA enforcement patterns for GB standards thermal abuse documentation as inflection indicator for captive equipment demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Power Stage Integration | Enables faster switching frequencies that reduce thermal losses and compress Stuttgart corridor validation timelines. |
| Cloud-Native Test Management Platform | Supports remote monitoring and multi-site data aggregation for distributed laboratory networks without on-site IT infrastructure. |
| Equipment-as-a-Service Model Expansion | Replaces capital expenditure with per-cycle pricing for South Korean mid-tier cell developers conserving runway. |
| Multi-Protocol Firmware Development | Extends switching costs through simultaneous CAN, Modbus, and proprietary BMS communication standard support. |
| Calibration Technician Training Consolidation | Addresses scarcity-driven wage premiums that strain laboratory operating budgets across European qualification sites. |
Research Methodology
Bottom-up channel installation modeling reconciled against top-down power electronics shipment tracking forms the analytical core. Primary interviews with qualification laboratory directors, automotive OEM test floor managers, contract laboratory procurement leads, and precision measurement R&D heads combined with secondary validation from SAMR GB standards documentation, EU Battery Regulation implementation guidance, EPA thermal runaway containment protocols, and customs data on IGBT and SiC module trade flows. Triangulation across these sources anchored volume and value estimates.
Input-output matrices mapped channel configurations against end-user sophistication tiers and application duty cycles across the projection horizon. Segmentation dimensions modeled include product architecture, customer type, cell chemistry, and geographic regulatory cluster. CAGRs derived from installed base growth rates and replacement cycle analysis. Forecast inputs incorporated NMPA certification timeline enforcement, solid-state cell format transition curves, and equipment-as-a-service adoption elasticity among mid-tier developers.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time channel-level pricing transparency introduce uncertainty bands around premium segment estimates. Forecasts reflect documented assumptions regarding SAMR enforcement intensity and silicon carbide power stage cost-down curves. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Silicon Carbide Power Devices Market
Power Systems
Power Diode Market
Power Systems
Global Data Center Transformer Market
Power Systems
AC DC Power Adapter Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Europe Micro Inverter Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Asia-Pacific Shunt Reactors Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Transformer Tap Changers and Voltage Control Relay Market
Power Systems
Charge Pumps Market
Power Systems
Vehicle Inverter Market
Power Systems
Asia-Pacific Automotive DC-DC Converters Market
Power Systems
South Korea Battery Management Systems Market
Power Systems
Space DC-DC Converters Market