
 PV Inverter Market | 2026-2036
PV Inverter Market Size, Share, and Industry Trends Forecast 2026-2036
PV Inverter Market Analysis
The direct-to-utility procurement channel is narrowing as developers consolidate vendor lists around fewer qualified suppliers. Huawei leverages its power electronics heritage to dominate utility-scale bids across multiple continents. SMA sustains engineering credibility in European commercial rooftop segments through decades of field-proven reliability. Sungrow competes aggressively on manufacturing scale, anchoring cost leadership in emerging solar markets.
A PV inverter converts direct current from photovoltaic modules into alternating current synchronized with grid frequency and voltage parameters, typically achieving efficiency ratings above 98 percent through silicon carbide power semiconductors and multi-level topologies. String inverters occupy the margin-rich residential and commercial rooftop tier where installation flexibility commands premium pricing. Central inverters lead the utility-scale segment where economies of scale and balance-of-system savings offset lower unit margins. Smart inverter technology is displacing conventional grid-tied architectures as grid codes mandate reactive power support, frequency-watt control, and ride-through capabilities.
Grid codes from Germany's BNetzA, India's CEA, and China's National Energy Administration enforce distinct reactive power and low-voltage ride-through requirements that fragment product certification burdens. IEEE 1547 in the United States and IEC 61727 globally establish interoperability benchmarks that determine market access eligibility. Stakeholders must monitor evolving grid stability mandates and semiconductor supply resilience as inverter architectures integrate storage and grid-forming functions.
Market Dynamics
Smart inverter mandates are compressing product lifecycles as grid codes in Germany, India, and China force simultaneous compliance with reactive power support, frequency-watt control, and low-voltage ride-through capabilities. This regulatory convergence is eliminating conventional grid-tied architectures and redrawing competitive boundaries around power electronics integration.
Growth Catalysts
- Utility-scale solar procurement:China's National Energy Administration and India's CEA are accelerating central and string inverter deployments through renewable capacity auctions and interconnection standard enforcement.
- Silicon carbide semiconductor adoption:Wide-bandgap devices enable efficiency ratings above 98 percent while reducing thermal management costs in multi-level topologies.
- EU Green Deal grid-tied mandates:The framework redirects supply chain investments toward regional manufacturing hubs across European member states.
Market Restraints
- IGBT and silicon carbide supply concentration:Wafer fabrication capacity clusters in East Asian foundries, exposing procurement timelines to geopolitical friction.
- Fragmented certification burdens:IEEE 1547 in the United States, IEC 61727 globally, and BNetzA requirements in Germany force redundant testing cycles for multi-market products.
- String inverter margin compression:Residential and commercial rooftop segments face pricing pressure from commoditized hardware despite premium installation flexibility.
Strategic Opportunities
- Grid-forming inverter architectures:Storage integration and islanding capabilities are opening utility-scale retrofit markets as microgrids proliferate.
- India's PLI scheme for domestic manufacturing:Production-linked incentives are attracting module-integrated electronics assembly to reduce import dependence.
- Aftermarket firmware monetization:Remote grid code updates and predictive maintenance subscriptions are creating recurring revenue streams from installed base.
Industry Challenges
- Power electronics talent scarcity:Shortages in magnetics design and thermal engineering are extending R&D timelines for next-generation topologies.
- Multi-standard compliance pipelines:Simultaneous certification against IEC 61727, IEEE 1547, and country-specific grid codes is stretching quality assurance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PV Inverter Market |
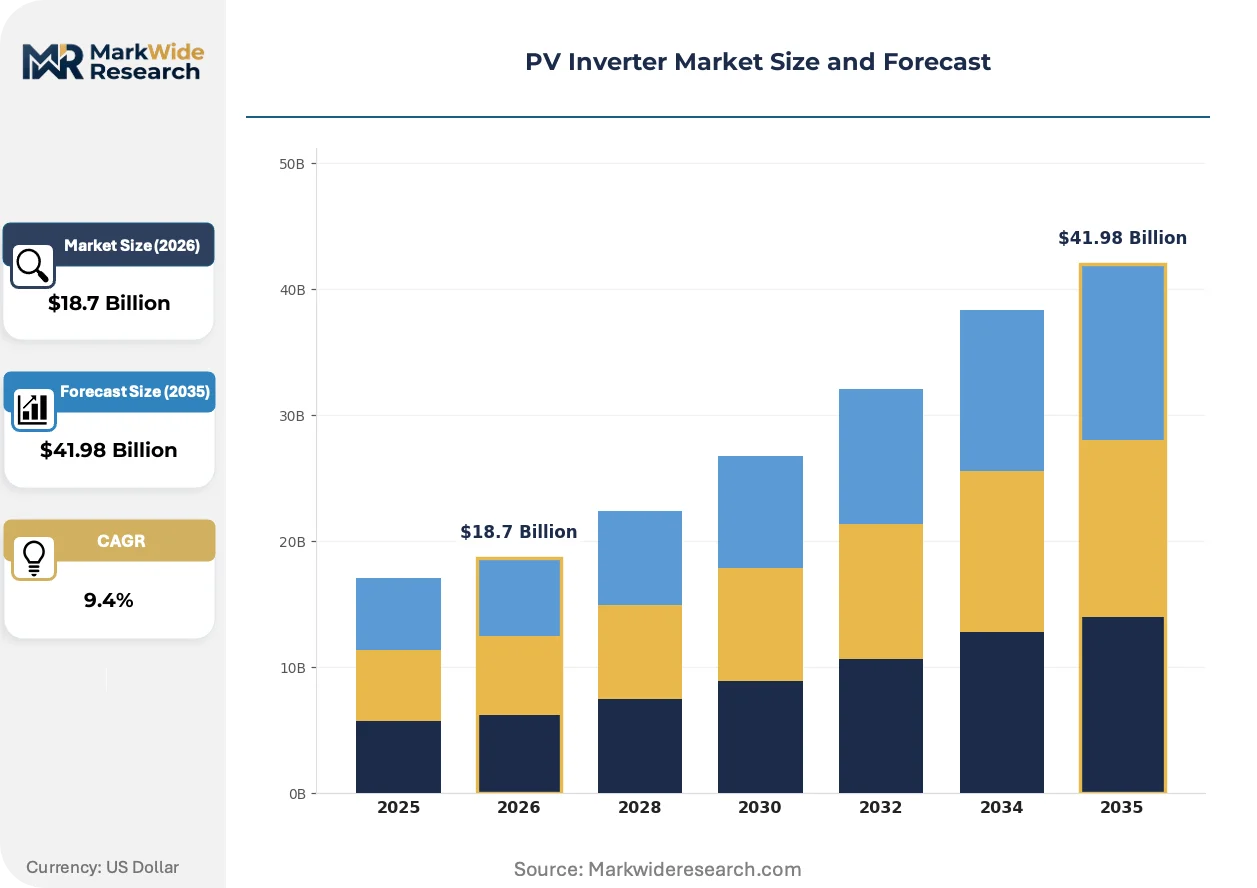
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: String Inverters, Central Inverters, Microinverters, Multi-MPPT Inverters End User: Residential, Commercial, Industrial, Utility-scale Technology: Grid-tied, Off-grid, Hybrid, Smart Inverters Installation Type: Rooftop, Ground-mounted, BIPV, Farm-scale |
| Companies Covered | Fronius, GoodWe, Huawei, Growatt, SolarEdge, Sungrow, Solis, Enphase, SMA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PV Inverter Market Emerging Trajectories
Digital intelligence is embedding into inverter hardware faster than component costs are declining, creating value migration from power conversion efficiency toward predictive grid services and asset management software layers.
Silicon carbide MOSFETs are digitizing inverter control systems by enabling higher switching frequencies that reduce passive component size and allow real-time grid parameter adjustment. Utility-scale developers in China and Germany are specifying SiC-based central inverters for new procurement cycles. This semiconductor transition is compressing the cost-performance gap between string and central architectures.
The EU Green Deal's grid stability mandates are forcing reactive power capability into all new inverter installations regardless of scale. Germany's BNetzA has tightened frequency-watt control requirements effective immediately for commercial rooftop systems. European vendors are redesigning thermal management systems to handle sustained reactive power operation without derating.
Direct-to-utility procurement consolidation is narrowing qualified supplier lists as developers centralize vendor qualification around field-proven reliability data. Engineering-procurement-construction firms are displacing distributor channels for projects above 50 MW. This concentration is most visible in Asia-Pacific utility-scale pipelines where state-owned developers maintain pre-approved vendor registries.
PV Inverter Market Segmentation
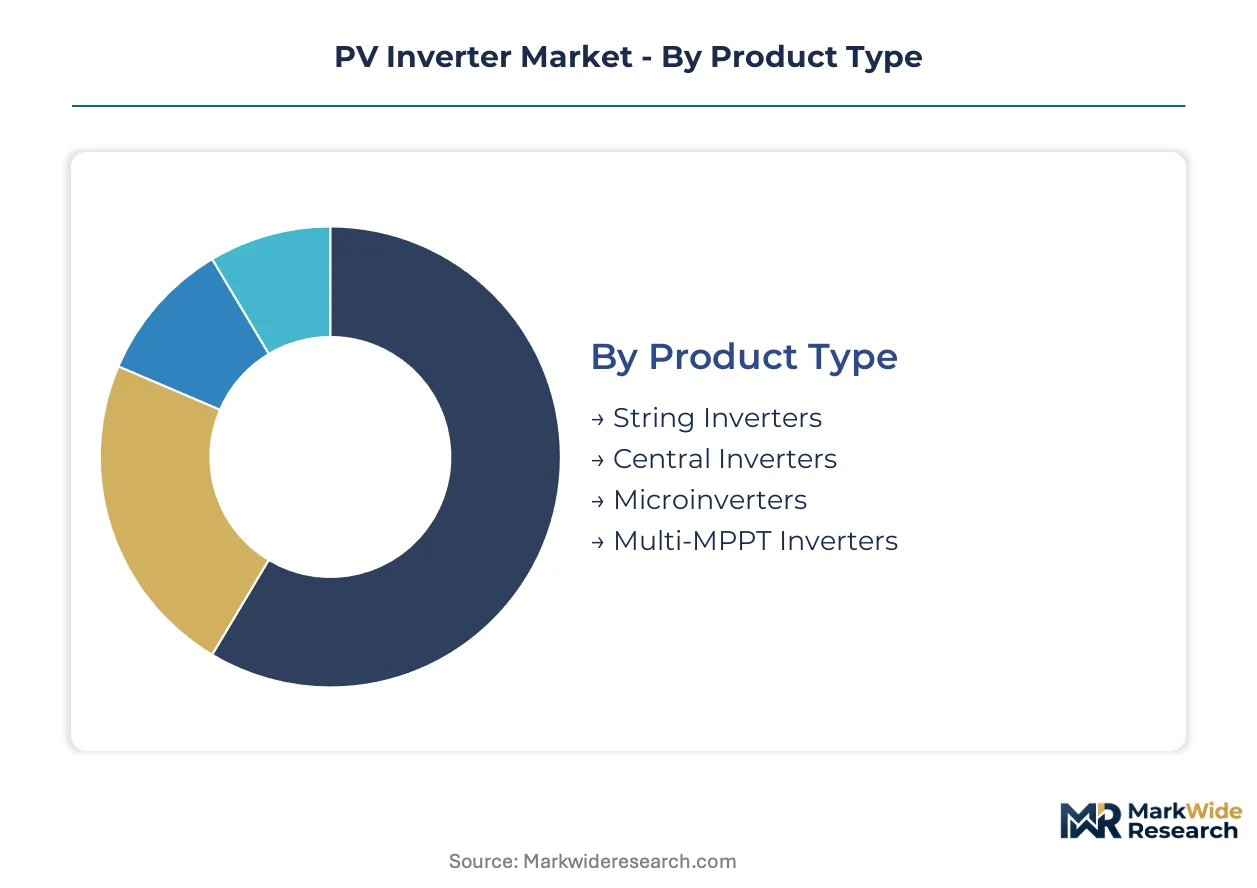
Segmentation in the PV inverter market reveals how technology choices map to distinct economic and regulatory environments. Product architecture, end-use scale, and grid interconnection requirements each create separate competitive arenas with unique margin structures and certification burdens.
Product Type:
Cost tier differentiation separates hardware families by manufacturing complexity and balance-of-system implications.
- String Inverters:Modular units process DC input from 8-12 modules through independent maximum power point tracking channels. Rooftop installers in Germany and Australia specify these for residential and commercial projects where shading variability demands granular optimization.
- Central Inverters:Single large-format units aggregate megawatt-scale PV arrays through centralized conversion architecture. Utility-scale developers in India and China deploy these for 100 MW+ solar parks where transformer-coupled designs minimize cabling costs.
- Microinverters:Panel-level electronics eliminate string mismatch losses through per-module AC conversion.
- Multi-MPPT Inverters:Hybrid architectures combine string modularity with central-scale power density for complex roof geometries.
Central inverters hold installed capacity. String inverters are rotating up the share rankings.
End User:
Customer type determines procurement channel, pricing power, and service contract structure.
- Residential:Single-phase units below 10 kW serve rooftop installations through distributor and installer networks. Homeowners in subsidy markets like Italy and Australia drive replacement cycles as early-generation systems age out.
- Commercial:Three-phase systems from 10 kW to 250 kW serve office buildings, warehouses, and retail facilities. Property developers in Spain and the Netherlands specify these for corporate sustainability mandates and net-metering optimization.
- Industrial:Heavy manufacturing facilities and data centers deploy 250 kW to 2 MW systems for behind-the-meter consumption.
- Utility-scale:Independent power producers and state-owned utilities procure containerized or skid-mounted solutions above 2 MW through competitive tender processes.
Utility-scale deployments dominate megawatt-hour volume. Commercial installations are expanding most quickly.
Technology:
Grid interconnection architecture defines compliance scope and functional capability requirements.
- Grid-tied:Synchronous inverters match utility frequency and voltage without energy storage integration. Legacy installations across Southern Europe rely on these as baseline configurations before smart inverter mandates took effect.
- Off-grid:Standalone systems with battery charging controllers serve remote installations beyond distribution network reach. Rural electrification programs in sub-Saharan Africa and island communities in Southeast Asia constitute primary demand.
- Hybrid:Bi-directional power electronics enable seamless switching between grid-connected and islanded operation.
- Smart Inverters:Grid-supportive functions including volt-var control, frequency-watt response, and ride-through capability are now mandatory under IEEE 1547 and EU grid codes.
Grid-tied architectures retain the largest installed base. Smart inverters are climbing the fastest.
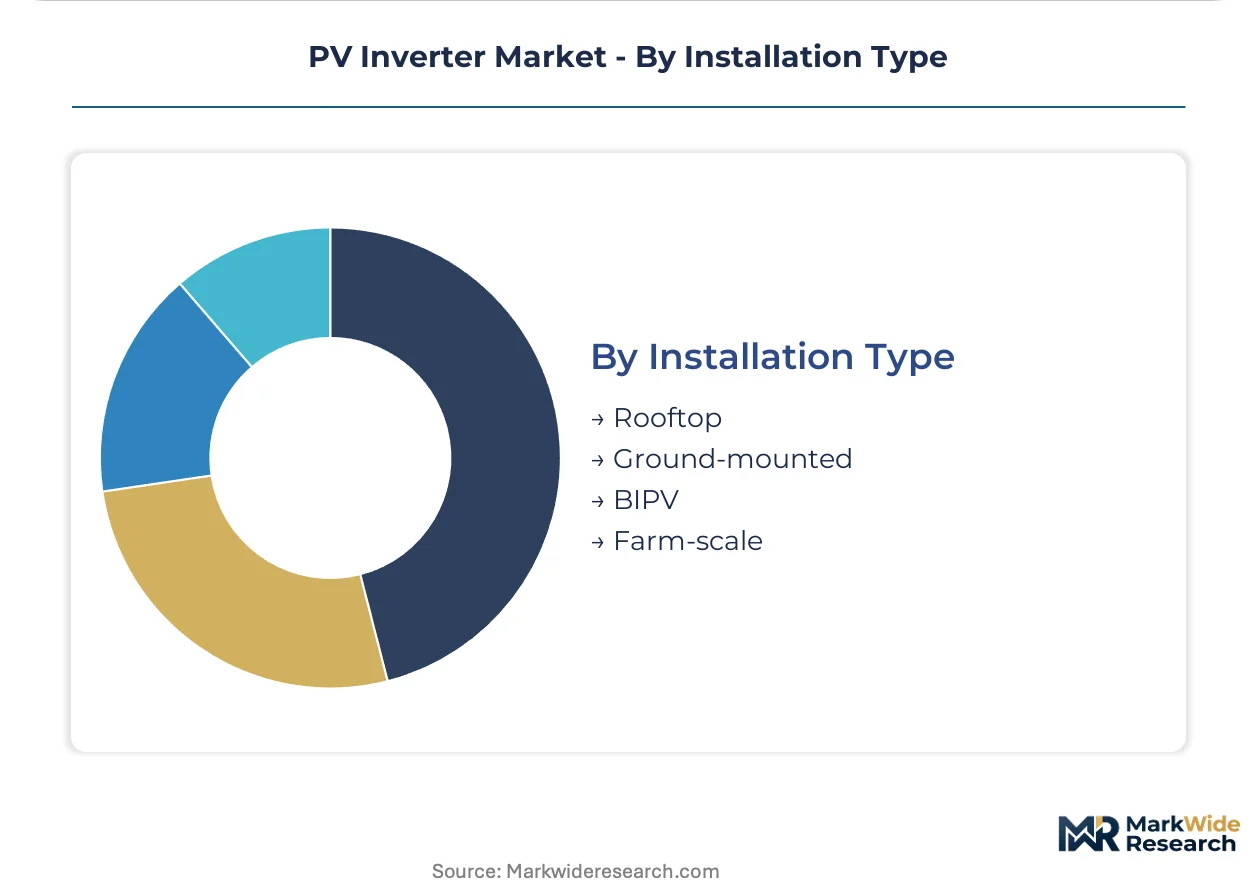
Installation Type:
Physical mounting configuration drives environmental protection ratings, cooling system design, and cabling topology.
- Rooftop:Weather-sealed enclosures with IP65 ratings withstand direct exposure on pitched or flat building surfaces. Urban density restrictions in Japan and South Korea favor these distributed configurations.
- Ground-mounted:Elevated platforms and transformer stations accommodate large-format central inverters in open terrain. Desert solar zones in the Middle East and North America specify these for thermal management and maintenance access.
- BIPV:Building-integrated photovoltaics embed inverters within facade or roofing materials for aesthetic conformity.
- Farm-scale:Agrivoltaic installations combine agricultural use with elevated solar arrays, requiring inverters resistant to dust, humidity, and chemical exposure.
Ground-mounted systems anchor utility-scale deployment. Rooftop configurations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production-linked incentives and renewable auction mechanisms are redrawing manufacturing footprints across major solar markets. National regulators enforce divergent grid codes that fragment certification requirements and reshape supplier selection criteria.
China
State-owned developers dominate utility-scale procurement through centralized tender processes. The National Energy Administration mandates smart inverter capabilities including reactive power support and low-voltage ride-through for all new grid connections. Manufacturing clusters in Jiangsu and Anhui provinces supply silicon carbide power modules and central inverter assemblies for domestic deployment and export markets.
Germany
Commercial rooftop installations drive string inverter demand as building owners pursue corporate renewable mandates. BNetzA grid codes enforce frequency-watt control and sustained reactive power operation without thermal derating. Industrial zones in Bavaria and North Rhine-Westphalia host engineering centers developing next-generation thermal management systems for smart inverter architectures.
India
Renewable capacity auctions by state distribution companies accelerate central and string inverter deployments across utility-scale solar parks. The CEA enforces stringent interconnection standards that mandate ride-through capabilities and grid-supportive functions. Manufacturing investments under the PLI scheme concentrate in Gujarat and Tamil Nadu, where module-integrated electronics assembly reduces import dependence.
United States
Independent power producers procure containerized central inverters through competitive RFP processes for utility-scale projects. IRA domestic content provisions redirect supply chain investments toward regional manufacturing hubs. Developer activity clusters in Texas and California, where interconnection queues and FERC Order 2023 implementation reshape procurement timelines and vendor qualification requirements.
Australia
Residential and commercial rooftop segments sustain string inverter demand through installer networks and distributor channels. State-level grid codes in New South Wales and Victoria mandate anti-islanding protection and voltage ride-through capabilities. Solar deployment concentrates in Queensland and Western Australia, where high irradiance levels and retail electricity tariffs support distributed generation economics.
PV Inverter Market Vendor Landscape
On the supply side, the industry is consolidating around vertically integrated power electronics specialists and scale-driven manufacturing platforms. Tiered competitive dynamics separate field-proven incumbents with decades of reliability data from challengers competing on cost and manufacturing velocity. Three archetypes dominate: diversified technology conglomerates with power electronics heritage, pure-play solar inverter specialists, and emerging challengers from adjacent industrial automation sectors. Competitive moves center on backward integration into semiconductor sourcing and geographic expansion through localized assembly partnerships.
Among the named players, Huawei and Sungrow exemplify scale-driven manufacturing platforms with integrated supply chain control, while SMA represents the engineering-credibility archetype built on field-proven reliability data. Fronius and SolarEdge occupy positions bridging premium-tier residential positioning with commercial segment expansion. Enphase anchors the module-level electronics specialization vector.
| Leading Market Players |
|---|
| Fronius |
| GoodWe |
| Huawei |
| Growatt |
| SolarEdge |
| Sungrow |
| Solis |
| Enphase |
| SMA |
| Others |
Supply Flow & Price Mechanics
Jiangsu province's silicon carbide wafer fabrication clusters anchor global power module supply, concentrating pricing leverage among integrated manufacturers who control both semiconductor sourcing and inverter assembly. This geographic concentration feeds downstream cost structures where module prices fluctuate with foundry utilization rates and export licensing timelines.
Pricing Analysis
Certification level creates the primary spread between premium-tier and economy offerings, with UL-listed and IEC 61727-certified units commanding substantial premiums over uncertified alternatives in regulated markets. Pricing stratifies across utility-scale tender bids, commercial rooftop installations, and residential distributor channels, with volume procurement in 100 MW+ solar parks generating the steepest discounts. Cost compression in string inverter tiers intensifies as Chinese manufacturing platforms flood distributor networks with commoditized hardware. Utility-scale independent power producers exhibit lowest price sensitivity due to balance-of-system savings, while residential installers face margin erosion from hardware commoditization.
Supply Chain Analysis
Geopolitical friction between China and the United States dominates supply chain risk exposure, threatening tariff escalation on silicon carbide substrates and magnetics components. Manufacturing concentration rests on China, Germany, and Taiwan for power semiconductors, magnetic cores, and thermal management systems. Raw material dependencies center on rare-earth magnetics, copper busbars, and aluminum heat sinks. Single-source vulnerability in 200 mm silicon carbide wafer supply creates procurement bottlenecks for high-efficiency inverter designs. Distribution runs through engineering-procurement-construction contractors for utility-scale projects and specialized electrical distributors for rooftop segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Power electronics engineering talent scarcity constrains product development velocity, with magnetics design and thermal simulation expertise commanding premium compensation across the competitive landscape. This capability gap separates incumbents with captive expertise from challengers dependent on contract engineering.
For Market Incumbents: Harden supply chain resilience through backward integration into silicon carbide sourcing or captive foundry partnerships in Taiwan and Germany. Consolidate field-proven reliability data into pre-qualification registries that state-owned developers in China and India mandate for tender participation. Defend against emerging challengers from industrial automation sectors by accelerating smart inverter firmware monetization through predictive maintenance subscriptions. For New Entrants and Emerging Players: Pursue aftermarket service contracts and remote grid code update subscriptions as entry vectors where incumbent installed bases generate recurring revenue vulnerability. Target India's PLI-supported manufacturing zones in Gujarat and Tamil Nadu where domestic content requirements disadvantage pure importers. White-space exists in agrivoltaic farm-scale inverters resistant to dust, humidity, and chemical exposure where specialized environmental protection ratings command pricing premiums. For Investors and Strategic Acquirers: Long-term, this sits as a grid-forming infrastructure play because storage integration and microgrid proliferation will retrofit existing solar parks with next-generation inverter architectures. Acquisition targets should center on firms with certified smart inverter platforms and software-layer revenue streams rather than pure hardware manufacturers. Watch FERC Order 2023 implementation and interconnection queue reform as signals for procurement timeline acceleration in the United States market.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Long-term wafer offtake contracts with foundries in Taiwan and Germany secure cost-competitive high-efficiency module production. |
| Smart Inverter Certification Investment | Simultaneous IEEE 1547 and BNetzA compliance opens access to United States and German procurement channels. |
| Aftermarket Firmware Platform | Predictive maintenance subscriptions and remote grid code updates convert installed base into recurring revenue streams. |
| Domestic Manufacturing Footprint | PLI-aligned assembly in India and IRA-compliant production in Texas satisfy local content mandates for utility tenders. |
| Grid-Forming Architecture Development | Storage-integrated islanding capabilities capture utility-scale retrofit demand as microgrid deployments accelerate. |
Methodological Framework
Operator-level perspectives from utility procurement officers, EPC contractor project managers, inverter manufacturer product strategists, and grid interconnection engineers anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FERC filings, CEA auction results, BNetzA grid code documentation, and customs trade data for power semiconductor imports. Bottom-up capacity and shipment estimates triangulated against top-down renewable auction pipelines and interconnection queue data.
Scenario-bracketing around regulatory implementation timelines and semiconductor supply elasticity informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, end-use scale tier, grid interconnection technology, and regional regulatory cluster. CAGRs derived from unit shipment trajectories, average selling price trends, and installed capacity buildout schedules. Forecast inputs incorporated silicon carbide adoption curves, smart inverter mandate phase-in schedules, and production-linked incentive uptake rates.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments, trade tariff schedules, or renewable auction clearing prices would shift the trajectory materially. Forecasts reflect documented assumptions regarding grid code implementation timelines and foundry capacity expansion plans. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
US Variable Frequency Drive Market
Power Systems
MOSFET and IGBT Gate Driver Market
Power Systems
Power Supply and Charger Market
Power Systems
Central Battery Systems Market
Power Systems
Electric Vehicle Power Inverter Market
Power Systems
North America Telecom Power Systems Market
Power Systems
Automotive Power Semiconductor Market
Power Systems
Marine Variable Frequency Drives Market
Power Systems
Battery Cyclers Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Global Pin Fin Heat Sink for IGBT Market
Power Systems
Train Auxiliary Rectifier Market
Power Systems
HVDC Converters Market
Power Systems
Micro-Inverter Market
Power Systems
Bypass Thyristor Market
Power Systems
Global Telecom Tower Power System Market