
 Low Voltage DC Circuit Breaker Market | 2026-2036
Low Voltage DC Circuit Breaker Market Size, Share, and Industry Trends Forecast 2026-2036
Low Voltage DC Circuit Breaker Market Analysis
Multi-source procurement for critical DC protection components is hardening across the supply base. Schneider Electric SE anchors European demand through deep channel partnerships with electrical distributors. Siemens AG leverages its factory automation footprint to bundle DC breakers with industrial control systems. Eaton Corporation PLC competes on thermal-magnetic specialization for harsh-environment installations.
A low voltage DC circuit breaker is an electromechanical switching device engineered to interrupt fault currents in direct current circuits up to 1500 volts, utilizing arc chutes and magnetic blowout coils to extinguish the non-zero-crossing DC arc. Its primary purpose is protecting batteries, solar arrays, and DC bus architectures from thermal damage during overload or short-circuit events. Circuit breaker units occupy the dominant revenue position due to recurring replacement cycles in renewable energy farms, while solid-state technology segments attract premium pricing for microsecond-level fault isolation in data center busway applications. Rack-mounted installation types are expanding fastest, driven by modular power architecture in hyperscale computing facilities.
IEC 60947-2 and UL 489-SA standards govern product certification across export markets, with China's GB/T 14048.2 creating parallel compliance obligations for manufacturers serving domestic solar installations. The US National Electrical Code and EU F-Gas Regulation indirectly shape DC breaker specifications by accelerating heat pump and electric vehicle charger deployments that strain legacy AC-to-DC conversion pathways. Stakeholders must monitor evolving arc-flash testing protocols and semiconductor material transitions that could obsolete electromechanical architectures without warning.
Market Dynamics
Data center power architecture is forcing a fundamental redesign of DC protection requirements as hyperscale operators abandon centralized UPS topologies in favor of rack-level battery integration, compressing fault-clearance timeframes from milliseconds to microseconds and invalidating conventional electromechanical breaker specifications.
Growth Catalysts
- EU Green Deal mandates:The EU Green Deal and national renewable energy targets are tightening electrical safety requirements for DC distribution networks, compelling utilities and installers to upgrade protection infrastructure across solar PV and energy storage installations.
- Hyperscale facility proliferation:Data center operators are expanding procurement of DC protection equipment as hyperscale facilities multiply, creating sustained demand for high-speed fault isolation in 48V and 380V DC bus architectures.
- Silicon carbide semiconductors:Wider bandgap materials are enabling higher switching frequencies in power conversion equipment, necessitating coordinated DC breaker development for matching response characteristics.
Market Restraints
- Copper price volatility:Magnetic blowout coils and busbar assemblies depend on copper feedstock, with price swings directly compressing manufacturing margins for electromechanical breaker producers.
- Chinese supply concentration:Solar-grade DC breaker manufacturing clusters heavily in Jiangsu and Zhejiang provinces, creating geographic concentration risk for procurement managers seeking supply diversification.
- Solid-state substitution threat:Thyristor-based and MOSFET-based protection devices are capturing premium applications in data center busway systems where microsecond isolation justifies higher unit costs.
Strategic Opportunities
- India renewable buildout:The country's PLI scheme for solar module manufacturing is stimulating downstream demand for DC protection equipment in utility-scale and rooftop installations.
- Marine DC microgrids:Battery-electric and hybrid propulsion systems in commercial shipping are creating new application requirements for corrosion-resistant, vibration-tolerant breaker designs.
- Digital twin integration:Convergence of breaker hardware with predictive maintenance software enables condition-based monitoring contracts, shifting revenue from unit sales to recurring service arrangements.
Industry Challenges
- Arc-flash testing capacity:Validating DC interruption performance at kiloampere fault levels requires specialized laboratory infrastructure that remains scarce outside established certification bodies.
- Dual compliance burden:Manufacturers serving both IEC 60947-2 and UL 489-SA markets must maintain parallel product variants, lengthening development cycles and inventory requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Voltage DC Circuit Breaker Market |
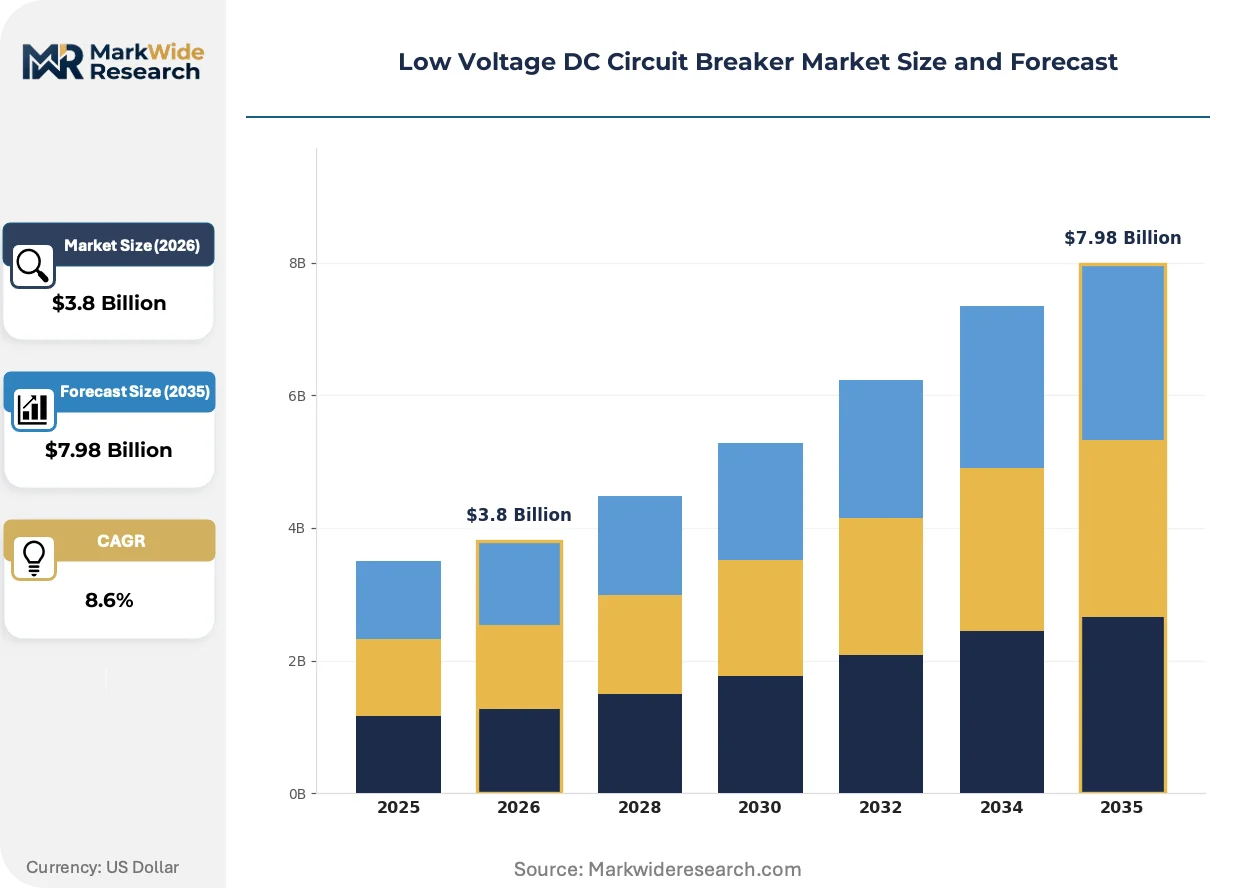
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.98 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Circuit Breaker, Fuse, Relay, Disconnect Switch End User: Data Centers, Renewable Energy, Automotive Industry, Marine Applications Installation Type: Indoor, Outdoor, Enclosed, Rack-Mounted Technology: Electromechanical, Solid State, Thermal, Hybrid |
| Companies Covered | Eaton Corporation PLC, Fuji Electric Co. Ltd., ABB Ltd, CHINT Global, LS ELECTRIC Co., Ltd., Schneider Electric SE, Mitsubishi Electric Corporation, Rockwell Automation Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Voltage DC Circuit Breaker Market Emerging Trajectories
Electromechanical architectures are confronting semiconductor-based alternatives across multiple voltage tiers, while regulatory pressure on carbon intensity and safety performance is accelerating product refresh cycles beyond traditional replacement timelines.
Solid-state DC protection is decentralizing fault management from centralized switchgear to individual rack-level units. Thyristor-based hybrid breakers combine mechanical contacts for normal load handling with semiconductor switches for sub-millisecond arc suppression. Hyperscale data center operators in Northern Virginia and Frankfurt are specifying these devices for 380V DC busway applications. This decentralization is compressing the addressable market for conventional thermal-magnetic breakers in premium computing infrastructure.
The EU F-Gas Regulation is indirectly reshaping DC breaker specifications by accelerating heat pump and electric vehicle charger deployments that strain legacy AC-to-DC conversion pathways. These installations require coordinated protection upgrades across distribution panels and point-of-load equipment. Residential and light commercial segments in Germany, France, and the Netherlands are experiencing the most pronounced specification changes as national building codes integrate electrification mandates.
Specification authority is migrating from electrical contractors to equipment OEMs as modular power architectures proliferate. Data center original equipment manufacturers now dictate breaker performance parameters in master service agreements, compressing distributor influence and technical sales cycles. This concentration of buying power is most visible in the Phoenix-Ashburn-Dallas corridor where hyperscale construction activity concentrates procurement decisions among a narrowing set of general contractors and engineering firms.
Low Voltage DC Circuit Breaker Market Segmentation
Low voltage DC circuit breaker procurement varies sharply across deployment contexts, with fault-current characteristics and response-time requirements dictating technology selection. Specification authority concentrates in distinct buyer profiles whose technical priorities reshape competitive positioning across each segment axis.
Product Type:
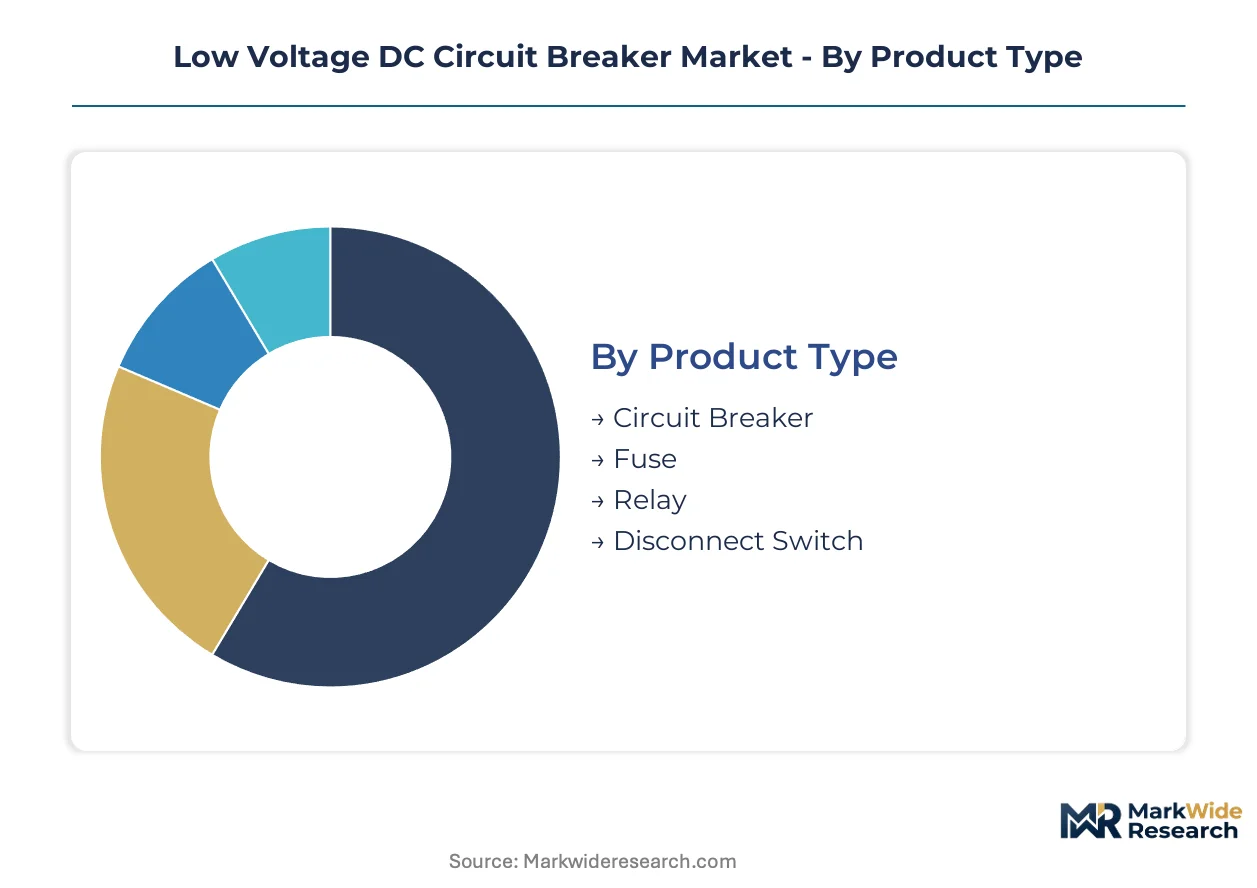
Thermal-magnetic and solid-state interruption mechanisms define cost-performance tradeoffs across the four product categories.
- Circuit Breaker:Electromechanical switching devices deploy arc chutes and magnetic blowout coils to extinguish non-zero-crossing DC arcs in circuits up to 1500 volts. Renewable energy farms in China and Germany drive recurring replacement cycles as solar PV and battery storage installations scale. IEC 60947-2 and UL 489-SA certifications govern cross-border shipments, creating dual compliance obligations for manufacturers.
- Fuse:Melting-element overcurrent protection offers lower unit costs but requires complete replacement after fault events. Automotive battery management systems and marine DC microgrids specify fuses for cost-sensitive branch circuit protection where reset capability is non-critical.
- Relay:Electromechanical switching elements coordinate with breakers for remote control and monitoring functions in industrial automation systems. Factory automation bundling with DC distribution equipment expands deployment in German and Japanese manufacturing facilities.
- Disconnect Switch:Manual isolation devices provide visible circuit separation for maintenance safety in solar combiner boxes and battery enclosures. Utility-scale solar installations in India and the United States specify these for lockout-tagout compliance.
Mature deployment sits with Circuit Breaker units. Newer deployment is concentrated in Relay products for digital twin integration.
End User:
Power architecture decisions at the facility level determine protection equipment specifications and procurement volumes.
- Data Centers:Hyperscale operators in Northern Virginia, Frankfurt, and Singapore are abandoning centralized UPS topologies for rack-level battery integration. Microsecond fault-clearance requirements are invalidating conventional electromechanical specifications and accelerating solid-state adoption.
- Renewable Energy:Solar PV and energy storage deployments require massive DC protection volumes, with China's Jiangsu and Zhejiang provinces anchoring manufacturing clusters. EU Green Deal mandates tighten electrical safety requirements across utility-scale and distributed generation.
- Automotive Industry:Electric vehicle charging infrastructure and battery pack protection create demand for compact, high-interruption-capacity devices. OEM specification authority concentrates procurement decisions among tier-one suppliers.
- Marine Applications:Battery-electric and hybrid propulsion systems in commercial shipping require corrosion-resistant, vibration-tolerant breaker designs. Classification society rules from Lloyd's Register and DNV shape certification requirements.
Volume concentration rests with Renewable Energy procurement. Value expansion is climbing fastest in Data Centers.
Installation Type:
Environmental exposure and spatial constraints dictate enclosure ratings and mounting configurations.
- Indoor:Controlled-environment installations in electrical rooms and switchgear assemblies specify standard IP ratings. Commercial and industrial facilities in Germany and Japan dominate specification activity.
- Outdoor:Weather-resistant enclosures with enhanced sealing protect against moisture and particulate ingress in solar farms and electric vehicle charging stations. Desert installations in Arizona and Saudi Arabia stress thermal management design.
- Enclosed:Factory-assembled switchgear integrates breakers with busbars and control wiring for streamlined field installation. Data center construction in the Phoenix-Ashburn-Dallas corridor specifies these for accelerated deployment schedules.
- Rack-Mounted:Modular power architecture in hyperscale computing facilities drives fastest expansion for this installation type. 48V and 380V DC busway applications in Northern Virginia and Frankfurt hyperscale campuses specify compact units for space-constrained rack designs.
Standardized deployment sits with Indoor configurations. Modular deployment is expanding most quickly in Rack-Mounted products.
Technology:
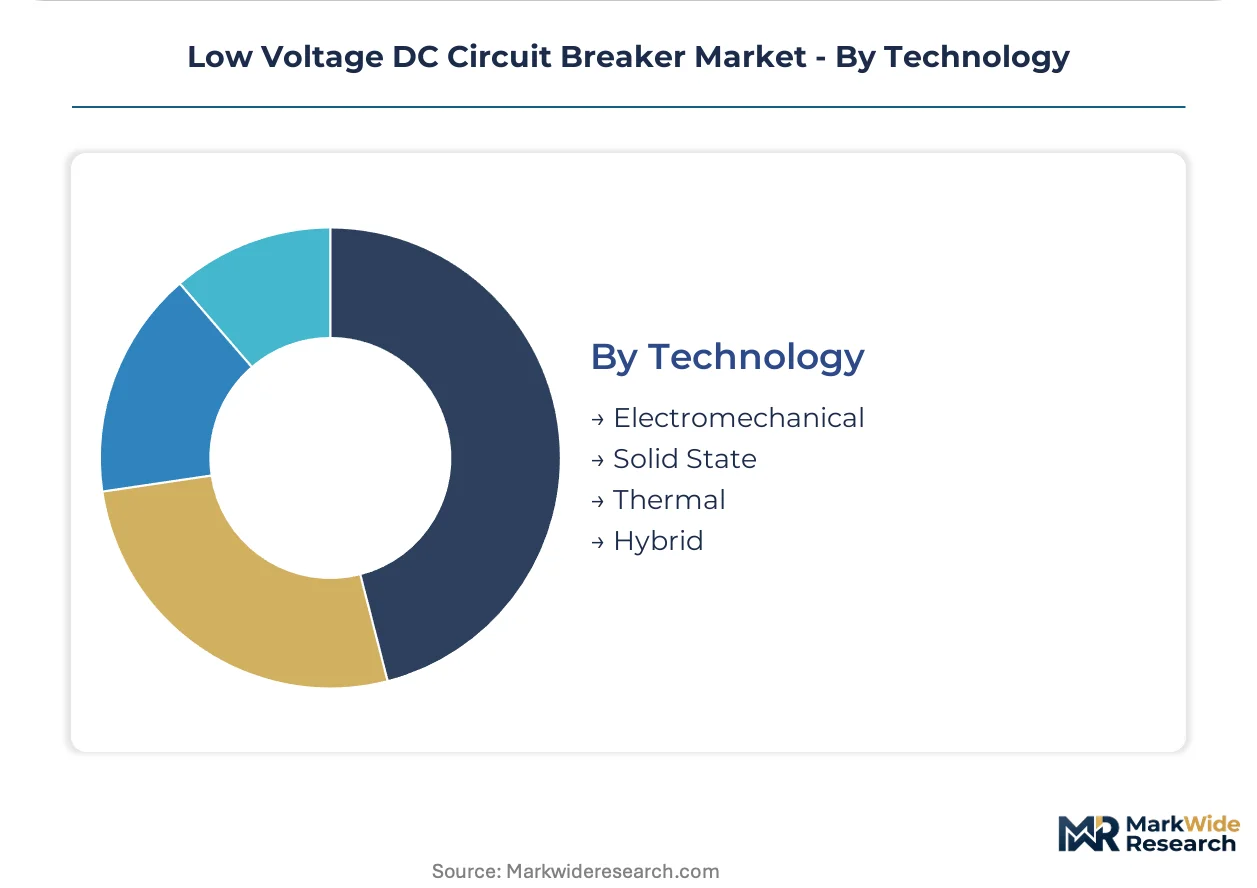
Interruption speed and arc management differentiate the four technological approaches.
- Electromechanical:Conventional thermal-magnetic mechanisms dominate installed base across renewable energy and industrial applications. Copper-dependent magnetic blowout coils face margin pressure from feedstock price volatility.
- Solid State:Thyristor-based and MOSFET-based devices capture premium applications requiring microsecond isolation. Data center busway systems in hyperscale facilities justify higher unit costs for sub-millisecond fault suppression.
- Thermal:Bimetallic strip actuation provides cost-effective overcurrent protection for low-fault-current applications. Residential and light commercial segments in the Netherlands and France specify these for heat pump and EV charger circuits.
- Hybrid:Combined mechanical contacts for normal load handling with semiconductor switches for arc suppression bridge performance and cost. Northern Virginia and Frankfurt hyperscale operators are specifying these for 380V DC applications.
Installed base concentration rests with Electromechanical architectures. Performance-critical deployment is gaining share fastest in Solid State technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper refining capacity in Jiangsu province anchors Asia-Pacific manufacturing for magnetic blowout coils and busbar assemblies. Jiangsu and Zhejiang provinces cluster solar-grade DC breaker production, creating geographic concentration for procurement managers.
China
Solar PV and energy storage deployments require massive DC protection volumes across utility-scale farms. GB/T 14048.2 standards create parallel compliance obligations for manufacturers serving domestic installations. Manufacturing gravity concentrates in Jiangsu and Zhejiang provinces where component suppliers feed integrated production lines.
Germany
Heat pump and electric vehicle charger deployments strain legacy AC-to-DC conversion pathways across residential and commercial segments. EU F-Gas Regulation accelerates electrification mandates that reshape breaker specifications. Industrial automation bundling expands in Baden-Württemberg and Bavaria where factory OEMs specify coordinated protection systems.
United States
Hyperscale data center construction in Northern Virginia compresses fault-clearance requirements from milliseconds to microseconds. National Electrical Code provisions indirectly shape DC breaker specifications through accelerated charger deployments. The Phoenix-Ashburn-Dallas corridor concentrates procurement decisions among narrowing sets of engineering firms and general contractors.
India
PLI scheme incentives for solar module manufacturing stimulate downstream demand for DC protection equipment. Central Electricity Authority mandates tighten grid integration standards for renewable installations. Gujarat and Rajasthan utility-scale solar parks anchor procurement volumes for combiner box and inverter protection.
Japan
Factory automation systems in automotive and electronics manufacturing specify DC breakers bundled with industrial control equipment. METI efficiency standards drive upgrades across aging industrial power distribution infrastructure. Nagoya and Osaka industrial corridors concentrate demand from precision manufacturing facilities.
Low Voltage DC Circuit Breaker Market Vendor Landscape
Global majors compete with regional champions across certification standards and channel access. The vendor base separates into three tiers: integrated electrical conglomerates with full distribution networks, specialized breaker manufacturers with thermal-magnetic expertise, and emerging solid-state technology developers. Strategic moves concentrate on M&A for geographic footprint expansion and technology licensing for semiconductor-based interruption capabilities.
Within the integrated conglomerate tier, Schneider Electric SE and Siemens AG exemplify archetypes combining factory automation presence with deep electrical distribution partnerships. Eaton Corporation PLC occupies a position among thermal-magnetic specialists serving harsh-environment installations. CHINT Global represents the regional champion model with concentrated manufacturing in Chinese solar supply clusters. These three anchors illustrate competitive positioning across certification breadth, application specialization, and geographic supply concentration.
| Leading Market Players |
|---|
| Eaton Corporation PLC |
| Fuji Electric Co. Ltd. |
| ABB Ltd |
| CHINT Global |
| LS ELECTRIC Co., Ltd. |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Rockwell Automation Inc. |
| Siemens AG |
| Others |
Supply Flow & Price Mechanics
Hyperscale data center OEMs in Northern Virginia and Frankfurt concentrate procurement decisions among narrowing engineering firm panels, compressing price negotiation leverage and forcing tiered pricing structures that unbundle warranty terms from base hardware costs.
Pricing Analysis
Warranty and service bundling separates premium-tier suppliers from standard offerings in this market, with extended arc-flash testing coverage and predictive maintenance software commanding 15-25% uplifts over transactional unit sales. Price differentiation hinges on dual IEC 60947-2 and UL 489-SA certification status plus after-sales service integration. Cost compression in the electromechanical tier intensifies as copper feedstock volatility squeezes magnetic blowout coil margins. Renewable energy EPC contractors in India and China exhibit highest price sensitivity, while hyperscale operators prioritize microsecond response specifications over unit economics.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Los Angeles anchor hub-and-spoke patterns that feed electrical distributor networks across Europe, Asia-Pacific, and North America. Manufacturing gravity centers on Jiangsu and Zhejiang provinces in China for solar-grade breaker production, with Germany and Japan anchoring precision electromechanical component supply. Copper cathode and silicon carbide wafer inputs draw from Chilean mining operations and Taiwanese foundries respectively. Single-source vulnerability concentrates in rare earth magnetic materials for blowout coils. Distribution runs through authorized electrical distributor channels with master service agreement direct sales gaining share in data center verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive control over silicon carbide semiconductor switching elements and arc-quenching magnetic coil production determines margin sustainability across solid-state and hybrid product transitions.
For Market Incumbents: To counter solid-state substitution in hyperscale 380V DC busway applications, Schneider Electric and Siemens must accelerate thyristor-based hybrid breaker R&D through in-house semiconductor switching element production, while locking exclusive channel partnerships with electrical distributors serving EU Green Deal-mandated renewable installations. For New Entrants and Emerging Players: Direct-to-OEM digital sales platforms bypass incumbent distributor control and unlock penetrable white-space in marine DC microgrid applications where Lloyd's Register and DNV certification requirements have kept specialized players out, and in India's PLI-stimulated solar manufacturing clusters where local content rules favor domestic assembly partnerships. For Investors and Strategic Acquirers: The window for entry favors solid-state technology developers with proven thyristor switching speeds below 500 microseconds; long-term viability hinges on acquisition of semiconductor packaging capabilities rather than pure electromechanical assets, with inflection signaled by IEC arc-flash testing protocol revisions that could obsolete conventional magnetic blowout architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Semiconductor Production | Captive thyristor supply secures hybrid breaker margins against foundry allocation constraints. |
| Dual Certification Fast-Track Program | Parallel IEC 60947-2 and UL 489-SA approval compresses time-to-revenue for export markets. |
| Digital Twin Platform Development | Predictive maintenance software shifts revenue from hardware sales to recurring service contracts. |
| Marine-Specific Corrosion-Resistant Product Line | Lloyd's Register and DNV compliance unlocks battery-electric propulsion system specifications. |
| India Manufacturing Joint Venture | PLI scheme incentives and CEA grid integration mandates localize supply for utility-scale solar parks. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs that were cross-referenced against primary interviews with data center power infrastructure directors, renewable energy EPC procurement leads, electrical distributor category managers, and marine classification society surveyors. NEMA, ZVEI, and CECA publications supplemented IEC and UL certification databases. Bottom-up installation forecasts across hyperscale facilities and utility-scale solar parks were triangulated against top-down copper consumption and magnetic component trade flows.
Segment-level modeling addressed product type, end-use vertical, installation configuration, and interruption technology across the projection horizon. CAGRs were derived from fitted growth curves applied to annual procurement volumes by facility type. Forecast inputs incorporated hyperscale construction pipeline tracking, EU Green Deal implementation timelines, and silicon carbide adoption curves in power conversion equipment.
The model holds under stable copper price regimes and sustained hyperscale data center investment; deviation in semiconductor material transitions or arc-flash testing protocol revisions would shift technology adoption timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Global Data Center Transformer Market
Power Systems
Digital Inverter Market
Power Systems
Silicon-Controlled Rectifier (SCR) Market
Power Systems
Smart Junction Box and Power Distribution Box Systems Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Automotive Inverters Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
AC DC Power Adapter Market
Power Systems
Grid Forming Inverters Market
Power Systems
Switch Mode Power Supply (SMPS) Market
Power Systems
Burner Management System (BMS) Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Southeast Asia Uninterruptible Power Supply (UPS) Market
Power Systems
PV Micro Inverters Market