
 Integrated UPS Market | 2026-2036
Integrated UPS Market Size, Share, and Industry Trends Forecast 2026-2036
Integrated UPS Market Outlook
High-efficiency double conversion topology is rotating toward dominance as data center operators demand sub-3% total harmonic distortion and 96%+ operating efficiency. Schneider Electric leverages its EcoStruxure platform to anchor software-defined power management across hyperscale facilities. Eaton competes through specialized industrial UPS configurations that sustain uptime in heavy manufacturing environments. Huawei extends its position in Asia-Pacific through integrated lithium-ion battery architectures that reduce footprint by half versus legacy valve-regulated lead-acid systems.
An integrated uninterruptible power supply combines rectifier, battery, inverter, and static switch into a single enclosure designed to deliver conditioned power during grid disturbances or outages. These systems employ insulated-gate bipolar transistor switching at 16-20 kHz frequencies to achieve fast transfer times below 4 milliseconds, protecting sensitive semiconductor fabrication equipment and server racks from voltage sags. Above 10 kVA power rating systems generate the largest revenue pool as hyperscale data centers consolidate backup power into fewer, larger units. Rack-mounted installation formats grow fastest at the margin as edge computing nodes proliferate in telecommunications closets and retail locations where floor space commands premium lease rates.
The U.S. Department of Energy enforces efficiency standards under 10 CFR Part 431 that disqualify standby UPS designs below 85% efficiency from federal procurement, redirecting institutional buyers toward line-interactive and double conversion alternatives. India's Bureau of Energy Efficiency mandates star ratings under its Standards and Labeling program that increase compliance costs for imported units while creating preference for locally tested products. Europe's Ecodesign Directive and Restriction of Hazardous Substances rules constrain battery chemistry choices and end-of-life disposal pathways. Stakeholders must monitor how lithium-ion thermal runaway testing protocols evolve across jurisdictions before committing to next-generation energy storage integrations.
Market Dynamics
Double conversion topology is displacing legacy standby architectures as hyperscale data center operators mandate sub-4 millisecond transfer times and 96%+ efficiency floors under U.S. Department of Energy procurement rules.
Growth Catalysts
- 10 CFR Part 431 efficiency mandates:Federal procurement disqualification below 85% efficiency redirects institutional buyers toward line-interactive and double conversion systems.
- Cloud computing workload expansion:Data center operators in Northern Virginia and Dallas-Fort Worth consolidate backup power into fewer, larger above-10 kVA units.
- Lithium-ion battery chemistry:Integrated architectures halve footprint versus valve-regulated lead-acid systems, unlocking premium lease-rate spaces.
Market Restraints
- Raw material concentration:Insulated-gate bipolar transistor supply chains concentrate in East Asian foundries, exposing manufacturers to geopolitical friction.
- Thermal runaway testing fragmentation:Evolving lithium-ion safety protocols across jurisdictions delay product certification cycles.
- Copper and rare earth price volatility:Input cost swings compress margin structures for systems above 100 kVA.
Strategic Opportunities
- Edge computing node proliferation:Rack-mounted formats penetrate telecommunications closets and retail locations where floor space commands premium rates.
- India's Bureau of Energy Efficiency star ratings:Compliance costs for imports create preference for locally tested products in industrial parks.
- Software-defined power management:Convergence of IoT sensors and predictive analytics enables remote monitoring contracts.
Industry Challenges
- Power electronics engineering scarcity:Specialized talent for 16-20 kHz switching design commands wage premiums that inflate R&D budgets.
- Legacy facility retrofit complexity:Integration with existing static switchgear in semiconductor fabrication plants extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Integrated UPS Market |
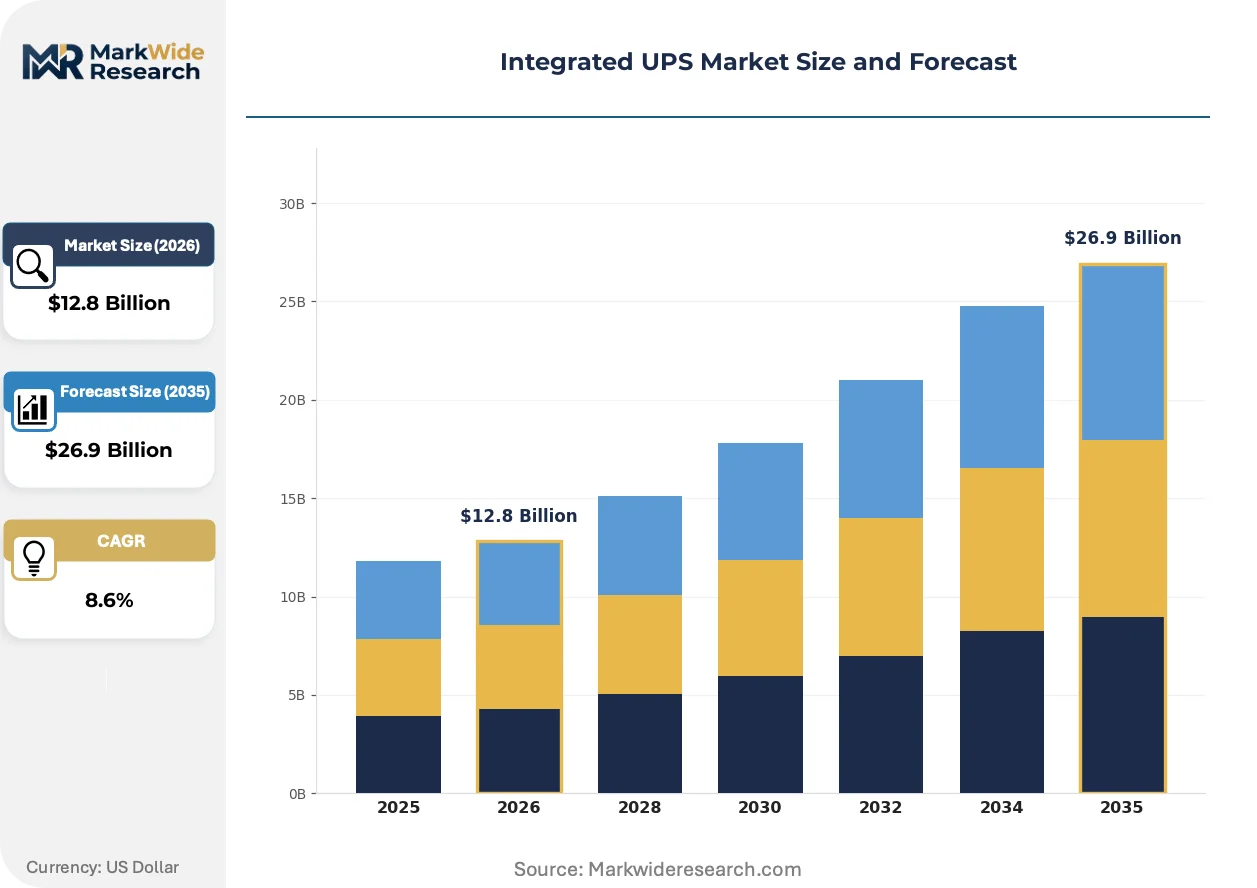
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $26.9 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Power Rating: 1-3 kVA, 3-5 kVA, 5-10 kVA, Above 10 kVA End User: Healthcare Facilities, Data Centers, Manufacturing Units, Telecommunications Installation: On-premises, Wall-mounted, Rack-mounted, Floor-standing Technology: Double Conversion, Line-interactive, Standby, Ferroresonant |
| Companies Covered | Schneider Electric, ABB, Eaton, Vertiv, Huawei, Emerson Electric, TEAL Electronics, GE, Delta Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Integrated UPS Market Strategic Shifts
Power semiconductor architecture is splitting along efficiency-versus-cost lines as end-users segment between hyperscale precision and industrial durability requirements. Three forces are actively reshaping competitive positioning.
Silicon carbide power modules are bifurcating the high-efficiency segment from conventional insulated-gate bipolar transistor designs. Hyperscale operators in Singapore and Frankfurt adopt silicon carbide for 98%+ conversion efficiency at partial loads. The technology is compressing total cost of ownership calculations for facilities above 500 kVA, forcing legacy vendors to defend position through service bundling.
Europe's Ecodesign Directive and Restriction of Hazardous Substances rules constrain battery chemistry choices and mandate end-of-life disposal pathways. Manufacturers must redesign enclosures to accommodate lithium-ion thermal management systems while maintaining CE marking compliance. Industrial UPS configurations face the tightest redesign timelines as the 2027 efficiency tier approaches.
Buying committees now unbundle hardware procurement from long-term service agreements, compressing vendor switching cycles from seven years to four. Systems integrators and direct manufacturer channels displace traditional electrical distributors for above-50 kVA installations. This pattern is most visible in India's pharmaceutical manufacturing corridors, where facility engineers negotiate separate battery replacement and remote monitoring contracts.
Integrated UPS Market Segmentation

Segmentation in the integrated UPS market reveals divergent engineering priorities across power ratings and installation contexts. Procurement patterns split between domestic infrastructure projects and export-led manufacturing for hyperscale deployments.
Power Rating:
Domestic demand concentrates in sub-10 kVA systems for healthcare and light commercial use, while above-10 kVA units drive export volumes to data center clusters in Singapore and Frankfurt.
- 1-3 kVA:Compact single-phase units serve point-of-care medical devices and small office server closets. Demand clusters in India's tier-2 cities where BIS certification requirements favor locally assembled units over imports.
- 3-5 kVA:These systems bridge residential and light commercial applications with modified sine wave or pure sine wave output options. Pharmacy chains in Brazil's São Paulo state specify this range for cold chain monitoring equipment.
- 5-10 kVA:Three-phase entry systems protect mid-size manufacturing lines and branch office data rooms. Germany's KBA automotive testing facilities specify this segment for power quality assurance during vehicle electronics calibration.
- Above 10 kVA:Hyperscale operators in Northern Virginia and Dallas-Fort Worth consolidate backup into fewer, larger double-conversion units. Silicon carbide power modules push efficiency past 98% at partial loads, compressing total cost of ownership for facilities above 500 kVA.
Above 10 kVA holds the largest share; momentum sits with 5-10 kVA as edge computing nodes proliferate.
End User:
Cost tiers separate premium-specification healthcare and data center buyers from price-sensitive manufacturing procurement committees.
- Healthcare Facilities:Operating rooms and imaging suites demand sub-4 millisecond transfer times with isolation transformers. FDA 510(k) clearance requirements for connected medical devices drive specification of line-interactive and double conversion systems over standby alternatives.
- Data Centers:Hyperscale and colocation operators mandate 96%+ efficiency floors under U.S. Department of Energy procurement rules. Lithium-ion battery integrations halve footprint versus legacy valve-regulated lead-acid systems, unlocking premium lease-rate spaces in Singapore and Frankfurt.
- Manufacturing Units:Heavy industrial configurations from Eaton sustain uptime in semiconductor fabrication environments. India's pharmaceutical manufacturing corridors in Hyderabad and Ahmedabad drive demand for above-50 kVA systems with specialized harmonic filtering.
- Telecommunications:Rack-mounted formats penetrate telecommunications closets and 5G edge nodes where floor space commands premium rates. TRAI infrastructure mandates in India accelerate procurement of compact, high-temperature-rated units for outdoor cabinet deployments.
Data centers command premium pricing; telecommunications is expanding most quickly as 5G infrastructure rolls out.
Installation:
Volume concentration shifts toward rack-mounted formats as data center density increases, while floor-standing units retain share in heavy industrial retrofit contexts.
- On-premises:Integrated enclosures combining rectifier, battery, inverter, and static switch suit dedicated electrical rooms in healthcare and manufacturing facilities. India's industrial parks specify these for grid instability protection.
- Wall-mounted:Space-constrained retail locations and small office branches favor this format for 1-5 kVA ranges. Brazil's ANVISA-regulated pharmaceutical distribution points specify wall-mounted units for temperature-controlled storage backup.
- Rack-mounted:19-inch standard enclosures serve edge computing nodes and telecommunications infrastructure. Lease rate premiums in Singapore's data center market drive fastest adoption of this format.
- Floor-standing:Above-100 kVA industrial configurations require reinforced concrete pads and dedicated HVAC. Germany's automotive manufacturing corridors specify these for robotic welding line protection.
Floor-standing retains the largest installed base; rack-mounted is gaining share fastest as edge infrastructure deploys.
Technology:
Maturity curves separate established double conversion and line-interactive architectures from declining standby and niche ferroresonant designs.
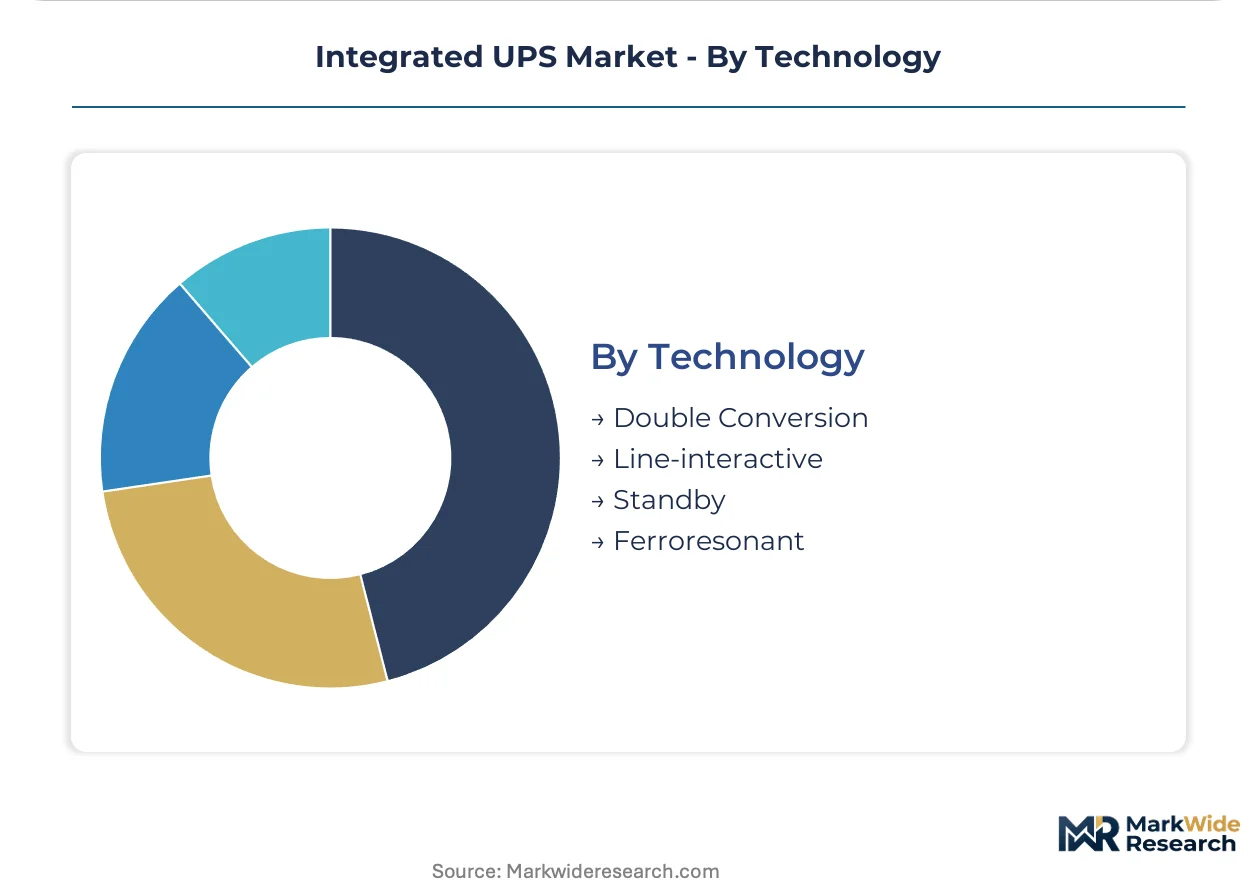
- Double Conversion:AC-to-DC-to-AC topology delivers conditioned power with sub-3% total harmonic distortion. U.S. Department of Energy 10 CFR Part 431 mandates above 85% efficiency, disqualifying standby alternatives from federal procurement.
- Line-interactive:Buck-boost voltage regulation with battery backup suits small business and light industrial applications. India's Bureau of Energy Efficiency star ratings create compliance cost advantages for locally tested products in this segment.
- Standby:Offline designs activate only during grid failure, offering lowest cost but 4-8 millisecond transfer times. Europe's Ecodesign Directive efficiency tiers accelerate displacement of this architecture.
- Ferroresonant:Saturated transformer designs provide inherent voltage regulation for heavy industrial motor loads. Niche demand persists in Brazil's mining corridors for crusher and conveyor protection.
Double conversion holds dominant share; line-interactive shows steepest expansion trajectory in cost-sensitive emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export double-conversion systems to hyperscale operators in Northern Virginia and Singapore, while Chinese suppliers ship lithium-ion integrated units to India's industrial corridors.
United States
Data center construction in Northern Virginia and Dallas-Fort Worth drives procurement of above-500 kVA silicon carbide systems. The Department of Energy enforces 10 CFR Part 431 efficiency mandates that disqualify standby designs below 85% from federal procurement. Ashburn's server farm clusters consolidate backup power into fewer, larger double-conversion units to maximize rack density.
Germany
Automotive testing facilities and semiconductor fabrication plants demand sub-3% total harmonic distortion specifications. The KBA automotive regulator mandates power quality assurance during vehicle electronics calibration. Stuttgart's manufacturing corridors specify floor-standing above-100 kVA configurations for robotic welding line protection.
India
Grid instability in industrial parks accelerates deployment of line-interactive and double conversion systems across pharmaceutical and electronics manufacturing. The Bureau of Energy Efficiency mandates star ratings under its Standards and Labeling program that increase compliance costs for imported units. Hyderabad and Ahmedabad corridors drive above-50 kVA procurement with specialized harmonic filtering requirements.
Singapore
Hyperscale operators mandate 98%+ conversion efficiency at partial loads to minimize cooling overhead in tropical climates. The Energy Market Authority enforces building energy efficiency standards that favor lithium-ion battery integrations halving footprint versus legacy systems. Changi data center clusters adopt rack-mounted formats to capture premium lease rates in space-constrained facilities.
Brazil
Pharmaceutical cold chain and mining corridor applications sustain demand for modified sine wave and ferroresonant architectures. ANVISA regulates pharmaceutical distribution point backup power for temperature-controlled storage. São Paulo state's pharmacy chains specify 3-5 kVA wall-mounted units for compliance with distribution integrity standards.
Integrated UPS Market Competitive Environment
Listed leaders compete with private specialists across capitalization and geographic coverage dimensions. The vendor base splits between diversified electrical conglomerates and focused power quality specialists, with tiering evident in R&D intensity and service network density. Strategic archetypes include platform-integrated software providers, industrial durability specialists, and Asia-Pacific cost-optimized fabricators. Dominant competitive moves center on silicon carbide technology licensing partnerships and lithium-ion thermal management system acquisitions.
Within the diversified electrical conglomerate tier, Schneider Electric and Eaton occupy positions spanning software-defined power management platforms through heavy industrial configurations. ABB anchors European high-efficiency engineering capabilities. Vertiv and Huawei exemplify specialists in data center and telecommunications infrastructure respectively. Delta Electronics represents Asia-Pacific manufacturing scale advantages. Emerson Electric and GE sit within the industrial automation and energy infrastructure archetype. TEAL Electronics occupies a position in defense-aerospace qualified power systems.
| Leading Market Players |
|---|
| Schneider Electric |
| ABB |
| Eaton |
| Vertiv |
| Huawei |
| Emerson Electric |
| TEAL Electronics |
| GE |
| Delta Electronics |
| Others |
Value Chain & Pricing Dynamics
Lithium-ion battery substitution for valve-regulated lead-acid systems redraws procurement geography toward East Asian cell manufacturers while compressing total cost of ownership calculations by half, simultaneously concentrating supplier power in integrated enclosure providers and eroding margin pools for legacy battery specialists.
Pricing Analysis
Silicon carbide power module pricing gaps separate incumbent insulated-gate bipolar transistor systems from next-generation 98%-efficiency architectures and legacy standby alternatives. Three-tier pricing structure across premium double-conversion, standard line-interactive, and economy standby levels reflects certification tier differentiation under U.S. Department of Energy 10 CFR Part 431 and customization depth for harmonic filtering. Cost compression in above-100 kVA industrial configurations is intensifying because copper and rare earth price volatility feeds directly into enclosure and magnetics costs. Manufacturing procurement committees exhibit highest price sensitivity, while hyperscale data center operators prioritize efficiency floors over unit economics.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell production and insulated-gate bipolar transistor wafer fabrication, while Taiwan concentrates power semiconductor packaging capacity. Integrated UPS manufacturing draws from copper winding stock, rare earth magnet feedstock, and battery management system controllers as critical inputs. Single-source vulnerability in silicon carbide substrate supply exposes manufacturers to allocation constraints as hyperscale demand surges. Distribution runs through direct manufacturer channels and systems integrators for above-50 kVA installations, displacing traditional electrical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated UPS demand sits in early-cycle expansion as edge computing node proliferation creates first-mover advantages in rack-mounted format penetration, with lithium-ion thermal management integration representing the critical capability gap for vendor differentiation.
For Market Incumbents: Secure silicon carbide power module supply agreements before substrate allocation tightens, and lock in lithium-ion thermal runaway testing certifications across U.S. Department of Energy and India's Bureau of Energy Efficiency jurisdictions to defend against emerging Asia-Pacific cost-optimized fabricators. Vertical integration into battery management system firmware development offers margin protection as hardware commoditizes. For New Entrants and Emerging Players: Anchor in India's pharmaceutical manufacturing corridors where Bureau of Energy Efficiency star rating compliance costs disadvantage imports, and target Brazil's ANVISA-regulated pharmaceutical cold chain for 3-5 kVA wall-mounted specifications. A service-unbundled go-to-market model separating hardware procurement from remote monitoring contracts accelerates customer acquisition against bundled incumbents. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed power quality specialists holding dense service networks in European automotive corridors. Five-to-ten year viability hinges on silicon carbide technology licensing positions and lithium-ion thermal management IP. The signal to watch is silicon carbide substrate allocation announcements from major wafer suppliers as inflection indicator for margin compression timing.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Technology Licensing | 98% efficiency at partial loads compresses total cost of ownership for hyperscale operators in Singapore and Frankfurt. |
| Lithium-Ion Thermal Management Acquisition | Halved footprint versus legacy systems unlocks premium lease-rate spaces in space-constrained facilities. |
| Software-Defined Power Management Platform | EcoStruxure-type convergence enables predictive analytics contracts with remote monitoring revenue streams. |
| India Bureau of Energy Efficiency Certification Investment | Star rating compliance creates preference for locally tested products in Hyderabad and Ahmedabad industrial parks. |
| Rack-Mounted Format Capacity Expansion | 19-inch standard enclosures capture edge computing proliferation in telecommunications closets and retail locations. |
Study Parameters
Operator-level perspectives from data center infrastructure directors, pharmaceutical plant engineers, telecommunications network operators, and power quality procurement managers anchored the qualitative base, triangulated against U.S. Department of Energy efficiency filings, India's Bureau of Energy Efficiency star rating databases, hyperscaler capex disclosures, and customs trade records for insulated-gate bipolar transistor and lithium-ion cell imports. Bottom-up unit economics and top-down market sizing converged through iterative validation.
Sensitivity analysis across power rating tiers, installation formats, and technology generations structured the analytical framework over the projection horizon. Segmentation dimensions modeled include power rating bands, end-user verticals, installation contexts, and topology architectures. CAGRs derived from shipment volume trajectories and average selling price evolution, with silicon carbide adoption curves and lithium-ion penetration rates as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of continued hyperscale data center construction and stable lithium-ion safety protocol harmonization; material deviation in either driver would warrant model refresh. Recalibration cycles align with material shifts in Department of Energy efficiency tier updates and thermal runaway testing protocol finalization across jurisdictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Shunt Capacitor Market
Power Systems
Asia Pacific Solid State Transformers Market
Power Systems
APAC Variable Frequency Drives Market
Power Systems
Piezoelectric Energy Harvesting System Market
Power Systems
Solid State Transformer Market
Power Systems
Distribution Voltage Regulator Market
Power Systems
Photovoltaic Inverters Market
Power Systems
Power Semiconductor Market
Power Systems
Embedded Power Generation Market
Power Systems
Asia-Pacific DC Distribution Networks Market
Power Systems
Hybrid Inverters Market
Power Systems
Asia Pacific Battery Management System Market
Power Systems
Global Excitation Systems Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
Global Data Center Transformer Market
Power Systems
Thyristor Market