
 Analog to Digital Converter Market | 2026-2036
Analog to Digital Converter Market Size, Share, and Industry Trends Forecast 2026-2036
Analog to Digital Converter Market Intelligence
The capital-intensity divergence between foundry-dependent and IDM-backed players is rotating competitive leverage toward vertically integrated manufacturers. Texas Instruments sustains cost advantages through captive 300mm analog fabrication in Richardson, Texas. Analog Devices Inc. differentiates via high-performance delta-sigma architectures for precision instrumentation. STMicroelectronics leverages European automotive qualification pipelines to anchor its industrial-grade ADC portfolio.
An analog-to-digital converter translates continuous voltage signals into discrete digital words, typically achieving resolutions from 8 to 24 bits and sample rates spanning kilohertz to gigahertz ranges for measurement, control, and communication systems. Flash conversion technology dominates ultra-high-speed segments where sub-nanosecond latency matters, while sigma-delta architectures occupy precision audio and sensor interfaces where noise shaping delivers superior dynamic range. Embedded deployment configurations are capturing margin pools as system designers eliminate standalone converter modules in favor of SoC-integrated acquisition channels.
FDA electromagnetic compatibility requirements for medical devices, FCC Part 15 emissions rules for consumer electronics, and EU CE marking under the Radio Equipment Directive collectively shape ADC performance specifications and market access conditions. The EU AI Act and emerging MDR cybersecurity annexes are adding functional-safety and data-integrity layers to converter qualification protocols. Stakeholders must monitor whether automotive OEMs will mandate ASIL-D rated ADC subsystems for autonomous sensor fusion arrays.
Market Dynamics
Precision sensing requirements in industrial automation are compressing design cycles for embedded acquisition subsystems, forcing ADC suppliers to integrate signal-conditioning and isolation functions that previously resided on separate boards.
Growth Catalysts
- EU Green Deal energy-efficiency mandates:Embedded measurement systems in motor drives and power inverters must now meet stricter consumption thresholds, accelerating 16-bit and higher-resolution ADC deployment across European industrial equipment.
- Automotive sensor fusion architectures:Lidar, radar, and camera arrays in autonomous vehicle prototypes require synchronized multi-channel acquisition, pulling 24-bit delta-sigma converters into qualification pipelines.
- Germany's automotive electronics corridor:Munich-Stuttgart supplier density creates localized demand concentration for AEC-Q100 qualified industrial-grade converters serving powertrain and chassis control modules.
Market Restraints
- 300mm analog wafer supply concentration:Captive fab capacity at dominant IDMs limits foundry access for fabless competitors, constraining volume scaling for mid-tier precision ADC suppliers.
- Raw silicon substrate cost volatility:Polysilicon and epitaxial wafer price swings compress gross margins on commodity 8-bit and 12-bit converter families.
- Flash ADC power-density limitations:Thermal dissipation constraints above 4 GSPS sample rates restrict deployment in portable instrumentation and battery-operated field equipment.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Design-linked incentives for semiconductor packaging and testing create entry points for ADC module assembly serving industrial automation exports.
- Time-sensitive networking convergence:IEEE 802.1AS synchronization requirements in factory automation are pulling ADC-PHY integrated solutions into motion control and robotic feedback loops.
- EU AI Act data-integrity requirements:Functional-safety rated acquisition channels for autonomous decision systems create premium positioning for ASIL-B and ASIL-D qualified converter subsystems.
Industry Challenges
- Mixed-signal design talent scarcity:Expertise in noise-shaping architectures and calibration algorithms concentrates at established IDMs, constraining fabless innovation pipelines.
- Multi-standard certification timelines:Simultaneous AEC-Q100, IEC 61508, and FDA EMC qualification cycles extend product launch windows by 18-24 months for medical-automotive crossover applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Analog to Digital Converter Market |
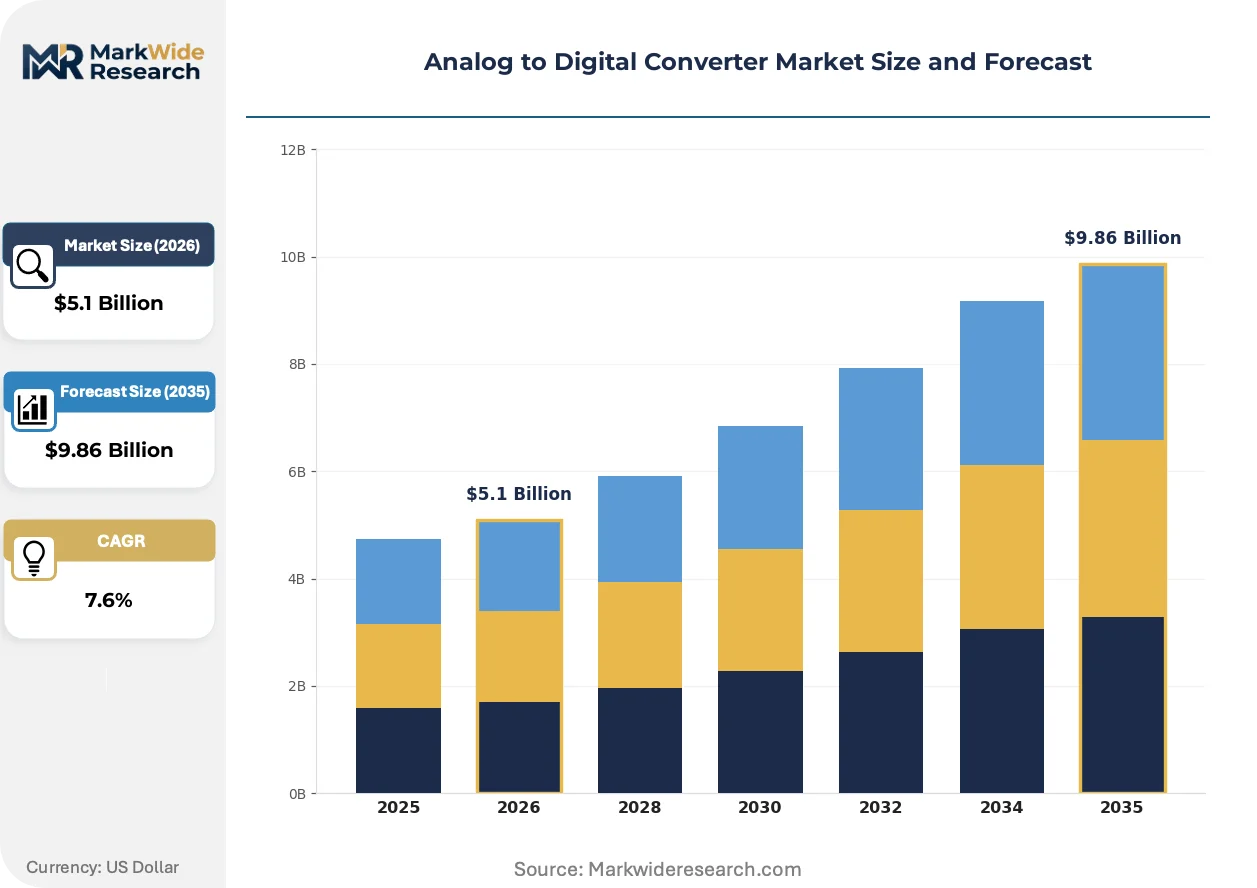
| Market Size in 2026 | $5.1 Billion |
| Market Size in 2035 | $9.86 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low-Speed ADCs, High-Speed ADCs, Pipelined ADCs, Delta-Sigma ADCs Technology: Flash Conversion, Successive Approximation, Sigma-Delta, Dual-Slope End User: Consumer Electronics, Telecommunications, Automotive, Industrial Automation Deployment: Embedded Systems, Standalone Units, Distributed Systems, Integrated Designs |
| Companies Covered | Texas Instruments, Analog Devices Inc., STMicroelectronics, NXP Semiconductors, Renesas Electronics Corporation, Infineon Technologies, Microchip Technology Inc., ON Semiconductor, Cirrus Logic Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analog to Digital Converter Market Strategic Shifts & Innovations
Signal-chain integration is collapsing discrete component boundaries as system architects eliminate standalone converter modules in favor of acquisition channels embedded within SoCs and intelligent sensors.
Sigma-delta modulation with continuous-time loop filters is decomposing the traditional anti-aliasing filter block in precision audio and vibration monitoring equipment. Medical device manufacturers in Switzerland and Germany are adopting these architectures for EEG and ECG front-ends, compressing bill-of-materials counts while maintaining 24-bit effective resolution. The structural consequence is margin pressure on discrete filter component suppliers as integrated noise-shaping absorbs their function.
The EU F-Gas Regulation and REACH substance restrictions are tightening material disclosure requirements for embedded measurement systems deployed in refrigeration and HVAC controls. Converter suppliers must now document halogen-free substrate compositions and tin-whisker mitigation plating for CE marking acceptance. Industrial equipment OEMs in France and Italy are responding by qualifying alternative package technologies ahead of 2025 compliance deadlines.
Consolidated procurement of signal-chain subsystems is displacing discrete ADC purchasing in mid-volume industrial automation. System integrators in Japan and South Korea now specify complete acquisition channels—amplifier, filter, converter, isolation—in single supplier agreements rather than optimizing individual components. This concentration is most visible in semiconductor fabrication equipment, where toolmakers standardize on qualified supplier lists to reduce qualification overhead.
Analog to Digital Converter Market Segmentation
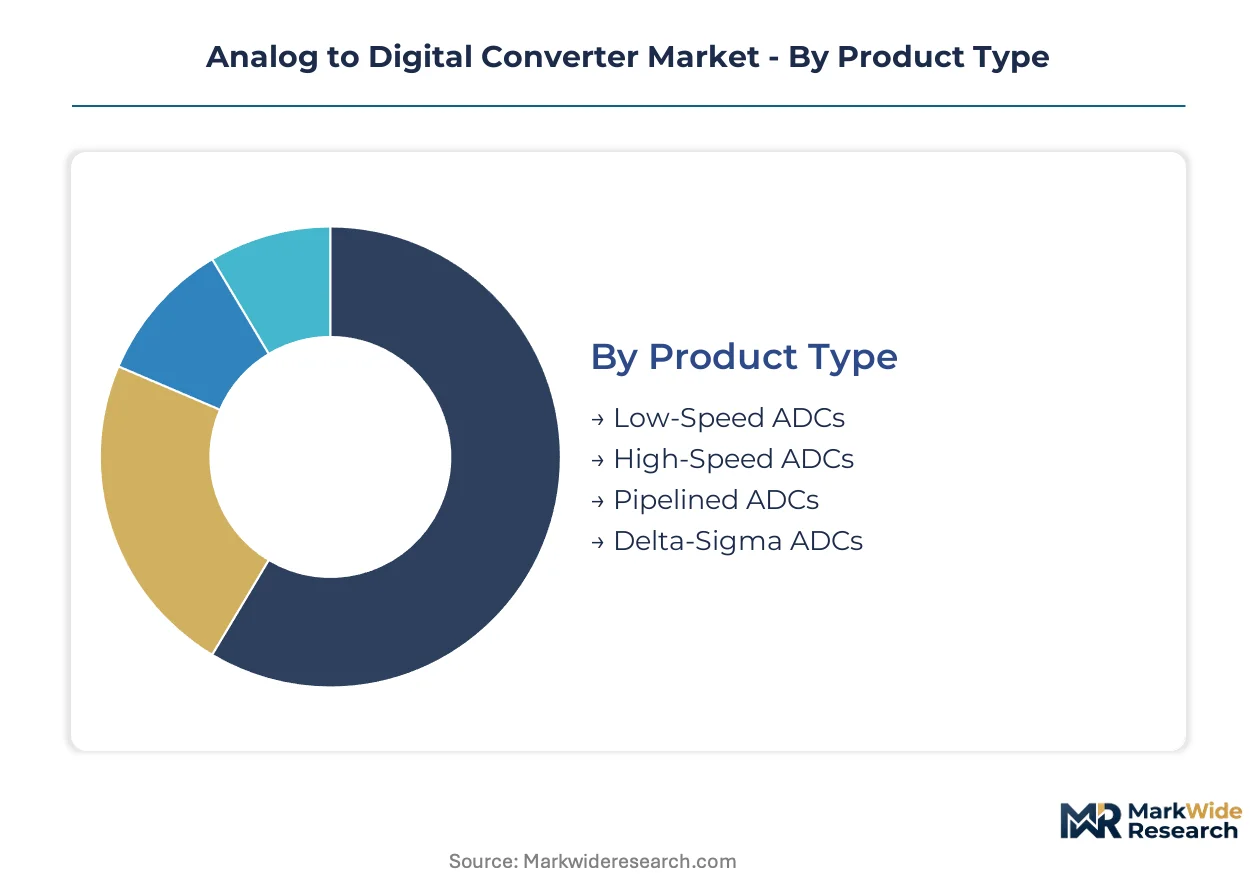
ADC segmentation reveals divergent margin structures across precision tiers and integration levels. Product architecture choices directly determine qualification pathways and geographic addressability for suppliers.
Product Type:
Domestic consumption patterns in Germany and Japan favor precision architectures, while export-led demand from China's industrial automation sector concentrates in high-speed variants.
- Delta-Sigma ADCs:Noise-shaping architectures achieve 24-bit effective resolution through oversampling and digital filtering. Medical device manufacturers in Switzerland and Germany deploy these for EEG and ECG front-ends where dynamic range requirements exceed 120 dB. The EU MDR cybersecurity annexes are extending qualification timelines for clinical-grade delta-sigma subsystems.
- High-Speed ADCs:Pipelined and flash-interleaved structures sample beyond 1 GSPS for software-defined radio and 5G baseband processing. Telecommunications infrastructure deployment in South Korea and Japan pulls these into high-volume production, though thermal constraints above 4 GSPS limit portable applications.
- Low-Speed ADCs:Successive-approximation architectures dominate battery-powered sensor nodes and IoT endpoints.
- Pipelined ADCs:Multi-stage conversion balances speed and resolution for radar signal processing and instrumentation.
Delta-Sigma ADCs hold the largest share; momentum sits with High-Speed ADCs.
Technology:
Cost tier stratification separates premium continuous-time sigma-delta implementations from commodity flash converters in high-volume consumer applications.
- Sigma-Delta:Continuous-time loop filters eliminate discrete anti-aliasing components, compressing bill-of-materials counts for audio and vibration monitoring. Industrial equipment OEMs in France and Italy qualify these for HVAC control loops ahead of EU F-Gas Regulation deadlines.
- Flash Conversion:Parallel comparator banks achieve sub-nanosecond latency for radar and electronic warfare receivers. Defense procurement in the US and UK sustains niche demand despite power-density limitations that restrict battery-operated deployment.
- Successive Approximation:Binary-search algorithms deliver moderate speed at low power for embedded microcontroller integration.
- Dual-Slope:Integrating architectures provide noise immunity for precision multimeters and industrial process control.
Sigma-Delta dominates precision applications; Flash Conversion maintains niche defense demand.
End User:
Application-driven qualification requirements fragment the customer base across automotive safety integrity levels and medical electromagnetic compatibility standards.
- Automotive:Lidar, radar, and camera fusion arrays require synchronized multi-channel acquisition with ASIL-B to ASIL-D functional safety ratings. Munich-Stuttgart supplier density creates localized procurement concentration for AEC-Q100 qualified converters serving powertrain modules.
- Industrial Automation:Motor drives and power inverters deploy 16-bit and higher-resolution ADCs to meet EU Green Deal energy-efficiency mandates for embedded measurement systems. Time-sensitive networking requirements in Japanese and South Korean fabrication equipment standardize complete acquisition channel procurement.
- Consumer Electronics:Smartphones and wearables integrate low-power SAR converters within SoC audio codecs.
- Telecommunications:5G massive MIMO and millimeter-wave base stations consume high-speed pipelined architectures.
Automotive commands premium pricing; Industrial Automation shows steepest expansion trajectory.
Deployment:
Supply concentration favors integrated design specialists with captive mixed-signal fabrication, while standalone unit suppliers face margin compression from module consolidation.
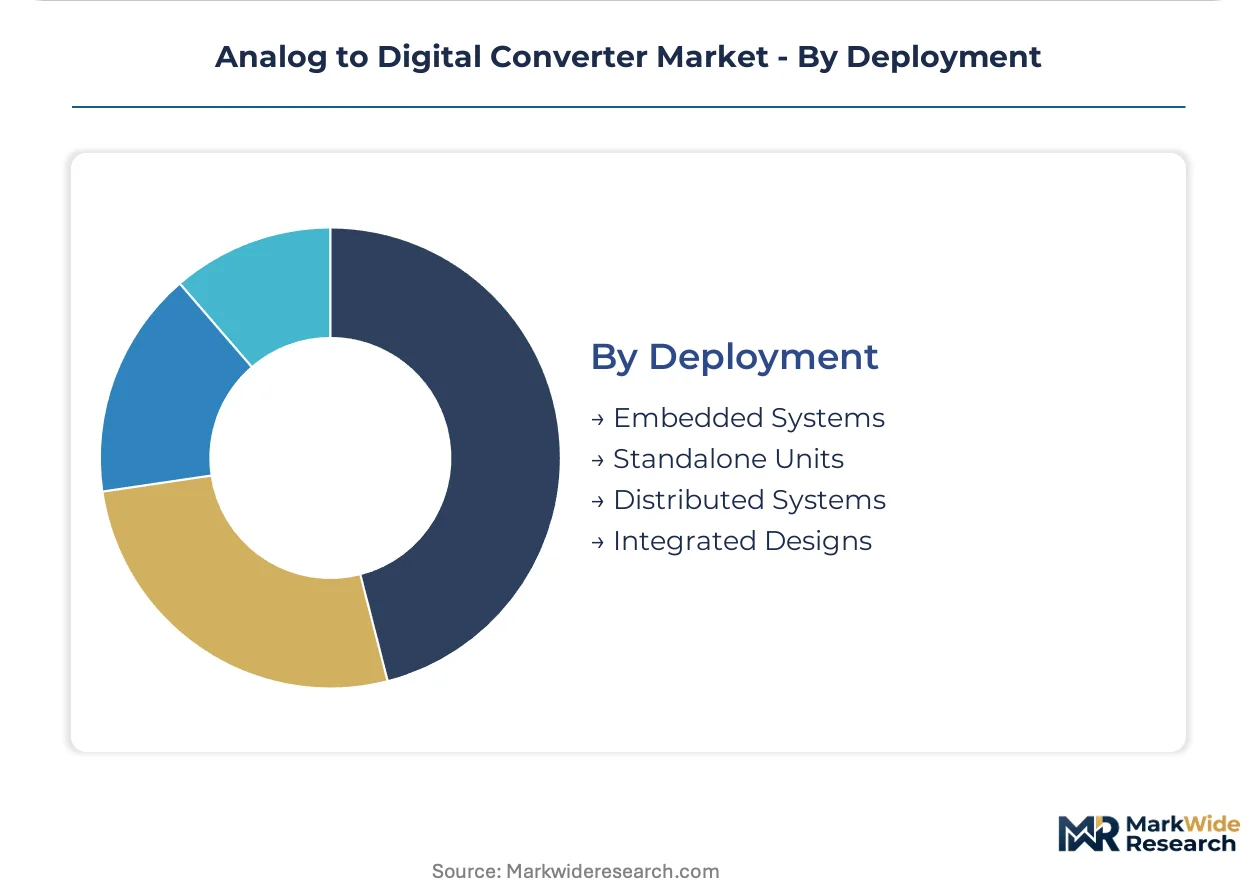
- Integrated Designs:SoC-embedded acquisition channels eliminate discrete converter modules, collapsing signal-chain boundaries. Texas Instruments and Analog Devices leverage captive 300mm analog fabrication to anchor integrated design supply for automotive and industrial customers.
- Embedded Systems:Microcontroller-integrated ADC peripherals serve cost-constrained sensor nodes and edge devices. India's PLI scheme for electronics manufacturing creates assembly opportunities for embedded ADC modules targeting industrial automation exports.
- Standalone Units:Modular data acquisition systems persist in test and measurement applications requiring field reconfigurability.
- Distributed Systems:Networked sensor arrays with edge preprocessing serve smart factory and building automation deployments.
Integrated Designs capture expanding margin pools; Embedded Systems scale fastest in emerging manufacturing geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German automotive electronics corridors where AEC-Q100 qualification commands premiums, while Chinese industrial automation buyers extract volume discounts through consolidated procurement of mid-tier precision converters.
United States
Defense procurement sustains niche demand for flash conversion architectures in radar and electronic warfare receivers. FCC Part 15 emissions rules shape ADC performance specifications for consumer electronics market access. Richardson, Texas hosts captive 300mm analog fabrication serving integrated design supply for automotive and industrial customers.
Germany
Motor drives and power inverters deploy 16-bit and higher-resolution ADCs to meet EU Green Deal energy-efficiency mandates for embedded measurement systems. The F-Gas Regulation and REACH substance restrictions tighten material disclosure requirements for HVAC control applications. Munich-Stuttgart supplier density creates localized procurement concentration for AEC-Q100 qualified converters serving powertrain modules.
China
Industrial automation export manufacturing pulls high-speed pipelined architectures into volume production for semiconductor fabrication equipment. MIIT standards and dual carbon goals accelerate precision sensing deployment in motor control systems. Yangtze River Delta electronics manufacturing clusters concentrate module assembly for time-sensitive networking convergence in factory automation.
Japan
Telecommunications infrastructure deployment consumes high-speed pipelined ADCs for 5G massive MIMO and millimeter-wave base stations. METI industrial policy supports domestic qualification of complete acquisition channel subsystems. Nagoya-Tokyo supplier corridors standardize on qualified supplier lists to reduce qualification overhead in semiconductor fabrication equipment.
South Korea
5G baseband processing and software-defined radio applications drive demand for gigasample-per-second conversion architectures. National semiconductor competitiveness programs anchor high-volume production of telecommunications-grade converters. Seoul-Incheon industrial complexes integrate ADC-PHY solutions for motion control and robotic feedback loops in smart factory deployments.
Analog to Digital Converter Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated IDMs sustaining fabrication advantages while fabless specialists concentrate on high-performance architectures. The vendor base separates into three strategic tiers: captive-fabrication scale players, precision-architecture specialists, and automotive-qualified European suppliers. Dominant competitive moves include backward integration into 300mm analog wafer production and portfolio diversification through signal-chain integration that collapses discrete converter boundaries.
Within the captive-fabrication tier, Texas Instruments and Analog Devices exemplify scale-driven positioning through in-house 300mm production. STMicroelectronics occupies a position within the European automotive-qualified supplier archetype, leveraging regional certification pipelines. These three anchors represent divergent strategic vectors: cost leadership through upstream wafer control, performance leadership through precision architecture specialization, and qualification leadership through regional automotive integration.
| Leading Market Players |
|---|
| Texas Instruments |
| Analog Devices Inc. |
| STMicroelectronics |
| NXP Semiconductors |
| Renesas Electronics Corporation |
| Infineon Technologies |
| Microchip Technology Inc. |
| ON Semiconductor |
| Cirrus Logic Inc. |
| Others |
Cost & Logistics Intelligence
AEC-Q100 automotive qualification gates both supply access and price differentiation simultaneously, compressing margin structures for non-qualified suppliers while allowing IDMs with captive fabrication to command configured-to-order premiums for ASIL-rated delta-sigma architectures serving Munich-Stuttgart powertrain procurement clusters.
Pricing Analysis
Configured-to-order pricing for ASIL-D qualified delta-sigma converters commands spreads exceeding standard catalog pricing by factors tied to certification investment recovery. Three-tier pricing structure across automotive-qualified, industrial-grade, and consumer-integrated levels separates buyers by functional-safety requirements and volume commitments. Cost compression in commodity 8-bit and 12-bit SAR families intensifies as Chinese industrial automation buyers consolidate procurement of mid-tier precision converters. Automotive OEMs exhibit lowest price sensitivity due to liability exposure in autonomous sensor fusion arrays, while IoT endpoint manufacturers drive hardest bargain negotiations on microcontroller-integrated peripherals.
Supply Chain Analysis
Extended lead times for 300mm analog wafers from Richardson, Texas and Dresden, Germany constrain inventory flexibility across the qualified supplier base. Taiwan, South Korea, and the United States anchor front-end fabrication for high-speed pipelined architectures, while Malaysia, Vietnam, and India concentrate back-end test and assembly for embedded modules. Polysilicon substrate costs and epitaxial wafer availability feed margin volatility at foundry-dependent competitors. Single-source vulnerability concentrates in 300mm analog-capable IDM capacity, with distribution running through authorized franchised channels for automotive-qualified tiers and spot-market brokers for commodity consumer-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market, with EU AI Act functional-safety mandates accelerating penetration of ASIL-rated acquisition channels into autonomous decision systems previously served by unqualified industrial-grade alternatives.
For Market Incumbents: Fortify qualification moats by accelerating AEC-Q100 and IEC 61508 dual-certification pipelines for medical-automotive crossover applications, compressing 18-24 month launch windows that currently cede share to STMicroelectronics' European automotive integration. Deepen backward integration into 300mm analog wafer production to deny foundry access for fabless competitors targeting industrial automation consolidation procurement.
For New Entrants and Emerging Players: Post-silicon calibration service gaps in precision delta-sigma deployments create entry points where Texas Instruments and Analog Devices under-serve mid-volume industrial automation buyers lacking in-house noise-shaping expertise. Target India's PLI-linked electronics manufacturing clusters for ADC module assembly serving export-oriented factory automation equipment. Pursue design-linked incentive partnerships with domestic Indian system integrators rather than direct IDM competition.
For Investors and Strategic Acquirers: EU AI Act data-integrity requirements reshape the acquisition landscape toward functional-safety-rated mixed-signal specialists with existing ASIL-B through ASIL-D qualification pipelines. Five-to-ten year viability favors vertically integrated precision-architecture players over fabless commodity converters exposed to raw silicon cost volatility. Watch for automotive OEM mandating of ASIL-D rated ADC subsystems in autonomous sensor fusion arrays as the definitive demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q100 Dual Certification Acceleration | Shortens 18-24 month launch windows for medical-automotive crossover applications against STMicroelectronics. |
| 300mm Analog Wafer Capacity Expansion | Captive Richardson or Dresden fabrication denies foundry access to fabless competitors in precision tiers. |
| India PLI Module Assembly Partnership | Design-linked incentives anchor export-oriented supply for industrial automation consolidation procurement. |
| Continuous-Time Sigma-Delta IP Acquisition | Eliminates discrete anti-aliasing filter BOM counts for EU F-Gas Regulation HVAC control compliance. |
| Time-Sensitive Networking PHY Integration | IEEE 802.1AS synchronization captures motion control and robotic feedback loop specifications in South Korea. |
Research Approach
Cross-validation between primary fieldwork with mixed-signal design directors and secondary SEC 10-K filings anchors the qualitative findings in documented financial performance of captive-fabrication IDMs. Semiconductor fabrication equipment procurement managers, automotive Tier 1 supplier quality engineers, industrial automation system integrators, and medical device EMC compliance officers provided forward-looking demand calibration. FDA 510(k) filings, ECHA REACH substance registrations, EU MDR technical documentation, and MIIT equipment-type approvals supplied regulatory constraint boundaries. Bottom-up unit shipment estimates triangulate against top-down wafer capacity absorption data from 300mm analog-capable foundries.
Sensitivity analysis across sample rate, resolution tier, and integration level segmentation dimensions stress-tests volume and value outputs over the projection horizon. Pipelined, flash, sigma-delta, and SAR technology categories cross-reference against automotive, industrial automation, telecommunications, and medical end-use applications. CAGRs derive from fitted adoption curves incorporating EU Green Deal energy-efficiency mandate compliance deadlines and automotive sensor fusion architecture deployment timelines. Raw silicon substrate cost volatility and AEC-Q100 qualification cycle duration constitute primary forecast uncertainty inputs.
Forecasts assume regulatory continuity in EU F-Gas Regulation, EU AI Act, and FDA EMC regimes; material policy shifts would require re-modeling of compliance cost burdens and qualification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Schottky Rectifiers Market
Semiconductor Devices
High Resistivity Silicon Wafers Market
Semiconductor Devices
Europe Microcontroller Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
Semiconductor in Phones Market
Semiconductor Devices
North America Silicon Carbide Wafers Market
Semiconductor Devices
Taiwan Discrete Semiconductor Market
Semiconductor Devices
Global Through Silicon via (TSV) Technology Market
Semiconductor Devices
Global ASIC Bitcoin Mining Hardware Market
Semiconductor Devices
Silicon Wafer Market
Semiconductor Devices
Silicon Carbide (SIC) Power Semiconductors Market
Semiconductor Devices
Leap Engine Market
Semiconductor Devices
Semiconductor Memory Market
Semiconductor Devices
Asia-Pacific Semiconductor (Silicon) Intellectual Property Market
Semiconductor Devices
Topcon Solar Cell Market
Semiconductor Devices
Middle East and Africa Silicon Carbide Wafers Market