
 China Pressure Sensors Market | 2026-2036
China Pressure Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
China Pressure Sensors Market Outlook
Industrial process control buyers are collapsing as electric vehicle manufacturers become the dominant procurement archetype in China's pressure sensor landscape. Bosch leverages its integrated MEMS fabrication capabilities to anchor automotive safety module supply chains. Honeywell International Inc. sustains aerospace-grade certification dominance through dual-use technology transfer from US operations. Xi'an UTOP Measurement Instrument Co.,Ltd competes on high-temperature oil-and-gas specifications for domestic energy infrastructure.
A pressure sensor transduces fluid or gas pressure into an electrical signal through piezoresistive, capacitive, or resonant sensing elements, typically operating across ranges from millibars to thousands of bars with accuracy thresholds of 0.1% full scale or tighter. These devices enable closed-loop control in process automation, tire pressure monitoring, and respiratory equipment by converting mechanical stress into quantifiable voltage or digital outputs. Gauge sensors occupy the highest volume tier across Chinese industrial applications where vented-reference atmospheric compensation proves essential. Piezoresistive technology leads in unit economics due to silicon micromachining scale, though capacitive architectures are gaining share in corrosive media environments. Automotive end-use commands the largest value pool as NEV battery thermal runaway protection mandates multiply sensor counts per vehicle platform.
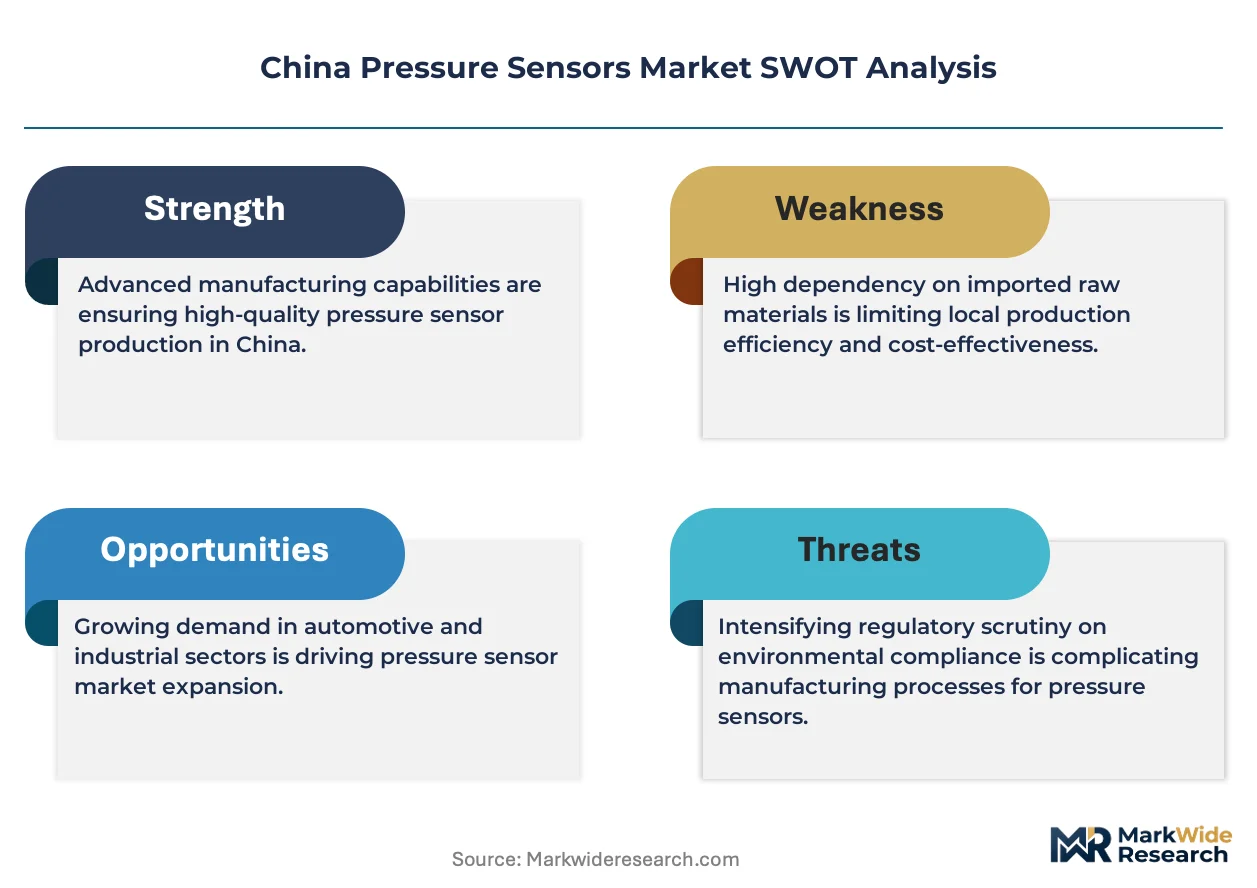
GB standards issued by SAMR establish metrological accuracy classes for industrial pressure instrumentation sold in China, while NMPA registration requirements dictate biocompatibility and sterilization validation for healthcare sensor deployments. MIIT automotive regulations mandate tire pressure monitoring systems and battery management sensor redundancy, directly expanding addressable unit demand. Stakeholders must monitor how China's dual carbon goals recalibrate energy sector sensor specifications toward hydrogen compatibility and carbon capture pressure envelopes.
Market Dynamics
Automotive OEM procurement consolidation is compressing supplier margins across China's pressure sensor landscape, as electric vehicle platforms demand tenfold sensor density increases for battery thermal management versus internal combustion architectures.
Growth Catalysts
- MIIT battery safety mandates:Thermal runaway detection requirements are multiplying sensor counts per NEV platform, creating sustained unit demand pull from automotive OEMs.
- Yangtze River Delta manufacturing cluster:Concentrated MEMS foundry capacity in Shanghai-Jiangsu-Zhejiang corridor is reducing procurement lead times for domestic system integrators.
- NMPA registration pathway streamlining:Accelerated healthcare-grade certification timelines are unlocking medical device sensor deployments previously blocked by regulatory backlog.
Market Restraints
- High-purity silicon wafer import dependency:Domestic 300mm SOI wafer supply remains insufficient for automotive-grade MEMS fabrication, exposing cost volatility.
- Single-source automotive module certification:Tier-1 safety system approvals lock suppliers into multi-year platform commitments with limited switching flexibility.
- Capacitive sensing cost premium:Corrosive-media-compatible architectures carry 3-4x unit economics disadvantage versus piezoresistive alternatives in industrial process control.
Strategic Opportunities
- Hydrogen infrastructure pressure envelopes:Dual carbon goals are recalibrating energy sector specifications toward 700-bar hydrogen storage compatibility.
- Guangdong-Hong Kong-Macao Greater Bay Area:Underpenetrated medical device manufacturing concentration offers healthcare sensor localization potential.
- Silicon carbide MEMS convergence:Wide-bandgap material integration with piezoresistive elements is opening high-temperature (>300°C) application white space.
Industry Challenges
- Automotive functional safety engineer scarcity:ISO 26262 competency gaps are extending development timelines for domestic suppliers targeting OEM qualification.
- Legacy 4-20mA integration complexity:Digital IO-Link retrofit requirements in process automation are forcing parallel analog-digital product line maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Pressure Sensors Market |
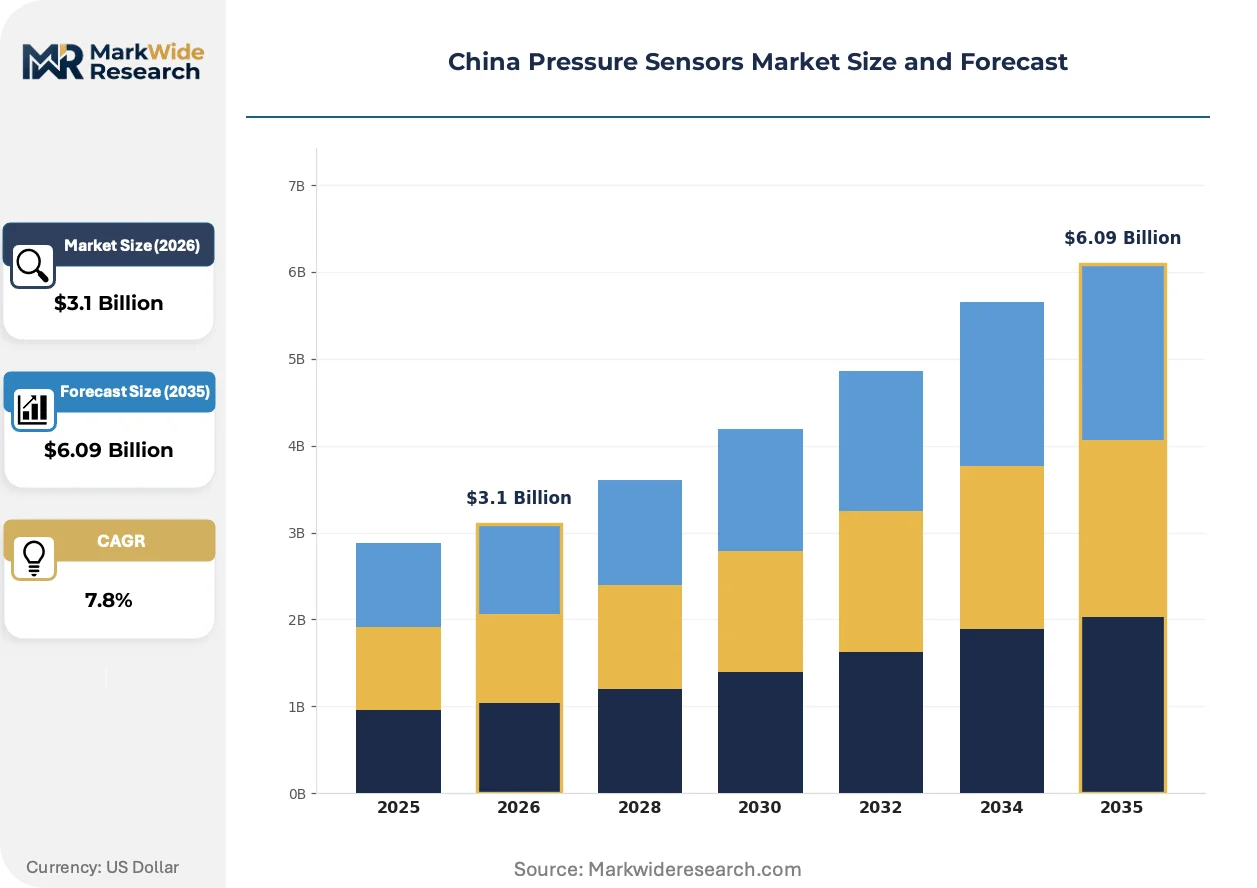
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absolute Sensors, Gauge Sensors, Differential Sensors, Sealed Sensors Technology: Piezoresistive, Capacitive, Optical, Resonant End User: Automotive, Aerospace, Industrial, Healthcare Application: Process Control, HVAC, Automotive Safety, Environmental Monitoring |
| Companies Covered | China Electronics Technology Corporation, Xi'an UTOP Measurement Instrument Co.,Ltd, Honeywell International Inc., TM Automation Instruments Co., Ltd., Ericco International Limited, Bosch, Shanghai Zhaohui Pressure Apparatus Co.,Ltd, Ninghai Sendo Sensor Co. Ltd, Infineon, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Pressure Sensors Market Strategic Shifts
Silicon micromachining scale economies are colliding with wide-bandgap material advances, reshaping performance-cost tradeoffs across automotive, industrial, and medical verticals.
Resonant silicon pressure sensing is fragmenting the high-accuracy segment previously dominated by bonded strain gauge architectures. Aerospace and metrology instrument manufacturers are adopting MEMS-based resonant elements for 0.01% full-scale precision requirements. This displacement is compressing addressable market scope for conventional metal-diaphragm technologies above 1000 bar.
GB standards issued by SAMR are tightening metrological accuracy classes for industrial pressure instrumentation sold in China. The regulatory tightening is forcing domestic manufacturers toward automated calibration investments. Process automation buyers in chemical and petrochemical verticals are responding by consolidating supplier relationships around certified-tier providers.
Direct OEM contracting is displacing traditional distribution channels for automotive-grade pressure sensors. Tier-1 module suppliers are absorbing sensor procurement functions previously executed through electronic component distributors. This channel compression is most visible in NEV battery management system deployments, where cell manufacturers negotiate sensor specifications directly with MEMS foundries.
China Pressure Sensors Market Segmentation
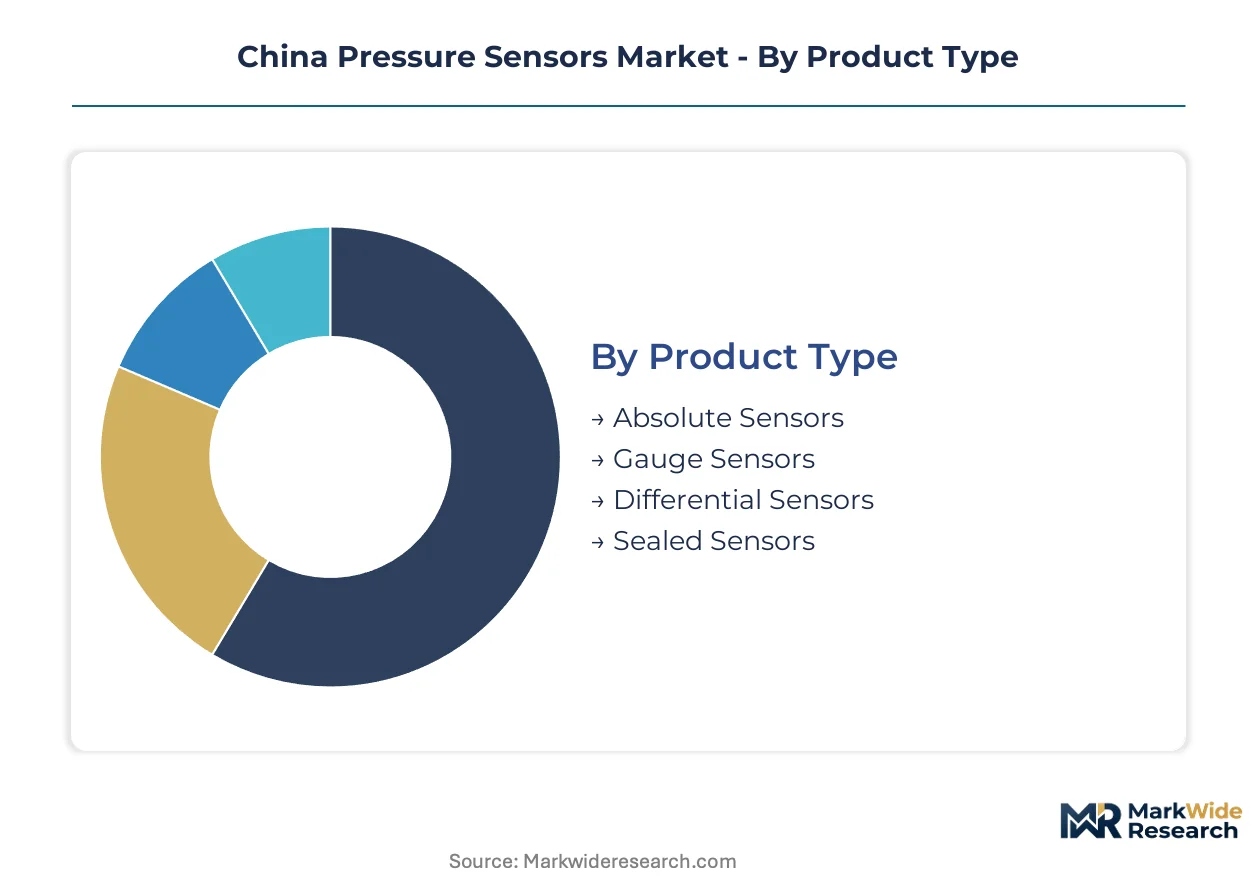
Pressure sensor procurement in China fragments across regulatory regimes that dictate performance thresholds. MIIT automotive mandates, SAMR industrial metrology classes, and NMPA biocompatibility requirements create distinct certification pathways that reshape supplier specialization.
Product Type:
SAMR GB standards establish separate accuracy classes for vented-reference versus sealed-reference architectures, conditioning procurement patterns across industrial verticals.
- Gauge Sensors:Vented-reference designs compensate against atmospheric pressure through external ports, dominating chemical processing and water treatment installations across Jiangsu province. Yangtze River Delta system integrators specify these for 0.25% accuracy class compliance under GB/T 17614.
- Absolute Sensors:Sealed vacuum-reference elements measure against fixed zero points, essential for altitude compensation in commercial aerospace and barometric applications. NEV battery management systems in Shenzhen deploy these for thermal runaway pressure detection where atmospheric variation would corrupt readings.
- Differential Sensors:Dual-port architectures measure pressure drops across filters, valves, and flow elements in HVAC and cleanroom infrastructure.
- Sealed Sensors:Welded-diaphragm constructions isolate sensing elements from corrosive media in offshore oil platforms and hydrogen storage vessels.
Established volume favors gauge architectures in legacy industrial automation; emerging adoption favors absolute sensors in NEV thermal management.
Technology:
Unit economics diverge sharply between silicon micromachining scale and specialized material platforms.
- Piezoresistive:Silicon strain gauges fabricated through bulk or surface micromachining deliver the lowest cost-per-sensor at automotive volumes. MIIT tire pressure monitoring mandates have driven 200mm and 300mm MEMS foundry investments in Shanghai and Wuxi, consolidating domestic supply.
- Capacitive:Electrode-gap sensing eliminates piezoresistor drift in corrosive or ionic media, penetrating chemical processing and semiconductor fab applications. Unit premiums of 3-4x over piezoresistive alternatives constrain adoption outside safety-critical environments.
- Optical:Fiber Bragg grating and interferometric architectures isolate electronics from high-voltage or explosive atmospheres in power transmission and mining.
- Resonant:Silicon resonator frequency-shift detection achieves 0.01% full-scale precision for metrology and aerospace instrumentation.
Cost-optimized piezoresistive platforms dominate automotive qualification pipelines; capacitive architectures gain share fastest in corrosive-media process control.
End User:
Customer procurement concentration determines margin structures and certification investment requirements.
- Automotive:NEV OEMs now specify sensor counts exceeding tenfold internal combustion equivalents for battery thermal management, tire pressure monitoring, and fuel cell hydrogen pressure envelopes. Direct MEMS foundry contracting is displacing traditional distributor channels.
- Industrial:Process automation buyers in petrochemical and power generation verticals consolidate around SAMR-certified tier providers as GB standards tighten accuracy class requirements.
- Healthcare:NMPA registration pathway streamlining is accelerating ventilator, anesthesia, and dialysis pressure sensor deployments previously stalled in regulatory backlog.
- Aerospace:Dual-use technology transfer constraints limit foreign supplier participation, creating captive demand for domestic certification to CAAC airworthiness directives.
Automotive procurement concentration compresses supplier margins; healthcare certification acceleration unlocks fastest expansion trajectory among regulated verticals.
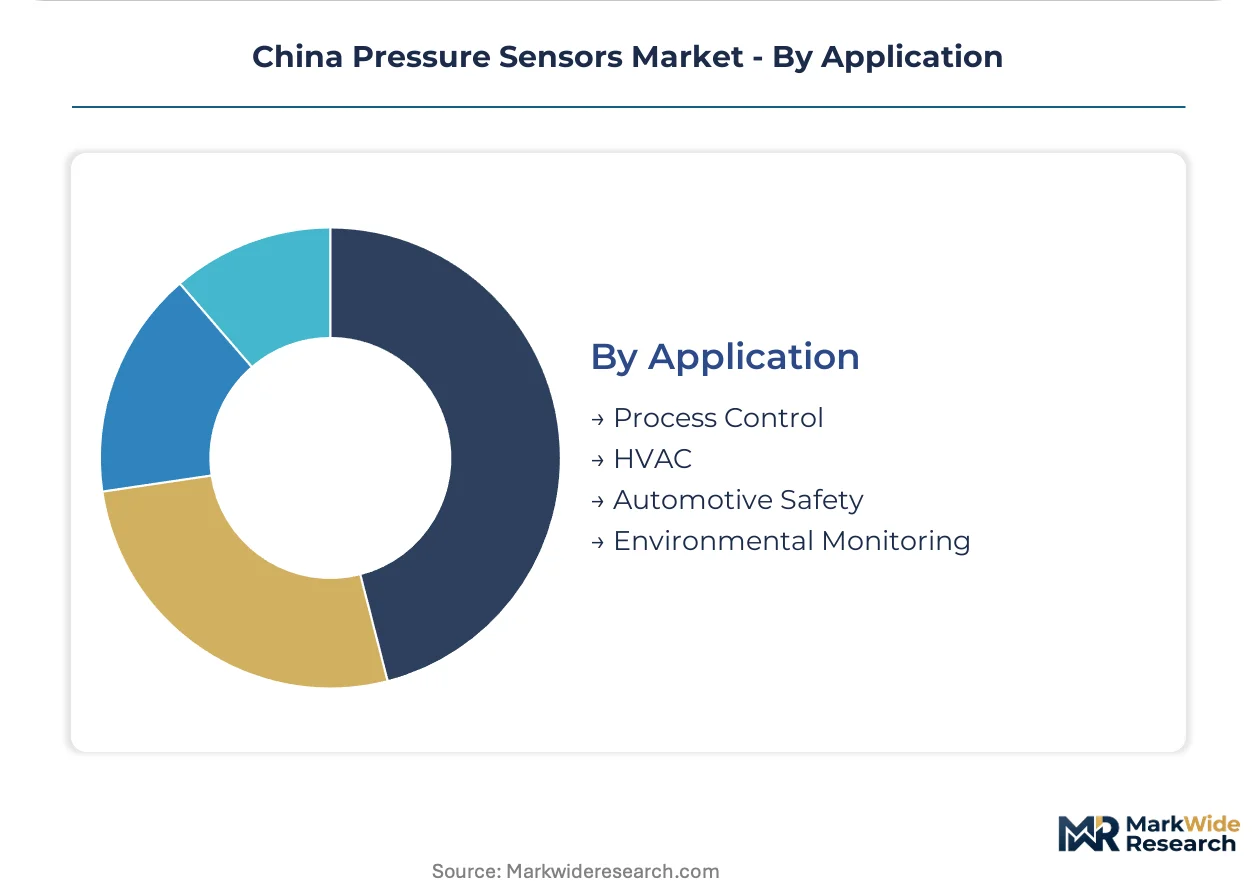
Application:
Deployment environments dictate packaging, media isolation, and communications protocol requirements.
- Process Control:4-20mA analog dominance persists in legacy chemical and petrochemical installations, though IO-Link digital retrofit requirements are forcing parallel product line maintenance.
- Automotive Safety:ISO 26262 functional safety compliance extends development timelines for domestic suppliers targeting OEM qualification, creating capability scarcity premiums.
- HVAC:Refrigerant pressure monitoring and building automation differential sensing concentrate demand in commercial construction corridors across Beijing-Tianjin-Hebei.
- Environmental Monitoring:Atmospheric and water quality sensing networks deploy low-cost gauge and differential architectures in provincial monitoring stations.
Legacy process control maintains largest installed base; automotive safety applications command steepest certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Automotive OEM procurement concentrates in coastal manufacturing corridors, with NEV battery thermal management systems driving sensor density requirements that exceed internal combustion platforms by an order of magnitude.
Yangtze River Delta
NEV battery pack manufacturers in Shanghai, Jiangsu, and Zhejiang provinces specify absolute pressure sensors for thermal runaway detection at cell and module levels. MIIT battery safety mandates require redundant pressure monitoring across high-voltage architectures. MEMS foundry investments in Wuxi and Suzhou are compressing procurement lead times for domestic system integrators.
Pearl River Delta
Shenzhen-based EV manufacturers deploy sealed-reference sensors for fuel cell hydrogen pressure envelopes reaching 700-bar storage specifications. SAMR metrology standards for high-pressure instrumentation are tightening calibration certification requirements. Guangzhou automotive clusters are absorbing sensor procurement functions previously executed through Hong Kong distribution channels.
Beijing-Tianjin-Hebei
Aerospace and defense contractors in the capital corridor source resonant silicon sensors for altitude compensation and cabin pressure systems. CAAC airworthiness directives limit foreign supplier participation, creating captive demand for domestic certification pathways. Tianjin port infrastructure supports bonded warehousing for imported high-purity silicon wafers.
Sichuan-Chongqing
Natural gas pipeline operators in the Southwest deploy high-temperature sealed sensors for wellhead pressure monitoring in shale formations. Dual carbon goals are recalibrating specifications toward hydrogen-compatible materials and carbon capture pressure envelopes. Chengdu instrumentation clusters are consolidating around SAMR-certified calibration laboratories.
Shandong Peninsula
Petrochemical refineries in Qingdao and Yantai specify gauge sensors with 0.25% accuracy class compliance under GB/T 17614 for process control applications. MEE environmental monitoring networks deploy differential architectures for atmospheric and water quality sensing stations. Jinzhou industrial zones are retrofitting legacy 4-20mA installations with IO-Link digital protocols.
China Pressure Sensors Market Competitive Environment
Player mix skews toward integrated MEMS fabricators with captive foundry capacity and specialized instrumentation houses serving energy infrastructure. Market structure exhibits tiered consolidation, with automotive safety module qualification creating multi-year platform lock-ins for approved suppliers. Three archetypes dominate: multinational electronics conglomerates with dual-use technology transfer capabilities, domestic high-temperature specialists for oil-and-gas specifications, and Yangtze River Delta MEMS foundries with automotive volume scale. Competitive moves center on backward integration into silicon wafer supply and strategic partnerships with NEV cell manufacturers for direct specification influence.
Within the multinational tier, Honeywell International Inc. and Bosch occupy positions anchored by aerospace-grade certification dominance and integrated fabrication capabilities respectively. Xi'an UTOP Measurement Instrument Co.,Ltd exemplifies the domestic high-temperature specialist archetype, while China Electronics Technology Corporation represents state-linked electronics conglomerates with defense-aerospace crossover positioning. These three entities collectively illustrate the competitive tension between foreign technology transfer dependence and indigenous capability building across MIIT-regulated automotive and SAMR-regulated industrial verticals.
| Leading Market Players |
|---|
| China Electronics Technology Corporation |
| Xi'an UTOP Measurement Instrument Co.,Ltd |
| Honeywell International Inc. |
| TM Automation Instruments Co., Ltd. |
| Ericco International Limited |
| Bosch |
| Shanghai Zhaohui Pressure Apparatus Co.,Ltd |
| Ninghai Sendo Sensor Co. Ltd |
| Infineon |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety day procurement lead times for automotive-grade MEMS pressure sensors concentrate pricing power within Yangtze River Delta foundries, compressing margins for downstream system integrators while amplifying cost pass-through leverage for wafer-scale manufacturers serving MIIT-regulated NEV platforms.
Pricing Analysis
Current-generation piezoresistive silicon sensors command 40-50% price premiums over prior-generation metal-diaphragm alternatives, while next-generation silicon carbide MEMS architectures remain pre-commercial with undefined pricing. Three-tier pricing structure across automotive safety-certified, industrial process-grade, and economy uncalibrated levels segments buyer access. Price differentiation hinges on ISO 26262 functional safety certification tier and SAMR GB/T metrology class compliance. Cost compression in industrial gauge sensors intensifies as Yangtze River Delta foundries absorb volume from legacy instrumentation houses. Process automation procurement teams exhibit highest price sensitivity; aerospace and NEV battery management buyers demonstrate lowest sensitivity due to qualification lock-in effects.
Supply Chain Analysis
Japan and Germany anchor high-purity 300mm SOI wafer production for automotive MEMS fabrication, while domestic China capacity concentrates in 200mm legacy nodes. Raw material dependencies encompass monocrystalline silicon ingots, borosilicate glass for anodic bonding, and specialized epoxy formulations for media isolation. Single-source vulnerability runs through photolithography equipment import restrictions affecting advanced node scaling. Distribution runs through direct OEM contracting displacing traditional electronic component distributors, particularly in NEV battery thermal management procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from silicon carbide MEMS architectures that threaten to displace piezoresistive dominance in high-temperature applications above 300°C.
For Market Incumbents: Compound backward integration into 300mm SOI wafer supply to reduce import dependency exposure, while accelerating ISO 26262 competency development to defend against domestic challengers targeting automotive safety module qualification. Lock in multi-year platform commitments with NEV cell manufacturers before silicon carbide MEMS reaches commercial scale. For New Entrants and Emerging Players: Lead with hydrogen infrastructure pressure envelope specifications targeting 700-bar storage compatibility in Sichuan-Chongqing shale formations, where dual carbon goals recalibrate energy sector demand. Guangdong-Hong Kong-Macao Greater Bay Area medical device manufacturing offers underpenetrated healthcare sensor localization potential with streamlined NMPA registration pathways. Pursue direct contracting with fuel cell system integrators bypassing established automotive Tier-1 gatekeepers. For Investors and Strategic Acquirers: Long-term, this sits as a certification-capture play because regulatory moats around MIIT automotive mandates and SAMR metrology classes compound faster than pure technology differentiation. Target domestic high-temperature specialists with existing oil-and-gas infrastructure relationships and CAAC aerospace certification pathways. Monitor silicon carbide MEMS pilot production announcements as inflection indicator for technology substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wafer Supply | Captive 300mm SOI production reduces Japan/Germany import dependency for automotive MEMS scaling. |
| ISO 26262 Competency Buildout | Functional safety engineering scarcity creates qualification bottlenecks that extend OEM platform lock-in durations. |
| Hydrogen Pressure Envelope Development | 700-bar compatibility specifications align with MIIT dual carbon infrastructure deployment timelines. |
| NMPA Registration Pathway Investment | Streamlined healthcare-grade certification unlocks ventilator and anesthesia sensor procurement previously stalled in backlog. |
| Direct OEM Contracting Infrastructure | Bypassing electronic component distributors captures margin compression from channel consolidation in NEV battery management. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with MEMS foundry operations directors, automotive Tier-1 procurement managers, NMPA regulatory affairs specialists, and SAMR calibration laboratory supervisors; alongside secondary validation through MIIT automotive safety mandate filings, SAMR GB standards documentation, NMPA medical device registration databases, and Yangtze River Delta industrial cluster trade data. Bottom-up sensor unit demand modeling triangulated against top-down market value reconstructions.
Across the analysis window, projections integrate technology adoption curves for silicon carbide MEMS convergence, regulatory enforcement intensity for GB/T metrology class compliance, and automotive platform sensor count specifications by propulsion architecture. Segmentation dimensions encompass product type, sensing technology, end-user vertical, and application environment. CAGRs derive from unit volume trajectories weighted by average selling price compression curves and certification tier mix shifts.
The analysis sits within stated boundaries; outcomes outside sustained MIIT battery safety mandate enforcement, stable high-purity silicon wafer import flows, or NMPA registration pathway streamlining would require recalibration. Forecasts reflect assumptions regarding automotive OEM procurement consolidation velocity and resonant silicon displacement rates for high-accuracy metrology applications. Recalibration cycles align with material shifts in dual carbon policy implementation and wide-bandgap semiconductor manufacturing readiness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Smart Thermometer Market
Sensors and Controls
Global Radar Sensor Market
Sensors and Controls
Dew Point Thermometer Market
Sensors and Controls
Industrial Wireless Sensor Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Underwater Ultrasonic Sensor Market
Sensors and Controls
Smart Visor Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Fingerprint Module Market
Sensors and Controls
High-Voltage Isolation and Leakage Sensor Components Market
Sensors and Controls
Italy Digital Thermometer Market
Sensors and Controls
Sensor Data Analytics Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
Gimbal Market