
 Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market | 2026-2036
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market Insights
Direct procurement channels between transformer manufacturers and Saudi utilities is reconfiguring as Aramco, SEC, and NEOM developers consolidate vendor lists around localized production. ABB leverages its Jeddah manufacturing footprint to anchor large-scale utility contracts. Siemens Energy competes through technology leadership in extra-high-voltage VPI designs. Saudi Transformers Company sustains cost advantages via in-house resin impregnation and domestic coil winding capabilities.
Vacuum Pressure Impregnated (VPI) transformers are dry-type units where windings undergo vacuum evacuation followed by resin penetration under pressure, yielding insulation systems rated up to 72.5 kV with Class F or H thermal performance. They serve critical applications requiring fire safety, minimal maintenance, and resistance to humidity or chemical exposure. Three-phase configurations dominate volume given industrial and utility scale requirements, while renewable energy end users represent the fastest-expanding demand pool as solar and wind integration strains conventional oil-filled alternatives. Medium-voltage power ratings capture the deepest margin pools due to customization intensity and shorter replacement cycles.
SASO efficiency mandates and SFDA electrical equipment safety protocols shape product certification pathways and import clearance timelines for non-local manufacturers. The Saudi Green Initiative drives specifications toward lower-loss core materials and recyclable resin systems. Stakeholders must monitor how NEOM and Red Sea Project procurement rules evolve around local content thresholds and long-term service bundling.
Market Dynamics
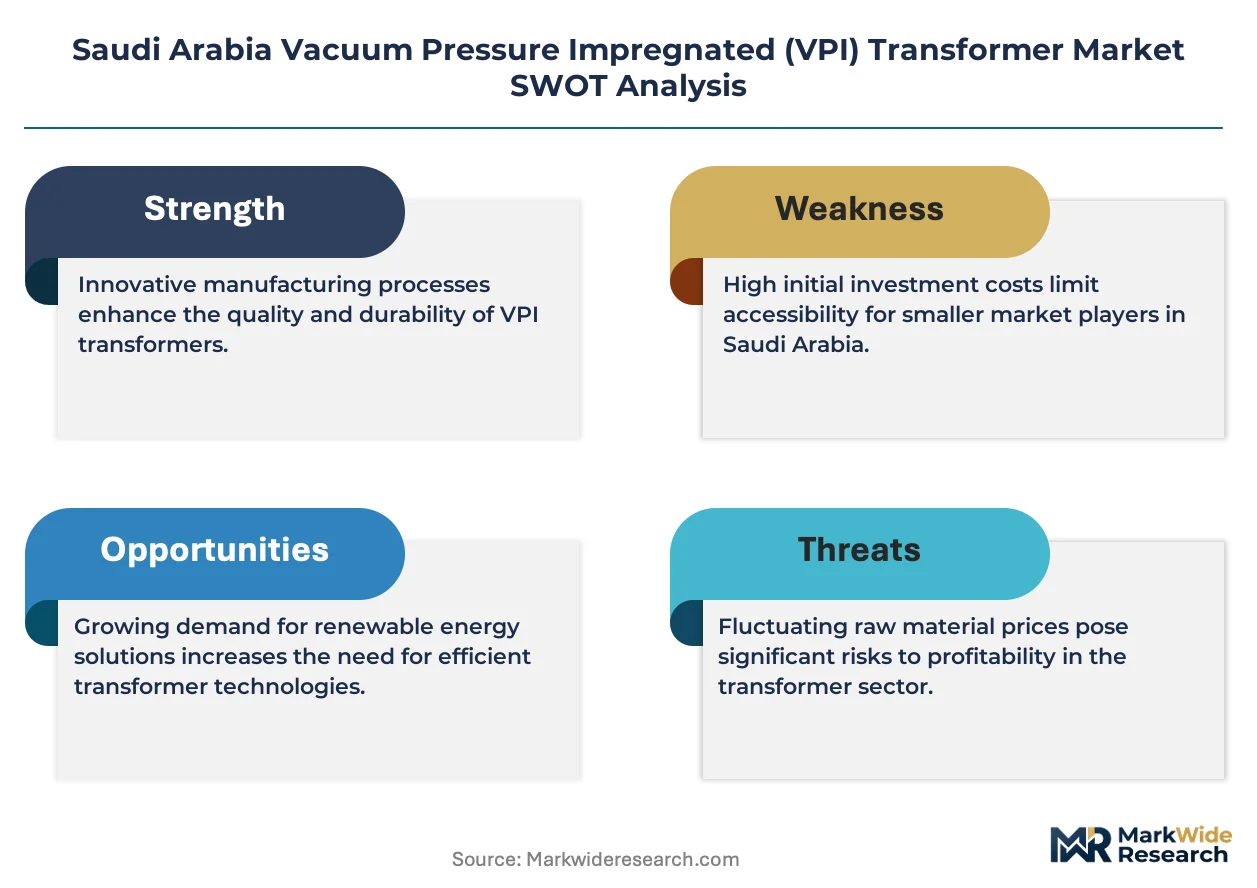
Saudi Arabia's VPI transformer market is restructuring around localization mandates and mega-project electrification timelines, with procurement consolidation by Aramco, SEC, and NEOM developers compressing vendor qualification windows and favoring domestic manufacturing footprints.
Growth Catalysts
- Saudi Green Initiative efficiency mandates:The initiative's targets for lower-loss electrical infrastructure are accelerating specifications for advanced core materials and recyclable resin systems in utility procurement.
- NEOM and Red Sea Project electrification:These giga-projects require fire-safe, minimal-maintenance transformers for critical infrastructure, creating sustained demand for medium-voltage VPI units in coastal and desert environments.
- Renewable energy integration strain:Solar and wind capacity additions are displacing conventional oil-filled alternatives in substations, with VPI technology capturing preference for its humidity resistance and reduced fire risk.
Market Restraints
- Epoxy resin price volatility:Petrochemical feedstock fluctuations directly impact insulation system costs, compressing margins for manufacturers without backward integration into resin production.
- Specialized copper winding supply concentration:Domestic coil winding capability remains limited to a handful of Saudi facilities, creating bottleneck risk for rapid project scaling.
- SASO certification timeline friction:Efficiency testing protocols and documentation requirements extend import clearance for non-local manufacturers, disadvantaging foreign suppliers against Jeddah-based producers.
Strategic Opportunities
- Eastern Province industrial corridor expansion:Petrochemical and mining electrification in Jubail and Ras Al-Khair is generating demand for customized VPI transformers with chemical-resistant specifications.
- SFDA safety protocol alignment:Early compliance with evolving electrical equipment safety standards positions vendors for preferred supplier status in healthcare and data center applications.
- Digital monitoring convergence:Integration of IoT sensors with VPI insulation systems is creating predictive maintenance service bundles, extending contract value beyond hardware sales.
Industry Challenges
- Vacuum impregnation technician scarcity:Specialized resin penetration process expertise is concentrated among a limited workforce, constraining production scaling for new market entrants.
- Legacy oil-filled transformer installed base:Existing utility infrastructure and maintenance contracts create switching friction, requiring extended payback demonstrations to displace conventional units.
- Multi-standard compliance complexity:Simultaneous SASO, SFDA, and project-specific NEOM technical requirements demand redundant testing programs, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market |
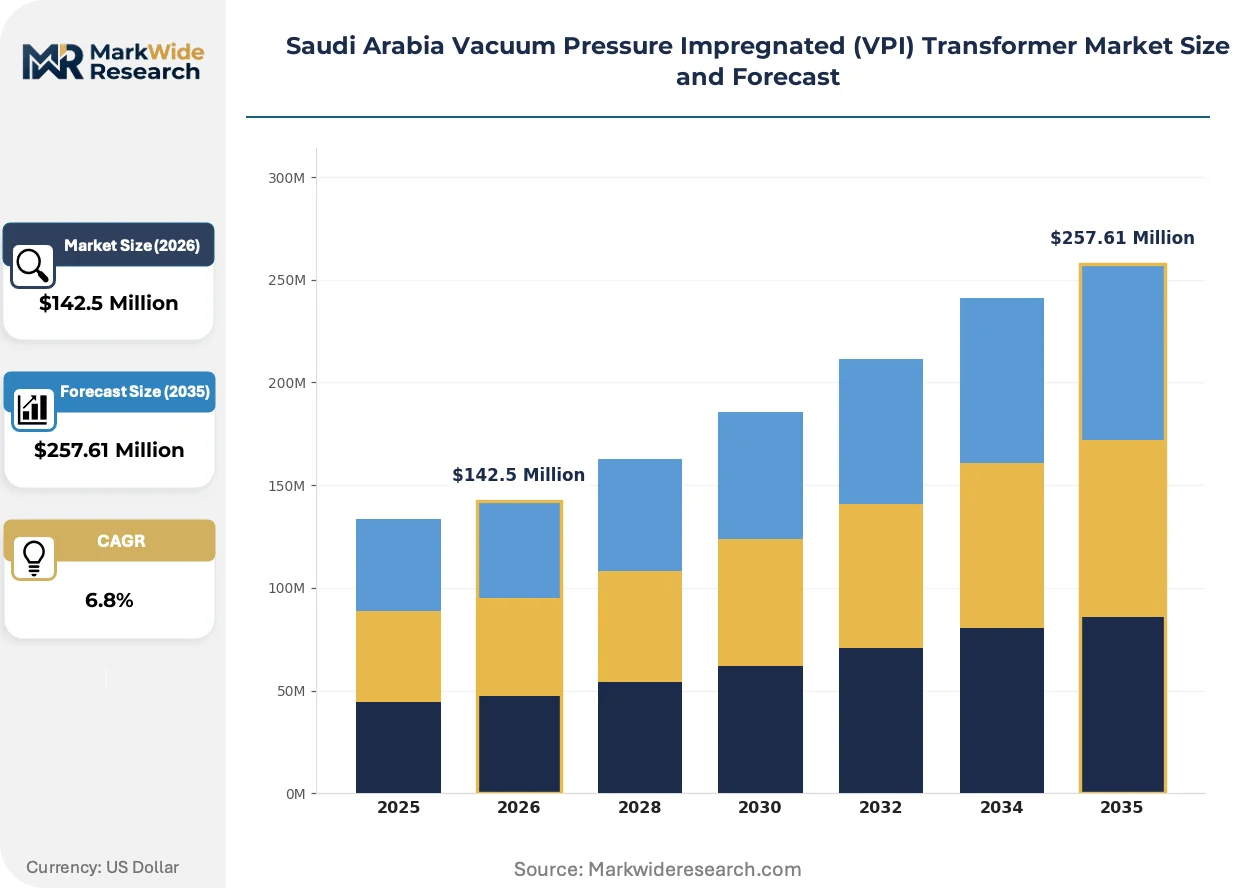
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $257.61 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Phase, Three-Phase, Cast Resin, Oil-Filled Installation Type: Indoor, Outdoor, Hybrid, Remote End User: Utilities, Industrial Sector, Commercial Buildings, Renewable Energy Power Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | ABB, Siemens Energy, Schneider Electric, GE Vernova, Eaton, Hitachi Energy, CG Power, Saudi Transformers Company, Alfanar Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market Trends and Innovations
Resin chemistry advances and digitalization are redefining VPI transformer performance benchmarks, while procurement centralization by Saudi utilities is compressing supplier margins and favoring integrated service providers.
Amorphous metal core technology is hybridizing with conventional silicon steel designs in Saudi utility specifications. Distribution network operators are piloting hybrid core configurations to meet Saudi Green Initiative loss-reduction targets without full material substitution. This hybridization is enabling tiered product portfolios that bridge cost-sensitive industrial buyers and efficiency-focused transmission utilities.
SFDA electrical equipment safety protocols are tightening insulation system documentation requirements. Manufacturers must now submit accelerated aging test data and thermal class verification for import clearance, extending certification timelines. Medium-voltage power ratings face the steepest compliance burden, as these units serve critical infrastructure where failure consequences trigger regulatory scrutiny.
Long-term service bundling is displacing transactional equipment sales in utility procurement. Aramco and SEC are unbundling maintenance from capital budgets, creating multi-year performance contracts that transfer operational risk to manufacturers. This shift is most visible in Riyadh, where consolidated vendor lists favor suppliers with localized technical service teams and spare parts inventory.
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market Segmentation
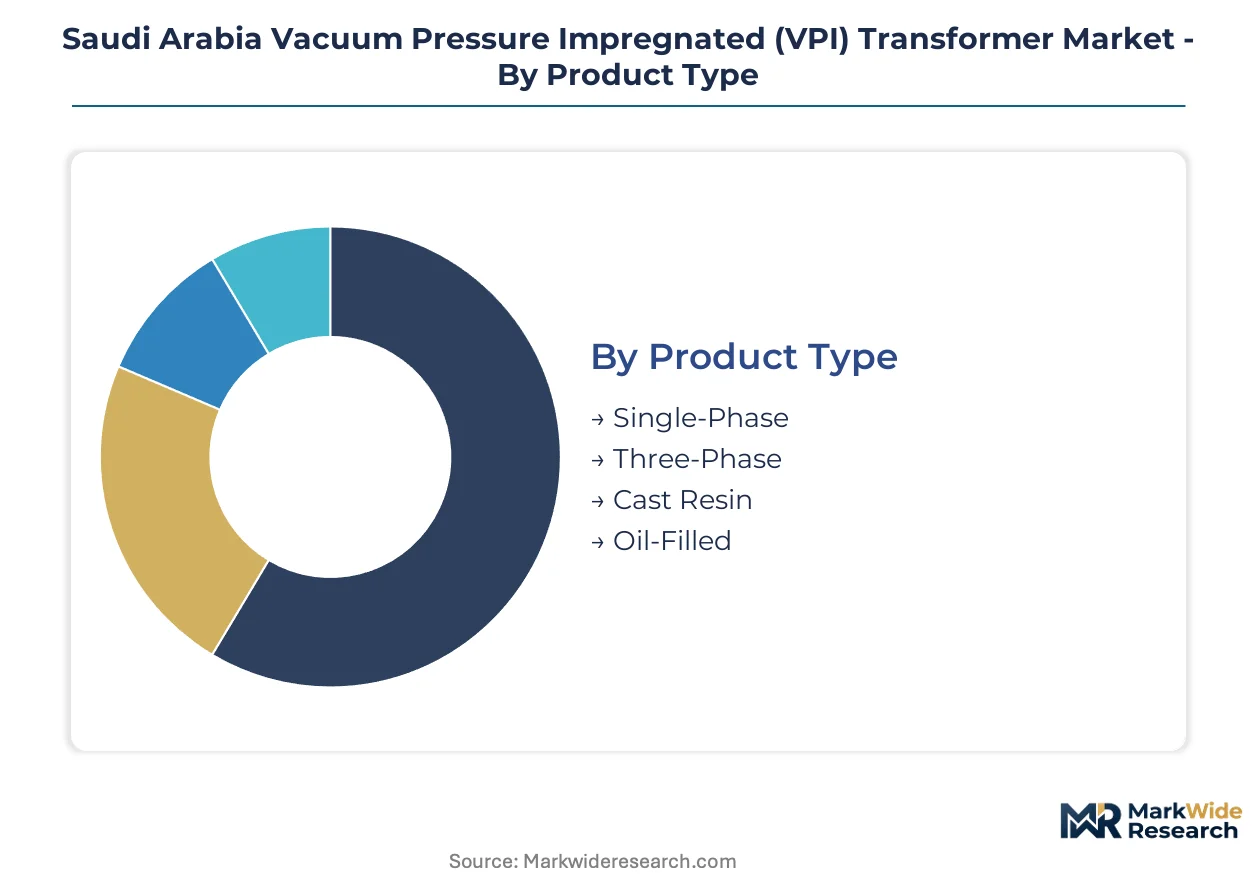
VPI transformer procurement in Saudi Arabia fragments across technical specifications, deployment environments, and end-use requirements. Each dimension carries distinct certification pathways and margin structures that shape vendor positioning.
Product Type:
Product configurations span the full use-case spectrum from compact commercial units to industrial-scale power distribution systems.
- Three-Phase:Industrial-scale windings configured for 11 kV through 36 kV distribution networks dominate utility and petrochemical procurement. Demand concentrates in Jubail and Ras Al-Khair industrial corridors where chemical-resistant insulation specifications are mandatory.
- Single-Phase:Compact units rated below 15 kVA serve commercial building secondary distribution and remote infrastructure. Riyadh's data center cluster is driving procurement of modular single-phase configurations for redundant power architectures.
- Cast Resin:Fully encapsulated designs with vacuum-cast epoxy housings eliminate fire risk for indoor installations in healthcare and high-occupancy facilities.
- Oil-Filled:Hybrid designs combining VPI windings with oil cooling for high-thermal-load applications in mining electrification.
The dominant share belongs to Three-Phase configurations, while Cast Resin is closing the gap fastest on SFDA safety protocol alignment.
Installation Type:
Deployment environments determine enclosure specifications, thermal management requirements, and maintenance access protocols.
- Outdoor:Weather-resistant housings with IP54+ ratings and desert-grade sealing serve NEOM and Red Sea Project coastal infrastructure. Salt-fog corrosion resistance and sand-ingress protection are non-negotiable specifications.
- Indoor:Compact footprints with reduced clearances fit substation retrofits and urban commercial buildings. Riyadh's underground distribution network favors indoor VPI units for fire-code compliance.
- Hybrid:Modular enclosures supporting both indoor and outdoor mounting address project-phase flexibility in giga-project construction timelines.
- Remote:Satellite-monitored units with extended maintenance intervals serve off-grid renewable installations and mining camps.
Outdoor deployments command the largest project volumes, though Remote installations are expanding most quickly on renewable integration timelines.
End User:
Customer archetypes diverge sharply on procurement centralization, technical specification depth, and service bundling expectations.
- Utilities:SEC and Aramco procurement teams consolidate vendor lists around localized manufacturing and multi-year performance contracts. Technical specifications emphasize loss reduction and 40-year asset life.
- Industrial Sector:Petrochemical and mining operators prioritize chemical resistance and minimal maintenance windows. Jubail industrial city operators specify Class H insulation for high-ambient-temperature environments.
- Commercial Buildings:Developers and facility managers focus on footprint reduction and fire safety certification for high-rise and healthcare applications.
- Renewable Energy:Solar and wind developers specify humidity-resistant VPI units for inverter duty and collector substations. NEOM's renewable integration targets are accelerating procurement of dry-type alternatives to oil-filled transformers.
Utilities anchor the revenue base, while Renewable Energy is gaining share fastest on capacity addition targets under the Saudi Green Initiative.
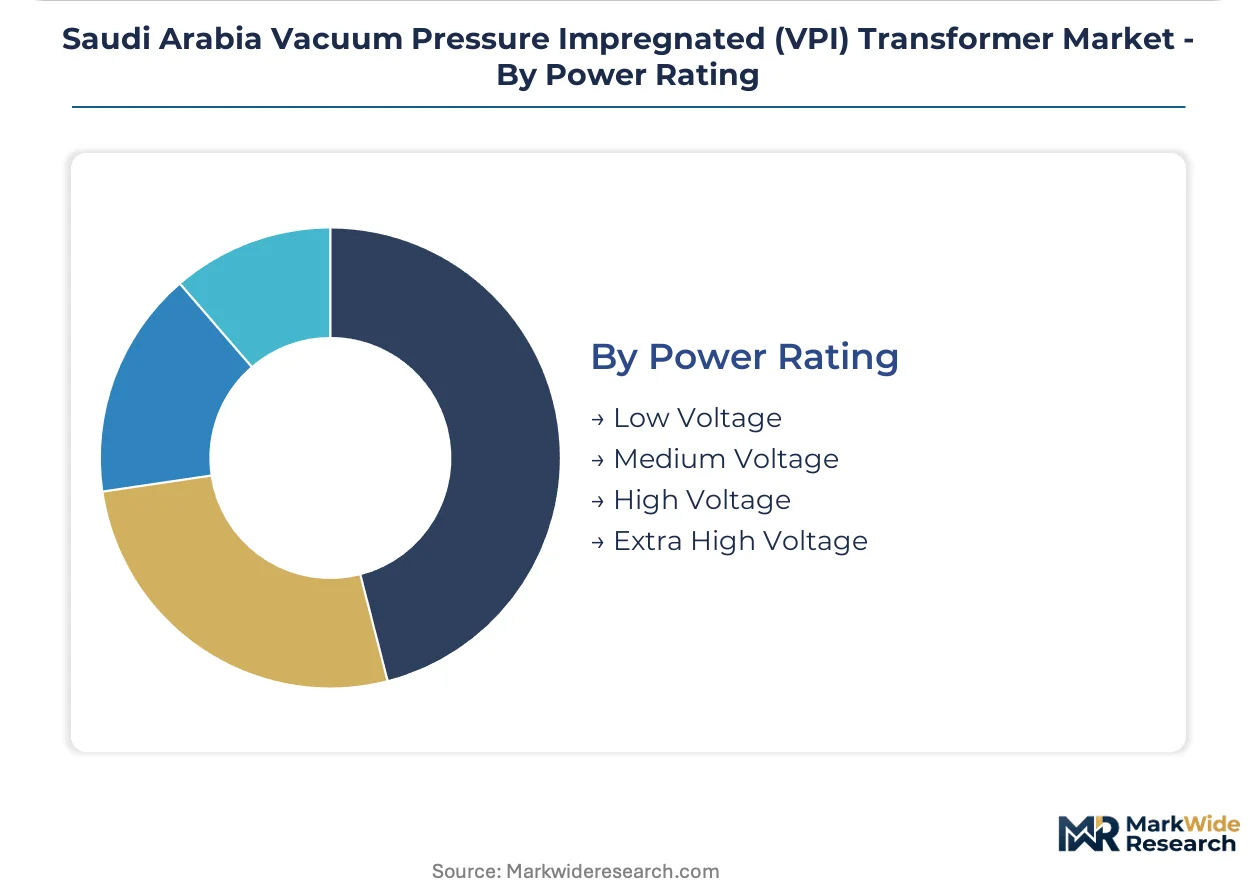
Power Rating:
Voltage tiers map directly to application criticality, customization intensity, and replacement cycle frequency.
- Medium Voltage:1 kV to 72.5 kV ratings serve primary distribution and industrial substations with the deepest customization requirements. SASO efficiency testing protocols impose the steepest compliance burden at this tier.
- Low Voltage:Sub-1 kV units for commercial building distribution and secondary industrial circuits offer faster procurement cycles but compressed margins.
- High Voltage:72.5 kV to 170 kV designs for transmission substations require specialized core materials and extended factory acceptance testing.
- Extra High Voltage:Above 170 kV applications remain limited in Saudi Arabia, with most procurement imported for specific grid backbone projects.
Medium Voltage captures the deepest margin pools, while Low Voltage is climbing the fastest on building electrification volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in the Eastern Province industrial corridor exceeds Riyadh's utility procurement rates by margins reflecting logistics premiums and chemical-resistant specification premiums. This asymmetry shapes vendor investment patterns across Saudi Arabia's transformer market.
Eastern Province
Jubail and Ras Al-Khair petrochemical complexes drive demand for Class H insulation systems rated for high-ambient-temperature environments. SASO efficiency mandates apply differentially to coastal installations requiring salt-fog corrosion resistance. Aramco's vendor consolidation around localized technical service teams concentrates procurement authority in Dammam-based supply chain nodes.
Riyadh
SEC grid modernization and data center cluster electrification sustain medium-voltage procurement volumes. The Saudi Green Initiative's loss-reduction targets accelerate specifications for amorphous metal hybrid cores in distribution substations. Underground distribution network retrofits favor compact indoor VPI configurations for fire-code compliance in high-density commercial zones.
Western Region
Jeddah's manufacturing footprint anchors ABB's localized production capacity for large-scale utility contracts. Red Sea Project coastal infrastructure requires IP54+ weather-resistant housings with desert-grade sealing specifications. SFDA electrical equipment safety protocols impose accelerated aging test documentation for healthcare facility installations in Mecca and Medina medical cities.
NEOM Northwest
The giga-project's renewable integration targets displace oil-filled alternatives with humidity-resistant dry-type units for solar and wind collector substations. NEOM procurement rules evolve around local content thresholds and long-term service bundling requirements. Remote monitoring specifications with extended maintenance intervals address off-grid renewable installation logistics.
Saudi Arabia Vacuum Pressure Impregnated (VPI) Transformer Market Competitive Landscape
Integrated multinationals and domestic specialists split the market between technology leadership and cost-advantaged localization. Procurement consolidation by Aramco, SEC, and NEOM developers compresses vendor qualification windows to favor domestic manufacturing footprints. Three archetypes dominate: Jeddah-based integrated manufacturers with resin impregnation capabilities, European technology leaders in extra-high-voltage designs, and regional fabricators with in-house coil winding. Competitive moves center on backward integration into resin production and multi-year performance contracting that transfers operational risk to manufacturers.
Among the integrated multinational tier, ABB leverages its Jeddah manufacturing footprint to anchor large-scale utility contracts. Siemens Energy occupies a position exemplifying technology leadership in extra-high-voltage VPI designs. Saudi Transformers Company represents the domestic specialist archetype with cost advantages via in-house resin impregnation capabilities. These three entities illustrate the strategic positioning required under SASO certification timelines and SFDA safety protocol alignment pressures.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| Schneider Electric |
| GE Vernova |
| Eaton |
| Hitachi Energy |
| CG Power |
| Saudi Transformers Company |
| Alfanar Company |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in domestic coil winding facilities across the Eastern Province is compressing lead times and amplifying pricing power for Jeddah-based manufacturers with captive resin impregnation capabilities. This utilization squeeze forces procurement teams at SEC and Aramco to accept longer contract windows and premium pricing for Class H insulation systems, while simultaneously pressuring foreign suppliers to absorb SASO certification delays to remain competitive.
Pricing Analysis
The customization-premium spread between configured-to-order medium-voltage units and standard low-voltage configurations spans project-based transactional pricing with volume-scaled discounts for utility offtake agreements. Price differentiation hinges on SASO efficiency certification tier and after-sales service bundling, with chemical-resistant specifications for Jubail petrochemical corridors commanding substantial premiums. Cost compression in standard low-voltage tiers is intensifying because of epoxy resin feedstock volatility and concentrated copper winding supply. Industrial sector buyers exhibit the highest price sensitivity due to capital budget cycles, while NEOM developers prioritize performance specifications over unit economics.
Supply Chain Analysis
Supplier-financing facilities extended by ABB and Saudi Transformers Company are locking in procurement relationships with SEC and Aramco through 90-120 day payment terms unavailable to non-local competitors. Geographic supply concentration draws from Germany for amorphous metal cores, China for silicon steel laminations, and South Korea for epoxy resin formulations. Raw material dependencies rest on petrochemical-derived insulation resins, electrolytic copper for windings, and grain-oriented electrical steel. Single-source vulnerability in specialized vacuum impregnation equipment creates bottleneck risk for capacity expansion. Distribution runs through Dammam-based logistics hubs serving the Eastern Province industrial corridor and direct-to-site delivery for NEOM giga-projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's VPI transformer market is experiencing high-growth disruption as the Saudi Green Initiative's loss-reduction mandates displace conventional oil-filled infrastructure and reconfigure procurement specifications across utility and industrial buyer segments.
For Market Incumbents: Insulate core margin pools by securing backward integration into resin formulation and expanding Jeddah manufacturing capacity to capture NEOM local content thresholds. The threat of European technology leaders capturing extra-high-voltage design premiums demands accelerated R&D investment in amorphous metal hybrid cores. Channel control through multi-year performance contracts with SEC transfers operational risk while locking out emerging competitors. For New Entrants and Emerging Players: Build out specialized service capabilities in predictive maintenance and IoT-enabled condition monitoring to penetrate the white-space of remote renewable installations in NEOM's off-grid solar and wind clusters. The most penetrable segment lies in single-phase compact units for Riyadh data center redundant power architectures, where SFDA safety protocol alignment creates qualification barriers for established foreign suppliers. A go-to-market angle centered on digital monitoring convergence with VPI insulation systems enables service-led entry without immediate manufacturing scale requirements. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among domestic manufacturers with in-house resin impregnation and localized technical service teams capable of multi-year performance contracting. Long-term viability over the projection horizon favors acquisition targets with established SASO certification pathways and existing relationships with Aramco or SEC procurement consolidation programs. The signal to watch is NEOM procurement rule evolution around local content thresholds, which would accelerate valuation premiums for Jeddah-based production assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive epoxy formulation insulates margins from petrochemical feedstock volatility affecting insulation system costs. |
| Multi-Year Performance Contracting | Aramco and SEC unbundling of maintenance from capital budgets transfers operational risk to manufacturers with localized service teams. |
| Amorphous Metal Hybrid Core Development | Saudi Green Initiative loss-reduction targets accelerate utility specifications for advanced core material configurations. |
| SFDA Safety Protocol Alignment | Accelerated aging test documentation positions vendors for preferred supplier status in healthcare and data center applications. |
| IoT-Enabled Predictive Maintenance Integration | Digital monitoring convergence with VPI insulation systems extends contract value beyond hardware sales into recurring service revenue. |
Research Methodology
A spread of perspectives from utility procurement officers at SEC, Aramco electrical infrastructure planners, NEOM project developers, resin chemistry specialists, and transformer manufacturing executives converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through SASO efficiency standard documentation, SFDA electrical equipment safety protocols, Saudi Green Initiative policy releases, and customs trade data for transformer component imports. Bottom-up triangulation across installation type and power rating segments was cross-checked against top-down utility capital expenditure disclosures and giga-project electrification timelines.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, installation environment, end-user archetype, and power rating tier. CAGRs were derived from installed base replacement cycles, renewable capacity addition targets, and industrial electrification project pipelines. Industry-specific forecast inputs incorporated NEOM procurement rule evolution around local content thresholds and epoxy resin price elasticity assumptions tied to petrochemical feedstock indices.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion or technology licensing moves by European extra-high-voltage specialists would shift outcomes beyond modeled ranges. Macroeconomic deviation in oil prices affecting Aramco capital budgets, regulatory acceleration of SFDA safety documentation requirements, or breakthrough advances in solid-state transformer technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Flyback Transformer Market
Power Systems
Electrical and Automation System Market
Power Systems
Global Next Generation Power Semiconductors Market
Power Systems
MCR Based Static VAR Compensator Market
Power Systems
Power Amplifier Modules Market
Power Systems
Voltage Regulators Market
Power Systems
PV Micro Inverters Market
Power Systems
Asia-Pacific Electric Vehicle Power Inverter Market
Power Systems
North America Variable Frequency Drive Market
Power Systems
Smart Power Strips Market
Power Systems
Global Frequency Converter Market
Power Systems
Electric Vehicle Inverter Market
Power Systems
Thyristor Surge Protectors Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market
Power Systems
Japan Surge Protector Market
Power Systems
Shunt Capacitor Market