
 Semiconductor Memory IP Market | 2026-2036
Semiconductor Memory IP Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor Memory IP Market Outlook
Specialized analog and mixed-signal design talent is bifurcating the competitive landscape into firms that retain deep transistor-level expertise and those dependent on automated synthesis flows. Arm Holdings leverages its pervasive architecture ecosystem to sustain royalty streams across mobile and automotive memory controllers. Synopsys anchors its position through integrated verification tools that reduce silicon respin rates for complex memory interfaces. Cadence Design Systems competes by extending its custom design platform into advanced node memory compiler development.
Semiconductor Memory IP comprises licensable circuit blocks, physical layouts, and verification models that enable integrated memory subsystems within larger chips, typically specified by bit density, access latency, and power consumption metrics measured in picojoules per bit. These IP cores serve as foundational components for system-on-chip designs where embedded memory occupies sixty to seventy percent of die area in leading processors. DRAM IP for data center accelerators leads absolute licensing value due to hyperscaler demand for high-bandwidth memory interfaces. SRAM compilers for automotive MCUs represent the fastest-growing segment as ISO 26262 functional safety requirements drive redundant bitcell architectures. Flash IP retains mature margin pools in industrial microcontroller applications where endurance specifications exceed one hundred thousand program-erase cycles.
REACH substance restrictions and EU AI Act transparency requirements are reshaping documentation burdens for memory IP sold into European automotive and edge-AI supply chains. FDA software validation guidance for medical devices incorporating embedded memory is extending design cycle timelines for US-bound healthcare semiconductors. TSMC's N3E process design kit releases and Samsung Foundry's gate-all-around roadmap will determine which memory IP vendors retain foundry certification priority through the next process transition. Stakeholders must monitor foundry-process co-development agreements as the primary signal of which IP libraries will secure early design wins at advanced nodes.
Market Dynamics
Foundry consolidation around TSMC and Samsung at 3nm-class nodes is compressing memory IP vendor certification windows, forcing design houses to align compiler roadmaps with single-source process transitions or lose socket access.
Growth Catalysts
- Automotive functional safety mandates:ISO 26262 ASIL-D requirements for ADAS processors are mandating redundant SRAM bitcells and error-correcting memory controllers in every new vehicle platform.
- REACH substance documentation:EU chemical disclosure rules for semiconductor materials are creating compliance-based differentiation among IP vendors with pre-validated substance declarations.
- HBM3E interface proliferation:Data center accelerators from hyperscalers are licensing high-bandwidth memory PHYs at densities exceeding 24 gigabits per stack.
Market Restraints
- Advanced node mask cost escalation:N3E full-mask sets now exceed twenty-five million dollars per tapeout, freezing mid-tier fabless designers from custom memory compiler development.
- Taiwan fabrication concentration:Over eighty percent of leading-edge memory IP validation occurs at Hsinchu Science Park facilities, exposing supply chains to seismic and geopolitical disruption.
- Gate-all-around process uncertainty:Samsung Foundry's SF2 yield trajectories remain unproven, delaying memory compiler certification timelines by multiple quarters.
Strategic Opportunities
- India design ecosystem expansion:Bangalore and Hyderabad are attracting memory IP R&D centers as PLI scheme incentives offset talent cost arbitrage against Taiwan.
- Chiplets and 3D stacking convergence:Die-to-die interface IP bundled with memory controllers is opening new licensing bundles for multi-die AI accelerators.
- EU AI Act transparency rules:Documentation requirements for edge-AI training hardware are creating premium tiers for memory IP with full provenance traceability.
Industry Challenges
- Transistor-level analog expertise attrition:Memory bitcell design requires deep device physics knowledge that automated synthesis tools cannot replicate, constraining hiring pools to retiring specialists.
- Foundry-process co-development lock-in:Early PDK access agreements favor incumbent IP vendors, erecting barriers for new entrants seeking N2 node certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor Memory IP Market |
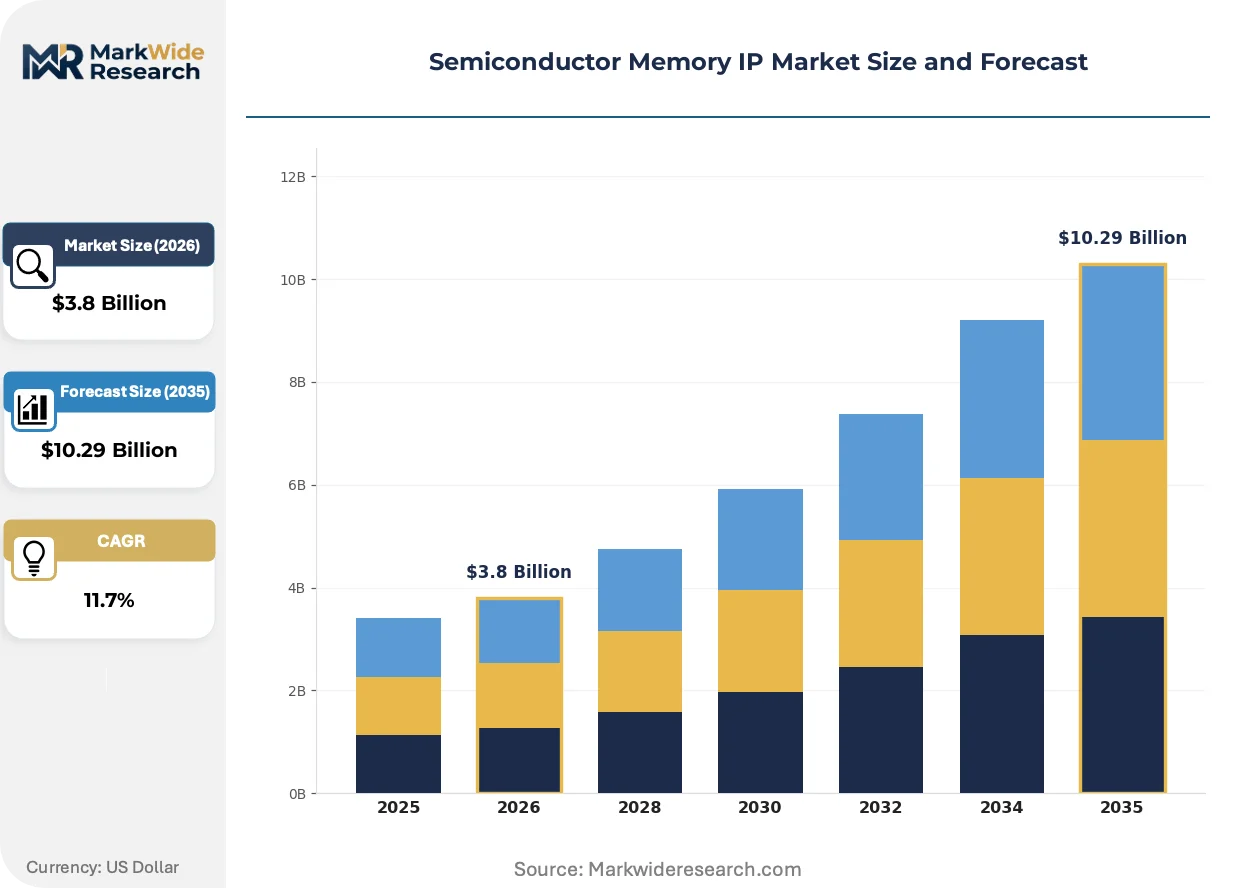
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash, EEPROM Technology: CMOS, BiCMOS, SOI, FinFET Application: Consumer Electronics, Data Centers, Automotive, Industrial End User: OEMs, Fabless Companies, Foundries, Design Houses |
| Companies Covered | Arm Holdings, Synopsys, Cadence Design Systems, Rambus, Mentor Graphics, Imagination Technologies, STMicroelectronics, eMemory Technology, Lattice Semiconductor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor Memory IP Market Strategic Shifts
Memory subsystem architectures are fragmenting along bandwidth-versus-latency tradeoffs, with each optimization path demanding distinct PHY and controller IP configurations.
Compute-in-memory arrays are displacing conventional von Neumann architectures in AI inference accelerators, with Mythic and Sambanova-class designs embedding analog MAC operations directly within SRAM bitcells. Edge-AI chip startups are licensing these topologies at 40nm nodes to sidestep external DRAM power penalties. This integration is displacing standalone HBM interfaces in sub-50-watt inference markets.
EU F-Gas Regulation phase-down schedules are pressuring memory IP vendors to eliminate sulfur hexafluoride from etch process documentation for European automotive customers. ECHA substance database alignment now precedes design win qualification for MCUs bound for German OEMs. IP houses with pre-certified green material declarations are capturing sockets in Stuttgart and Munich supply chains.
Hyperscaler procurement teams are consolidating memory IP vendor lists to three qualified sources per node, compressing qualification cycles from eighteen months to nine. This concentration is eliminating second-tier compiler houses from data center socket contests. The shift is most visible in Taiwan, where MediaTek and Alchip are absorbing former independent IP vendors into captive design flows.
Semiconductor Memory IP Market Segmentation
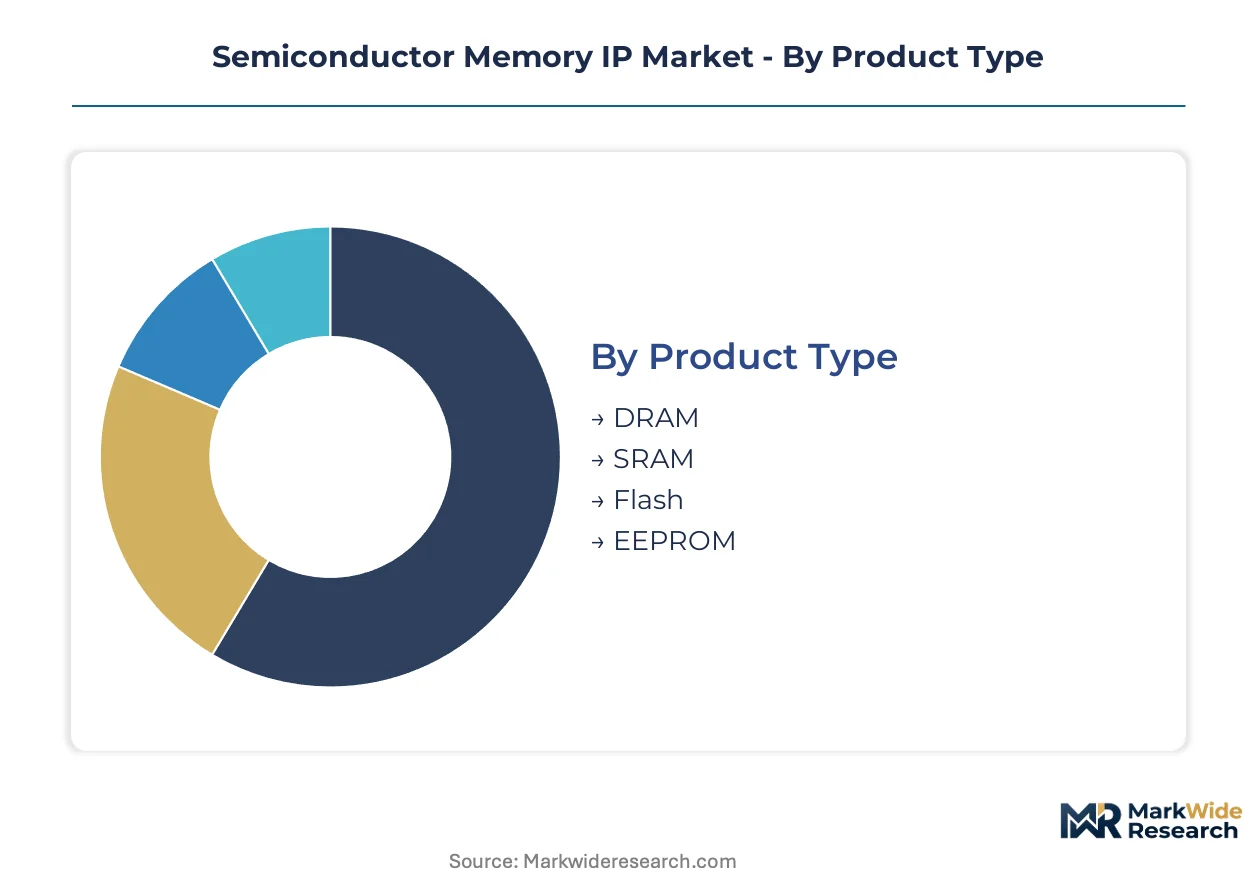
Memory IP segmentation reveals distinct procurement patterns across foundry nodes and end-use certifications. Each dimension carries implications for licensing terms, royalty structures, and validation timelines.
Product Type:
DRAM IP concentrates licensing value in Taiwan and South Korea where hyperscaler accelerator tapeouts dominate. SRAM and Flash IP serve more geographically dispersed automotive and industrial supply chains.
- DRAM:High-bandwidth memory PHYs for data center accelerators command premium royalties due to complex signal integrity requirements at advanced nodes. Licensing concentrates with TSMC-certified vendors serving hyperscaler procurement teams in Hsinchu.
- SRAM:Redundant bitcell architectures for ISO 26262 ASIL-D compliance are expanding fastest in automotive MCUs. Demand clusters around German OEM supply chains requiring REACH substance documentation.
- Flash:Industrial microcontroller applications with endurance specifications exceeding one hundred thousand program-erase cycles retain mature margin pools in Japanese and European factory automation.
- EEPROM:Low-density non-volatile IP for sensor calibration and security keys ships predominantly to Chinese consumer electronics OEMs.
DRAM holds the largest share; momentum sits with SRAM.
Technology:
Process node selection determines foundry certification priority and directly shapes which IP vendors retain socket access at each geometry.
- CMOS:Mature-node compilers at 28nm and above serve cost-sensitive microcontroller markets in India and Southeast Asia where PLI scheme incentives attract design activity.
- FinFET:TSMC N3E and Samsung SF2 memory compilers face tightening supply as foundry migration validates fewer IP sources per node. Certification windows compress to single-source dependencies.
- BiCMOS:Mixed-signal integration for RF-fronted memory controllers finds niche demand in South Korean smartphone baseband designs.
- SOI:Silicon-on-insulator bitcells target radiation-hardened aerospace applications with limited commercial volume.
FinFET commands premium positioning; CMOS delivers volume scale.
Application:
End-use certification requirements fragment procurement specifications across safety-critical and consumer-grade tiers.
- Automotive:Functional safety mandates from NHTSA and KBA drive redundant memory controller architectures. EU AI Act transparency rules add documentation burdens for edge-AI training hardware.
- Data Centers:Hyperscaler accelerator designs license HBM3E PHYs at densities exceeding 24 gigabits per stack, consolidating vendor lists to three qualified sources per node.
- Consumer Electronics:Smartphone SoC memory subsystems prioritize area efficiency over absolute bandwidth, favoring foundry-optimized SRAM compilers.
- Industrial:Programmable logic controllers and motor drives specify Flash IP with extended temperature ranges and hundred-thousand-cycle endurance.
Data centers generate highest absolute licensing value; automotive climbs fastest.
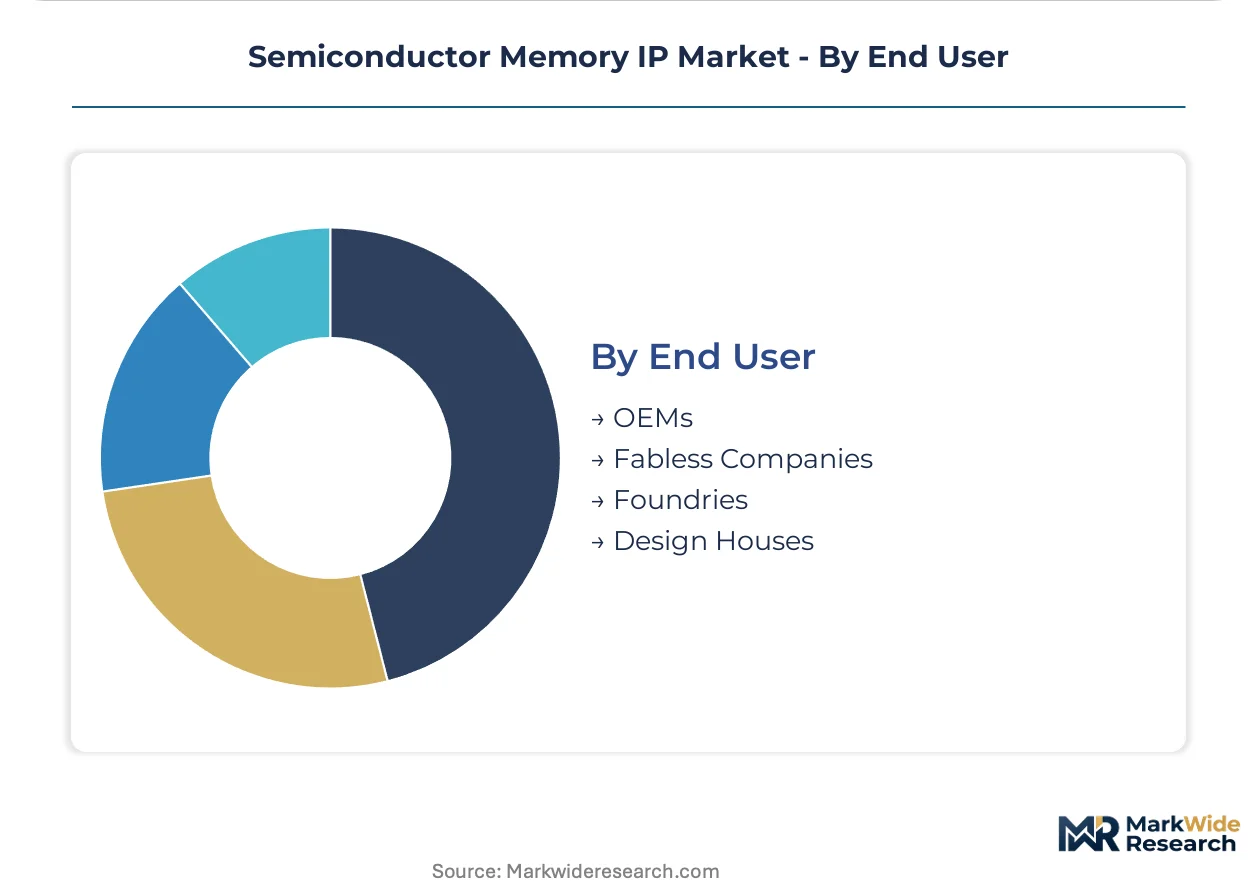
End User:
Business model differentiation separates captive design flows from merchant IP licensing with distinct contract structures and royalty terms.
- Fabless Companies:MediaTek-class integrated device vendors absorb independent IP vendors into captive flows, reducing external licensing dependence.
- Foundries:TSMC and Samsung Foundry co-development agreements determine which memory compilers receive early PDK access at N2-class nodes.
- OEMs:German automotive OEMs pre-qualify IP vendors with ECHA-aligned substance declarations before design win consideration.
- Design Houses:Alchip-class ASIC specialists bundle memory IP with die-to-die interfaces for chiplet-based AI accelerators.
Foundries gate access to leading-edge nodes; design houses capture chiplet bundling opportunity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
TSMC's N3E process development at Hsinchu Science Park anchors memory IP certification pipelines, with Taiwan's national semiconductor regulator coordinating foundry-process co-development agreements that gate access to leading-edge compiler libraries.
Taiwan
Hsinchu Science Park and Tainan Science Park concentrate over eighty percent of leading-edge memory IP validation facilities for TSMC N3E and N2 nodes. The National Science and Technology Council coordinates foundry-process co-development agreements that determine which IP vendors receive early PDK access. MediaTek and Alchip design centers in Taipei are absorbing independent IP vendors into captive flows, reducing external licensing dependence.
South Korea
Samsung Foundry's gate-all-around SF2 roadmap drives memory compiler certification timelines for data center accelerator designs. The Ministry of Trade, Industry and Energy oversees PLI-equivalent incentives for domestic memory IP R&D. Seoul and Suwon host design centers where hyperscaler procurement teams consolidate vendor lists to three qualified sources per node.
United States
Silicon Valley and Austin design houses license HBM3E PHYs for hyperscaler accelerators requiring complex signal integrity at advanced nodes. FDA software validation guidance for medical devices extends design cycle timelines for healthcare semiconductors incorporating embedded memory. NVIDIA and AMD procurement teams in Santa Clara are compressing qualification cycles from eighteen months to nine.
Germany
Stuttgart and Munich automotive OEMs pre-qualify memory IP vendors with ECHA-aligned REACH substance declarations before design win consideration. KBA functional safety mandates drive redundant SRAM bitcell architectures for ISO 26262 ASIL-D compliance. Infineon and Bosch design centers in Dresden and Reutlingen specify redundant memory controllers for ADAS processors.
China
Yangtze River Delta design houses in Shanghai and Suzhou license mature-node CMOS compilers at 28nm and above for cost-sensitive microcontroller markets. MIIT domestic substitution policies prioritize local memory IP development for industrial automation. SMIC fabs in Beijing and Shenzhen validate compilers for consumer electronics OEMs with extended temperature range requirements.
Semiconductor Memory IP Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with architecture-license incumbents commanding premium royalties while automated synthesis vendors compete on compiler development cost. The vendor base concentrates around three tiers: pervasive ecosystem architects, integrated verification platforms, and specialized bitcell developers. Strategic moves center on foundry-process co-development lock-in and geographic R&D expansion to capture PLI scheme incentives.
Within the pervasive ecosystem tier, Arm Holdings exemplifies architecture-license dominance across mobile and automotive memory controllers. Synopsys and Cadence Design Systems anchor the integrated platform tier, with Synopsys representing verification-tool bundling and Cadence occupying the custom design platform position. These three entities collectively determine which memory IP libraries secure early design wins at TSMC N2-class nodes through PDK access priority.
| Leading Market Players |
|---|
| Arm Holdings |
| Synopsys |
| Cadence Design Systems |
| Rambus |
| Mentor Graphics |
| Imagination Technologies |
| STMicroelectronics |
| eMemory Technology |
| Lattice Semiconductor |
| Others |
Value Chain & Pricing Dynamics
ISO 26262 ASIL-D certification gates both foundry qualification timelines and royalty tier differentiation, forcing automotive memory IP vendors to absorb validation costs upfront while commanding premium pricing for redundant bitcell architectures. This dual-gate mechanism concentrates pricing power with TSMC-certified incumbents who secured early N3E PDK access.
Pricing Analysis
Taiwan-based licensing commands fifteen to twenty percent premiums over South Korean and US equivalents due to Hsinchu Science Park validation density. The market operates on a licensing-plus-royalty hybrid model where upfront compiler fees scale with process node advancement while per-unit royalties reflect bit density and access latency specifications. Price differentiation hinges on foundry certification tier and functional safety compliance grade, with ASIL-D validated IP capturing standard-tier margins threefold. Cost compression in mature-node CMOS compilers is intensifying because Indian and Southeast Asian design houses are internalizing compiler development under PLI scheme subsidies. Fabless microcontroller vendors exhibit highest price sensitivity, whereas hyperscaler accelerator teams prioritize signal integrity guarantees over absolute licensing cost.
Supply Chain Analysis
Hsinchu Science Park fabrication concentration underwrites eighty percent of leading-edge memory IP validation, creating single-source vulnerability for N2-class compiler certification. Raw material dependencies span EUV photoresist from Japan, high-purity silicon wafers from Germany, and specialty gases from US chemical suppliers. Tariff exposure on semiconductor manufacturing equipment imports threatens to extend foundry-process co-development timelines by multiple quarters. Distribution runs through direct foundry partnerships rather than merchant channels, with TSMC and Samsung Foundry gatekeeping PDK access that determines which IP libraries reach design houses.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Memory IP economics are shifting toward platform dominance as hyperscaler procurement teams consolidate vendor lists and gate-all-around process transitions demand co-development lock-in. Interoperability between die-to-die interface standards and memory controller architectures is becoming the primary ecosystem battleground.
For Market Incumbents: Secure foundry-process co-development agreements at Samsung SF2 and TSMC N2 nodes before gate-all-around yield trajectories stabilize, denying new entrants early PDK access. Defend margin position by backward integration into custom bitcell design teams in Bangalore and Hyderabad, capturing PLI scheme talent subsidies while automated synthesis vendors struggle to replicate transistor-level expertise. For New Entrants and Emerging Players: Differentiate on REACH substance documentation pre-certification for German automotive OEM supply chains, where ECHA-aligned declarations precede design win consideration. Target mature-node CMOS compiler development for Indian microcontroller markets under PLI scheme incentives, where cost-sensitive fabless designers are freezing out advanced node dependencies. Lead with green material transparency as the go-to-market wedge against incumbent IP vendors with legacy etch process documentation. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across gate-all-around memory compiler development as mask set costs exceed twenty-five million dollars per N3E tapeout. Long-term viability favors acquisition targets with captive foundry relationships or specialized analog bitcell expertise that automated flows cannot replicate. Monitor Samsung Foundry SF2 yield announcements as the primary signal for which memory IP vendors will retain socket access through the next process transition.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry-Process Co-Development Agreement | Early PDK access at TSMC N2 nodes gates which IP vendors secure hyperscaler accelerator sockets. |
| Functional Safety Certification Investment | ISO 26262 ASIL-D compliance opens German automotive OEM supply chains requiring redundant bitcell architectures. |
| Geographic R&D Expansion | Bangalore and Hyderabad design centers capture PLI scheme incentives while offsetting Taiwan talent cost premiums. |
| Green Material Documentation Pre-Certification | ECHA-aligned REACH declarations differentiate vendors for EU F-Gas Regulation compliance in automotive MCUs. |
| Chiplet Interface Bundling | Die-to-die PHY integration with memory controllers creates new licensing tiers for multi-die AI accelerators. |
Study Parameters
A standing panel of memory compiler design leads, foundry platform engineers, hyperscaler procurement managers, and automotive SoC architects provided ongoing calibration across the study period. Primary interviews with TSMC-certified IP vendors and Samsung Foundry co-development partners were cross-validated against secondary sources including SEC 10-K filings, foundry PDK release documentation, and ECHA substance database records. Bottom-up bitcell architecture demand modeling was triangulated with top-down foundry capacity allocation analysis.
Consistency checks against hyperscaler accelerator tapeout announcements and automotive MCU design win disclosures validated projection outputs across the modeling period. The analytical framework segmented by memory type, process node, application certification tier, and end-user business model, with CAGRs derived from foundry node transition pacing and functional safety mandate adoption curves. Forecast inputs incorporated gate-all-around yield trajectory uncertainty and PLI scheme incentive uptake rates in India.
Material uncertainties — gate-all-around process yield delays, Taiwan seismic disruption, and EU AI Act documentation scope expansion — sit outside the modeled envelope. Forecasts reflect assumptions about foundry consolidation continuity and certification regime stability that practitioners should keep alternative scenarios live as geopolitical conditions and process technology roadmaps evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Japan MCU Market
Semiconductor Devices
Embedded Multimedia Card Market
Semiconductor Devices
Analog to Digital Converter Market
Semiconductor Devices
United Arab Emirates (UAE) CEP Market
Semiconductor Devices
Nanowires Market
Semiconductor Devices
Middle East Distribution Panel Market
Semiconductor Devices
High Voltage Diodes Market
Semiconductor Devices
Modular Plating System Market
Semiconductor Devices
Asia-Pacific Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Multilayer Chip Bead Market
Semiconductor Devices
Digital Tunable Capacitors Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
Silicon Carbide Semiconductor Devices Market
Semiconductor Devices
APAC Semiconductor Device in Aerospace and Defense Market