
 Europe Outdoor LED Lighting Market | 2026-2036
Europe Outdoor LED Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Outdoor LED Lighting Market Insights
Municipal buyers are reorganizing procurement priorities around connected infrastructure and lifecycle cost models rather than upfront capex. Signify N.V. dominates the smart controls segment through its Interact platform deployment across Dutch and Belgian city networks. TRILUX Group anchors its position in German road-tunnel and highway projects with high-lumen efficacy modules. ams-OSRAM AG extends its LED component supply relationships into luminaire-agnostic sensor ecosystems.
Europe outdoor LED lighting encompasses solid-state luminaires engineered with aluminum or polycarbonate housings, typically delivering 100-150 lumens per watt, designed for exterior illumination in public and commercial environments exposed to weather, vibration, and thermal cycling. Street lights and flood lights command the largest installed base, though bollard lights and wall lights carry higher margin profiles in heritage district and pedestrian-zone retrofits where aesthetic compliance restricts standardization. Smart lighting and solar-powered technologies are expanding fastest, while traditional LED replacements of high-pressure sodium installations remain the volume core across Eastern European municipalities with deferred infrastructure budgets.
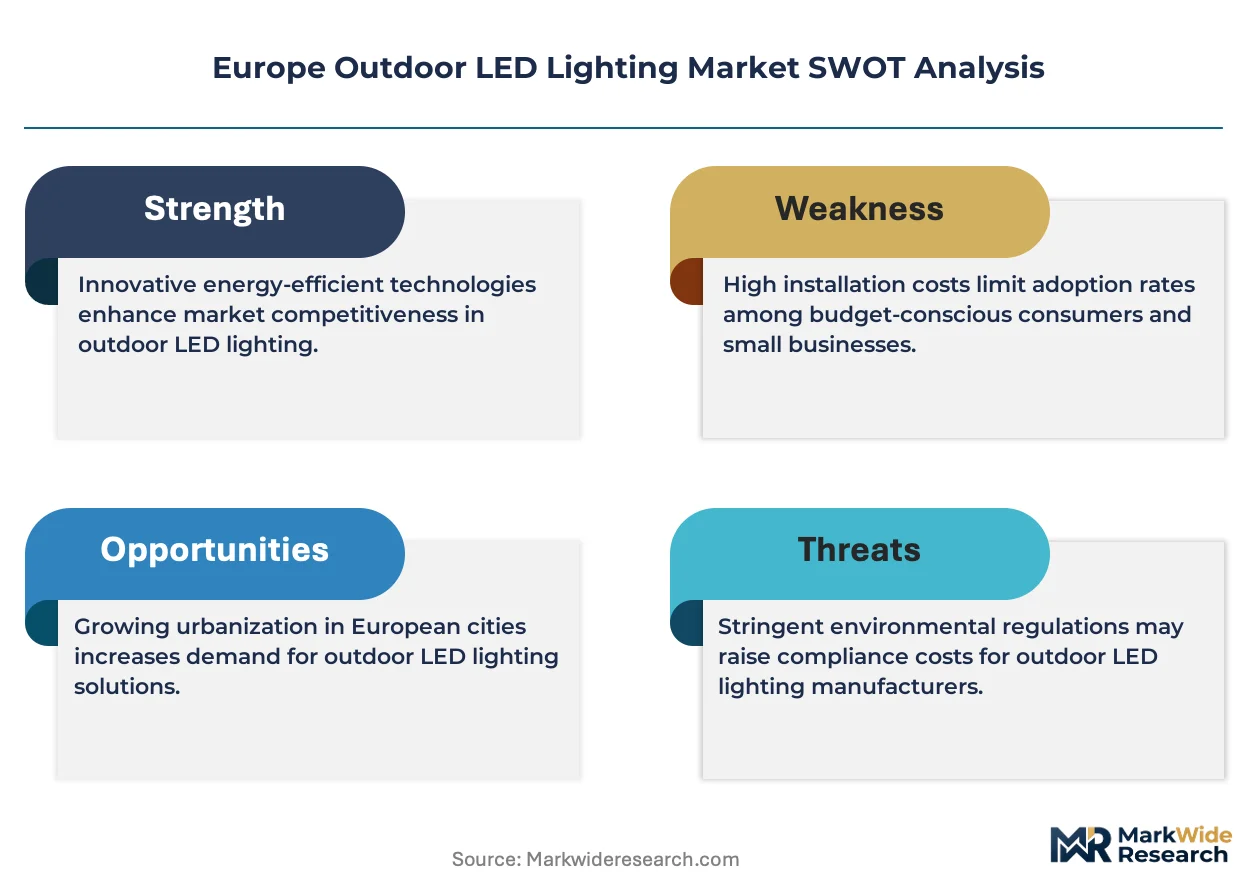
The EU Green Deal and F-Gas Regulation constrain legacy lighting energy profiles, while CE marking and Ecodesign requirements enforce minimum efficacy thresholds that filter out low-cost imports. ECHA REACH compliance on aluminum alloy and phosphor chemistries adds material traceability burdens that favor established European supply chains. Stakeholders must weigh the pace of subsidy tapering against the embedded software upgrade paths that determine whether installed luminaires remain interoperable with evolving city data platforms.
Market Dynamics
The EU Green Deal's binding energy-efficiency mandates are compressing replacement cycles for sodium-vapor street lighting across European municipalities, forcing procurement departments to prioritize networked LED retrofits with embedded sensor architectures over standalone luminaire swaps.
Growth Catalysts
- EU Green Deal mandates:Binding national targets for public-sector energy reduction are accelerating municipal LED conversion timelines in Germany, France, and the Netherlands.
- Smart city sensor convergence:Embedded environmental and traffic monitoring capabilities are transforming street lights into multi-purpose data collection nodes.
- Eastern European deferred infrastructure:Polish and Romanian municipalities are executing backlog replacements of high-pressure sodium installations with EU cohesion fund support.
Market Restraints
- Aluminum alloy input volatility:Die-cast housing material costs fluctuate with energy-intensive smelting economics, compressing luminaire margin structures.
- ECHA REACH compliance burdens:Phosphor chemistry traceability requirements add documentation overhead that filters out smaller import competitors.
- Legacy control system incompatibility:Existing DALI and 0-10V dimming infrastructures limit seamless upgrade paths to wireless mesh networks.
Strategic Opportunities
- Portuguese and Greek solar-hybrid retrofits:High insolation hours and island grid fragility create favorable economics for off-grid capable LED installations.
- CSRD-aligned lifecycle service contracts:Corporate sustainability reporting requirements are opening municipal-adjacent commercial campus lighting to performance-based procurement.
- LiDAR-integrated adaptive dimming:Convergence of automotive sensing technology with street lighting controls enables predictive illumination adjustment.
Industry Challenges
- Embedded software talent scarcity:Firmware engineering for interoperable city data platforms commands premium compensation that strains mid-tier luminaire vendors.
- CE marking and Ecodesign certification timelines:Third-party testing backlogs for efficacy verification delay product launches by 4-8 months.
- Multi-vendor platform fragmentation:Proprietary smart city protocols from competing controls suppliers complicate municipal interoperability specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Outdoor LED Lighting Market |
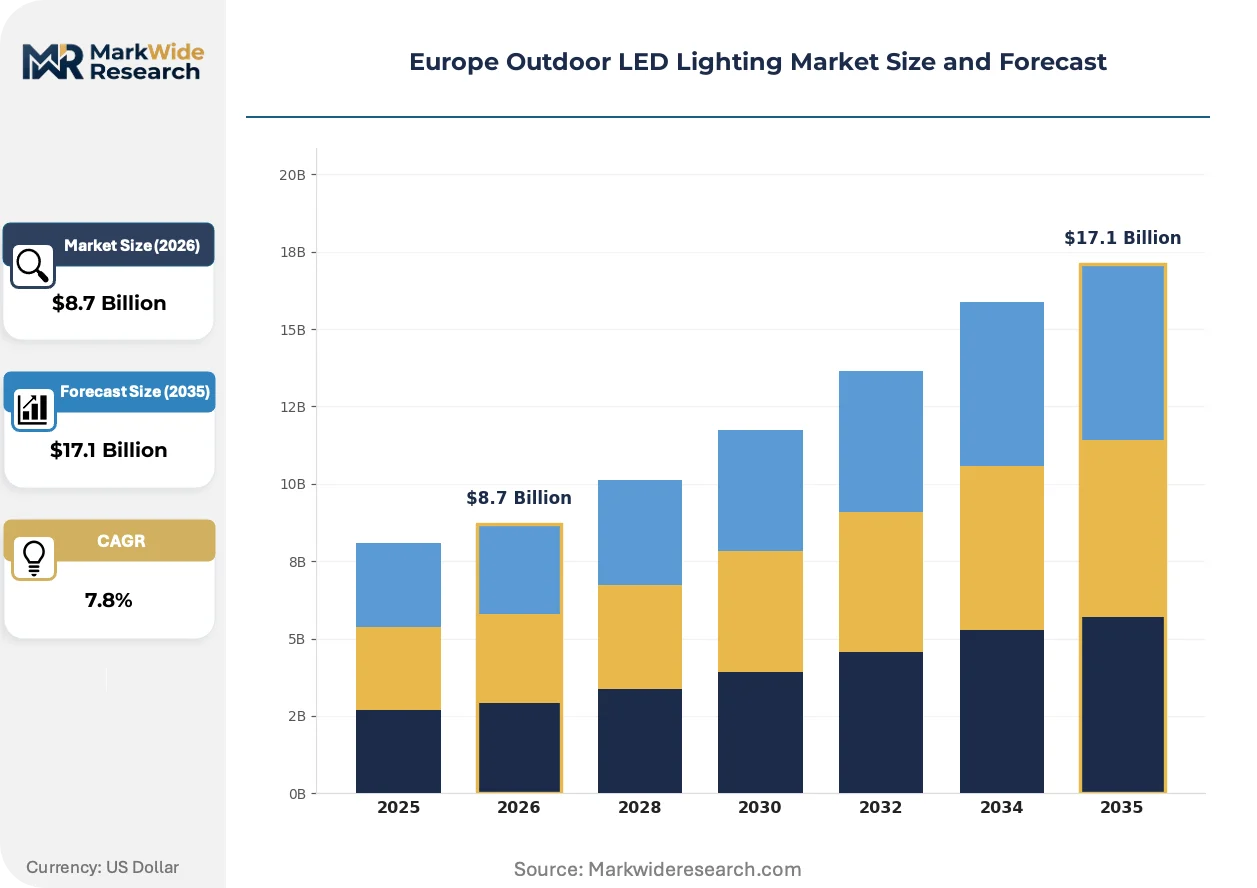
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.1 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Street Lights, Flood Lights, Bollard Lights, Wall Lights Application: Public Spaces, Roadways, Park Lighting, Commercial Areas Technology: Smart Lighting, Solar Powered, Traditional LED, Hybrid Systems End User: Cities, Contractors, Real Estate Developers, Organizations |
| Companies Covered | TRILUX Group, Thorn Lighting, Signify N.V., SG Lighting Europe, Luceco plc, ams-OSRAM AG, Fagerhult Group, Cree, Inc., Zumtobel Group AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Outdoor LED Lighting Market Trends and Innovations
Connected infrastructure architectures are displacing standalone luminaire sales across European public procurement, with software-defined lighting controls capturing an expanding share of total project value and reshaping vendor competitive positioning.
Adaptive street lighting technology is bifurcating the installed base between basic photocell-equipped replacements and fully networked systems with motion-sensing and environmental monitoring. Scandinavian urban renewal programs in Stockholm and Copenhagen are specifying sensor-embedded luminaires as standard, compressing demand for conventional LED retrofits without connectivity. This technology split is forcing manufacturers to maintain dual product lines or abandon the low-connectivity segment entirely.
The F-Gas Regulation's phase-down of high-global-warming-potential refrigerants in outdoor fixture cooling systems is accelerating adoption of passive thermal management designs. Die-cast aluminum heat sinks with optimized fin geometries are displacing active cooling in high-lumen output flood and tunnel applications. German road-tunnel specifications under KBA guidelines now prioritize passive thermal architectures for maintenance-access reduction.
Municipal procurement departments are consolidating vendor relationships around single-platform smart city ecosystems rather than best-of-luminaire sourcing. French and Belgian cities are bundling street lighting, traffic signal, and EV charging infrastructure under unified Interact-compatible contracts. This buyer concentration is squeezing smaller controls-agnostic manufacturers from premium tender participation.
Europe Outdoor LED Lighting Market Segmentation
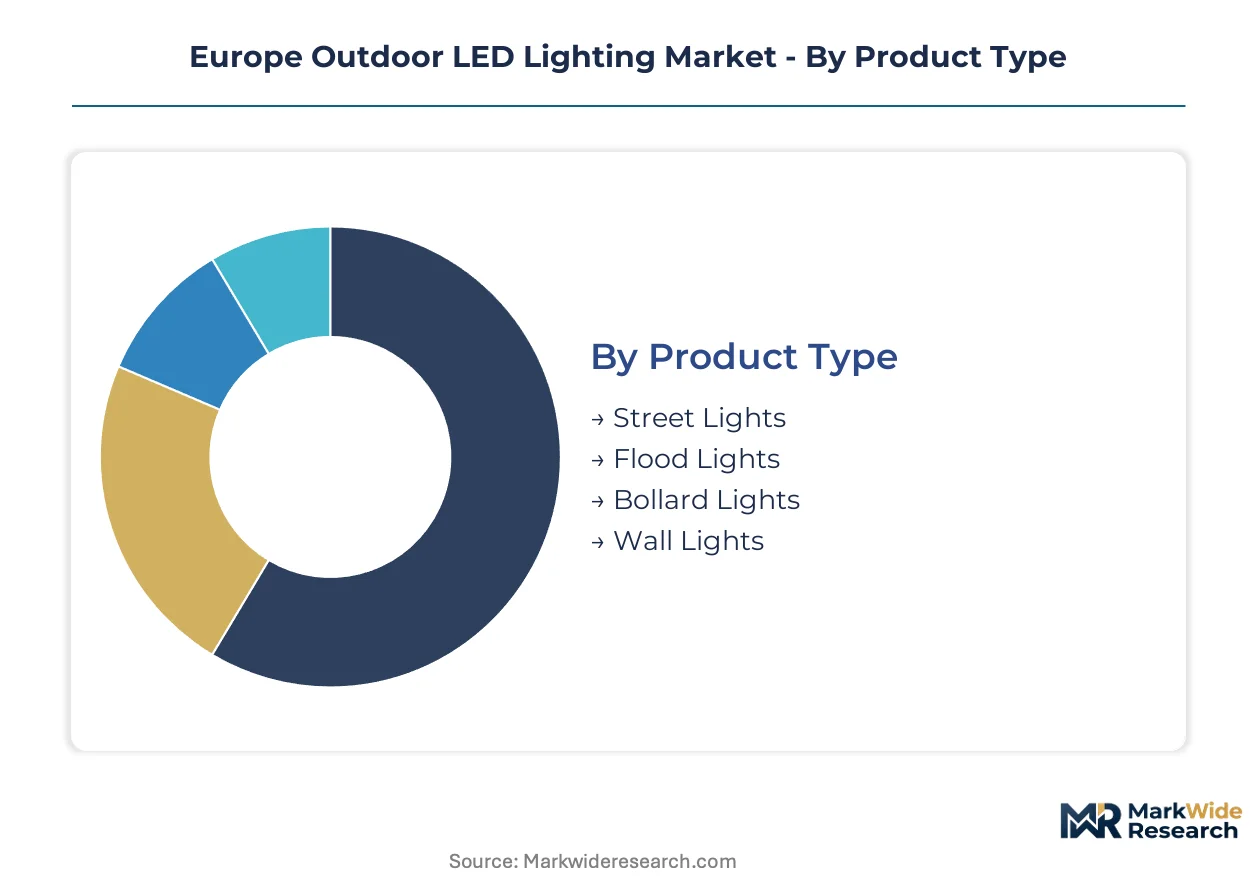
Segmentation in Europe outdoor LED lighting reveals distinct procurement channels and margin architectures. Municipal buyers, commercial developers, and infrastructure contractors each route through separate specification pathways that determine technology adoption speed and pricing power.
Product Type:
Street lights and flood lights flow primarily through municipal procurement frameworks with extended tender cycles, while bollard and wall lights reach end-users via architectural specification channels and heritage district contractors.
- Street Lights:Pole-mounted luminaires delivering 100-150 lumens per watt with die-cast aluminum housings engineered for wind loading and vibration resistance. German, French, and Dutch municipalities are specifying these with embedded DALI-2 and wireless mesh controls to satisfy EU Green Deal energy-efficiency mandates.
- Flood Lights:High-lumen output fixtures with optimized passive thermal management replacing active cooling in road-tunnel applications. TRILUX Group anchors its competitive position in German highway and tunnel projects under KBA guidelines that prioritize maintenance-access reduction.
- Bollard Lights:Low-level pedestrian zone luminaires with higher margin profiles in heritage district retrofits where aesthetic compliance restricts standardization.
- Wall Lights:Building-mounted exterior fixtures specified by real estate developers for commercial campus and hospitality applications with design-forward requirements.
By volume, Street Lights leads. By growth pace, Bollard Lights is ahead.
Application:
Application segments stratify by project scale and subsidy eligibility, with public-sector roadways commanding the largest contract values and commercial areas offering faster payment cycles.
- Public Spaces:Plazas, civic centers, and pedestrian corridors requiring aesthetic compliance alongside efficacy targets. Scandinavian urban renewal programs in Stockholm and Copenhagen are specifying sensor-embedded luminaires as standard, compressing demand for conventional retrofits without connectivity.
- Roadways:Arterial streets, highways, and tunnels with the highest lumen output requirements and most stringent safety regulations. Polish and Romanian municipalities are executing backlog replacements of high-pressure sodium installations with EU cohesion fund support.
- Park Lighting:Recreational and conservation area illumination balancing wildlife impact constraints with security requirements.
- Commercial Areas:Retail parks, logistics facilities, and corporate campuses where CSRD-aligned lifecycle service contracts are opening performance-based procurement pathways.
Roadways generates the largest contract values. Commercial Areas shows the steepest expansion trajectory as private-sector sustainability reporting obligations deepen.
Technology:
Technology segments diverge by infrastructure dependency, with solar-hybrid systems gaining traction in grid-fragile geographies and smart lighting capturing software-defined value pools.
- Smart Lighting:Networked controls with embedded environmental and traffic monitoring transforming street lights into multi-purpose data collection nodes. French and Belgian cities are bundling street lighting, traffic signal, and EV charging infrastructure under unified platform-compatible contracts.
- Solar Powered:Off-grid capable installations with battery storage for island and remote applications. Portuguese and Greek municipalities are deploying these where high insolation hours and grid fragility create favorable economics.
- Traditional LED:Basic photocell-equipped replacements without connectivity, still dominating Eastern European volume where deferred infrastructure budgets limit smart city investment.
- Hybrid Systems:Grid-tied solar with battery backup for resilience in critical infrastructure corridors.
Traditional LED retains the largest installed base. Smart Lighting is climbing the fastest as municipal procurement reorganizes around connected infrastructure and lifecycle cost models.
End User:
End-user concentration determines specification complexity, with cities driving standardization and contractors fragmenting demand across project-specific requirements.
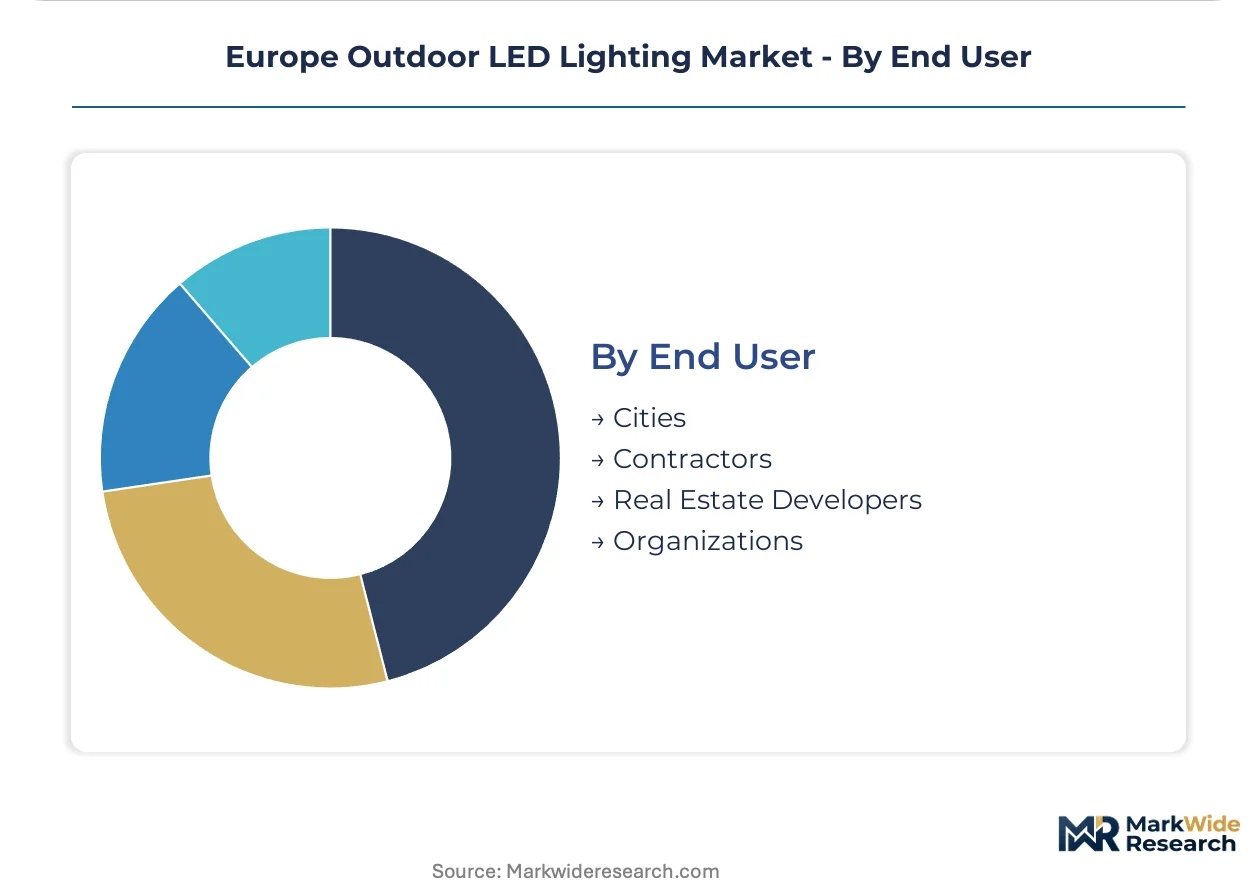
- Cities:Municipal governments with binding EU Green Deal targets compressing replacement cycles for sodium-vapor street lighting. Procurement departments are prioritizing networked LED retrofits with embedded sensor architectures over standalone luminaire swaps.
- Contractors:Infrastructure and electrical installation firms executing public and private projects with varying technical specifications and interoperability requirements.
- Real Estate Developers:Commercial and residential project sponsors specifying exterior lighting for new construction and major renovation, increasingly subject to CSRD disclosure obligations.
- Organizations:Universities, healthcare campuses, and industrial facilities with autonomous procurement authority and sustainability commitments.
Cities account for the dominant procurement volume. Real Estate Developers are gaining share fastest as corporate sustainability reporting requirements expand the commercial-adjacent market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component supply and luminaire assembly concentrate in German industrial clusters, with control system development gravitating toward Dutch and Belgian technology hubs. Municipal procurement patterns diverge sharply between Western European smart-city adopters and Eastern European backlog replacement markets.
Germany
Road-tunnel and highway illumination drives specialized demand for high-lumen efficacy modules with passive thermal management. KBA guidelines now mandate maintenance-access reduction protocols that favor die-cast aluminum heat sink architectures. The Ruhr industrial corridor hosts concentrated luminaire manufacturing capacity serving domestic infrastructure tenders.
Netherlands
Networked street lighting deployment leads European adoption curves as municipalities bundle illumination with traffic signal and EV charging infrastructure. Signify N.V.'s Interact platform compatibility dominates procurement specifications across Randstad urban networks. Eindhoven's technology ecosystem supplies embedded sensor architectures for multi-purpose data collection nodes.
France
CSRD disclosure obligations are expanding municipal-adjacent commercial campus lighting into performance-based procurement channels. CE marking and Ecodesign efficacy verification create certification bottlenecks that filter non-compliant imports. The Île-de-France region concentrates specification authority for national infrastructure renewal programs.
Poland
Deferred high-pressure sodium replacement backlogs are clearing with EU cohesion fund support for basic LED retrofits without connectivity infrastructure. Municipal budgets prioritize upfront capex minimization over lifecycle cost optimization. The Silesian urban agglomeration represents the largest concentrated replacement opportunity in Eastern Europe.
Portugal
Solar-hybrid installations gain traction where high insolation hours and island grid fragility create favorable off-grid economics. Alentejo and Algarve municipalities are deploying autonomous systems with battery storage for resilience in critical corridors. National energy independence targets accelerate subsidy allocation toward renewable-integrated lighting.
Europe Outdoor LED Lighting Market Competitive Landscape
Concentration sits with diversified lighting conglomerates possessing integrated control platforms and established municipal procurement relationships. The vendor base stratifies across three tiers: platform-anchored solution providers, component-specialized suppliers, and regional installation contractors. Competitive dynamics revolve around software interoperability certification and lifecycle service contract capture rather than luminaire unit pricing. Strategic moves emphasize platform ecosystem bundling and CSRD-aligned performance contracting.
Among platform-anchored conglomerates, Signify N.V. and ams-OSRAM AG represent contrasting archetypes of system integration versus component supply specialization. TRILUX Group occupies a position within German engineering-focused fabrication. These entities exemplify the strategic divergence between software-defined lighting controls and luminaire-agnostic hardware supply.
| Leading Market Players |
|---|
| TRILUX Group |
| Thorn Lighting |
| Signify N.V. |
| SG Lighting Europe |
| Luceco plc |
| ams-OSRAM AG |
| Fagerhult Group |
| Cree, Inc. |
| Zumtobel Group AG |
| Others |
Pricing and Supply Chain Analysis
CE marking and Ecodesign efficacy verification gates both supply qualification and price differentiation simultaneously, filtering non-compliant imports from premium municipal tenders while compressing margin structures for mid-tier vendors caught between certification investment and procurement budget constraints.
Pricing Analysis
The EU Green Deal dictates the pricing tier structure across European outdoor LED lighting procurement. Three-tier pricing separates smart-connected systems with embedded sensor architectures from basic photocell-equipped retrofits and economy-grade sodium-vapor replacements. Price differentiation rests on certification grade and after-sales service bundling, with lifecycle service contracts commanding premiums over transactional luminaire sales. Cost compression in the traditional LED segment is intensifying because Eastern European municipalities prioritize upfront capex minimization. Municipal buyers exhibit highest price sensitivity, while commercial developers under CSRD obligations show lowest sensitivity to premium positioning.
Supply Chain Analysis
Just-in-time inventory strategies dominate luminaire assembly operations serving municipal tender cycles, while strategic stockpiling of aluminum alloy and phosphor chemistries mitigates ECHA REACH documentation delays. Manufacturing concentrates in Germany, the Netherlands, and China, with die-cast housing fabrication anchored in the Ruhr industrial corridor and control system development gravitating toward Eindhoven's technology ecosystem. Raw material dependencies draw from aluminum smelters, rare-earth phosphor suppliers, and semiconductor foundries. Single-source vulnerability in embedded sensor chipsets poses structural risk. Distribution runs through municipal procurement frameworks, architectural specification channels, and electrical installation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe outdoor LED lighting market is emerging from a cyclical trough driven by EU cohesion fund disbursement acceleration, which is clearing Eastern European deferred infrastructure backlogs and restoring volume momentum to component suppliers.
For Market Incumbents: Consolidate control platform ecosystems through interoperability certification investments that lock out smaller competitors from bundled smart city tenders. Acquire embedded software engineering capabilities to address firmware talent scarcity that strains mid-tier vendors. Vertical integration into aluminum heat sink fabrication defends margin position against energy-intensive smelting cost volatility. For New Entrants and Emerging Players: Differentiate on solar-hybrid system design for Portuguese and Greek island municipalities where grid fragility creates favorable off-grid economics. Target heritage district bollard and wall light specifications where aesthetic compliance restricts standardization and margins exceed street light commoditization. Pursue CSRD-aligned lifecycle service contracts as the go-to-market angle for commercial campus penetration. For Investors and Strategic Acquirers: The F-Gas Regulation phase-down reshapes the acquisition landscape toward passive thermal management specialists with KBA-compliant tunnel lighting credentials. Long-term viability favors platform-anchored solution providers over luminaire-agnostic hardware vendors. Target acquisition archetype: mid-cap controls developers with municipal procurement relationships and embedded sensor IP. Watch EU subsidy tapering schedules as the inflection indicator for replacement cycle velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Platform Integration | Signify's Interact deployment across Randstad networks demonstrates bundled infrastructure capture. |
| Passive Thermal Management Transition | TRILUX's KBA-compliant tunnel specifications validate die-cast aluminum heat sink architectures. |
| Solar-Hybrid System Development | Portuguese Alentejo municipalities prove autonomous battery storage economics in high-insolation corridors. |
| CSRD-Aligned Service Contracting | French commercial campuses adopt performance-based procurement under sustainability reporting obligations. |
| Embedded Sensor Architecture Licensing | ams-OSRAM extends component supply into luminaire-agnostic environmental monitoring ecosystems. |
Research Methodology
A standing panel of municipal procurement directors, electrical installation contractors, smart city platform engineers, and aluminum alloy suppliers provided ongoing calibration across the research process. Primary interviews with these stakeholders combined with secondary validation from EU tender databases, ECHA REACH registration filings, KBA technical guidelines, and SEC disclosures from listed lighting conglomerates. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic indicators.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning product type, application, technology, and end-user concentration, with regional regulatory cluster and subsidy eligibility tier as additional industry-specific variables. CAGRs were derived from replacement cycle compression rates and smart city investment trajectories. Forecast inputs incorporated EU Green Deal mandate timelines and cohesion fund disbursement schedules.
Material uncertainties — aluminum smelting energy cost volatility, embedded software talent availability, and multi-vendor platform fragmentation — sit outside the modeled envelope. Forecasts reflect assumptions regarding subsidy continuity and interoperability standard convergence. Revision becomes warranted when EU municipal budget austerity crosses thresholds that delay networked retrofit procurement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
LED
Global LED Phosphor Market
LED
Global Industrial and Commercial LED Lighting Market
LED
France Indoor LED Lighting Market
LED
High-Brightness Light-Emitting Diodes (LED) Headlamps Market
LED
LED Flip Chip Market
LED
UAE LED Lights Market
LED
Mexico LED Lighting Market
LED
United States Micro LED Market
LED
LED Display Market
LED
Infrared (IR) LED Market
LED
Four-Digit 7 Segment LED Displays Market
LED
US LED Downlight Market
LED
South America Indoor LED Lighting Market
LED
Asia Pacific Indoor LED Lighting Market
LED
South America LED Lighting Market
LED
Gan Micro LED Market