
 United States Frequency Converter Market | 2026-2036
United States Frequency Converter Market Size, Share, and Industry Trends Forecast 2026-2036
United States Frequency Converter Market Intelligence
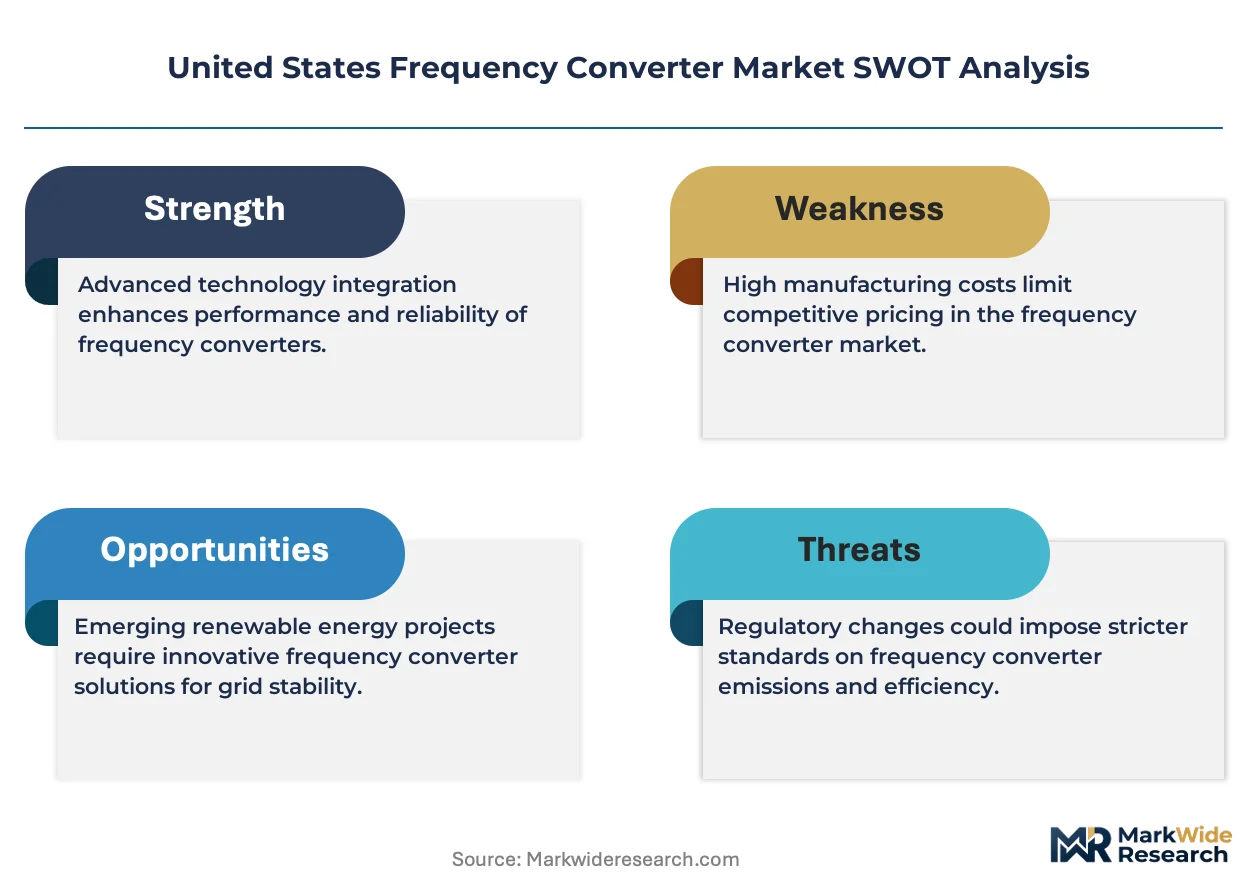
A widening capability gap between integrated power-electronics platforms and component-assembled systems is rotating competitive advantage toward firms with in-house semiconductor fabrication. Siemens AG leverages vertical integration across IGBT and SiC module production to sustain margin capture in high-voltage industrial segments. ABB Ltd anchors its position through dedicated R&D centers in North Carolina that specialize in marine and rail converter architectures. General Electric Company competes via its retained manufacturing scale in Schenectady, where it controls foundry-to-assembly workflows for aerospace-qualified units.
United States frequency converters are electromechanical or solid-state devices that transform input power at one frequency to output power at another, typically spanning 50 Hz to 60 Hz or 400 Hz for aviation ground support, with power ratings from fractional kilowatts to multi-megawatt systems. Their primary purpose is to enable cross-border equipment compatibility, stabilize variable renewable generation, and supply precision power to sensitive military and telecommunications loads. Static converter designs dominate volume shipments due to silicon carbide adoption lowering switching losses, while rotary converter demand persists in legacy defense installations where electromagnetic isolation remains non-negotiable. Pulse width modulation technology leads new installations across renewable energy and rail transportation applications, whereas cycloconverter architectures retain niche positions in high-torque marine propulsion systems.
FAA certification standards under 14 CFR Part 25 govern airborne frequency converter safety, while NHTSA electromagnetic compatibility rules shape automotive test-rig procurement, and IEEE 519 harmonic limits constrain industrial automation grid-connection designs. These frameworks compel manufacturers to maintain dual certification tracks, raising barriers for non-domestic suppliers without U.S. testing infrastructure. Stakeholders must monitor pending EPA efficiency regulations for variable-frequency drives, as these will cascade into converter specification requirements across power generation and industrial automation verticals.
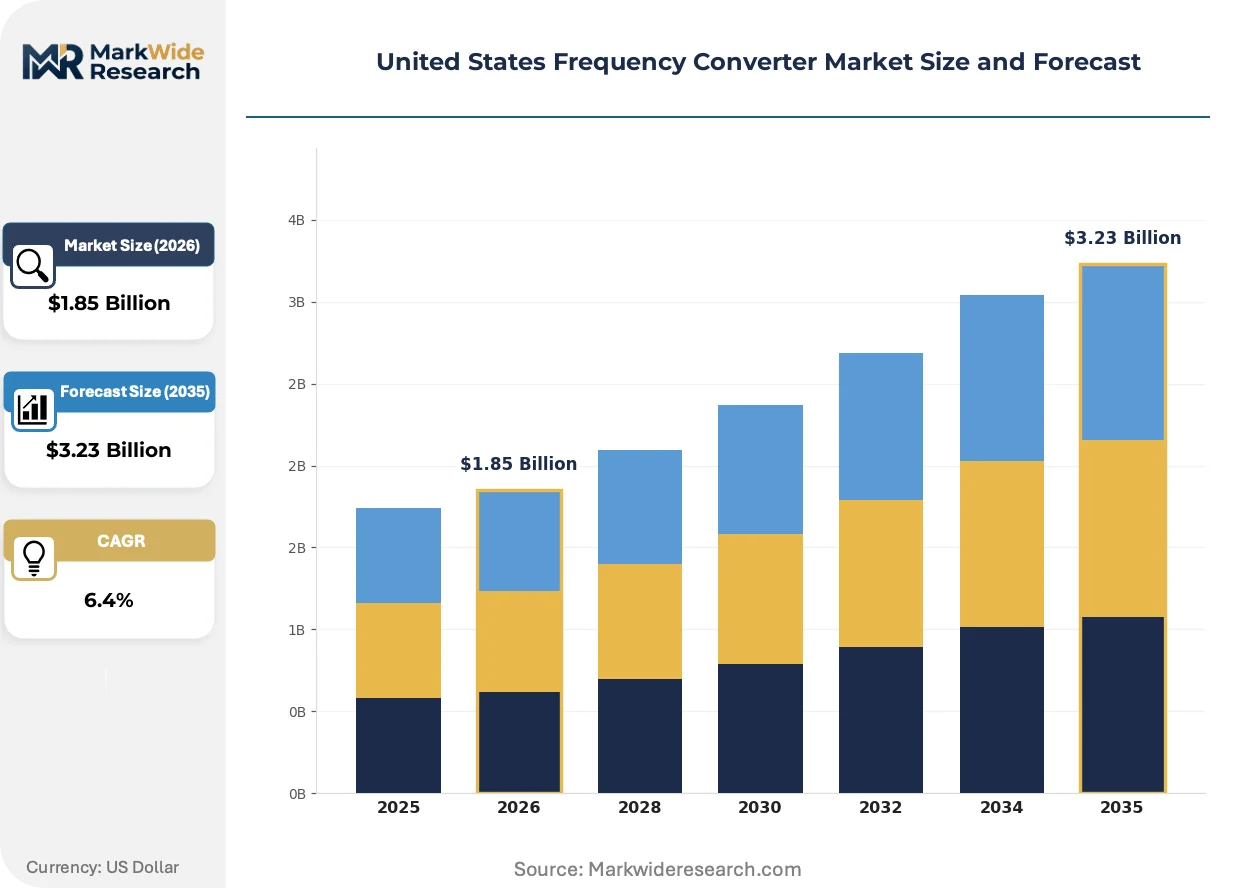
Market Dynamics
Silicon carbide power modules are compressing switching losses below IGBT thresholds, forcing converter manufacturers to redesign thermal management architectures and recertify platforms under FAA electromagnetic compatibility protocols.
Growth Catalysts
- Industrial automation corridors:Texas, California, and Michigan manufacturing clusters are synchronizing variable-frequency motor drives with grid interconnection requirements, expanding converter procurement across automotive test-rig and precision-machining installations.
- NHTSA electromagnetic compatibility tightening:Automotive OEMs must validate power electronics under stricter radiated-emission thresholds, compelling tier-one suppliers to upgrade frequency-converter specifications for dynamometer and battery-cycling equipment.
- Aviation ground support electrification:Solid-state 400 Hz converters are replacing rotary units at major commercial hubs, driven by jet-bridge retrofit mandates and reduced maintenance intervals for solid-state architectures.
Market Restraints
- Domestic foundry concentration:Silicon carbide wafer fabrication capacity concentrates in North Carolina and New York facilities, exposing converter OEMs to single-source disruption risks for high-voltage switching modules.
- FAA dual-certification burden:Airborne converter platforms require parallel validation under 14 CFR Part 25 and RTCA DO-160G, extending product-development timelines and freezing out suppliers without U.S. testing infrastructure.
- Legacy rotary converter persistence:Defense installations at Norfolk and San Diego naval bases maintain electromagnetic-isolation requirements that static converters cannot satisfy, fragmenting procurement volumes across incompatible technologies.
Strategic Opportunities
- Renewable energy storage integration:Grid-forming inverters in Texas and California solar-plus-storage projects require bidirectional frequency conversion, opening multi-megawatt procurement channels for utility-scale power-electronics platforms.
- EPA efficiency pre-regulation positioning:Pending variable-frequency drive efficiency standards will cascade into converter specifications, rewarding early movers with pre-certified platforms before mandatory compliance windows.
- Marine electrification architectures:Pulse-width-modulation converters are penetrating Great Lakes shipping corridors and Gulf Coast offshore supply vessels, displacing mechanical reduction gears in hybrid propulsion retrofits.
Industry Challenges
- Power-electronics engineering scarcity:Converter manufacturers in Michigan and North Carolina report acute shortages of silicon carbide gate-driver specialists and thermal-simulation engineers, compressing R&D throughput.
- Legacy defense system integration:Rotary-to-static converter replacements at legacy military installations require electromagnetic-isolation emulation that static architectures struggle to replicate, extending qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Frequency Converter Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Converter, Rotary Converter, Modular Converter, Dual Converter End User: Telecommunications, Aerospace, Industrial Automation, Power Generation Technology: Phase Shifting, Pulse Width Modulation, Transformers, Cycloconverter Application: Rail Transportation, Renewable Energy, Military Equipment, Marine Systems |
| Companies Covered | ABB Ltd, Siemens AG, General Electric Company, Danfoss A/S, Eaton Corporation plc, Schneider Electric, NR Electric USA, Georator, AMETEK, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Frequency Converter Market Strategic Shifts & Innovations
Frequency converter development is converging on wide-bandgap semiconductors and modular thermal architectures, compressing form factors while expanding power-density thresholds for aviation and renewable applications.
Silicon carbide MOSFETs enable switching frequencies above 50 kHz with losses below 30% of comparable IGBT platforms. Aviation ground-support OEMs in California and Texas are adopting these devices for 400 Hz mobile power units. This transition is supplanting forced-air cooling with liquid-cooled cold-plate designs, reducing converter weight by 40% for aircraft tug and jet-bridge applications.
FAA certification under 14 CFR Part 25 is tightening electromagnetic-interference thresholds for airborne frequency converters, mandating enhanced filtering and shielding validation. Converter manufacturers must now submit expanded test matrices covering conducted and radiated susceptibility. Marine and rail segments in the Pacific Northwest and Gulf Coast are absorbing these compliance costs by consolidating procurement with suppliers holding pre-certified platforms.
Industrial automation buyers are unbundling after-sales service contracts from hardware procurement, shifting toward third-party maintenance networks and remote diagnostics subscriptions. This reconfiguration compresses converter OEM service margins while expanding software-recurring revenue pools. The pattern is most visible across Michigan automotive test-rig installations and Texas semiconductor-fabrication facilities.
United States Frequency Converter Market Segmentation
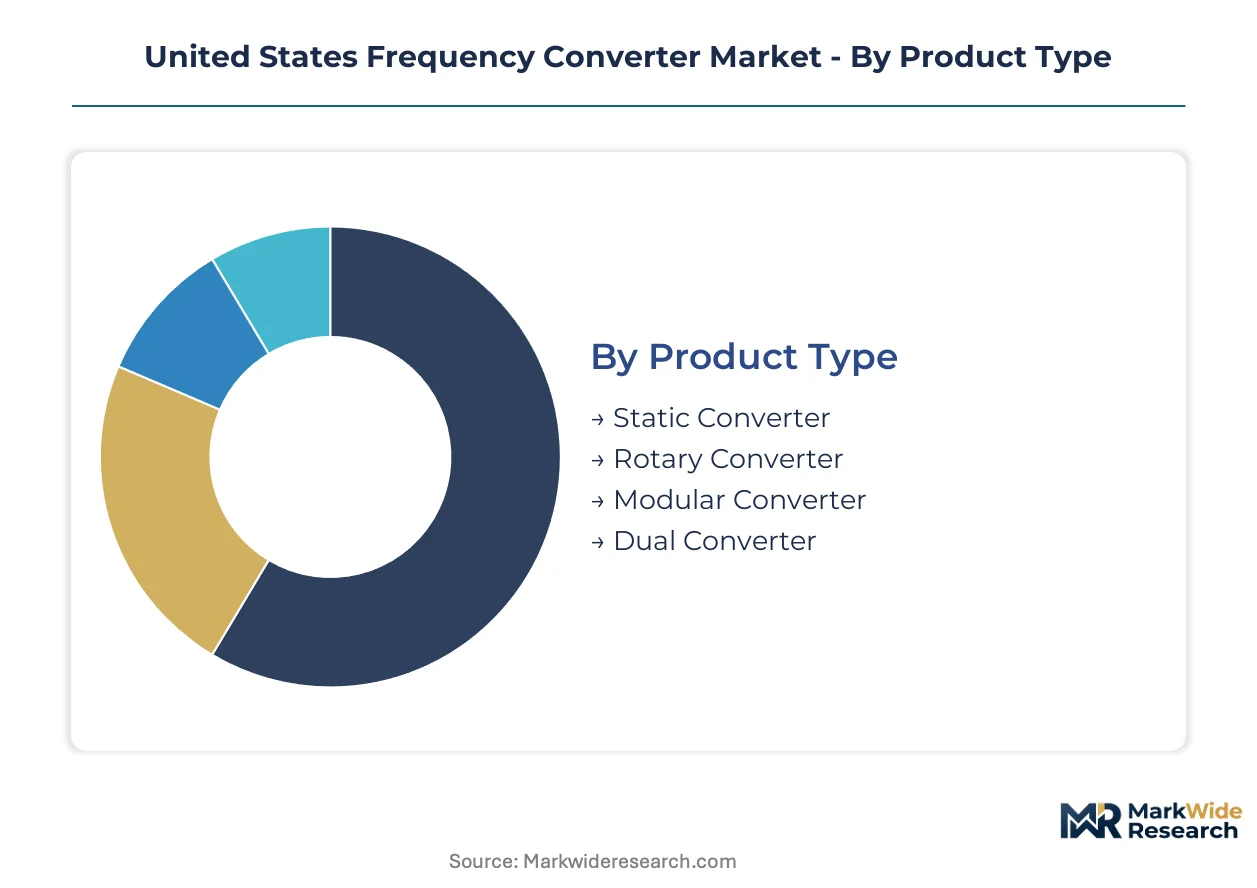
Segmentation in the United States frequency converter market reveals how substitution pressures and regulatory requirements reshape procurement patterns across power electronics verticals. Buyers prioritize semiconductor architecture, end-use certification burdens, and application-specific thermal constraints when selecting converter platforms.
Product Type:
Static converters face intensifying substitution pressure from modular architectures in industrial automation corridors, while rotary designs defend niche positions through electromagnetic isolation requirements that solid-state platforms cannot replicate.
- Static Converter:Silicon carbide MOSFETs enable switching frequencies above 50 kHz with losses below comparable IGBT thresholds. Texas and California manufacturing clusters are synchronizing these units with variable-frequency motor drives for automotive test-rig and precision-machining installations. FAA electromagnetic compatibility protocols under 14 CFR Part 25 mandate enhanced filtering validation for airborne deployments.
- Rotary Converter:Electromechanical designs maintain rotating mass for frequency transformation with inherent galvanic isolation. Defense installations at Norfolk and San Diego naval bases specify these units where electromagnetic isolation remains non-negotiable, fragmenting procurement volumes across incompatible technologies.
- Modular Converter:Scalable rack-mounted architectures allow capacity expansion without full system replacement.
- Dual Converter:Back-to-back rectifier-inverter configurations enable four-quadrant operation for regenerative loads.
Static converters anchor the volume base while modular converters gain share at the steepest rate.
End User:
Cost tier differentiation separates premium-certified aerospace procurement from price-sensitive industrial automation volumes, with telecommunications occupying a mid-tier position balancing reliability requirements against capital constraints.
- Industrial Automation:Variable-frequency drive synchronization demands dominate converter procurement across Michigan automotive corridors and Texas semiconductor fabrication facilities. NHTSA electromagnetic compatibility tightening compels tier-one suppliers to upgrade specifications for dynamometer and battery-cycling equipment.
- Aerospace:400 Hz ground support units require FAA certification under 14 CFR Part 25 with parallel RTCA DO-160G validation. Jet-bridge retrofit mandates at California and Texas commercial hubs are supplanting rotary units with solid-state architectures.
- Telecommunications:Precision power conditioning for data centers and cellular infrastructure prioritizes harmonic compliance.
- Power Generation:Grid-forming inverters in solar-plus-storage projects require bidirectional frequency conversion capabilities.
Industrial automation commands the largest procurement volumes while aerospace applications deliver the highest margin capture per unit.
Technology:
Application requirements dictate technology selection, with pulse width modulation penetrating renewable energy and rail transportation while cycloconverter architectures retain marine propulsion niches demanding high-torque low-speed operation.
- Pulse Width Modulation:High-frequency switching enables precise voltage control with reduced harmonic distortion. Great Lakes shipping corridors and Gulf Coast offshore supply vessels are adopting these converters for hybrid propulsion retrofits, displacing mechanical reduction gears.
- Cycloconverter:Direct AC-AC conversion without intermediate DC link supports high-torque marine propulsion systems. High-torque requirements in specialized vessel classes sustain demand despite silicon carbide displacement elsewhere.
- Phase Shifting:Multi-pulse rectification reduces harmonic injection into distribution networks.
- Transformers:Magnetic coupling provides galvanic isolation and voltage transformation for legacy installations.
Pulse width modulation dominates new installations while cycloconverter technology defends its marine niche through torque-density advantages.
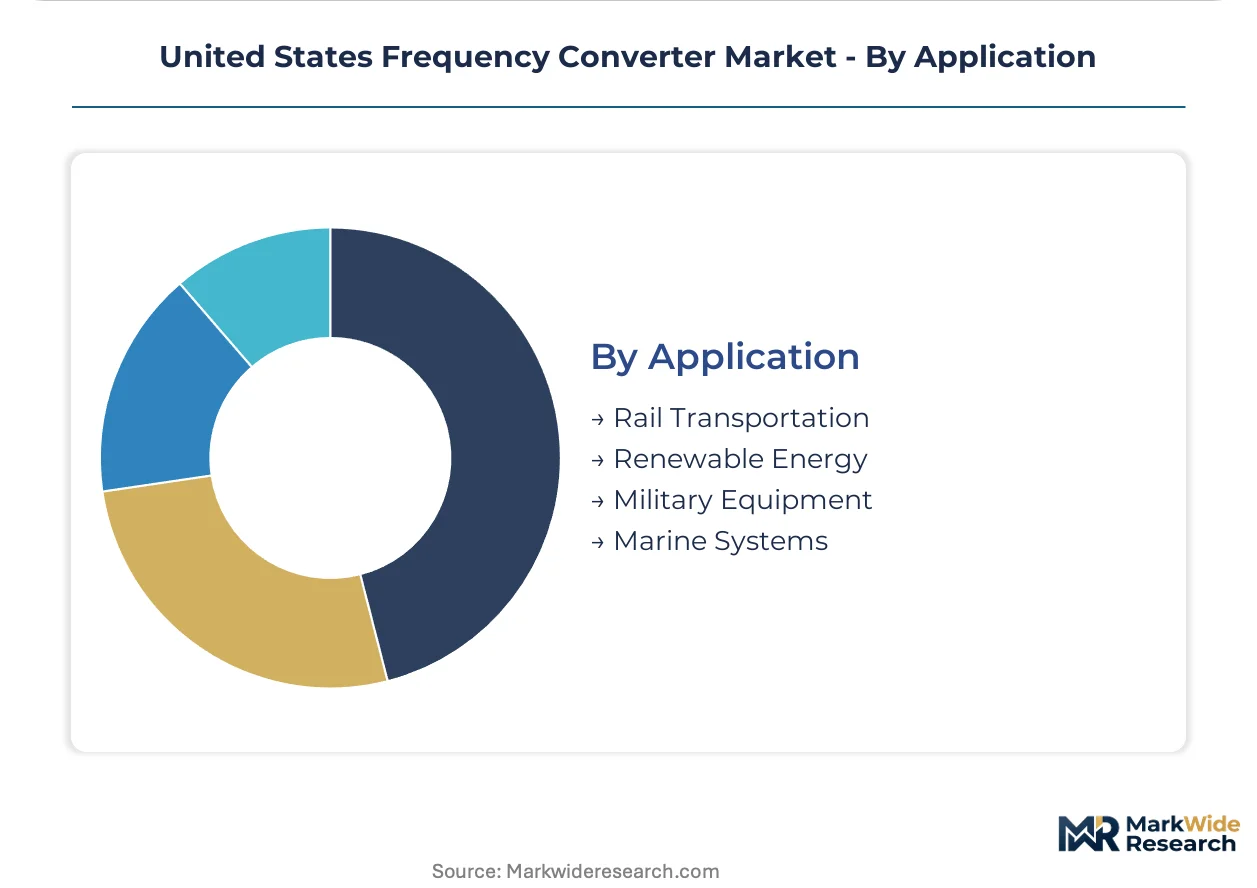
Application:
Geographic concentration patterns concentrate renewable energy procurement in Texas and California solar corridors, while military equipment demand fragments across defense installations with divergent electromagnetic isolation requirements.
- Renewable Energy:Grid-forming inverters in utility-scale solar-plus-storage projects require bidirectional frequency conversion. Texas and California procurement channels are opening for multi-megawatt power-electronics platforms as battery storage integration accelerates.
- Military Equipment:Legacy rotary-to-static replacement programs face electromagnetic-isolation emulation challenges. Static architectures struggle to replicate isolation properties at Norfolk and San Diego facilities, extending qualification timelines.
- Rail Transportation:Traction power systems require robust converters for regenerative braking energy recovery.
- Marine Systems:Hybrid propulsion electrification drives converter adoption in commercial shipping retrofits.
Renewable energy applications are expanding most quickly while military equipment maintains the most fragmented procurement structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across U.S. frequency converter demand centers. Industrial automation buyers in Michigan and Texas prioritize capital efficiency, while aerospace procurement in California accepts premium pricing for FAA-certified platforms.
Texas
Semiconductor fabrication facilities and oilfield equipment manufacturers drive converter procurement across the Austin-San Antonio corridor. ERCOT grid interconnection standards shape specifications for variable-frequency drive synchronization. Houston-area marine electrification projects are adopting pulse-width-modulation converters for hybrid offshore supply vessels.
California
Solar-plus-storage deployments in the Central Valley require bidirectional grid-forming inverters with multi-megawatt frequency conversion capability. CARB emissions regulations accelerate jet-bridge electrification at LAX and SFO, supplanting rotary 400 Hz units with solid-state architectures. Bay Area data centers prioritize harmonic-compliant precision power conditioning for telecommunications infrastructure.
Michigan
Automotive test-rig installations and battery-cycling equipment dominate converter demand across Detroit-Warren manufacturing clusters. NHTSA electromagnetic compatibility tightening compels tier-one suppliers to upgrade dynamometer specifications. Ann Arbor-area R&D centers report acute shortages of silicon carbide gate-driver specialists.
North Carolina
Silicon carbide wafer fabrication concentrates in Durham and Research Triangle Park facilities, exposing converter OEMs to single-source disruption risks for high-voltage switching modules. Marine converter R&D centers specialize in pulse-width-modulation architectures for Great Lakes shipping electrification. Charlotte-area rail transportation projects require regenerative braking energy recovery systems.
Washington State
Pacific Northwest marine electrification drives converter adoption across Seattle-Tacoma commercial shipping corridors. Boeing supplier networks demand FAA-certified airborne frequency converters with parallel RTCA DO-160G validation. Spokane-area defense contractors face electromagnetic-isolation emulation challenges in rotary-to-static replacement programs.
United States Frequency Converter Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the U.S. frequency converter market. Vertically integrated semiconductor fabricators capture margin in high-voltage industrial segments, while modular system assemblers compete on price for standardized automation applications. Three archetypes dominate: captive foundry operators, application-specialized engineering houses, and scale-driven component integrators. Competitive moves center on silicon carbide module backward integration and pre-certified platform development for EPA efficiency regulations.
Among European-headquartered industrial conglomerates, ABB Ltd and Siemens AG occupy positions reflecting captive semiconductor production capabilities. General Electric Company anchors the aerospace-qualified tier through retained manufacturing scale. These three exemplify how foundry-to-assembly control separates premium-tier suppliers from component-assembled competitors in FAA-regulated segments.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| General Electric Company |
| Danfoss A/S |
| Eaton Corporation plc |
| Schneider Electric |
| NR Electric USA |
| Georator |
| AMETEK, Inc. |
| Others |
Cost & Logistics Intelligence
Multi-megawatt converter foundry utilization at North Carolina and New York facilities anchors price floors across the U.S. market, compressing margins for component-assemblers while rewarding captive silicon carbide producers with pricing power in FAA-certified aerospace tiers.
Pricing Analysis
After-sales service contracts now drive lifetime value capture across industrial automation corridors. Three-tier pricing structure across premium, standard, and economy levels separates FAA-certified airborne platforms from automotive test-rig units and legacy rotary replacements. Cost compression in standard-tier static converters is intensifying because unbundled maintenance contracts shift revenue to third-party service networks. Automotive OEMs in Michigan exhibit the highest price sensitivity, while aerospace procurement in California accepts premium positioning for 14 CFR Part 25 validation.
Supply Chain Analysis
SiC wafer fabrication chokepoints at Durham and Research Triangle Park facilities tether converter OEMs to single-source disruption risks for high-voltage switching modules. Raw material dependencies span silicon carbide substrates, copper busbar assemblies, and aerospace-grade aluminum enclosures. Distribution runs through direct OEM relationships for certified platforms and distributor networks for standard industrial units. Tariff exposure on European IGBT modules compounds sourcing vulnerability for non-vertically integrated assemblers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: FAA dual-certification requirements under 14 CFR Part 25 and RTCA DO-160G erect structural barriers that freeze out suppliers lacking U.S. testing infrastructure.
For Market Incumbents: Consolidate backward integration into silicon carbide module production to defend margin capture against emerging fabless competitors. Expand pre-certified platform portfolios before EPA efficiency regulations cascade into converter specifications. Lock in long-term supply agreements with North Carolina foundries to neutralize single-source vulnerability. For New Entrants and Emerging Players: Differentiate on marine electrification architectures for Great Lakes shipping corridors, where pulse-width-modulation converter demand outruns incumbent R&D throughput. Target third-party maintenance network partnerships as the most penetrable channel, bypassing hardware procurement barriers through software-recurring revenue models. For Investors and Strategic Acquirers: Application-specialized engineering houses with marine and rail certification track records offer the strongest acquisition profile. Long-term viability hinges on silicon carbide gate-driver specialist scarcity resolving within the next decade. Watch EPA pre-regulation positioning as the inflection signal for platform consolidation windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Modules | Captive wafer supply from North Carolina foundries insulates margin capture against IGBT price volatility. |
| FAA Pre-Certification Investment | Parallel 14 CFR Part 25 and RTCA DO-160G validation accelerates jet-bridge electrification procurement at California hubs. |
| Marine Electrification R&D Center | Great Lakes shipping corridor specialization opens hybrid propulsion retrofit channels for pulse-width-modulation architectures. |
| Third-Party Maintenance Network Partnership | Unbundled service contracts shift revenue from hardware margins to recurring software diagnostics subscriptions. |
| EPA Efficiency Pre-Regulation Positioning | Pre-certified platforms capture procurement preference before variable-frequency drive standards cascade into converter specifications. |
Research Approach
A spread of perspectives from converter OEM product managers, FAA certification engineers, automotive test-rig procurement leads, and silicon carbide foundry operations directors converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC 10-K filings, FERC interconnection standards documentation, and IEEE electromagnetic compatibility databases. Bottom-up unit shipment estimates triangulated against top-down industrial automation capex flows.
Segmentation dimensions modeled span product type, end-user vertical, switching technology, and application geography across the projection horizon. CAGRs derived from installed base replacement cycles and renewable energy storage integration trajectories. Forecast inputs incorporated ERCOT grid interconnection standards and NHTSA electromagnetic compatibility tightening timelines.
The analysis sits within stated boundaries; outcomes outside FAA certification pathway stability or silicon carbide foundry capacity expansion would require recalibration. Forecasts reflect documented assumptions about EPA regulatory cascade timing and defense installation rotary-to-static replacement schedules. Practitioners should keep alternative scenarios live as electromagnetic isolation emulation technology and marine electrification subsidy programs evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Wire Splicing Kits Market
Electrical Equipment
Pad-Mounted Transformer Market
Electrical Equipment
North America Electrical Bushing Market
Electrical Equipment
High Voltage Circuit Breaker Market
Electrical Equipment
Portable Fan Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
Middle East and Africa Busbar Market
Electrical Equipment
High Voltage Electric Insulators Market
Electrical Equipment
Electrical Label Market
Electrical Equipment
Fiberglass Electrical Enclosure Market
Electrical Equipment
South America High Voltage Switchgear Market
Electrical Equipment
Vacuum Circuit Breaker Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
Soft Starter Market
Electrical Equipment
North America Thermal Protector Market