
 Continuous Inkjet Printers Market | 2026-2036
Continuous Inkjet Printers Market Size, Share, and Industry Trends Forecast 2026-2036
Continuous Inkjet Printers Market Outlook
Distributor networks for industrial marking equipment is fragmenting as OEMs build direct service arms and regional integrators capture mid-market accounts. Videojet Technologies leverages its North American service infrastructure to control high-volume food packaging accounts. Markem-Imaje anchors European pharmaceutical serialization contracts through its coding-software integration. Domino Printing Sciences competes in Asia-Pacific with localized ink formulation labs that reduce import lead times.
Continuous inkjet printers propel electrically charged droplets through a piezoelectric or electrostatic deflection field at velocities exceeding 50 meters per second, depositing alphanumeric codes, barcodes, and graphics onto porous and non-porous substrates without contact. These systems serve primary industrial functions of product traceability, regulatory compliance marking, and supply chain authentication across high-speed production environments. Standalone printers dominate capital expenditure budgets in retrofit-heavy facilities where legacy line integration limits embedded system deployment. High-speed printers capture the fastest expansion trajectory as beverage bottlers and pharmaceutical blister-pack lines push throughput beyond 100,000 units per hour. Integrated printers concentrate margin pools in greenfield packaging plants where total cost of ownership calculations favor single-vendor line responsibility.
FDA food labeling regulations and EPA volatile organic compound standards for solvent-based inks constrain formulation choices and equipment certification pathways in the United States. REACH chemical authorization procedures and CE machinery directives in Europe elevate compliance costs for ink suppliers and OEMs serving cross-border manufacturing clients. Stakeholders must monitor evolving serialization mandates in pharmaceutical supply chains and the displacement of solvent chemistries by UV-curable alternatives.
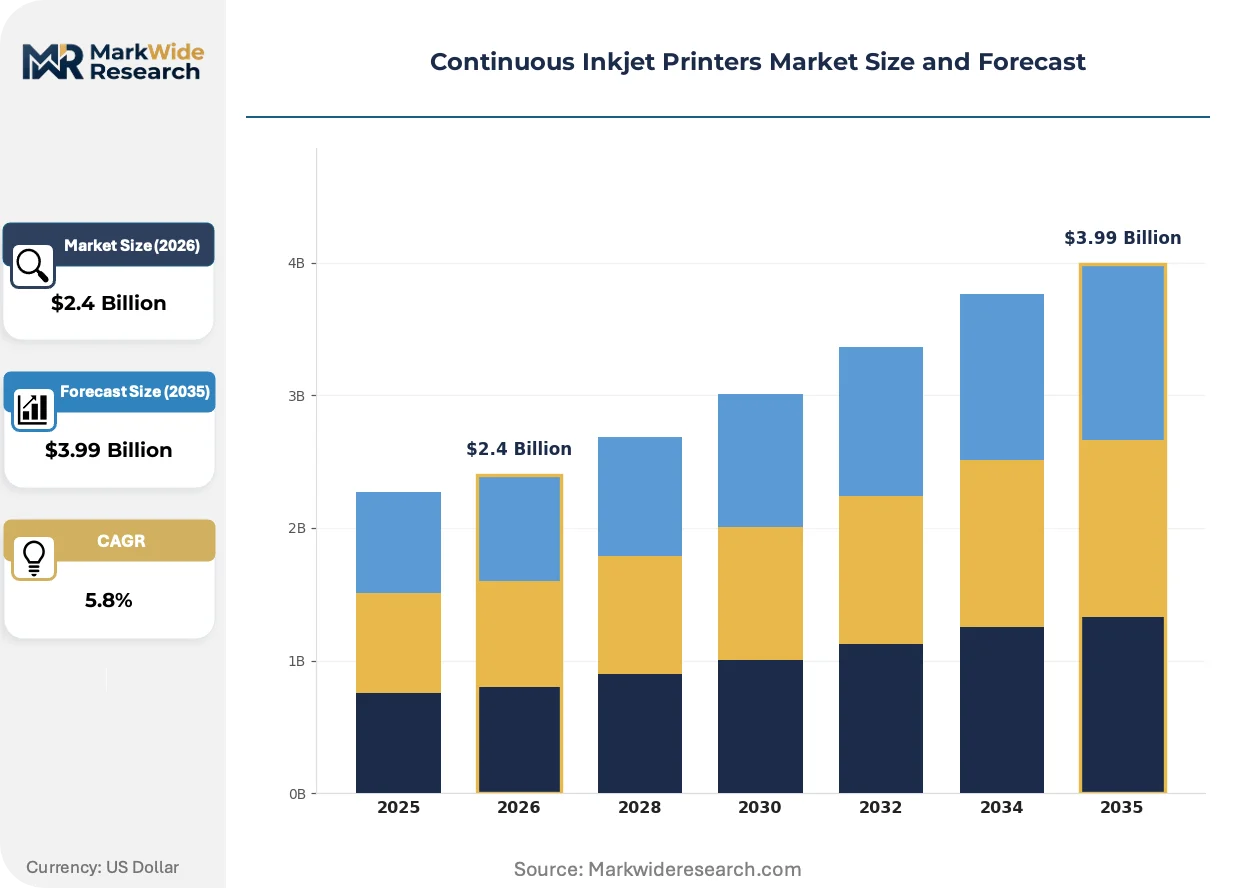
Market Dynamics
Pharmaceutical serialization mandates and food traceability regulations are compressing replacement cycles for legacy batch-coding equipment across high-volume packaging lines. Manufacturers face simultaneous pressure to upgrade throughput capabilities while reformulating inks to meet tightening chemical safety standards.
Growth Catalysts
- REACH chemical authorization:European ECHA procedures for solvent-based ink constituents are forcing equipment upgrades as older chemistries lose authorization, creating replacement demand across German automotive and French pharmaceutical packaging clusters.
- High-speed beverage bottling:Throughput requirements exceeding 100,000 units per hour on carbonated drink lines in Brazil and Mexico are pulling investment toward advanced continuous inkjet systems with sub-millisecond droplet control.
- UV-curable ink chemistry:Volatile organic compound elimination targets are accelerating displacement of MEK-based solvents, with new formulations enabling marking on previously incompatible polymer substrates.
Market Restraints
- Piezoelectric actuator supply concentration:Specialized ceramic component fabrication concentrates in Japanese and German supplier bases, exposing OEMs to lead-time volatility and single-source risk for high-frequency printhead modules.
- Solvent ink regulatory friction:EPA volatile organic compound standards and ECHA substance of very high concern listings are narrowing formulation options, extending certification timelines and constraining regional product availability.
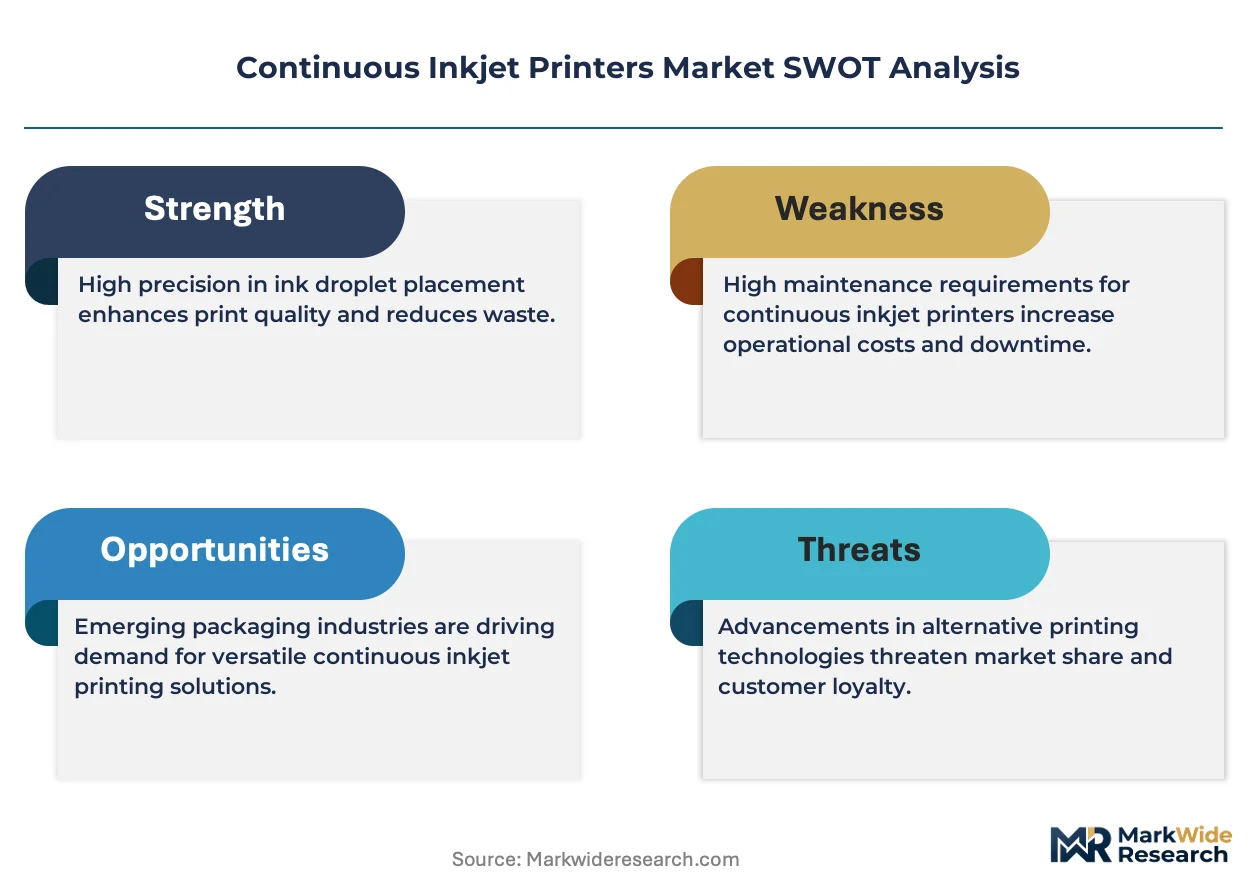
- Laser marking substitution:Fiber laser systems are capturing permanent-code applications in metal packaging and electronics where ink adhesion and abrasion resistance requirements exceed continuous inkjet capabilities.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO serialization mandates for export-bound drug packaging are creating first-time system adoption among mid-tier generic manufacturers in Hyderabad and Ahmedabad clusters.
- Industrial IoT convergence:Integration of continuous inkjet controllers with manufacturing execution systems and predictive maintenance platforms is enabling outcome-based service contracts and remote diagnostics revenue streams.
- Direct OEM service arms:Bypassing traditional distributor networks to capture aftermarket ink and spare parts margins represents channel restructuring opportunity in fragmented Southeast Asian markets.
Industry Challenges
- Electrohydrodynamic printhead calibration:Specialized technicians capable of servicing high-frequency piezoelectric systems are scarce in emerging manufacturing regions, constraining deployment velocity and elevating service costs.
- FDA 21 CFR Part 11 validation:Pharmaceutical serialization equipment requires extensive documentation and qualification protocols, extending sales-to-revenue cycles and demanding dedicated regulatory affairs resources.
- Legacy line integration complexity:Retrofit deployments in established food and beverage facilities must synchronize with existing programmable logic controller architectures, often requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Continuous Inkjet Printers Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Printers, Integrated Printers, Portable Printers, High-Speed Printers End User: Manufacturing, Packaging, Publishing, Textile Technology: Thermal Inkjet, Piezoelectric, Solvent-Based, UV-Curable Application: Labeling, Coding, Marking, Decorating |
| Companies Covered | Videojet Technologies, Markem-Imaje, Domino Printing Sciences, Hitachi Industrial Equipment Systems, Linx Printing Technologies, Leibinger Group, Squid Ink Manufacturing, Matthews Marking Systems, KGK Jet, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Continuous Inkjet Printers Market Strategic Shifts
Digital twin architectures and predictive maintenance algorithms are restructuring how continuous inkjet systems are specified, deployed, and monetized across industrial packaging operations. Equipment vendors are repositioning around software-enabled service models rather than hardware shipment economics.
Cloud-connected print management platforms are virtualizing traditional on-premise controller functions, enabling centralized job scheduling and real-time quality monitoring across distributed production networks. Beverage multinationals in North American and European bottling operations are piloting these architectures to consolidate oversight of hundreds of line-side marking stations. This shift is virtualizing the hardware-software boundary, compressing capital expenditure models toward subscription-based consumption.
EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are accelerating reformulation of solvent-based ink systems toward lower-global-warming-potential alternatives. Equipment OEMs serving cross-border manufacturing clients must now qualify multiple regional ink portfolios, elevating supply chain complexity. German automotive parts suppliers and Italian food packaging lines are experiencing the most acute certification bottlenecks as 2027 reduction targets approach.
Consolidated procurement functions at multinational CPG conglomerates are unbundling hardware acquisition from consumables and service contracts, reversing traditional bundled pricing structures. Category managers now negotiate separate agreements for capital equipment, aftermarket ink, and technical support across three-year horizons. This pattern is most pronounced in North American pharmaceutical and European dairy packaging verticals, where procurement centralization has compressed vendor margins and elevated importance of total cost of ownership documentation.
Continuous Inkjet Printers Market Segmentation
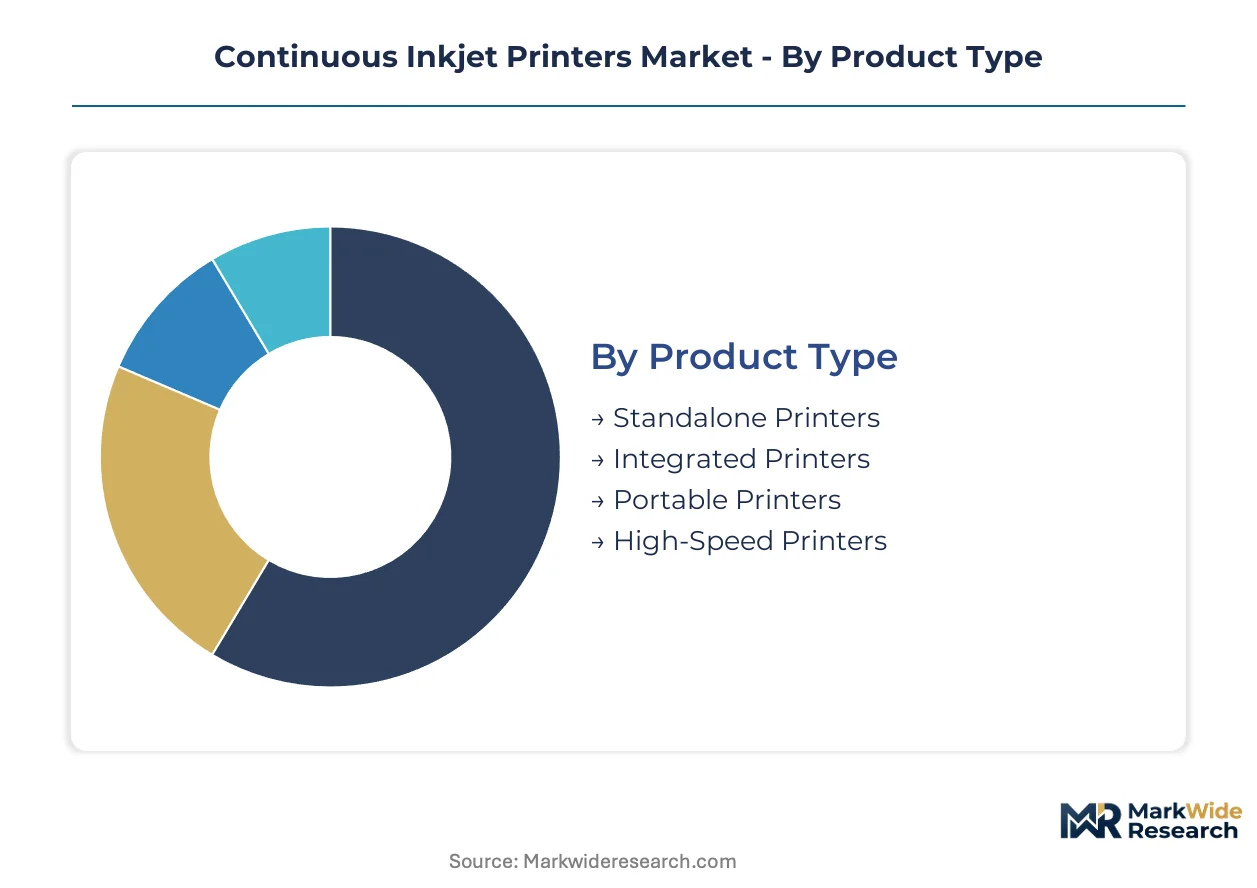
Continuous inkjet printer procurement patterns diverge sharply across installation contexts and throughput requirements. Equipment specification cycles vary from months for portable units to multi-year capital planning for integrated production lines.
Product Type:
Replacement velocity spans two orders of magnitude, with portable units turning over in under three years while integrated systems persist for fifteen years or more.
- Standalone Printers:Self-contained marking stations with dedicated controllers and ink delivery systems operate independently of host line architecture. Demand concentrates in retrofit-heavy North American food processing facilities where legacy programmable logic controller integration constraints prevent embedded deployment. FDA 21 CFR Part 11 validation requirements extend procurement timelines but lock in long-term aftermarket revenue for OEMs.
- High-Speed Printers:Sub-millisecond droplet control systems achieve velocities exceeding 50 meters per second for beverage bottling lines surpassing 100,000 units per hour. Brazilian and Mexican carbonated drink manufacturers are pulling investment toward these systems as throughput requirements compress replacement cycles to five-year intervals.
- Integrated Printers:Embedded marking modules designed for greenfield packaging plants where single-vendor line responsibility dominates total cost of ownership calculations.
- Portable Printers:Handheld or cart-mounted units for secondary coding, rework stations, and contract packaging operations with intermittent marking requirements.
Standalone printers dominate installed base. High-speed printers are where expansion concentrates.
End User:
Margin capture potential tracks regulatory burden intensity, with pharmaceutical-facing packaging commanding premium pricing over commodity manufacturing.
- Packaging:Primary and secondary packaging lines for food, beverage, pharmaceutical, and consumer goods applications constitute the core demand pool. German automotive parts suppliers and Italian food packaging clusters drive specification intensity as REACH chemical authorization procedures force ink reformulation and equipment recertification.
- Manufacturing:Direct part marking for electronics, automotive components, and industrial equipment requires specialized adhesion and abrasion resistance properties. Indian pharmaceutical export compliance mandates from CDSCO are creating first-time system adoption among mid-tier generic manufacturers in Hyderabad and Ahmedabad.
- Publishing:Variable data printing for direct mail, catalogs, and transactional documents with moderate speed requirements and high job change frequency.
- Textile:Fabric marking and garment coding applications with specialized ink chemistries for fiber compatibility and wash durability.
Packaging commands the deepest aftermarket revenue pools. Manufacturing is climbing the fastest as serialization mandates proliferate.
Technology:
Formulation chemistry determines regional market access, with solvent-based systems facing authorization erosion while UV-curable alternatives expand substrate compatibility.
- UV-Curable:Photoinitiator-activated inks polymerize instantly under ultraviolet exposure, eliminating volatile organic compound emissions and enabling marking on previously incompatible polymer substrates. EU F-Gas Regulation phase-down schedules for hydrofluorocarbon propellants are accelerating displacement of traditional solvent systems in German automotive and French pharmaceutical packaging operations.
- Piezoelectric:Ceramic actuator-driven droplet ejection achieves precise control at frequencies exceeding 100 kilohertz for high-resolution alphanumeric and barcode marking. Japanese and German supplier concentration for specialized ceramic components exposes OEMs to lead-time volatility and single-source risk.
- Solvent-Based:MEK and ethanol-based formulations with established adhesion profiles on porous substrates face narrowing authorization under EPA volatile organic compound standards and ECHA substance of very high concern listings.
- Thermal Inkjet:Resistive heating element bubble-jet technology for lower-speed applications with disposable printhead economics and minimal maintenance requirements.
Piezoelectric systems anchor high-value installed base. UV-curable is gaining share fastest as environmental compliance tightens.
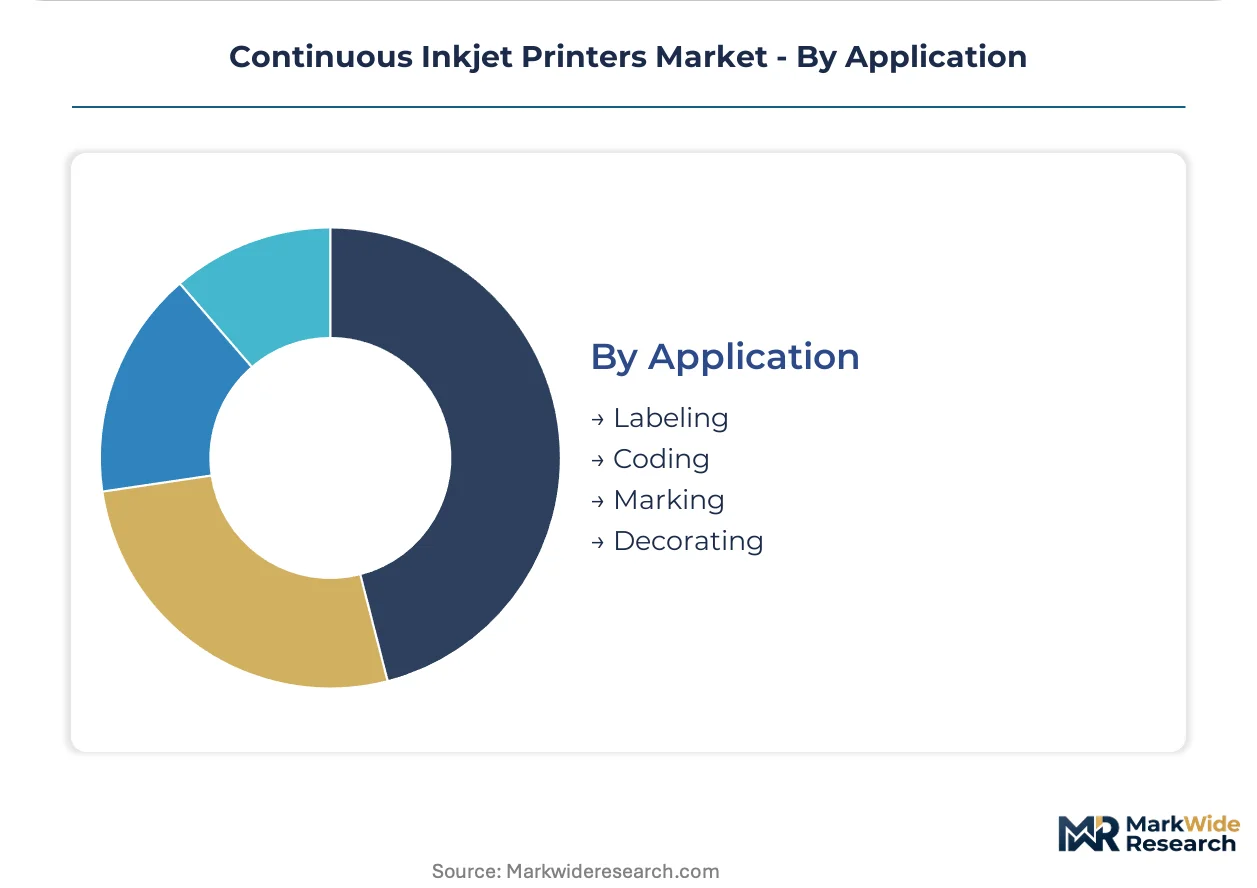
Application:
Functional specification intensity escalates from decorative surface enhancement to legally mandated traceability encoding.
- Coding:Alphanumeric batch numbers, lot codes, expiration dates, and serialized identifiers for regulatory compliance and supply chain traceability. Pharmaceutical serialization mandates in the United States and Europe are compressing replacement cycles for legacy batch-coding equipment.
- Marking:Permanent or semi-permanent identification for asset tracking, quality control, and anti-counterfeiting applications. Fiber laser substitution pressure is strongest here for metal packaging and electronics where abrasion resistance requirements exceed inkjet capabilities.
- Labeling:Variable information printing on adhesive labels and tags for secondary packaging and logistics applications.
- Decorating:Aesthetic surface enhancement with graphics, patterns, and brand elements on consumer-facing packaging.
Coding generates the highest service attach rates. Marking faces the steepest technology substitution threat.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany's industrial corridor while Brazilian beverage bottlers operate on compressed margins. Equipment specification intensity tracks regulatory burden rather than manufacturing scale.
United States
FDA 21 CFR Part 11 validation requirements and EPA volatile organic compound standards drive specification complexity. Pharmaceutical serialization mandates from the FDA compress replacement cycles for legacy batch-coding equipment. New Jersey and Illinois packaging clusters absorb premium pricing for compliant systems.
Germany
Automotive and pharmaceutical packaging clusters anchor European demand for high-throughput marking systems. REACH chemical authorization procedures through ECHA force ink reformulation and equipment recertification. Baden-Württemberg suppliers face acute certification bottlenecks as 2027 F-Gas reduction targets approach.
Brazil
Carbonated drink lines exceeding 100,000 units per hour pull investment toward sub-millisecond droplet control systems. ANVISA traceability regulations reshape equipment specifications for export-bound food packaging. São Paulo state bottling operations compress replacement cycles to five-year intervals.
India
CDSCO serialization mandates for pharmaceutical exports create first-time system adoption among generic manufacturers. Hyderabad and Ahmedabad clusters upgrade from legacy batch-coding equipment to meet compliance deadlines. Domestic ink formulation capabilities remain underdeveloped, extending import lead times.
Japan
Piezoelectric actuator fabrication concentrates in specialized ceramic component suppliers, exposing OEMs to lead-time volatility. METI industrial standards shape equipment certification pathways for domestic packaging lines. Nagoya automotive parts suppliers integrate marking systems with existing programmable logic controller architectures.
Continuous Inkjet Printers Market Competitive Environment
Integrated-system specialists and standalone-equipment fabricators split the market along greenfield versus retrofit deployment lines. Three strategic archetypes dominate: North American service-anchored players, European coding-software integrators, and Asia-Pacific ink-formulation laboratories. Competitive moves concentrate on direct service arm construction and regional distributor network bypass.
Among diversified marking-equipment conglomerates, Videojet Technologies exemplifies the service-infrastructure archetype through its North American footprint. Markem-Imaje occupies a position within the European pharmaceutical serialization tier. Domino Printing Sciences represents the Asia-Pacific localization model with formulation capabilities that reduce cross-border supply dependencies.
| Leading Market Players |
|---|
| Videojet Technologies |
| Markem-Imaje |
| Domino Printing Sciences |
| Hitachi Industrial Equipment Systems |
| Linx Printing Technologies |
| Leibinger Group |
| Squid Ink Manufacturing |
| Matthews Marking Systems |
| KGK Jet |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese piezoelectric ceramic fabrication drives supplier prioritization toward high-volume OEM contracts and compresses pricing flexibility for mid-tier equipment buyers across European packaging clusters. This utilization squeeze elevates configured-to-order premiums while forcing buyers toward longer-term offtake commitments to secure printhead module allocation.
Pricing Analysis
The customization-premium spread separates standard standalone printers from configured-to-order integrated systems by certification tier and line-integration complexity. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 21 CFR Part 11 validation status, CE machinery directive compliance, and aftermarket service bundling. Cost compression in the economy tier is intensifying because Indian and Southeast Asian contract packaging buyers are consolidating procurement functions and unbundling hardware from consumables contracts. Pharmaceutical serialization accounts show least price sensitivity due to regulatory non-negotiability, while Brazilian beverage bottlers operate on compressed margins and five-year replacement cycles.
Supply Chain Analysis
Extended payment terms from German automotive packaging clusters and supply-chain finance facilities anchored by Japanese component suppliers are restructuring working capital flows across the printhead module tier. Manufacturing concentration centers on Japan for piezoelectric ceramics, Germany for precision fluid handling systems, and China for controller electronics assembly. Raw material dependencies include lead zirconate titanate ceramics, stainless steel precision tubing, and UV photoinitiator chemicals. Single-source vulnerability for high-frequency actuator modules exposes OEMs to lead-time volatility when Nagoya-area fabrication runs at capacity. Distribution runs through regional integrator networks in Southeast Asia and direct service arms in North America and Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized technicians capable of calibrating electrohydrodynamic printheads at sub-millisecond frequencies represent the critical capability gap constraining deployment velocity in emerging manufacturing regions. This scarcity elevates service attach rates and compresses margin capture for equipment vendors lacking trained field organizations.
For Market Incumbents: Harden defensive positioning by backward integration into piezoelectric ceramic fabrication to reduce Nagoya supplier dependency, and anchor European pharmaceutical accounts through preemptive REACH-compliant ink portfolio certification. Fiber laser substitution pressure in metal packaging demands accelerated UV-curable formulation R&D to recover abrasion-resistance performance gaps.
For New Entrants and Emerging Players: Indian pharmaceutical export compliance creates first-time system adoption among mid-tier generic manufacturers in Hyderabad and Ahmedabad clusters with limited incumbent service presence. Target cloud-connected print management platform partnerships with North American beverage multinationals piloting centralized job scheduling architectures. Pursue outcome-based service contracts with predictive maintenance algorithms as the primary go-to-market wedge.
For Investors and Strategic Acquirers: Long-term, this sits as a consumables-anchored recurring revenue play because pharmaceutical serialization mandates and REACH chemical authorization procedures compress replacement cycles and lock in aftermarket ink demand. Acquisition target archetype: regional ink formulation laboratories with localized certification capabilities that reduce cross-border supply dependencies. Watch for CDSCO mandate acceleration in Indian pharmaceutical exports as the inflection signal indicating compliance-driven replacement cycle compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Piezoelectric Ceramics | Reduces single-source exposure to Nagoya fabrication capacity constraints for high-frequency printhead modules. |
| UV-Curable Ink Portfolio Expansion | Captures displacement demand as EU F-Gas Regulation phase-down schedules force solvent system obsolescence. |
| Cloud-Connected Print Management Platform | Enables subscription-based consumption models with North American beverage multinationals consolidating distributed line oversight. |
| Direct Service Arm Construction | Bypasses fragmented Southeast Asian distributor networks to capture aftermarket ink and spare parts margins. |
| REACH-Compliant Certification Prepositioning | Locks in European pharmaceutical serialization contracts before ECHA substance authorization procedures narrow formulation options. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with equipment OEM product managers, aftermarket service directors, plant engineers at packaging line operations, and ink formulation chemists; and secondary validation against SEC filings from diversified marking-equipment conglomerates, ECHA substance authorization databases, FDA 21 CFR Part 11 guidance documents, and trade customs records for piezoelectric component flows. Bottom-up equipment shipment estimates triangulated against top-down packaging line investment surveys across beverage, pharmaceutical, and automotive verticals.
Forecast inputs considered product type segmentation across standalone, high-speed, integrated, and portable printer configurations; technology tiering across piezoelectric, UV-curable, solvent-based, and thermal inkjet systems; and application intensity across coding, marking, labeling, and decorating use cases. CAGRs were derived from regression analysis of historical replacement cycle compression against regulatory mandate implementation timelines, with specific weighting for pharmaceutical serialization compliance deadlines and F-Gas Regulation phase-down schedules.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by Japanese component suppliers or accelerated cloud-platform consolidation by North American beverage multinationals would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printers
A3 and A4 Multi-Function Printer Market
Printers
Direct-To-Shape Inkjet Printers Market
Printers
Production Printer Market
Printers
Printer Ribbons Market
Printers
NCR Printers Market
Printers
Ink Tank Printer Market
Printers
Global Inkjet Coders Market
Printers
Global Thermal Inkjet Print-Heads Market
Printers
Portable Printer Market
Printers
Laser Printer Market
Printers
Inkjet Printing Market
Printers
Nanographic Printing Market
Printers
Mobile Photo Printer Market
Printers
Single Function Printer Market
Printers
Global UV LED Printers Market
Printers
Photocopiers Market