
 Global Excitation Systems Market | 2026-2036
Global Excitation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Excitation Systems Market Intelligence
IEC 60034 qualification for rotating electrical machines is redrawing competitive boundaries in excitation systems. ABB leverages its integrated power electronics portfolio to anchor large hydro and thermal installations across Scandinavia and Latin America. Siemens Energy sustains technology leadership in digital excitation platforms through its microprocessor-based control architectures. Basler Electric Company specializes in protective relay integration, occupying a defensible niche among North American independent power producers.
Excitation systems are electromechanical assemblies that regulate generator output voltage by controlling DC field current, typically operating at field voltages between 125 V and 750 V with response times under 500 milliseconds for grid stability events. Their primary purpose is maintaining synchronous machine terminal voltage and reactive power balance across interconnected power networks. Brushless excitation dominates installed base economics due to reduced maintenance intervals, while digital control platforms represent the fastest-expanding technology segment as utilities phase out analog voltage regulators. Thyristor-controlled systems retain margin strength in retrofit markets where existing rotating equipment demands compatible upgrade paths.
The Federal Energy Regulatory Commission in the United States enforces grid interconnection standards that mandate specific excitation system response characteristics for generators above 20 MVA. EMA and national regulators across Europe apply CE marking and MDR-adjacent reliability requirements to excitation components packaged with rotating machinery. China's National Energy Administration and GB standards bodies impose localized electromagnetic compatibility testing that shapes market access protocols for imported excitation controllers. Stakeholders must monitor evolving grid codes in high-growth power markets to align product roadmaps with region-specific transient stability requirements.
Market Dynamics
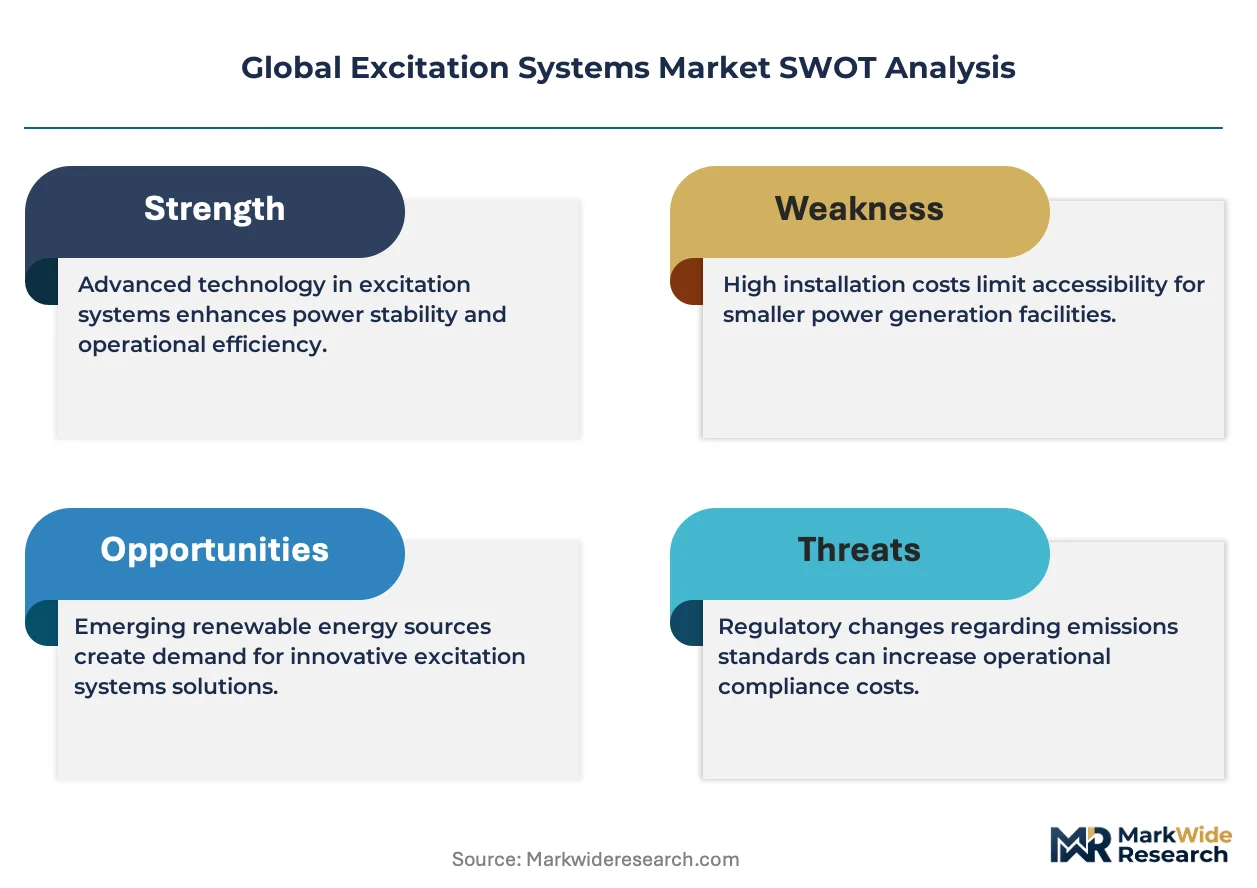
The excitation systems market faces structural pressure from IEC 60034 and IEEE 421 compliance tightening, which elongates product qualification cycles and forces suppliers to redesign control architectures for synchronous machine compatibility across interconnected grids.
Growth Catalysts
- Grid Code Harmonization:FERC interconnection standards in the United States mandate specific excitation response characteristics for generators above 20 MVA, compelling fleet upgrades and controller replacements across aging thermal installations.
- Renewable Penetration:Southeast Asian power generation plants deploy excitation systems to stabilize grid frequency amid variable solar and wind output, creating sustained demand for fast-response digital voltage regulators.
- Brushless Technology Maturation:Reduced maintenance intervals and elimination of slip-ring assemblies drive replacement cycles in hydroelectric and thermal baseload facilities seeking operational expenditure compression.
Market Restraints
- Input Cost Volatility:Power semiconductor prices for thyristor and IGBT modules fluctuate with rare earth processing constraints in China, compressing margin structures for controller manufacturers.
- Supply Concentration Risk:Precision wound magnetic components and high-voltage capacitors concentrate among Japanese and German specialty suppliers, exposing procurement timelines to single-source vulnerabilities.
- Technical Limitation:Analog voltage regulator obsolescence creates stranded asset risk for utilities with limited capital budgets, slowing upgrade adoption despite digital platform superiority.
Strategic Opportunities
- Brazilian Capacity Expansion:Hydroelectric and thermal additions in Brazil create demand for excitation systems compatible with local grid codes and electromagnetic compatibility requirements under national energy administration protocols.
- Digital-Twin Convergence:Integration of real-time excitation control with predictive maintenance platforms enables utilities to unbundle after-sales service contracts and capture recurring revenue streams.
- India PLI Tailwind:Production-linked incentive schemes for power equipment domestic manufacturing reduce landed cost disadvantages for imported controller assemblies, opening local assembly opportunities.
Industry Challenges
- Specialized Firmware Talent Scarcity:Microprocessor-based excitation control requires embedded systems engineers with power electronics and grid stability expertise, a skill combination concentrated among aging workforces in OECD markets.
- Legacy Integration Complexity:Retrofit projects demand backward compatibility with existing rotating exciter machinery, extending engineering timelines and requiring custom interface development for each installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Excitation Systems Market |
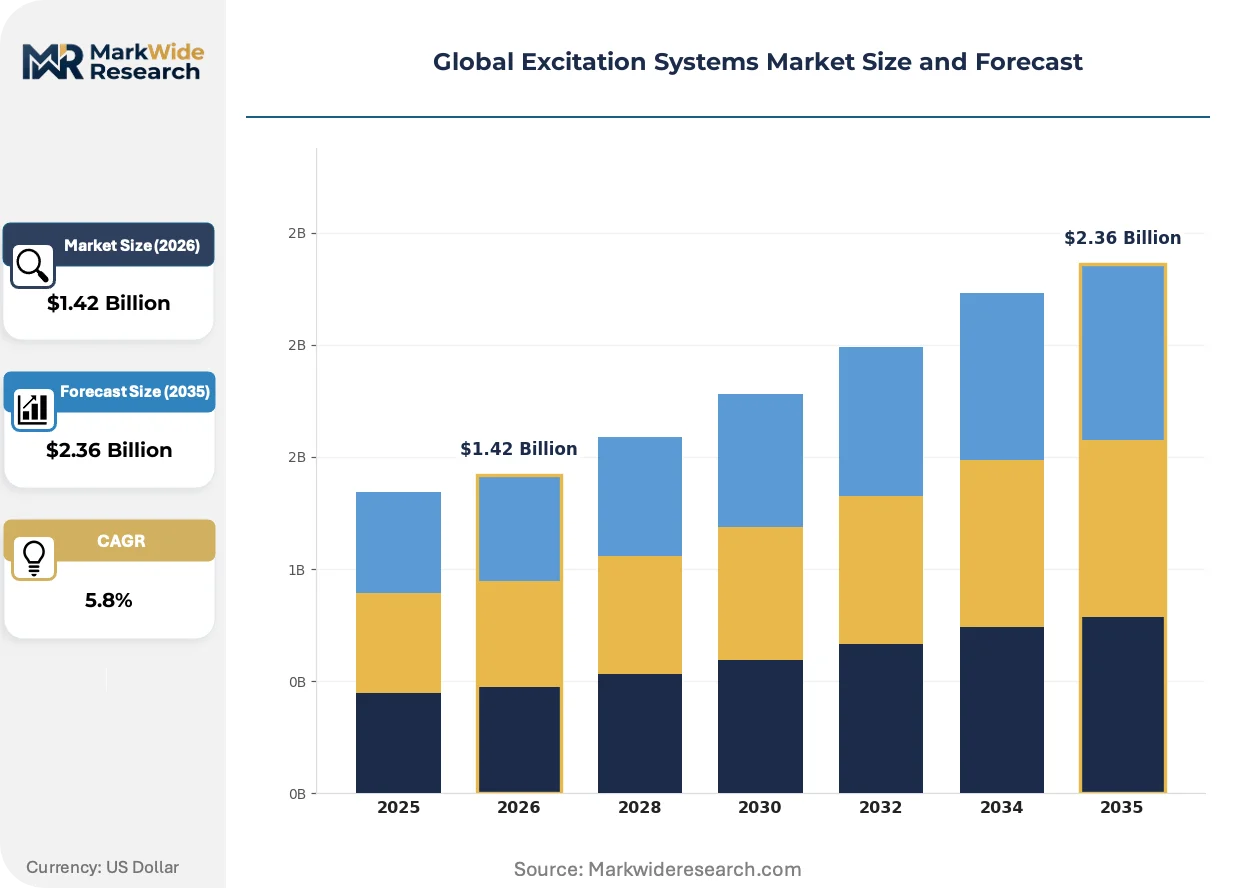
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Brushless, Static, Rotating, Permanent Magnet, Compound Technology: Analog, Digital, Hybrid, Microprocessor-Based, Thyristor-Controlled Application: Power Generation Plants, Renewable Energy Systems, Marine Vessels, Railways, Mining Operations End User: Independent Power Producers, Transmission Companies, OEMs, Utility Operators, Industrial Manufacturers |
| Companies Covered | ABB, Siemens Energy, General Electric, ANDRITZ Group, Mitsubishi Electric Corporation, Emerson, Voith Group, Nidec Corporation, Basler Electric Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Excitation Systems Market Strategic Shifts & Innovations
Digital control architectures are actively displacing analog voltage regulators across utility-scale installations, while regulatory pressure on grid stability and electromagnetic compatibility accelerates product redesign cycles. Three developments dominate competitive positioning.
Model-predictive control algorithms are decomposing traditional PID-based voltage regulation into multi-variable optimization frameworks. European grid operators and Nordic hydroelectric utilities adopt these platforms for their sub-100 millisecond response capabilities. The technology is compressing commissioning timelines and reducing field calibration labor.
China's National Energy Administration and GB standards bodies impose localized electromagnetic compatibility testing protocols that reshape market access requirements. Imported excitation controllers face additional certification layers beyond IEC baselines. Suppliers are responding with regional product variants and in-country testing partnerships.
After-sales service unbundling accelerates as independent power producers separate hardware procurement from long-term maintenance agreements. North American merchant generators and Brazilian concessionaires lead this transition, favoring suppliers with modular spare parts programs and remote diagnostic capabilities over traditional bundled offerings.
Global Excitation Systems Market Segmentation
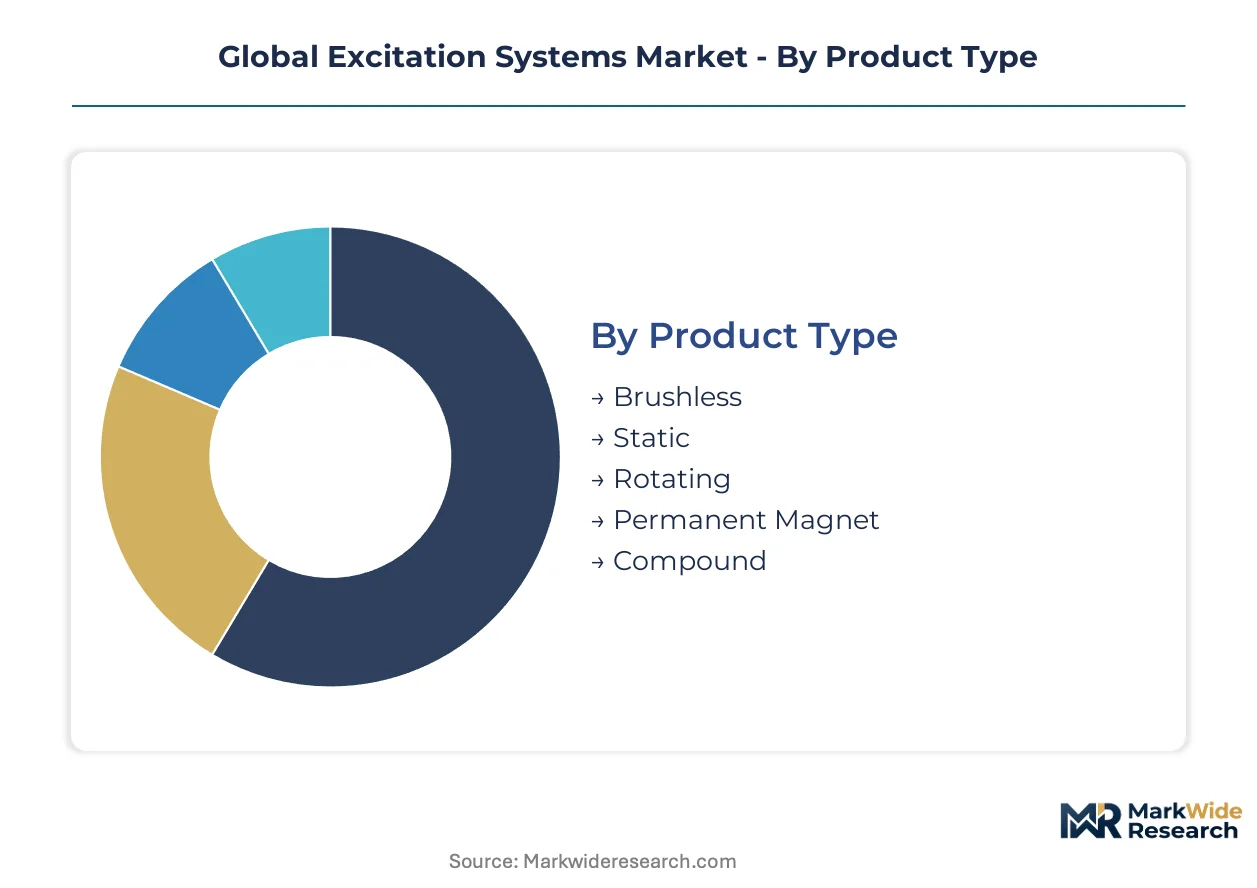
Excitation system architectures diverge sharply across voltage ratings, control philosophies, and duty cycles. Procurement patterns split between utilities seeking lifecycle cost compression and industrial operators prioritizing rapid commissioning.
Product Type:
Brushless systems dominate export flows to Southeast Asian hydroelectric installations, while static configurations serve domestic retrofit markets in North America and Europe.
- Brushless:Elimination of slip-ring assemblies reduces maintenance intervals from quarterly to annual cycles. Demand concentrates in Brazilian and Chinese hydroelectric basins where remote site access elevates reliability premiums.
- Static:Thyristor-based field forcing delivers sub-200 millisecond response for grid stability events. Independent power producers in Texas and California specify these for gas turbine installations under FERC interconnection mandates.
- Rotating:Traditional DC exciter architecture persists in legacy thermal fleets across India and Russia.
- Permanent Magnet:Compact footprint suits offshore wind turbine nacelles with severe space constraints.
- Compound:Self-excited design eliminates external power source dependency for isolated industrial applications.
Brushless holds the largest share; momentum sits with static systems as grid codes tighten response requirements.
Technology:
Cost tiers separate mature analog platforms from digital architectures commanding 40-60% price premiums for embedded diagnostics.
- Digital:Multi-variable optimization frameworks replace PID control loops. Nordic utilities and German transmission operators deploy these for predictive grid stability management.
- Microprocessor-Based:Modular firmware architecture enables remote parameter updates without site visits. Merchant generators in PJM and ERCOT territories favor this flexibility for capacity market participation.
- Analog:Obsolescent voltage regulator designs strand capital in developing markets with constrained replacement budgets.
- Hybrid:Analog signal conditioning with digital supervisory layers bridges legacy and modern control paradigms.
- Thyristor-Controlled:Phase-controlled rectification retains cost advantage in high-current thermal generator retrofits.
Digital platforms command the revenue concentration; microprocessor-based systems are expanding most quickly among independent power producers.
Application:
Volume concentrates in baseload thermal and hydroelectric installations, while margin accrues to specialized marine and railway specifications.
- Power Generation Plants:Synchronous machine voltage regulation across 50 MVA to 1,000 MVA units. Chinese and Indian state-owned utilities drive procurement for coal and hydro capacity additions.
- Renewable Energy Systems:Grid-forming inverters and synchronous condensers require excitation support for weak grid penetration. Southeast Asian solar-wind hybrid projects in Vietnam and Thailand specify fast-response digital controllers.
- Marine Vessels:Classification society rules from Lloyd's Register and DNV govern shock and vibration tolerance for propulsion generators.
- Railways:Traction power substations demand high-availability excitation for 25 kV overhead electrification systems.
- Mining Operations:Isolated grid operation at remote sites favors brushless reliability in Australian and Chilean copper extraction zones.
Power generation plants hold the largest share; renewable energy systems gain share fastest as variable generation penetration deepens.
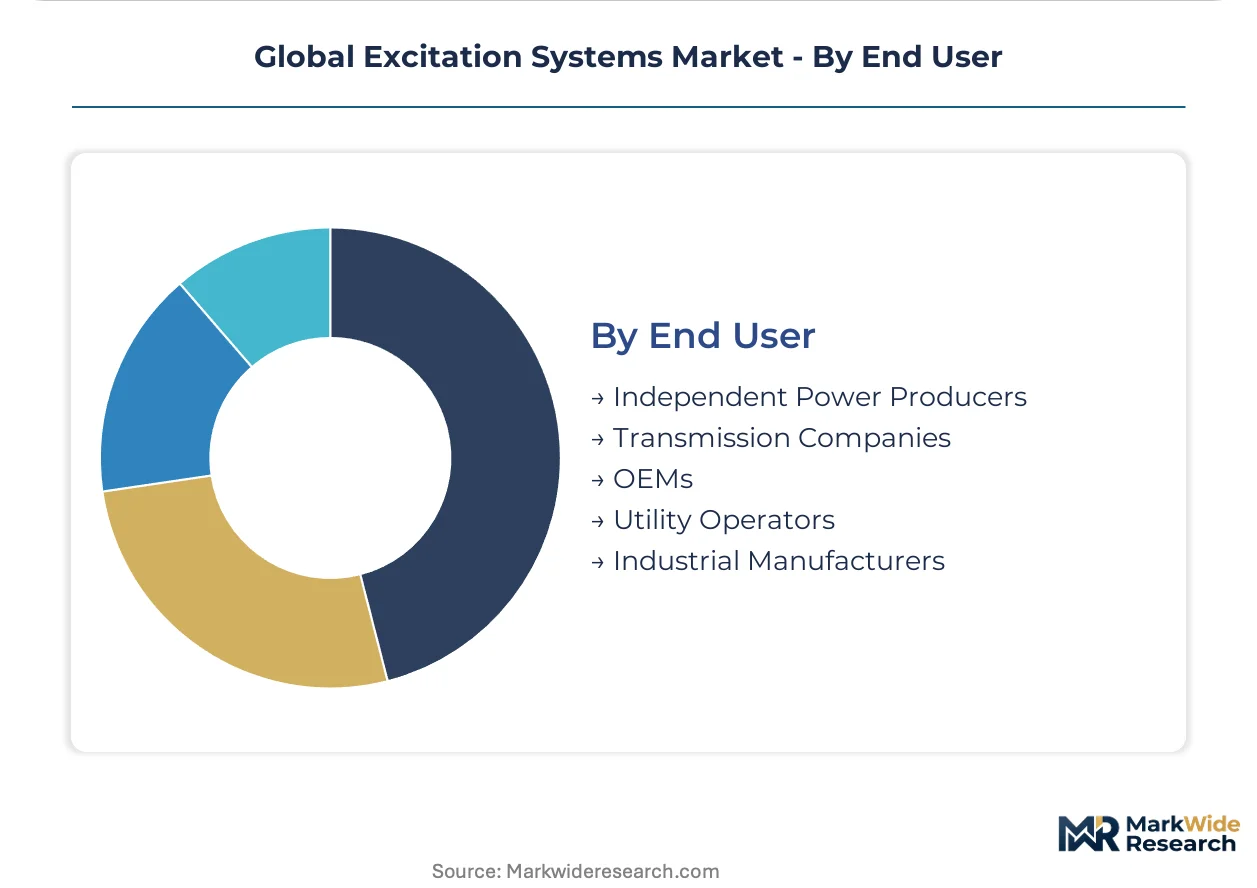
End User:
Customer type determines procurement modality: utilities favor long-term service contracts while industrial manufacturers prioritize capital expenditure minimization.
- Utility Operators:Vertically integrated grid companies in France, Japan, and South Korea standardize on manufacturer-agnostic digital platforms for fleet interoperability.
- Independent Power Producers:Merchant generators separate hardware procurement from aftermarket service, favoring suppliers with modular spare parts logistics.
- Transmission Companies:Grid stability obligations drive synchronous condenser installations in Germany and Texas for reactive power compensation.
- OEMs:Generator original equipment manufacturers bundle excitation systems with rotating machinery for turnkey project delivery.
- Industrial Manufacturers:Cement, steel, and chemical captive power plants prioritize minimum commissioning disruption over technical sophistication.
Utility operators hold the largest share; independent power producers show the steepest expansion trajectory as generation unbundling advances.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Utility operators and independent power producers in China, India, Brazil, Germany, and the United States account for the majority of procurement volume. Each market exhibits distinct regulatory drivers and infrastructure investment patterns that shape excitation system specifications.
China
State-owned utilities drive demand for hydroelectric and thermal capacity additions along the Yangtze River basin. The National Energy Administration enforces GB standards for electromagnetic compatibility testing on imported controllers. Manufacturing clusters in Shanghai and Jiangsu province produce domestic excitation components for grid-scale synchronous machines.
India
Coal and hydroelectric expansion under the Central Electricity Authority's grid stability mandates sustains procurement from state generation companies. Production-linked incentive schemes reduce landed cost disadvantages for imported controller assemblies. Industrial corridors in Gujarat and Tamil Nadu host local assembly operations for power electronics.
Brazil
Hydroelectric concessions in the Amazon and Paraná basins require excitation systems compatible with national grid codes. ANEEL, the national electric energy regulator, mandates specific transient response characteristics for generators above 50 MVA. Equipment suppliers concentrate technical support capabilities in São Paulo and Belo Horizonte.
Germany
Transmission system operators deploy synchronous condensers for reactive power compensation under European network codes. EMA-adjacent reliability requirements and CE marking shape product qualification timelines. Engineering clusters in Bavaria and North Rhine-Westphalia specialize in digital control platform integration.
United States
FERC interconnection standards compel fleet upgrades across aging thermal installations in Texas and California. Merchant generators in PJM and ERCOT territories favor modular firmware architectures for capacity market participation. Independent power producers separate hardware procurement from aftermarket service contracts.
Global Excitation Systems Market Key Industry Players
Player mix skews toward diversified industrial conglomerates with integrated power electronics portfolios, creating a tiered structure where technology breadth determines competitive position. Strategic archetypes include full-spectrum system integrators, specialized protective relay manufacturers, and regional component assemblers. Consolidation pressures intensify as digital platform development costs rise and utilities standardize on manufacturer-agnostic architectures. Dominant competitive moves encompass strategic partnerships for localized certification support and portfolio diversification into predictive maintenance software.
Among European-based industrial groups, ABB and Siemens Energy occupy positions as full-spectrum system integrators with technology leadership in digital excitation platforms. Basler Electric Company represents the specialized protective relay tier, anchoring a defensible niche among North American independent power producers. These three entities exemplify how competitive positioning stratifies across integrated versus focused business models.
| Leading Market Players |
|---|
| ABB |
| Siemens Energy |
| General Electric |
| ANDRITZ Group |
| Mitsubishi Electric Corporation |
| Emerson |
| Voith Group |
| Nidec Corporation |
| Basler Electric Company |
| Others |
Cost & Logistics Intelligence
Long-term capacity reservation contracts with power generation utilities lock in semiconductor module supply and establish price visibility across multi-year commissioning cycles. These arrangements tether controller manufacturers to fixed pricing schedules indexed to rare earth processing costs while insulating procurement timelines from spot market volatility in thyristor and IGBT sourcing.
Pricing Analysis
Cost-plus contracts with rare earth indexation dominate procurement frameworks for thyristor and IGBT modules. Three-tier pricing structure across premium, standard, and economy levels separates IEC 60034-certified digital platforms from analog retrofit configurations and basic static exciter assemblies. Price differentiation hinges on certification grade and after-sales service bundling. Pricing pressure stems from power semiconductor cost compression in Chinese processing facilities. Industrial captive power plants exhibit highest price sensitivity; Nordic transmission operators show lowest sensitivity due to grid stability mandates.
Supply Chain Analysis
China and Japan anchor power semiconductor fabrication for thyristor and IGBT modules deployed in excitation controllers. German and Japanese specialty suppliers concentrate precision wound magnetic components and high-voltage capacitors. Raw material dependencies include rare earth elements, silicon carbide substrates, and copper winding stock. Single-source vulnerability concentrates in Japanese ceramic capacitor production. Distribution runs through OEM bundling agreements with generator manufacturers and direct utility procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Excitation systems sit in early-cycle expansion as digital control architectures displace analog voltage regulators across utility-scale installations. Grid code harmonization in high-growth power markets sustains penetration tailwinds for fast-response platforms.
For Market Incumbents: Secure firmware talent pools through embedded systems engineering partnerships with Nordic technical universities. Deepen backward integration into power semiconductor sourcing to mitigate rare earth price volatility exposure from Chinese processing concentration. Anchor fleet interoperability contracts with vertically integrated European utilities to defend against manufacturer-agnostic platform standardization. For New Entrants and Emerging Players: ANEEL certification fast-track for Brazilian hydroelectric concessions opens accessible entry pathways against entrenched European suppliers. Target Indian state generation companies under PLI scheme localization requirements where landed cost disadvantages for imported assemblies are compressing. Pursue digital-twin integration partnerships with North American independent power producers unbundling aftermarket service contracts. For Investors and Strategic Acquirers: Regional component assemblers with in-country electromagnetic compatibility testing capabilities present consolidation targets as certification barriers rise. Long-term viability centers on recurring revenue capture through predictive maintenance software rather than hardware shipment cycles. Monitor FERC interconnection standard enforcement intensity as inflection indicator for North American retrofit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Control Platform Migration | Utilities in Germany and Texas phase out analog voltage regulators under tightened grid codes. |
| Regional Certification Partnerships | Chinese GB standards testing collaborations reduce market access friction for imported controllers. |
| Predictive Maintenance Software Integration | North American merchant generators unbundle hardware procurement from long-term service agreements. |
| Power Semiconductor Backward Integration | Controller manufacturers secure thyristor supply chains against rare earth processing volatility. |
| PLI Scheme Local Assembly | Indian industrial corridors host domestic power electronics assembly for state utility procurement. |
Research Approach
Operator-level perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from FERC filings, IEA reports, EIA data, and project development databases. Bottom-up installation tracking across generation capacity tiers triangulated with top-down equipment spend estimates from national energy administration disclosures.
Sensitivity analysis tested forecast robustness across renewable penetration scenarios and grid code implementation timelines. The projection framework modeled segmentation across excitation system type, control technology, application, and end-user category throughout the forecast period. CAGRs derived from capacity addition pipelines and replacement cycle analysis for aging thermal installations. Industry-specific inputs included synchronous condenser deployment schedules and electromagnetic compatibility certification timelines.
Decision-makers should treat outputs as directional under stable rare earth processing capacity and sustained grid code enforcement; material deviation in semiconductor supply constraints or regulatory implementation delays would warrant model refresh. Recalibration cycles align with material shifts in renewable penetration rates and national energy administration procurement policy revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Organic Fixed Power Capacitors Sales Market
Power Systems
Middle East and Africa Low Voltage Drives Market
Power Systems
Thermoelectric Coolers Market
Power Systems
PV Inverter Market
Power Systems
Telecom Battery Market
Power Systems
Ultrafast Rectifiers Market
Power Systems
Battery Cyclers Market
Power Systems
Medium Voltage Drives Market
Power Systems
Global Power Discrete and Modules Market
Power Systems
Bypass Thyristor Market
Power Systems
Power Amplifier Modules Market
Power Systems
Thermoelectric Generator (TEG) Market
Power Systems
Battery Charge Controller Market
Power Systems
Vehicle Inverter Market
Power Systems
Global Inverter Market
Power Systems
PV Micro Inverters Market