
 Solid State Transformer Market | 2026-2036
Solid State Transformer Market Size, Share, and Industry Trends Forecast 2026-2036
Solid State Transformer Market Analysis
Silicon carbide power semiconductor integration is fragmenting traditional transformer architectures into distributed, software-controlled converter systems. Schneider Electric leverages its grid automation portfolio to anchor European utility deployments. Hitachi ABB Power Grids sustains technology leadership through high-voltage direct-current tie-ins with solid-state transformer interfaces. General Electric competes on military and aerospace ruggedization programs that demand compact power conversion.
A solid-state transformer employs power electronic converters—typically voltage source or hybrid converter topologies—combined with high-frequency isolation stages to replace conventional copper-and-iron electromagnetic transformers, enabling bidirectional power flow and real-time voltage regulation for grid modernization. Integrated product configurations capture premium margins in utility-scale renewable integration, while modular designs dominate microgrid and commercial EV charging deployments where scalability and field serviceability matter. Power electronic converter subsystems represent the fastest-expanding segment as silicon carbide device costs decline and thermal management architectures improve.
The US Department of Energy and FERC shape demand through grid resilience mandates and interconnection standards that favor bidirectional, fault-tolerant transformer technologies. In Europe, the EU Green Deal and F-Gas Regulation accelerate replacement of oil-filled distribution transformers with dry-type solid-state alternatives that eliminate SF6 and mineral oil. China MIIT promotes domestic silicon carbide supply chains through GB standards alignment, tightening market access for non-compliant foreign converter systems. Stakeholders must monitor raw material concentration in silicon carbide substrates and wafer processing capacity as the decisive supply constraint.
Market Dynamics
Silicon carbide substrate concentration in Wolfspeed's North Carolina facilities and II-VI's Pennsylvania operations is constraining converter module output, forcing transformer OEMs into multi-year supply commitments that reshape procurement calendars and design roadmaps.
Growth Catalysts
- EU Green Deal decarbonization mandates:The F-Gas Regulation and SF6 phase-out directives compel German, French, and Italian utilities to replace oil-filled distribution transformers with dry-type solid-state alternatives, accelerating tender volumes for bidirectional converter systems.
- Silicon carbide trench MOSFET commercialization:Device manufacturers are shipping 650V-1.7kV SiC switches with 40% lower switching losses than IGBT equivalents, enabling 50kHz isolation stages that shrink magnetic component volume by an order of magnitude.
- Electric vehicle fast-charging infrastructure buildouts:China's State Grid and private operators are deploying 350kW+ charging hubs that require compact, bidirectional solid-state transformers to manage grid interconnection and vehicle-to-grid power flows.
Market Restraints
- Silicon carbide wafer supply concentration:Over 80% of conductive SiC substrates originate from US and Japanese crystal growth facilities, creating geographic single-source risk for European and Chinese converter system integrators.
- High-frequency magnetic material cost volatility:Nanocrystalline alloy and ferrite core prices fluctuate with rare earth element markets, compressing margins on isolation stage subassemblies that constitute 25-35% of bill-of-materials costs.
- Conventional transformer substitution persistence:Amorphous metal core distribution transformers from Hitachi Metals and transformer manufacturers in India offer 70-80% efficiency at one-third the capital cost, delaying solid-state adoption in price-sensitive emerging markets.
Strategic Opportunities
- India renewable integration white space:The country's Central Electricity Authority mandates smart grid readiness for all new substations above 33kV, creating demand for solid-state transformers with embedded power quality management that incumbent oil-filled suppliers cannot fulfill.
- Marine vessel electrification:Classification societies DNV and Lloyd's Register are drafting rules for all-electric propulsion in offshore support vessels, opening a specification channel for compact, liquid-cooled solid-state transformers that replace heavy conventional units.
- US Inflation Reduction Act manufacturing incentives:Domestic content bonuses for grid infrastructure projects are pulling converter assembly toward Michigan, Texas, and South Carolina facilities, rewarding early localization commitments with 10-year offtake visibility.
Industry Challenges
- Power electronics-utility engineering skill gap:Solid-state transformer deployment requires specialists fluent in both high-voltage grid protection and embedded converter control, a hybrid profile scarce in traditional transformer service organizations.
- Grid code certification timelines:IEEE 1547-2018 and regional interconnection standards demand 12-18 month validation cycles for fault-ride-through and anti-islanding behavior, delaying revenue recognition for new product variants.
- Legacy asset integration complexity:Bidirectional power flow capabilities conflict with existing protection relay settings and sectionalizer logic, forcing costly engineering studies for each retrofit installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid State Transformer Market |
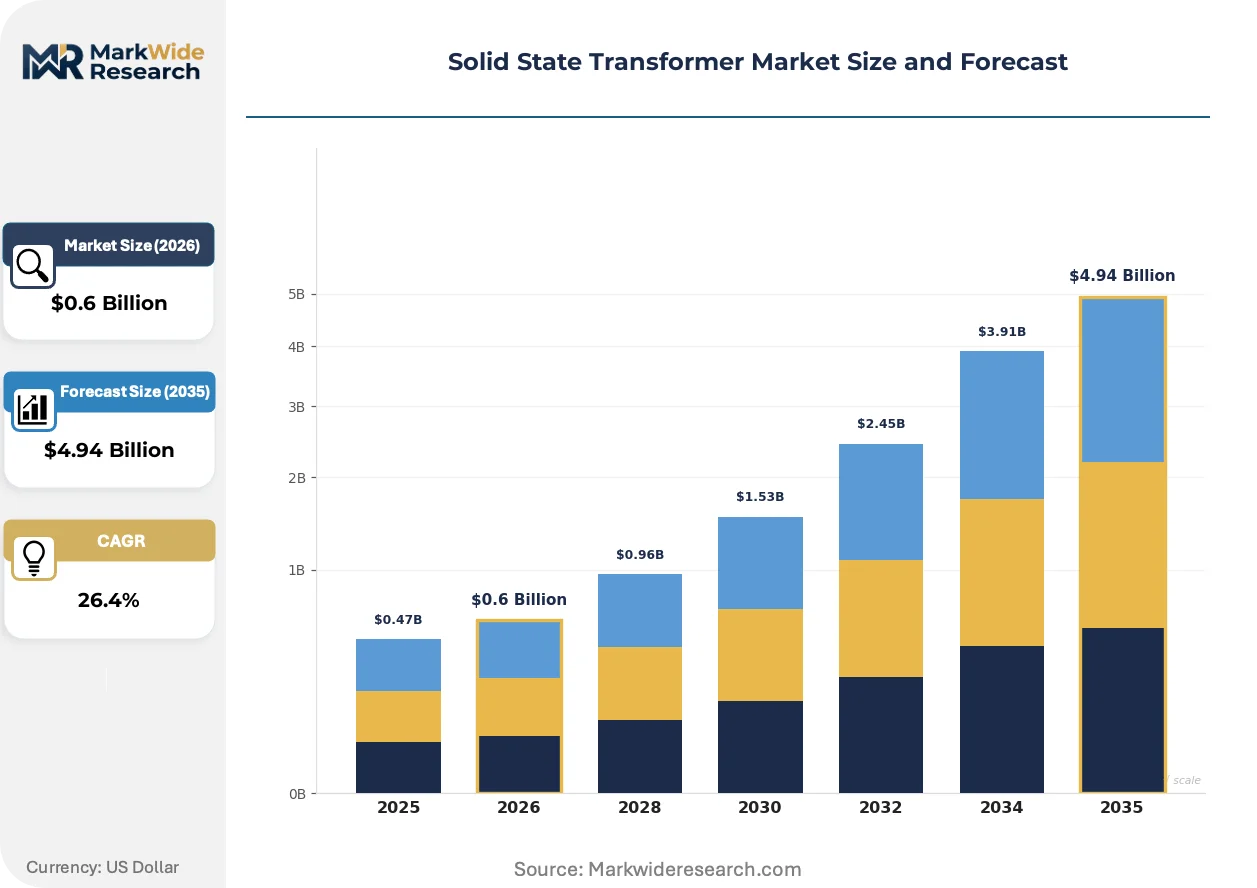
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $4.94 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular, Integrated, Power Electronic Converter, Transformer Module Application: Renewable Integration, Electric Vehicle Charging, Microgrid, Grid Management End User: Utilities, Industrial, Commercial, Residential Technology: Voltage Source Converter, Current Source Converter, Hybrid Converter, Software-Controlled Converter |
| Companies Covered | Schneider Electric, Hitachi ABB Power Grids, General Electric, Alstom, Mitsubishi Electric, Siemens, Eaton, SPX Transformer Solutions, ABB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid State Transformer Market Emerging Trajectories
Converter topology innovation is compressing the functional boundary between power electronic transformers and grid-forming inverters, collapsing historical product category distinctions and rewiring competitive positioning across the value chain.
Silicon carbide power modules with integrated temperature sensing and gate driver protection are collapsing the thermal management overhead that previously limited solid-state transformer power density. Data center operators in Northern Virginia and Frankfurt are specifying these integrated modules for 10MVA-class installations, reducing cooling infrastructure footprint by 60% compared to silicon IGBT alternatives. The structural consequence is collapsing price premiums for high-density converter systems as module costs follow semiconductor learning curves rather than copper commodity cycles.
The EU F-Gas Regulation's 2030 phase-down targets for sulfur hexafluoride are forcing transmission operators in Germany, Spain, and Poland to accelerate procurement of SF6-free switching and transformation equipment. Solid-state transformer suppliers are positioning their dry-type, vacuum-interrupter designs as compliant drop-in replacements for gas-insulated substations. Distribution grid planners in Bavaria and Lombardy are now requiring SF6-free technology in all new tender specifications, redirecting capital from conventional GIS suppliers toward power electronic alternatives.
Utility procurement departments are unbundling transformer supply from 20-year service contracts, compressing vendor selection criteria toward lifecycle cost modeling and modular upgrade paths. European distribution system operators in the Netherlands and Denmark are piloting power-as-a-service arrangements where solid-state transformer providers retain asset ownership and guarantee availability metrics. This model is displacing capital purchase frameworks in municipal utilities with constrained balance sheets, particularly in German states with aggressive renewable connection queues.
Solid State Transformer Market Segmentation
Solid-state transformer architectures fragment across competing design philosophies, each optimizing for distinct grid interconnection scenarios. Segmentation reveals how silicon carbide device economics and thermal management requirements reshape procurement patterns across utility, industrial, and mobility infrastructure deployments.
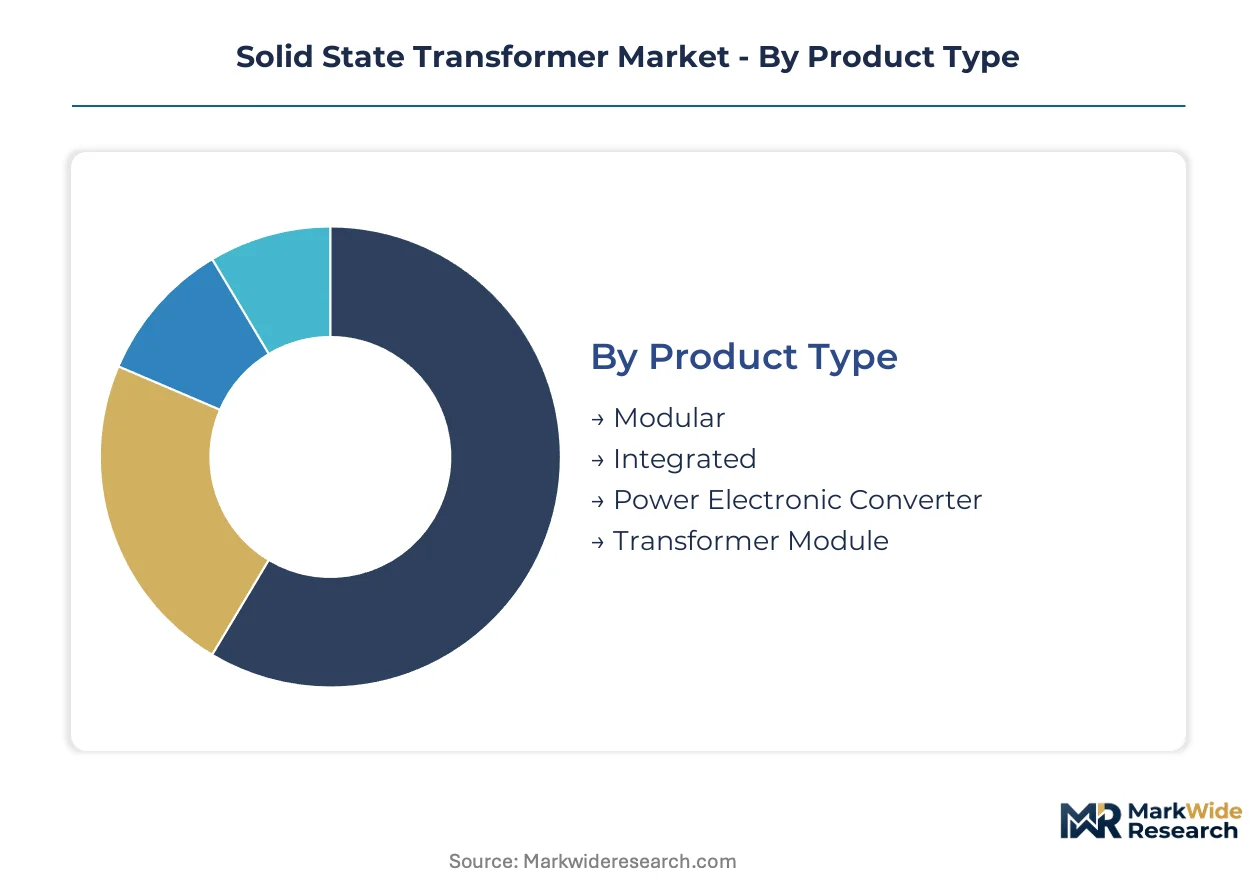
Product Type:
Cost tier differentiation separates field-serviceable modular units from capital-intensive integrated systems purpose-built for utility-scale renewable hubs.
- Modular:Field-replaceable converter blocks enable incremental capacity scaling and reduced mean-time-to-repair for commercial EV charging operators. Demand concentrates in China's private charging networks where 350kW hub deployment schedules favor pay-as-you-grow procurement models over front-loaded integrated investments.
- Integrated:Factory-sealed systems with embedded isolation stages and liquid cooling loops target utility-scale solar and offshore wind interconnections. German transmission operators in Bavaria specify these configurations for SF6-free substation retrofits where space constraints and reliability guarantees outweigh premium capital costs.
- Power Electronic Converter:Standalone converter subsystems without magnetic isolation capture mid-market microgrid and industrial power quality applications.
- Transformer Module:Discrete high-frequency isolation stages sold separately to system integrators assembling custom solid-state transformer architectures.
Integrated configurations hold installed capacity. Modular designs are rotating up the share rankings.
Application:
Application segmentation tracks where bidirectional power flow capabilities create irreplaceable value versus incremental efficiency gains.
- Renewable Integration:Grid-forming converter topologies manage variable inverter-based resource penetration for utility-scale solar and wind farms. Developers in Rajasthan, India deploy these systems where Central Electricity Authority mandates require smart grid readiness for substations above 33kV.
- Electric Vehicle Charging:Compact 350kW+ charging hubs demand solid-state transformers for vehicle-to-grid power flow management and grid stability services. China's State Grid Corporation anchors procurement volumes for highway corridor electrification and urban fast-charging networks.
- Microgrid:Islanding-capable systems with seamless grid-disconnect functionality serve remote industrial facilities and campus environments.
- Grid Management:Distribution-level voltage regulation and power quality conditioning for congested urban networks.
Renewable Integration anchors current deployment scale. Electric Vehicle Charging is expanding most quickly as charging infrastructure buildouts accelerate.
End User:
Customer type segmentation exposes divergent procurement rhythms between regulated utilities with 20-year asset horizons and commercial operators optimizing for utilization rates.
- Utilities:Regulated grid operators in Germany, France, and Italy drive tender volumes for SF6-free distribution transformers under EU F-Gas Regulation compliance deadlines. These buyers prioritize 25-year lifecycle cost modeling and modular upgrade paths over upfront capital minimization.
- Industrial:Heavy manufacturing and data center operators specify solid-state transformers for power quality resilience and harmonic mitigation. Northern Virginia hyperscale facilities demand 10MVA-class installations with 60% cooling footprint reduction versus silicon IGBT alternatives.
- Commercial:Retail and office building operators with constrained balance sheets favor power-as-a-service arrangements over capital purchases.
- Residential:Single-family and multi-unit building applications remain nascent due to cost thresholds and distribution voltage standardization.
Utilities hold installed capacity. Industrial buyers are rotating up the share rankings.
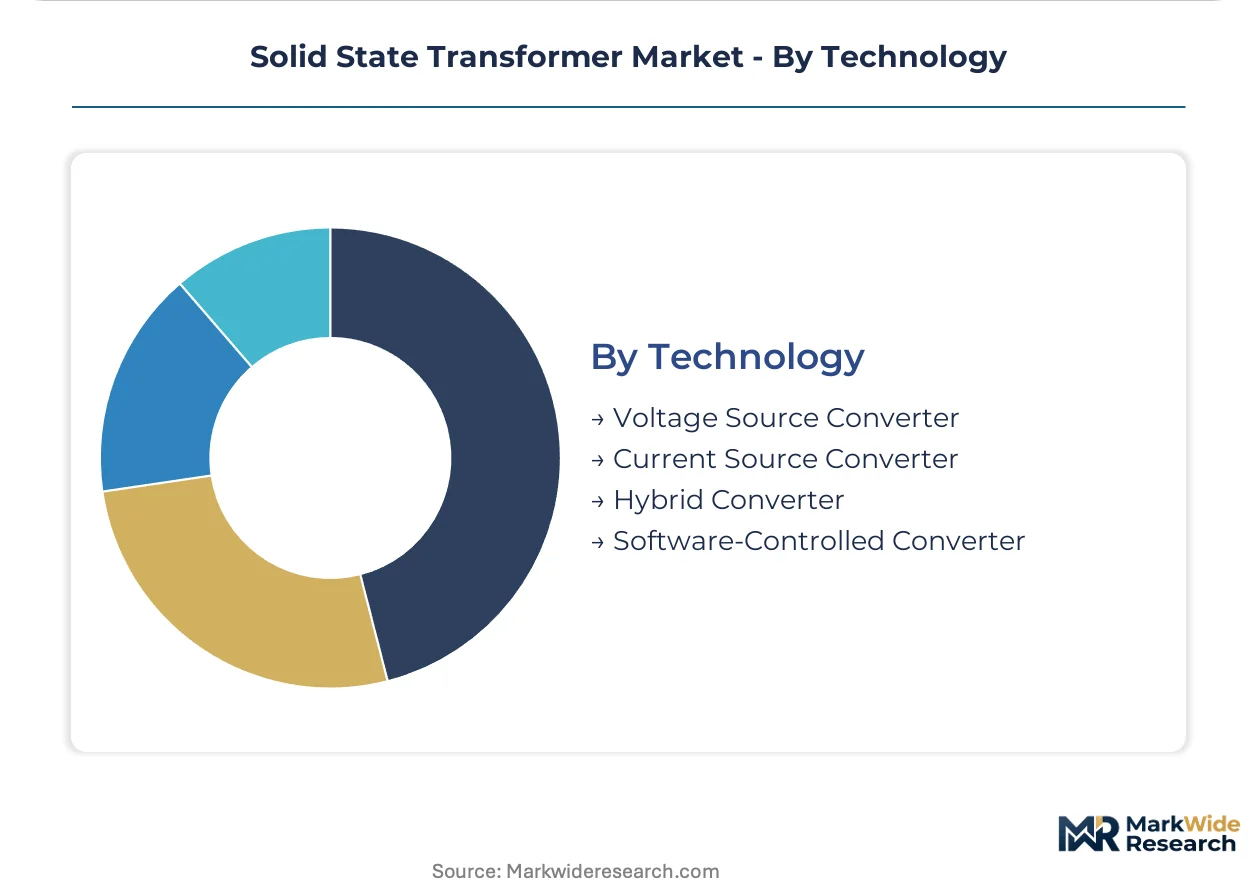
Technology:
Converter topology selection determines switching frequency capability, thermal management burden, and control system complexity for target power ratings.
- Voltage Source Converter:Two-level and three-level topologies with silicon carbide MOSFETs enable 50kHz switching frequencies that shrink magnetic component volume by an order of magnitude versus IGBT equivalents. German and Chinese suppliers converge on this architecture for 1.7kV-class utility applications.
- Hybrid Converter:Combinations of silicon IGBTs and silicon carbide MOSFETs balance cost and performance for mid-voltage industrial segments. US Inflation Reduction Act manufacturing incentives pull assembly toward Michigan and Texas facilities for domestic content compliance.
- Current Source Converter:Inductor-based topologies with inherent short-circuit protection for specialized high-reliability applications.
- Software-Controlled Converter:Digitally intensive architectures with grid-forming inverter functionality and embedded protection logic.
Voltage Source Converter holds installed capacity. Hybrid Converter is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German utilities anchor procurement volumes for SF6-free distribution transformers, while Chinese State Grid Corporation drives highway corridor electrification and India's Central Electricity Authority mandates smart grid readiness for substations above 33kV.
Germany
Bavarian transmission operators specify integrated solid-state transformer configurations for SF6-free substation retrofits where space constraints dominate. The EU F-Gas Regulation's 2030 phase-down targets compel replacement of gas-insulated equipment with dry-type alternatives. Industrial clusters in Baden-Württemberg host converter system integrators aligning with MIIT-promoted silicon carbide supply chains.
China
State Grid Corporation deploys 350kW+ charging hubs requiring compact bidirectional transformers for vehicle-to-grid power flow management. The Ministry of Industry and Information Technology promotes domestic silicon carbide substrate production through GB standards alignment. Yangtze River Delta manufacturing zones concentrate high-frequency magnetic component suppliers serving converter module assemblers.
United States
Northern Virginia hyperscale data center operators demand 10MVA-class installations with 60% cooling footprint reduction versus silicon IGBT alternatives. FERC grid resilience mandates and IEEE 1547-2018 interconnection standards favor bidirectional, fault-tolerant transformer technologies. Michigan and Texas converter assembly facilities capture Inflation Reduction Act domestic content bonuses for grid infrastructure projects.
India
Rajasthan solar developers deploy grid-forming converter topologies where Central Electricity Authority mandates require smart grid readiness for substations above 33kV. The country's national electricity regulator enforces renewable integration standards that oil-filled transformer suppliers cannot fulfill. Maharashtra industrial corridors attract power quality management deployments for heavy manufacturing facilities.
Japan
Tokyo metropolitan utilities pilot modular solid-state transformer configurations for congested urban distribution networks with limited substation footprints. METI energy transition programs subsidize high-efficiency power conversion equipment replacing conventional distribution infrastructure. Osaka-Kobe manufacturing zones host precision magnetic component suppliers feeding converter subsystem integrators.
Solid State Transformer Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered procurement frameworks that separate utility-scale integrated systems from modular commercial deployments. The vendor base clusters around three strategic archetypes: diversified electrical equipment conglomerates with grid automation portfolios, power semiconductor-integrated converter specialists, and ruggedized compact system providers for defense-aerospace applications. Dominant competitive moves include strategic partnerships for silicon carbide supply security and geographic expansion toward Inflation Reduction Act-compliant manufacturing zones.
Within the diversified conglomerate tier, Schneider Electric, Hitachi ABB Power Grids, and General Electric exemplify contrasting geographic anchoring strategies. The France-based S.A. represents European utility channel control through grid automation integration. The Swiss-Japanese entity occupies a position linking high-voltage direct-current infrastructure with solid-state transformer interfaces. The US-based Inc. exemplifies defense-aerospace specialization where ruggedization requirements override cost minimization. Each archetype faces procurement unbundling pressures as utility departments separate transformer supply from long-term service contracts.
| Leading Market Players |
|---|
| Schneider Electric |
| Hitachi ABB Power Grids |
| General Electric |
| Alstom |
| Mitsubishi Electric |
| Siemens |
| Eaton |
| SPX Transformer Solutions |
| ABB |
| Others |
Supply Flow & Price Mechanics
Wolfspeed's North Carolina silicon carbide substrate facilities and II-VI's Pennsylvania crystal growth operations anchor upstream supply, concentrating margin capture in wafer processing while converter module assemblers compete on assembly efficiency and thermal management integration.
Pricing Analysis
Cost-plus contracts with silicon carbide wafer indexation dominate utility-scale procurement, insulating transformer OEMs from raw material volatility while compressing margins on fixed-price modular units sold to commercial EV charging operators. Price differentiation rests on certification tier—UL-listed and IEEE 1547-compliant systems command substantial premiums over industrial-grade alternatives—and volume scale, with 10MVA-class integrated configurations benefiting from learning-curve effects unavailable to pilot-scale deployments. Cost compression in the modular tier intensifies as Chinese converter suppliers enter European markets with aggressively priced field-replaceable blocks. Commercial charging network operators exhibit acute price sensitivity, while German transmission utilities prioritize lifecycle cost modeling over upfront capital minimization.
Supply Chain Analysis
Export controls on wide-bandgap semiconductor manufacturing equipment limit technology transfer to Chinese substrate growth facilities, constraining domestic supply expansion and reinforcing dependence on US and Japanese crystal growth capacity. The supply chain draws from conductive silicon carbide substrates originating predominantly in North Carolina and New York facilities, high-frequency nanocrystalline magnetic cores from Japanese and German specialty alloy producers, and liquid-cooled thermal management subassemblies concentrated in Michigan and Texas assembly plants. Single-source vulnerability in 150mm SiC wafer supply creates procurement risk for European and Chinese converter integrators lacking multi-year supply commitments. Distribution runs through direct utility tender channels for integrated systems and specialist electrical distributors for modular commercial deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solid-state transformer market constitutes a high-growth disruption driven by silicon carbide trench MOSFET commercialization collapsing switching losses and enabling 50kHz isolation stages that shrink magnetic volume by an order of magnitude.
For Market Incumbents: Harden silicon carbide supply security through captive wafer processing investments or multi-year offtake agreements with Wolfspeed and II-VI, defending against emerging Chinese substrate producers capturing domestic market share through MIIT-promoted GB standards alignment. Prioritize grid-code certification pre-positioning for IEEE 1547-2018 and regional interconnection standards to compress 12-18 month validation cycles that delay revenue recognition. Expand converter assembly capacity in Michigan and Texas to capture Inflation Reduction Act domestic content bonuses.
For New Entrants and Emerging Players: Mid-market commercial buildings in Southeast Asia with constrained balance sheets and aggressive renewable connection timelines represent the most penetrable entry point, particularly where power-as-a-service arrangements displace capital purchase frameworks. Marine vessel electrification specifications from DNV and Lloyd's Register offer a white-space channel with limited incumbent presence and premium pricing tolerance for liquid-cooled compact systems. Pursue certification-first positioning to bypass established supplier relationships that lock utility procurement departments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed converter specialists holding stranded technology positions from earlier silicon IGBT iterations and lacking capital to pivot toward silicon carbide integration. Long-term viability in this market hinges on 5-10 year positioning around semiconductor learning curves rather than copper commodity cycles. Monitor silicon carbide substrate capacity expansion announcements as the decisive inflection signal for margin trajectory and competitive consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Commitment | Multi-year wafer offtake agreements with Wolfspeed secure converter module output against substrate scarcity. |
| Grid-Code Certification Pre-Positioning | Early IEEE 1547-2018 validation compresses revenue recognition delays for fault-ride-through compliance. |
| Domestic Assembly Localization | Michigan and Texas facilities capture IRA manufacturing incentives for utility infrastructure procurement. |
| Power-as-a-Service Model Development | Asset-retention arrangements penetrate municipal utilities with constrained capital budgets. |
| Marine Classification Society Engagement | DNV and Lloyd's Register rule alignment opens offshore vessel electrification specifications. |
Methodological Framework
The analysis maps converter topology sub-sectors, application deployment modes, and end-user procurement frameworks, each validated through converter system integrators, utility planning officers, and silicon carbide device procurement leads. Primary interviews with EPC contractors, grid operators, and thermal management subsystem suppliers combined with secondary validation from FERC filings, EIA grid infrastructure databases, EU Green Deal implementation reports, and MIIT GB standards documentation. Bottom-up project pipeline aggregation triangulates against top-down utility capex forecasts.
Assumptions held fixed include silicon carbide device cost decline trajectories, EU F-Gas Regulation compliance deadlines, and IEEE 1547 interconnection standard adoption rates; variables tested include Chinese substrate capacity expansion timing and Inflation Reduction Act domestic content bonus persistence. The projection framework models segmentation across product type, application, end user, and technology topology, with CAGRs derived from installed capacity buildout curves and replacement cycle analysis. Forecast inputs incorporate EV charging hub deployment schedules, renewable interconnection queue depths, and SF6-free substation retrofit tender volumes.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting utility capital expenditure cycles or semiconductor capital equipment investment would shift the trajectory. Forecasts reflect assumptions that silicon carbide wafer supply constraints ease gradually and that grid-code certification timelines remain stable. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Low Voltage Drives Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Solid State Power Controller Market
Power Systems
Bypass Thyristor Market
Power Systems
E-Axle Inverter and Control Unit Systems Market
Power Systems
Power Electronics Equipment Cooling System Market
Power Systems
Intelligent Power Module (IPM) Market
Power Systems
PV Micro Inverters Market
Power Systems
Data Center Power Quality and Harmonics Monitoring Test Systems Market
Power Systems
Three Phase Micro Inverters Market
Power Systems
Series Reactor Market
Power Systems
Global Power Semiconductor Switches Market
Power Systems
Telecom Battery Market
Power Systems
Vacuum Pressure Impregnated (VPI) Transformer Market
Power Systems
Battery Balancer Market
Power Systems
Global Battery Thermal Management System Market